What are the top AI coding startups by revenue today?
Everything we know about the AI code assistant market, in one place. Get our report whether you build or invest.
Summary
Cursor is the top AI coding startup by revenue today, with a $4 billion annualized revenue run-rate in June 2026. Anthropic's Claude Code follows at more than $2.5 billion, while Windsurf ranks third with approximately $82 million in historical annual recurring revenue.
AI coding assistants and vibe-coding platforms serve overlapping but different markets. Our ranking focuses on developer-facing coding assistants and autonomous coding agents, excluding prompt-to-app platforms such as Lovable and Base44.
The revenue gap at the top is enormous. Cursor's reported run-rate is roughly 49 times Windsurf's last standalone ARR estimate, while Claude Code's is more than 30 times as large. These comparisons use different periods and financial measures, but the concentration is unmistakable.
Enterprise customers are driving much of this growth. Approximately 75% of Cursor's reported run-rate comes from businesses, while enterprise customers account for more than half of Claude Code's revenue. AI coding has moved well beyond subscriptions purchased by individual programmers.
Acquisitions have reshaped the competitive landscape. SpaceX acquired Cursor in August 2026, Cognition acquired Windsurf in July 2025, Tricentis bought Tabnine, and Anaconda acquired Kilo Code. Their historical startup figures should not be confused with the revenue of their new owners.
Poolside illustrates why commercial value and revenue must be separated. Its $6 billion NVIDIA licensing arrangement is a major transaction, but it does not mean Poolside generates $6 billion annually from AI coding subscriptions.
Below the leaders, financial transparency drops sharply. Augment Code has an estimated $20 million in 2025 revenue, CoreStory has a $20.7 million historical estimate from its Crowdbotics business, Code Metal disclosed more than $10 million in contracted delivery, and Cline has an estimated $5 million ARR.
Large user numbers are not necessarily evidence of large revenues. OpenAI Codex reported more than 5 million weekly active users, TRAE reached approximately 1.6 million monthly active users, and BLACKBOX AI reported reaching 30 million developers. These figures reveal distribution, but not how many customers pay.
Specialized coding agents are finding enterprise opportunities outside mainstream software development. Code Metal targets safety-critical code, ChipAgents has deployments across more than 120 semiconductor companies, and Zencoder reports adoption at more than 500 organizations.
The shift from autocomplete to autonomous coding is accelerating. JetBrains' 2026 survey found that 90% of professional developers used AI coding agents at work at least weekly, while 68% used them daily. The commercial opportunity increasingly comes from completing engineering tasks rather than merely suggesting code.
The next competitive pressure is control over underlying AI models. Cursor's acquisition by SpaceX and OpenAI's planned withdrawal of model services show how dependent coding platforms remain on model access, inference economics and their ability to build competitive technology of their own.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

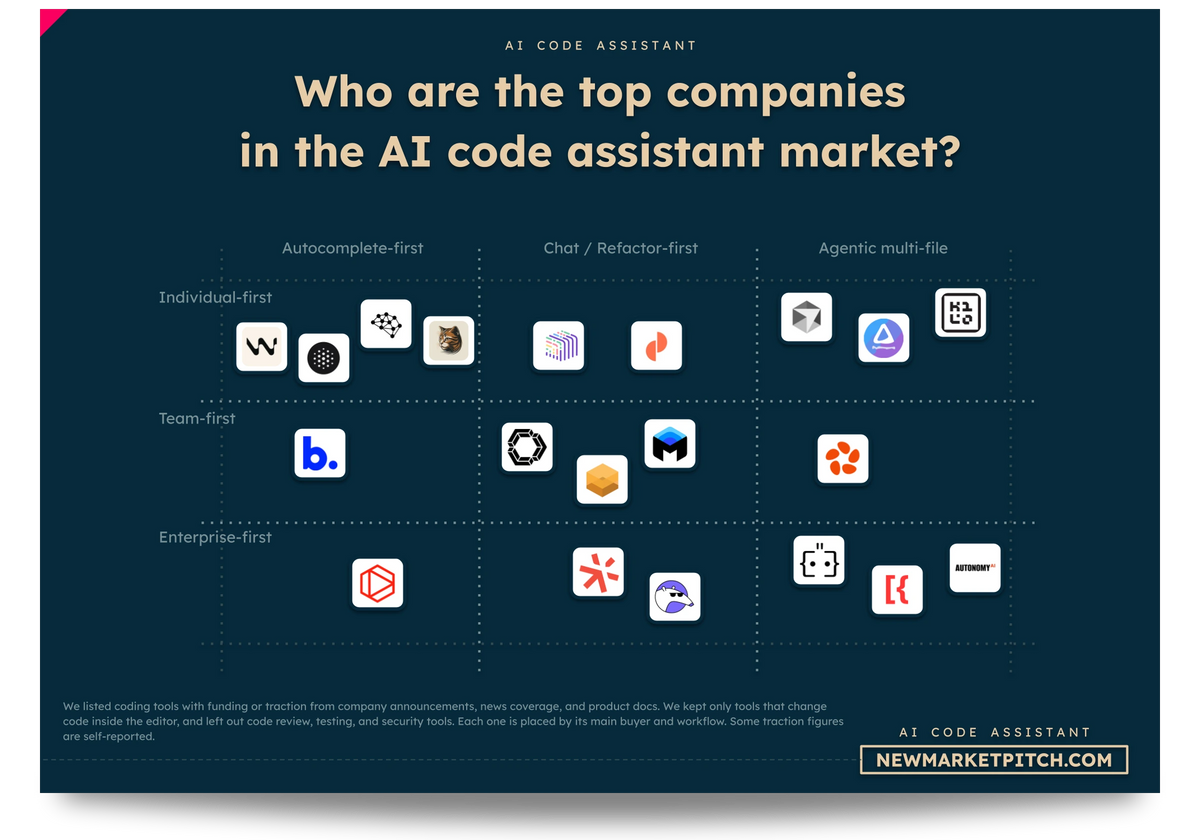
In our report covering the AI coding market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
The ranking of top startups in the AI code assistant market by revenue
Below is a table ranking the startups of this market by their current revenue scale. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our report on the AI code assistant market.
| Ranking | Company | Latest Metric | Metric Type | Freshness | Disclosed When | Source Quality | Confidence | Segment | Why This Ranking | Local Metric | Country |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | Cursor | $4B | Revenue Run-Rate | Very Fresh · 4mo | Jun 8, 2026 | Credible Reported | High | AI-native coding environment | Strongest current direct financial evidence found. Its $4B annualized revenue is substantially above Claude Code's disclosed run-rate and every other assistant with financial evidence. | us | |
| 2 | Anthropic: Claude Code | >$2.5B | Revenue Run-Rate | Fresh · 8mo | Feb 1, 2026 | Company Disclosed | High | IDE / CLI coding agent | Direct company disclosure and enormous current scale. Below Cursor because the disclosed run-rate is smaller and several months older. | us | |
| 3 | Windsurf | ~$82M | ARR | Fresh · 15mo | Third-Party Estimate | Medium | AI-native coding environment | The strongest conventional ARR evidence after Cursor and Claude Code, despite weaker sourcing. Above Poolside because a licensing deal value is not comparable to recurring revenue. | us | ||
| 4 | Poolside | $6B | Licensing Deal Value | Very Fresh · 2mo | Aug 20, 2026 | Credible Reported | Low | Coding models and developer agent platform | The $6B raw amount exceeds every company above it, but it is deliberately penalized because it is a one-off licensing transaction for Poolside's model technology, not recurring assistant revenue. | us | |
| 5 | Code Metal | >$10M | Contracted Revenue | Fresh · 10mo | Nov 12, 2025 | Company Disclosed | Medium | AI code translation and refactoring | Stronger provenance than the third-party revenue estimates immediately below. It stays below Poolside because its disclosed magnitude is far smaller, while outranking Augment because the evidence comes directly from the company. | us | |
| 6 | Augment Code | $20M | Annual Revenue | Fresh · 10mo | Sep 14, 2026 | Third-Party Estimate | Low | Enterprise coding copilot | Fresh financial evidence keeps it above CoreStory. It stays below Code Metal because Code Metal's revenue claim is direct rather than a database estimate. | us | |
| 7 | CoreStory | $20.7M | Annual Revenue | Aging · 22mo | Third-Party Estimate | Low | Code understanding / modernization | Nominally slightly larger than Augment's figure, but ranked below because it is older and the revenue perimeter predates the CoreStory rebrand and current code-intelligence positioning. | us | ||
| 8 | Cline | ~$5M | ARR | Fresh · 14mo | Third-Party Estimate | Low | Open-source IDE coding agent | Recent ARR evidence is more informative about current scale than Tabnine's substantially older revenue figure. | us | ||
| 9 | Tabnine | $5.8M | Annual Revenue | Historical · 46mo | Third-Party Estimate | Low | Enterprise coding copilot | Retained because actual revenue remains valuable evidence, but heavily penalized for age. Cline ranks above it despite a slightly smaller number because Cline's ARR reflects 2025 operations. | il | ||
| 10 | Magic | ~$2M | Annual Revenue | Historical · 34mo | Third-Party Estimate | Low | AI pair programmer / coding models | Last company in the ranking with a reasonably specific dollar revenue figure. Its old, weakly sourced financial metric receives only modest precedence over recent non-dollar commercial signals below. | us | ||
| 11 | JetBrains | >100K active paid users | Active Paid Users | Fresh · 10mo | 2026 | Company Disclosed | Medium | IDE-native AI coding assistant | Strongest non-dollar commercial disclosure found: recent, first-party and explicitly limited to paying active users. | cz | |
| 12 | OpenAI: Codex | >5M weekly active users | Users | Very Fresh · 4mo | Jun 2, 2026 | Company Disclosed | Medium | IDE / CLI coding agent | Very large, recent base of >5M weekly active users; ranked below JetBrains, whose >100K users are paid, and above TRAE on active usage. | us | |
| 13 | ByteDance: TRAE | ~6M registered users; ~1.6M monthly active users | Users | Fresh · 10mo | Feb 28, 2026 | Company Disclosed | Medium | AI coding environment / plugin | Strong current adoption but lower active usage than Codex and without a disclosed enterprise or paid-user figure. | cn | |
| 14 | BLACKBOX AI | 30M developers | Users | Very Fresh · 3mo | Jul 1, 2026 | Credible Reported | Low | Developer coding assistant | Huge reported reach, but it ranks below smaller first-party active-user figures because the 30M perimeter is broad and the metric is partner-reported. | us | |
| 15 | Kilo Code | >5M users | Users | Very Fresh · 1mo | Sep 19, 2026 | Company Disclosed | Low | Open-source IDE / CLI coding agent | Large, very current base of >5M users places it above Zencoder's organization count, though it sits below BLACKBOX AI's broader 30M reported reach. | us | |
| 16 | Zencoder | >500 organizations | Customers / Organizations | Very Fresh · 1mo | Sep 19, 2026 | Company Disclosed | Medium | Enterprise coding agent | Organization adoption is more commercially informative than generic downloads or signups immediately below. | us | |
| 17 | ChipAgents | >120 semiconductor company deployments | Customer Deployments | Very Fresh · 3mo | Jul 29, 2026 | Company Disclosed | Medium | Semiconductor coding copilot | Very strong commercial penetration inside a narrow market. Below Zencoder because its addressable segment is specialized and no absolute ARR figure was disclosed. | us | |
| 18 | Unblocked | tens of thousands of daily developers | Users | Very Fresh · 6mo | Apr 28, 2026 | Company Disclosed | Low | Code understanding assistant | Recent daily usage is stronger than download/signup metrics below, but less directly commercial than organization/customer deployment counts above. | ca | |
| 19 | Amp | ~51K weekly package downloads | Other Scale Signal | Very Fresh · 1mo | Sep 1, 2026 | Third-Party Estimate | Low | IDE / CLI coding agent | Extremely fresh measurable activity, but weaker than direct company user/customer disclosures because package downloads cannot be equated with active or paying users. | us | |
| 20 | Pieces for Developers | >100K signups | Users / Signups | Very Fresh · 1mo | Sep 19, 2026 | Company Disclosed | Low | Developer coding copilot | Larger nominal count than some lower rows, but signups are a substantially weaker commercial metric than customers or active usage. | us | |
| 21 | Moderne | 5,000 users onboarded | Customer Deployment | Very Fresh · 5mo | May 2026 | Company Disclosed | Low | AI code refactoring / modernization | Demonstrates a very large enterprise deployment, but the figure covers one customer only, preventing comparison with company-wide adoption above. | us | |
| 22 | Sourcegraph: Cody Enterprise | >1,000 developers at Qualtrics | Customer Deployment | Historical · 32mo | Feb 15, 2024 | Company Disclosed | Low | Enterprise code understanding assistant | Retained because Cody Enterprise still operates, but its best quantitative deployment disclosure is old and customer-specific. | us | |
| 23 | TabbyML | >19K GitHub stars | Other Scale Signal | Aging · 27mo | Jul 1, 2024 | Company Disclosed | Low | Self-hosted coding copilot | Weakest quantified signal in the ranking. No defensible revenue or customer count was found, so its open-source community footprint is shown without translating it into commercial revenue. | us |

Our research about AI coding assistants gets updated several times a month, so you always get the latest view of where things stand.
Are AI coding assistants and vibe-coding platforms the same market?
AI coding assistants and vibe-coding platforms overlap, but they sell different products, so we should distinguish them before comparing revenue. AI coding assistants help developers write, understand, modify and maintain existing codebases, while vibe-coding platforms let users create applications through natural-language instructions, often without traditional programming experience.
Cursor, Claude Code and Windsurf belong to the first category. They increasingly operate as autonomous coding environments, with agents that can inspect repositories, edit multiple files, execute tests and complete longer engineering tasks. Lovable, Replit and Base44 belong more naturally to the second category, where the customer wants to turn an idea into a working application.
The business models are different, too. An AI coding assistant can become part of a professional developer's daily workflow, with recurring subscriptions and enterprise contracts. A prompt-to-app platform can reach a much broader audience, including founders, designers and non-technical users.
We focus the ranking on AI coding assistants and coding agents, rather than mixing in the separate prompt-to-app market. That makes the revenue comparison more meaningful for companies selling tools that directly participate in software engineering.
Why are AI coding startups suddenly making so much money?
AI coding startups are growing rapidly because their products have moved from suggesting individual lines of code to completing substantial engineering tasks. That makes them much more valuable to professional developers and businesses.
The adoption numbers are striking. Stack Overflow's 2026 Developer Survey found that 65.9% of respondents used AI coding assistants or coding agents at work. Among these users, 73% reported using them daily. JetBrains' separate 2026 Developer Ecosystem Survey, covering more than 15,000 professional developers, found that 90% used AI coding agents at work at least weekly, with 68% using them daily.
The products themselves have changed. Earlier coding assistants primarily completed code as developers typed. Today's agents can investigate an unfamiliar repository, identify the files that need changing, implement a feature, execute tests and attempt to fix the problems they encounter. Claude Code, Cursor and Codex have all moved substantially in this direction.
Developers are no longer just experimenting with autocomplete. Companies are paying for software that takes on actual engineering work.

In our market report about AI coding assistants, we look at what the winners do differently, so you can learn from the best instead of guessing.
Which AI coding startups make the most money today?
Cursor, Anthropic's Claude Code and Windsurf occupy the first three positions in our AI coding startup ranking, with the strongest financial evidence concentrated heavily at the top.
The ranking below preserves our startup order and distinguishes actual revenue estimates from annual recurring revenue, run-rates, contractual commitments and non-financial commercial indicators. Acquired startups remain included.
| Rank | Startup | Figure | Metric | Period |
|---|---|---|---|---|
| 1 | Cursor | $4B | Revenue Run-Rate | Early Jun 2026 run-rate |
| 2 | Anthropic: Claude Code | >$2.5B | Revenue Run-Rate | Feb 2026 run-rate |
| 3 | Windsurf | ~$82M | ARR | Jul 2025 |
| 4 | Poolside | $6B | Licensing Deal Value | NVIDIA non-exclusive licensing arrangement announced Aug 2026 |
| 5 | Code Metal | >$10M | Contracted Revenue | Calendar 2025 contracted delivery |
| 6 | Augment Code | $20M | Annual Revenue | 2025 |
| 7 | CoreStory | $20.7M | Annual Revenue | 2024 |
| 8 | Cline | ~$5M | ARR | Aug 2025 |
| 9 | Tabnine | $5.8M | Annual Revenue | 2022 |
| 10 | Magic | ~$2M | Annual Revenue | 2023 |
| 11 | JetBrains | >100K active paid users | Active Paid Users | Q4 2025 |
| 12 | OpenAI: Codex | >5M weekly active users | Users | As of Jun 2026 |
| 13 | ByteDance: TRAE | ~6M registered users; ~1.6M monthly active users | Users | End of 2025 |
| 14 | BLACKBOX AI | 30M developers | Users | As of Jul 2026 |
| 15 | Kilo Code | >5M users | Users | As of Sep 2026 |
| 16 | Zencoder | >500 organizations | Customers / Organizations | As of Sep 2026 |
| 17 | ChipAgents | >120 semiconductor company deployments | Customer Deployments | H1 / Jul 2026 |
| 18 | Unblocked | Tens of thousands of daily developers | Users | As of Apr 2026 |
| 19 | Amp | ~51K weekly package downloads | Other Scale Signal | Four-week average ending Sep 2026 |
| 20 | Pieces for Developers | >100K signups | Users / Signups | Measurement date unstated |
| 21 | Moderne | 5,000 users onboarded | Customer Deployment | Morgan Stanley rollout through May 2026 |
| 22 | Sourcegraph: Cody Enterprise | >1,000 developers at Qualtrics | Customer Deployment | Feb 2024 |
| 23 | TabbyML | >19K GitHub stars | Other Scale Signal | Jul 2024 |
How far ahead are Cursor and Claude Code?
Cursor and Claude Code occupy a completely different commercial scale from the other AI coding startups with identifiable financial figures.
The gap becomes obvious when we compare their annualized figures with Windsurf's earlier ARR. Cursor's run-rate is roughly 49 times Windsurf's disclosed ARR, while Claude Code's reported run-rate is more than 30 times that amount. These are indicative comparisons between different recurring-revenue measures and periods, not audited like-for-like annual sales.
The first two products have disclosed figures measured in billions, while the next group relies on estimates and figures measured in tens of millions. Even allowing for differences between ARR, revenue and run-rate, the commercial gap is huge.
A small number of products have captured a disproportionate amount of the spending on AI-assisted software development. The rest of the field includes enterprise specialists, open-source agents and tools with meaningful user adoption but much less financial transparency.
And these products are competing directly for the same developer workflows. The companies that win can generate enough revenue to fund their own models, infrastructure and enterprise distribution, making it even harder for smaller rivals to catch up.

In our document detailing everything you need to know about AI coding, you will always find fresh funding data, taken straight from our own verified funding database.
Is Cursor really making $4B a year?
Cursor has reached an extraordinary commercial scale, but its reported $4B figure is an annualized revenue run-rate rather than $4B of recognized revenue collected over a completed financial year.
Forbes reported that Cursor passed the $4B annualized threshold in early June. The trajectory was unusually fast: the company had reached approximately $2B in February and $3B in late April before crossing the $4B threshold in June.
That represents a doubling of its run-rate over roughly four months. Older revenue estimates for Cursor can become obsolete remarkably quickly.
The composition of its business is equally interesting. According to information Cursor shared with Forbes, approximately 75% of its run-rate came from businesses. Its enterprise business had grown threefold in the first quarter compared with the fourth quarter of the previous year.
That's a major change from the image of Cursor as a tool primarily purchased by individual programmers. Its business now depends heavily on enterprise engineering departments.
Cursor's expansion also coincided with the introduction of Cloud Agents, which allow developers to delegate longer tasks rather than simply request code suggestions. Its commercial growth suggests that customers are willing to pay for increasingly autonomous software development workflows.
There is, however, an important corporate development. Cursor was officially acquired by SpaceX on August 14, 2026, as confirmed by SpaceX's SEC filing and Cursor's own announcement. Cursor remains at its original position in our startup ranking, now as part of SpaceX.
How much money does Claude Code generate?
Claude Code has become a multibillion-dollar AI coding product, with Anthropic officially disclosing a revenue run-rate exceeding $2.5B in February.
The announcement also revealed how quickly the business was growing. Claude Code's run-rate had more than doubled since the beginning of 2026, while its weekly active users had also doubled since January.
Enterprise demand is especially important. Anthropic said business subscriptions to Claude Code had quadrupled since the beginning of the year and that enterprise customers accounted for more than half of Claude Code revenue.
This goes well beyond consumer adoption. Enterprise subscriptions generally involve larger deployments, recurring spending and deeper integration into engineering workflows.
Another interesting figure concerns software production itself. Anthropic cited an analysis estimating that Claude Code was responsible for approximately 4% of all public GitHub commits worldwide, twice the estimated share from the preceding month.
We should be careful about interpreting this number because public commits are not the same as all software development activity. Still, 4% is a remarkable share for a relatively new coding product.
The financial perimeter is also important: the $2.5B-plus run-rate concerns Claude Code, not Anthropic's entire business or its total revenue from Claude subscriptions and API services.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the AI coding market, we look at what broke startups before you, so you don't repeat it.
What happened to Windsurf after Cognition bought it?
Windsurf remains at rank three in our AI coding startup ranking, with its strongest specific financial evidence being approximately $82M ARR in July 2025, before its acquisition by Cognition.
The acquisition followed an unusual sequence of events. OpenAI agreed to acquire Windsurf in May 2025, but that transaction did not close. Google subsequently hired CEO Varun Mohan, co-founder Douglas Chen and approximately 40 employees through a separate arrangement involving technology licensing.
Cognition then signed an agreement to acquire the remaining Windsurf business, including its intellectual property, product, brand and customer base. Cognition announced the agreement on July 14, 2025.
Sacra estimated that Windsurf had reached approximately $82M ARR by July, up from around $40M in February. Its enterprise ARR had also been doubling quarter over quarter, according to reporting around the acquisition.
Google did not acquire the remaining operating company. Cognition acquired that business and continued developing its products alongside Devin.
We retain Windsurf's own historical ARR figure in the ranking. Replacing it with Cognition's broader company revenue, or adding the two figures together, would distort the comparison.
Are AI coding startups actually winning enterprise customers?
Yes. Enterprise adoption is becoming a major source of revenue for AI coding startups, and the strongest companies are increasingly selling to engineering organizations rather than relying exclusively on individual subscriptions.
Cursor provides a clear example. Approximately three-quarters of its reported run-rate came from businesses, while its enterprise activity had tripled quarter over quarter in the period reported by Forbes.
Anthropic has disclosed a similar development for Claude Code. Enterprise use represents more than half of its product revenue, and business subscriptions grew fourfold from the beginning of 2026 to February.
The trend also appears further down the ranking. Code Metal said in its November 2025 announcement that it was already under contract to deliver eight figures in revenue during the calendar year. Its customers operate in defense, automotive and semiconductor industries, where software must satisfy demanding safety and reliability requirements.
Zencoder also reports adoption across more than 500 organizations. These deployments suggest that coding agents are finding their way into established engineering departments.
Two business models are emerging. Horizontal products sell to large numbers of developers and engineering teams, while specialized products target industries where code modernization, verification and security are particularly valuable.

In our research about AI coding assistants, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Does Poolside's $6B NVIDIA deal count as AI coding revenue?
Poolside's $6B NVIDIA arrangement is a licensing deal value, not recurring AI coding revenue. Treating it as annual sales would badly distort the financial picture.
The agreement announced in August involved NVIDIA licensing Poolside technology, alongside a separate $1B investment and offers to hire more than 100 employees involved in developing the technology.
The $6B represents a transaction covering technology licensing and related arrangements, rather than a subscription business generating $6B annually.
The Information and Bloomberg reported the details of the arrangement, including the licensing and hiring components. Poolside's founders were expected to remain independent, and the agreement was not described as a conventional acquisition.
It was an unusual deal for an AI coding startup. Poolside originally developed coding agents before expanding its work into model development and infrastructure.
Its position at rank four should therefore be read with the correct metric attached. The transaction demonstrates the economic value NVIDIA places on Poolside's technology, but it tells us little about the company's recurring coding revenue.
We keep the transaction value visible as evidence of commercial scale, while separating licensing proceeds from annual software revenue.
How much revenue does Code Metal actually have?
Code Metal disclosed contracted revenue exceeding $10M for calendar 2025, giving us a much stronger financial indication than a user count or an open-source adoption figure.
The company announced in November 2025 that it was already under contract to deliver eight figures in revenue during the year. It did not disclose a more precise amount, so we retain the threshold rather than inventing a figure.
Code Metal targets industries where generic AI code generation can create serious problems. Its platform focuses on verifiable code translation, modernization and software development for defense, automotive and semiconductor applications.
The company's argument is straightforward: generating code quickly is useful, but producing code that can be verified, tested and deployed in safety-critical environments is a different challenge.
There are fewer potential customers here than in the general developer market, but individual contracts can be substantial. Code Metal's commercial commitments suggest that specialized AI coding products can generate meaningful business without millions of individual users.
One qualification remains: contracted delivery does not necessarily equal recognized revenue. The disclosure confirms a commercial commitment, but not that the entire amount had already been recognized in the company's accounts.

If you build or invest in the AI coding market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
How much revenue does Augment Code make?
Augment Code is estimated to have generated $20M in annual revenue during 2025, although the figure comes from third-party company data rather than a public financial statement.
GetLatka's company profile lists the $20M figure for October 2025. The listing does not identify the underlying source for this particular revenue estimate, so we should not present it as a company-confirmed disclosure.
Augment Code sells an enterprise-oriented coding assistant designed to understand an organization's codebase, documentation and dependencies. Its value proposition is particularly relevant for teams working on large software projects, where understanding existing architecture can be as important as generating new code.
That positioning also distinguishes it from simpler autocomplete tools. Augment attempts to use a team's existing technical knowledge to produce suggestions that fit the way its software is actually built.
The $20M estimate gives us a useful indication of its commercial scale, but the confidence level is lower than for Cursor, Claude Code or Code Metal, where we have more explicit financial disclosures.
Why does CoreStory rank below Augment Code despite its $20.7M estimate?
CoreStory remains below Augment Code because its $20.7M figure relates to an older 2024 estimate for its predecessor, Crowdbotics, rather than a more recent financial disclosure covering the current business.
GetLatka estimates that Crowdbotics generated $20.7M in 2024. The company subsequently rebranded as CoreStory and shifted its positioning toward code intelligence, legacy software understanding and modernization.
The change in business focus is significant. Crowdbotics originally concentrated on helping organizations build applications, combining software automation with developer services. CoreStory now emphasizes understanding existing codebases, mapping dependencies and translating legacy systems into structured knowledge that developers and agents can use.
Augment Code's $20M estimate is associated with 2025, giving us more recent evidence of its commercial scale. CoreStory's figure is older and relates to a different business positioning.
The two amounts are close enough that treating them as directly comparable would create a false impression of precision. We therefore retain Augment at rank six and CoreStory at rank seven.

In our document detailing everything you need to know about AI coding, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are open-source AI coding startups making real money?
Yes, open-source AI coding startups can generate meaningful recurring revenue, although Cline currently provides the clearest financial example among the companies in this part of the market.
Sacra estimates that Cline reached approximately $5M ARR in August 2025. Its business model is interesting because the company passes AI inference costs through at cost rather than adding a markup.
Payments flowing through Cline's platform should therefore not be confused with its own software revenue. The economically relevant revenue comes from licensing, enterprise contracts and paid team subscriptions.
The company has also expanded beyond an individual developer tool through Cline Teams and enterprise features.
Kilo Code illustrates another route to scale. Its open-source product attracted millions of developers and was subsequently acquired by Anaconda. TabbyML has built a substantial open-source community, but its disclosed GitHub stars do not establish a comparable revenue figure.
Open source can create distribution and developer trust. Turning that popularity into a business still depends on paid seats, enterprise capabilities, support and the value of the software itself.
Is Tabnine still a serious AI coding business?
Tabnine remains an active enterprise AI coding product, but its $5.8M annual revenue figure dates back to 2022 and should be treated as historical evidence rather than a reliable measure of current sales.
CB Insights records the $5.8M figure for 2022, with no newer revenue disclosure in its financial profile.
Tabnine has continued developing its enterprise product, with a stronger focus on organizational context, security and private deployment. Its Enterprise Context Engine is designed to give AI agents a structured understanding of company repositories, documentation, dependencies and architecture.
The company was acquired by Tricentis in July 2026. Its technology is now being integrated into Tricentis' agentic quality engineering platform, extending its potential use beyond code generation into software testing and validation.
The acquisition says quite a lot about where enterprise AI coding is heading. Software companies increasingly want agents that understand the systems they operate within, rather than tools that simply generate code from isolated prompts.
Tabnine stays at rank nine, but its historical financial figure should not be confused with the revenue of its new owner or the current commercial performance of the combined platform.

In our report covering the AI coding market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
How big is OpenAI Codex today?
OpenAI Codex has achieved substantial adoption, with more than 5 million weekly active users reported in June 2026, although OpenAI has not disclosed a separate Codex revenue figure.
OpenAI said the product's weekly active user base had grown more than sixfold since the launch of its desktop application in February.
An especially interesting development is that Codex is attracting people outside traditional software engineering. OpenAI reported that knowledge workers represented approximately 20% of its users and were growing more than three times as quickly as developers.
These users increasingly apply Codex to analysis, document creation, information gathering and workflow automation, in addition to conventional programming tasks.
For our ranking, the user figure demonstrates product adoption, but it does not tell us how much revenue Codex generates. We do not estimate sales by multiplying its users by a subscription price or assume that every active user is paying.
OpenAI remains included at its position because Codex has substantial commercial potential and its adoption is publicly measurable. The ranking does not substitute OpenAI's overall business revenue for Codex revenue.
How popular is ByteDance's TRAE coding assistant?
ByteDance's TRAE reached approximately 6 million registered users and 1.6 million monthly active users, showing that AI coding tools have attracted substantial audiences outside the American market.
TRAE's 2025 annual review reported more than 6 million registered users across nearly 200 countries. Its product development has also moved beyond conventional code completion toward agentic development, with its SOLO mode and enterprise-oriented offerings.
The difference between registered and monthly active users is worth highlighting. The 1.6 million monthly active figure gives us a much better indication of ongoing engagement than the cumulative registration count.
TRAE also reported substantial growth in token consumption during the second half of 2025 and close to 100 billion lines of generated code over the year. Those figures demonstrate activity at scale, although neither directly establishes the product's revenue.
ByteDance's international distribution is particularly interesting because TRAE is competing for developers across multiple markets rather than relying solely on Chinese demand.
We include it at rank thirteen because ByteDance's coding product has measurable traction, while the available figures do not establish reliable standalone revenue.

When you build or invest in the AI coding market, you need clarity, not confusion. In our research about AI coding assistants, we always try to put numbers on and quantify whatever is usually vague and confusing.
Do millions of AI coding users translate into revenue?
Millions of AI coding users demonstrate distribution, but they tell us very little about revenue unless we also understand how many users are active, paying and generating recurring spending.
BLACKBOX AI illustrates the problem. Partner materials from ElevenLabs describe more than 30 million developers using its products. That's substantial reach, but the figure does not establish how many developers pay for subscriptions or use the product regularly.
Codex, TRAE and Kilo Code also demonstrate how different user metrics can be. Weekly active users, monthly active users, registered accounts and cumulative users measure different types of engagement.
Kilo Code, for example, had attracted more than 3 million developers when Anaconda announced its acquisition in July 2026. Anaconda subsequently described Kilo as having more than 5 million users. Impressive distribution, certainly, but we still don't have an ARR figure.
The problem becomes even more pronounced when a product is free or open source. A developer may install an extension, experiment with it once and never return. Another developer may use it every day through a paid enterprise subscription.
We therefore keep user numbers as evidence of commercial reach, without turning them into invented revenue estimates.
Can specialized AI coding startups win enterprise contracts?
Yes. Specialized AI coding startups can win substantial enterprise deployments by solving problems that general-purpose coding agents do not necessarily handle well.
Code Metal, Zencoder and ChipAgents illustrate three different approaches.
Code Metal focuses on code translation and modernization for industries with strict reliability requirements. Its contracted revenue disclosure confirms that customers are prepared to pay for specialized engineering automation.
Zencoder reports more than 500 organizations using its platform. Its product combines AI coding assistance with autonomous agents designed to automate tasks such as bug fixes and dependency updates.
ChipAgents targets semiconductor design and verification. The company reported deployments at more than 120 semiconductor businesses and sixfold ARR growth during the first half of 2026.
ChipAgents is especially interesting because it shows that a coding agent doesn't have to serve every software developer to build a meaningful business. Semiconductor engineering is a narrow market, but the workflows are technically demanding and economically valuable.
These companies have an opportunity to understand specialized codebases, processes and industry requirements better than a general-purpose assistant. That can create a defensible product, particularly when customers need secure deployments and verifiable results.

A good product starts with a real problem. In our report covering the AI coding market, we show you the ones customers still live with.
Are developers really switching from copilots to autonomous coding agents?
Yes. Developer surveys show a clear shift toward autonomous coding agents, although traditional code completion and IDE assistance remain part of everyday development.
JetBrains' 2026 Developer Ecosystem Survey found that approximately 90% of professional developers were using AI coding agents at work weekly, with 68% using them daily.
The same study found that Claude Code was being used by approximately 39% of professional developers at work during the May–July survey period, up from 18% in January. Codex also grew rapidly, moving from approximately 3% adoption in January to 16% in the later survey period.
That's a significant change in a relatively short period. Developers are increasingly experimenting with tools that can take responsibility for longer tasks instead of simply suggesting the next line of code.
Traditional copilots still have an important role. Microsoft reported 4.7 million paid GitHub Copilot subscribers in its FY2026 second-quarter earnings discussion, up 75% year over year. That is an established-player benchmark, not part of our startup ranking.
The two approaches will probably continue to coexist. Developers still benefit from quick suggestions while writing code, but agents are becoming more useful for larger tasks involving multiple files, tests and longer execution cycles.
Is AI coding delivering real productivity gains?
AI coding is producing measurable productivity improvements, although much of the public evidence still comes from developer surveys and company-reported results rather than controlled measurements across the entire software industry.
BairesDev's Q3 2026 Dev Barometer, based on 705 developers across 60 countries, reported that developers saved approximately 13 hours per week on coding tasks, compared with seven hours a year earlier.
The same survey found that 42% of developers said AI now assisted with at least half of their code, compared with 12% one year earlier.
These figures are self-reported, so we should not automatically treat every claimed hour saved as an equivalent increase in productive output. Developers may also spend more time reviewing, testing and correcting generated code.
McKinsey's 2026 State of AI survey adds another perspective. Approximately two in ten organizations reported scaling software coding agents, rising to 31% among larger enterprises. More surprisingly, 32% of respondents said their organizations had decided against purchasing at least one software product or feature because they believed they could build it internally using agentic coding tools.
That second figure could have significant consequences for the wider software industry. AI coding tools may generate new revenue for their own developers while reducing demand for certain categories of conventional software.
The productivity opportunity is real. The harder question is how much of the time saved translates into better software, lower costs and additional output.
In our report covering the AI coding market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Can Cursor keep growing without OpenAI models?
Cursor can continue growing without OpenAI models, but losing access to those models creates a meaningful technical and commercial transition risk.
The situation changed after SpaceX acquired Cursor. On August 28, 2026, OpenAI announced that it intended to wind down its contract for supplying models to Cursor, citing concerns about whether SpaceX would use its technology within the agreed terms.
OpenAI proposed a future end date under the contractual provisions governing a change of control. The announcement also made clear that existing customers would receive notice before access ended.
Coding assistants depend heavily on the quality, availability and economics of their underlying models. A model access dispute can quickly become a product problem.
Cursor has been developing its own Composer models and now has access to SpaceX's broader computing infrastructure and Grok models. Its acquisition changes its strategic position: it can increasingly rely on technology developed within its new parent group.
Still, losing access to a major model provider reduces flexibility. Cursor will need to maintain strong performance across different models and ensure that customers don't experience a deterioration in the quality of their workflows.
This is one of the more important developments to watch. A coding assistant can build a large customer base, but keeping it requires consistent access to competitive models and affordable inference.
Which smaller AI coding startups have the strongest commercial traction?
Among the smaller AI coding startups, Zencoder and ChipAgents have particularly useful enterprise deployment evidence, while the remaining companies demonstrate varying levels of user activity, customer adoption and community interest.
The differences become clearer when we examine the metrics individually. An organization using a platform is stronger commercial evidence than a simple registration, while a customer-specific deployment should not be confused with company-wide adoption.
| Rank | Startup | Commercial indicator | Period |
|---|---|---|---|
| 16 | Zencoder | >500 organizations | As of Sep 2026 |
| 17 | ChipAgents | >120 semiconductor company deployments | H1 / Jul 2026 |
| 18 | Unblocked | Tens of thousands of daily developers | As of Apr 2026 |
| 19 | Amp | ~51K weekly package downloads | Four-week average ending Sep 2026 |
| 20 | Pieces for Developers | >100K signups | Measurement date unstated |
| 21 | Moderne | 5,000 users onboarded | Morgan Stanley rollout through May 2026 |
| 22 | Sourcegraph: Cody Enterprise | >1,000 developers at Qualtrics | Feb 2024 |
| 23 | TabbyML | >19K GitHub stars | Jul 2024 |
Moderne provides a particularly interesting example of enterprise adoption. A Morgan Stanley presentation hosted by Moderne described 5,000 users onboarded, more than 2,000 running recipes and over 1,000 commits shipped through its deployment.
That is substantial evidence of usage inside a major financial institution, but the figure covers one customer rather than Moderne's entire customer base.
Unblocked also reports tens of thousands of developers using its product experiences every day. Its focus on helping developers retrieve information from documentation, codebases and internal company systems is becoming increasingly relevant as autonomous agents need better context to operate effectively.
Amp's package downloads and TabbyML's GitHub stars tell a different story. They demonstrate developer interest and product distribution, but neither establishes paying customer numbers or recurring revenue.
There is meaningful activity below the first few commercial heavyweights. However, more financial disclosures are needed before we can confidently describe most of this group as substantial revenue-generating businesses.
Our research about AI coding assistants gets updated several times a month, so you always get the latest view of where things stand.
So, what are the top AI coding startups by revenue today?
Cursor is the clear answer at the top of our AI coding startup ranking, followed by Anthropic's Claude Code and Windsurf.
The first two companies have reached a commercial scale that separates them sharply from the rest of the field. Their disclosed run-rates, combined with strong enterprise adoption, demonstrate that AI coding has become a substantial software market.
Windsurf comes next, with a meaningful historical ARR figure and a business that now operates within Cognition. The following positions include Poolside, Code Metal, Augment Code, CoreStory, Cline, Tabnine and Magic, with increasingly different levels of financial evidence.
The AI coding market has developed several business models. Some startups sell subscriptions to individual developers, others sell enterprise coding agents, and specialized companies target demanding engineering environments such as semiconductor design and safety-critical software.
We should also resist treating every commercial indicator as revenue. A licensing transaction, contracted delivery, ARR estimate, weekly active user count and enterprise deployment all tell us something different about a company's scale.
For now, the clearest commercial success belongs to the companies that have turned AI coding into a recurring part of professional software development. The next big question is how many smaller competitors can convert their adoption into equally strong recurring revenue.
Our methodology
This analysis ranks AI coding startups using the strongest available evidence of revenue and commercial scale as of November 2026. We focus on AI coding assistants, autonomous coding agents and specialized software engineering automation, rather than combining them with the broader prompt-to-app and vibe-coding market.
Our startup definition includes companies founded in 2000 or later that have never been publicly listed or first listed within the last five years, and that developed their businesses independently. Startups acquired within the last three years remain eligible, with their ownership changes identified. Established companies outside this definition are excluded from the startup comparison.
We examined annual revenue, fiscal-year revenue, trailing-twelve-month figures, ARR, annualized revenue run-rates and contracted revenue. Where reliable financial figures were unavailable, we used measurable commercial activity such as active users, paid subscriptions, enterprise deployments, customer organizations and developer adoption.
The ranking prioritizes the relevance, freshness and reliability of each figure rather than sorting every number as though it were equivalent. Company disclosures carry more weight than third-party estimates, and recent financial measures generally carry more weight than older estimates. Commercial commitments and non-financial adoption indicators remain explicitly labeled.
We also distinguish product-level revenue from broader company revenue. Claude Code's run-rate is attributed to Claude Code rather than Anthropic as a whole, and Codex's adoption is not converted into an estimate of OpenAI's coding revenue. Historical figures from acquired startups are kept separate from the current financial performance of their parent companies.
For companies such as Poolside, licensing transactions are treated as evidence of commercial value rather than annual recurring sales. Similarly, contracted revenue is distinguished from recognized revenue, while registered users, downloads, GitHub stars and enterprise deployments are never converted into speculative sales estimates.
We drew on official company announcements, regulatory filings, financial disclosures, independent financial analysis, developer surveys and established technology and business reporting. Historical financial figures remain identified by their original reporting periods to avoid presenting old revenue as current performance.
Key financial and transaction sources include Forbes on Cursor's $4B annualized revenue, Anthropic's Claude Code revenue disclosure, SpaceX's SEC filing on its acquisition of Cursor, OpenAI's announcement concerning Cursor model access, Cognition's Windsurf acquisition announcement, Sacra's Windsurf revenue analysis, Bloomberg on NVIDIA's Poolside licensing deal, Code Metal's contracted revenue announcement, Sacra's Cline ARR estimate, and CB Insights' Tabnine financial profile.
Additional company and adoption sources include Tabnine's Tricentis acquisition announcement, JetBrains' 2026 annual highlights, OpenAI's Codex adoption announcement, TRAE's 2025 annual review, ChipAgents' enterprise deployment announcement, Zencoder's customer information, Anaconda's Kilo Code acquisition announcement, and ElevenLabs on BLACKBOX AI's developer reach.
For wider industry context, we also used JetBrains' 2026 study on coding agent adoption, Stack Overflow's 2026 Developer Survey, and McKinsey's State of AI analysis. Survey-based adoption and productivity findings are identified separately from financial disclosures, since they measure developer behavior rather than company revenue.
In our market report about AI coding assistants, we look at what the winners do differently, so you can learn from the best instead of guessing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us