AI Drug Discovery: what are the top startups now?
Whether you're building or investing in the AI in drug discovery market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Insilico Medicine, Isomorphic Labs, Recursion Pharmaceuticals, Generate Biomedicines, and Chai Discovery are the top AI drug discovery startups right now. But they lead for different reasons: clinical progress, financial backing, pharmaceutical partnerships, and the ability to produce useful drug candidates repeatedly.
Insilico Medicine has one of the strongest clinical cases. Its AI-discovered pulmonary fibrosis drug, rentosertib, has reached Phase 3 following a randomized Phase 2a trial. It is among the clearest examples of AI contributing to a medicine that has advanced into late-stage human testing.
Isomorphic Labs has attracted considerably more capital, raising $2.7 billion across two disclosed external financing rounds. Yet its publicly demonstrated clinical progress remains behind Insilico's. The best-funded drug discovery platform is not necessarily the one closest to producing an approved medicine. Money raised versus progress in patients is one of the market signals we follow every quarter in our AI drug discovery market report.
Recursion has built a more diversified position than most competitors. It combines its own clinical pipeline with large-scale biological experiments and pharmaceutical partnerships, including $144 million in cumulative upfront and milestone payments from Sanofi. That gives it several ways to demonstrate value before a drug reaches the market.
Generate Biomedicines stands out in AI-engineered proteins. Its lead antibody is already in Phase 3 for severe asthma, while its platform has reportedly generated, built, and tested more than 42,000 proteins. Its advantage rests on the combination of computational design, experimental data, and advanced clinical development.
Chai Discovery illustrates a different kind of success. It secured six pharmaceutical partnerships in nine months, showing unusually strong demand for its molecular design technology despite having less publicly available human clinical evidence than the leading therapeutic developers.
Pharmaceutical payments provide a better commercial test than announced deal values. Genesis Molecular AI secured $150 million in total upfront consideration from Incyte, while insitro's AstraZeneca collaboration includes $40 million upfront and approximately $1.46 billion in conditional milestones. Those figures should not be treated as equivalent revenue achievements.
The industry is still clinically young. A study covering 129 AI-enabled therapeutic assets from 69 companies found that only five had entered or completed Phase 3 by its March 2026 cutoff. Most of the industry's apparent progress is therefore concentrated in early clinical development rather than completed pivotal trials.
Early success rates also deserve caution. One recent study reported 77.8% observed Phase 1 success but only 19.5% Phase 2 success. AI is helping generate candidates that reach patients, but the evidence that it consistently produces better medicines than conventional discovery remains incomplete.
The competitive divide is becoming clearer. Companies such as Insilico, Generate, and Recursion are taking clinical development risks to potentially own valuable medicines. Chai, Genesis, and insitro are building technologies that pharmaceutical companies can pay to use across multiple programs. Both models have potential, but their economics and evidence of success are different.
Our conclusion is that Insilico currently leads in clinical proof for AI-discovered small molecules, Isomorphic leads in capital-backed platform ambition, and Recursion has one of the strongest combinations of clinical development and paid partnerships. Generate is a leader in AI-designed biologics, while Chai is emerging as a major commercial platform contender. The next decisive test will be whether these advantages translate into successful late-stage trials, approved medicines, and repeatable pharmaceutical revenues.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

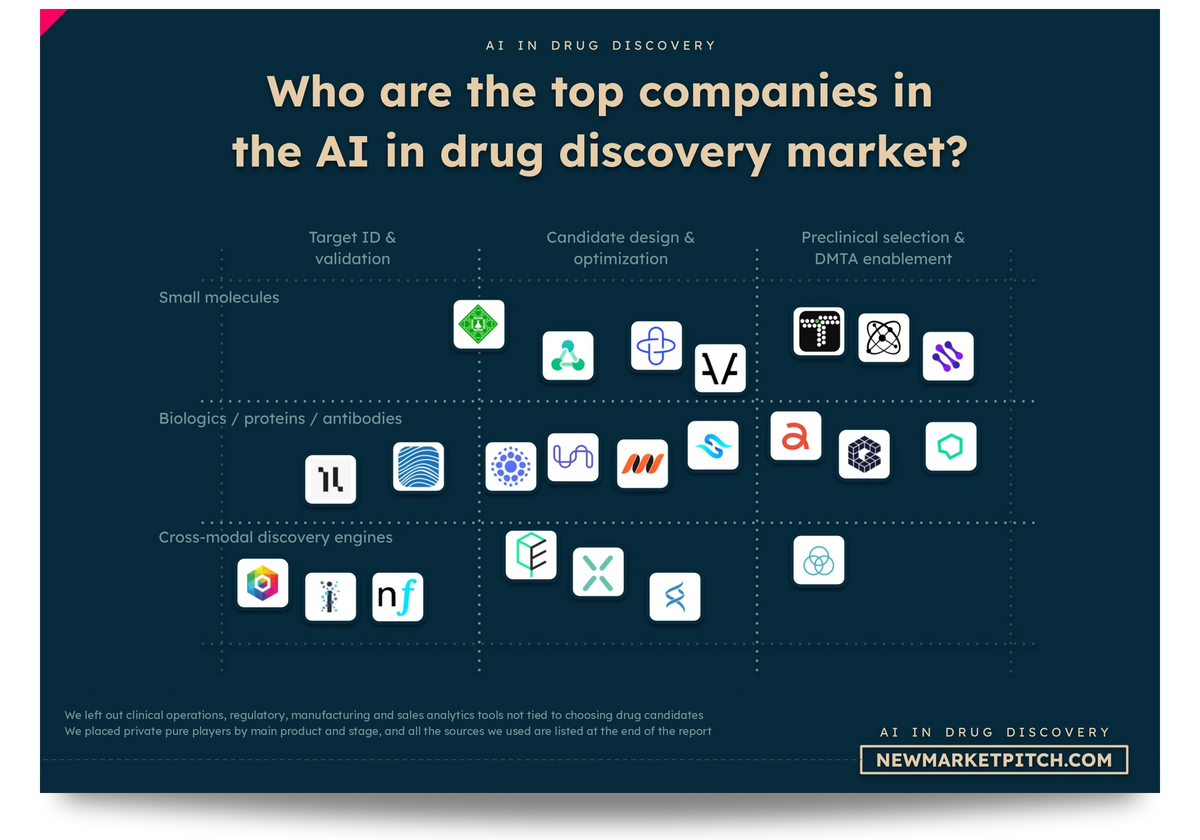
In our report covering the AI drug discovery market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Which AI drug discovery startups are leading right now?
Insilico Medicine, Isomorphic Labs, Recursion Pharmaceuticals, Generate Biomedicines, and Chai Discovery are currently among the top AI drug discovery companies, although their strongest achievements are surprisingly different.
Insilico Medicine has some of the best clinical evidence for a genuinely AI-discovered drug. Its experimental lung disease treatment, rentosertib, has reached Phase 3 after encouraging results in a randomized Phase 2a trial.
Isomorphic Labs leads in financial backing and ambition. The Alphabet-backed company raised $2.1 billion in May 2026, bringing its disclosed external financing to $2.7 billion. Its drug candidates, however, have yet to produce comparable publicly disclosed results in humans. Which funds back platforms before there is clinical proof, and what they now avoid, is traced in our report on AI drug discovery.
Recursion Pharmaceuticals has built one of the industry's broadest discovery platforms, combining large-scale biological experiments, machine learning, and drug development. Its experimental treatment REC-4881 recently delivered encouraging results in patients with an inherited condition that causes intestinal polyps.
Generate Biomedicines stands out in AI-designed proteins, with an antibody already in Phase 3 trials. Chai Discovery, meanwhile, has become one of the fastest-rising molecular AI companies, securing six pharmaceutical partnerships in nine months.
Developing a successful medicine and selling technology that helps other companies discover medicines are two very different businesses. Both can be valuable, but their achievements need to be judged differently.
Why is everyone suddenly paying attention to AI drug discovery?
AI drug discovery is getting serious attention today because AI-designed medicines are finally producing human clinical results, while pharmaceutical companies are spending substantial amounts to access the technology.
A study published in Cancer Treatment Reviews in October 2026 identified 129 AI-enabled therapeutic assets from 69 companies that had entered human clinical trials by March 1, 2026.
Of those 129 drugs, 103 were small molecules, representing almost 80% of the total. Cancer treatments accounted for 74 candidates, or 57%. Only five had entered or completed Phase 3, showing how young the clinical pipeline remains.
At the same time, large pharmaceutical companies have been signing expensive agreements with AI specialists.
Incyte expanded its partnership with Genesis Molecular AI in May 2026, committing $120 million in upfront consideration. AstraZeneca subsequently agreed to pay insitro $40 million upfront in a collaboration carrying approximately $1.46 billion in potential milestone payments.
The pharmaceutical industry has been experimenting with computational drug discovery for decades. What has changed is the amount of clinical evidence available and the willingness of major drugmakers to commit substantial money to specialized AI platforms.

Our research about AI drug discovery gets updated several times a month, so you always get the latest view of where things stand.
How do we tell which AI drug discovery startups are actually the best?
The best AI drug discovery startups are the ones turning their technology into clinically promising medicines or valuable pharmaceutical contracts. We judge those two achievements separately.
Insilico Medicine, Recursion, Generate Biomedicines, and Iambic Therapeutics are developing their own experimental medicines. These companies can potentially capture a large share of a successful drug's future sales, but they also take on expensive clinical trials and the risk that a treatment fails.
Chai Discovery and Genesis Molecular AI follow a different route. They provide molecular design technology to pharmaceutical companies, allowing them to earn money from research collaborations before the resulting medicines reach patients. Collaboration income now or drug ownership later: we compare which of those models make money in our report on AI drug discovery.
Other companies, including insitro and Owkin, concentrate heavily on understanding disease biology. They help researchers work out which biological processes to target, which patients might benefit, and which experiments deserve attention.
For our ranking, we give the greatest weight to clinical evidence, pharmaceutical payments, the ability to repeat successful discoveries, and access to enough capital to keep operating.
A company with a promising model but no independently demonstrated results cannot be assessed in the same way as one already testing its medicines in patients. Equally, a clinical-stage company with no substantial pharmaceutical partnerships may be a strong drug developer without having proved that its technology can become a widely adopted commercial platform.
Is Insilico Medicine the most successful AI drug discovery startup?
Insilico Medicine currently has one of the strongest claims to leadership in AI-discovered medicines, thanks to rentosertib, an experimental pulmonary fibrosis treatment that has reached Phase 3.
Rentosertib targets TNIK, a protein involved in biological processes associated with idiopathic pulmonary fibrosis, a progressive condition that causes scarring of the lungs.
What makes the treatment particularly interesting is that Insilico used AI to help identify the biological target and generate the molecule designed to act on it.
In June 2025, Nature Medicine published results from a multicenter, randomized, double-blind, placebo-controlled Phase 2a trial.
The group receiving 60 milligrams of rentosertib once daily showed a mean increase of 98.4 milliliters in forced vital capacity after 12 weeks, according to the company's published results.
Forced vital capacity measures how much air someone can exhale after taking a deep breath. It is an important measure of lung function in patients with pulmonary fibrosis.
Insilico started its Phase 3 program in July 2026 and announced that the first patient had received treatment in September. The pivotal program evaluates outcomes over 52 weeks.
That progression puts Insilico ahead of many better-funded competitors in clinical maturity. Still, the Phase 2a trial was relatively small and lasted only 12 weeks. The findings need confirmation in a much larger study before the company can claim a genuine clinical breakthrough.

In our market report about AI drug discovery, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Isomorphic Labs really ahead of Insilico Medicine?
Isomorphic Labs is ahead of Insilico Medicine in disclosed external financing and the scale of its AI platform ambitions, but Insilico currently has stronger human clinical evidence for an AI-discovered drug.
Founded in 2021 as a Google DeepMind spinout, Isomorphic builds on advances in protein structure prediction and the modeling of molecular interactions.
Its AI drug design engine, IsoDDE, aims to help researchers understand biological molecules and design new therapeutic compounds.
Investors have backed that approach on an exceptional scale.
Isomorphic raised $600 million in March 2025, followed by another $2.1 billion in May 2026. Across those rounds, it secured $2.7 billion in disclosed external financing.
The second round alone was 3.5 times the size of the first, reflecting how aggressively investors are backing its research ambitions.
Isomorphic has also established partnerships with Eli Lilly, Novartis, and Johnson & Johnson, giving it access to pharmaceutical development expertise and commercially important research programs.
Yet its clinical progress has been slower than its financial expansion.
Reuters reported in May 2026 that Isomorphic expected to begin its first clinical trials by the end of the year, after previously targeting human testing by the end of 2025.
That leaves a substantial gap between Isomorphic and Insilico in publicly demonstrated clinical maturity.
Isomorphic may eventually build a more widely adopted drug design platform, but its extraordinary financing has created equally extraordinary expectations. Insilico already offers stronger evidence that its AI discovery process can produce a candidate capable of reaching late-stage human testing.
For now, we would put Insilico ahead on demonstrated clinical progress. Isomorphic has the financial resources to challenge that position, but the clinical evidence hasn't caught up yet.
Has Recursion Pharmaceuticals proved its AI drug discovery technology works?
Recursion Pharmaceuticals has produced increasingly convincing evidence that its AI-enabled discovery technology can support useful experimental medicines, although it still needs larger trials to prove those treatments work.
Recursion combines automated biological experiments, cell imaging, machine learning, and chemical design. Its merger with Exscientia in November 2024 added further capabilities in AI-driven medicinal chemistry.
The company's REC-4881 program provides an especially interesting clinical test.
REC-4881 is an experimental MEK1/2 inhibitor being developed for familial adenomatous polyposis, an inherited condition that causes extensive precancerous intestinal polyps.
In October 2026, Recursion reported a median reduction of 47% in total gastrointestinal polyp burden after 12 weeks of treatment. In the upper gastrointestinal tract, the median reduction reached 55%.
Among participants with available follow-up measurements, 85% maintained total polyp burden below baseline after another 12 weeks without treatment.
The efficacy analysis included just 16 evaluable patients in an open-label study, so the findings still need confirmation in a larger controlled trial.
Recursion also has meaningful evidence from its pharmaceutical partnerships.
Sanofi exercised an option on a development candidate originating from their collaboration, generating a $10 million milestone payment. Following that decision, cumulative upfront and milestone payments under the collaboration reached $144 million.
Recursion therefore has something many younger AI drug discovery companies lack: clinical activity in its own pipeline and a pharmaceutical customer that has repeatedly paid to advance partnered research.

In our document detailing everything you need to know about AI drug discovery, you will always find fresh funding data, taken straight from our own verified funding database.
Which AI drug discovery companies have drugs closest to approval?
Insilico Medicine and Generate Biomedicines currently stand out among AI-native companies with Phase 3 drug programs, while Recursion and Iambic Therapeutics remain at earlier stages of clinical development.
Insilico's rentosertib is being evaluated for idiopathic pulmonary fibrosis, a progressive lung disease.
Generate's GB-0895 is being tested in two global Phase 3 trials for severe asthma. The company hopes to develop a treatment that can be administered through a subcutaneous injection twice a year. Which AI-made medicines are in late-stage trials and which are still on paper is mapped in our report covering the AI drug discovery market.
Recursion's REC-4881 has produced encouraging Phase 1b/2 results, while Iambic's IAM1363 is undergoing Phase 1/1b testing in patients with advanced HER2-altered solid tumors.
Those stages carry very different levels of evidence.
Phase 1 studies primarily establish safety and appropriate dosing. Phase 2 trials investigate whether a treatment produces useful effects in patients, and Phase 3 trials generally test those effects in much larger populations.
The way AI contributed to each drug also varies. Some programs use AI to identify biological targets and generate new molecules, while others apply machine learning to optimize proteins or improve decisions during development.
We therefore compare clinical progress alongside the type of AI contribution rather than treating every AI-enabled medicine as the product of an identical discovery process.
| Company | Leading drug | Reported stage | What has been demonstrated |
|---|---|---|---|
| Insilico Medicine | Rentosertib | Phase 3 | Randomized Phase 2a clinical results |
| Generate Biomedicines | GB-0895 | Phase 3 | Advanced clinical development in severe asthma |
| Recursion | REC-4881 | Phase 1b/2 | Polyp reduction in a small patient study |
| Iambic Therapeutics | IAM1363 | Phase 1/1b | Early human testing in oncology |
| Owkin | OKN4395 | Early clinical development | Progress into immuno-oncology development |
| Isomorphic Labs | Internal pipeline | Preclinical | AI-enabled molecular design |
| Xaira Therapeutics | Internal pipeline | Preclinical | AI-based therapeutic design capabilities |
| Genesis Molecular AI | Internal and partnered programs | Discovery/preclinical | Pharmaceutical-supported molecular research |
Is Generate Biomedicines becoming the top AI protein drug company?
Generate Biomedicines has become one of the strongest AI-designed protein therapeutics companies, with an antibody in Phase 3 and a discovery platform attracting pharmaceutical partners.
Generate focuses on engineering proteins with specific biological properties, an approach that differs from the small-molecule discovery strategies used by Insilico Medicine and many of its competitors.
Its platform combines machine learning, protein engineering, and experimental testing. According to the company, researchers have generated, built, and tested more than 42,000 proteins.
That is a substantial experimental foundation. Protein design models need real laboratory results to establish whether their predictions translate into useful biological properties.
Generate's lead candidate, GB-0895, targets thymic stromal lymphopoietin, or TSLP, a protein involved in inflammatory signaling.
The antibody is being developed for severe asthma, with the possibility of a twice-yearly dosing schedule. Generate is also studying the candidate for chronic obstructive pulmonary disease.
The company raised approximately $400 million in its Nasdaq IPO in February 2026, giving it additional resources for clinical trials.
Its commercial relationships extend beyond its own medicines.
In October 2026, Generate announced a collaboration with Zealand Pharma to design protein therapeutics for metabolic diseases. The reported potential deal value reached $1.2 billion, although most of that amount depends on future milestones.
Generate now has an unusually strong combination of late-stage clinical development, extensive protein engineering data, and external pharmaceutical interest.
We consider it one of the clearest leaders in AI-designed biologics. Its combination of a Phase 3 antibody and a substantial experimental protein dataset gives it a more concrete claim to leadership than companies relying mainly on computational benchmarks.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the AI drug discovery market, we look at what broke startups before you, so you don't repeat it.
Why is Chai Discovery attracting so many pharmaceutical companies?
Chai Discovery is becoming one of the most sought-after AI molecular design startups because major pharmaceutical companies are repeatedly choosing its technology for protein and antibody discovery projects.
Chai develops generative AI models designed to create biological molecules with specific structures and properties.
The company's rapid expansion has been accompanied by substantial financial backing.
In July 2026, Chai announced a $400 million Series C round to accelerate its molecular design technology.
But its pharmaceutical partnerships tell us more about customer interest than the financing announcement alone.
Chai announced a collaboration with argenx in July, followed by Bristol Myers Squibb in August and GSK in October.
Endpoints News reported that the GSK agreement represented Chai's sixth pharmaceutical partnership in nine months.
The GSK collaboration followed an experimental laboratory evaluation of Chai's platform, giving the agreement more substance than a purely exploratory announcement.
Six pharmaceutical partnerships in nine months represent unusually rapid customer adoption. Chai has yet to produce the same level of publicly available human clinical evidence as the leading therapeutic developers, but that isn't the primary test of its business model today. Waiting years for human clinical proof is the kind of risk we rate by likelihood in our market report about AI drug discovery.
Is insitro becoming a leader in AI drug discovery?
insitro is currently one of the strongest AI drug discovery companies focused on understanding the biological causes of disease, with a major new AstraZeneca partnership reinforcing its position.
The company uses machine learning and large-scale biological experiments to identify disease mechanisms and promising drug targets.
Its Virtual Human platform aims to determine which biological changes are likely to drive disease rather than merely correlate with it.
That could solve an expensive problem in pharmaceutical research.
Researchers may successfully design a molecule that interacts with a selected protein, only to discover during clinical trials that the protein was never the right target for treating the disease.
insitro wants to improve those decisions before companies commit large amounts to drug development.
In October 2026, AstraZeneca agreed to pay insitro $40 million upfront for a collaboration targeting metabolic dysfunction-associated steatohepatitis, or MASH, and cardiomyopathies.
The agreement also includes approximately $1.46 billion in possible milestone payments and tiered royalties.
Those future milestones are conditional, so the total headline amount should not be confused with money already received.
insitro has also established pharmaceutical relationships with Gilead, Bristol Myers Squibb, and Eli Lilly.
There is a clear commercial opportunity for companies that improve target selection, especially in diseases where the biology is poorly understood.
Genesis and Chai are competing to improve how molecules are designed. insitro is concentrating more heavily on making sure researchers pursue the right biological mechanisms in the first place.
That gives it a distinct position among the leading AI drug discovery startups, particularly if improved target selection eventually translates into fewer expensive clinical failures.

In our research about AI drug discovery, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Could Iambic Therapeutics or Xaira Therapeutics become the next big winners?
Iambic Therapeutics is currently the more clinically advanced challenger, while Xaira Therapeutics has the larger long-term ambition to build an integrated AI system for discovering and developing medicines.
Iambic combines computational molecular design, automated chemistry, and experimental testing.
Its lead drug, IAM1363, is an oral HER2 inhibitor being investigated in patients with advanced HER2-altered solid tumors.
According to the company's SEC registration documents, the treatment was undergoing Phase 1/1b testing as of September 2026.
Iambic has also disclosed IAM217, a KIF18A inhibitor for which it submitted an investigational new drug application, and IAM-C1, a preclinical dual CDK2/4 inhibitor.
Its partnership network includes AbbVie, Takeda, Lundbeck, Bayer, Revolution Medicines, and Jazz Pharmaceuticals.
Iambic raised $150 million in gross proceeds through its October 2026 IPO, giving it additional capital for clinical development.
Xaira is pursuing a much broader technological approach.
Launched in 2024 with more than $1 billion in backing, Xaira combines systems designed to understand disease biology, generate therapeutic molecules, identify relevant patient populations, and automate laboratory experiments.
Its platform includes X-Cell for disease biology, X-Design for molecule generation, and X-Patient for patient-focused analysis.
The company has also described research agents and laboratory automation systems intended to connect these different activities.
Building all those capabilities into one discovery operation is ambitious, but Xaira has yet to demonstrate comparable publicly disclosed human clinical results.
For the moment, Iambic has stronger clinical evidence, while Xaira offers a broader bet on what a future AI-driven pharmaceutical company could look like.
We would favor Iambic on demonstrated progress today. Xaira could ultimately build something much bigger, but it still has more to prove. Neither has established enough late-stage clinical success to displace the leading therapeutic developers.
Which AI drug discovery startups have the strongest pharmaceutical partnerships?
Genesis Molecular AI, Recursion, Chai Discovery, insitro, and Isomorphic Labs currently have some of the strongest pharmaceutical relationships, although the agreements differ considerably in how much money has actually been paid.
Genesis is particularly interesting because it has turned its GEMS molecular AI platform into a substantial commercial relationship with Incyte. Pharma companies signing platform deals are buyers with problems to solve, and we describe them in our AI drug discovery market report.
The companies began collaborating in 2025 and expanded their agreement in May 2026. Under the expansion, Genesis received $120 million in upfront consideration, including $80 million in cash and a $40 million equity investment.
Total upfront consideration across the relationship reached $150 million, according to Genesis.
The expanded partnership covers at least five additional drug targets and gives Genesis access to selected proprietary experimental data from Incyte to help train its models.
That could give Genesis an advantage over competitors relying mainly on publicly available molecular data. The company has also worked with Gilead and raised $200 million in a Series B round in 2023.
Recursion has already received repeated milestone payments from Sanofi, showing that a pharmaceutical customer has continued advancing projects originating from the collaboration.
Chai's strength is the speed at which major drugmakers are signing agreements to evaluate and use its technology.
Isomorphic has relationships with several of the world's largest pharmaceutical companies, while insitro has secured a mix of established collaborations and new research commitments.
Drugmakers are also spreading their AI investments across several providers.
AstraZeneca has relationships with both insitro and Owkin. Sanofi works with Recursion and has also partnered with Owkin on AI-enabled research.
Large pharmaceutical companies currently appear more interested in assembling useful technologies than choosing one provider to handle every discovery problem.
| Company | Pharmaceutical partners | Commercial evidence | Main strength |
|---|---|---|---|
| Genesis Molecular AI | Incyte, Gilead | $150M total upfront consideration from Incyte | Paid molecular AI platform adoption |
| Recursion | Sanofi, Roche/Genentech | $144M cumulative Sanofi upfront and milestone payments | Progress across partnered programs |
| Chai Discovery | GSK, BMS, argenx | Six partnerships in nine months | Rapid customer acquisition |
| insitro | AstraZeneca, Lilly, Gilead, BMS | $40M AstraZeneca upfront payment | AI-driven disease biology |
| Isomorphic Labs | Lilly, Novartis, J&J | Multiple major research partnerships | Molecular AI design technology |
| Generate Biomedicines | Zealand Pharma, Novartis, Amgen | $30M Zealand upfront payment; up to $1.2B in potential milestones | AI protein engineering |
| Iambic Therapeutics | AbbVie, Takeda, Lundbeck, Bayer | Multiple discovery partnerships | AI-enabled medicinal chemistry |
| Owkin | Sanofi, AstraZeneca, Boehringer Ingelheim | Multiple platform and research agreements | AI tools for pharmaceutical research |

If you build or invest in the AI drug discovery market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Are AI-discovered drugs actually more successful in clinical trials?
AI-discovered drugs have shown encouraging early clinical success rates, but the latest research still does not prove that they consistently perform better than conventional drugs in larger clinical trials.
A 2024 analysis published in Drug Discovery Today reported Phase 1 success rates of approximately 80–90% for the AI-discovered molecules included in its sample.
That was encouraging because Phase 1 trials often fail when researchers discover unexpected safety problems or unfavorable behavior in the human body. What has to happen for AI to show higher approval rates, not just good Phase 1 results, is covered under growth drivers in our AI drug discovery report.
However, the same analysis estimated Phase 2 success at approximately 40%, based on limited available evidence.
A newer study published in Cancer Treatment Reviews in October 2026 examined a broader collection of AI-enabled therapeutic programs.
The researchers found an observed Phase 1 success rate of 77.8%, while Phase 2 success stood at 19.5%.
Those figures cannot be compared directly with the earlier analysis because the studies used different samples and observation periods.
A 2026 analysis in Nature Reviews Drug Discovery also raised an important concern: some apparently strong AI drug success rates may reflect the selection of well-understood biological targets rather than AI's ability to solve genuinely difficult disease biology.
We have evidence that AI can contribute to drugs reaching human trials. We still lack enough completed late-stage programs to establish whether it improves the proportion of medicines ultimately approved.
Can AI drug discovery really make medicines faster and cheaper?
AI drug discovery can speed up parts of molecular design and laboratory research, but companies have not yet demonstrated that the entire process of developing an approved medicine becomes dramatically faster or cheaper.
AI can help researchers predict molecular properties, generate candidates, choose experiments, and improve designs.
Clinical trials still require patients, medical monitoring, manufacturing, regulatory oversight, and sufficient time to measure treatment outcomes.
Insilico illustrates the difference. Its AI-enabled discovery process helped produce an advanced therapeutic candidate, yet its pivotal pulmonary fibrosis program must still assess patients over 52 weeks.
Generate Biomedicines provides another example. The company's platform describes protein design-and-testing cycles as short as approximately eight days for certain research activities.
That can be a major improvement in laboratory productivity, but its lead asthma treatment still needs to complete extensive clinical testing.
Recursion has built large experimental and computational systems, while its leading REC-4881 program still faces the work required to prepare and execute a potential registration-enabling trial.
The best-supported efficiency gains today are concentrated in discovery, molecular optimization, and some research decisions.
Developing more candidates quickly could even increase clinical spending if those candidates do not have a better chance of treating patients. The industry still needs to show that faster research produces more successful medicines per dollar spent.

In our document detailing everything you need to know about AI drug discovery, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Could pharmaceutical giants make AI drug discovery startups irrelevant?
Large pharmaceutical companies are unlikely to replace specialized AI drug discovery startups anytime soon, but they could gradually capture more of the industry's value as AI tools become easier to build and use.
The recent partnership activity shows why startups remain important.
Incyte is paying Genesis for specialized molecular AI and access to its discovery capabilities. AstraZeneca is working with insitro on difficult disease biology. Sanofi has committed resources to both Recursion and Owkin for different research applications.
These pharmaceutical companies already have extensive internal scientific teams.
Their willingness to pay external specialists suggests that proprietary datasets, advanced models, and tightly integrated experimental systems still offer capabilities worth buying.
The risk for startups comes as those capabilities become more common.
Large drugmakers control valuable clinical datasets, development infrastructure, manufacturing capacity, and regulatory expertise. They can develop their own AI systems, license foundation models, or work with several specialized providers.
A molecular design platform relying mainly on capabilities available through widely distributed models could eventually struggle to justify premium pricing.
Companies with proprietary experimental data, repeatable laboratory results, deeply integrated customer workflows, or successful internal drug candidates have a better chance of protecting their position.
There is also a financial difference.
A company that owns a successful medicine can potentially receive substantial long-term drug revenue. A technology supplier may receive upfront research payments, milestones, and royalties while its pharmaceutical customers retain greater control over commercialization.
We expect both types of business to survive, although their economics may look very different. The weakest position may belong to companies selling molecular AI capabilities that customers can eventually reproduce themselves, without proprietary data or a differentiated experimental system to protect the business.
AI drug discovery: what are the top startups now?
Insilico Medicine, Isomorphic Labs, Recursion Pharmaceuticals, Generate Biomedicines, and Chai Discovery are our five leading AI drug discovery contenders today, with Genesis Molecular AI, insitro, Iambic Therapeutics, Xaira Therapeutics, and Owkin also deserving serious attention.
Insilico takes the lead in AI-discovered small-molecule clinical progress. Its pulmonary fibrosis program has advanced far enough to test whether encouraging earlier results can hold up in a much larger patient population.
Isomorphic is the strongest contender in capital-backed molecular AI ambition. With $2.7 billion raised across two disclosed external financing rounds, the company has the resources to pursue a particularly ambitious discovery platform. Clinical results now need to catch up with that investment.
Recursion has one of the broadest combinations of experimental infrastructure, clinical activity, and paid pharmaceutical relationships.
Generate is particularly strong in AI-engineered therapeutic proteins, while Chai's recent pace of pharmaceutical partnerships makes it one of the industry's most interesting commercial platform companies.
Genesis and insitro have also shown that pharmaceutical companies will pay meaningful amounts for specialized AI research capabilities. Iambic brings promising early clinical development, Xaira has unusual financial and scientific resources, and Owkin has built a significant position in AI-enabled disease research.
There is still no universal winner.
The clearest divide today is between companies already testing AI-enabled medicines in patients and companies building the technology that many pharmaceutical developers could eventually use.
As seen above, the industry's 129 identified clinical-stage AI-enabled therapeutic assets included only five that had entered or completed Phase 3 by the study cutoff. That puts the sector's progress into perspective.
AI drug discovery is now a real pharmaceutical business, with clinical programs, paying customers, and large financial commitments. Yet the decisive evidence remains limited: the industry still needs more approved medicines and convincing proof that AI improves overall development success rates.
For now, Insilico leads in clinical proof for AI-discovered small molecules, Isomorphic leads in financial backing and platform ambition, and Recursion offers one of the most developed combinations of clinical and partnership evidence. Those are the three companies we would watch most closely for the next major shift in leadership.
Our methodology
To identify the top AI drug discovery startups, we broke the question into five dimensions: clinical progress, scientific validation, pharmaceutical adoption, commercial traction, and financial capacity. We examined each independently, assembled recent evidence from clinical studies, trial developments, company filings, financing announcements, and pharmaceutical agreements, then compared which companies showed the strongest combination of measurable progress.
We placed greater weight on evidence that had survived a meaningful external test. Randomized clinical findings carry more weight than early laboratory results; repeated pharmaceutical payments are stronger evidence of customer commitment than partnership announcements alone; and a large funding round demonstrates financial capacity without proving that a discovery platform works. We also distinguished companies developing their own medicines from those supplying discovery technologies, since their commercial achievements and development risks are fundamentally different.
For clinical comparisons, we examined trial maturity, study design, patient numbers, reported efficacy outcomes, and the extent of independent scientific scrutiny. We used published research to examine whether individual company achievements reflect broader progress across the industry, while keeping early-stage success rates separate from evidence of eventual regulatory approval.
For commercial comparisons, we examined actual upfront consideration, completed milestone payments, the number and quality of pharmaceutical relationships, and evidence that partners continued advancing research programs. Potential future milestones were treated as conditional contract value, not revenue already earned. Financing was considered alongside these measures to assess each company's ability to sustain long and expensive development programs.
Key clinical and scientific sources include Nature Medicine's randomized rentosertib trial, Insilico Medicine's Phase 3 development update, Generate Biomedicines' investor and clinical disclosures, the Cancer Treatment Reviews study of AI-enabled clinical assets, the Drug Discovery Today analysis of clinical success rates, and the Nature Reviews Drug Discovery assessment of clinical translation.
For financial and commercial evidence, we used Isomorphic Labs' initial external financing disclosure and subsequent funding announcement, Iambic's IPO announcement, Incyte's expanded Genesis collaboration, Genesis' partnership disclosures, Recursion's Sanofi milestone announcement, insitro's AstraZeneca agreement, and Generate's Zealand Pharma collaboration.
We also examined Chai Discovery's financing and pharmaceutical partnership announcements, Xaira's integrated discovery platform, Generate's protein engineering technology, and Owkin's AstraZeneca licensing agreement to assess different technological approaches and evidence of industry adoption.
Our conclusions come from bringing these findings together rather than extrapolating from a single funding round, clinical announcement, or technology benchmark. The resulting comparison separates leadership already supported by human clinical evidence from leadership in commercial adoption or financial resources, and makes clear where promising progress still awaits decisive validation.

In our report covering the AI drug discovery market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us