Who are the top conversational AI startups by revenue today?
Everything we know about the conversational AI market, in one place. Get our report whether you build or invest.
Summary
OpenAI’s directly attributable ChatGPT Ads business is the largest conversational AI revenue figure in this ranking at a $1 billion annualized run-rate, while ElevenLabs, Perplexity, Harvey and Glean form the clearest group of large focused startups behind it.
The ranking is messy for a good reason: private AI companies disclose ARR, recognized revenue, annualized revenue and run-rate rather than one standardized metric. The numbers are useful together, but they are not accounting equivalents.
ElevenLabs currently has the strongest directly disclosed figure among independent pure-play conversational AI companies, at more than $500 million ARR. Perplexity is close behind at more than $450 million ARR, while Harvey has crossed $400 million and Glean has reached $300 million.
Enterprise AI is producing more repeatable nine-figure businesses than consumer AI. Harvey, Glean, EliseAI, Sierra, Cresta and several voice-agent companies show that expensive workflows can support large contracts without mass-market user counts.
Voice has become one of the deepest commercial layers in conversational AI. ElevenLabs sits far ahead, but Deepgram, Sanas and Parloa show that speech infrastructure, contact-center automation and real-time voice products can each support meaningful revenue.
Legal AI is unusually monetizable relative to its audience size. Harvey’s more than $400 million ARR and Legora’s estimated scale suggest that a relatively narrow professional user base can still produce very large software businesses when the workflow value is high.
Consumer conversational AI is more uneven. Perplexity, CHAI and Speak have all reached serious scale, but high engagement does not automatically translate into comparable revenue, as the broader consumer-assistant market makes clear.
Several of the largest-looking figures still depend on estimates rather than company disclosures. Manus, OpenEvidence, Legora and Decagon may belong high in the ranking, but their positions deserve less confidence than similarly sized company-reported ARR figures.
Agents are increasingly replacing simple chatbots as the economic center of the category. The largest companies are moving from answering questions toward completing support cases, legal work, internal workflows and other tasks that customers already spend heavily on.
The most important shift is that $100 million is no longer exceptional here. Conversational AI now has a real cohort of nine-figure private companies, with several already in the $200 million to $500 million range and still adding revenue quickly.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

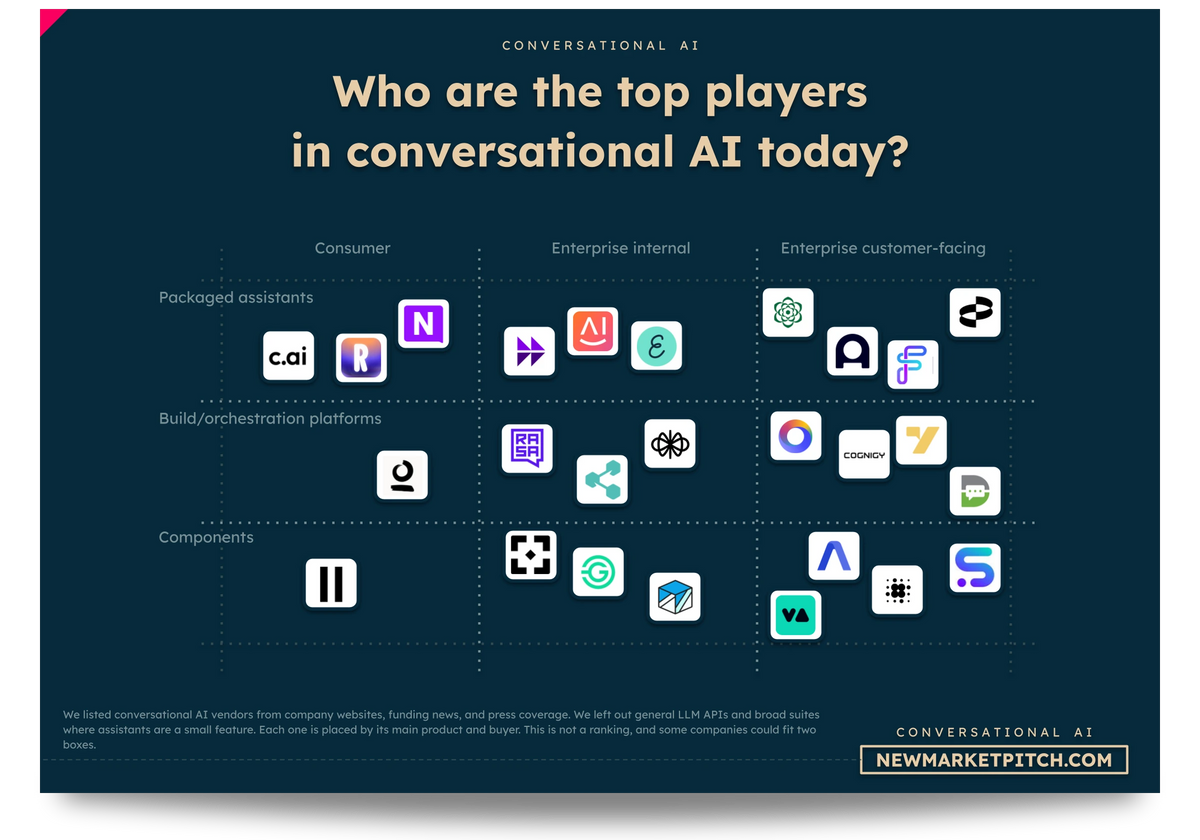
In our report covering the conversational AI market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
The ranking of top startups in the conversational AI market by revenue
Below is a table ranking all the companies in this market by their current revenue scale. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our report covering the Conversational AI Market.
| Ranking | Company | Latest Metric | Metric Type | Freshness | Disclosed When | Source Quality | Confidence | Segment | Why This Ranking | Local Metric | Country |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | OpenAI | $1B | Revenue Run-Rate | Very Fresh · 2mo | Aug 31, 2026 | Company Disclosed | High | Consumer AI Assistant | The in-scope ChatGPT advertising stream alone exceeds every other selected figure. Broader OpenAI/API revenue is deliberately excluded. | us | |
| 2 | ElevenLabs | >$500M | ARR | Very Fresh · 6mo | May 5, 2026 | Company Disclosed | High | Voice AI Infrastructure & Agents | Direct, extremely recent ARR. Below OpenAI's $1B in-scope run-rate but stronger evidence than Perplexity's media-reported figure. | us | |
| 3 | Perplexity | >$450M | ARR | Fresh · 7mo | Apr 2026 | Credible Reported | Medium | Consumer & Enterprise AI Assistant | Slightly below ElevenLabs in scale and source quality, but ahead of Harvey on the disclosed commercial figure. | us | |
| 4 | Harvey | $400M | ARR | Very Fresh · 1mo | Sep 17, 2026 | Company Disclosed | High | Legal AI Assistant | Strong direct executive evidence. Ranks above Manus despite Manus' larger nominal estimate because Harvey's figure is substantially better sourced. | us | |
| 5 | Manus | ~$450M | Annualized Revenue | Very Fresh · 4mo | Jun 1, 2026 | Third-Party Estimate | Low | General AI Agent / Assistant | Larger nominal figure than Harvey, but third-party estimation and the Meta acquisition unwind materially reduce confidence. | sg | |
| 6 | Glean | >$300M | ARR | Very Fresh · 5mo | 2026 | Company Disclosed | High | Enterprise Knowledge Assistant | Direct recent ARR beats the similarly sized OpenEvidence estimate. | us | |
| 7 | OpenEvidence | ~$300M | Annualized Revenue | Very Fresh · 3mo | 2026 | Third-Party Estimate | Low | Medical AI Assistant | Very fresh and large enough to rank ahead of ~$250M businesses, but source quality keeps it below Glean. | us | |
| 8 | Cerence | $252M | Fiscal-Year Revenue | Fresh · 13mo | Nov 20, 2025 | Filed / Audited | High | Automotive Conversational AI | Recognized company-wide revenue and regulatory evidence outweigh Genspark's similarly sized ARR. | us | |
| 9 | Genspark | ~$250M | ARR | Very Fresh · 4mo | Jun 2026 | Company Disclosed | High | General AI Agent / Assistant | Much fresher than Cerence but ARR rather than recognized revenue; decisively above LivePerson on current scale. | us | |
| 10 | LivePerson | $244M | Fiscal-Year Revenue | Fresh · 10mo | Mar 16, 2026 | Filed / Audited | High | Enterprise Conversational AI | High-quality recognized revenue. Slightly below Genspark because its operating period is older and lower. | us | |
| 11 | EliseAI | >$200M | ARR | Very Fresh · 4mo | Jun 10, 2026 | Company Disclosed | High | Vertical Voice & Messaging Agents | Very current direct ARR gives it the edge among the ~$200M group. | us | |
| 12 | Sierra | $200M | ARR | Very Fresh · 4mo | Aug 31, 2026 | Company Disclosed | High | Customer-Service AI Agents | Essentially tied with EliseAI, but Elise's >$200M milestone is slightly stronger. | us | |
| 13 | Uniphore | >$200M | ARR | Fresh · 11mo | Nov 21, 2025 | Company Disclosed | Medium | Enterprise Voice & Agent AI | Comparable scale to Sierra, but older and the business has broadened beyond conversational AI. | us | |
| 14 | Aisera | ~$257M | Annual Revenue | Aging · 22mo | Sep 2, 2026 | Third-Party Estimate | Low | Enterprise AI Assistants | Nominally larger than several companies above, but an aging unsupported estimate is materially weaker evidence. | us | |
| 15 | SoundHound AI | $169M | Fiscal-Year Revenue | Fresh · 10mo | Mar 2, 2026 | Filed / Audited | High | Voice AI Platform | Lower than the $200M ARR cohort, but superior evidence quality to Legora's estimate. | us | |
| 16 | Legora | ~$150M | ARR | Very Fresh · 4mo | 2026 | Third-Party Estimate | Low | Legal AI Assistant | Very fresh but estimated, so it stays below SoundHound's filed revenue. | se | |
| 17 | Deepgram | >$100M | ARR | Very Fresh · 2mo | Aug 12, 2026 | Company Disclosed | High | Voice AI Infrastructure | Strongest and freshest evidence among the ~$100M conversational-infrastructure cohort. | us | |
| 18 | Cresta | >$100M | ARR | Very Fresh · 6mo | Apr 30, 2026 | Company Disclosed | High | Contact-Center AI Agents | Direct company-sourced ARR; slightly older than Deepgram but stronger than estimates below. | us | |
| 19 | CHAI | >$100M | ARR | Very Fresh · 3mo | Jul 12, 2026 | Company Disclosed | High | Consumer AI Companions | Highly current direct figure; sits immediately behind companies explicitly above $100M. | us | |
| 20 | Fin | >$100M | ARR | Fresh · 8mo | Feb 11, 2026 | Company Disclosed | Medium | Customer-Service AI Agents | Strong product-line ARR, but not the entire historical Intercom business, so it ranks below cleaner company-wide figures. | us | |
| 21 | Speak | $100M | ARR | Fresh · 11mo | Nov 12, 2025 | Company Disclosed | High | Conversational Language Learning | Direct but older than the other $100M disclosures above. | us | |
| 22 | Decagon | ~$100M | Annualized Revenue | Very Fresh · 3mo | 2026 | Third-Party Estimate | Low | Customer-Service AI Agents | Exceptionally fresh, but estimated rather than company disclosed, pushing it below Speak. | us | |
| 23 | Cognigy | ~$85M | Annual Revenue | Fresh · 15mo | Jul 28, 2025 | Credible Reported | Medium | Enterprise Conversational AI | Recognized-revenue language beats similarly sized estimates, though acquisition reduces current standalone comparability. | de | |
| 24 | You.com | ~$90M | ARR | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Consumer & Enterprise AI Assistant | Larger than Cognigy nominally, but weaker estimated evidence. | us | |
| 25 | Retell AI | ~$80M | Annualized Revenue | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Voice Agent Infrastructure | Very fresh estimate places it above Wonderful, but below You.com's higher figure. | us | |
| 26 | Wonderful | ~$70M | Annualized Revenue | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Enterprise AI Agents | Current but estimated; below Retell's $80M and above Sanas' directly disclosed $60M. | il | |
| 27 | Sanas | $60M | ARR | Very Fresh · 0mo | 2026 | Company Disclosed | High | Real-Time Conversational Speech AI | Lower amount than Wonderful but substantially stronger source quality. | us | |
| 28 | Moveworks | >$100M | ARR | Aging · 25mo | Sep 24, 2024 | Company Disclosed | Low | Enterprise Employee Assistant | Much larger historical figure than nearby companies, but it is nearly two years old and Moveworks was acquired by ServiceNow. | us | |
| 29 | Parloa | >$50M | ARR | Fresh · 10mo | Dec 18, 2025 | Company Disclosed | High | Voice Customer-Service Agents | Recent direct evidence places it ahead of slightly larger third-party estimates. | de | |
| 30 | Rogo | ~$53M | ARR | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Financial-Services AI Assistant | Very current and slightly larger than Parloa, but third-party estimation keeps it below Parloa. | us | |
| 31 | Langdock | ~$42M | ARR | Very Fresh · 4mo | 2026 | Third-Party Estimate | Low | Enterprise AI Assistant Platform | Fresh estimate; below Rogo on amount and source quality parity. | de | |
| 32 | Inbenta | ~$53.3M | Annual Revenue | Aging · 24mo | 2026 | Third-Party Estimate | Low | Enterprise Conversational AI | Raw estimate exceeds Langdock, but age and weak sourcing materially reduce current relevance. | us | |
| 33 | Kore.ai | >$100M | ARR | Historical · 33mo | Jan 30, 2024 | Company Disclosed | Low | Enterprise Conversational AI Platform | Excellent historical scale signal but now over 30 months old, so it is heavily discounted. | us | |
| 34 | Yellow.ai | $34.8M | Fiscal-Year Revenue | Fresh · 9mo | 2026 | Filed / Audited | Medium | Enterprise Conversational AI | Smaller than historical Kore.ai but much fresher and from a regulatory document. | us | |
| 35 | Wrtn Technologies | ~$33.2M | Annual Revenue | Fresh · 10mo | Apr 14, 2026 | Filed / Audited | High | Consumer AI Assistant | Clean audited revenue places it just behind Yellow.ai. | KRW 47.1B | kr |
| 36 | Character.AI | ~$30M | Annualized Revenue | Fresh · 15mo | 2025 | Third-Party Estimate | Low | Consumer AI Companions | Close to Wrtn numerically but materially weaker evidence. | us | |
| 37 | Loora | >$10M | ARR | Very Fresh · 1mo | Sep 16, 2026 | Company Disclosed | Medium | Conversational Language Learning | Extremely current and direct, but imprecision prevents placing it confidently above Character.AI. | il | |
| 38 | Boost.ai | ~$28.2M | Annual Revenue | Fresh · 10mo | 2026 | Credible Reported | Medium | Enterprise Conversational AI | Stronger revenue evidence than most companies below, though not a formal filing. | ~€25M | no |
| 39 | PolyAI | ~$24M | Turnover | Fresh · 9mo | Jun 7, 2026 | Filed / Audited | High | Enterprise Voice Agents | Filed turnover provides stronger comparability than the nearby startup ARR estimates. | £17.9M | gb |
| 40 | Fish Audio | $21M | ARR | Very Fresh · 3mo | Jul 28, 2026 | Company Disclosed | High | Conversational Speech Infrastructure | Very fresh direct ARR; ranks close to PolyAI because sterling turnover is recognized revenue. | us | |
| 41 | Dust | ~$20M | ARR | Fresh · 7mo | 2026 | Third-Party Estimate | Low | Enterprise AI Assistants | Similar nominal scale to Fish Audio but externally estimated. | fr | |
| 42 | Observe.AI | ~$15.5M | Fiscal-Year Revenue | Aging · 19mo | 2026 | Filed / Audited | Medium | Conversation Intelligence & Agent Assistance | Good financial evidence, but it covers the Indian legal entity rather than clearly the entire global group. | INR 1.34B | us |
| 43 | Hippocratic AI | ~$15.8M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Healthcare Voice AI Agents | Useful current estimate, but weaker than Observe.AI's filed data. | us | |
| 44 | Gnani.ai | ~$15.3M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Enterprise Voice AI | Same evidence class as Hippocratic AI and marginally smaller. | in | |
| 45 | HappyRobot | >$10M | Annual Revenue | Very Fresh · 1mo | Company Disclosed | Medium | Logistics Voice & Messaging Agents | Direct company evidence beats ConverzAI's slightly larger estimate. | us | ||
| 46 | ConverzAI | ~$10.9M | Annual Revenue | Fresh · 10mo | Aug 10, 2026 | Third-Party Estimate | Low | Recruiting Voice AI | Nominally above HappyRobot but weaker third-party sourcing. | us | |
| 47 | fonio.ai | $10M | ARR | Very Fresh · 2mo | Aug 11, 2026 | Company Disclosed | High | Voice AI Agents | Very current direct ARR; below ConverzAI only on reported scale. | at | |
| 48 | Kasisto | ~$10.1M | Annual Revenue | Historical · 34mo | 2026 | Third-Party Estimate | Low | Banking Conversational AI | Similar amount to fonio.ai but dramatically older and weaker. | us | |
| 49 | Vapi | ~$8M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Voice Agent Developer Platform | Recent enough to remain useful, but source quality is limited. | us | |
| 50 | Linq | $8M | ARR | Fresh · 7mo | Mar 26, 2026 | Credible Reported | Low | Messaging-Based AI Assistant | Same nominal amount as Vapi, with a fresher operating metric but less established source provenance. | us | |
| 51 | Maven AGI | $7M | Annual Revenue | Aging · 22mo | Jun 18, 2025 | Company Disclosed | Medium | Customer-Service AI Agents | Direct recognized revenue is valuable, but the period is now aging. | us | |
| 52 | Creative Virtual | ~$6.7M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Enterprise Conversational AI | Current-enough estimate and slightly larger than Slang AI. | gb | |
| 53 | Slang AI | ~$5.9M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Restaurant Voice AI | Below Creative Virtual on the same evidence class. | us | |
| 54 | Hume AI | ~$5.5M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Emotion-Aware Voice AI | The published 2026 forecast is deliberately not used; only the latest historical estimate is ranked. | us | |
| 55 | PlayAI | ~$3.8M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Voice AI Infrastructure | Lower estimate than Hume and standalone relevance is reduced by its acquisition. | us | |
| 56 | Assort Health | ~$3M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Healthcare Voice Agents | Limited revenue evidence, but preferable to non-financial proxies below. | us | |
| 57 | Bolna | $2.1M | Revenue Run-Rate | Very Fresh · 3mo | Jul 22, 2026 | Credible Reported | Low | Voice Agent Platform | Very fresh financial evidence gives it an edge over older/smaller estimates. | in | |
| 58 | CoRover | >$1.39M | Fiscal-Year Revenue | Aging · 19mo | 2025 | Credible Reported | Medium | Enterprise & Government Assistants | Real fiscal revenue, but substantially smaller than the dollar figures above. | >INR 120M | in |
| 59 | Synthflow AI | ~$1.1M | Annual Revenue | Fresh · 10mo | Aug 10, 2026 | Third-Party Estimate | Low | Voice Agent Platform | Financial estimate is weak, but still more directly comparable than user or call counts. | de | |
| 60 | Gradient Labs | $1M | ARR | Fresh · 16mo | Jun 1, 2025 | Company Disclosed | Medium | Financial-Services AI Agents | Direct ARR but materially older than Synthflow's estimated operating period. | gb | |
| 61 | Replika | ~$200K | Monthly Revenue | Very Fresh · 0mo | 2026 | Third-Party Estimate | Low | Consumer AI Companions | Last monetary row. It is a partial monthly app metric and is intentionally not annualized. | us | |
| 62 | Anthropic | 245M monthly active users | Users | Very Fresh · 5mo | Jun 16, 2026 | Third-Party Estimate | Low | Consumer & Enterprise AI Assistant | Company-wide Anthropic revenue is excluded because it mixes general-purpose API revenue; this begins the non-revenue proxy tier. | us | |
| 63 | DeepSeek | ~130M monthly active users | Users | Very Fresh · 5mo | Sep 2026 | Third-Party Estimate | Low | Consumer AI Assistant | Massive assistant adoption, but no sufficiently clean revenue figure; cannot outrank monetary disclosures. | cn | |
| 64 | xAI | ~117M Grok monthly active users | Users | Fresh · 7mo | Jun 2026 | Credible Reported | Low | Consumer AI Assistant | Important assistant business, but xAI's broader model/API economics are outside the clean conversational perimeter. | us | |
| 65 | Avaamo | >5B conversations/month | Other Scale Signal | Very Fresh · 0mo | Company Disclosed | Low | Enterprise Conversational AI | Enormous interaction volume, but conversation counts cannot be translated into revenue. | us | ||
| 66 | DRUID AI | 1.2B conversations/year | Other Scale Signal | Fresh · 10mo | 2025 | Company Disclosed | Low | Enterprise Conversational AI | Strong deployment signal but financially incomparable with Avaamo and all revenue-ranked companies. | ro | |
| 67 | Forethought | >1B customer interactions/month | Other Scale Signal | Fresh · 10mo | Mar 11, 2026 | Credible Reported | Low | Customer-Service AI Agents | Very large activity scale, discounted for missing revenue and acquisition. | us | |
| 68 | Bland AI | 671.8M calls resolved | Other Scale Signal | Very Fresh · 0mo | Company Disclosed | Low | Voice Agent Infrastructure | More useful current evidence than Bland's much older early-stage ARR milestone, but still not revenue. | us | ||
| 69 | WIZ.AI | >100M AI calls/month | Other Scale Signal | Very Fresh · 1mo | Company Disclosed | Medium | Enterprise Voice AI | Strong recurring operational volume and enterprise-client evidence. | sg | ||
| 70 | Hyro | >100M patient interactions | Other Scale Signal | Very Fresh · 0mo | 2026 | Company Disclosed | Medium | Healthcare Conversational AI | Strong vertical deployment scale, but cumulative interactions are not revenue. | us | |
| 71 | Hi Auto | ~100M orders/year | Other Scale Signal | Fresh · 10mo | Dec 2025 | Company Disclosed | Medium | Restaurant Voice AI | Meaningful recurring commercial deployment, but transaction count cannot be converted into sales. | il | |
| 72 | Liberate | >$100B premium volume processed | Other Scale Signal | Fresh · 7mo | Mar 24, 2026 | Company Disclosed | Low | Insurance Voice AI | Large economic throughput, but premium volume belongs to customers and is emphatically not Liberate revenue. | us | |
| 73 | Luzia | >65M users | Users | Fresh · 17mo | May 6, 2025 | Company Disclosed | Low | Consumer AI Assistant | Large consumer footprint but no defensible financial disclosure. | es | |
| 74 | Cartesia | >50K customers | Customers | Fresh · 7mo | 2026 | Credible Reported | Low | Conversational Speech Infrastructure | Customer count is commercially stronger than a generic user count, but customer economics remain unknown. | us | |
| 75 | Manychat | ~1.5M customers | Customers | Fresh · 18mo | Apr 22, 2025 | Credible Reported | Medium | Conversational Commerce & Messaging AI | Huge customer footprint, but its monetization cannot be inferred from customer count. | us | |
| 76 | Zapia | >7M users | Users | Very Fresh · 4mo | Jun 24, 2026 | Company Disclosed | Low | Consumer AI Assistant | Very fresh adoption metric but weaker commercially than paying/customer counts. | ar | |
| 77 | Mistral AI | 1.19M monthly active app users | Users | Very Fresh · 4mo | Jul 2026 | Third-Party Estimate | Low | Consumer & Enterprise AI Assistant | Mistral's model/API revenue is excluded; only its conversational-assistant usage is represented. | fr | |
| 78 | Yoodli | 1M users | Users | Very Fresh · 3mo | Jul 27, 2026 | Company Disclosed | Low | Conversational Coaching AI | Clean recent adoption milestone, but no revenue or paying-user split. | us | |
| 79 | Replicant | >1B automated phone minutes | Other Scale Signal | Fresh · 8mo | Feb 5, 2026 | Company Disclosed | Medium | Contact-Center Voice AI | Revenue growth direction is disclosed but no amount, so the phone-minute metric is retained instead. | us | |
| 80 | Ada | >550 enterprise AI agents | Other Scale Signal | Fresh · 7mo | Mar 3, 2026 | Company Disclosed | Medium | Customer-Service AI Agents | Enterprise deployment signal is credible, but absolute ARR is absent. | ca | |
| 81 | Rasa | ~50M downloads | Other Scale Signal | Historical · 32mo | Feb 2024 | Credible Reported | Low | Conversational AI Developer Platform | Large historical developer footprint but badly stale versus newer proxy metrics. | us | |
| 82 | Hello Patient | >5M patient conversations | Other Scale Signal | Very Fresh · 2mo | Aug 18, 2026 | Credible Reported | Low | Healthcare Voice AI | Very recent deployment evidence, but no customer economics disclosed. | us | |
| 83 | Hostie AI | >2M guest conversations | Other Scale Signal | Very Fresh · 3mo | Jul 8, 2026 | Company Disclosed | Low | Restaurant Voice AI | Useful multi-dimensional commercial scale signal, but still non-financial. | us | |
| 84 | Rime | 1.5M conversation minutes | Other Scale Signal | Very Fresh · 1mo | Company Disclosed | Low | Conversational Speech Infrastructure | Material real-world usage, but minutes have no defensible conversion to revenue. | us | ||
| 85 | Tucuvi | >1M autonomous calls | Other Scale Signal | Very Fresh · 0mo | 2026 | Company Disclosed | Low | Healthcare Voice AI | Strong proof of production use but weaker commercial evidence than customer counts. | es | |
| 86 | Loman AI | >1,000 restaurants | Customers | Very Fresh · 1mo | Company Disclosed | Medium | Restaurant Voice AI | Customer/location deployment is commercially relevant but contract values are unknown. | us | ||
| 87 | Thoughtly | >1,000 GTM teams | Customers | Very Fresh · 1mo | Company Disclosed | Medium | Voice & Messaging Agents | Similar deployment breadth to Loman but less directly tied to a count of physical commercial locations. | us | ||
| 88 | Quiq | >200 enterprise customers | Customers | Very Fresh · 1mo | Company Disclosed | Medium | Enterprise Conversational AI | High-quality enterprise logos/customer count, but substantially fewer disclosed customers than companies immediately above. | us | ||
| 89 | Toma | >200 dealerships | Customers | Very Fresh · 1mo | Company Disclosed | Medium | Automotive Retail Voice AI | Concrete customer deployment, but no financial scale figure. | us | ||
| 90 | Pactum | >60 major brands | Customers | Very Fresh · 1mo | Company Disclosed | Medium | Conversational Procurement Agents | Important specialized conversational-AI vendor, but its disclosed commercial footprint is the smallest comparable customer signal in this ranking. | us |

Our research about conversational AI gets updated several times a month, so you always get the latest view of where things stand.
What are the top conversational AI startups by revenue right now?
The biggest conversational AI startups are already generating hundreds of millions of dollars a year, with ElevenLabs, Perplexity, Harvey and Glean forming the clearest group behind OpenAI’s much larger ChatGPT business.
There is one catch: private AI companies rarely report revenue in the same way. Some disclose ARR, others annualized revenue or run-rate, and a few figures are outside estimates. We kept those labels intact rather than pretending they are interchangeable.
OpenAI also needs special treatment. Its wider business includes subscriptions, enterprise products and APIs that go well beyond conversational AI, so using total company revenue would distort the ranking. The cleanest current figure we found is the $1B annualized revenue run-rate that OpenAI disclosed for ChatGPT Ads.
Among more focused startups, ElevenLabs has passed $500M ARR, the Financial Times reported Perplexity above $450M ARR, Harvey has crossed $400M ARR, and Glean has reached $300M ARR. Genspark, EliseAI and Sierra form another substantial group around $200M–$250M.
Several estimated figures belong in the discussion too. Sacra puts Manus around $450M in annualized revenue and OpenEvidence around $300M. We include them because the businesses appear too large to ignore, but they carry less weight than similarly sized figures disclosed directly by companies.
| Rank | Startup | Best current figure | Metric | Evidence |
|---|---|---|---|---|
| 1 | OpenAI / ChatGPT Ads | $1B | Revenue run-rate | Company disclosed |
| 2 | ElevenLabs | >$500M | ARR | Company disclosed |
| 3 | Perplexity | >$450M | ARR | Financial Times reported |
| 4 | Manus | ~$450M | Annualized revenue | Third-party estimate |
| 5 | Harvey | >$400M | ARR | Founder disclosed |
| 6 | Glean | $300M | ARR | Company disclosed |
| 7 | OpenEvidence | ~$300M | Annualized revenue | Third-party estimate |
| 8 | Genspark | ~$250M | ARR | Company-reported figure |
| 9 | EliseAI | >$200M | ARR | Company disclosed |
| 10 | Sierra | $200M | ARR | Company disclosed |
| 11 | Uniphore | >$200M | ARR | CEO disclosed |
| 12 | Legora | ~$150M | ARR | Third-party estimate |
| 13 | Deepgram | >$100M | ARR | Reported company milestone |
| 14 | Cresta | >$100M | ARR | Company disclosed |
| 15 | CHAI | >$100M | Annual revenue | Company disclosed |
| 16 | Speak | $100M | ARR | Company disclosed |
| 17 | Decagon | ~$100M | Annualized revenue | Third-party estimate |
| 18 | Sanas | $60M | ARR | Company disclosed |
| 19 | Parloa | >$50M | ARR | Company disclosed |
| 20 | Rogo | ~$53M | ARR | Third-party estimate |
Is OpenAI really the largest conversational AI startup by revenue?
OpenAI is clearly the biggest company in conversational AI, although its total revenue is too broad to compare directly with specialist conversational AI startups.
The cleaner number is ChatGPT Ads. OpenAI says that advertising reached a $1B annualized revenue run-rate in fewer than 200 days, with tens of thousands of advertisers already using the platform.
That figure covers only one ChatGPT monetization stream. It leaves out consumer subscriptions, business subscriptions, enterprise contracts and API usage. The full economic scale of ChatGPT is much larger, but we cannot separate every part cleanly enough for a fair startup ranking.
A $1B run-rate also does not mean that OpenAI has already booked $1B of annual advertising revenue. It describes the pace of the business at that point in time.
Even with those limitations, ChatGPT Ads alone currently sits well above the disclosed commercial scale of most standalone conversational AI companies.

In our market report about conversational AI, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is ElevenLabs the biggest pure conversational AI startup?
ElevenLabs currently has the strongest case for being the largest independent pure-play conversational AI startup, with more than $500M in ARR.
The company ended 2025 at $350M ARR and said in May 2026 that it had already moved past $500M during the first four months of the year. Growing by more than $150M from such a large base in a few months is far more meaningful than posting triple-digit growth from a tiny starting point.
Voice agents are now a major part of that expansion. ElevenLabs specifically points to companies using its technology for customer support, sales, hiring and marketing operations.
That makes the company harder to describe as simply a text-to-speech provider these days. ElevenLabs still sells voice infrastructure, but more of that infrastructure is being used inside systems that conduct complete conversations and take actions for businesses.
Its evidence is also unusually clean for a private AI company: the ARR number comes directly from ElevenLabs and is very recent.
Is Perplexity really making more than $450M a year?
Perplexity has become a $450M-plus ARR business, putting the AI search and assistant company surprisingly close to ElevenLabs in commercial scale.
The Financial Times reported that Perplexity moved above $450M ARR after monthly revenue increased about 50% in March 2026. The company now combines consumer subscriptions, enterprise subscriptions and usage-based products.
Perplexity has also been pushing much further into agents. Its Computer product and related tools let users ask the system to carry out work rather than simply return search-style answers.
More than 100 million people use Perplexity monthly according to the same reporting, but the more interesting number for this ranking is how much revenue the company is extracting from that audience and its growing enterprise customer base.
Perplexity still does not publish audited financial statements, so we would place slightly less confidence in its number than in public-company revenue. The Financial Times reporting is strong enough, however, that we treat the $450M-plus ARR figure as credible current evidence rather than a loose market estimate.
How big is Harvey today?
Harvey has crossed $400M ARR, making the legal AI startup one of the largest specialist AI application companies in the world.
Founder Winston Weinberg disclosed that Harvey had passed $400M ARR while serving more than 3,000 customers. He also said that the company now works with 80% of the Am Law 100, 20% of the Fortune 500 and half of the Fortune 10.
Those customer numbers explain how legal AI can become so large without a mass-market audience. Harvey sells into organizations where lawyer time is expensive, contract values can be substantial and the product touches research, drafting, litigation, transactions and compliance.
The business has moved very quickly. Earlier in 2026, Harvey said it added more than $100M of net-new ARR in a single quarter.
Legal AI looks much less niche financially than the size of its user population would suggest. A product used by tens of thousands of professionals can generate the kind of revenue normally associated with software serving millions of people.

In our document detailing everything you need to know about conversational AI, you will always find fresh funding data, taken straight from our own verified funding database.
How did Glean reach $300M ARR so quickly?
Glean has reached $300M ARR only 15 months after crossing $100M, which puts the enterprise AI assistant firmly among the largest companies in this market.
Glean says its Fortune 500 customer count nearly doubled year over year, while more than 85% of customers now use the product across at least five departments.
That second number is particularly useful. Enterprise AI products often begin as isolated experiments inside one team. Glean appears to be spreading across organizations after the initial purchase, which gives the company much more room to grow inside each account.
Glean also shows that conversational AI revenue is not limited to customer-facing bots. Its assistant helps employees search company information, work with internal knowledge and increasingly use agents to carry out tasks across software systems.
The product began in enterprise search, but its current economics increasingly come from becoming a conversational layer over the company’s own information and workflows.
Is voice AI becoming one of the biggest conversational AI businesses?
Voice AI is currently one of the deepest parts of conversational AI, with several independent companies already reaching meaningful eight- or nine-figure revenue scale.
As seen above, ElevenLabs is the standout at more than $500M ARR. Further down the market, Deepgram has moved beyond the $100M level, Sanas says it has grown from zero to $60M ARR since going to market in 2023, and Parloa passed $50M ARR at the end of 2025.
The interesting part is the variety of business models. ElevenLabs sells voice technology and agents across many industries. Deepgram provides voice infrastructure. Sanas works on real-time speech. Parloa builds customer-service agents. Other startups focus specifically on restaurants, healthcare, recruiting, insurance or sales.
Voice works well commercially because businesses already spend huge amounts of money on spoken interactions. Contact centers, medical scheduling, sales calls, collections and restaurant ordering already exist at scale; companies do not need to invent a completely new workflow before buying AI.
Sanas gives us a good example of how fast this can move. The company recently said it had reached $60M ARR and was on track to exceed $120M. That is still a forward-looking target rather than current revenue, so we do not use the higher number in the ranking.
Which customer-service AI startups make the most money?
Sierra and EliseAI currently lead the customer-service and operational-agent group at around $200M ARR or more, while Cresta and Decagon have reached roughly the $100M level.
Sierra says it hit $100M ARR in seven quarters and $200M in nine. EliseAI has passed $200M ARR after five consecutive years of roughly 100% annual growth across housing and healthcare.
Cresta disclosed that it had moved above $100M ARR, while Sacra estimates Decagon around $100M in annualized revenue. Parloa is smaller for now, but its directly disclosed ARR has already passed $50M.
The cluster is more interesting than any individual company. We now have several unrelated startups selling AI into customer conversations and reaching tens or hundreds of millions of dollars in recurring revenue.
Customer service now has much stronger commercial proof than categories where nearly all the revenue sits with one exceptional company.
| Company | Current commercial figure | Main use case | Evidence |
|---|---|---|---|
| EliseAI | >$200M ARR | Housing and healthcare operations | Company disclosed |
| Sierra | $200M ARR | Customer-facing AI agents | Company disclosed |
| Cresta | >$100M ARR | Contact-center AI | Company disclosed |
| Decagon | ~$100M annualized revenue | Customer-support agents | Third-party estimate |
| Parloa | >$50M ARR | Enterprise customer-service agents | Company disclosed |
| Maven AGI | $7M 2024 revenue | Customer-service agents | Company disclosed |
| Replicant | Revenue undisclosed | Contact-center voice automation | Company scale metrics disclosed |

Learning from others' mistakes is the cheapest lesson there is. In our report covering the conversational AI market, we look at what broke startups before you, so you don't repeat it.
Is Sierra really growing that fast?
Sierra is currently one of the fastest-growing enterprise conversational AI startups, doubling from $100M to $200M ARR in only two quarters.
As pointed out above, the company needed seven quarters to reach its first $100M and only two more to reach the second. That is acceleration at a scale where many software companies begin slowing down.
Sierra also says it now works with more than 40% of the Fortune 50, one-third of leading banks and five of the world’s ten largest healthcare companies.
Those are unusually large customers, which changes the math. Sierra does not need millions of paying users if a relatively small number of global companies run high-volume customer interactions through its agents.
The company is also pushing beyond one-off support questions toward longer tasks linked to customer outcomes and revenue. If that model keeps working, contract sizes can expand without Sierra having to chase a completely new customer for every extra dollar of ARR.
Which legal AI startup makes the most revenue?
Harvey is currently the revenue leader in legal AI, while Legora appears to be the closest specialist challenger.
As seen above, Harvey has passed $400M ARR. Legora’s current figure is less certain: third-party research puts the Swedish startup around $150M ARR, following very rapid growth from a much smaller base.
The gap is still large enough that Harvey sits comfortably ahead on the evidence we have today.
Legal AI now supports more than one company at nine-figure scale. That would have sounded aggressive only a few years ago for a software category serving lawyers.
Law firms can buy access to general models such as ChatGPT or Claude. Many are still paying separately for legal products because those products connect the models to firm documents, permissions, research sources and actual legal workflows.
That extra layer is proving valuable enough to build very large businesses.
Which healthcare conversational AI startups make the most money?
OpenEvidence and EliseAI currently show the most commercial scale among healthcare-focused conversational AI startups, although their business models are very different.
Sacra estimates OpenEvidence at roughly $300M in annualized revenue. The figure is not company-filed revenue, so we treat it more cautiously, but the direction is hard to dismiss: the estimate was around $150M at the end of 2025.
OpenEvidence is unusual because clinicians can use much of the product for free. Revenue comes heavily from commercial and advertising relationships around a very large physician audience rather than standard per-seat software alone.
EliseAI takes a more conventional enterprise route. Its agents automate conversations and operational work across housing and healthcare, and the company directly reports more than $200M ARR.
Below those leaders, the market is much younger. Companies such as Hippocratic AI, Assort Health and several healthcare voice-agent startups have strong deployment stories but much thinner public revenue evidence.
For now, healthcare conversational AI looks commercially real, although most of the visible revenue is concentrated in a small number of companies.

In our research about conversational AI, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Are consumer conversational AI startups actually making serious money?
Consumer conversational AI can produce very large businesses, but revenue drops off quickly after a handful of winners.
As we saw previously, Perplexity has already moved above $450M ARR. CHAI says it now generates more than $100M a year, and Speak has crossed $100M ARR with its conversational language-learning product.
CHAI is especially interesting because the team says millions of people use the service every day while the company remains relatively small operationally. That is a very different cost and distribution model from enterprise software.
Speak monetizes another type of consumer conversation: language practice. The company publicly celebrated crossing $100M ARR after years of focusing on AI-driven spoken learning.
Character.AI shows the other side of the market. Its cultural reach and usage have been huge, but the strongest current revenue estimates we found are far below the leaders above.
A popular conversational product can have enormous engagement without turning that engagement into comparable revenue. Consumer scale helps, but pricing, retention and willingness to pay still decide whether that audience becomes a large business.
Where does Anthropic rank among conversational AI startups?
Anthropic is clearly one of the largest companies behind a conversational AI product, but Claude cannot be given a clean revenue rank from public information today.
Anthropic generates money from Claude subscriptions, enterprise deployments and model/API usage. Public revenue reporting generally combines those activities.
Using all of Anthropic’s revenue as “Claude revenue” would therefore credit the conversational assistant with spending that may come from developers calling Anthropic models inside completely different products.
The same perimeter problem appears with other foundation-model companies, which is why we isolate ChatGPT Ads for OpenAI rather than dropping OpenAI’s whole top line into the table.
Claude belongs among the most commercially important conversational AI products. The problem is measurement, not lack of scale.
Until Anthropic breaks out assistant revenue more clearly, placing Claude above or below companies such as ElevenLabs or Perplexity would create false precision.
Can we really compare ARR, revenue and run-rate in one conversational AI ranking?
ARR, recognized revenue and run-rate are useful together for judging conversational AI scale, but they should never be read as if they were the same accounting number.
ARR tells us the annual value of recurring business at a point in time. A startup can finish a year at $200M ARR while recognizing substantially less than $200M of revenue during that year.
A revenue run-rate can be even more sensitive to timing. It often takes the latest pace of business and expresses that pace over twelve months. That is useful for a company growing extremely quickly, but it does not tell us how much revenue has already been recognized.
Fiscal-year revenue is cleaner because it measures what the company actually recognized over a completed period. The drawback is that it can lag badly in a market where a startup may double within months.
That is why we rank with judgment rather than a mechanical sort. A recent, directly disclosed ARR figure can tell us more about a fast-growing private company today than an audited number from two years ago, while an audited revenue figure deserves more confidence than a similarly sized outside estimate.
| Metric | What it tells us | Main limitation |
|---|---|---|
| Fiscal-year revenue | Revenue actually recognized during a completed year | Can become stale quickly |
| TTM revenue | Revenue recognized over the latest twelve months | Rarely disclosed by private startups |
| ARR | Current recurring contract base expressed annually | Not the same as recognized revenue |
| Revenue run-rate | Current revenue pace annualized | Sensitive to the chosen month or period |
| Annualized revenue estimate | Outside estimate of current yearly pace | Depends heavily on source methodology |
| Quarterly revenue | Revenue recognized during one quarter | Seasonal and incomplete |
| Users or customers | Adoption and commercial reach | Cannot be converted into revenue safely |

If you build or invest in the conversational AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
How concentrated is conversational AI revenue at the top?
Conversational AI revenue is already quite concentrated, with a small group of startups accounting for several billion dollars of annualized commercial scale.
Taking the five strongest large disclosed or credibly reported figures in our ranking gives at least about $2.65B of combined annualized scale before adding Manus, OpenEvidence or any Claude-specific revenue.
This is only a directional aggregate. It combines different metrics, so we would never present the total as audited market revenue.
The concentration still tells us something useful. There is a large financial gap between the first group of companies and the long tail of conversational AI vendors still operating below $50M.
At the same time, the market is deeper than one blockbuster. Several companies now sit above $200M, and the list around $100M is getting crowded.
Which conversational AI startups are growing fastest right now?
Genspark, Sierra, Glean, ElevenLabs and EliseAI stand out because they have been adding very large amounts of revenue after already reaching meaningful scale.
Genspark’s reported trajectory is the most extreme. Public reporting around the company puts it near $250M ARR after the Super Agent business ramped from almost nothing in roughly a year. We would still treat that figure with more caution than a formal filing.
As seen above, Glean went from $100M to $300M ARR in 15 months. ElevenLabs moved from $350M at the end of 2025 to more than $500M during the first four months of 2026.
Sierra doubled from $100M to $200M in two quarters, while EliseAI says it has doubled ARR for five consecutive years.
These are stronger growth signals than a young startup moving from $1M to $5M. Every company here has already reached a level where adding another $50M or $100M means winning a substantial amount of real business.
| Startup | Earlier level | Latest level | Approximate interval |
|---|---|---|---|
| Genspark | Near-zero early agent revenue | ~$250M ARR | Roughly one year |
| Glean | $100M ARR | $300M ARR | 15 months |
| ElevenLabs | $350M ARR | >$500M ARR | About four months |
| Sierra | $100M ARR | $200M ARR | Two quarters |
| EliseAI | Roughly half its current ARR | >$200M ARR | About one year |
Does enterprise conversational AI make more money than consumer AI?
Enterprise conversational AI currently produces more large independent companies, while consumer AI produces a smaller number of enormous winners.
Harvey, Glean, EliseAI, Sierra and Cresta are all substantial enterprise businesses. Voice specialists such as Sanas and Parloa add another layer of companies selling directly into corporate budgets.
Consumer AI is much more uneven. Perplexity, CHAI and Speak have built large revenue streams, while ChatGPT sits in a category of its own because of its enormous reach and broader business model.
The difference comes down partly to pricing. An enterprise does not need millions of employees to justify a large contract if an AI product replaces expensive labor, handles customer volume or improves a high-value professional workflow.
Consumer startups can scale distribution much faster, but getting a large percentage of users to pay meaningful amounts is harder.
Right now, enterprise conversational AI looks like the more repeatable path to $50M–$200M businesses. Consumer AI can go much larger, but there are fewer proven examples.

Theory only gets you so far. In our document detailing everything you need to know about conversational AI, we dig up the real signals from the field and show you the ones worth watching.
Are AI agents replacing traditional chatbots as the big revenue opportunity?
AI agents are increasingly where the largest conversational AI startups are finding growth because customers want systems that can finish work, not simply answer a question.
Sierra handles customer interactions and outcomes. Harvey increasingly works across complete legal workflows. Glean combines enterprise knowledge with actions. Cresta and Decagon automate more of the support process rather than stopping after generating suggested text.
Even Perplexity has been pushing beyond search-style answers into products that can carry out tasks.
A chatbot that answers a question may save a few minutes. An agent that resolves the case, updates the relevant system and completes the next step can replace a much larger amount of work.
That gives vendors more room to charge based on outcomes, resolutions, usage or the value of the process being automated.
“Conversational AI” is therefore becoming a broader economic category than chatbots. Conversation remains the interface, while more of the revenue comes from the work executed behind it.
How many conversational AI startups have crossed $100M?
At least a dozen private conversational AI companies now have credible evidence around or above $100M in revenue, ARR or annualized revenue, with several more crossing the line when we include third-party estimates.
The strongest group includes ElevenLabs, Perplexity, Harvey, Glean, Genspark, EliseAI, Sierra, Uniphore, Deepgram, Cresta, CHAI and Speak.
Estimated figures would also bring Manus, OpenEvidence, Legora and Decagon into the nine-figure group.
The exact count depends on how strictly we define conversational AI and how much confidence we require from an estimated figure. That uncertainty should stay visible.
Reaching $100M is no longer an isolated achievement in conversational AI. There is now a real cohort of startups at that scale, and several have continued rapidly toward $200M, $300M or more.
Which conversational AI revenue numbers should we trust most?
The conversational AI figures we trust most are recent numbers disclosed directly by companies or executives and clearly identified as revenue, ARR or another specific financial metric.
ElevenLabs, Glean, EliseAI, Sierra, Cresta, CHAI, Sanas and Parloa all provide relatively clean examples. The companies tell us what the metric is and give enough context to understand the period it represents.
Perplexity also ranks highly in confidence because the Financial Times reported the current ARR figure directly, even though the company has not published audited accounts.
Estimates from firms such as Sacra are useful for companies where no direct number exists. They let us see that OpenEvidence or Manus may belong near the top of the market, but we would not treat an estimated $300M exactly like a company-disclosed $300M.
Old figures deserve another kind of caution. Kore.ai, for example, disclosed more than $100M ARR in early 2024. That tells us the company had already achieved serious commercial scale, but it is now too old to use confidently against businesses reporting fresh numbers.
The best ranking does not simply sort the biggest numbers. It also asks who said the number, what the number measures and how current it still is.

In our report covering the conversational AI market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are new AI startups already bigger than the old conversational AI companies?
Several new conversational AI startups now report annualized commercial scale comparable with or above established public conversational-software companies.
Cerence reported $251.8M of fiscal-year 2025 revenue. LivePerson reported $243.7M for 2025. SoundHound AI reported $168.9M, almost double the previous year.
Those figures are real recognized revenue and come from public financial reporting, so they are cleaner than private-startup ARR.
Yet several much younger companies now sit above those levels on current annualized metrics. That is a remarkable change from the previous conversational AI cycle, when the established vendors had the revenue and newer generative-AI companies mostly had usage and venture funding.
The comparison still needs care. A startup ending the period at $300M ARR has not necessarily recognized $300M during the year, while a listed company reporting $250M of revenue actually booked that amount.
Even after allowing for that difference, newer AI-native companies have clearly reached the same commercial order of magnitude.
What do the biggest conversational AI startups have in common?
The highest-revenue conversational AI startups usually connect conversation to something customers already value enough to pay for.
Harvey connects AI to legal work. Glean connects it to company knowledge and internal workflows. Sierra and Cresta connect it to customer operations. ElevenLabs connects voice to support, sales and communications. Speak connects conversation to language learning.
The strongest consumer exceptions can monetize a huge audience directly through subscriptions, usage or advertising.
This pattern explains why user count alone tells us so little. A specialized product with a few thousand large customers can earn more than a famous consumer application with millions of users.
These days, the conversation itself is rarely the most valuable part of the product. The value comes from the problem sitting behind that conversation: resolving a support case, completing legal work, finding internal information, booking an appointment, learning a language or completing a transaction.
So which conversational AI startups are really the biggest by revenue?
The clearest leaders today are ElevenLabs, Perplexity, Harvey and Glean, while OpenAI remains much larger if we include the directly attributable ChatGPT business.
The next tier is already substantial. Genspark, EliseAI and Sierra have reached roughly the $200M–$250M range, while a growing group including Cresta, CHAI and Speak sits around or above $100M.
Manus and OpenEvidence could belong very high in the ranking too, but their strongest current figures are third-party estimates, so we would not give them the same confidence as a directly disclosed ARR number.
Conversational AI has already produced a real class of nine-figure startups. This market is no longer being measured mainly through users, funding rounds or impressive demos.
Revenue is now large enough to show where companies are actually getting paid, and the strongest businesses currently tend to sit where conversational interfaces meet expensive workflows, enterprise operations or unusually strong consumer monetization.
Our methodology
This analysis ranks conversational AI startups by the best current evidence of revenue scale, rather than forcing every company into one accounting metric. We reviewed company announcements, executive disclosures, regulatory filings, annual reports, investor materials and reputable financial or industry reporting.
Private companies report commercial scale in very different ways, so we considered fiscal-year revenue, TTM revenue, ARR, revenue run-rate, quarterly revenue and annualized revenue estimates when stronger evidence was unavailable. We kept each metric in its original category rather than converting ARR, run-rate or estimates into recognized revenue.
When several disclosures existed for one company, we selected the figure that gave the best evidence of current scale, placing metric relevance first, source quality second and freshness third. A recent ARR figure can be more informative for a fast-growing private startup than an older annual revenue number, but a company filing still deserves more confidence than a similarly sized outside estimate.
We also checked what each number actually covered. OpenAI is the clearest example: instead of treating all OpenAI revenue as conversational AI revenue, we use the directly attributable ChatGPT Ads run-rate because the company’s broader subscriptions, enterprise products and API business extend beyond the conversational product itself.
We did not manufacture revenue from users, customers, subscription prices, traffic or other operating metrics. Older disclosures were kept only when they remained useful context, and estimated figures were marked as estimates rather than blended with company-reported numbers.
Key sources include OpenAI on the ChatGPT Ads annualized run-rate, ElevenLabs on surpassing $500M ARR, ElevenLabs on its earlier 2025 ARR milestone, the Financial Times on Perplexity’s ARR, Harvey founder Winston Weinberg on current ARR and customers, Legal IT Insider on Harvey’s $400M ARR milestone, Harvey on adding more than $100M of ARR in one quarter, Glean on surpassing $300M ARR, EliseAI on surpassing $200M ARR, Sierra on reaching $100M and $200M ARR, Cresta on surpassing $100M ARR, Axios on Cresta’s $100M ARR milestone, Parloa on surpassing $50M ARR, Sanas on reaching $60M ARR, CHAI on more than $100M in annual revenue, Speak on crossing $100M ARR, Cerence’s FY2025 filing, LivePerson’s 2025 filing, and SoundHound AI’s full-year revenue release.

In our research about conversational AI, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us