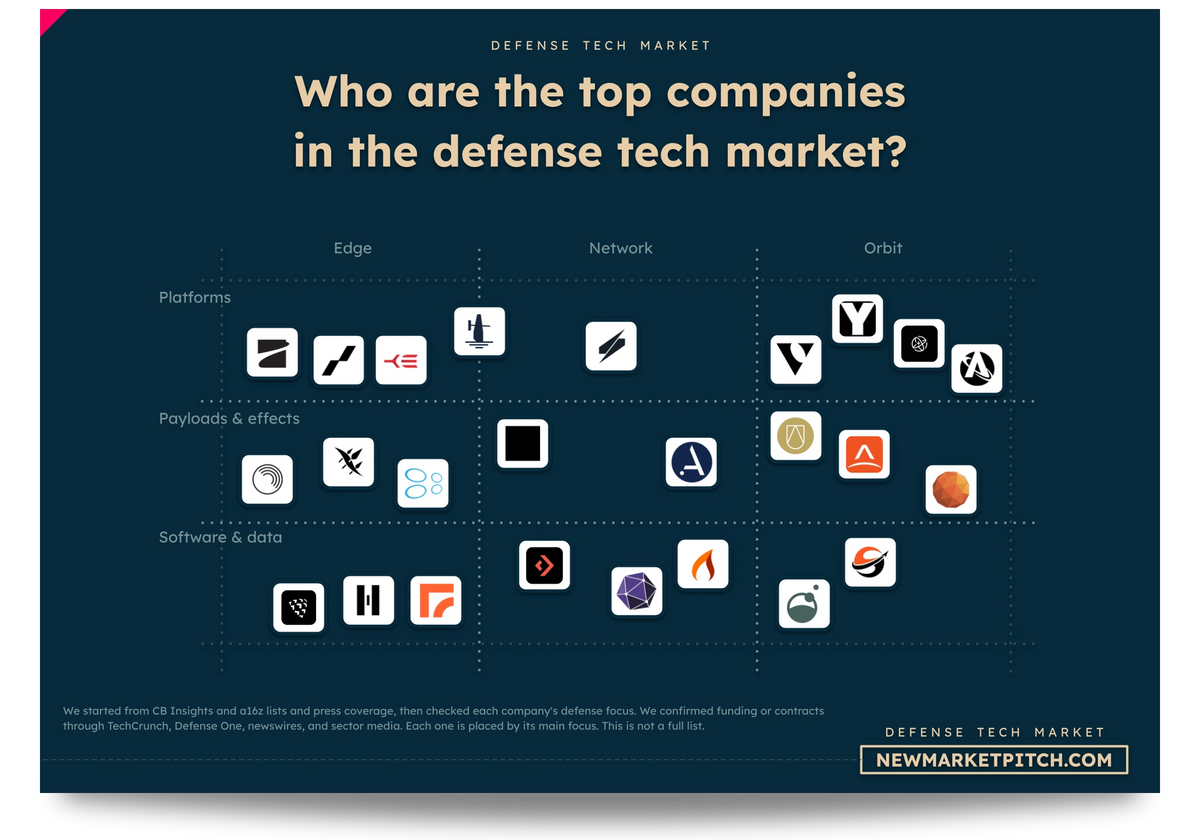
Defense Tech: what are the top startups now?


Every funding round, every investor, and who is really ahead in defense tech, in one document. Have a look ↓
Summary
Anduril is the top defense tech startup today, with Helsing, Shield AI, ICEYE, Quantum Systems, Saronic, and Castelion forming the strongest group of challengers. Anduril leads overall, but several competitors have advantages in specific technologies, battlefield adoption, or commercial execution.
Anduril's lead is backed by actual business scale. The company generated $2.2 billion in revenue in 2025 and reached a $61 billion valuation in May 2026, making it the clearest independent challenger to traditional defense contractors. Anduril's lead is backed by real scale, and we show who is ahead, and who is slipping, in our report on top defense tech companies.
Investor money is heavily concentrated at the top. Anduril, Helsing, Shield AI, ICEYE, and Saronic are collectively valued at more than $110 billion, with Anduril representing roughly 54% of that total. These valuations reflect very different levels of operational and financial maturity.
Government procurement tells a more restrained story. Pentagon obligations to 15 selected defense technology companies grew approximately 139% between fiscal 2023 and fiscal 2025, yet those companies still captured less than 1% of total contract obligations. Startup valuations are moving much faster than defense budgets are being redistributed.
ICEYE and Quantum Systems have some of the strongest evidence of business execution. ICEYE generated an estimated $283 million in 2025 revenue and supplies sovereign satellite capabilities to European governments, while Quantum Systems reported more than 19,000 missions in Ukraine during 2025 alongside profitability.
European military drone manufacturers are becoming serious competitors. TEKEVER has accumulated more than 50,000 operational flight hours in Ukraine and secured a British Army contract framework worth up to £400 million, while Quantum Systems is expanding manufacturing internationally.
Helsing and Shield AI represent a different kind of opportunity: military autonomy that can work across existing and future platforms. Their potential is enormous, but the public financial evidence is less complete, and several of their most ambitious programs still need to prove themselves operationally.
Saronic is attempting to industrialize autonomous naval vessels, while Castelion is entering missile production through U.S. Navy orders worth up to $200 million. Both have moved beyond early demonstrations, although manufacturing reliably at military scale remains their biggest test.
Defense technology valuations are already demanding. Anduril is valued at nearly 28 times its 2025 revenue, while ICEYE's valuation represents roughly 42 times estimated sales. These multiples leave little room for procurement delays, manufacturing problems, or weaker-than-expected demand.
The next winners will probably be determined less by who raises the largest round than by who can repeatedly deliver equipment that militaries actually use. Anduril currently has the strongest overall position, but the market remains early enough for specialists in drones, satellites, autonomy, naval systems, and affordable weapons to build substantial businesses.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us
Which defense tech startups are leading the industry today?
Anduril is currently the strongest defense tech startup overall, followed by a group of serious competitors led by Helsing, Shield AI, ICEYE, Quantum Systems, Saronic, and Castelion.
The gap between these companies and the rest of the sector is getting wider. Several have moved beyond promising prototypes and are now supplying military equipment, winning large government contracts, and building factories to meet demand.
Anduril has the clearest lead. The American company generated $2.2 billion in revenue in 2025 and reached a $61 billion valuation in its latest funding round. Germany's Helsing is valued at $18 billion, while Shield AI and Finland's ICEYE are both worth more than $12 billion. A handful of companies sit far above the rest, and we cover who the top companies are today in our defense tech report.
But those valuations hide some interesting differences.
Quantum Systems reported more than 19,000 missions conducted by its systems in Ukraine during 2025. ICEYE generated an estimated $283 million in revenue while supplying satellite intelligence capabilities to European governments. Saronic has deployed autonomous naval vessels in real military operations, and Castelion recently received a U.S. Navy production order worth up to $200 million.
Anduril looks like the strongest overall company. ICEYE and Quantum Systems stand out for commercial execution, while Shield AI, Helsing, Saronic, and Castelion could become much bigger if their newer programs succeed.
Why are defense tech startups growing so fast right now?
Defense tech startups are attracting record levels of investment because modern warfare has created urgent demand for drones, autonomous weapons, battlefield intelligence, and equipment that can be manufactured quickly.
The war in Ukraine has been particularly important. It exposed how rapidly drones and electronic warfare systems can change battlefield conditions, while also revealing how difficult it is for traditional defense industries to replace equipment consumed in prolonged conflicts.
The Pentagon's Replicator initiative, announced in 2023, was an early response. Its objective was to field thousands of autonomous systems on a much shorter schedule than conventional military procurement programs.
Private investors followed that shift.
According to Dealroom and the NATO Innovation Fund, European defense, security, and resilience startups raised $8.7 billion in 2025, up 55% from the previous year.
The acceleration continued. Anduril raised $5 billion in May 2026, followed by $1.2 billion for Quantum Systems and $1.8 billion for Helsing in July. TEKEVER added a $580 million Series D financing in September.
Yet government procurement has changed much more slowly than venture funding. Traditional contractors still receive the overwhelming majority of defense spending.
Is Anduril the number-one defense tech startup right now?
Anduril is currently the clear number one because no other independent defense startup matches its combination of revenue, military products, funding, and ambition to compete with traditional defense contractors.
Founded in 2017, Anduril initially gained attention for surveillance technology before expanding into autonomous aircraft, counter-drone systems, missiles, underwater vehicles, and military command software.
Its Lattice platform connects sensors, vehicles, and other systems so military operators can control different technologies through a shared software environment.
The company's financial growth has been extraordinary. According to Reuters, Anduril more than doubled its revenue to $2.2 billion in 2025, compared with roughly $1 billion in 2024.
Its valuation also doubled, moving from $30.5 billion in June 2025 to $61 billion in May 2026.
The U.S. Army subsequently established a ten-year enterprise contract framework with Anduril carrying a ceiling of up to $20 billion. That figure represents possible future purchasing capacity rather than guaranteed revenue, but it shows how deeply the company's technology is becoming integrated into military procurement.
Anduril is also investing heavily in its Arsenal-1 manufacturing campus in Ohio, designed to support production of autonomous systems at much greater scale.
At its latest valuation, investors are paying almost 28 times its 2025 revenue. That's expensive for a business with significant hardware operations, even one growing this quickly.
Still, the company has already achieved something most defense startups have yet to demonstrate: substantial revenue across a growing collection of military products.


This is just a preview page. Don’t worry if a number looks old: the report gets refreshed, and you’ll always get the latest version.
Can Helsing become Europe's version of Anduril?
Helsing is currently Europe's strongest broad defense AI challenger to Anduril, although we have much less public information about Helsing's revenue and profitability.
Founded in 2021, the German company started with artificial intelligence software for military applications. It has since moved into autonomous weapons, aircraft technology, underwater systems, and electronic warfare.
Investors have responded aggressively. Helsing raised €600 million in June 2025 at a valuation of approximately €12 billion. A year later, it completed a $1.8 billion financing round valuing the business at $18 billion. Money like this adds up fast, and we look at who has raised the most, and from whom, in our report covering defense tech.
More importantly, European military customers are beginning to place substantial orders.
Germany moved forward with procurement of Helsing's HX-2 loitering munitions under a contract initially reported at approximately €268 million, with additional options potentially worth around €1 billion.
Helsing has also worked with Saab to test its Centaur AI agent on the Gripen E fighter aircraft.
That partnership could be especially important. An autonomy system that works with existing aircraft gives Helsing a way to enter major military programs without manufacturing every vehicle itself.
Anduril already has a large reported revenue base. Helsing has impressive financing and growing government relationships, but the public evidence of its overall financial performance remains thinner.
Is Shield AI winning the race to build autonomous military aircraft?
Shield AI is one of the strongest companies in autonomous military aviation, and its Hivemind software could become more valuable than any single aircraft it develops.
The American company builds systems that allow military aircraft to operate with limited human control, including in environments where GPS signals and communications are disrupted.
Its V-BAT drone provides an established product, while Hivemind is being developed for increasingly sophisticated aircraft.
One particularly revealing development came when the U.S. Air Force selected Shield AI's autonomy software for work connected to its Collaborative Combat Aircraft program.
That program also involves Anduril's Fury aircraft. The Air Force is effectively creating an environment where competing autonomy technologies and aircraft manufacturers can work within the same broader program.
Shield AI strengthened its position further through the acquisition of Aechelon Technology, a specialist in military simulation.
The company then announced that government and private commitments to its X-BAT autonomous fighter program had reached $400 million. According to Shield AI, approximately 500 engineers across the company and its suppliers are working on the aircraft.
That's a serious development program, although X-BAT still needs to complete flight testing and prove its operational performance.
Shield AI's business is already substantial. Fortune reported that the company expected more than $540 million in revenue in 2026, with projected annual growth exceeding 80%.
We see Shield AI's biggest opportunity in Hivemind becoming an autonomous pilot that works across several aircraft manufacturers.
Is Saronic becoming a major competitor to traditional shipbuilders?
Saronic is quickly becoming one of the strongest autonomous naval startups, with real military deployments and an ambitious plan to manufacture larger unmanned vessels.
The Texas-based company builds autonomous surface vessels for surveillance, interception, logistics, and other military missions.
The U.S. Navy wants more ships and maritime capabilities, but conventional shipbuilding is expensive and slow. Autonomous vessels could help expand the fleet without requiring crews on every platform.
Saronic's financing reflects those expectations.
The company raised $600 million at a $4 billion valuation in February 2025. Just over a year later, it raised another $1.75 billion at a $9.25 billion valuation.
The valuation more than doubled in approximately 13 months.
Saronic also has an operational achievement that few defense startups can match.
In June 2026, a Saronic Corsair unmanned vessel helped rescue two American service members after their helicopter went down near the Strait of Hormuz. U.S. Central Command confirmed the operation, according to ABC News.
The vessel was remotely piloted during that mission, so the rescue should not be presented as proof of fully autonomous rescue capabilities. Still, a relatively small unmanned boat proved useful during a real military emergency.
Saronic is now expanding into larger vessels through its Marauder platform and manufacturing operations in Louisiana.
Manufacturing small autonomous boats and building larger military vessels involve different production demands, costs, and integration requirements. Saronic's next test is whether it can handle that transition while keeping its production costs competitive.
Which defense tech startups are worth the most today?
Anduril is by far the most valuable private defense tech company, but the rest of the ranking shows how widely investors are spreading their bets across military AI, satellites, drones, ships, and manufacturing.
The top five companies by their latest disclosed financing valuations, Anduril, Helsing, Shield AI, ICEYE, and Saronic, are collectively valued at more than $110 billion. Together those five are worth over $110 billion; we compare what each company was worth then and now in our report on defense tech.
Anduril alone accounts for roughly 54% of that combined figure.
This is an unusually concentrated market, especially considering how different the companies' products are.
We have included private defense technology companies and specialists with substantial defense exposure. Mature publicly traded businesses such as Palantir are excluded. Some older private companies, such as TEKEVER, are included because they remain important venture-backed challengers.
The figures below are reported funding valuations, not independent estimates of current market value.
| Defense tech startup | Country | Latest reported valuation | Main market |
|---|---|---|---|
| Anduril | United States | $61B | Autonomous defense systems |
| Helsing | Germany | $18B | Military AI and weapons |
| Shield AI | United States | $12.7B | Autonomous aviation |
| ICEYE | Finland | Over $12B | Satellite intelligence |
| Saronic | United States | $9.25B | Autonomous naval vessels |
| Quantum Systems | Germany | ~$8B | Reconnaissance drones |
| Hadrian | United States | ~$7.9B | Automated manufacturing |
| TEKEVER | Portugal / UK | $6.4B | Surveillance drones |
| CHAOS Industries | United States | ~$4.5B | Radar and sensing |
| Skydio | United States | ~$4.4B | Autonomous drones |
Is Quantum Systems one of the most successful military drone startups?
Quantum Systems is currently one of the most convincing military drone startups because its products have extensive battlefield experience and the company reports both rapid growth and profitability.
The German company develops reconnaissance drones, including the Vector system used in Ukraine.
According to Quantum Systems' July 2026 financing announcement, its systems completed more than 19,000 missions in Ukraine during 2025.
That works out to more than 52 missions per day on average. The company did not disclose enough information to determine mission success rates or the total number of active aircraft, but the scale of activity is significant.
Quantum Systems also reported triple-digit revenue growth and double-digit profitability. Although it did not provide detailed public financial statements alongside those claims, profitability sets it apart from many defense startups still financing development through venture capital.
Its international expansion has been rapid, too. Production operations now extend across Germany, Ukraine, the United States, Australia, Romania, the United Kingdom, and the Baltic region.
The company's latest $1.2 billion financing round included major investors such as Blackstone, Airbus, Advent, and Noteus.
Its battlefield experience gives Quantum Systems a strong position as it competes for long-term contracts with NATO members and other international customers.
Is ICEYE already one of the biggest defense space startups?
ICEYE is already a major defense-related space company, and its estimated financial performance makes it one of the more commercially convincing businesses in the sector.
The Finnish company operates synthetic aperture radar satellites that can capture imagery at night and through clouds.
That gives military customers a reliable way to monitor locations even when conventional optical satellites cannot obtain useful images. Radar satellites that see through cloud and darkness fill a gap optical ones leave; we follow what technologies are gaining traction in our defense tech report.
Demand has grown quickly.
According to Sacra, ICEYE generated an estimated $283 million in revenue in 2025, up 116% from approximately $131 million in 2024.
Sacra also estimated EBITDA above $113 million, operating cash flow exceeding $147 million, and a contract backlog of approximately $1.7 billion.
These are third-party estimates rather than audited public-company financial statements, but they suggest an unusually mature business for a venture-backed space company.
ICEYE's manufacturing capabilities are equally important.
Sacra reported that the company had 64 satellites in orbit by March 2026 and could manufacture a launch-ready satellite in approximately 10 to 11 weeks.
The company has also started supplying governments with their own dedicated satellite systems rather than limiting its business to selling intelligence products.
According to ICEYE's June 2026 financing announcement, seven European governments had procured sovereign satellite capabilities from the company.
That creates two complementary revenue opportunities: building satellites for customers and supplying ongoing imagery and intelligence services.
ICEYE currently looks more commercially mature than many highly valued defense AI companies. Its challenge is maintaining that advantage while satellite technology becomes cheaper and competitors increase their own constellations.

This is a preview page. Spotted an outdated number? That’s normal here. The report you get is always the freshest version.
Is TEKEVER becoming another major European defense drone company?
TEKEVER has become one of Europe's strongest military drone manufacturers, and its latest British Army contract gives it a clear path toward much larger government business.
The company was founded in Portugal in 2001 and now operates internationally, with a substantial presence in the United Kingdom.
Its AR3 and AR5 unmanned aircraft have been used for surveillance, reconnaissance, and maritime monitoring.
The company has extensive experience in Ukraine. Reuters reported that TEKEVER systems had accumulated more than 50,000 operational flight hours there since 2022.
Unlike a startup that is still working toward its first deployment, TEKEVER has had several years to improve its products using demanding operational feedback.
The British Army subsequently selected the company's AR5-based technology for the CORVUS surveillance program, with a reported maximum contract value of £400 million over ten years.
That's a significant opportunity, although the ceiling does not guarantee that the full amount will be spent.
TEKEVER's financing has also changed dramatically.
The company raised $580 million in September 2026 at a $6.4 billion valuation, compared with approximately $1.25 billion in its previous major round.
Its reported valuation therefore increased more than fivefold in roughly 16 months.
The Financial Times also reported that TEKEVER had been profitable for more than six years, although the company has not publicly disclosed comparable revenue figures.
We would place TEKEVER alongside Quantum Systems as one of Europe's most credible military drone businesses.
Both have strong operational experience, but TEKEVER's longer history and major UK procurement opportunity make it particularly interesting.
Can Castelion really compete with the biggest missile manufacturers?
Castelion is one of the most promising new missile manufacturers, and its Blackbeard program has already reached a stage that many defense startups never achieve: a U.S. Navy production order.
Founded in 2022 by former SpaceX engineers, Castelion develops hypersonic weapons designed for more affordable, large-scale manufacturing.
The company wants to address a problem that has troubled American defense procurement for years: advanced weapons can be so expensive and difficult to manufacture that military stockpiles become difficult to replenish.
Castelion's contracts show a clear progression.
In February 2026, the Navy selected Blackbeard for its Multimission Affordable Capacity Effector program, awarding approximately $50 million.
In June, Castelion received a $23.4 million pre-production order associated with 50 early operational weapons.
Then came a much bigger step.
In September, the U.S. Navy announced a production delivery order for Blackbeard valued at up to $200 million.
The Navy's fiscal 2027 budget request also included $156 million for 353 MACE missiles, according to reporting by Navy Times.
Blackbeard has now moved into an actual procurement pathway.
Castelion is building Project Ranger, a large manufacturing campus in New Mexico, to support production.
The project also comes with challenges beyond manufacturing. Recent reporting by Wired described concerns among nearby residents about hazardous materials, emergency planning, and industrial safety around the facility.
The company still needs to demonstrate reliable production, successful testing, and a cost structure that works at higher volumes.
For now, Castelion deserves to be ranked among the leading defense startups because the Navy has committed to production. Whether it becomes a lasting competitor to established missile manufacturers depends on successful deliveries.
Preview only. Some numbers may have changed since we made this page, but your report will be up to date.
Are smaller military drones a better business than autonomous fighter jets?
Small military drones currently have clearer evidence of repeat demand than autonomous fighter jets, although advanced aircraft could eventually produce much larger individual contracts.
The differences are easy to see when comparing Skydio, Quantum Systems, and Shield AI. Small drones and autonomous fighters are different businesses, and we compare which business models are winning in our report on top defense tech companies.
Skydio supplies small reconnaissance drones, including the X10D, which the U.S. Army began fielding through its Short-Range Reconnaissance program in 2025.
These systems can be used by smaller military units without requiring the infrastructure associated with conventional aircraft.
They also have a shorter replacement cycle. Battlefield losses, changing electronic warfare threats, and frequent software upgrades can create demand for continuing purchases.
Advanced autonomous combat aircraft face a different development process.
They need extensive flight testing, integration with military weapons, reliable navigation systems, and approval for much more demanding operational missions.
A successful aircraft program can eventually be worth billions, but getting there takes time.
Small drone manufacturers also face difficult economics. Military customers want equipment that is inexpensive enough to replace, and competitors can sometimes reproduce hardware features quickly.
We currently favor the more established small-drone manufacturers for proven demand, while seeing greater technological upside in reusable autonomy platforms for larger aircraft.
Which defense startups could win the counter-drone market?
Epirus and CHAOS Industries are two of the most interesting counter-drone startups, but they tackle different parts of the same military problem.
Cheap attack drones have made air defense much more complicated. Traditional interceptors can be extremely expensive compared with the targets they destroy.
Epirus develops Leonidas, a high-power microwave system designed to disable drone electronics.
Its approach could allow military units to engage multiple drones without firing an expensive missile at each target.
CHAOS Industries focuses more heavily on advanced radar and detection.
Before an air defense system can defeat a drone, it has to detect and track it reliably. That gives CHAOS a different opportunity from companies building weapons.
Neros Technologies and other manufacturers working on cheaper interceptors address another part of the problem.
Epirus is particularly interesting for its specialized weapon technology. CHAOS Industries could benefit from the growing need for more advanced sensing systems, while lower-cost interceptor manufacturers are addressing the economics of physically destroying attacking drones.
Are defense startups actually taking business away from Lockheed Martin and other giants?
Defense startups are winning government contracts much faster than the overall market is growing, but traditional defense contractors still control almost all Pentagon spending.
The clearest comparison comes from the Reagan Foundation's 2026 National Security Innovation Base report.
The study tracked Pentagon contract obligations for 15 major defense technology companies, including Anduril, Shield AI, Saronic, Skydio, Castelion, SpaceX, and Palantir.
Together, their annual contract obligations increased from approximately $1.8 billion in fiscal 2023 to $4.3 billion in fiscal 2025.
That represents growth of roughly 139% over two years.
Over the same period, total Pentagon contract obligations increased from approximately $472 billion to $506 billion, or about 7%.
The difference is striking. The selected defense technology companies grew nearly 20 times faster than the overall procurement market in percentage terms.
Yet their share of Pentagon obligations remained below 1%.
These companies are still small relative to the whole market, but their government business is expanding unusually quickly. It's precisely the combination investors are betting on.
The report also found that SpaceX, Palantir, and Anduril accounted for 84% of the selected group's obligations in fiscal 2025.
That concentration shows how much harder it remains for smaller companies to win substantial procurement spending.
| Pentagon procurement measure | FY2023 | FY2025 |
|---|---|---|
| Obligations to 15 selected defense tech firms | $1.8B | $4.3B |
| Total Pentagon contract obligations | $472.2B | $506.2B |
| Selected firms' market share | 0.4% | 0.8% |
| Spending outside selected firms | ~$470.3B | ~$502.0B |
| Selected firms' cumulative growth from FY2023 | Baseline | ~139% |
| Total Pentagon spending growth from FY2023 | Baseline | ~7% |
| Selected firms' approximate share of incremental spending | - | ~7% |
| Share of selected firms' FY2025 obligations captured by top three | - | 84% |
This is just a preview page. Don’t worry if a number looks old: the report gets refreshed, and you’ll always get the latest version.
Which smaller defense tech startups could become the next big names?
Neros Technologies, Harmattan AI, ARX Robotics, Overland AI, and Auterion are among the younger defense technology companies worth watching now.
They operate in markets where military interest is growing quickly, but most have not yet demonstrated the financial scale of Anduril or the operational maturity of Quantum Systems. Few young startups have reached Anduril's scale yet; we look at who the likely future winners are in our report covering defense tech.
Neros develops tactical drones designed for military use, including systems intended to be produced in large quantities.
Harmattan AI is building autonomous defense technology in France, where demand for domestic military technology has become increasingly important.
ARX Robotics develops unmanned ground vehicles for reconnaissance, logistics, and other military tasks.
Overland AI specializes in autonomous navigation for ground vehicles. Its technologies have been involved in U.S. Defense Innovation Unit programs, giving the company a path toward military deployment.
Auterion takes a software-focused approach. Its technology helps operate and coordinate unmanned systems, potentially allowing it to benefit from drone adoption across multiple hardware manufacturers.
Several other companies also deserve attention because of their positions in fast-growing defense markets.
| Startup | Country | Main technology | What makes it interesting |
|---|---|---|---|
| Neros Technologies | United States | Tactical military drones | Focus on affordable production |
| Harmattan AI | France | Autonomous defense systems | European military AI demand |
| ARX Robotics | Germany | Unmanned ground vehicles | Military logistics and robotics |
| Overland AI | United States | Ground vehicle autonomy | U.S. military development programs |
| Auterion | United States / Switzerland | Drone operating software | Cross-platform autonomy |
| STARK | Germany | Loitering munitions | German military procurement |
| Epirus | United States | Microwave counter-drone weapons | Specialized U.S. military contracts |
| Cambridge Aerospace | United Kingdom | Air defense systems | Demand for cheaper interceptors |
Are defense tech startup valuations getting too high?
Defense tech startup valuations are already pricing in years of strong growth, and some companies will struggle to justify what investors are paying today.
A high valuation tells us that investors expect a company to become valuable. It reveals much less about how many products the company has delivered.
Take three very different businesses.
Anduril already generates billions in annual revenue from a broad range of defense products. Quantum Systems has extensive battlefield deployment experience and reports profitability. Castelion has secured major missile production orders but still needs to demonstrate manufacturing at the scale it is targeting.
Military contracts also need careful interpretation. Governments regularly announce agreements with maximum potential values far above the money initially committed. A $1 billion contract ceiling might cover years of possible purchases without guaranteeing that the full amount will ever be spent.
We therefore give more weight to delivered systems, recurring orders, actual revenue, and operating performance than to headline contract ceilings.
Anduril provides a useful financial benchmark because its revenue is publicly reported.
At $61 billion, the company is valued at approximately 28 times its latest annual revenue.
ICEYE's valuation is even higher relative to its estimated sales. Using Sacra's $283 million revenue estimate and ICEYE's approximately $12 billion funding valuation, the company trades at roughly 42 times historical revenue.
Those multiples are demanding, particularly for businesses with physical manufacturing costs.
The comparison becomes more difficult with other private startups because revenue and profitability disclosures are inconsistent.
Shield AI has published ambitious growth expectations, but comparable audited financial information is unavailable for many of its competitors.
There are reasons investors accept such high prices.
Autonomy software could eventually be used across entire fleets. Satellite intelligence can produce recurring service revenue. Weapons manufacturing could benefit from unusually large long-term procurement programs.
But none of those outcomes is guaranteed, and investors are already paying as though much of that growth will happen.
The bigger risk is that companies are spending heavily on factories, engineers, and product development before government orders become sufficiently predictable.
A delayed military program can create serious financial pressure, even for a company with excellent technology.
Our assessment is that defense technology is experiencing a genuine commercial expansion alongside aggressive financial speculation. Investors are already paying for much of the industry's expected future success.

Defense Tech: What are the top startups now?
Anduril is the top defense tech startup today, followed by Helsing, Shield AI, ICEYE, Quantum Systems, Saronic, and Castelion. However, the companies behind Anduril lead in different technologies, and several have stronger evidence of commercial execution than their public profiles suggest.
Anduril deserves first place for its revenue, wide product range, and ambition to become a major defense contractor.
ICEYE stands out for its satellite intelligence business and reported financial performance. Quantum Systems and TEKEVER are especially convincing in military drones because their aircraft have accumulated extensive operational experience.
Shield AI has one of the strongest positions in autonomous aviation, while Helsing is building the broadest European defense AI platform.
Saronic could become a major autonomous naval manufacturer. Castelion has a credible opportunity to challenge established missile suppliers if it successfully scales Blackbeard production.
The biggest observation from our research is that military procurement is changing much more slowly than startup valuations.
As seen above, a selected group of defense technology companies increased its Pentagon contract obligations by approximately 139% over two years, but still accounted for less than 1% of the total.
That gap is where much of the industry's future opportunity sits. It also shows how early the transformation really is.
Anduril is currently the strongest company. The next leaders will be the startups that can keep delivering useful technology, manufacture it reliably, and turn initial military orders into years of repeat business.
Our methodology
To identify the leading defense tech startups, we broke the central question into six dimensions: financial performance, military adoption, technological capabilities, manufacturing readiness, government procurement, and competitive positioning. We examined recent developments within each dimension, brought together the most relevant evidence, and compared what the findings actually demonstrated about each company's progress.
Our assessment combines different kinds of evidence rather than relying on funding rankings alone. Revenue and profitability help establish business maturity; operational deployments and military procurement help establish customer adoption; production investments and technological developments help assess how far a company can realistically expand. We paid particular attention to the distinction between working systems, funded development programs, and longer-term ambitions.
We also tested the broader industry narrative against Pentagon procurement data. This provided a useful independent check on whether rising private valuations were being matched by changes in government spending. Contract ceilings were distinguished from committed spending, while company-reported operating figures, third-party financial estimates, and disclosed funding valuations were considered according to their respective evidentiary strength.
Our selection covers independent private defense technology companies and venture-backed challengers with substantial military exposure, including some older businesses that remain relevant competitors. The valuation comparison uses the latest publicly reported financing figures rather than estimates of what each company might be worth today. Overall leadership is a qualitative conclusion drawn from the combined evidence, not a mechanical ranking based on valuation or any single performance metric.
Key sources include Dealroom and the NATO Innovation Fund's European investment research, the Ronald Reagan Institute's National Security Innovation Base Report Card, and the U.S. Department of Defense's Replicator announcements. For individual companies, we used Reuters reporting on Anduril's financing and revenue, the U.S. Army's Anduril procurement announcement, Helsing's financing disclosure, Shield AI's financing and acquisition announcement, Shield AI's X-BAT development update, the U.S. Air Force's Collaborative Combat Aircraft update, and Saronic's company announcements.
Additional evidence comes from Quantum Systems' financing and operational disclosure, ICEYE's financing announcement, Sacra's ICEYE financial research, ICEYE's sovereign satellite procurement disclosures, TEKEVER's Series D announcement, TEKEVER's CORVUS contract disclosure, the U.S. Navy's Blackbeard production announcement, and Castelion's earlier delivery-order disclosure.
The resulting assessment reflects the aggregation of these financial, operational, procurement, and technological findings. Giving greater weight to demonstrated execution, while keeping future programs and investor expectations in perspective, allows us to distinguish today's strongest defense companies from those whose leadership still depends on what they deliver next.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us