How big is the edge AI market really?
Building a startup or looking for your next investment in edge AI? Our report gives you the full picture.
Summary
The edge AI market is about $25–30 billion in direct annual revenue today, while the broader computing and device markets influenced by edge AI are already worth several hundred billion dollars.
The biggest source of confusion is not forecasting error. It is scope: some estimates isolate dedicated AI software and accelerators, while others count much more of the processor, device or surrounding edge infrastructure.
Hardware dominates the direct market because local AI needs physical compute in every device that performs inference. Standalone software remains much smaller partly because chipmakers, operating-system vendors and cloud platforms bundle many of the tools developers need.
Smartphones show how adoption can explode faster than monetization. Hundreds of millions of AI-capable phones can ship in a year without making the full value of their processors or handsets new edge AI revenue.
AI PCs reveal the same pattern from another angle. NPUs are becoming standard hardware before local AI applications have proven that users will consistently pay a premium for them.
Removing phones, tablets and PCs does not make the market disappear. Berg Insight already measured more than $10 billion of on-device AI revenue in IoT applications alone, which gives industrial, automotive and embedded edge AI a meaningful commercial base of its own.
Automotive is especially important because revenue per device can be far higher than in consumer electronics. Vehicle volumes are much lower than smartphone volumes, but rising compute content can still create a very large edge AI revenue pool.
Industrial adoption looks more durable than the hype cycle around consumer AI features. Vision inspection, predictive maintenance, robotics and process control have direct operating reasons to run locally when latency, bandwidth or connectivity becomes a constraint.
The $265 billion edge-computing market should not be treated as edge AI revenue. It is better understood as the infrastructure territory around edge AI, with AI taking a growing share of spending that also supports IoT, drones, robotics, AR, VR and other workloads.
A believable growth range for the direct edge AI market is roughly 20–25% a year. Forecasts above 30% can make sense for narrower categories such as software or dedicated accelerators, but small changes in CAGR assumptions create huge differences over a decade.
The path to a $100 billion direct market depends less on putting an NPU into every device than on increasing the amount of semiconductor and software value that buyers are actually willing to pay for because of local AI. Edge AI can become universal without every dollar of that adoption becoming incremental revenue.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the edge AI market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why do estimates of the edge AI market disagree so much?
Edge AI market estimates disagree so badly today because researchers often use the same label for very different businesses.
Look at the latest numbers. Grand View Research values the overall edge AI market at $30 billion for 2026. Its separate report on edge AI chips puts chips alone at $36.2 billion. The same research firm also estimates edge AI accelerators at $13.1 billion and edge AI software at $3.1 billion.
Those figures cannot all describe mutually exclusive pieces of one neatly defined $30 billion market.
The problem becomes clearer when we compare research firms. Estimates for the whole edge AI market tend to land somewhere around the mid-$20 billions to low-$30 billions when using 2025 as the base year. Hardware estimates are much less stable: depending on what gets counted, they range from a few billion dollars to well above $20 billion.
Most of that gap comes from processors.
A dedicated AI accelerator is easy to classify. A smartphone SoC is harder. The chip may contain CPUs, GPUs, connectivity, image processing and an NPU on the same piece of silicon. Some researchers effectively attribute a large share of that processor to edge AI. Others try to isolate the AI-specific component.
Both approaches can produce internally consistent reports while giving us completely different market sizes.
So the first thing we need to fix is the definition. Without that, asking how big edge AI is produces a precise-looking number with a very fuzzy meaning.
What should actually count as edge AI?
Edge AI should cover the hardware, software and services whose value depends materially on running AI close to where data is created.
That includes an accelerator performing vision inference inside a factory camera, an automotive computer interpreting sensor data, software that compresses and deploys models onto embedded processors, or an NPU running local AI features on a phone or laptop.
We should be much more careful with the full value of the surrounding product.
A $1,000 laptop does not become $1,000 of edge AI revenue because it contains an NPU. The same applies to a car, smartphone, robot or industrial machine. AI may make the product more useful and may increase the amount of computing hardware inside it, but most of the selling price still comes from other functions.
Processors create a harder boundary.
Suppose a $100 SoC includes CPU cores, a GPU, modem functions, image processing and an NPU. Counting the full $100 makes sense if we are measuring the market for AI-capable processors. It overstates the answer if we are trying to measure how much money customers are actually spending specifically because of edge AI.
For this article, we use a stricter economic definition. We count technology whose commercial value is materially connected to local AI processing, while avoiding the temptation to absorb the entire value of every AI-capable device.
That gives us a smaller number, but a much cleaner one.
If you want more recent data on this point, please see our latest edge AI market report.

In our research about edge AI, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
How big is the edge AI market today?
The direct edge AI market is probably around $25–30 billion today, with a much larger hardware and infrastructure ecosystem sitting around it.
The latest Grand View Research update is especially useful because it was refreshed recently and puts the market at $24.9 billion in 2025 and $30 billion in 2026. Several other market studies using 2025 as their base year also cluster around the mid-$20 billions.
We should not pretend the range is exact. The definition problem we just discussed makes that impossible.
But the clustering still tells us something. Edge AI has clearly moved beyond a niche technology market. A $25–30 billion category is already comparable in size with major enterprise software or semiconductor segments.
At the same time, calling edge AI a $200 billion or $300 billion market today requires us to include a lot of adjacent spending.
IDC says worldwide edge-computing spending reached $265 billion in 2025. That market includes AI, IoT, drones, robotics, AR, VR, networking and many other workloads. AI is currently one of its fastest-growing parts, but the full $265 billion does not belong to edge AI.
The cleanest answer therefore has two layers. Direct edge AI is around $25–30 billion. The infrastructure and products being influenced by edge AI are already worth several hundred billion dollars.
Which edge AI market estimates can we actually trust?
No single edge AI market estimate deserves to be treated as the definitive number, but estimates become much more useful once we understand exactly what each one is measuring.
The most revealing comparison is between software, accelerators and broader chip estimates.
Grand View Research currently estimates edge AI software at $3.1 billion for 2026. Its edge AI accelerator estimate is $13.1 billion. Its broader edge AI chip estimate reaches $36.2 billion.
That gap tells us more than picking one number and calling the others wrong.
Software has a relatively clear commercial boundary. Model deployment, optimization, inference tooling and device-management software can usually be identified as software revenue.
Hardware gets progressively harder to isolate. An accelerator designed mainly for AI gives us a fairly clean edge AI sale. A general processor containing an NPU creates much more ambiguity. Once entire CPU, GPU or SoC revenue streams enter the calculation, the apparent market grows very quickly.
The figures below should therefore be read as different market boundaries rather than competing measurements of exactly the same thing.
| Market definition | Recent estimate | What it is really measuring |
|---|---|---|
| Total edge AI, Grand View Research | $30.0B in 2026 | Broad hardware, software, infrastructure and services |
| Edge AI software, Grand View Research | $3.1B in 2026 | Dedicated software and related services |
| Edge AI accelerators, Grand View Research | $13.1B in 2026 | Processor products used to accelerate local AI |
| Edge AI chips, Grand View Research | $36.2B in 2026 | Much broader processor category |
| On-device AI for IoT, Berg Insight | $10.1B in 2024 | AI SoCs, accelerators, MCUs and software excluding phones, tablets and PCs |
| Total edge computing, IDC | $265B in 2025 | All edge workloads, not just AI |
| AI infrastructure, IDC | $318B in 2025 | Mostly centralized AI servers and storage rather than edge AI |
If you want more recent data on this point, please see our latest edge AI market report.

In our market report about edge AI, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Is edge AI mostly a hardware market?
Edge AI is currently much more valuable in hardware than in standalone software.
Grand View Research says hardware represented 51.8% of the overall edge AI market in 2025. Its newer accelerator study values that narrower hardware category at $13.1 billion in 2026, compared with only $3.1 billion for dedicated edge AI software.
The reason is easy to see in the products.
Running AI locally requires physical compute in every phone, camera, vehicle, robot, industrial machine or edge server that performs the inference. Adding more capable NPUs, GPUs or other accelerators can raise semiconductor content even when the customer never buys a product labelled “edge AI.”
Software follows a different model.
Qualcomm can provide inference tools to make Snapdragon processors more useful. NVIDIA can bundle software with Jetson and DRIVE platforms. Apple, Microsoft and Google can build local-AI capabilities directly into operating systems and devices. Cloud vendors can include edge deployment tools inside much larger platforms.
A lot of edge AI software is therefore monetized indirectly through hardware, cloud services or broader software subscriptions.
This makes the software market look surprisingly small beside the installed base of AI-capable devices.
The balance could shift over time. Deploying models across thousands of devices and many chip architectures is getting complicated enough that companies may pay more for optimization, monitoring, orchestration and model lifecycle tools.
For now, though, the money sits mainly in silicon.
Are smartphones already the biggest edge AI market?
Smartphones are already the biggest edge AI device category by volume, and their scale explains why broad chip estimates become enormous so quickly.
Counterpoint Research recently forecast that generative-AI-capable smartphones would reach roughly 45% of global smartphone shipments in 2026.
With the smartphone market normally measured in more than a billion units a year, that means hundreds of millions of new local-AI-capable devices can enter the installed base in a single year.
Very few other edge AI categories can approach that volume.
But smartphone penetration also exposes one of the easiest ways to overstate the market.
Consumers were already buying phones before NPUs became important. Qualcomm, Apple, MediaTek and Samsung were already selling high-value application processors. Moving more silicon area toward local AI increases the economic importance of AI, but it does not make the entire processor or handset a brand-new edge AI sale.
The distinction between adoption and incremental revenue matters here.
Edge AI can reach a billion devices while the directly monetized AI layer remains only a fraction of the value of those devices.
Smartphones therefore prove that edge AI has reached mass-market deployment. They do not prove that edge AI itself has suddenly become a hundred-billion-dollar standalone market.

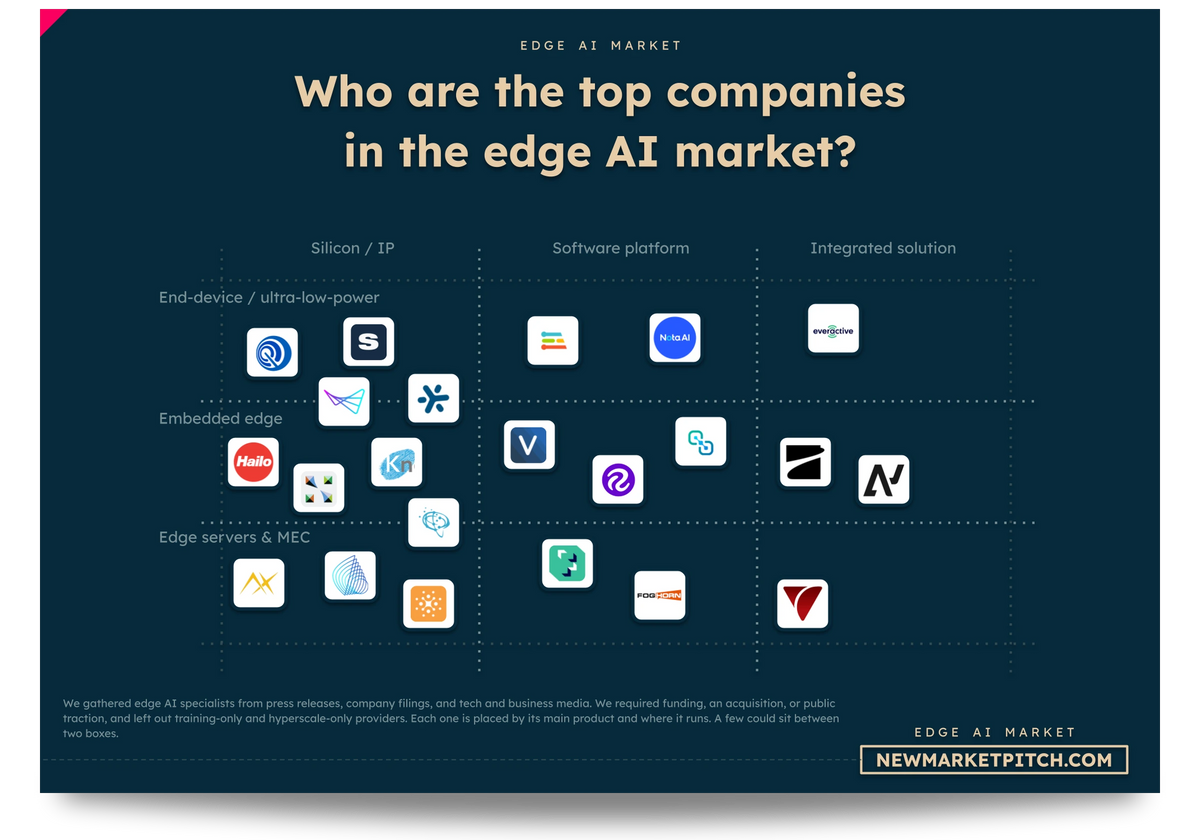
In our document detailing everything you need to know about edge AI, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Are AI PCs creating a real edge AI market?
AI PCs are creating a huge installed base for edge AI, but the actual software value running on those NPUs still trails the hardware rollout.
Gartner forecast 143 million AI PCs in 2026, around 55% of worldwide PC shipments under its earlier definition and shipment outlook.
That sounds like a rapid commercial breakthrough. The newer evidence is more complicated.
In its subsequent PC-market commentary, Gartner said many organizations were still buying AI PCs mainly to future-proof their fleets because local-inference features had yet to deliver major productivity gains compared with cloud AI. Gartner has also warned that rising memory costs are slowing AI-PC adoption and pushing device prices higher.
This is exactly the distinction we need when sizing edge AI.
An NPU can become standard hardware before users find a killer local application for it.
We saw similar transitions with GPUs, Wi-Fi and hardware video engines. Once a capability becomes part of every mainstream processor, customers stop thinking of it as a separate purchase.
AI PCs could follow that path.
The upside comes from software. Gartner has forecast a sharp increase in the share of software vendors prioritizing AI features that run directly on PCs. If those applications become useful enough that companies specifically pay for them, AI PCs will create a much more visible edge AI revenue layer.
As of now, the hardware adoption story is ahead of the monetization story.
If you want more recent data on this point, please see our latest edge AI market report.
How big is edge AI if we remove phones and PCs?
Edge AI is still a $10 billion-plus market even after removing smartphones, tablets and PCs, which is one of the strongest pieces of evidence that this market is broader than consumer-device hype.
Berg Insight estimated that on-device AI solutions for IoT applications generated $10.1 billion in revenue in 2024, up 22% from the previous year.
Its definition includes AI systems-on-chip, systems-on-module, accelerators, AI-capable microcontrollers and specialized on-device AI software. Phones, tablets and personal computers are explicitly excluded.
That makes the number unusually useful.
The remaining market covers industrial systems, vehicles, cameras, embedded equipment and many other connected devices where local inference has a practical reason to exist.
Berg expects this narrower market to reach $30.6 billion by 2029.
The 22% growth already recorded also gives us something stronger than a long-range forecast. Companies were actually buying more on-device AI technology before many of the current edge-AI projections were published.
Once we remove the largest consumer categories, edge AI still looks like a real commercial market with double-digit billions of revenue and strong underlying growth.

Our report covering the edge AI market gets updated several times a month, so you always get the latest view of where things stand.
What do Qualcomm and NVIDIA tell us about real edge AI demand?
Qualcomm and NVIDIA show that edge-oriented computing businesses are already generating billions of dollars, although neither company gives us a clean “edge AI revenue” line.
Qualcomm provides one of the freshest signals.
In its latest reported quarter, Qualcomm generated $1.59 billion from automotive chips and $1.83 billion from IoT. Automotive revenue jumped 61% year over year, while automotive and IoT combined grew 28%.
Qualcomm has now recorded 23 consecutive quarters of double-digit year-over-year automotive revenue growth.
That is more useful than one flashy product announcement. It tells us that high-value computing has been moving into vehicles for years.
NVIDIA shows the same trend from another direction.
Its latest results put company-wide growth overwhelmingly inside data centers, so edge AI is not what drives NVIDIA today. Still, NVIDIA continues expanding DRIVE for vehicles and Jetson for robotics, while its newer physical-AI push is bringing the same accelerated-computing strategy into machines that operate outside data centers.
The contrast is informative.
Cloud AI currently generates vastly more money for NVIDIA. Qualcomm has a much larger direct footprint across phones, vehicles and embedded devices. Both companies are increasing their exposure to local AI workloads, but the economics differ sharply from one product category to another.
Company revenue helps us validate demand, but it does not give us a market-size shortcut.
Is automotive becoming the most valuable edge AI use case?
Automotive is becoming one of the most valuable edge AI markets because each vehicle can absorb far more AI computing value than a typical consumer device.
Grand View Research's latest accelerator study already puts automotive first by end-use revenue, with a 24.8% share of the edge AI accelerator market in 2025.
The company results support that direction.
Qualcomm's automotive business recently reached $1.59 billion in quarterly revenue, up 61% from a year earlier. Earlier in the year, Qualcomm said its automotive design-win pipeline had reached roughly $45 billion.
That pipeline spans more than AI alone, but AI is becoming increasingly central to the product stack through ADAS, automated driving, digital cockpits and software-defined vehicle architectures.
The economics are attractive because cars can carry much more compute per unit than phones.
A premium smartphone may need one integrated processor capable of running local AI. A modern vehicle can use high-performance compute for sensor fusion, driver monitoring, cockpit systems, perception and assisted driving, backed by cameras, radar and other sensors.
Vehicle shipments will never approach smartphone volumes, but they do not need to.
A category selling tens of millions of units can become enormous if computing content per unit rises into the hundreds or thousands of dollars.
Automotive therefore has a strong case for becoming one of edge AI's biggest revenue pools even while consumer electronics remains far larger by unit count.

In our research about edge AI, you will always find fresh funding data, taken straight from our own verified funding database.
Is industrial edge AI actually being used at scale?
Industrial edge AI has moved beyond the demo stage, although most factories still have plenty of deployment work left.
Deloitte's latest large smart-manufacturing survey found that 29% of respondents were already using AI or machine learning at the facility or network level. Another 23% were piloting it.
For generative AI, 24% had reached facility- or network-level deployment and 38% were still running pilots.
Those numbers describe a market somewhere between early adoption and mainstream use.
The strongest industrial applications are also less glamorous than the AI products getting most of the attention online.
Factories use local AI for visual inspection, predictive maintenance, anomaly detection, process control and robotics. These jobs often have a clear reason to stay close to the machine producing the data.
A production line may need to reject a defective component immediately. A robot needs to react locally. A machine generating continuous sensor data may create little value by uploading every raw reading to a distant data center.
Local inference becomes useful when latency, connectivity or data volume creates a real operating constraint.
That helps explain why manufacturing adoption can keep growing even if enthusiasm around consumer AI features cools. The industrial buyer cares less about whether a device is marketed as “AI” and more about whether it catches defects or reduces downtime.
Is computer vision still the biggest practical edge AI workload?
Computer vision remains one of the clearest edge AI businesses today because cameras produce huge amounts of data and often need an immediate local decision.
Grand View Research's newest edge AI software data puts video and image recognition at 19.7% of software revenue in 2025, making it the largest data-type segment.
The economics explain the staying power.
Imagine dozens of factory cameras inspecting products all day. Uploading every high-resolution stream for cloud inference means paying to transmit and process enormous amounts of mostly uninteresting video.
Local inference changes the flow completely. The device can inspect every frame and send only defects, alerts or selected metadata upstream.
The same pattern works in retail, security, traffic management, medical devices, warehouse systems and robots.
Computer vision also benefits from years of deployment experience. Edge AI did not begin with local language models. Vision models were already running close to cameras long before today's generative-AI boom.
That gives the edge market an existing commercial base rather than forcing the entire growth story to depend on a future generation of local AI assistants.

In our market report about edge AI, we look at what the winners do differently, so you can learn from the best instead of guessing.
How much of the $265 billion edge-computing market is actually edge AI?
Only part of the $265 billion spent on edge computing belongs to AI, although AI is currently growing faster than the broader edge market.
IDC says worldwide edge-computing spending reached $265 billion in 2025 and should reach about $450 billion by 2029.
Its spending guide covers more than AI. IDC tracks workloads across AI, IoT, AR, VR, drones and robotics, along with hardware and services needed to support them.
That wider definition explains why IDC's number is almost an order of magnitude above the direct edge AI estimates.
The growth rates add another useful clue.
IDC expects the overall edge market to grow at roughly 15% a year through 2029. AI workloads at the edge are expected to grow closer to 25%.
AI is taking a larger share of an infrastructure market that was already expanding without it.
This is a more believable growth mechanism than assuming edge AI needs to create an entirely new $265 billion category from scratch. Companies are already buying edge servers, networking equipment, gateways and distributed systems. More of that infrastructure can gradually be used for AI.
As we saw above, the useful number for direct edge AI remains much smaller. The $265 billion figure tells us how large the territory around it has become.
Why is edge AI software still only a few billion dollars?
Edge AI software remains surprisingly small because chip companies, device makers and cloud platforms give away or bundle much of the software needed to run AI locally.
Grand View Research currently values dedicated edge AI software at about $3.1 billion for 2026.
Compare that with the firm's $13.1 billion accelerator estimate or $36.2 billion broader chip estimate and the imbalance becomes obvious.
The software itself is doing important work.
Models have to be compressed, quantized and converted. Developers need runtimes and hardware-specific optimization. Companies running thousands of devices need remote monitoring, updates and model management.
The problem is who gets paid separately for those tasks.
NVIDIA uses software to make Jetson and other hardware more attractive. Qualcomm provides tools around Snapdragon platforms. Apple and Google build AI frameworks into their operating systems. Microsoft can push local AI through Windows. AWS and other cloud companies can offer edge management inside wider infrastructure contracts.
A specialized software company therefore competes against functionality that customers often receive as part of something larger.
That keeps the standalone market relatively small even while edge AI usage grows.
There is room for this to change. Supporting the same models across CPUs, GPUs, NPUs and embedded accelerators from different vendors is becoming messy. Companies may eventually pay more for a neutral software layer that makes this complexity disappear.
Software is still the smaller part of the market today, but it may have more room to become genuinely incremental revenue than hardware that is gradually turning into a standard device feature.

If you build or invest in the edge AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Is generative AI really moving from the cloud onto devices?
Generative AI is moving onto phones, PCs and other devices very quickly, but the winning architecture currently looks hybrid rather than fully local.
Hundreds of millions of new phones are gaining local generative-AI capability. AI PCs are moving toward the mainstream. Qualcomm, Apple, MediaTek, Intel and AMD keep dedicating more silicon to neural processing.
The reason is practical.
Small models can handle transcription, summarization, image processing, personalization and private contextual tasks without sending every request to a remote server. Local processing also works when connectivity is poor or latency has to stay extremely low.
Bigger workloads remain harder.
Long reasoning chains, huge models and tasks requiring constantly updated external knowledge can demand more memory and compute than a phone or laptop can sensibly provide.
The cloud also keeps advancing.
IDC says AI infrastructure spending reached $318 billion in 2025, more than double the previous year's level, and expects another large increase in 2026.
So local AI is growing during an even larger cloud infrastructure boom.
We should expect devices to absorb the jobs where privacy, latency, bandwidth or offline use really matter, while data centers continue handling the heaviest work.
That split can make edge AI much bigger without requiring cloud AI to shrink.
Can edge AI really take meaningful business away from cloud AI?
Edge AI can replace a lot of individual cloud inference calls, but it is unlikely to reduce overall cloud AI spending anytime soon.
The scale difference is enormous.
IDC measured $318 billion of AI infrastructure spending in 2025 and now expects roughly $487 billion in 2026. The direct edge AI market sits in the tens of billions.
Even if some voice, vision, summarization or personalization workloads migrate onto devices, companies are simultaneously creating entirely new cloud workloads.
An edge camera might stop sending every video frame to a server. A new AI agent could generate thousands of additional remote inference requests elsewhere in the same company.
The cloud-versus-edge framing can therefore be misleading.
The important question is which workload runs more efficiently where.
Local AI has a strong case when transferring the data creates a clear problem: video bandwidth, privacy, unreliable connectivity, safety-critical latency or continuous sensor streams.
Cloud inference still has the advantage when large shared models, elastic compute and centralized updates matter more.
The total AI workload is growing fast enough for both architectures to expand at the same time.

When you build or invest in the edge AI market, you need clarity, not confusion. In our report covering the edge AI market, we always try to put numbers on and quantify whatever is usually vague and confusing.
Is edge AI already a $100 billion market?
Edge AI is not yet a convincing $100 billion direct market, although several current forecasts put that milestone within reach during the next decade.
Reaching $100 billion today requires us to count a lot of revenue that would exist without edge AI.
We could include most of the $265 billion edge-computing market. We could count complete smartphone processors, AI PCs, automotive computers, cameras and industrial systems.
That produces a very large number, but it blurs the exact thing we are trying to measure.
The current direct-market evidence still centers around tens of billions.
The more interesting question is whether edge AI can genuinely grow past $100 billion without changing the definition.
Grand View Research expects its $30 billion 2026 market to reach $118.7 billion by 2033. Berg Insight expects on-device AI for IoT alone, excluding phones, tablets and PCs, to triple from $10.1 billion in 2024 to $30.6 billion in 2029.
Those forecasts do not require every smart device to become a new market. They require the AI content inside each device to rise and more industrial, automotive and embedded products to perform useful inference locally.
That path looks plausible.
But the milestone depends on customers paying for additional AI compute and software rather than simply receiving NPUs as standard features.
If you want more recent data on this point, please see our latest edge AI market report.
How fast is the edge AI market really growing?
Edge AI appears to be growing at roughly 20–30% a year across several useful measures, while forecasts above 30% should be treated more cautiously.
We have actual growth evidence to work with rather than relying only on distant projections.
Berg Insight measured 22% year-over-year growth in on-device AI revenue for IoT applications. Qualcomm's latest automotive and IoT revenue grew 28% combined. Its automotive business alone rose 61%, although that growth obviously includes more than pure AI.
The broader infrastructure data points in the same direction. IDC expects edge-computing spending to grow around 15% annually through 2029, while the AI portion grows closer to 25%.
Research forecasts for direct edge AI generally sit around the low-to-high 20s, with some estimates going well above 30%.
Thirty percent sounds only moderately higher than 20%, but compounding makes the difference huge. A market growing 20% annually becomes about 6.2 times larger over ten years. At 30%, it becomes almost 14 times larger.
That is why small changes in CAGR assumptions create wildly different long-term market estimates.
We would use something around the 20–25% range as a sensible central case today, with faster growth possible in narrower categories such as accelerators or software where the starting base is still small.
| Market or company signal | Recent growth | What we learn from it |
|---|---|---|
| Berg Insight on-device AI for IoT | +22% YoY | Real market growth excluding phones and PCs |
| Qualcomm automotive + IoT | +28% YoY | Strong growth in edge-oriented chip categories |
| Qualcomm automotive | +61% YoY | Vehicle compute remains exceptionally strong |
| IDC total edge computing | ~15% CAGR to 2029 | Broader edge infrastructure grows more slowly |
| IDC AI workloads at the edge | ~25% CAGR to 2029 | AI is taking a larger share of edge spending |
| Grand View total edge AI | 21.7% CAGR to 2033 | Reasonable broad-market forecast |
| Grand View edge AI software | 29.9% CAGR to 2033 | Smaller software base leaves more room to grow |
| Grand View edge AI accelerators | 31.4% CAGR to 2033 | Dedicated AI silicon has a more aggressive trajectory |

A good product starts with a real problem. In our research about edge AI, we show you the ones customers still live with.
What could make edge AI much bigger than expected?
Edge AI gets much bigger if local AI becomes a standard part of how machines work rather than an occasional accelerator feature.
The biggest opportunity comes from increasing AI content per device.
There are already billions of phones, computers, cameras, vehicles, industrial machines and connected devices in the world. Edge AI does not need another billion completely new products to create a large market.
It can grow by making each existing product more compute-intensive.
A car can move from one basic infotainment processor toward several high-value computing domains. A camera can move from recording video to interpreting everything it sees. A robot can move from programmed movements to continuous perception and decision-making. A laptop can run persistent local agents rather than a handful of NPU-assisted features.
Even a modest increase in AI-related semiconductor and software value across enormous device volumes creates billions of dollars in additional revenue.
The biggest uncertainty is whether users find enough local workloads worth paying for.
Hardware vendors can ship NPUs everywhere. That part is happening already.
The much larger market appears only if software turns that compute into useful tasks often enough that buyers care about the difference.
What could make edge AI smaller than the forecasts?
Edge AI could become technologically universal while producing much less standalone revenue than current forecasts expect.
AI PCs already show how that could happen.
If every mainstream processor eventually contains an NPU, local AI stops being a premium hardware category and becomes part of the normal processor specification.
Customers may use it every day without paying a visible edge AI surcharge.
Software faces the same risk.
Apple, Google, Microsoft, NVIDIA, Qualcomm and cloud providers have strong reasons to bundle edge AI tools into larger ecosystems. Independent vendors then have to charge for functionality that customers may already receive from their operating system, chip supplier or cloud contract.
Cloud inference could also become cheaper faster than expected.
Better accelerators, smaller models and lower inference costs would weaken the financial argument for local processing in workloads where latency, privacy and connectivity are not major constraints.
And managing thousands of distributed devices remains operationally awkward. Models need updates. Hardware generations differ. Devices fail. Security patches have to reach equipment that may stay installed for a decade.
These factors do not threaten edge AI usage itself.
They threaten the assumption that every increase in usage creates an equally large new revenue pool.
That distinction is probably the biggest downside risk hidden inside the more aggressive market forecasts.

Learning from others' mistakes is the cheapest lesson there is. In our market report about edge AI, we look at what broke startups before you, so you don't repeat it.
So how big is the edge AI market really?
The edge AI market is currently about $25–30 billion in direct annual revenue, while the technology is already influencing several hundred billion dollars of broader computing and device spending.
That is the answer that best survives the definition test.
The $25–30 billion range fits the central cluster of recent whole-market estimates. Berg Insight independently shows that on-device AI outside smartphones and PCs was already worth more than $10 billion. Dedicated software is still only a few billion dollars. The much bigger $265 billion edge-computing figure includes plenty of activity unrelated to AI.
At the device level, edge AI is already huge.
Generative-AI phones are heading toward roughly half of smartphone shipments. AI-capable PCs are becoming normal. Qualcomm's automotive business is growing sharply. Manufacturers are deploying AI across real factories rather than limiting it to pilots. Computer vision has years of established commercial use behind it.
Revenue has not caught up with that technological reach.
That gap is the most important thing to understand about edge AI today.
A large percentage of edge AI arrives inside products people would have bought anyway. The next phase depends on whether AI increases semiconductor content, creates software people will pay for and moves more industrial and automotive workloads onto local compute.
If that happens, a direct market above $100 billion during the next decade is credible.
For now, $25–30 billion is the better number to remember: large enough to be a serious global technology market, still small beside cloud AI infrastructure, and increasingly embedded in products whose combined economic value is vastly larger.
If you want more recent data on this point, please see our latest edge AI market report.
Our methodology
This analysis asks one question: how big is the edge AI market really? Because published estimates use different boundaries, we did not start from a preferred headline number. We broke the market into hardware, software, device adoption, company revenue, industrial deployment, surrounding edge infrastructure and observed versus forecast growth.
We treated reported revenue, shipments and measured adoption as current evidence, while using forecasts mainly to understand direction and potential scale. We did not add overlapping market estimates together, and when two figures appeared to conflict, we checked what each source was actually including before using the difference as evidence.
Our core definition counts hardware, software and services whose commercial value is materially connected to running AI close to where data is created. We do not count the full value of a phone, PC, vehicle, robot or industrial machine just because it contains AI-capable hardware.
We also separate direct edge AI revenue from the much larger infrastructure market around it. IDC's edge-computing figures are therefore used as context for the territory in which edge AI operates, not as a substitute for the size of edge AI itself. The same distinction applies to centralized AI infrastructure spending.
Source selection followed the same rule. We prioritized first-hand company disclosures, established market trackers, recent industry surveys and research organizations with clearly defined datasets. Recurring commercial evidence and observed activity carried more weight than individual product launches or distant projections.
Key market-sizing sources include Grand View Research on the overall Edge AI market, Grand View Research on Edge AI accelerators, Grand View Research on Edge AI chips, Grand View Research on Edge AI software, and Berg Insight on on-device AI for IoT applications.
For the wider infrastructure and device context, we used IDC on worldwide edge-computing spending, IDC on AI infrastructure spending, Counterpoint Research on GenAI smartphones, IDC on worldwide smartphone volumes, and Gartner on AI PC adoption, together with Gartner's later update on memory costs and revised AI-PC adoption.
For commercial validation, we used Qualcomm's Q3 FY2026 results, Qualcomm on automotive scale and its design-win pipeline, NVIDIA's Q2 FY2027 results, NVIDIA on Jetson Thor, and Deloitte's Smart Manufacturing Survey.
Finally, we used first-hand technical sources to check what is actually moving onto devices: Apple's foundation-model technical report, Microsoft's local AI documentation for Windows, and AMD's Ryzen AI 300 announcement. The final range comes from where these independent signals converge, not from treating any single market report as definitive.

In our document detailing everything you need to know about edge AI, we try to remove everything that could confuse you, especially if you're investing or building in this market.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us