What are the top generative AI startups by revenue today?
Everything we know about the generative AI market, in one place. Get our report whether you build or invest.
Summary
Anthropic is the top generative AI startup by revenue today, with a reported annualized revenue run-rate above $65 billion, followed by OpenAI at more than $40 billion and Cursor / Anysphere above $4 billion. These three lead a market where dozens of AI startups have already reached nine-figure commercial scale.
Anthropic and OpenAI are in a different league. Anthropic's reported run-rate grew more than sevenfold between December 2025 and July 2026, while OpenAI roughly doubled its annualized revenue between the end of 2025 and August 2026. Even Cursor, the third-largest company in our ranking, remains far behind.
Cursor is arguably the biggest surprise. Its annualized revenue surpassed $4 billion in June 2026, with approximately 75% coming from enterprise customers, before SpaceX acquired the company in August at an implied equity value of $60 billion. AI coding has become a multi-billion-dollar business remarkably quickly.
China now has several serious commercial competitors. Z.ai reached $1.8 billion ARR, Moonshot AI surpassed $1 billion, and DeepSeek's annualized revenue was estimated at $400 million to $500 million. The Chinese market extends well beyond free consumer chatbots.
AI infrastructure is also generating enormous commercial activity. Fireworks AI exceeded $1 billion in revenue run-rate, while Together AI reported annual bookings above $1.15 billion. Those figures cannot be compared directly: bookings measure commitments, whereas revenue run-rate annualizes current sales activity.
Specialized applications are catching up faster than expected. Cognition, Replit and Lovable have reached hundreds of millions in annualized revenue, while Harvey, Glean and Sierra have built substantial enterprise businesses around legal workflows, workplace knowledge and customer service.
Voice and music are no longer tiny experimental categories. ElevenLabs surpassed $500 million ARR in 2026, and Suno reached $300 million ARR with roughly two million paying subscribers. Subscription demand has emerged even in categories facing major copyright and licensing questions.
At least 39 companies in our ranking have a reported commercial-scale figure of $100 million or more. That group includes foundation models, coding tools, model infrastructure, healthcare AI, video generation, enterprise agents and consumer applications, although the underlying metrics differ considerably.
Revenue growth is not the same as profitability. MiniMax reported $116.6 million in recognized revenue during H1 2026, but also an adjusted net loss of $293 million and a gross margin of just 17.9%. The cost of developing and operating models remains a serious constraint.
The biggest lesson from the ranking is that generative AI spending now spans the entire technology stack. Foundation-model companies command the largest revenue figures, but infrastructure providers and specialized applications are building large businesses of their own. The main caution is comparability: ARR, run-rates, bookings, partial-year revenue and third-party estimates all describe different levels of commercial evidence.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

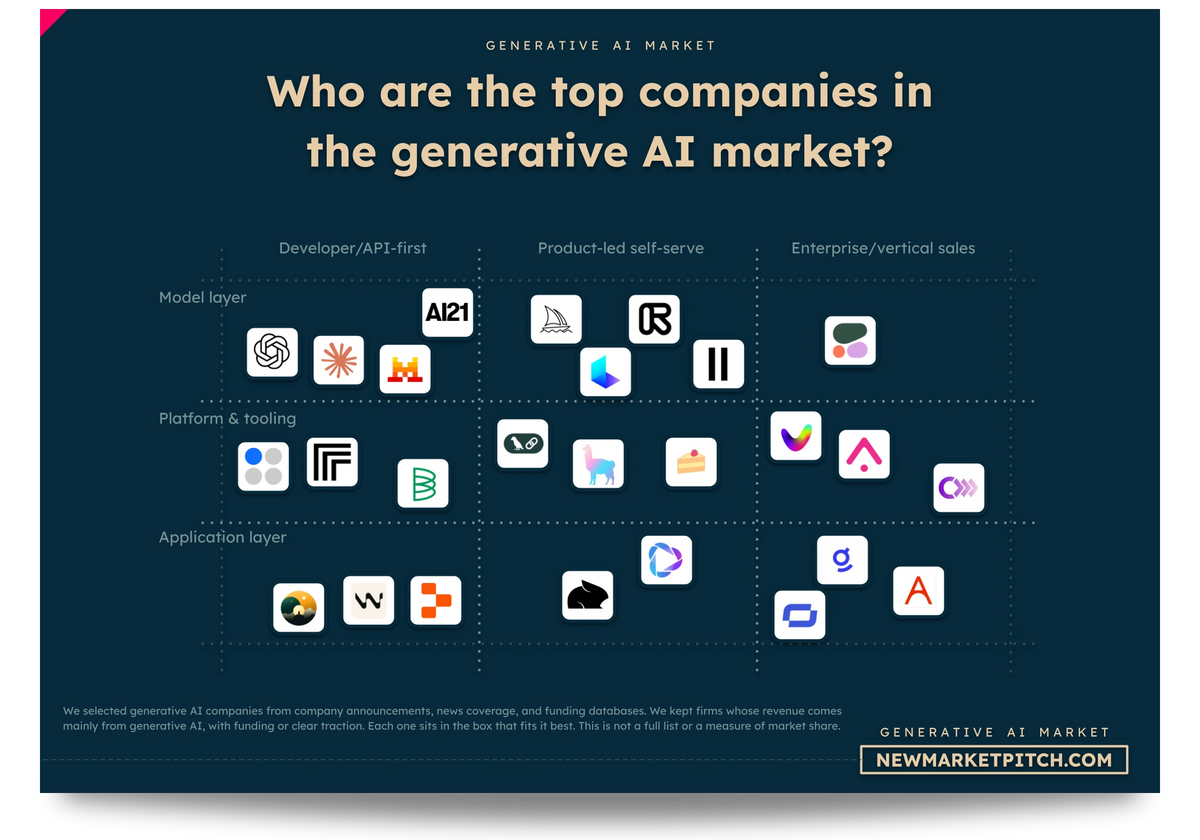
In our report covering the generative AI market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
The ranking of top startups in the generative AI market by revenue
Below is a table ranking the startups of this market by their current revenue scale. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our report on the generative AI market.
| Ranking | Company | Latest Metric | Metric Type | Freshness | Disclosed When | Source Quality | Confidence | Segment | Why This Ranking | Local Metric | Country |
|---|---|---|---|---|---|---|---|---|---|---|---|
| 1 | Anthropic | >$65B | Revenue Run-Rate | Very Fresh · 3mo | Aug 17, 2026 | Credible Reported | Medium | Foundation Models | Largest achieved current commercial metric found; later $100B-$120B figures are forecasts rather than achieved revenue. | us | |
| 2 | OpenAI | >$40B | Revenue Run-Rate | Very Fresh · 2mo | Aug 2026 | Credible Reported | Medium | Foundation Models | Extremely current and large, but below Anthropic's achieved July pace. | us | |
| 3 | Cursor / Anysphere | >$4B | Revenue Run-Rate | Very Fresh · 4mo | Jun 1, 2026 | Credible Reported | Medium | AI Coding | Strong current revenue-scale evidence, far ahead of the next independent coding vendors. | us | |
| 4 | Z.ai / Zhipu AI | $1.8B | ARR | Very Fresh · 1mo | Sep 2026 | Company Disclosed | Medium | Foundation Models | Very current direct executive disclosure; $3B is only year-end guidance and is therefore not used. | cn | |
| 5 | Fireworks AI | >$1B | Revenue Run-Rate | Very Fresh · 3mo | Jul 15, 2026 | Company Disclosed | Medium | Model Infrastructure | Clean, recent company disclosure; outranks Together because the metric is revenue run-rate rather than bookings. | us | |
| 6 | Together AI | >$1.15B | Bookings | Very Fresh · 4mo | Jul 2026 | Company Disclosed | Low | Model Infrastructure | Nominal figure exceeds Fireworks, but bookings are materially weaker evidence of revenue. | us | |
| 7 | Moonshot AI / Kimi | >$1B | ARR | Very Fresh · 2mo | Sep 11, 2026 | Credible Reported | Medium | Foundation Models | Very recent $1B ARR; $2B year-end number is guidance and excluded. | cn | |
| 8 | Cognition | $900M | Revenue Run-Rate | Very Fresh · 2mo | Sep 8, 2026 | Company Disclosed | Medium | AI Coding | Strong current metric following Windsurf acquisition; below $1B-scale vendors but materially above Perplexity. | us | |
| 9 | Perplexity | >$750M | Revenue Run-Rate | Very Fresh · 2mo | Aug 23, 2026 | Credible Reported | Medium | AI Search / Agents | Highly current run-rate, but below Cognition's $900M pace. | us | |
| 10 | SenseTime | ~$328M | Segment Revenue | Very Fresh · 4mo | Aug 26, 2026 | Filed / Audited | Medium | Foundation Models / GenAI Platform | Six months of directly recognized GenAI revenue gets more weight than similar-sized third-party ARR estimates below. | CNY 2.33B | cn |
| 11 | Replit | ~$525M | Revenue Run-Rate | Very Fresh · 6mo | 2026 | Third-Party Estimate | Low | AI Coding | Large current estimate, but weaker provenance keeps it below directly disclosed figures. | us | |
| 12 | ElevenLabs | >$500M | ARR | Very Fresh · 5mo | May 5, 2026 | Company Disclosed | Medium | Generative Audio | Direct and recent ARR disclosure supports placement above less authoritative ~$500M figures. | us | |
| 13 | Lovable | >$500M | Revenue Run-Rate | Very Fresh · 4mo | Jun 9, 2026 | Company Disclosed | Medium | AI Coding / App Building | Extremely fresh, but run-rate rather than recognized annual revenue. | se | |
| 14 | Manus | ~$400–500M | Revenue Run-Rate | Very Fresh · 1mo | Sep 1, 2026 | Credible Reported | Medium | General AI Agents | Current commercial pace places it around DeepSeek/Harvey, but disclosed as a range. | sg | |
| 15 | DeepSeek | ~$400–500M | Revenue Run-Rate | Very Fresh · 0mo | 2026 | Credible Reported | Medium | Foundation Models | Similar scale to Manus, with recognized Jan-Jul revenue also reported but substantially lower because it covers historical months rather than the latest pace. | cn | |
| 16 | Harvey | >$400M | ARR | Very Fresh · 1mo | Sep 9, 2026 | Company Disclosed | Medium | Legal GenAI | One of the freshest direct ARR disclosures in the application layer. | us | |
| 17 | Mistral AI | >$400M | ARR | Fresh · 8mo | Feb 2026 | Company Disclosed | Medium | Foundation Models | Same broad scale as Harvey but noticeably older. | fr | |
| 18 | fal | ~$400M | Revenue Run-Rate | Fresh · 8mo | 2026 | Third-Party Estimate | Low | Generative Media Infrastructure | High estimated scale, but weaker source quality than Harvey and Mistral. | us | |
| 19 | Glean | $300M | ARR | Very Fresh · 5mo | May 28, 2026 | Company Disclosed | Medium | Enterprise GenAI | Strong direct figure, but ARR definition includes consumption economics. | us | |
| 20 | Suno | $300M | ARR | Fresh · 8mo | Feb 2026 | Company Disclosed | Medium | Generative Music | Direct ARR equals Glean's headline number but is several months older. | us | |
| 21 | OpenEvidence | ~$300M | Revenue Run-Rate | Very Fresh · 3mo | Sep 18, 2026 | Third-Party Estimate | Low | Healthcare GenAI | Very fresh, but third-party provenance places it behind equally sized direct disclosures. | us | |
| 22 | Midjourney | ~$300M | Annual Revenue | Aging · 22mo | 2026 | Third-Party Estimate | Low | Generative Images | Large figure but materially stale in a fast-moving market, so it receives a strong freshness penalty. | us | |
| 23 | Genspark | ~$250M | Revenue Run-Rate | Fresh · 7mo | 2026 | Third-Party Estimate | Low | AI Search / Agents | Current enough to be useful, but an estimate rather than direct disclosure. | us | |
| 24 | Cohere | $240M | ARR | Fresh · 10mo | Feb 13, 2026 | Credible Reported | Medium | Foundation Models | More authoritative than many estimates below, although the operating period is older. | ca | |
| 25 | Sierra | $200M | ARR | Very Fresh · 5mo | Aug 1, 2026 | Company Disclosed | Medium | Customer-Service AI Agents | Direct $200M ARR gives it an edge over similarly sized estimated businesses. | us | |
| 26 | HeyGen | >$200M | ARR | Very Fresh · 4mo | Jun 25, 2026 | Company Disclosed | Medium | Generative Video | Very recent and directly disclosed; comparable to Sierra. | us | |
| 27 | Base44 | >$200M | ARR | Very Fresh · 2mo | Aug 20, 2026 | Company Disclosed | Medium | AI App Building | Newer than Sierra/HeyGen but product-level rather than a fully independent company perimeter. | il | |
| 28 | MiniMax | $117M | Half-Year Revenue | Very Fresh · 4mo | Aug 2026 | Filed / Audited | High | Foundation Models / GenAI Apps | Direct recognized revenue gets substantial weight even though the six-month number is lower than ARR/run-rate figures nearby. | cn | |
| 29 | OpenRouter | ~$160M | Revenue Run-Rate | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Model Gateway / Infrastructure | Larger headline figure than MiniMax's H1 revenue, but substantially weaker evidence quality. | us | |
| 30 | Synthesia | ~$150M | ARR | Very Fresh · 5mo | May 2026 | Third-Party Estimate | Low | Generative Video | Current estimate is useful, but selected figure exceeds the last directly confirmed company milestone. | gb | |
| 31 | Emergent | $120M | Revenue Run-Rate | Very Fresh · 3mo | Jul 16, 2026 | Company Disclosed | Medium | AI App Building | Recent founder disclosure outweighs slightly larger but older/weaker estimates. | us | |
| 32 | Venice AI | ~$110M | Revenue Run-Rate | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Consumer AI / Model Access | Very fresh, but estimate quality keeps it below Emergent's direct disclosure. | us | |
| 33 | Thinking Machines Lab | >$100M | Revenue Run-Rate | Very Fresh · 1mo | Sep 3, 2026 | Credible Reported | Medium | Foundation Models | Extremely current >$100M commercial signal despite very young operating history. | us | |
| 34 | Gamma | $100M | ARR | Fresh · 11mo | Nov 2025 | Company Disclosed | Medium | Generative Presentations | Clean ARR, but older than Thinking Machines' current run-rate. | us | |
| 35 | Otter.ai | >$100M | ARR | Aging · 19mo | Mar 2025 | Company Disclosed | Low | Meeting AI | Strong direct amount but older and corporate perimeter is not exclusively generative AI. | us | |
| 36 | Decagon | ~$100M | Revenue Run-Rate | Very Fresh · 3mo | 2026 | Third-Party Estimate | Low | Customer-Service AI Agents | Much fresher than Otter but weaker source quality. | us | |
| 37 | Abridge | ~$100M | ARR | Fresh · 17mo | 2025 | Third-Party Estimate | Low | Healthcare GenAI | Substantial healthcare GenAI scale, but figure is older than Decagon's. | us | |
| 38 | EvenUp | $100M | ARR | Very Fresh · 3mo | Jul 17, 2026 | Third-Party Estimate | Low | Legal GenAI | Highly current $100M signal, but third-party rather than company filing/disclosure. | us | |
| 39 | Moveworks | >$100M | ARR | Aging · 25mo | Sep 24, 2024 | Company Disclosed | Low | Enterprise GenAI | High-quality historical figure, but two-year age and subsequent acquisition sharply reduce current comparability. | us | |
| 40 | Runway | >$90M | Revenue Run-Rate | Fresh · 16mo | 2025 | Credible Reported | Medium | Generative Video | Slightly smaller than the $100M cohort but reasonably strong reporting. | us | |
| 41 | You.com | ~$90M | ARR | Fresh · 10mo | 2026 | Third-Party Estimate | Low | AI Search / Agents | More recent than Runway but weaker source quality. | us | |
| 42 | Aleph Alpha | ~$81.5M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Foundation Models | Annual-revenue metric is attractive, but provenance is considerably weaker than a filing or company disclosure. | de | |
| 43 | Retell AI | ~$80M | Revenue Run-Rate | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Voice AI | Extremely current scale estimate, but not company disclosed. | us | |
| 44 | Wonderful | ~$70M | Revenue Run-Rate | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Customer-Service AI Agents | Current commercial estimate supports inclusion above older ~$70M figures. | il | |
| 45 | Wrtn Technologies | ~$70M | Annual Revenue | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Consumer GenAI | Full-year metric is useful, but still externally estimated. | kr | |
| 46 | Jasper | ~$80M | ARR | Historical · 46mo | 2023 | Credible Reported | Low | Enterprise GenAI Content | Nominal figure is larger than several companies below, but its age makes it poor evidence of Jasper's current scale. | us | |
| 47 | Descript | $55M | ARR | Fresh · 14mo | Aug 27, 2025 | Credible Reported | Low | Generative Audio / Video | Higher reported ARR than the ~$50M cohort, but mixed product perimeter limits comparability. | us | |
| 48 | CodeRabbit | >$50M | ARR | Very Fresh · 2mo | Aug 11, 2026 | Company Disclosed | Medium | AI Code Review | Direct, current disclosure gets preference over slightly higher third-party estimates. | us | |
| 49 | Langdock | $50M | ARR | Very Fresh · 2mo | Aug 1, 2026 | Company Disclosed | Medium | Enterprise GenAI Platform | Exact, current company ARR gets more weight than Rogo/Parloa estimates. | de | |
| 50 | Rogo | ~$53M | ARR | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Financial-Services GenAI | Nominally above Langdock, but weaker provenance produces the lower rank. | us | |
| 51 | Parloa | ~$52M | ARR | Fresh · 10mo | 2026 | Third-Party Estimate | Low | Voice / Customer-Service AI | Similar to Rogo but older operating period. | de | |
| 52 | Writer | >$50M | Signed Contracts / Bookings | Fresh · 18mo | Apr 10, 2025 | Company Disclosed | Low | Enterprise GenAI Platform | Source is strong, but signed contract value is less comparable than ARR. | us | |
| 53 | Stability AI | ~$50M | Annual Revenue | Aging · 22mo | 2026 | Third-Party Estimate | Low | Generative Images / Models | Revenue metric is stronger than bookings, but old operating period and estimate quality materially weaken it. | gb | |
| 54 | Hebbia | ~$48M | ARR | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Enterprise Knowledge GenAI | Slightly smaller than $50M cohort but dramatically fresher than Stability's figure. | us | |
| 55 | Fyxer | $35M | ARR | Very Fresh · 0mo | 2026 | Company Disclosed | Medium | AI Productivity | Current company-originated scale outweighs nearby third-party estimates. | gb | |
| 56 | Typeface | ~$34.3M | Annual Revenue | Fresh · 10mo | Sep 2026 | Third-Party Estimate | Low | Enterprise GenAI Content | Close to Fyxer numerically, but weaker source quality. | us | |
| 57 | Ambience Healthcare | ~$30M | ARR | Fresh · 17mo | 2025 | Third-Party Estimate | Low | Healthcare GenAI | Meaningful scale but older than most figures above. | us | |
| 58 | Character.AI | ~$30M | Revenue Run-Rate | Fresh · 15mo | 2026 | Third-Party Estimate | Low | Consumer AI Characters | Similar scale to Ambience; commercial perimeter is primarily consumer subscriptions. | us | |
| 59 | Mirage / Captions | $28.4M | TTM In-App Revenue | Fresh · 7mo | Mar 24, 2026 | Third-Party Estimate | Low | Generative Video | Direct app-store measurement is useful but only covers one revenue channel. | us | |
| 60 | PolyAI | ~$24M | Fiscal-Year Revenue | Fresh · 9mo | Jun 7, 2026 | Filed / Audited | High | Conversational / Voice AI | One of the strongest evidence-quality figures in this range: audited FY2026 revenue of £17.9M (~$24M), ranked above Upstage's ~$17.5M and the estimate-based Freed. | £17.9M | gb |
| 61 | Upstage | ~$17.5M | Fiscal-Year Revenue | Fresh · 10mo | 2026 | Filed / Audited | Medium | Foundation Models / Document AI | Strong audited evidence, though not every won of revenue is demonstrably generative AI. | KRW 24.8B | kr |
| 62 | Freed | ~$19M | ARR | Aging · 19mo | 2025 | Third-Party Estimate | Low | Healthcare GenAI | Latest usable financial scale signal; less authoritative than filed figures above. | us | |
| 63 | Vapi | $10M | ARR | Fresh · 16mo | Jun 16, 2025 | Company Disclosed | Medium | Voice AI Infrastructure | Direct founder disclosure outranks similarly sized third-party estimates. | us | |
| 64 | Wispr Flow | ~$10M | Annual Revenue | Fresh · 10mo | Sep 2026 | Third-Party Estimate | Low | Voice Productivity | Similar nominal scale to Vapi but weaker evidence. | us | |
| 65 | Fireflies.ai | ~$10.9M | Annual Revenue | Aging · 22mo | Jul 3, 2026 | Third-Party Estimate | Low | Meeting AI | Slightly larger nominal amount than Vapi, but considerably older and estimated. | us | |
| 66 | Luma AI | ~$8M | Revenue Run-Rate | Aging · 22mo | 2025 | Third-Party Estimate | Low | Generative Video / 3D | Older estimated run-rate receives a significant freshness penalty. | us | |
| 67 | Krea | ~$5.8M | Annual Revenue | Fresh · 10mo | Sep 2026 | Third-Party Estimate | Low | Generative Design | Current third-party estimate but no direct company revenue disclosure found. | us | |
| 68 | Cluely | $2.7M | ARR: separate segments | Fresh · 16mo | Mar 5, 2026 | Company Disclosed | Low | AI Assistant | Components are reported separately rather than silently summed; reliability concerns justify conservative placement. | us | |
| 69 | Sarvam AI | ~$3.36M | Fiscal-Year Revenue | Aging · 19mo | 2026 | Credible Reported | Low | Foundation Models | Real company revenue is preferable to user/funding proxies, but the period is older and source is secondary. | INR 291M | in |
| 70 | Bland AI | $2M | ARR | Aging · 22mo | Apr 20, 2026 | Company Disclosed | Low | Voice AI | Useful historical commercial proof, but particularly poor proxy for current scale because the company subsequently cut customers. | us | |
| 71 | Helicone | >$1M | ARR | Fresh · 7mo | Mar 2026 | Company Disclosed | Low | LLM Observability | Direct ARR milestone, though small relative to the broader GenAI tooling market. | us | |
| 72 | Synthflow AI | ~$1.1M | Annual Revenue | Fresh · 10mo | Aug 10, 2026 | Third-Party Estimate | Low | Voice AI | Slightly higher nominal amount than Helicone but substantially weaker source quality. | de | |
| 73 | Braintrust | ~$1M | Revenue Run-Rate | Aging · 22mo | 2025 | Credible Reported | Low | GenAI Evaluation | Useful historical revenue evidence, but market scale has likely changed materially since disclosure. | us | |
| 74 | Patronus AI | ~$1M | Revenue Run-Rate | Aging · 22mo | 2025 | Credible Reported | Low | GenAI Evaluation / Safety | Comparable to Braintrust's old figure, with no stronger current financial disclosure found. | us | |
| NR | xAI / Grok | 117M Grok monthly active users | Users | Fresh · 7mo | 2026 | Filed / Audited | Low | Foundation Models / Consumer AI | Commercially important but no clean standalone Grok revenue separate from the wider corporate perimeter. | us | |
| NR | Canva | ~800M AI-tool uses/month | Other Scale Signal | Very Fresh · 0mo | 2026 | Company Disclosed | Low | Generative Design | Overall Canva revenue includes a large non-GenAI design business, so company-wide ARR is not used. | au | |
| NR | Hugging Face | ~$150M | Other Scale Signal | Very Fresh · 2mo | 2026 | Third-Party Estimate | Low | Model Platform / Tooling | Hugging Face clearly participates in GenAI, but its broad ML platform ARR cannot be treated as pure GenAI revenue. | us | |
| NR | Weights & Biases | ~2% of company ARR | Other Scale Signal | Aging · 22mo | 2025 | Credible Reported | Low | GenAI Evaluation / Observability | The GenAI-specific product share is disclosed only as a percentage; no dollar figure is derived from it. | us | |
| NR | Factory | 2x MoM revenue growth for 6 months | Other Scale Signal | Very Fresh · 6mo | Apr 1, 2026 | Company Disclosed | Low | AI Coding | Strong growth signal but no absolute revenue amount, so no numerical rank is defensible. | us | |
| NR | Cartesia | >50K companies | Customers | Very Fresh · 0mo | 2026 | Credible Reported | Low | Generative Voice / Models | Customer count demonstrates scale but cannot be translated into revenue. | us | |
| NR | Copy.ai | Not disclosed | Other Scale Signal | Aging · 22mo | 2026 | Company Disclosed | Low | Enterprise GenAI / GTM | Percentage growth without a base value cannot support a numerical revenue rank. | us | |
| NR | Granola | ~400% YoY growth | Other Scale Signal | Very Fresh · 0mo | 2026 | Credible Reported | Low | Meeting AI | Strong usage trajectory, but no absolute financial disclosure that can be compared with ranked companies. | gb |

Our research about generative AI gets updated several times a month, so you always get the latest view of where things stand.
Which generative AI startups make the most money today?
Anthropic ranks first among generative AI startups, with a revenue run-rate above $65 billion, followed by OpenAI at more than $40 billion and Cursor / Anysphere above $4 billion. The gap between these three companies and the rest of the market is enormous, although several other startups have already crossed the billion-dollar mark on ARR or annualized revenue.
The ranking also shows how quickly the market has spread beyond general-purpose AI models. Coding tools, inference infrastructure, AI search, voice generation and enterprise applications are now generating hundreds of millions of dollars in annualized sales. Chinese companies have also established a substantial presence near the top.
One important distinction is that these figures measure different things. Some are annualized revenue run-rates, others are ARR, recognized segment revenue or bookings. We preserve those differences rather than treating every figure as achieved annual revenue.
| Rank | Startup | Reported figure | Metric and period |
|---|---|---|---|
| 1 | Anthropic | >$65B | Revenue Run-Rate, End-Jul 2026 |
| 2 | OpenAI | >$40B | Revenue Run-Rate, Aug 2026 |
| 3 | Cursor / Anysphere | >$4B | Revenue Run-Rate, Early Jun 2026 |
| 4 | Z.ai / Zhipu AI | $1.8B | ARR, Sep 2026 |
| 5 | Fireworks AI | >$1B | Revenue Run-Rate, Jul 2026 |
| 6 | Together AI | >$1.15B | Bookings, Latest quarter 2026 |
| 7 | Moonshot AI / Kimi | >$1B | ARR, Aug 2026 |
| 8 | Cognition | $900M | Revenue Run-Rate, Aug 2026 |
| 9 | Perplexity | >$750M | Revenue Run-Rate, Aug 2026 |
| 10 | SenseTime | CNY 2.33B (~$328M) | Segment Revenue, H1 2026 |
| 11 | Replit | ~$525M | Revenue Run-Rate, Apr 2026 |
| 12 | ElevenLabs | >$500M | ARR, May 2026 |
| 13 | Lovable | >$500M | Revenue Run-Rate, Jun 2026 |
| 14 | Manus | ~$400–500M | Revenue Run-Rate, 2026 |
| 15 | DeepSeek | ~$400–500M | Revenue Run-Rate, 2026 |
| 16 | Harvey | >$400M | ARR, Sep 2026 |
| 17 | Mistral AI | >$400M | ARR, Feb 2026 |
| 18 | fal | ~$400M | Revenue Run-Rate, Feb 2026 |
| 19 | Glean | $300M | ARR, May 2026 |
| 20 | Suno | $300M | ARR, Feb 2026 |
The positions reflect both commercial scale and the quality of the financial evidence. That is why a company with a larger headline figure can rank below one with a smaller but more directly comparable revenue metric.
Are Anthropic and OpenAI already in a league of their own?
Anthropic and OpenAI are operating at a completely different revenue scale from the other generative AI startups, with reported annualized revenue above $65 billion and $40 billion respectively.
Reuters reported that Anthropic's revenue run-rate increased from approximately $9 billion at the end of 2025 to $47 billion in May 2026 and more than $65 billion by the end of July. That represents more than sevenfold growth in roughly seven months. The acceleration has been closely linked to Claude's adoption by developers and enterprise customers, particularly for software engineering and increasingly complex workplace tasks.
OpenAI has also experienced substantial growth. Bloomberg reported that its annualized revenue exceeded $40 billion in August 2026, approximately double its $20 billion run-rate at the end of 2025. ChatGPT subscriptions, enterprise contracts, coding products and advertising have all contributed to the expansion. Subsequent October reporting placed OpenAI's run-rate closer to $50 billion, after some higher estimates had circulated.
The comparison becomes particularly striking when we look beyond the two companies. Cursor, ranked third, had a run-rate above $4 billion. Using those reported milestones, Anthropic's figure was more than 16 times Cursor's, while OpenAI's was more than 10 times higher.
These numbers annualize recent sales activity rather than representing audited full-year revenue. The lead is still extraordinary, though. The foundation-model business has produced two companies operating at a scale that most software startups take decades to reach.

In our market report about generative AI, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Cursor already a multi-billion-dollar AI business?
Cursor had already crossed a $4 billion annualized revenue run-rate by early June 2026, making it one of the largest commercial AI application businesses in the world.
Dealroom reported that Cursor's run-rate increased from $2 billion in February to $3 billion in late April and more than $4 billion in early June. That is a doubling in approximately four months.
The customer mix is particularly interesting. Around 75% of Cursor's reported run-rate came from enterprise customers, equivalent to more than $3 billion in annualized business-to-business revenue at the June milestone. Its enterprise business reportedly tripled in Q1 2026 compared with Q4 2025.
AI coding tools have clearly moved beyond individual developers experimenting with productivity software. Companies are now paying substantial amounts to integrate AI directly into engineering workflows.
There is also an important ownership development. Cursor was acquired by SpaceX on August 14, 2026, in a transaction based on an implied equity value of $60 billion. Cursor remains at rank three because the acquisition falls within the period covered by our startup inclusion rule.
Are Chinese generative AI startups catching up with US rivals?
Chinese generative AI startups are already producing billion-dollar commercial metrics, with Z.ai, Moonshot AI and DeepSeek demonstrating that the market is no longer dominated by American companies alone.
Z.ai, also known as Zhipu AI, reported $1.8 billion in ARR during an investor call in September 2026. The company also increased its year-end ARR guidance to $3 billion, although that remains a target rather than achieved revenue.
Moonshot AI, the company behind Kimi, reported ARR above $1 billion in August, according to Bloomberg. Its annualized revenue had reportedly increased from $300 million in June, following the release of its Kimi K3 model in July.
DeepSeek was estimated to have reached a $400 million to $500 million revenue run-rate in 2026, primarily through paid API access to its models. Its commercial model is particularly interesting because the popular chatbot application remains free, while developers and businesses pay to use the underlying models.
SenseTime adds another dimension to the Chinese market. Its generative AI business generated CNY 2.33 billion in recognized segment revenue during the first half of 2026, according to its interim financial results. That is a six-month figure rather than ARR or an annualized estimate.
China now has sizable commercial businesses across foundation models, API access and enterprise AI. Their figures are not directly interchangeable, but the market is clearly more competitive than a simple OpenAI-versus-Anthropic comparison suggests.

In our document detailing everything you need to know about generative AI, you will always find fresh funding data, taken straight from our own verified funding database.
Which AI coding startups are actually making money?
AI coding is already one of the strongest commercial categories in generative AI, with Cursor, Cognition, Replit and Lovable all reporting hundreds of millions or billions of dollars in annualized revenue.
Cursor's position is particularly striking, but Cognition has also grown quickly through its Devin AI engineering agent. The company reported a $900 million revenue run-rate in August 2026, up from $492 million in May.
Replit reached an estimated $525 million annualized revenue run-rate in April 2026, according to Sacra. Its business has expanded from a browser-based coding environment into an AI platform where users can create and deploy complete applications.
Lovable crossed $500 million in annualized revenue in June. Its product is aimed at people who want to build working applications through natural-language instructions, including users without traditional programming experience.
Base44, now part of Wix, also crossed $200 million ARR in August. Emergent reached a $120 million run-rate in July, according to its founder, while CodeRabbit reported ARR above $50 million in August.
The interesting part is how different these businesses are becoming. Cursor sells deeply into professional software teams, Devin automates engineering tasks, and Lovable and Replit increasingly compete for people who want software built without writing much code themselves.
| Overall rank | Startup | Reported figure | Metric and period |
|---|---|---|---|
| 3 | Cursor / Anysphere | >$4B | Revenue Run-Rate, Early Jun 2026 |
| 8 | Cognition | $900M | Revenue Run-Rate, Aug 2026 |
| 11 | Replit | ~$525M | Revenue Run-Rate, Apr 2026 |
| 13 | Lovable | >$500M | Revenue Run-Rate, Jun 2026 |
| 27 | Base44 | >$200M | ARR, Aug 2026 |
| 31 | Emergent | $120M | Revenue Run-Rate, Jul 2026 |
| 48 | CodeRabbit | >$50M | ARR, Aug 2026 |
Are AI model infrastructure companies already billion-dollar businesses?
AI infrastructure has become a major revenue category in its own right, with Fireworks AI reporting more than $1 billion in annualized revenue and Together AI reporting more than $1.15 billion in annual bookings.
Fireworks runs infrastructure for serving AI models. In its July 2026 funding announcement, the company explicitly disclosed that it had surpassed $1 billion in annualized revenue run-rate while processing more than 40 trillion tokens per day.
Together AI operates in a similar part of the market, helping businesses train and run AI workloads using open models. Its July funding announcement disclosed annual bookings above $1.15 billion in the latest quarter.
Other companies are building substantial businesses around the infrastructure required to use generative AI. fal, which focuses on generative media infrastructure, has an estimated $400 million revenue run-rate. OpenRouter, which offers access to multiple AI models through a unified interface, has an estimated $160 million run-rate.
There is plenty of money to be made without building the underlying foundation model. Inference capacity, model routing, APIs and deployment tools have become valuable products in their own right, particularly as more companies use several models rather than committing to one provider.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the generative AI market, we look at what broke startups before you, so you don't repeat it.
Does Together AI make more than Fireworks AI?
Together AI reports a larger headline figure than Fireworks AI, but Fireworks ranks higher because its figure represents revenue run-rate while Together's represents bookings.
Together AI crossed $1.15 billion in annual bookings in the latest quarter of 2026. Fireworks AI had surpassed $1 billion in annualized revenue run-rate in July.
Bookings represent the value of customer commitments or contracts recorded during a period. They do not necessarily represent revenue already recognized or generated from completed services.
Fireworks therefore offers stronger evidence of current revenue generation, even though its headline number is slightly lower.
Neither number tells us how profitable the business is, and the comparison does not establish which company has more realized revenue. What we can say is that independent inference infrastructure has already become a billion-dollar commercial category.
Are enterprise AI startups becoming major businesses?
Enterprise generative AI has become a substantial commercial market, with Glean, Harvey, Cohere and Sierra all reporting ARR between $200 million and more than $400 million.
Glean reached $300 million ARR in May 2026, just 15 months after crossing $100 million. The company sells an enterprise search and knowledge platform that connects information across different workplace applications.
Harvey, which builds AI tools for legal professionals, crossed $400 million ARR in September. The company reported that more than 80% of the Am Law 100 law firms were using its platform.
Cohere reached $240 million ARR in 2025, according to an investor memo reported by TechCrunch. Its business focuses on enterprise foundation models and AI platforms, with an emphasis on private deployments and business-specific applications.
Sierra, meanwhile, had reached $200 million ARR by May 2026. Its conversational AI platform helps large companies automate customer-service interactions.
These businesses sell into budgets that already exist: legal services, customer support, knowledge management and enterprise software. They can charge for specific workflows and measurable results, without having to compete directly with the biggest foundation-model developers.

Your time is limited. In our research about generative AI, we put numbers on each part of the market, so you can see where it makes sense to focus.
Are AI agents generating real revenue yet?
AI agents are already generating substantial commercial revenue, with Perplexity, Manus and several specialized agent platforms reporting hundreds of millions of dollars in annualized sales.
Perplexity had surpassed $750 million in annualized revenue by August 2026, according to a report by The Information cited by Reuters. Its growth has increasingly involved Perplexity Computer, a product designed to automate complex computer-based tasks for professionals.
Manus had reached an estimated $400 million to $500 million revenue run-rate in 2026, according to The Information. Its business is based on subscriptions to general-purpose AI agents capable of carrying out multi-step tasks.
There is an unusual ownership story here. Manus was acquired by Meta in December 2025, but Chinese authorities subsequently ordered the transaction to be unwound. Its original investors later bought back the shares, and the unwinding was completed in 2026.
Genspark, with an estimated $250 million run-rate, and Venice AI, with approximately $110 million, add further examples of consumer-facing AI search and agent businesses finding paying customers.
The shift is toward selling completed work: multi-step automation, professional information retrieval and tasks that would otherwise consume employee time. The revenue figures are becoming sizable, although the reliance on third-party estimates remains higher in parts of the agent market.
Is generative video already a big business?
Generative video has developed into a substantial commercial category, with Midjourney, HeyGen and Synthesia demonstrating that AI-generated creative products can reach hundreds of millions of dollars in revenue or ARR.
HeyGen crossed $200 million ARR in June 2026, doubling its ARR in approximately eight months. The company serves businesses and individuals creating AI-generated videos, avatars and multilingual content.
Midjourney has an estimated $300 million in annual revenue, although its figure relates to 2024 and is considerably older than HeyGen's disclosure.
Synthesia had an estimated $150 million ARR as of May 2026. Runway, which focuses on generative video tools for creators and professional production teams, had a revenue run-rate above $90 million in June 2025.
The smaller businesses are also worth following. Stability AI had estimated annual revenue of approximately $50 million in 2024, Mirage / Captions generated $28.4 million in trailing twelve-month in-app revenue for the period ending March 2026, and Luma AI had an estimated $8 million run-rate in December 2024.
Corporate video, AI avatars, advertising content and professional creative tools are already supporting real sales. But the figures come from different years and business models, making this a harder category to rank cleanly than the largest foundation-model companies.
| Overall rank | Startup | Reported figure | Metric and period |
|---|---|---|---|
| 22 | Midjourney | ~$300M | Annual Revenue, 2024 |
| 26 | HeyGen | >$200M | ARR, Jun 2026 |
| 30 | Synthesia | ~$150M | ARR, May 2026 |
| 40 | Runway | >$90M | Revenue Run-Rate, Jun 2025 |
| 54 | Stability AI | ~$50M | Annual Revenue, 2024 |
| 60 | Mirage / Captions | $28.4M | TTM In-App Revenue, 365 days ending Mar 2026 |
| 67 | Luma AI | ~$8M | Revenue Run-Rate, Dec 2024 |

In our market report about generative AI, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Are AI voice startups making serious money?
AI voice is already a substantial revenue category, led by ElevenLabs with more than $500 million ARR and supported by a growing group of companies selling voice agents and speech-generation infrastructure.
ElevenLabs disclosed that it ended 2025 with $350 million ARR and surpassed $500 million during the first four months of 2026. The company attributed much of its growth to enterprise deployments of voice agents in customer support, sales, recruitment and marketing.
Retell AI is another interesting example. Sacra estimates that the company reached an $80 million annualized revenue run-rate in August 2026, up from approximately $45 million at the end of 2025.
Parloa, which focuses on enterprise customer-service automation, has an estimated $52 million ARR. PolyAI reported £17.9 million in fiscal-year revenue for FY2026, based on its group accounts filed at Companies House.
Smaller companies are also generating meaningful revenue. Vapi reported $10 million ARR in June 2025, while Wispr Flow, Fireflies.ai and Synthflow AI have estimated annual revenues of approximately $10 million, $10.9 million and $1.1 million respectively.
Voice has two attractive markets at once: generating realistic speech and handling conversations that previously required human agents. ElevenLabs has pulled well ahead, but there is already a meaningful second group of companies selling to businesses.
| Overall rank | Startup | Reported figure | Metric and period |
|---|---|---|---|
| 12 | ElevenLabs | >$500M | ARR, May 2026 |
| 43 | Retell AI | ~$80M | Revenue Run-Rate, Aug 2026 |
| 52 | Parloa | ~$52M | ARR, 2025 |
| 61 | PolyAI | £17.9M | Fiscal-Year Revenue, FY2026 |
| 64 | Vapi | $10M | ARR, Jun 2025 |
| 65 | Wispr Flow | ~$10M | Annual Revenue, 2025 |
| 66 | Fireflies.ai | ~$10.9M | Annual Revenue, 2024 |
| 73 | Synthflow AI | ~$1.1M | Annual Revenue, 2025 |
Is AI music already a $300M business?
Suno has already reached $300 million ARR, making generative music one of the more commercially developed creative AI categories.
In February 2026, Suno's co-founder and CEO Mikey Shulman disclosed that the company had reached $300 million ARR and approximately two million paying subscribers.
The progression is particularly interesting. Just three months earlier, Suno had told The Wall Street Journal that annual revenue had reached $200 million.
That is a remarkable amount of subscription revenue for a product built around generating songs. People are willing to pay for music creation even when the result is a track they may listen to only a few times.
Copyright remains the major complication. Licensing agreements with music publishers and record labels directly affect Suno's ability to operate and commercialize its models. Its settlement and licensing agreement with Warner Music Group is an important example of how the industry is trying to resolve that problem.

If you build or invest in the generative AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Are healthcare AI startups becoming major businesses?
Healthcare generative AI is already producing several substantial businesses, particularly in medical research, clinical documentation and physician workflow automation.
OpenEvidence reached an estimated $300 million revenue run-rate in July 2026, according to The Information. Its platform helps doctors research medical information and answer clinical questions, with pharmaceutical advertising forming an important part of its business model.
Abridge, which focuses on AI-powered clinical documentation, has an estimated $100 million ARR. Ambience Healthcare has an estimated $30 million ARR, while Freed has an estimated $19 million ARR.
These companies make money in quite different ways. OpenEvidence monetizes medical information and clinician attention, while Abridge and Ambience focus more directly on automating documentation and administrative work.
The strongest opportunities may be in activities that already consume substantial clinical time, such as documenting appointments and navigating medical records. Healthcare AI does not need to replace a doctor to become a large software business.
Are legal AI startups making serious money?
Legal AI is already one of the strongest specialized enterprise categories, with Harvey exceeding $400 million ARR and EvenUp reaching $100 million ARR.
Harvey has grown particularly quickly by selling AI tools for legal research, document review, drafting and increasingly complex legal workflows. In September 2026, the company reported more than $400 million ARR and adoption across over 80% of the Am Law 100.
EvenUp, which applies generative AI to personal injury law and legal case preparation, has an estimated $100 million ARR.
The commercial appeal is straightforward. Lawyers spend a lot of time reviewing documents, preparing arguments and handling large volumes of information. Firms already pay heavily for specialized software and information services, so a tool that meaningfully reduces this workload has an obvious customer.
Harvey's growth also demonstrates that a specialized AI application can become a major business without building its own frontier foundation model. Legal expertise, workflow integration and customer relationships can be valuable advantages of their own.

Theory only gets you so far. In our report covering the generative AI market, we dig up the real signals from the field and show you the ones worth watching.
How many generative AI startups have already crossed $100 million?
At least 39 ranked generative AI startups have reached a reported commercial-scale figure of $100 million or more, although these figures include ARR, revenue run-rate, bookings and partial-period revenue.
The cohort extends from Anthropic at rank one through Moveworks at rank 39. The next company, Runway, has a reported revenue run-rate above $90 million.
What stands out is the variety. The $100 million group includes foundation-model developers, coding tools, AI infrastructure, enterprise search, video generation, healthcare applications, legal software and consumer AI products.
Some companies have achieved this scale through subscriptions, while others rely on enterprise contracts, consumption-based pricing or API usage.
The number needs to be interpreted carefully. Together AI's figure is bookings, MiniMax reports six months of recognized revenue, and several other companies report ARR or annualized revenue. Consequently, 39 companies with $100 million-scale metrics should not be confused with 39 businesses that have each recognized $100 million in annual sales.
Still, it is a sizable group. Generative AI now has a broad commercial market beneath its two biggest foundation-model companies, rather than a handful of isolated success stories.
Which generative AI startups report actual revenue rather than ARR?
Several generative AI startups now disclose recognized revenue in financial statements or interim results, offering a more direct view of achieved sales than annualized estimates.
SenseTime reported CNY 2.33 billion in generative AI segment revenue during H1 2026. This is a six-month figure covering its generative AI business rather than the company's entire revenue.
MiniMax reported approximately $117 million in total revenue for H1 2026, compared with $30.4 million during the corresponding period in 2025. Its open platform and other AI-based enterprise services generated $73.9 million of that amount.
PolyAI reported £17.9 million in fiscal-year revenue for the year ending January 2026, according to its Companies House group accounts.
Upstage reported KRW 24.8 billion in fiscal-year revenue for FY2025, while Sarvam AI reported INR 291 million for FY2025.
These conventional financial disclosures are particularly useful. They reveal sales recognized during a defined accounting period, although the business perimeter still varies from one company to another.
A six-month revenue figure, an annual fiscal-year figure and an ARR estimate answer different financial questions. Mixing them without explanation would make the ranking look more precise than it really is.

In our research about generative AI, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are generative AI startups profitable yet?
Generative AI startups can reach impressive revenue figures while still losing substantial amounts of money, as MiniMax's financial results demonstrate.
MiniMax reported $116.6 million in recognized revenue during H1 2026, representing 283.1% year-over-year growth. Yet the company also reported an adjusted net loss of $293 million during the same six-month period.
Its gross profit was $20.8 million, equivalent to a gross margin of 17.9%. That is a relatively low margin for a software business, reflecting the substantial costs associated with running AI models and serving customers.
The company has been investing heavily in infrastructure, model development and inference capacity while expanding its commercial platform.
The economics are tough. Strong demand can coexist with expensive computing infrastructure, heavy model-development costs and weak margins. Revenue growth alone does not establish whether an AI business can eventually generate attractive profits.
MiniMax is a useful case because it publishes more detailed financial information than many private competitors. As other AI companies release income statements, we will get a clearer picture of how much of their rapid sales growth translates into sustainable earnings.
Can we trust the revenue numbers these AI startups report?
The strongest generative AI revenue figures generally come from company disclosures and reputable financial reporting, but the underlying metrics still require careful interpretation.
Looking at the 20 highest-ranked startups, ten figures are company-disclosed, seven come from credible reported disclosures, one comes from company financial results and two are third-party estimates.
That is a relatively strong evidence base for a market dominated by private companies. The bigger problem is what the figures actually measure.
Anthropic, OpenAI and Cursor report revenue run-rates. Z.ai, Moonshot and ElevenLabs report ARR. Together AI reports bookings, while SenseTime reports recognized revenue from a specific business segment.
Those distinctions can change the meaning of a billion-dollar headline. A company reporting $1.15 billion in bookings has not necessarily generated $1.15 billion in revenue. Likewise, a $1 billion ARR figure represents the annualized value of recurring revenue at a particular point, rather than $1 billion already recognized over a full financial year.
Third-party estimates also deserve less confidence than direct financial disclosures. Replit and fal, for example, have substantial estimated revenue figures, but their financial evidence is less direct than a company announcement or a regulatory filing.
Our ranking keeps these differences visible. The exact order becomes less certain when companies use different metrics, but the broader picture of commercial scale is much clearer than it was even a year ago.

A good product starts with a real problem. In our report covering the generative AI market, we show you the ones customers still live with.
Which promising generative AI startups still have no comparable revenue figure?
Several important generative AI companies remain outside the numerical ranking because their available commercial metrics do not establish a comparable revenue figure.
xAI / Grok, for example, had 117 million Grok monthly active users reported in March 2026. That demonstrates significant product adoption, but does not tell us how much revenue Grok independently generates.
Canva disclosed approximately 800 million AI-tool uses per month in 2026, but its overall revenue includes a much broader design business. We cannot attribute that entire business to generative AI.
Hugging Face has an estimated $150 million in ARR for its broader machine-learning platform, but that figure cannot be treated as pure generative AI revenue.
Other examples include Factory, which reported two-times month-over-month revenue growth for six months without an absolute revenue amount, and Cartesia, which has reported adoption by more than 50,000 companies.
Weights & Biases has also been reported to derive approximately 2% of its company ARR from generative AI-related products, while Granola has reported approximately 400% year-over-year growth.
Some of these businesses may already be making considerable money. But user adoption, revenue growth percentages and total company sales are not enough to establish how much revenue belongs specifically to generative AI.
What does the growth of generative AI startups tell us about where AI spending is going?
Generative AI spending is spreading across the entire technology stack, with foundation models still representing the largest individual businesses but applications increasingly generating substantial revenue of their own.
Seven of the top 20 ranked startups operate primarily in foundation models or closely related GenAI platforms. The remaining 13 cover coding, infrastructure, search, agents, voice, legal AI, enterprise knowledge and music generation.
Coding is particularly prominent, with Cursor, Cognition, Replit and Lovable all appearing in the top 20. Businesses are increasingly paying for AI systems that produce working software rather than just answer questions.
Infrastructure is another major opportunity. Fireworks and Together AI demonstrate that there is significant commercial demand for the computing and model-serving services required to deploy generative AI at scale.
Meanwhile, ElevenLabs, Harvey, Glean and Suno show that specialized applications can build substantial businesses around particular workflows and creative activities.
There is an interesting division of spending emerging. Model developers charge for access to AI capabilities, infrastructure companies charge to run and deliver those models, and application companies charge for what customers can accomplish with them.
The boundaries overlap, of course, especially as foundation-model developers move further into applications. But AI spending is no longer concentrated in subscriptions to general-purpose chatbots. It has become a much wider software and infrastructure market.

When you build or invest in the generative AI market, you need clarity, not confusion. In our document detailing everything you need to know about generative AI, we always try to put numbers on and quantify whatever is usually vague and confusing.
So, who is actually winning the generative AI revenue race today?
Anthropic is the top-ranked generative AI startup by revenue scale, followed by OpenAI and Cursor / Anysphere, with Z.ai, Fireworks AI, Together AI and Moonshot AI forming the next major group.
Anthropic's reported revenue run-rate above $65 billion puts it at the top of the ranking, while OpenAI's figure above $40 billion confirms that the two largest foundation-model businesses operate at a scale far beyond most competitors.
Cursor's position above $4 billion is arguably one of the most interesting developments because it shows how quickly a specialized AI application can become a multi-billion-dollar business. Its acquisition by SpaceX does not change its position in this startup ranking.
Below the top three, the market becomes more diversified. Chinese foundation-model developers have reached substantial commercial scale, AI infrastructure companies are generating billion-dollar metrics, and specialized applications in coding, voice, legal services, enterprise software and healthcare are producing hundreds of millions in annualized revenue.
There is no single winner across all those categories. Anthropic leads on our reported revenue-scale ranking, Cursor has become a giant in coding, Fireworks has built a major inference business, and companies such as Harvey and ElevenLabs are establishing strong positions in particular markets.
The clearest conclusion is that generative AI has already produced a sizable group of commercial businesses. The next test is whether these companies can sustain their growth while keeping inference costs, customer acquisition spending and model-development expenses under control.
Our methodology
We ranked generative AI startups by their latest credible evidence of commercial revenue scale, using information available through November 2026. The ranking covers foundation-model developers, AI coding platforms, inference infrastructure, enterprise applications, AI agents, generative media, voice technology and specialized industry tools. We considered both the amount reported and the strength of the evidence behind it.
Our startup definition includes companies founded in 2000 or later that have never been publicly listed or were first listed within the last five years. We generally exclude established companies and subsidiaries of larger groups, while retaining startups acquired within the last three years. Acquired companies are identified where relevant, including Cursor / Anysphere under SpaceX and Base44 under Wix.
We considered fiscal-year revenue, trailing twelve-month revenue, interim revenue, annual recurring revenue, annualized revenue run-rate, bookings and credible third-party estimates. We prioritized recognized revenue and reliable recurring-revenue disclosures, then assessed freshness and comparability. Bookings, ARR and revenue run-rates remain separate metrics, and partial-period or segment figures are identified explicitly. The ranking is therefore evidence-weighted rather than a mechanical sort of headline dollar amounts.
We also checked whether each figure covered the whole company, a particular business segment or an individual product. Financial statements, regulatory filings, direct company announcements and reputable financial reporting received more weight than estimates from third parties. Companies with adoption figures, customer counts or growth percentages but no defensible revenue amount were excluded from the numerical positions.
Key sources include Reuters on Anthropic's revenue run-rate, Bloomberg on OpenAI's August revenue run-rate, Bloomberg on OpenAI's October revenue estimate, Dealroom on Cursor's annualized revenue, SpaceX's SEC filing on the Cursor acquisition, South China Morning Post on Z.ai, Fireworks AI's funding and revenue announcement, and Reuters on Together AI's annual bookings.
Additional sources include Bloomberg on Moonshot AI, TechCrunch on Cognition, ElevenLabs' ARR announcement, TechCrunch on Lovable, Harvey's company announcement, Glean's ARR disclosure, TechCrunch on Suno, SenseTime's H1 2026 financial results, MiniMax's H1 2026 financial results, and PolyAI's Companies House filings.

In our report covering the generative AI market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us