Which InsurTech startup is growing the fastest?
Whether you're building or investing in the insurtech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Lemonade is currently the fastest-growing established publicly traded property and casualty InsurTech in our comparison, with revenue up 79.4% year over year in Q2 2026. Oscar Health leads by absolute revenue growth, while no private startup can yet be verified as the fastest-growing InsurTech worldwide.
The difference between percentage growth and actual scale is enormous. Oscar added approximately $2.02 billion in quarterly revenue over twelve months, more than 15 times Lemonade's $130.3 million increase, despite posting a slightly lower growth rate of 70.4%.
Lemonade's headline growth also exaggerates the pace of its underlying insurance expansion. Changes in reinsurance arrangements helped revenue rise 79.4%, while in-force premium increased 32.4% and customer numbers grew 22.9%. The business is expanding rapidly, but those three figures tell quite different stories.
What makes Lemonade more interesting is the improvement beneath that growth. Its gross loss ratio fell from 67% to 60%, while its quarterly net loss barely changed despite a 79% revenue increase. Growth is beginning to look more financially efficient.
Hippo offers a different growth story. Its gross written premiums increased 61.5%, far ahead of its 23.4% revenue growth, driven partly by a shift toward casualty and commercial insurance. Its homeowners business now represents only 22% of gross written premium.
Kin's 29% annual revenue growth is substantial, but the composition deserves attention. Renewal written premium climbed from roughly $302 million to $440 million, while new written premium remained broadly flat. Its existing portfolio is doing most of the growing.
Cover Genius is one of the strongest disclosed private contenders, with 50% revenue growth in 2025. Its embedded-insurance model benefits from distribution through major digital platforms, although its $3 billion in cumulative gross written sales cannot be treated as annual revenue or compared directly with an insurer's premiums.
Root illustrates the opposite strategic choice. Quarterly revenue growth slowed to just 2%, and gross written premiums declined slightly, yet the company generated $25 million in net income. It appears increasingly willing to sacrifice rapid expansion for underwriting discipline and profitability.
The biggest potential challengers may be young AI insurance software companies whose revenue figures remain private. Ondo InsurTech's recurring revenue grew 51% while its total revenue increased only 20%, illustrating how dramatically the answer can change depending on which part of a software business we measure.
Our conclusion favors Lemonade for the clearest combination of sustained disclosed growth, customer acquisition, and improving insurance performance among established public P&C InsurTechs. Oscar wins on absolute scale, Hippo on the premium-growth measure examined, and Cover Genius remains a compelling private challenger. A definitive worldwide winner is still beyond what the available financial disclosures can establish.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us
Which InsurTech startup is growing the fastest today?
Lemonade currently leads the established publicly traded property and casualty InsurTechs in revenue growth, while Oscar Health is adding far more revenue in absolute dollars. Among private companies, Cover Genius is one of the strongest contenders, with 50% annual revenue growth.
Lemonade reported $294.4 million in second-quarter 2026 revenue, up 79.4% from $164.1 million a year earlier. Oscar Health grew approximately 70%, reaching $4.88 billion, while Hippo increased revenue 23.4% and Root managed just 2% growth.
But these companies are growing at very different scales. Oscar added approximately $2.02 billion in quarterly revenue year over year, compared with Lemonade's $130.3 million increase. In other words, Oscar added more than 15 times as much revenue, despite growing slightly more slowly in percentage terms.
The private market adds another complication. Cover Genius reported 50% revenue growth in 2025, Kin grew 29%, and several newer insurance software companies are expanding without publishing comparable financial statements.
For now, Lemonade has the strongest reported percentage growth among the established public property and casualty insurers we've examined. Whether it is growing faster than every private InsurTech worldwide is impossible to establish from the available disclosures.
Why is it so hard to tell which InsurTech is growing fastest?
InsurTech growth rankings are surprisingly unreliable because companies often report different things under the broad label of growth.
Insurance carriers disclose revenue, earned premiums, written premiums, and policies in force. Insurance marketplaces report commissions or fees. Managing general agents may highlight gross written premiums handled through carrier partners, while software vendors usually emphasize recurring revenue.
Consider Lemonade, Kin, and Cover Genius.
Lemonade reported $294.4 million in quarterly revenue and $1.43 billion in annualized in-force premium at the end of June 2026. Kin reported $201.6 million in full-year 2025 revenue alongside $634.4 million in gross written premium. Cover Genius announced that it had exceeded $3 billion in cumulative gross written sales, covering multiple years of activity.
Those premium figures measure different things.
Lemonade's revenue reflects insurance accounting and reinsurance arrangements. Kin earns revenue through its insurance distribution and management model. Cover Genius facilitates insurance sales embedded within third-party digital platforms.
Even among insurers, higher premiums can come from more customers, higher prices, broader coverage, or simply retaining more premium instead of passing it to reinsurers. A company can report spectacular revenue growth without attracting customers at anything close to the same rate.
We therefore give the most weight to reported revenue growth, supported by customer numbers, premium expansion, and operating results. Funding rounds, valuations, and cumulative transaction volumes cannot tell us which business is growing fastest.

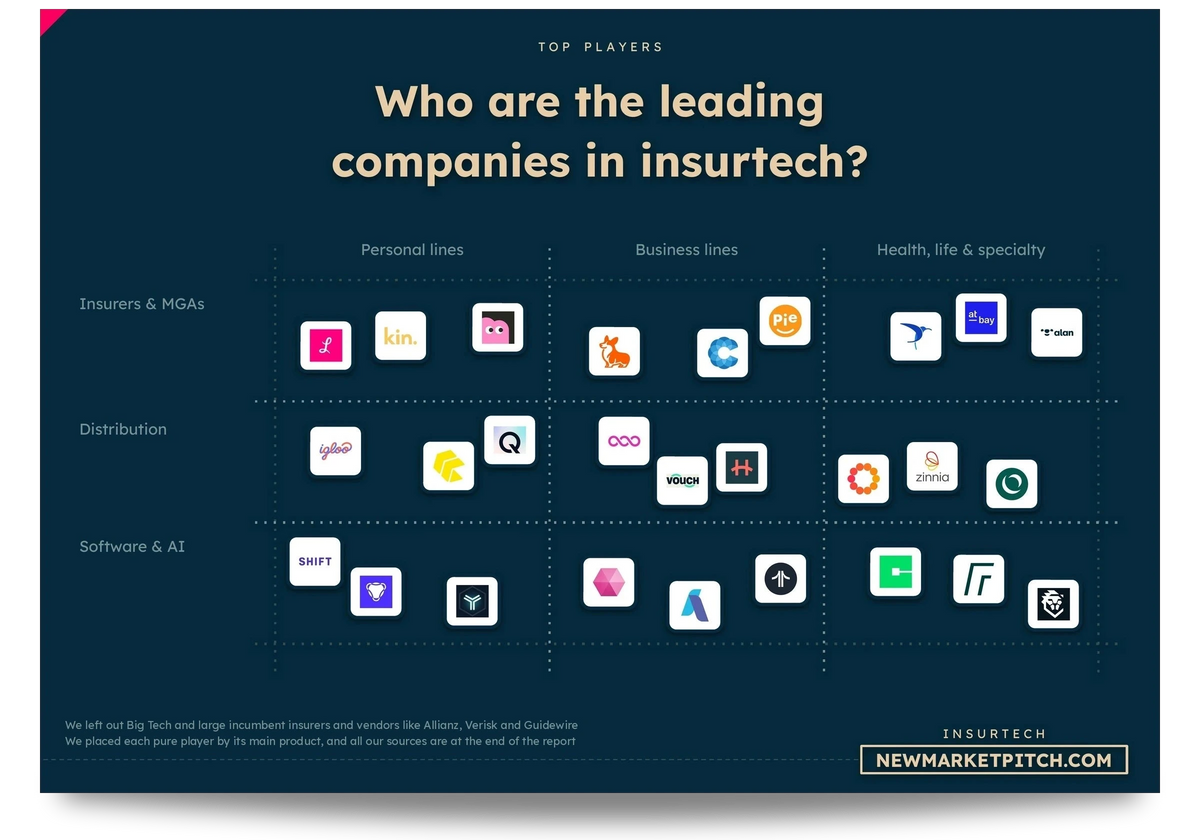
In our report covering the insurtech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is Lemonade really growing faster than other digital insurers?
Lemonade is currently growing revenue faster than the established public digital property and casualty insurers we examined, although its underlying insurance business is growing considerably more slowly than its headline revenue rate.
Second-quarter 2026 revenue increased 79.4%, following 71% growth in the first quarter. Across the first six months, revenue reached $552.4 million, compared with $315.3 million in the same period of 2025.
That works out to approximately 75.2% growth over six months, making the latest quarter part of a sustained acceleration rather than an isolated spike.
However, Lemonade's in-force premium grew 32.4% year over year, from $1.08 billion to $1.43 billion. Its customer base increased from 2.69 million to 3.31 million, approximately 22.9%.
Part of the gap comes from changes in reinsurance arrangements. When Lemonade retains more of the premiums it writes, recognized revenue can increase faster than the number of customers or the amount of insurance coverage it sells.
The underlying results are still impressive. Maintaining approximately 32% premium growth at more than $1 billion in in-force premium is difficult, particularly for an insurer that also needs to control claims.
Lemonade's gross loss ratio improved from 67% to 60% year over year in the second quarter. That suggests the company is getting better at pricing and managing claims while adding business.
The 79% revenue growth grabs attention, but the combination of premium growth and improving loss performance makes Lemonade a serious contender.
If you want more recent data on this point, please see our latest InsurTech market report.
How do Lemonade, Oscar Health, Hippo, and Root compare?
Lemonade has the fastest reported revenue growth among the selected public property and casualty insurers, Oscar Health is adding the most revenue, and Hippo is expanding its premium volume much faster than its recognized revenue.
The gap between these companies is large enough that calling all of them high-growth InsurTechs would hide more than it explains.
Root, for example, generated more quarterly revenue than Lemonade but grew only 2%. Hippo's revenue growth was relatively modest, yet its gross written premium increased more than 60%. Oscar operates in an entirely different league by revenue size.
The following figures use the latest reported periods discussed in this analysis.
| Company | Recent revenue | Revenue growth | Other growth indicator |
|---|---|---|---|
| Lemonade | $294.4M, Q2 2026 | +79.4% | In-force premium +32.4% |
| Oscar Health | $4.88B, Q2 2026 | +70.4% | Membership +46.2% |
| Hippo | $144.7M, Q2 2026 | +23.4% | Gross written premium +61.5% |
| Root | $389M, Q2 2026 | +2% | Policies in force +6% |
| EverQuote | $195.1M, Q2 2026 | +25% | Adjusted EBITDA +37% |
| Kin | $201.6M, FY2025 | +29% | Gross written premium +28% |
| Cover Genius | Undisclosed | +50%, FY2025 | Cumulative gross written sales above $3B |
Kin and Cover Genius are private companies reporting annual rather than quarterly growth. EverQuote operates an insurance marketplace, while Oscar specializes in health insurance.
We can compare their disclosed growth rates, but the figures do not form a standardized global ranking.

Our research about insurance technology gets updated several times a month, so you always get the latest view of where things stand.
Could Oscar Health actually be the fastest-growing InsurTech?
Oscar Health has the most impressive large-scale revenue growth among the digital insurers we've examined, even though Lemonade is growing faster in percentage terms.
Oscar generated $4.88 billion in second-quarter 2026 revenue, compared with approximately $2.86 billion a year earlier. Its growth rate reached 70.4%, while first-half revenue increased approximately 61.2% to $9.53 billion.
The company also added a remarkable number of customers. Membership reached approximately 2.96 million at the end of June 2026, up from 2.03 million a year earlier.
That's nearly 936,000 additional members in twelve months, an increase of 46.2%.
Oscar's financial results improved sharply too. The company recorded $361.8 million in quarterly net income attributable to the company, reversing a $228.4 million loss a year earlier.
However, Oscar's growth is closely tied to the U.S. individual health insurance market. Government subsidies, enrollment patterns, medical costs, premium rates, and risk adjustments can all have a substantial effect on revenue and earnings.
Its second-quarter profitability also benefited from $164 million of favorable prior-period reserve development. That accounting benefit helped earnings but should not be mistaken for recurring growth from new customers.
Oscar's sheer scale makes it difficult to overlook. Adding more than $2 billion in quarterly revenue within a year is a different achievement from growing a smaller business by 80%.
If we're looking for the fastest percentage revenue growth among the selected property and casualty insurers, Lemonade wins. If we're looking for the largest increase in revenue dollars across the broader digital insurance group, Oscar is the clear leader.
If you want more recent data on this point, please see our latest InsurTech market report.
Is Hippo growing faster than its revenue suggests?
Hippo is one of the fastest-growing InsurTechs in terms of premium volume, and its latest results show a company moving well beyond its original homeowners insurance business.
In the second quarter of 2026, gross written premium increased 61.5% to $482.2 million, from $298.6 million a year earlier. Revenue grew 23.4% to $144.7 million.
The difference comes from how Hippo operates. Its platform handles insurance premiums that do not all become consolidated company revenue, so premium volume is useful for understanding the scale of business flowing through its operations.
The composition of that growth is particularly interesting.
Casualty gross written premium increased 177% year over year to approximately $180 million, while commercial multi-peril premiums grew 65% to $138 million.
Casualty accounted for 37% of quarterly gross written premium, commercial multi-peril for 29%, and homeowners for just 22%.
Hippo is increasingly a commercial and specialty insurance platform rather than primarily the homeowners insurer many people remember.
Its financial performance improved alongside that expansion. Hippo reported $10.1 million in quarterly net income, compared with $1.3 million a year earlier, while its combined ratio improved from 100.1% to 95.8%.
A combined ratio below 100% generally indicates that premiums earned exceeded the associated claims and underwriting expenses under that measure.
Hippo's 61.5% premium growth is considerably faster than Lemonade's 32.4% in-force premium growth, though the two measures and business models are different. Hippo deserves more attention in the growth debate than its 23% revenue increase alone would suggest.

In our market report about insurance technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Kin Insurance the fastest-growing private insurer?
Kin is one of the more convincing fast-growing private insurance companies, particularly because its recent results show how much of its expansion comes from existing customers.
The company generated $201.6 million in revenue during 2025, representing 29% annual growth. Gross written premium increased approximately 28% to $634.4 million, while premiums in force reached $634.8 million.
One detail stands out when we look deeper into those numbers.
Kin's renewal written premium increased from approximately $302 million to $440 million, while new written premium remained broadly flat at $194.5 million.
Most of the growth therefore came from its existing insurance portfolio rather than a wave of new business.
Renewal revenue increased from $95.2 million to $139.8 million, while new revenue reached $61.8 million.
This is encouraging for retention and the value of its customer base, though it also raises a question about whether Kin can accelerate new customer acquisition.
The company reported a 116% increase in baseline operating income to $68.6 million, with its baseline operating margin rising from 33% to 49%.
Baseline operating income is a company-defined measure, so it should not be confused with consolidated net income or a conventional insurance underwriting margin.
Kin's growth rate is below Lemonade's and Cover Genius's disclosed revenue growth. Still, for a private company operating in homeowners insurance markets exposed to hurricanes and other severe weather, nearly 30% revenue growth alongside improving operating results is a strong performance.
Is Cover Genius growing faster than most private InsurTech startups?
Cover Genius is currently one of the strongest disclosed private InsurTech growth stories, with 50% annual revenue growth in 2025 and distribution through some of the world's largest digital platforms.
The company disclosed that revenue increase when announcing a $100 million financing arrangement with Vista Credit Partners in 2026.
It also reported more than $3 billion in cumulative gross written sales and distribution extending to 240 million policies through integrations with digital platforms.
Cover Genius works with companies including Booking.com, Agoda, Revolut, Klarna, Priceline, and Uber.
Its business model is quite different from Lemonade's or Kin's. Instead of attracting every insurance customer to a dedicated insurance website or app, Cover Genius integrates protection products into transactions people are already making.
Someone booking a hotel, purchasing an item, or using a financial app can encounter insurance directly within that experience.
The model offers a way to grow without relying entirely on expensive direct customer acquisition. New platform integrations can introduce Cover Genius to large existing customer bases, while established partners can generate additional sales as their own transaction volumes grow.
The catch is financial transparency. The $3 billion figure represents cumulative insurance sales over multiple years, and Cover Genius has not published enough recent annual revenue detail to calculate its absolute revenue increase or compare its current scale directly with Lemonade.
Its 50% annual revenue growth is faster than Kin's 29%, but below Lemonade's latest reported quarterly rate.
Cover Genius remains a serious candidate for private-market leadership, especially in embedded insurance.
If you want more recent data on this point, please see our latest InsurTech market report.

In our document detailing everything you need to know about insurtech, you will always find fresh funding data, taken straight from our own verified funding database.
Why is Lemonade growing so fast right now?
Lemonade's growth has been accelerating because it keeps adding customers, earns more premium per customer, and now retains a greater share of its insurance revenue.
Its in-force premium grew approximately 31% in the fourth quarter of 2025 and 32% in both the first and second quarters of 2026.
The company described the second quarter as its eleventh consecutive quarter of accelerating year-over-year in-force premium growth.
That is a more useful growth record than a single exceptionally strong earnings release.
Lemonade also increased its customer count from approximately 2.69 million to 3.31 million over twelve months, adding nearly 616,000 customers.
Average premium per customer increased from $402 to $433, approximately 7.7%.
The combination explains much of the underlying expansion: more customers, each generating slightly more premium on average.
That higher premium per customer can reflect product purchases, coverage changes, and rate increases. We cannot attribute all of it to successful cross-selling without more detailed disclosures.
Product-level results help explain where the growth is coming from.
Lemonade's pet insurance business passed $500 million in in-force premium early in the second quarter, after growing 55% during 2025. Its car insurance product recorded approximately 60% year-over-year in-force premium growth in the first quarter.
These products are giving Lemonade more ways to grow beyond its original renters insurance business.
Customer retention is improving as well. Annual dollar retention rose from 84% to 85% year over year. That metric measures premium retained from existing customer cohorts after policy changes and cancellations, rather than the percentage of customers who renew.
The improvement is small, but paired with customer growth, it helps support premium expansion.
Reinsurance changes then amplified the effect on recognized revenue. Keeping more of the premiums it writes allows Lemonade to report much faster revenue growth than customer or in-force premium growth.
The 79.4% revenue increase is therefore partly an accounting and retention story. The sustained 30%-plus premium growth is the stronger evidence that Lemonade's underlying business is expanding quickly.
Can Lemonade keep growing this fast without losing more money?
Lemonade's losses are shrinking relative to revenue while the business continues to grow quickly, although it has yet to deliver sustained net profitability.
In the second quarter of 2026, Lemonade reported a net loss of $43.4 million, compared with a $43.9 million loss a year earlier.
Revenue increased approximately 79% over that period, but the absolute quarterly loss barely changed.
The net loss represented approximately 14.7% of revenue, down from 26.8% a year earlier.
Gross profit increased from $64.3 million to $113.2 million, approximately 76% growth.
For the first half of 2026, net losses narrowed from $106.3 million to $79.2 million, while adjusted EBITDA losses improved from $87.9 million to $35.8 million.
The company is generating considerably more revenue without a proportionate increase in its losses. That's real progress.
Profitability is still a different challenge. Insurance losses can fluctuate sharply due to weather, claims inflation, and pricing errors. Retaining more premium also changes how much insurance risk stays on the company's books.
Lemonade expects to achieve positive adjusted EBITDA in the fourth quarter of 2026 and full-year adjusted EBITDA profitability in 2027.
Those are management forecasts, and adjusted EBITDA excludes certain costs that still affect net income.
For now, Lemonade has demonstrated a much more efficient growth pattern than it had several years ago. It still needs to prove that the improvement can carry through to consistent net profits.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the insurtech market, we look at what broke startups before you, so you don't repeat it.
Has Root Insurance stopped growing quickly?
Root Insurance has slowed dramatically from its earlier growth rates and now appears more focused on profitability than on adding premiums as quickly as possible.
In 2024, Root increased gross written premiums by 66% and grew policies in force by approximately 21%.
The company subsequently reported full-year 2025 net income of $40.3 million, compared with $30.9 million in 2024.
Policies in force reached 481,869 at the end of 2025, approximately 16% higher than a year earlier.
By the second quarter of 2026, revenue growth had slowed to 2%, with quarterly revenue reaching $389 million.
Gross written premium declined 2% year over year, while policies in force increased 6% to approximately 484,000.
Root nevertheless generated $25 million in quarterly net income and $44 million in adjusted EBITDA.
The slowdown is striking when compared with Lemonade's performance over the same period.
Root's premium growth went from 66% in 2024 to slightly negative in the latest quarter examined, while Lemonade has continued reporting more than 30% annual growth in in-force premium.
Root has indicated that it is managing expansion selectively instead of pursuing premium growth at unattractive prices.
That approach may ultimately create a stronger insurance business, especially if it protects underwriting margins.
But when the question is simply which InsurTech is growing fastest today, Root is no longer near the top.
If you want more recent data on this point, please see our latest InsurTech market report.
Could AI insurance startups be growing even faster than Lemonade?
Some AI insurance startups could be growing faster than Lemonade in percentage terms, but we do not have enough disclosed revenue data to prove which ones are ahead.
This is especially relevant for companies selling software to insurers rather than underwriting policies themselves.
In September 2026, CB Insights selected 50 promising InsurTech startups from more than 6,000 companies.
Twenty-seven were founded in 2022 or later, and 31 were classified as early-stage businesses.
The list included Sixfold, Federato, Clearspeed, Artificial Labs, CoverForce, and Counterpart, covering underwriting, insurance operations, risk assessment, and distribution.
Many of these companies sell technology that can be deployed across existing insurance companies. Their growth depends on enterprise contracts, software adoption, and integrations, which are quite different from the drivers of insurance premium growth.
There is also a useful hiring indicator. CB Insights reported a 33% median twelve-month headcount increase among the surviving companies in its 2025 Insurtech 50 cohort.
That points to substantial organizational growth, although headcount is an imperfect proxy for commercial performance.
An early-stage AI underwriting company could potentially double or triple revenue while remaining far smaller than Lemonade.
A startup growing from $2 million to $6 million in annual recurring revenue would post 200% growth, yet its absolute increase would be a tiny fraction of what Lemonade or Oscar adds.
This is why an unqualified claim that Lemonade is the fastest-growing InsurTech in the world would go beyond the evidence.

Your time is limited. In our research about insurance technology, we put numbers on each part of the market, so you can see where it makes sense to focus.
Are insurance software startups growing faster than actual insurers?
Insurance software startups can grow quickly without taking on the same financial risks as insurance carriers, but the available results do not show that software companies are universally growing faster.
Ondo InsurTech provides a useful example.
The company sells LeakBot water-leak prevention technology through insurance partners. For the financial year ended March 2026, Ondo reported a 20% increase in total revenue to £4.6 million.
Its recurring revenue grew considerably faster, increasing 51% to £3.8 million.
U.S. revenue increased 117% to £2.3 million as the company's American operations expanded.
Active revenue-generating LeakBot devices increased 33% to 144,507 globally, while U.S. deployments more than doubled.
Those figures show a company growing extremely quickly in the United States, even though its total company revenue increased at a much slower rate.
The business also reported a £6.4 million operating loss.
For companies such as Sixfold and Federato, the appeal of the model is straightforward. Software can be sold to multiple insurers without the vendor having to fund the insurance claims itself.
That creates the potential for rapid revenue growth and attractive margins once the business reaches sufficient scale.
However, enterprise sales cycles can be long, insurance software integrations are often complicated, and a successful pilot does not always turn into a large recurring contract.
We also lack enough recent financial disclosures from the most promising private AI insurance vendors to compare them directly with established digital insurers.
The software category could contain the fastest-growing InsurTech startup today. The available numbers simply do not identify it.
Which InsurTech companies are growing fastest in each category?
Lemonade leads the selected digital property and casualty insurers on reported revenue growth, Oscar Health leads in absolute revenue expansion, and Hippo has one of the strongest disclosed premium-volume growth rates.
Private embedded insurance and insurance software companies also have impressive figures, although the available reporting is less complete.
The companies below illustrate how different the rankings become depending on what we measure.
| Company | Business model | Growth measure | Growth rate |
|---|---|---|---|
| Lemonade | Digital P&C insurer | Q2 revenue, YoY | +79.4% |
| Oscar Health | Digital health insurer | Q2 revenue, YoY | +70.4% |
| Hippo | Insurance platform | Q2 gross written premium, YoY | +61.5% |
| Ondo InsurTech | Claims prevention technology | Annual recurring revenue | +51% |
| Cover Genius | Embedded insurance | FY2025 revenue, YoY | +50% |
| Kin | Home insurance platform | FY2025 revenue, YoY | +29% |
| EverQuote | Insurance marketplace | Q2 revenue, YoY | +25% |
| Root | Digital auto insurer | Q2 revenue, YoY | +2% |
These figures cover different periods and measures. Ondo's 51% refers to recurring revenue rather than total company revenue, while Hippo's 61.5% reflects gross written premium.
The table is best read as a comparison of disclosed growth leaders across different kinds of InsurTech, rather than a precise ranking from first to eighth.

In our market report about insurance technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is the InsurTech market growing faster again?
The InsurTech sector is attracting renewed investment and producing more exits, but the broader insurance market is still growing far more slowly than its best-performing startups.
CB Insights reported that InsurTech IPO and acquisition exits increased by a combined 67% in 2025 compared with the previous year.
Its September 2026 Insurtech 50 cohort had already raised more than $800 million during 2026, accounting for approximately 16% of year-to-date sector funding.
Investors are still willing to fund young insurance technology businesses, particularly those with a credible path to commercial scale.
However, the underlying insurance market tells a more restrained story.
According to AM Best, U.S. property and casualty direct written premiums increased approximately 5% in 2025 to $1.11 trillion.
The industry's combined ratio improved to approximately 93%, while underwriting income reached $61.2 billion.
Those are strong operating results for insurers, but overall premium growth remained relatively modest.
Cyber insurance provides another example of how growth can be misleading when we look at only one measure.
The National Association of Insurance Commissioners reported that U.S. cyber insurance direct written premiums, including eligible foreign surplus lines, increased approximately 3.5% to $9.46 billion in 2025.
Yet domestic policies in force grew 33%.
The gap suggests that factors such as pricing and coverage mix can produce very different trends in policy counts and premium revenue.
It also puts the InsurTech leaders in perspective. A company increasing premiums by 30% or 60% is growing many times faster than the broader U.S. property and casualty insurance market.
Some of that advantage may come from gaining market share, introducing new products, or expanding into markets where the company previously had little presence.
Price increases can also contribute, and the effect varies by company. Lemonade's customer growth, Oscar's membership increase, and Kin's expanding renewal portfolio help us distinguish actual business expansion from growth driven only by higher premiums.
Which InsurTech startup has the best chance of keeping its growth going?
Lemonade currently has the strongest documented combination of sustained growth, customer expansion, and improving insurance performance among the fast-growing public property and casualty InsurTechs we examined.
The company has maintained approximately 32% annual growth in in-force premium across consecutive quarters, increased its customer base by nearly 23%, and improved its gross loss ratio.
Those operating trends give us more confidence than the revenue growth figure alone.
However, maintaining the same pace becomes increasingly demanding as Lemonade gets larger.
At $1.43 billion in annualized in-force premium, another 32% increase would require approximately $458 million in additional in-force premium over twelve months.
That's a substantial amount of new insurance business to add while keeping claims under control.
Its competitors face different challenges.
Kin's expanding renewal portfolio is encouraging, but its broadly flat new written premium in 2025 raises questions about how quickly it can accelerate customer acquisition.
Hippo has considerable room to expand in casualty and commercial insurance. The test will be whether its newer premium volume continues producing attractive underwriting results.
Oscar has already reached enormous scale, but its future growth is particularly exposed to health insurance enrollment patterns, government policy, premium affordability, and medical costs.
Cover Genius has an interesting advantage through embedded distribution. Adding insurance products to established digital platforms can put the company in front of large customer bases without having to build all those relationships directly.
But maintaining 50% revenue growth will still require additional integrations, stronger sales through existing partners, or new insurance products.
Lemonade's financial disclosures give us the clearest view of sustained growth. Cover Genius looks promising, and Oscar is operating at a much larger scale, but we have less comparable evidence that any of these businesses can maintain their latest growth rates indefinitely.
If you want more recent data on this point, please see our latest InsurTech market report.

If you build or invest in the insurtech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Which InsurTech startup is growing the fastest overall?
Lemonade is currently the fastest-growing established publicly traded property and casualty InsurTech in our comparison, with 79.4% year-over-year revenue growth in the second quarter of 2026. No company can be verified as the fastest-growing InsurTech worldwide without comparable financial results from private startups.
Oscar Health is the strongest contender when growth is measured in absolute revenue dollars. Its approximately $2.02 billion quarterly revenue increase dwarfs Lemonade's $130.3 million increase, while its membership grew 46%.
Hippo stands out for premium-volume growth, with gross written premiums up 61.5%. Cover Genius is one of the strongest disclosed private candidates, posting 50% annual revenue growth, while Kin grew revenue 29% and reported substantial improvements in its operating results.
Lemonade's revenue growth needs some adjustment in how we interpret it. Changes in reinsurance arrangements helped push the headline figure higher than the company's underlying premium growth.
Even with that distinction, its approximately 32% in-force premium growth, sustained customer expansion, and improving loss performance make it an unusually strong growth story.
For investors or readers looking for the clearest current leader among public property and casualty InsurTechs, Lemonade is our choice. Oscar deserves the title for absolute revenue expansion, while Cover Genius remains one of the more interesting private challengers.
The biggest unknown is the newer generation of AI insurance software startups. Some may already be growing considerably faster in percentage terms, but until their revenue figures are disclosed, naming one as the global winner would be speculation.
Our methodology
To answer which InsurTech startup is growing the fastest, we examined the question across several dimensions: reported revenue growth, absolute revenue expansion, customer and premium growth, operating performance, and the ability to sustain that momentum. We combined recent company disclosures with independent industry research, assessing each dimension separately before drawing an overall conclusion.
We used year-over-year revenue growth as the main comparative measure, then examined customer numbers, premiums, retention, and profitability to understand what was actually driving it. This distinction was particularly important for Lemonade, whose changing reinsurance arrangements contributed to revenue growing considerably faster than its underlying in-force premium.
We separated percentage growth from absolute revenue increases and distinguished insurance revenue from gross written premiums, recurring software revenue, and cumulative insurance sales. We also considered reporting periods and business models before identifying category leaders. The resulting comparison prioritizes measurable commercial expansion rather than valuations, fundraising announcements, or market perception.
For sustainability, we looked at how growth developed across reporting periods and whether operating performance improved alongside it. Customer acquisition, renewal activity, loss ratios, underwriting profitability, and margin development helped us distinguish rapid expansion from growth increasingly dependent on pricing, accounting changes, or financial risk.
We prioritized primary financial disclosures and company-reported operating data, complemented by independent sector research. Publicly traded insurers provide a more consistent financial record, while private companies and emerging AI insurance vendors are assessed using their disclosed results rather than estimated or assumed revenue. Our conclusions reflect the combined weight of the available evidence across these different dimensions.
Key company sources include Lemonade's Q2 2026 SEC filing, Lemonade's investor relations disclosures, Oscar Health's Q2 2026 financial results, Oscar Health's SEC disclosure, Hippo's Q2 2026 results, Root's Q2 2026 shareholder letter, Root's FY2025 shareholder letter, and EverQuote's Q2 2026 results.
For private InsurTechs and insurance software, we used Kin's FY2025 operating results, Cover Genius's 2026 financing and business update, and Ondo InsurTech's FY2026 results. Broader market context comes from CB Insights' 2026 Insurtech 50, CB Insights' State of Insurtech 2025, AM Best's U.S. property and casualty industry reporting, and the NAIC's 2026 Report on the Cybersecurity Insurance Market.

Theory only gets you so far. In our report covering the insurtech market, we dig up the real signals from the field and show you the ones worth watching.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us