How big is the Legal Tech market really?
Whether you're building or investing in the Legal Tech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The Legal Tech market is roughly $35 billion globally today, with serious current estimates clustering between about $31 billion and $37 billion.
The disagreement around market size is mostly a definition problem. Contract management, compliance, implementation services and consumer legal platforms can add billions depending on where researchers draw the boundary. Where the line falls for contract management, compliance and consumer platforms is a definition we set out in our legal tech market report.
Software is meaningfully smaller than the headline market. Under Grand View Research's latest breakdown, software represented 75.5% of Legal Tech revenue in 2025, putting the software layer at roughly $21.7 billion rather than $35 billion.
The company numbers support a market measured in tens of billions. Thomson Reuters Legal Professionals and LexisNexis Legal & Professional alone generate several billion dollars annually, before adding Clio, LegalZoom, Intapp, litigation platforms, contract software and hundreds of specialist vendors.
Dedicated Legal AI is still much smaller, at roughly $2.1 billion under one current estimate. But that number increasingly understates AI's commercial importance because established research, case-management and workflow subscriptions are absorbing AI rather than selling it as a separate category.
The new AI vendors are not simply replacing Westlaw and LexisNexis yet. Harvey and Legora have grown unusually quickly while Thomson Reuters and LexisNexis continue to expand, which suggests that firms are currently adding a new software layer rather than funding AI entirely by cancelling old tools.
Buyer behavior is moving faster than the market-size number suggests. Law firms increased technology investment by 9.7% in 2025, while corporate legal teams are prioritizing AI and technology even when headcount and outside-counsel budgets remain constrained.
The most important scale comparison sits outside Legal Tech itself. Global legal services are worth about $1.16 trillion, making the current Legal Tech market equivalent to only around 3% of annual legal-services revenue.
That creates a much larger economic opportunity than conventional SaaS forecasts imply. A shift affecting just 3% of today's legal-services economics would represent roughly $35 billion, about another entire Legal Tech market at its current size.
The business model may change along with the market. Usage-based AI pricing, automated contract review and systems capable of completing larger pieces of legal work could let vendors charge for activity and output rather than mainly for software seats.
A $50 billion Legal Tech market therefore looks plausible within a few years, but the more interesting question is not whether today's $35 billion grows normally. It is how much spending can move from software that organizes lawyers' work toward technology that actually performs part of that work.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the legaltech market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why does nobody agree on the size of the Legal Tech market?
Legal Tech is difficult to size because researchers are often measuring different markets under the same name.
An e-discovery platform built for litigation teams clearly belongs in Legal Tech. The same is true for legal research, law-firm practice management and specialist legal AI. Things become less obvious when we reach contract management, compliance software, consulting, managed services and consumer legal platforms.
That difference is large enough to move a market estimate by billions of dollars. Because the boundary can move estimates by billions, we build our own size from the ground up, with every assumption visible, in our report on legal tech.
Grand View Research, for example, includes software and services across e-discovery, legal research, practice management, analytics, compliance, document management, contract lifecycle management and billing. Its latest study says contract lifecycle management alone represented 25.6% of Legal Tech revenue in 2025.
Other researchers draw the borders differently. Gartner currently breaks the Legal Tech landscape into 17 technology markets. Some studies include implementation and support services. Others stay closer to software. Corporate contract tools can also be counted even when procurement, sales and finance use them as much as the legal department.
So before asking whether Legal Tech is a $30 billion, $40 billion or $50 billion market, we need to know what has actually been counted.
How big is the Legal Tech market today?
The best current answer is roughly $35 billion, with serious 2026 estimates clustering between about $31 billion and $37 billion.
Grand View Research currently estimates the market at $31.1 billion, up from $28.7 billion in 2025. Fortune Business Insights, whose estimate was updated recently, puts it at $36.72 billion after $33.97 billion in 2025. The Business Research Company has also published an estimate around $36 billion.
That is a useful convergence. These firms use different methodologies, yet the current estimates still land within roughly $6 billion of one another.
The range also tells us what Legal Tech probably is not. A current figure below $10 billion looks too small once we compare it with the revenue of the largest vendors. A figure above $50 billion already requires a wider definition or a future forecast rather than a clean estimate of today's core market.
We would therefore use about $35 billion as the practical headline number. Anything more precise than that starts giving the decimal place more credibility than the underlying definitions deserve.
| Market estimate | 2025 estimate | 2026 estimate | Longer-term forecast | Useful takeaway |
|---|---|---|---|---|
| Grand View Research | $28.7B | $31.1B | $69.7B by 2033 | Lower end of the main current range |
| Fortune Business Insights | $33.97B | $36.72B | $77.93B by 2034 | Upper end of the main current range |
| The Business Research Company | ~$33.0B | ~$36.0B | ~$51.2B by 2030 | Very close to Fortune's current estimate |
| Grand View Research software share | ~$21.7B | - | - | Software alone is already above $20B |
| Grand View Research services share | ~$7.0B | - | - | Services explain part of the broad headline TAM |
| Grand View Research Legal AI | - | $2.1B | $3.9B by 2030 | AI is still a minority of total Legal Tech |
| Practical range we would use | $29–34B | $31–37B | - | About $35B is the most useful current shorthand |

In our research about legal technology, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
What should actually count as Legal Tech?
Legal Tech should cover products whose value depends mainly on legal work, while general business software should only count when the legal portion can be separated sensibly.
Westlaw, Lexis+, Clio, Harvey, Legora, e-discovery platforms, legal billing systems and matter-management software are easy cases. They were built for lawyers or legal departments and are bought primarily to perform legal work.
Contract lifecycle management is trickier. Icertis and similar platforms deal with contracts, but legal teams are only part of the user base. Procurement negotiates contracts. Sales creates them. Finance tracks obligations. Operations depends on them. Counting every dollar of enterprise CLM revenue as Legal Tech stretches the category.
Horizontal AI creates the same problem. A law firm buying Harvey is clearly buying Legal Tech. A lawyer using ChatGPT or Microsoft Copilot is using AI for legal work, but OpenAI's or Microsoft's entire subscription revenue obviously cannot be moved into the Legal Tech column.
LegalZoom sits somewhere in between software and legal services. The company generated $756 million in 2025, but customers are paying for a combination of technology, subscriptions and access to legal help. The revenue tells us something important about digitized legal work, even though it is not pure SaaS.
Our definition therefore needs to be broad enough to capture how legal work is really being digitized without turning every product that touches a contract into Legal Tech.
How much of Legal Tech is actually software?
Legal Tech software itself is probably a little above $20 billion today, with services making up a meaningful part of the larger market estimates.
Grand View Research says software represented 75.5% of its $28.7 billion market in 2025. That works out to roughly $21.7 billion. The remaining $7 billion or so comes from services. Software and services earn money in different ways, and we look at which keep their margins in our report covering the legal tech market.
This changes how we should read a "$35 billion Legal Tech market."
A startup selling subscriptions does not have $35 billion of directly addressable SaaS spending waiting for it. Part of that number covers consulting, implementation, support and other services. The software portion is then divided again among legal research, e-discovery, case management, contracts, billing, compliance, document tools and several smaller categories.
Contract lifecycle management was the largest category in Grand View Research's latest breakdown, at 25.6% of the market. Law firms represented 53.9% of end-user revenue.
Legal Tech is already a sizable software market, but it is fragmented across many jobs that lawyers do rather than concentrated in one giant product category.

In our market report about legal technology, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Do real Legal Tech companies actually add up to a $35 billion industry?
Yes. The revenue of the largest Legal Tech businesses makes a market in the tens of billions quite believable before we even reach the long tail of smaller vendors.
Thomson Reuters' Legal Professionals segment generated $2.868 billion in 2025. LexisNexis Legal & Professional produced £1.806 billion. LegalZoom generated $756 million. Intapp reported $577.8 million in its latest fiscal year, although part of Intapp serves professional-services firms outside law.
The private market has become substantial too. Clio has now passed $500 million in annual recurring revenue. Harvey is estimated around $400 million ARR. Icertis operates at several hundred million dollars of annual revenue or recurring revenue depending on the measure used. Filevine has also reached the hundreds-of-millions range according to private-market estimates.
DISCO, which is much narrower than these platforms, generated $156.8 million in 2025 from e-discovery and litigation technology.
We cannot simply add every figure. ARR and recognized revenue are different, some companies sell beyond legal departments, and several vendors combine software with services.
Still, the order of magnitude works. A relatively small group of vendors already accounts for several billion dollars, and behind them sits a very long list of specialist products in research, litigation, contracts, compliance, billing, intellectual property and firm management.
| Company | Latest useful commercial figure | What we are actually measuring |
|---|---|---|
| Thomson Reuters Legal Professionals | $2.868B | 2025 segment revenue |
| LexisNexis Legal & Professional | £1.806B | 2025 segment revenue |
| LegalZoom | $756M | 2025 revenue |
| Intapp | $577.8M | Latest fiscal-year revenue; not exclusively legal |
| Clio | >$500M | ARR |
| Harvey | ~$400M | Estimated ARR |
| Icertis | Several hundred million dollars | Revenue/ARR depending on source and period |
| Filevine | Hundreds of millions of dollars | Private-market ARR estimate |
| DISCO | $156.8M | 2025 revenue |
| Legora | >$100M | ARR |
How big is legal AI right now?
Legal AI is already a multi-billion-dollar category, but it still represents a fairly small part of the broader Legal Tech market.
Grand View Research currently estimates the global legal AI market at $2.1 billion in 2026, up from $1.4 billion in 2024. Against a Legal Tech market around $31–37 billion, that puts dedicated legal AI at only about 6% of the total.
The number also understates how much AI is already influencing Legal Tech revenue because the boundary has become blurry.
Harvey's entire product is built around AI, so classifying its revenue is easy. Legora is similar. With Thomson Reuters or LexisNexis, the customer may buy a broader research or workflow subscription that now includes a large AI component. Clio combines practice-management software, legal intelligence and AI. Filevine is adding AI to a mature case-management platform.
LexisNexis gives us one of the clearest indications of how quickly that mix is changing. The company recently said AI-related products now account for 90% of its new business, while LexisNexis Legal is growing at the fastest rate in its history.
That does not mean 90% of LexisNexis revenue is AI revenue. It means AI has become central to winning new business even inside a company whose core legal databases existed decades before generative AI.
Dedicated legal AI is therefore much smaller than Legal Tech today, while AI-influenced Legal Tech is already becoming difficult to separate from the rest of the market.

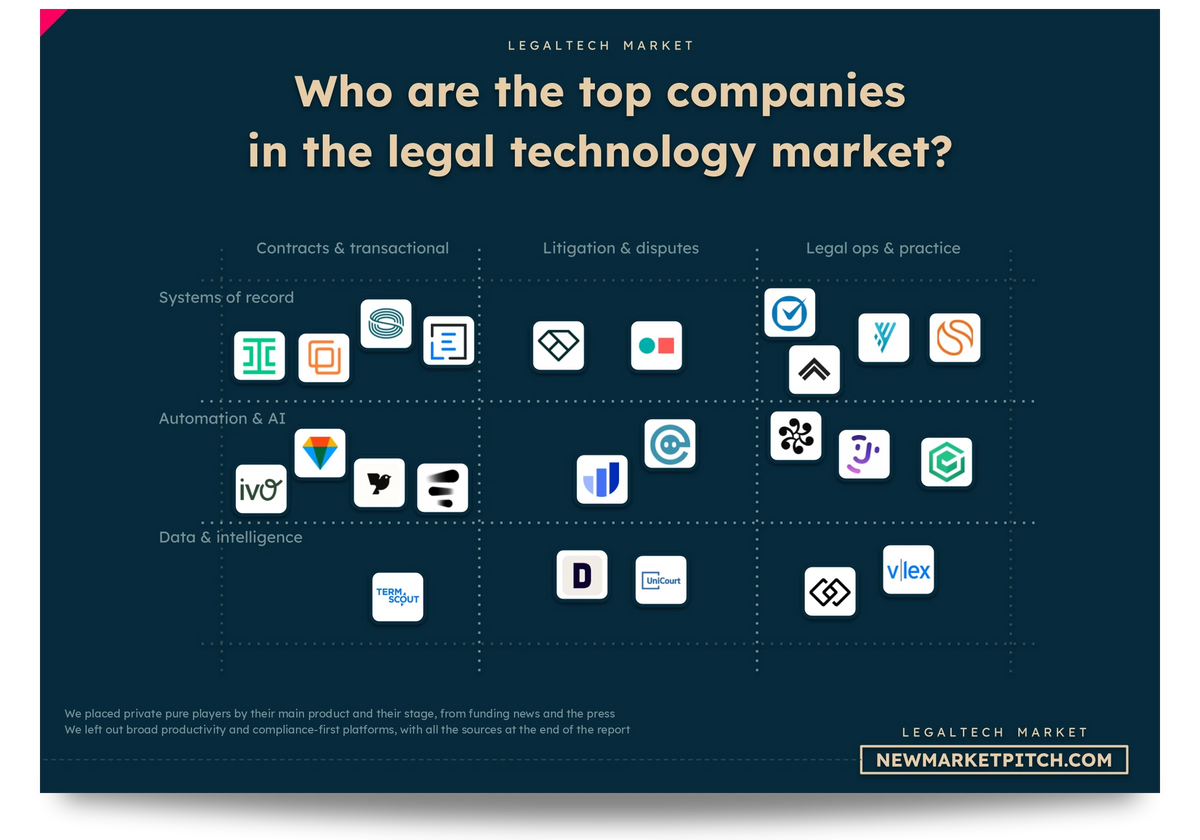
In our document detailing everything you need to know about legaltech, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Are Harvey and Legora really taking business from Westlaw and LexisNexis?
Harvey and Legora are winning serious legal work, but the latest numbers do not show the old research platforms collapsing.
Harvey has gone from an AI experiment to a business estimated around $400 million ARR, and the company says its platform is used by 80% of the Am Law 100. Legora has already crossed $100 million ARR and signed firms including White & Case, Cleary Gottlieb and Goodwin. How the new AI players stack up against the established legal publishers is shown on the market maps in our market report about legal tech.
Those are no longer small startup adoption stories.
At the same time, LexisNexis Legal has just reported the fastest growth in its history. Revenue grew 9% on an underlying basis in 2025, growth reached 10% in the first half of 2026, and management says AI-related products account for 90% of new business.
Thomson Reuters is moving in the same direction. Legal Professionals produced $2.868 billion in 2025 and still grew 8% organically despite the reported revenue figure being affected by disposals. Westlaw and CoCounsel remain central products.
For now, many large firms are paying for the new AI layer while keeping the legal databases and workflows they already depend on. That can change as products overlap more, but the current market looks more like expanding software spend than a simple transfer from incumbents to startups.
Competition can become much fiercer while the biggest incumbents keep growing. Right now, both things are happening at once.
Are law firms really spending much more on Legal Tech now?
Yes. Law firms increased technology investment by almost 10% last year, which is unusually fast for a mature professional-services industry.
The latest Thomson Reuters and Georgetown Law report found that average law-firm technology investment rose 9.7% in 2025. Lawyer compensation rose 8.2% over the same period, so technology was growing even faster than one of the industry's largest cost lines.
This was not happening during a weak year for law firms either. Demand was strong and profits per lawyer across the Am Law 100 had risen 53.7% compared with 2019.
Firms were not buying more technology simply because business was collapsing and they needed emergency cost cuts. Many were profitable and still spending heavily on AI, knowledge systems and workflow tools.
The latest adoption data points in the same direction. Thomson Reuters found active GenAI use at 41% of law firms in its 2026 research, compared with 28% a year earlier.
The exact percentages vary from survey to survey because some measure personal AI use while others measure formal firm deployment. The spending figure is harder to dismiss: real technology budgets are moving up quickly.

Our report covering the legaltech market gets updated several times a month, so you always get the latest view of where things stand.
Are corporate legal departments spending more on Legal Tech too?
Corporate legal departments are turning more heavily toward technology even though many of them do not have much more money to spend.
CLOC's latest State of the Industry research found that 80% of legal-operations teams now consider technology strategy a priority and 85% of legal departments have dedicated AI oversight or resources.
Yet only 47% expect inside legal spending to rise. Just 37% expect outside-counsel spending to increase, down sharply from 58% in the previous survey. Only 32% expect attorney headcount to increase.
The workload is moving the other way. Some 63% reported rising demand around regulatory compliance and 58% around cybersecurity.
That creates a simple constraint: more work is arriving without matching growth in lawyers or outside-counsel budgets.
Technology is increasingly being asked to absorb part of that gap.
The newest pricing evidence makes this more concrete. Gartner says major legal AI vendors are now moving away from purely predictable per-seat subscriptions toward hybrid models that charge partly according to AI usage. Gartner expects consumption-based pricing to represent more than 35% of net new corporate Legal Tech spending with major vendors by 2028.
If that happens, Legal Tech revenue will depend increasingly on how much legal work software performs rather than simply how many lawyers have seats.
How small is Legal Tech compared with the amount spent on legal services?
Legal Tech currently generates only a few cents for every dollar spent on legal services worldwide.
Grand View Research estimates the global legal-services market at about $1.16 trillion in 2026. Put beside our roughly $31–37 billion Legal Tech range, Legal Tech is equivalent to only around 3% of that amount. Legal tech equals about 3% of legal-services spend, and the growth drivers that could change that are weighed in our legal tech market report.
This is an order-of-magnitude comparison rather than a formal market-share calculation. The two markets do not have identical boundaries. Legal-services revenue largely measures professional work, while Legal Tech includes software and some technology-related services. Internal legal-department salaries create another complication.
The scale gap is still enormous.
Legal technology is already a serious industry with several billion-dollar businesses, yet human legal services remain more than 30 times larger.
That is why the AI opportunity can look enormous even when the current Legal Tech TAM does not.
How much legal work would AI need to capture to make Legal Tech much bigger?
A shift of only 1% of global legal-services economics would represent roughly $11.6 billion, enough to enlarge today's Legal Tech market by about one-third.
This calculation is more useful than another distant TAM forecast.
Using Grand View Research's current legal-services estimate of about $1.16 trillion, a 2% shift corresponds to roughly $23 billion. At 3%, we reach almost $35 billion, which is around the size of the entire Legal Tech market today. A 5% shift would represent close to $58 billion.
We are not forecasting that those percentages will move directly from law firms into software-company revenue. The value can be captured in several ways. A law firm may automate work and keep much of the savings as higher margin. A corporate department may reduce outside-counsel bills. A vendor may charge more as its AI completes more work. Clients may eventually capture part of the gain through lower prices.
But the calculation shows how little needs to change before the economics become large.
| Share of current legal-services economics affected | Approximate value at a $1.16T legal-services market | Compared with today's Legal Tech market |
|---|---|---|
| 0.5% | $5.8B | Already a meaningful additional category |
| 1% | $11.6B | Roughly one-third of today's Legal Tech market |
| 2% | $23.2B | Around two-thirds of today's market |
| 3% | $34.7B | Roughly another Legal Tech market |
| 5% | $57.9B | Far larger than current Legal Tech software spending |
| 7.5% | $86.9B | More than twice today's broader Legal Tech market |
| 10% | $115.8B | More than three times today's market |

In our research about legal technology, you will always find fresh funding data, taken straight from our own verified funding database.
Is Legal Tech becoming one big platform market?
Legal Tech is still fragmented today, but the largest companies are clearly trying to own more of the lawyer's workflow.
Gartner's map still identifies 17 separate Legal Tech markets. That reflects how the industry developed: legal research, discovery, billing, contracts, practice management and matter management were traditionally bought as different products.
Recent acquisitions are starting to erase some of those boundaries.
Clio's $1 billion acquisition of vLex is the strongest example. Clio built its business around law-firm operations and practice management. vLex added a huge legal-information database, research products and the Vincent AI platform. One company can now serve both the business of running a law firm and part of the legal work performed inside it.
Wolters Kluwer has been moving in a similar direction through its planned acquisition of Brightflag, a legal spend and matter-management platform, for roughly €425 million. Clio had already bought ShareDo to reach larger law firms and enterprise legal teams.
AI makes this consolidation more logical. A lawyer asking one interface to research a case, inspect documents, draft text and update a matter has less reason to think of each underlying function as a completely separate product.
Specialist tools will remain important, especially in areas where proprietary data or deep workflow knowledge matters. But the company controlling the main interface can capture more of the customer's budget.
That is where the platform battle is heading now.
Will AI actually kill the billable hour?
AI will put more pressure on hourly billing, although law firms have barely started changing their pricing models.
Thomson Reuters found that 71% of in-house legal professionals expect outside firms to change their commercial models as AI use increases. Only 28% of law firms said they had already changed pricing because of AI.
That gap is likely to become uncomfortable.
If a research task that used to take four hours can be completed in one, clients will eventually ask why they should pay for four. Firms can respond in several ways: keep hourly pricing and improve margins, lower the number of hours billed, move toward fixed fees, or price more work around outcomes and value.
The latest market data shows that law firms are still doing very well under the existing model. Strong demand and rising rates helped produce another profitable year, so they have little reason to abandon hourly billing overnight.
The pressure should become stronger as AI moves from helping individual lawyers write faster to completing larger pieces of a legal workflow.
That transition could change Legal Tech economics quite a lot. Software vendors have a much larger revenue opportunity if customers begin paying partly for work completed rather than mainly for seats.

In our market report about legal technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
Why are Legal Tech valuations so high if the market is only about $35 billion?
The biggest Legal Tech valuations assume that software will eventually capture more of the money currently spent on legal work, rather than simply taking share inside today's $35 billion technology market.
Harvey provides the clearest example. The company has been valued at $15.5 billion while private-market estimates put ARR around $400 million. Legora reached a valuation around $5.6 billion after crossing $100 million ARR. Those are very rich valuations if we assume they are fighting only for a fixed slice of today's Legal Tech spending. Valuations that assume a much bigger market are a risk we rate by likelihood in our report on legal tech.
Clio looks different. The company has passed $500 million ARR and was valued at $5 billion around the period of its vLex transaction and financing. It already has a much larger revenue base relative to its valuation.
The gap tells us what investors are paying for in the AI-native companies.
They are betting that legal AI can monetize tasks that were previously sold as lawyer time: research, document review, drafting, due diligence, contract analysis and parts of litigation preparation.
With a legal-services market above $1.1 trillion, capturing even a small part of that work changes the revenue ceiling.
Whether today's valuations prove sensible will depend much more on that shift than on whether conventional Legal Tech grows from $35 billion to $40 billion.
Can Legal Tech realistically become a $50 billion market soon?
Yes. A $50 billion Legal Tech market now looks plausible within a few years, although some forecasts get there much faster than others.
Grand View Research expects its $31.1 billion 2026 market to reach $69.7 billion by 2033, implying 12.2% annual growth. Fortune Business Insights starts higher at $36.72 billion and expects $77.93 billion by 2034.
Those growth rates put $50 billion comfortably within reach before the end of either forecast period.
Gartner is even more aggressive on actual technology budgets. Its latest research predicts that legal departments will double Legal Tech budgets by 2028 as specialized AI spreads across research, litigation support, contract review, due diligence and intake.
Gartner also expects around half of contract reviews to be delegated to self-service systems by 2029, with only one in ten of those reviews escalated to a human. The same forecast says 60% of legal departments could use AI-driven intake systems that answer half of incoming requests without human involvement.
Those forecasts may prove too optimistic, particularly because corporate legal budgets remain constrained. But they describe a different kind of Legal Tech growth from the SaaS expansion of the last decade.
If software begins completing work rather than simply organizing it, revenue can grow faster than lawyer headcount.

If you build or invest in the legaltech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
How big is the Legal Tech market really?
Legal Tech is currently about a $35 billion global market, and that is the number we would use rather than stretching today's market into a $50 billion or $100 billion story.
The freshest serious estimates put 2026 Legal Tech revenue between roughly $31 billion and $37 billion. Software probably accounts for a little above $20 billion of the market under one major methodology. Dedicated legal AI is much smaller at around $2.1 billion, although AI is now influencing an increasingly large share of spending across older Legal Tech products.
The company data supports that scale. Thomson Reuters Legal Professionals produces almost $2.9 billion annually. LexisNexis Legal & Professional generates £1.8 billion. Clio has crossed $500 million ARR. Harvey is already estimated around $400 million ARR. Legora has passed $100 million.
What makes the market unusually interesting today is the size of the industry sitting beside it. Global legal services are now estimated above $1.15 trillion. Legal Tech therefore remains equivalent to only around 3% of annual legal-services revenue.
We can already see the boundary moving. Law firms increased technology investment 9.7% last year. LexisNexis says AI-related products now make up 90% of new business. CLOC finds that 85% of corporate legal departments have dedicated AI oversight or resources. Gartner expects Legal Tech budgets to double by 2028 and usage-based AI charges to become a major part of new corporate spending.
As we saw above, only a 3% shift in the economics of legal services would represent roughly another $35 billion.
So the clean answer today is about $35 billion. The bigger question is how quickly Legal Tech starts charging for work that used to be billed almost entirely through lawyers. That is where the market can become much larger than the current estimates suggest.
Our methodology
We approached this as an evidence-aggregation problem rather than a single-source market-sizing exercise. We broke the question into several dimensions that could independently test whether the final answer made sense: published market estimates, category boundaries, software and services, actual company revenues, Legal AI, buyer spending and adoption, consolidation, pricing models, and the much larger legal-services economy surrounding the technology market.
For current market size, we compared several recent research estimates rather than selecting the largest or smallest figure. Grand View Research, Fortune Business Insights and The Business Research Company form the main sizing cross-check because their latest estimates land in a relatively tight range despite differences in scope.
We kept different commercial measures separate. Recognized revenue is not ARR, ARR is not valuation, adoption is not spending, and a forecast is not a current market size. Where private-company numbers are estimates rather than formal financial disclosures, we treat them as estimates.
Company economics are used as a sanity check on the market estimates. Public disclosures from Thomson Reuters, RELX, LegalZoom, Intapp and DISCO show the observable scale of established Legal Tech businesses, while Clio, Harvey and Legora provide useful evidence on how quickly newer private platforms are becoming commercially significant.
We also separate dedicated Legal AI from Legal Tech products that increasingly contain AI. A company such as Harvey can be classified relatively cleanly, while an AI feature sold inside a broader Westlaw, LexisNexis, Clio or case-management subscription cannot always be isolated as a separate revenue stream.
Buyer data is used to test whether the growth implied by market forecasts is visible in actual behavior. Thomson Reuters and Georgetown Law provide the law-firm technology-spending evidence, while CLOC gives us the corporate legal-operations view. Gartner's research is used for changes in Legal Tech budgets, workflow automation and consumption-based AI pricing.
The global legal-services market is used differently. It is a scale reference, not an extension of the Legal Tech market. The percentage-shift calculations above are sensitivity tests showing the economic size of small changes in how legal work is performed and monetized; they are not forecasts that the same percentage of legal-services revenue will move directly into software-company revenue.
We also looked at acquisitions and platform expansion to understand whether historically separate Legal Tech categories are beginning to converge. Clio's acquisition of vLex and Wolters Kluwer's planned acquisition of Brightflag are particularly useful because they combine established workflow products with legal data, AI, spend management or matter management.
We gave more weight to recent, observable evidence than to distant forecasts. The roughly $35 billion figure comes from convergence between independent market estimates, company economics and buyer behavior rather than from mechanically averaging every number available.
Key sources include Grand View Research's Legal Technology Market report, Fortune Business Insights' Legal Technology Market report, The Business Research Company's Legal Technology report, Gartner's Legal Technology Market Map, Grand View Research's Legal AI report, Grand View Research's Legal Services market report, Thomson Reuters' 2025 results, RELX's 2025 Annual Report, Clio's $500 million ARR announcement, Harvey's latest funding announcement, CLOC's 2026 State of the Industry research, LexisNexis on its latest Legal AI growth, Gartner on consumption-based AI pricing, Clio's vLex acquisition announcement, Wolters Kluwer's Brightflag acquisition announcement, and Thomson Reuters' Future of Professionals 2026 Legal report.

When you build or invest in the legaltech market, you need clarity, not confusion. In our report covering the legaltech market, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us