Which longevity company is closest to FDA approval?
Building a startup or looking for your next investment in longevity? Our report gives you the full picture.
Summary
No human longevity company now has a clear lead toward FDA approval. Loyal is much closer if dog longevity counts, Insilico Medicine is furthest along by trial stage, and Calico has the strongest rare-disease regulatory signals.
The central regulatory constraint is that the FDA still approves drugs for recognized diseases and conditions, not for “aging” itself. A longevity company can reach the market first without ever putting lifespan or biological age on the label. With no approval path for aging itself, a lot stays unresolved, and we cover the biggest open problems in our longevity market report.
That makes disease selection almost as important as the underlying aging science. Rare diseases can create surprisingly short regulatory paths, while a broad chronic-disease program may need much larger and longer trials even when the biology looks stronger.
Longeveron lost its place as the obvious human pure-play leader in September 2026, when its ELPIS II trial in hypoplastic left heart syndrome missed its primary endpoint. In October, the company reported far fewer major cardiac events in treated infants, but a positive secondary result does not erase a failed primary one.
Longeveron’s Alzheimer’s route still has a seamless Phase 2/3 design discussed with the FDA. The company now faces a strategic review, cost cuts and an advisor exploring a possible business combination, so financing that study is far from settled.
Insilico Medicine dosed the first patient in its Phase 3 rentosertib trial for idiopathic pulmonary fibrosis in September 2026. The trial runs in China, so it puts Insilico ahead on stage without showing a U.S. registration path.
Calico is the most credible rare-disease challenger. Fosigotifator holds FDA Breakthrough Therapy Designation and, since October 2026, EMA PRIME status in Vanishing White Matter disease, though it is still in Phase 1b/2.
BioAge, Cambrian, Rubedo and Juvenescence are credible clinical-stage longevity companies, but they are still proving efficacy rather than negotiating a mature registrational package. Biomarker movement is useful; it is not the same thing as showing that patients live better or avoid meaningful disease outcomes.
Life Biosciences reported its first human data in October 2026, from three glaucoma patients, and Retro remains in Phase 1. Life’s partial epigenetic reprogramming program is the more radical rejuvenation experiment, while Retro has the simpler oral-drug format.
NewLimit’s huge financing does not make it close to approval. It is still preclinical, which is a useful reminder that capital, scientific ambition and regulatory distance are three very different things.
The most likely first “longevity” approval in humans will probably look ordinary on the FDA label: a treatment for a specific disease whose mechanism happens to come from aging biology. The broader claim that a drug changes human aging will need much more evidence than the first market authorization.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

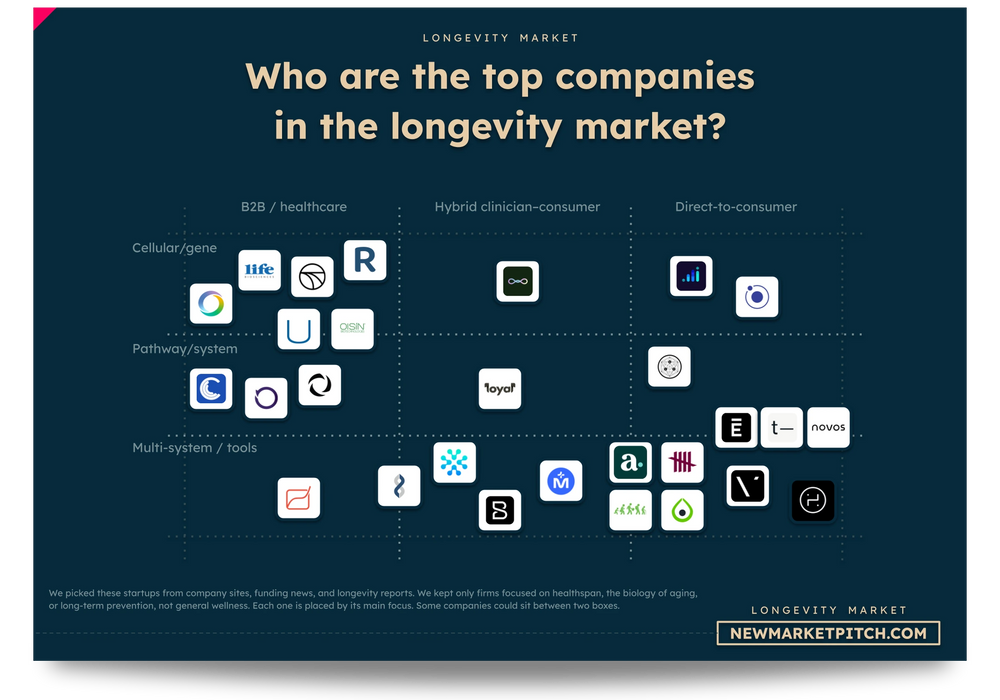
In our report covering the longevity market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Can the FDA actually approve a human longevity drug today?
No human company is currently close to getting a drug approved for “aging” itself, because the FDA still evaluates these therapies through specific diseases rather than aging as a standalone indication.
That distinction controls the whole ranking. A company can be built around longevity biology while pursuing FDA approval for Alzheimer’s disease, pulmonary fibrosis, glaucoma or a rare pediatric condition. The label on the eventual medicine may never mention lifespan or biological age.
Life Biosciences is testing partial cellular reprogramming, one of the most radical attempts to reverse age-related cellular changes, but ER-100 is still in Phase 1. Longeveron’s laromestrocel has several randomized Phase 2 studies behind it, but its most advanced one missed its main goal in September 2026. Insilico Medicine has gone further on stage with rentosertib, which started a Phase 3 trial for idiopathic pulmonary fibrosis in China that month.
The FDA has also qualified no aging biomarker as a surrogate endpoint for an approval based on slowing aging. Biological-age clocks can strengthen the scientific case, but today a company still needs to show that patients with a recognized condition actually benefit.
Does Loyal become the obvious winner if dog longevity counts?
Yes. If veterinary longevity counts, Loyal is currently far closer to an FDA market authorization than any human longevity company.
LOY-002 is a daily pill being developed for dogs aged 10 and older. Loyal is using the FDA Center for Veterinary Medicine’s expanded conditional approval pathway, which can allow a veterinary drug onto the market before the full effectiveness package has been completed.
LOY-002 has cleared two of the three major technical sections needed for conditional approval. The FDA accepted Loyal’s reasonable-expectation-of-effectiveness package in 2025 and its target-animal safety package in early 2026. Loyal’s own tracker still shows manufacturing and chemistry in progress, and no approval decision has been announced.
In September 2026, Loyal said the FDA had also accepted reasonable-expectation-of-effectiveness evidence for LOY-003, its program for large and giant breeds. That widens the pipeline, but it does not complete the missing manufacturing section for LOY-002.
The company is also running STAY, a study of more than 1,300 dogs across about 70 veterinary practices designed to test whether LOY-002 extends healthy lifespan. That larger study matters for eventual full approval, but Loyal does not have to wait for the final survival result before a conditional launch becomes possible.
Conditional approval carries a real qualification: the effectiveness standard is lower than the one required for full approval. Yet a conditionally approved drug can legally be prescribed and sold while the company continues generating the evidence needed for full approval.

Our research about longevity companies gets updated several times a month, so you always get the latest view of where things stand.
Which human longevity company is actually closest to FDA approval?
There is no clear single answer anymore. The ranking depends on whether you count trial stage, FDA designations or patient data, and each measure points to a different company.
By stage, Insilico leads: rentosertib is in Phase 3, but in China. By regulatory signal, Calico leads: fosigotifator has FDA Breakthrough Therapy Designation and EMA PRIME status in a rare disease, but only Phase 1b/2 data. By volume of randomized human data, Longeveron still has the most among pure-plays, but its lead HLHS trial missed its primary endpoint in September 2026.
The rest of the field is earlier. BioAge has two Phase 2 trials running for BGE-102. Cambrian has early human data and is preparing Phase 2 programs. Life Biosciences and Retro are in Phase 1. NewLimit remains preclinical. Companies sit anywhere from preclinical to Phase 3, and we cover which ones are pulling ahead in our report covering longevity.
Longeveron’s fall is the main reason the answer changed. Before September, it looked like a company one good Phase 2b readout away from a filing discussion. Now it needs the FDA to accept a case built on secondary endpoints, while it reviews strategic options.
Our read today: Calico and Insilico form the front group, with Longeveron just behind. None has a disclosed U.S. marketing application.
| Company | Most advanced relevant program | Current position | Our read |
|---|---|---|---|
| Calico | Fosigotifator | Phase 1b/2, FDA Breakthrough Therapy, EMA PRIME | Strongest rare-disease contender |
| Insilico Medicine | Rentosertib | Phase 3 in IPF, in China; no U.S. registration path disclosed | Furthest along by stage, not a pure-play |
| Longeveron | Laromestrocel | Phase 2b missed primary endpoint; FDA meeting planned | Most human data, weakened path |
| BioAge | BGE-102 | Two Phase 2 trials | Needs clinical proof-of-concept |
| Cambrian | ATX-304 | Phase 1b completed, Phase 2 planned | Still early |
| Life Biosciences | ER-100 | Phase 1, first data in 3 patients | First reprogramming program in humans |
| Retro Biosciences | RTR242 | Phase 1 | Early human development |
| NewLimit | Liver reprogramming program | Preclinical | Human trial planned next |
Can Longeveron’s cardiac-event benefit overcome ELPIS II’s failed endpoint?
Not on its own. ELPIS II missed its primary endpoint, so any FDA filing would rest on secondary results the agency has not yet reviewed.
ELPIS II is a 40-patient randomized Phase 2b trial testing laromestrocel alongside surgery in babies with hypoplastic left heart syndrome, or HLHS. The program has Orphan Drug, Fast Track and Rare Pediatric Disease designations, and the trial is supported through the National Heart, Lung, and Blood Institute.
Longeveron reported topline results on 16 September 2026. The primary endpoint, change in right-ventricular ejection fraction at 12 months, showed no benefit: a difference of −0.7 percentage points, p=0.8336. The FDA had already told the company in 2026 that this endpoint was not enough to show efficacy and no longer saw ELPIS II as pivotal.
On 26 October 2026, Longeveron released further analyses. The prespecified secondary endpoint of major adverse cardiac events showed 8 events in the standard-care arm versus 1 in the treated arm, p=0.043. Total major cardiac events were 22 versus 3, a rate ratio of 0.16. In September, the company had reported an as-treated count of 19 versus 12 that was not statistically significant, and the two releases do not explain the gap between these counts.
The company plans to request an FDA meeting, with no date disclosed, and will present the data at the American Heart Association meeting in November 2026. In parallel, it started a strategic review and cost cuts in September, and in October hired Lucid Capital Markets to explore options including a potential business combination.
The cardiac-event signal is the most interesting thing to come out of the trial. But a small study, a missed primary endpoint and inconsistent event counts make another trial the more likely outcome than a quick filing.

In our market report about longevity companies, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Longeveron’s Alzheimer’s program actually a cleaner FDA route?
On paper, yes. It is now Longeveron’s most plausible remaining route, but it is further from a readout and has no funded trial.
The company completed the randomized CLEAR MIND Phase 2a study in 48 people with mild Alzheimer’s disease. The study was primarily designed around safety, but Longeveron also reported encouraging results across a composite clinical score and MRI measures of brain-volume loss.
The FDA subsequently granted laromestrocel Regenerative Medicine Advanced Therapy and Fast Track designations for mild Alzheimer’s disease.
During a Type B meeting, Longeveron says it reached tentative alignment with the FDA on the basic design of a single seamless adaptive Phase 2/3 study, including the patient population, dose, placebo arm, treatment duration and endpoints. According to the company’s SEC filings, the FDA also agreed to consider a BLA based on positive interim results from that study.
The problem is execution. Longeveron has been seeking a partner to fund the Alzheimer’s trial, and the ELPIS II miss has made that harder: the company is cutting costs and weighing strategic options. A clear design is not the same as a positive confirmatory study, and that study has not started.
Does Insilico’s Phase 3 in China put it closest to FDA approval?
It puts Insilico closest by trial stage, not necessarily closest to a U.S. FDA approval. Rentosertib is the most advanced human drug tied explicitly to aging biology, but its Phase 3 runs in China.
Rentosertib is an oral TNIK inhibitor for idiopathic pulmonary fibrosis, a progressive lung disease that becomes much more common with age. Insilico originally identified TNIK through its AI drug-discovery platform using disease and aging-related biological data.
On 10 September 2026, Insilico dosed the first patient in GENESIS-IPF-3, a 52-week Phase 3 trial expected to enroll 320 patients across 47 centers in China. Insilico says it could take three to four years from the start of Phase 3 to approval under favorable conditions. That puts it one full clinical stage ahead of Longeveron, Calico, BioAge and the better-known cellular-rejuvenation startups. A full clinical stage between Insilico and the rest is a big gap, and we look at how far the challengers trail in our report on longevity.
The U.S. picture is less clear. Rentosertib has had FDA Orphan Drug Designation for IPF since 2023, but no U.S. Phase 3 or agreed U.S. registration path has been disclosed. A Chinese trial may support a Chinese approval first.
The biological-age analysis keeps the program interesting for longevity. Researchers applied six proteomic aging clocks to samples from the Phase 2 trial and reported that all six shifted toward a younger predicted biological age in patients receiving the drug. Those clocks have no role as validated surrogate endpoints, so the FDA would still judge rentosertib only on lung disease.
Insilico is usually described as an AI drug-development company rather than a pure longevity biotech. If readers accept it inside the category, it leads the human race on stage, with a clear asterisk on geography.

In our document detailing everything you need to know about longevity, you will always find fresh funding data, taken straight from our own verified funding database.
Does Calico’s FDA Breakthrough plus EMA PRIME status put it in front?
It puts Calico in the front group. Fosigotifator now has strong regulatory support on both sides of the Atlantic, but the clinical evidence is still Phase 1b/2.
Calico was founded around the biology of aging, yet for years its clinical position looked less advanced than its reputation and funding suggested. That changed when the FDA gave fosigotifator Breakthrough Therapy Designation in June 2026, and again when Calico said in October 2026 that the European Medicines Agency had granted PRIME designation based on preliminary Phase 1b/2 data.
The drug activates eIF2B and is being tested in a Phase 1b/2 study in adults, children and infants with Vanishing White Matter disease, a rare progressive neurological disorder with no approved disease-modifying treatment.
Both designations require early clinical evidence that a therapy may offer a major improvement for a serious condition. Neither is an approval, and Calico has not disclosed a marketing application. But rare neurological diseases can follow short development paths when patient numbers are small and the treatment effect is large.
Calico’s previous experience also gives us a reason to stay cautious. Fosigotifator was studied in ALS through the HEALEY platform trial and failed to show a statistically significant benefit on the main disease-progression endpoint. The VWM biology and patient population are different, so the ALS failure does not settle the VWM question.
Today, Calico has the cleanest regulatory momentum of any human longevity company, even if Insilico is further along on stage.
Is BioAge close to an FDA approval now?
No. BioAge has one of the stronger clinical pipelines in longevity biotech today, but BGE-102 still needs to prove that its impressive biomarker effect translates into meaningful patient benefit.
BioAge develops drugs by studying the biology of human aging and identifying pathways associated with healthier or less healthy aging trajectories. Its current lead asset, BGE-102, inhibits NLRP3, an inflammatory pathway increasingly linked to cardiovascular, metabolic and retinal disease.
The Phase 1 numbers were striking. BioAge reported median reductions of at least 85% in high-sensitivity C-reactive protein at its 60-milligram and 120-milligram once-daily doses. The company also reported good tolerability across the tested dose levels.
BioAge’s Phase 2 cardiovascular study, QUELL-CV, has completed enrollment, with topline data expected in the second half of 2026. Its primary endpoint is change in hsCRP, and it is designed to help pick a Phase 3 dose. In September 2026, BioAge also dosed the first participant in QUELL-DME, a Phase 2 trial of about 180 people with diabetic macular edema, with results expected in the second half of 2027.
A large reduction in an inflammatory biomarker can make the mechanism look compelling without proving that patients experience fewer cardiovascular events or better vision. BioAge still needs that clinical proof before an FDA approval path becomes concrete.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the longevity market, we look at what broke startups before you, so you don't repeat it.
How far behind are Cambrian and the other clinical longevity biotechs?
Cambrian, Rubedo and Juvenescence have become credible human-stage longevity companies, but none is currently close enough to an FDA filing to challenge the leaders.
Cambrian’s ATX-304 produced encouraging Phase 1b data in 23 adults with obesity and prediabetes. The company reported improvements in liver fat, visceral fat, triglycerides, adiponectin and resting metabolic rate after eight weeks. Phase 2 studies are still planned rather than running.
Cambrian also received up to $30.8 million from ARPA-H to advance its TORnado selective mTORC1 program. That program is even closer to classic geroscience because mTOR is one of the best-established aging pathways in experimental biology, but its regulatory development is earlier. ARPA-H funding is one source of money among many, and we cover who is funding whom in our longevity report.
Rubedo has generated one of the more interesting recent human datasets. Its RLS-1496 program entered Phase 1b/2a testing, and the company reported a 46% reduction in actinic keratosis lesions after four weeks in preliminary results. Counting skin lesions directly gives Rubedo a more concrete early efficacy measure than many biomarker-heavy longevity studies.
Juvenescence has also taken MDI-2517, a PAI-1 inhibitor, through Phase 1 and toward proof-of-concept development.
All three are past the purely preclinical stage. What separates them from Calico, Insilico and Longeveron is the lack of a late-stage trial, a major regulatory designation or a mature registrational discussion.
| Company | Recent human evidence | Next real test |
|---|---|---|
| BioAge | BGE-102 cut hsCRP by ≥85% at key doses in Phase 1 | QUELL-CV Phase 2 readout, then QUELL-DME |
| Cambrian | ATX-304 showed metabolic changes in 23 Phase 1b participants | Larger Phase 2 studies |
| Rubedo | RLS-1496 reported 46% AK lesion reduction at four weeks | Confirm effect in larger controlled cohorts |
| Juvenescence | MDI-2517 completed Phase 1 development | Phase 2 efficacy |
| Longeveron | Phase 2b missed primary endpoint; fewer cardiac events reported | FDA view on secondary data; funded Alzheimer’s trial |
Are Life Biosciences and Retro actually close to FDA approval yet?
No. Life Biosciences and Retro have both reached human testing, but their lead programs are still near the beginning of clinical development.
Life Biosciences crossed an important line when the FDA cleared its IND for ER-100 and the company dosed the first participant in 2026. ER-100 uses controlled expression of OCT4, SOX2 and KLF4 to push aged retinal cells toward younger patterns of gene expression.
This is the first in-vivo partial epigenetic-reprogramming therapy to reach human testing. The study plans up to about 18 participants with open-angle glaucoma or non-arteritic anterior ischemic optic neuropathy. In October 2026, Life reported the first data: ER-100 was well tolerated through Day 56 in three glaucoma patients, with no serious adverse events, and two showed early visual-field improvements. A safety board recommended moving to the next dose. Three uncontrolled patients are a signal, not proof of efficacy.
Retro Biosciences entered the clinic through a different route. It dosed the first participant with RTR242 in Australia in late 2025. The oral small molecule is designed to improve lysosomal function and autophagy, the cellular recycling process that removes damaged proteins and other waste.
Retro’s first study is in healthy volunteers and focuses mainly on safety, tolerability and exploratory biomarkers. Company executives have said the study has progressed without dose-limiting toxicities so far, which is encouraging but still far from evidence that RTR242 can slow Alzheimer’s disease.
Life Biosciences therefore has the more direct rejuvenation experiment, while Retro has the simpler oral-drug format and a large funding base. Both still need controlled human efficacy data before FDA approval becomes a serious near-term question.

In our research about longevity companies, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why is NewLimit still far from FDA approval after raising $435 million?
NewLimit remains preclinical, so its enormous funding round says much more about investor confidence than about proximity to FDA approval.
The company raised $435 million in 2026 at a reported valuation of roughly $3.1 billion, one of the largest private financings in the longevity sector. Its technology uses epigenetic reprogramming to restore youthful functions in old cells without pushing them all the way back into pluripotency.
NewLimit has made real technical progress. It narrowed its first clinical effort around liver biology and, in an October 2026 update, said it had scaled up manufacturing and run its first large-animal studies. That update did not report human dosing. The company said earlier in 2026 that it expected to start human testing in 2027.
Before approval becomes a serious conversation, NewLimit still has to finish preclinical safety work, clear the regulatory process needed to dose humans, establish tolerability, identify an appropriate dose, show an efficacy signal and then run later-stage studies.
Altos Labs sits even further from a public approval race. Despite billions of dollars in initial funding and some of the best-known scientists in rejuvenation research, Altos has yet to disclose a human therapeutic program comparable with Life Biosciences’ ER-100.
Could one rare-disease trial unexpectedly win the longevity FDA race?
Yes. Rare diseases create the clearest path for an earlier-stage longevity company to jump several places in the ranking.
Calico’s fosigotifator is the clearest example today. Vanishing White Matter disease has no approved disease-modifying therapy, the patient population is small, and the drug now has both FDA Breakthrough Therapy and EMA PRIME support. If the ongoing Phase 1b/2 study produces a large, consistent clinical effect, Calico could move into registrational discussions much faster than a Phase 1b/2 label normally implies.
Longeveron tried the same regulatory shortcut through rare pediatric heart diseases. Laromestrocel carries Orphan Drug, Fast Track and Rare Pediatric Disease designations in HLHS. Its pediatric dilated cardiomyopathy program has also been structured around a direct move into a registrational Phase 2 study, subject to financing.
These programs show why a simple phase ranking can fail. A 30- or 40-patient rare-disease study with dramatic hard outcomes can sometimes create more regulatory leverage than a much larger mid-stage study in obesity or Alzheimer’s disease.
Longeveron’s HLHS experience also shows the limit of that shortcut: once the FDA rejected the endpoint and the trial then missed it, a supposedly short route turned into a negotiation over secondary data.

If you build or invest in the longevity market, you need to know which business models pay off now and which ones are fading. That's why our market report about longevity companies has a whole section on it.
Has any aging-related biotech already received FDA approval?
Yes, and Stealth BioTherapeutics shows what the first wave of aging-biology approvals may look like: a mechanism associated with aging reaches the FDA through a tightly defined disease.
The FDA granted accelerated approval to elamipretide, marketed as Forzinity, for Barth syndrome. Elamipretide acts on mitochondrial biology, an area heavily studied in aging because mitochondrial dysfunction accumulates across many age-related conditions.
Barth syndrome, however, is a rare inherited mitochondrial disease that often begins in childhood. Stealth developed elamipretide as a mitochondrial-disease therapy rather than as a medicine intended to extend lifespan. Approval for a rare disease is no proof of lifespan benefit; we look at who has real data and who only promises in our report on longevity.
That makes Forzinity a useful precedent without making it an “anti-aging drug.” No drug has been approved for aging reversal or lifespan extension.
Insilico could eventually follow a similar route through pulmonary fibrosis. Calico could do it through Vanishing White Matter disease, and Longeveron through a pediatric heart disease or Alzheimer’s. Life Biosciences is attempting it through optic neuropathies.
Which longevity company is closest to FDA approval right now?
Loyal is closest if dog longevity counts. For humans, no company has a clear lead: Insilico is furthest along by stage, Calico has the strongest rare-disease regulatory signals, and Longeveron has dropped back after ELPIS II.
Longeveron no longer wins the narrow human-longevity definition by default. It still has the most randomized Phase 2 data among pure-plays and five FDA expedited or special designations across its programs. But ELPIS II missed its primary endpoint in September 2026, and its case now rests on secondary cardiac-event results the FDA has yet to weigh.
Its finances add a second layer of doubt. Longeveron is in a strategic review, has cut costs and hired an advisor to explore a possible business combination. The Alzheimer’s program has a clear Phase 2/3 design discussed with the FDA, but no one has yet committed to fund it.
Calico now sits in the front group. Fosigotifator’s FDA Breakthrough Therapy Designation and October 2026 EMA PRIME designation in Vanishing White Matter disease give it a rare-disease route that could accelerate sharply if the Phase 1b/2 results are strong.
Insilico is further ahead in conventional drug development. Rentosertib started Phase 3 for idiopathic pulmonary fibrosis in September 2026 and has human proteomic-aging data layered onto its program. Two things stop us calling it the straightforward winner: the trial is in China, with no U.S. registration path disclosed, and the company is primarily an AI drug developer rather than a longevity pure-play.
And Loyal remains in a league of its own on sheer regulatory distance. LOY-002 has satisfied two of the three big technical sections required for FDA expanded conditional approval. If the remaining manufacturing work clears review, the first FDA-authorized drug sold with an explicit healthy-lifespan goal may arrive for dogs well before humans.
| Definition of “longevity company” | Closest company today | Why |
|---|---|---|
| Any longevity drug, including animals | Loyal | LOY-002 has cleared 2 of 3 major conditional-approval sections |
| Human pure-play longevity company | No clear leader (Calico, Longeveron) | Calico has the stronger designations; Longeveron more data but a missed primary endpoint |
| Broad human aging-biology company | Insilico Medicine | Rentosertib is in Phase 3, in China |
| Most likely rapid challenger | Calico | FDA Breakthrough and EMA PRIME status in a rare disease could compress development |
| Most advanced cellular rejuvenation company | Life Biosciences | First partial epigenetic-reprogramming therapy dosed in humans, with first data in three patients |
So the direct answer today is Loyal for any FDA-authorized longevity product, and an open race for humans, with Calico and Insilico slightly ahead of a weakened Longeveron.
Human aging itself remains much further away. The first successful longevity biotech will almost certainly reach pharmacies through a disease label first, and only later will we have enough evidence to decide whether the medicine changes how humans age.

In our document detailing everything you need to know about longevity, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Our methodology
There is no single obvious way to answer which longevity company is closest to FDA approval. The category is fluid, clinical stages do not translate neatly into regulatory distance, and some of the most important signals sit outside the headline trial phase. We therefore broke the question into separate dimensions rather than ranking companies by reputation, funding or trial phase alone.
We looked at five things in particular: how directly each company is built around longevity or aging biology; how far its most relevant program has progressed in humans; the quality and maturity of the clinical evidence; how concrete its regulatory path has become; and whether rare-disease pathways, endpoint alignment, manufacturing requirements or financing could materially accelerate or delay approval.
For each dimension, we prioritized the freshest direct evidence available. FDA materials, SEC filings, ClinicalTrials.gov records, government program data and companies’ own clinical or regulatory disclosures carried the most weight. Where newer FDA feedback or clinical information changed the picture, we gave that more weight than older descriptions of the program.
We did not treat every signal equally. Direct FDA feedback on what could support a filing carries more weight than a designation alone. A trial’s primary endpoint carries more weight than its secondary analyses. Controlled human efficacy evidence carries more weight than an early biomarker result. Trial stage matters, but we also looked at where a study runs, what it is designed to establish and whether it could plausibly produce registrational evidence for the FDA.
Funding was treated mainly as an execution signal, not as proof that a drug is closer to approval. Biological-age clocks and other mechanistic biomarkers were treated as supporting evidence unless they have a validated role in an FDA approval pathway.
We also tested the answer under more than one definition of “longevity company.” A human longevity pure-play, a broader drug developer using aging biology and a company pursuing lifespan extension in animals are not the same category, so we kept those answers separate instead of forcing them into one artificial ranking.
Key sources used for this analysis include FDA guidance on biomarkers and surrogate endpoints, FDA guidance on conditional approval for veterinary drugs, Loyal’s LOY-002 reasonable-expectation-of-effectiveness update, Loyal’s target-animal safety update, Longeveron’s ELPIS II topline results, Longeveron’s updated ELPIS II results, Longeveron’s Form 10-Q for the June 2026 quarter, Longeveron’s Type B meeting disclosure, Calico’s Breakthrough Therapy announcement, ClinicalTrials.gov for fosigotifator in Vanishing White Matter disease, Insilico Medicine’s GENESIS-IPF-3 Phase 3 announcement, Insilico’s proteomic aging-clock analysis, BioAge’s QUELL-DME Phase 2 announcement, ARPA-H’s Cambrian PrevenTOR award, Life Biosciences’ ER-100 first-in-human data, Retro Biosciences’ clinical-stage update, NewLimit’s financing and clinical-timeline update, the FDA’s Forzinity approval announcement, as well as Calico’s October 2026 EMA PRIME announcement, Loyal’s LOY-003 update, Longeveron’s October 2026 announcement on Lucid Capital Markets and NewLimit’s October 2026 progress update.
The final conclusion comes from aggregating recent signals across regulatory distance, clinical maturity, evidence quality and category fit, assessing them point by point, and then looking at where the evidence converges.

In our report covering the longevity market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us