Longevity M&A: what is happening now?
Building a startup or looking for your next investment in longevity? Our report gives you the full picture.
Summary
Longevity M&A is becoming a real acquisition market, but the money is going mainly into preventive healthcare, diagnostics, clinics, and health-monitoring technology rather than breakthrough treatments that reverse human aging.
The market is smaller than the headlines suggest. New Market Pitch identified 25 longevity-related transaction records across 24 months, or roughly one per month. Activity in that sample actually fell by 33% between its first and second 12-month periods, although acquisitions continued through October 2026. Activity fell by a third between the two years, so we look at how the picture has shifted over the past year in our longevity market report.
The biggest limitation is financial transparency. Around 80% of the tracked transactions lacked a usable disclosed acquisition price. We can identify active buyers and their strategies, but there isn't enough information to establish a reliable annual M&A dollar volume or calculate most investors' returns.
Repeat buyers are more revealing than isolated acquisitions. Function Health has purchased Ezra and Getlabs, Oura has acquired several complementary technology businesses, and Agentis Longevity is assembling a network of clinics. These companies are buying capabilities that strengthen existing platforms rather than betting everything on an unproven longevity breakthrough.
Function Health illustrates where much of the immediate commercial opportunity lies. Combining blood testing, MRI screening, and mobile sample collection gives it more ways to serve the same customer. The acquisition thesis depends heavily on convenience, distribution, and repeat spending, not just better biomarker measurements.
Private equity is making a similar bet in clinics. Shore Capital's Agentis has expanded through acquisitions such as Arete Wellness and BioDesign, bringing fragmented preventive-health services into a larger operating network. The model is familiar from other healthcare specialties, but longevity clinics still need to prove that their services generate sustainable demand and credible medical outcomes.
Biological-age testing is starting to consolidate too. Infinite Epigenetics acquired Tally Health, combining consumer reach with established epigenetic-testing infrastructure. Larger testing businesses may enjoy lower operating costs and richer datasets, although better commercial scale doesn't automatically make biological-age estimates more clinically useful.
Actual aging biotechnology remains a much thinner acquisition market. Altos Labs bought Dorian Therapeutics, Granata Bio acquired Oviva Therapeutics, and Daewoong purchased Turn Bio technology assets. These are targeted scientific acquisitions, often focused on a specific therapeutic application, rather than evidence of pharmaceutical companies paying billions for broad anti-aging platforms.
The largest disclosed financial reference comes from an adjacent market. Illumina paid $350 million upfront for SomaLogic, with up to $75 million in additional performance-based payments and specified royalties. Proteomics is relevant to longevity research, but treating that entire transaction as dedicated longevity M&A would exaggerate the market.
For now, diagnostics and clinical services offer buyers something aging therapies mostly cannot: existing customers, commercial products, and measurable operating activity. A much larger acquisition wave will probably require convincing human clinical results from senescence-targeting drugs, cellular reprogramming, or other treatments addressing age-related decline. Until then, expect focused acquisitions and clinic consolidation, not a flood of billion-dollar longevity takeovers.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the longevity market, you will always find fresh funding data, taken straight from our own verified funding database.
Is longevity M&A really taking off now?
Longevity M&A is becoming a real market, but acquisitions are still relatively small, selective, and concentrated in a handful of active buyers.
According to New Market Pitch's June 2026 transaction tracker, the sector recorded 25 longevity-related transaction records over 24 months. That works out to roughly one transaction per month, covering preventive-health clinics, biological-age testing, wearables, diagnostics, and experimental aging therapies. The count includes asset sales, mergers, and other transaction structures alongside conventional acquisitions.
More recent deals show that buyers are still interested. Function Health acquired mobile blood-collection provider Getlabs in April 2026, Infinite Epigenetics acquired Tally Health's biological-age testing business, and Daewoong Pharmaceutical purchased assets from Turn Biotechnologies in May. Temple acquired the London longevity clinic Longevous in August, while Viome announced its acquisition of Sōlaria Biō in October.
The targets tell us a lot about where the money is going. Function wants to make preventive testing easier. Infinite Epigenetics wants more biological-age testing capabilities. Daewoong wants technology that could eventually support regenerative treatments.
Is longevity M&A accelerating or slowing down?
Longevity M&A has slowed compared with its earlier wave, although recent acquisitions suggest the market is still active.
New Market Pitch recorded 15 transaction records in the first half of its 24-month observation window and 10 in the second half. That's a 33% decline. The tracker is a curated dataset rather than a complete worldwide registry, so the percentage describes the trend within that sample.
The concentration of activity is just as telling. The earlier period included acquisitions by Function Health, Altos Labs, Granata Bio, Illumina, and several healthcare platforms. More recently, repeat buyers such as Oura and Agentis have accounted for a meaningful share of the transactions. Repeat buyers like Oura and Agentis show one way to build a company, and we compare which business models are winning in our report on longevity.
The June tracker does not include later announcements such as Temple's Longevous acquisition and Viome's Sōlaria Biō transaction. Those newer deals improve the picture somewhat, but we cannot calculate an updated growth rate without rebuilding the entire transaction dataset.
So yes, acquisitions are happening. But 25 transaction records over two years isn't exactly a buying frenzy.
What actually counts as a longevity acquisition?
A longevity acquisition should involve a business directly focused on healthy aging or a technology with a clear role in preventing, measuring, or treating age-related decline.
This definition becomes important when examining the largest transactions. Function Health's acquisition of Ezra clearly fits: the combination connects preventive blood testing with MRI screening. Granata Bio's acquisition of Oviva Therapeutics also qualifies because Oviva develops treatments targeting ovarian aging.
Illumina's acquisition of SomaLogic is more complicated. Proteomics can contribute to aging research by measuring thousands of proteins and studying changes associated with disease and aging. However, Illumina bought SomaLogic primarily to strengthen its broader molecular-analysis business.
Oura presents a similar boundary problem. Its acquisitions of Veri, Sparta Science, Doublepoint, and Galen AI support a broader health-monitoring platform, but gesture recognition and performance analytics are not exclusively longevity technologies.
We therefore separate dedicated longevity transactions from acquisitions of adjacent healthcare infrastructure. Both are worth studying, but including every medical-technology acquisition would make the longevity M&A market appear much larger than it really is.

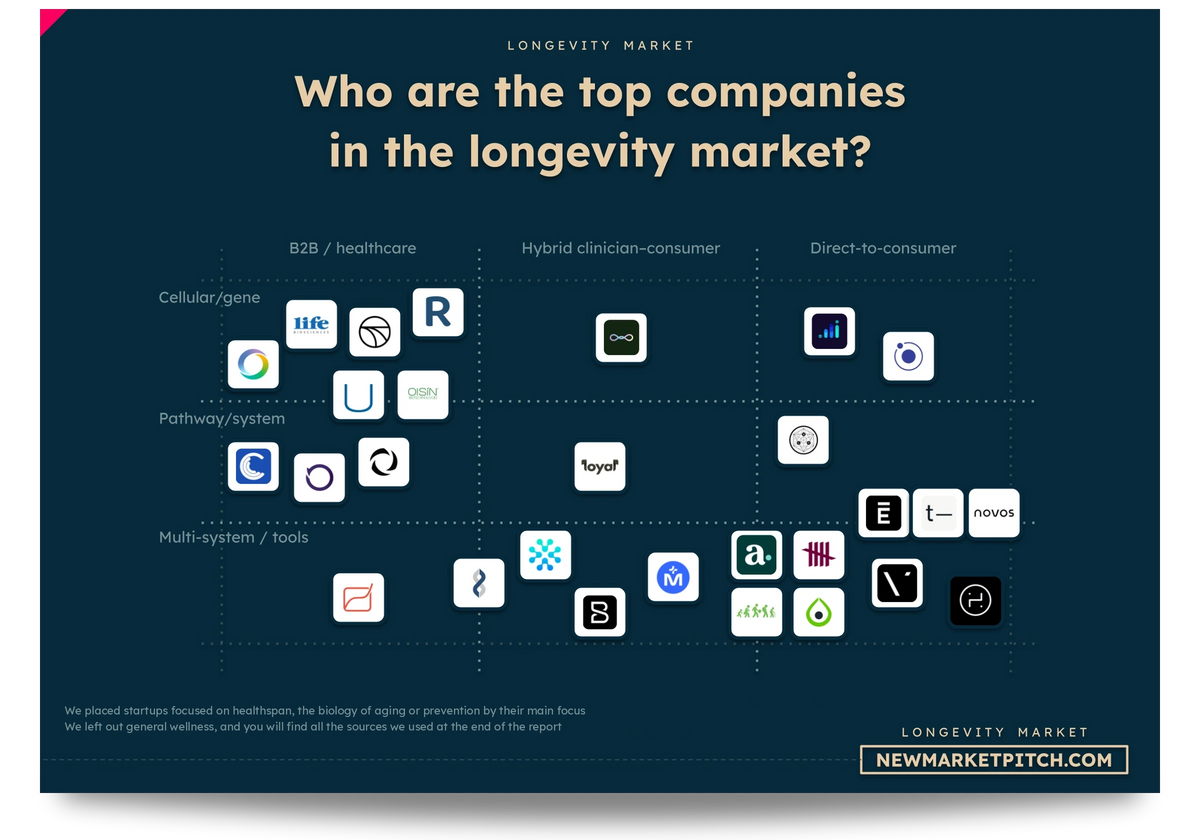
In our research about longevity companies, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
How big are the biggest longevity acquisitions?
The biggest publicly priced longevity-related transactions involve diagnostics and adjacent healthcare technology, while most dedicated longevity deals have undisclosed values.
Illumina provides the clearest financial reference. The company completed its acquisition of SomaLogic in January 2026, paying $350 million upfront with up to $75 million in additional performance-based payments and specified royalties.
Illumina's subsequent quarterly filing reported a total accounting purchase price of approximately $460 million, reflecting closing adjustments and the fair value of contingent consideration. That accounting figure should be distinguished from the cash received by the seller.
The Pulmatrix–Eos SENOLYTIX merger announcement offers a much smaller financial reference. The proposed transaction included approximately $19 million in concurrent financing, with existing Pulmatrix shareholders expected to own about 6% of the combined company. The $19 million represented financing rather than an acquisition purchase price.
| Transaction | Timing | Disclosed terms | What the buyer acquired |
|---|---|---|---|
| Illumina / SomaLogic | Completed January 2026 | $350M upfront, up to $75M earnout, plus royalties | Proteomics technology |
| Pulmatrix / Eos SENOLYTIX | Announced March 2026 | $19M concurrent financing | Proposed geroscience merger |
| Function / Ezra | May 2025 | Undisclosed | MRI screening |
| Function / Getlabs | April 2026 | Undisclosed | Mobile healthcare services |
| Infinite Epigenetics / Tally Health | Announced April 2026 | Undisclosed | Biological-age testing |
| Daewoong / Turn Bio assets | May 2026 | Undisclosed | Cellular reprogramming IP |
| Altos Labs / Dorian Therapeutics | May 2025 | Undisclosed | Senescence research |
| Granata Bio / Oviva Therapeutics | April 2025 | Undisclosed | Ovarian-aging therapeutics |
| Temple / Longevous | August 2026 | Undisclosed | Longevity clinic expertise |
| Viome / Sōlaria Biō | October 2026 | Undisclosed | Microbiome-related technology |
Are longevity clinics becoming the hottest acquisition targets?
Longevity clinics are currently one of the clearest acquisition opportunities because buyers can purchase operating healthcare businesses with existing patients and services.
Agentis Longevity is a good example. Shore Capital Partners established the platform in December 2024, and Agentis went on to acquire Arete Wellness in January 2026 and BioDesign in February. By March, the company described a network of 14 partner clinics operating across more than 10 markets.
These acquisitions bring together services such as hormonal health, diagnostics, performance medicine, recovery treatments, and personalized care.
Other companies have made similar moves. Novellum Longevity was formed around ThriveMD's non-clinical assets, while Chi Longevity acquired Sparkd to expand its cognitive and physical-performance offerings. Temple's acquisition of Longevous adds another example of a buyer purchasing established medical expertise rather than developing every service internally.
Clinics have something early-stage anti-aging drug developers don't: patients already paying for services. That's an obvious attraction for buyers, even if the longer-term economics still need proving.

In our market report about longevity companies, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is private equity starting to consolidate longevity clinics?
Private equity is already building longevity clinic platforms, with Shore Capital's Agentis providing the strongest evidence of a repeatable acquisition strategy.
Agentis follows an approach familiar from dental practices, dermatology, and other fragmented healthcare specialties. An investor establishes a platform and adds smaller businesses, while some administrative, technology, and marketing functions can be managed across the group.
Shore Capital launched Agentis around Mantality Health, then expanded through Arete Wellness and BioDesign. The sequence shows a planned consolidation effort rather than an isolated purchase. Shore Capital building Agentis step by step is a sizeable wager; we weigh which investors are making the biggest bets in our longevity market report.
Novellum Longevity illustrates another approach. Its formation around ThriveMD's non-clinical assets involved a management services organization, a structure that can help medical practices share business operations while preserving the required separation between clinical and non-clinical responsibilities.
The economics still need proving. Hormone therapy, preventive screening, wellness programs, and other longevity services have different medical requirements and reimbursement models. Bringing clinics under common ownership does not automatically make their treatments more effective or their customers more loyal.
Why did Function Health acquire Ezra and Getlabs?
Function Health acquired Ezra and Getlabs to make its preventive-health service broader and more convenient, bringing imaging and blood collection closer to its existing testing business.
Function originally focused on giving members access to extensive laboratory testing and personalized interpretation. Its May 2025 acquisition of Ezra added MRI screening, allowing customers to combine blood biomarkers with medical imaging.
At the time, the companies announced an imaging offer priced at $499 and highlighted a scanning process that had been reduced from approximately 60 minutes to 22 minutes. That made MRI screening a more accessible component of the service, although pricing and clinical appropriateness remain important considerations.
Function's April 2026 acquisition of Getlabs tackled another problem: getting biological samples collected. Getlabs operates a mobile healthcare services network that allows patients to receive services such as blood draws outside traditional laboratory locations.
Function had also raised $298 million in Series B funding at a $2.5 billion valuation in November 2025. That financing gives some context for its ability to acquire complementary businesses.
The next test is whether combining more tests, imaging, and convenient collection produces better health decisions and enough repeat spending to support the business. Additional screening is commercially attractive, but its medical value depends on which tests are offered and how their results are used.
Is Oura becoming the biggest buyer in wearable longevity?
Oura is currently one of the most active strategic acquirers in preventive-health wearables, with four relevant acquisitions in roughly 19 months.
The company acquired Veri in September 2024 to strengthen its metabolic-health capabilities. It followed with Sparta Science in October, adding technology focused on physical performance and movement assessment.
In March 2026, Oura acquired Doublepoint, a Finnish company developing gesture-recognition technology. One month later, it announced the acquisition of Galen AI's technology and team to help connect wearable information with medical records, medications, laboratory results, and other clinical data.
Oura has been filling gaps around its original sleep and recovery product. Metabolic information, movement analysis, easier interactions, and clinical records all make a wearable more useful as a broader health companion.
Doublepoint is an interesting exception because gesture recognition does not directly measure health. It makes sense when viewed as a way to improve how users interact with future devices.
Oura's acquisition history shows a deliberate move toward richer personal-health information. Whether that eventually leads to clinically proven longevity benefits is a separate question, but the product strategy behind the purchases is already clear.

Our document detailing everything you need to know about longevity gets updated several times a month, so you always get the latest view of where things stand.
Are biological-age testing companies starting to merge?
Biological-age testing is beginning to consolidate, and Infinite Epigenetics' acquisition of Tally Health is a particularly revealing transaction.
Tally Health was co-founded by aging researcher David Sinclair and built consumer products around DNA methylation testing. These tests examine chemical markers on DNA to estimate aspects of biological aging.
Infinite Epigenetics, associated with TruDiagnostic, already operated in epigenetic testing. The acquisition brought Tally's brand, assets, and consumer-facing capabilities into a business with established testing infrastructure. Epigenetic testing already has the infrastructure buyers want, and we track which technologies are gaining traction in our longevity report.
Tally's privacy documentation identifies March 19, 2026, as the effective acquisition date, with the transaction publicly announced in April.
The commercial rationale is straightforward. Laboratories can spread operating costs across more customers, while larger datasets may help researchers compare measurements across people and over time.
The scientific limitations remain important. A biological-age test estimates aging-related patterns using a particular model. Different models can generate different results, and improving a score does not automatically mean someone will live longer or avoid disease.
Is big pharma finally buying anti-aging startups?
Large pharmaceutical companies are showing interest in specific aging-related technologies, but we still see very few major takeovers centered directly on slowing human aging.
Daewoong Pharmaceutical's purchase of Turn Biotechnologies assets in May 2026 is one of the clearest examples of a traditional pharmaceutical company acquiring technology associated with cellular rejuvenation.
Turn Bio developed partial cellular reprogramming technology using messenger RNA. The idea is to restore certain youthful cellular characteristics without fully resetting cells to an earlier developmental state.
Daewoong already had a relationship with Turn Bio through licensing arrangements involving its subsidiary HanAll Biopharma. The acquisition therefore built on an existing technical and commercial connection.
Other transactions have come from specialized biotechnology buyers. Altos Labs acquired Dorian Therapeutics in May 2025 to strengthen its work on cellular senescence, while Granata Bio acquired Oviva Therapeutics to develop treatments related to ovarian aging.
Deloitte reported approximately $220 billion in life-sciences M&A through November 2025. The largest buyers continued to focus heavily on therapeutic areas with clearer commercial pathways, including oncology and metabolic diseases.
The gap is understandable. Aging-related biotechnology still needs convincing human clinical results before major pharmaceutical companies can confidently attach large values to its potential. For all the excitement around longevity science, big pharma hasn't made its big move yet.
Why are longevity biotech startups selling technology instead of whole companies?
Some longevity biotechnology startups are selling specific technologies because their research can remain valuable even when the original business struggles to fund further development.
Daewoong's acquisition of Turn Bio assets is a good example. The transaction followed an auction process and focused on intellectual property associated with partial cellular reprogramming.
Buying individual assets allows an established pharmaceutical company to integrate selected technology into its research portfolio without necessarily taking responsibility for the seller's entire business.
The proposed Pulmatrix–Eos SENOLYTIX merger illustrates a different problem. Eos was pursuing a public-market route for its geroscience program, accompanied by $19 million in financing. That kind of transaction depends on financial structuring and shareholder approvals as well as the attractiveness of the underlying science.
Granata Bio's purchase of Oviva Therapeutics represents a more conventional strategic fit, bringing ovarian-aging research into a business already focused on reproductive medicine.

In our report covering the longevity market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Are diagnostics becoming more valuable than anti-aging drugs in M&A?
Diagnostics currently attract more visible commercial acquisition activity than medicines designed specifically to reverse biological aging.
Function Health has acquired MRI screening and mobile blood-collection capabilities. Infinite Epigenetics has bought a biological-age testing business. Illumina has acquired proteomics technology, while Viome's purchase of Sōlaria Biō connects microbiome research with personalized nutritional products.
These companies can already sell tests, analytical services, or health products. Drug developers attempting to modify aging biology face a much longer road involving human trials, regulatory review, manufacturing, and reimbursement. Diagnostics firms already sell tests while drug developers face a long road, so we ask who is leading and who is slipping in our report on longevity.
Illumina's SomaLogic acquisition also has an interesting history. The companies began collaborating on proteomics in 2021, several years before the acquisition was announced in June 2025.
By purchasing SomaLogic, Illumina gained technology with an established role in research and existing commercial applications. That makes the investment easier to evaluate than an early-stage program targeting a biological aging mechanism.
Still, we shouldn't assume diagnostics will eventually produce better financial returns. Large successful medicines can generate far more revenue than individual testing products.
For now, diagnostics have the clearer acquisition record. The longer-term contest depends on whether aging-related therapeutic programs can deliver convincing clinical results.
Is women's longevity becoming a serious M&A market?
Women's longevity is turning into a credible acquisition category because buyers can target specific health needs such as menopause, hormonal health, and reproductive aging.
Granata Bio's acquisition of Oviva Therapeutics in April 2025 provides the biotechnology example. Oviva's lead research program, OVI-586, focuses on ovarian function, with potential applications connected to menopause and reproductive health.
On the clinical side, Joi + Blokes acquired HerMD in December 2025. HerMD specialized in gynecology, menopause, sexual health, and related services, while Joi + Blokes had already developed a virtual healthcare business involving hormone management.
The HerMD story also reveals some of the challenges behind longevity clinic acquisitions.
According to reporting by the Cincinnati Business Courier, HerMD had raised approximately $36 million but closed five physical clinics earlier in 2025 before restructuring and moving toward a virtual-care model.
The acquisition therefore combined an expansion opportunity for Joi + Blokes with a change in how HerMD delivered its services.
Women's longevity has an advantage over broad anti-aging offerings: many of its potential customers already seek care for recognizable medical issues. That creates clearer ways to develop services and treatments, even if experimental ovarian-aging therapies still need clinical validation.
Are longevity startup acquisitions actually making investors money?
Longevity acquisitions are creating exit opportunities, but publicly available deal terms rarely tell us whether venture investors are making attractive returns.
HerMD offers a useful example. The company reportedly raised around $36 million, closed its physical clinics, underwent restructuring, and was subsequently acquired by Joi + Blokes for an undisclosed amount.
An acquisition announcement alone cannot tell us whether its investors recovered their capital.
Turn Bio presents a similar uncertainty. Daewoong acquired selected assets through an auction process, but the financial return to Turn Bio's original investors has not been established publicly.
The same information gap applies to acquisitions such as Tally Health, Ezra, and Dorian Therapeutics. We know who bought the businesses and why the assets were interesting, but we lack the purchase prices and shareholder distribution details needed to calculate returns.
Meanwhile, the funding market continues to support ambitious companies. NewLimit announced a $435 million Series C in June 2026, while Neko Health announced a $700 million Series C in July.
Those large rounds show that investors are willing to commit substantial money to selected longevity businesses. They are financing events, however, and provide no proof that comparable amounts can be recovered through acquisitions.

In our research about longevity companies, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Could longevity M&A already be worth billions of dollars?
The disclosed evidence is too incomplete to establish a billion-dollar annual longevity M&A market, even though adjacent healthcare acquisitions can easily reach hundreds of millions.
New Market Pitch's June 2026 tracker identified 20 transactions without a clean disclosed acquisition value among 25 records. That means approximately 80% of the sample lacked usable transaction pricing. Four in five deals with no disclosed price leave valuations murky; we look at what these companies are valued at in our longevity market report.
It would be misleading to estimate market size by applying a single assumed deal value to all 25 transactions. An early-stage technology acquisition, a healthcare clinic purchase, a reverse merger, and a large molecular-diagnostics transaction have completely different financial characteristics.
Illumina's SomaLogic purchase shows that relevant deals can reach substantial values. But counting its entire consideration as dedicated longevity M&A would also be misleading because proteomics serves many areas beyond aging research.
The wider healthcare market provides a useful comparison. Deloitte recorded approximately $42 billion in diagnostics M&A during 2025, far more than the disclosed value of the dedicated longevity transactions we can identify.
For the longevity sector to demonstrate an annual M&A market worth more than $1 billion, we would need a better set of disclosed transaction prices or several large acquisitions clearly attributable to longevity.
At present, the market is too opaque for a reliable annual dollar-volume estimate. Anyone putting a precise figure on it needs to explain where those undisclosed deal values came from.
Which companies could buy the next longevity startups?
Function Health, Oura, and Agentis Longevity are among the most credible potential repeat buyers because they have already completed multiple relevant acquisitions.
We can also identify more specialized purchasers. Infinite Epigenetics has demonstrated an interest in consolidating biological-age testing, while Altos Labs and Granata Bio have acquired research businesses relevant to their therapeutic priorities.
Illumina belongs in a different category. Its SomaLogic acquisition demonstrates substantial purchasing capacity, but its acquisition strategy covers molecular testing broadly rather than longevity alone.
The following companies have demonstrated interest through actual transactions. The potential target categories reflect the capabilities they already own and the gaps that similar acquisitions could fill; they are not announced acquisition plans.
| Potential buyer | Acquisition evidence | Plausible future targets |
|---|---|---|
| Function Health | Ezra, Getlabs | Screening, clinical services, diagnostic infrastructure |
| Oura | Veri, Sparta Science, Doublepoint, Galen AI | Biometrics, AI, medical-data integration |
| Agentis Longevity | Arete Wellness, BioDesign | Longevity clinics and regional networks |
| Infinite Epigenetics | Tally Health | Epigenetic testing, aging biomarkers |
| Illumina | SomaLogic | Proteomics and molecular diagnostics |
| Viome | Sōlaria Biō | Microbiome technology and interventions |
| Granata Bio | Oviva Therapeutics | Reproductive-aging treatments |
| Daewoong Pharmaceutical | Turn Bio assets | Regenerative medicine and reprogramming IP |
| Altos Labs | Dorian Therapeutics | Senescence and cellular rejuvenation research |
| Temple | Longevous | Clinical expertise and preventive-health services |

Learning from others' mistakes is the cheapest lesson there is. In our market report about longevity companies, we look at what broke startups before you, so you don't repeat it.
What is stopping a bigger longevity acquisition boom?
The biggest obstacle to a larger longevity M&A market is the lack of clinically proven treatments that directly target human aging.
Pharmaceutical companies generally need to see evidence that a treatment is safe and effective for a defined medical condition before making major commercial commitments.
Longevity biotechnology is making progress, but many programs are still working toward those milestones. Cellular reprogramming, senescence-targeting drugs, and interventions designed to restore aspects of cellular function remain scientifically challenging.
This is why several acquisitions involve relatively specific medical applications. Granata acquired Oviva's ovarian-aging research, Eos SENOLYTIX has pursued programs related to sarcopenia, and Daewoong obtained reprogramming technology with possible regenerative applications.
These are more concrete development paths than trying to obtain approval for a treatment that simply claims to slow aging in general.
The commercial side has its own difficulties. Longevity clinics need paying patients who continue using their services. Biological-age testing companies need credible measurements that support useful health decisions. Preventive screening platforms must demonstrate medical value without exposing customers to excessive testing and unnecessary follow-up procedures.
Financing conditions also affect the market. Although selected companies such as NewLimit and Neko Health have raised exceptionally large rounds, smaller biotechnology developers still face difficult choices when clinical development costs rise.
So what is really happening in longevity M&A now?
Longevity M&A is becoming more established, but the market remains small, fragmented, and far more active in preventive healthcare than in life-extension drugs.
Our review shows that clinic operators, diagnostics businesses, and wearable-health platforms are making the most repeatable acquisitions. Function Health, Oura, and Agentis have each purchased complementary assets to expand existing operations. Infinite Epigenetics, Viome, and Temple have added further activity in biological-age testing, microbiome technology, and clinical services.
A second, smaller acquisition market exists around aging-related biotechnology. Altos Labs, Granata Bio, and Daewoong have bought research capabilities or intellectual property, although these transactions have not established a widespread market for large pharmaceutical takeovers.
The available figures also put some limits on the excitement. The June 2026 transaction sample showed a 33% decline between its two 12-month periods, and 80% of its records lacked a usable disclosed transaction value. More recent deals confirm continued activity, but they do not yet prove an accelerating market or consistently attractive investor exits.
Longevity buyers currently place the most visible value on capabilities they can integrate into existing businesses: patient access, diagnostics, data, clinical expertise, and selected scientific technologies.
The next major turning point will come when aging-related medicines deliver sufficiently strong human clinical results to attract large pharmaceutical buyers. Until then, longevity M&A looks set to grow through relatively focused acquisitions rather than a wave of billion-dollar takeovers.

If you build or invest in the longevity market, you need to know which business models pay off now and which ones are fading. That's why our document detailing everything you need to know about longevity has a whole section on it.
Our methodology
This analysis examines whether longevity M&A is accelerating, which types of businesses are attracting buyers, how much transaction value is publicly visible, and what recent acquisitions reveal about the sector's development. We reviewed acquisitions across preventive-health clinics, wearable technology, diagnostics, biological-age testing, and aging-related biotechnology, using transaction-level announcements, financial disclosures, and industry research.
Our main activity benchmark is New Market Pitch's longevity M&A transaction tracker, which recorded 25 transaction records across a 24-month period. We compared activity between the two 12-month halves and examined subsequent announcements through October 2026. Because the tracker includes mergers, asset purchases, and other structures alongside conventional acquisitions, we treat its count as a curated transaction sample rather than a complete measure of global longevity takeovers.
We classify transactions according to their relationship with healthy aging. Dedicated longevity businesses, such as biological-age testing companies, specialized clinics, and developers of aging-related therapies, are distinguished from adjacent healthcare technologies with broader applications. This distinction is particularly important for acquisitions involving proteomics, wearables, and molecular diagnostics, where the entire transaction value cannot automatically be attributed to longevity.
For transaction values, we distinguish disclosed purchase consideration, contingent payments, accounting purchase prices, concurrent financing, and funding rounds. We do not treat these figures as interchangeable or estimate undisclosed acquisition values. Financial evidence includes Illumina's SomaLogic acquisition announcement, Illumina's quarterly financial filing, and Pulmatrix's announcement of the proposed Eos SENOLYTIX merger.
To assess strategic buyer behavior, we examined acquisition sequences rather than relying on individual transactions. Function Health's expansion is documented through its Ezra acquisition, Getlabs acquisition, and Series B financing announcement. Oura's strategy was assessed using its announcements concerning Veri, Sparta Science, Doublepoint, and Galen AI. We used Agentis Longevity's corporate announcements to examine clinic consolidation and repeat acquisitions.
For specialized longevity transactions, we used Infinite Epigenetics' acquisition announcement and Tally Health's ownership disclosure to establish the Tally Health transaction and its effective date of March 19, 2026. Additional evidence includes Granata Bio's Oviva Therapeutics acquisition announcement and the Korea Exchange disclosure concerning Daewoong's purchase of Turn Bio technology assets.
We also compared acquisition activity with continued private-market financing. NewLimit's $435 million Series C announcement and Neko Health's $700 million Series C announcement provide evidence of investor interest, but these financings are not counted as acquisitions or investor exits. For wider healthcare context, we used Deloitte's life-sciences M&A analysis, including its diagnostics transaction data.
Our conclusions weigh transaction frequency, disclosed economics, repeat-buyer activity, commercial maturity, and therapeutic development together. Acquisition announcements establish that assets have changed hands, while disclosed terms provide a narrower view of economic value. We use those distinctions to assess where longevity consolidation is already occurring and what would need to change before the sector could support a substantially larger acquisition market.

In our report covering the longevity market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us