How's Cognition doing these days?
Whether you're building or investing in the AI coding market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Cognition is doing exceptionally well commercially, with roughly $1 billion in annualized revenue and major enterprises adopting Devin at scale. But its $48 billion valuation, heavy spending, and fierce competition make its long-term financial success much less certain than its extraordinary growth suggests.
Revenue run rate more than doubled from $492 million in May 2026 to approximately $1 billion in September. That is an exceptional acceleration for a company founded in 2023, although annualized revenue is not the same as sales earned over a full year.
The acquisition of Windsurf was a major turning point. It more than doubled Cognition's annual recurring revenue at the time and gave the company a second product to sell, making its growth story partly about a very successful acquisition rather than Devin's organic expansion alone.
Cognition's strongest commercial advantage may be its ability to automate engineering work that large companies have postponed for years. Itaú, Mercedes-Benz, and Nubank have reported substantial gains in legacy modernization, repository documentation, security remediation, and code migrations. Migrations that big companies keep postponing are exactly the kind of problem buyers pay to solve, as we show in our AI coding assistant market report.
Banks are emerging as particularly valuable customers. Their enormous legacy systems create expensive, repetitive engineering problems, and partnerships with Infosys, Cognizant, and AWS could help Cognition reach many more enterprises without selling every deployment directly.
The productivity evidence is promising but uneven. Customer case studies report dramatic improvements on specific tasks, while independent research shows that AI coding tools do not reliably make every developer faster. Devin's clearest advantage is in large, well-defined engineering projects.
Cognition is also developing its own coding models. SWE-2 has approached leading competitors on Cognition's benchmarks while improving execution efficiency, although Anthropic, OpenAI, and Cursor remain serious threats and the company has not established overall technical leadership.
The financial picture is considerably weaker than the commercial one. Reporting suggests approximately 50% enterprise gross margins and potentially $800 million in annual cash burn, with proprietary model development accounting for much of the spending. Cognition has not demonstrated profitability.
Customer concentration deserves attention. Approximately 50 enterprises were reportedly on pace to spend more than $1 million annually, but one customer may account for roughly 10% of Cognition's business. Large contracts accelerate growth while making individual renewals and procurement decisions more consequential.
At $48 billion against a $1 billion revenue run rate, Cognition is valued at 48 times annualized sales. That multiple would fall to 24 times at $2 billion in revenue and 12 times at $4 billion, but reaching those levels profitably is a far tougher challenge than attracting another funding round.
Our assessment is that Cognition has already proved that autonomous software engineering can become a major enterprise software business. The next test is whether it can preserve its growth, improve margins, and build advantages that remain valuable as competing coding agents become cheaper and more capable.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

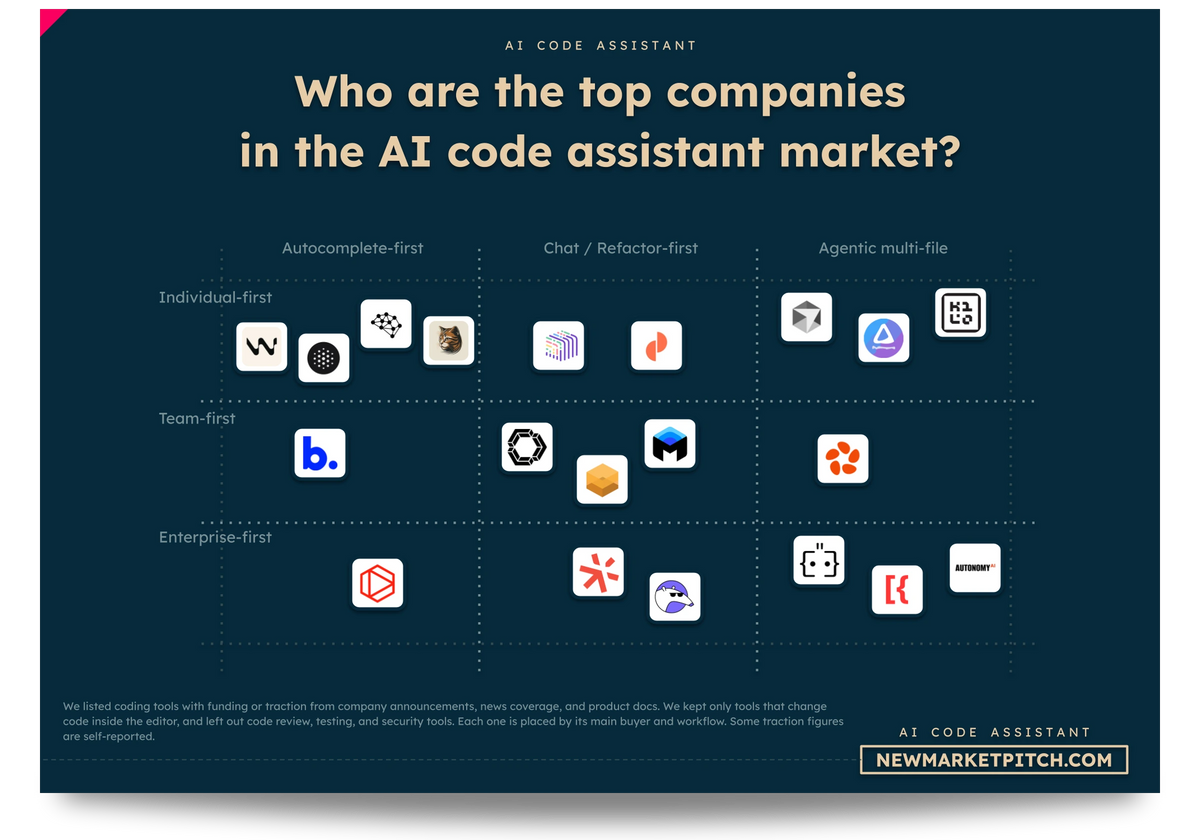
In our report covering the AI coding market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is Cognition actually doing well right now?
Cognition is doing exceptionally well right now, with revenue growing faster than almost any established software company and major enterprises increasingly using its AI coding tools.
According to Bloomberg's September 2026 reporting, Cognition reached approximately $1 billion in annualized revenue, up from $492 million in May. That means its revenue run rate more than doubled in roughly four months, adding over $500 million in annualized business.
Investors have responded accordingly. Cognition raised more than $2 billion at a $48 billion valuation in September, compared with $26 billion just four months earlier. That's an 85% increase in valuation over a remarkably short period. A valuation up 85% in four months is one of the market signals we follow every quarter in our report on AI coding assistants.
The customer list has also grown beyond technology startups. NVIDIA, GE Aerospace, Citi, Mercedes-Benz, BNY, and Santander are among the companies using Cognition's products. Several have moved beyond small trials into broader engineering deployments.
There are two important limits to these figures. Annualized revenue describes the sales pace at a particular moment rather than revenue actually earned over twelve months. And Cognition has not published audited financial statements showing whether its rapid expansion is profitable.
Still, the commercial picture is unusually strong. Cognition has established that large companies will pay serious money for autonomous software engineering, something that remained far from certain when Devin first appeared.
How did Cognition become a $48 billion company so quickly?
Cognition became a $48 billion company by growing revenue at an extraordinary pace while convincing investors that autonomous software engineering could become a huge market of its own.
The company's valuation has increased almost twelvefold since mid-2025. Cognition was valued at approximately $4 billion before acquiring Windsurf, reached $10.2 billion in September 2025, climbed to $26 billion in May 2026, and secured a $48 billion valuation in September.
Its business changed just as dramatically. Before acquiring Windsurf, Devin had grown from $1 million in annual recurring revenue in September 2024 to $73 million in June 2025. Cognition then bought Windsurf's remaining business, adding an established AI coding product and an existing customer base.
The valuation is nevertheless demanding. At $48 billion against a $1 billion revenue run rate, investors are effectively paying 48 times annualized sales.
That's a huge premium for a company whose reported gross margins remain well below those of many traditional software businesses. Investors are betting that Cognition can keep growing quickly enough for its revenue to catch up with its valuation.
| Period | Valuation | Revenue milestone |
|---|---|---|
| September 2024 | Not disclosed | Devin reaches $1M ARR |
| Mid-2025 | Approximately $4B | Devin reaches $73M ARR |
| July 2025 | No new valuation disclosed | Windsurf acquisition |
| September 2025 | $10.2B | Acquired business expands ARR |
| May 2026 | $26B | $492M annualized revenue |
| Early September 2026 | $48B | Nearly $900M annualized revenue |
| Late September 2026 | $48B, latest disclosed | Approximately $1B annualized revenue |

Our research about AI coding assistants gets updated several times a month, so you always get the latest view of where things stand.
Is Cognition's revenue growth as impressive as it looks?
Cognition's revenue growth is genuinely remarkable, although the acquisition of Windsurf makes the headline numbers look more organic than they really are.
Before buying Windsurf, Devin increased its annual recurring revenue from $1 million to $73 million in nine months. That's a 73-fold increase, albeit from a tiny starting point.
The Windsurf acquisition then changed the calculation. Cognition said in September 2025 that the transaction had more than doubled its ARR. We therefore cannot attribute the combined company's subsequent growth entirely to new Devin customers.
However, the more recent numbers remain impressive even after accounting for the acquisition. Revenue run rate increased from $492 million in May 2026 to almost $900 million in early September, before reaching approximately $1 billion later that month.
Converting those annualized figures into monthly revenue gives us a clearer picture. Cognition went from approximately $41 million per month to $83 million per month in about four months.
Another useful detail comes from Cognition CEO Scott Wu. In May, he told TechCrunch that enterprise usage of Devin had grown by approximately 50% month over month for six consecutive months.
Usage growth and revenue growth are different measures, but the reported figures suggest Cognition was benefiting from customers using its agents more extensively, alongside new sales.
We still lack an organic growth breakdown, revenue retention figures, and separate results for Devin and Windsurf. Those missing details prevent a precise assessment of how much revenue comes from new customers versus expansion within existing accounts.
Is Devin becoming an essential tool for big companies?
Devin is becoming an important part of software engineering at several major companies, particularly for maintaining old systems, fixing security problems, and handling large migrations.
Itaú offers one of the clearest examples. According to Cognition's September 2026 announcement about its expansion into Latin America, more than 75% of the bank's technology teams use Devin.
The bank has used the agent to document more than 300,000 repositories, migrate legacy .NET services to Java six times faster, and automatically resolve approximately 70% of security vulnerabilities. Itaú also reported a 20–30% improvement in engineering throughput.
Mercedes-Benz provides a very different example. During an initial four-week pilot, Devin analyzed more than 200,000 lines of COBOL, cutting an estimated eight-month modernization project to eight days. Mercedes-Benz subsequently announced a broader deployment of Devin and Windsurf across its global engineering organization.
At Nubank, Cognition reported that Devin accelerated a migration involving millions of lines of code from years to weeks, with costs more than 20 times lower than the original estimate.
These are company-published case studies, so we should be careful about treating estimated time savings as independently verified results. Still, we're looking at substantial projects across three different companies, rather than isolated coding demonstrations.
Devin's strongest commercial opportunity currently seems to be engineering work that companies already need to complete but struggle to justify doing manually at scale.

In our market report about AI coding assistants, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Devin actually making software engineers more productive?
Devin appears to make engineers dramatically faster on certain tasks, but the evidence doesn't support applying those gains to every kind of software development.
Cognition's enterprise case studies are strongest when the work is repetitive, well-defined, and involves large amounts of existing code.
Mercedes-Benz reported an enormous reduction in estimated modernization time. Itaú reported a 20–30% improvement in engineering throughput. Nubank described major savings on a complex migration. What coding agents already do well, and what is still being tested, is sorted out in our report covering the AI coding assistant market.
Independent research, though, paints a more complicated picture.
In July 2025, the research organization METR published a randomized study involving experienced open-source developers. The researchers found that using AI coding tools made participants approximately 19% slower on the tasks they studied, even though developers believed the tools were helping them.
By February 2026, METR's newer experiments suggested that AI tools were probably making developers faster. Unfortunately, the researchers couldn't reliably measure the improvement because many developers were reluctant to work without AI and became selective about which tasks they submitted.
A separate METR survey of 349 technical workers, published in May 2026, found median self-reported improvements of approximately 1.4 to 2 times in the value of work produced. The researchers warned that self-reported gains may be exaggerated.
These studies examine broader AI development tools rather than isolating Devin's contribution. They do, however, show why we shouldn't treat one spectacular migration as proof that every developer will become ten times more productive.
For now, Devin has the strongest evidence behind tasks involving technical debt, migration, documentation, and other engineering work with clearly defined outcomes.
Why are so many banks choosing Cognition?
Banks are choosing Cognition because they have enormous amounts of old software to maintain, and Devin can automate work that would otherwise consume thousands of engineering hours.
The concentration of financial institutions among Cognition's customers is striking. Citi, Goldman Sachs, Santander, BNY, Itaú, and Nubank have all appeared in its publicly disclosed customer base.
These organizations operate large, interconnected systems that often include older programming languages, complex databases, strict security requirements, and applications developed over decades. Decades-old code is a problem big banks would pay to solve, and we describe those buyers in our report on AI coding assistants.
Replacing those systems requires engineers to understand how existing software works before changing it. That can involve reading hundreds of thousands of lines of code, mapping dependencies, preparing documentation, and repeatedly testing changes.
Devin is particularly suited to parts of that process.
Itaú's repository documentation and vulnerability remediation work illustrates the scale. Nubank's migration project shows how automation can help banks replace old infrastructure faster. Cognition's April 2026 COBOL report also described work involving millions of lines of legacy code.
There is a distribution advantage here as well. Cognition has formed partnerships with Infosys and Cognizant, two consulting companies that already manage major software modernization projects for large enterprises.
Rather than convincing every bank to build its own autonomous engineering system, Cognition can reach some customers through firms that already manage their technology transformations.
This helps explain why Devin is gaining traction in traditional industries even while competing with popular developer tools such as Claude Code and Cursor.

In our document detailing everything you need to know about AI coding, you will always find fresh funding data, taken straight from our own verified funding database.
Is Cognition beating Cursor and Claude Code?
Cognition is winning valuable enterprise customers, but Cursor and Anthropic's Claude Code remain formidable competitors, and Cognition hasn't demonstrated leadership across the broader AI coding market.
The products have somewhat different starting points.
Devin was built around delegating engineering tasks to an autonomous agent. Cursor became popular as an AI-powered development environment where engineers work directly with the assistant. Claude Code gives developers access to Anthropic's models through an increasingly capable coding agent.
Those distinctions have narrowed considerably. Cursor and Claude Code can now handle more autonomous work, while Cognition offers both Devin and the Windsurf development environment.
Revenue figures give us a sense of the competitive scale.
According to reporting from The Information and Bloomberg, Cursor had reached roughly $4 billion in annualized revenue before SpaceX completed its reported $60 billion acquisition in August 2026. That was approximately four times Cognition's latest $1 billion revenue run rate.
Cursor's larger revenue base doesn't automatically mean it has a better product for every enterprise task. Cognition's success with banks, automakers, and modernization programs suggests it has found demand that goes beyond individual developer productivity.
Anthropic presents another challenge. Claude Code benefits from direct access to one of the world's leading AI model developers, while OpenAI offers similar integration through Codex.
Cognition has carved out a meaningful place in this crowded market. Becoming its overall leader is a much bigger challenge.
Did Cognition's acquisition of Windsurf actually pay off?
Buying Windsurf was one of Cognition's smartest commercial moves, giving the company a much larger business and a second way to reach software developers.
The acquisition followed an unusual sequence in July 2025.
Windsurf had been negotiating a possible $3 billion sale to OpenAI. That arrangement fell apart, and Google subsequently agreed to a $2.4 billion licensing and talent deal involving Windsurf's leadership and key researchers.
Cognition then acquired Windsurf's remaining business, product, intellectual property, and employees.
The immediate commercial benefit was substantial. Cognition reported that the acquisition more than doubled its ARR, while Windsurf gave it an established AI-powered development environment to complement Devin.
The two products now serve different parts of an engineering team's work. Developers can use Windsurf while actively building software and delegate more independent tasks to Devin.
Mercedes-Benz is already deploying both products across its engineering operations. That gives us a practical example of how Cognition can sell multiple tools within one large customer.
The integration also involved difficult decisions. The Information reported that Cognition laid off approximately 30 Windsurf employees and offered voluntary departure packages to roughly 200 others.
Cognition subsequently expanded its overall workforce rapidly, reporting growth from 44 to around 350 employees over the preceding year.
The acquisition clearly accelerated Cognition's commercial expansion. What we still don't know is how much additional revenue came specifically from selling Devin to Windsurf customers, or whether combining the two products has improved customer retention.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the AI coding market, we look at what broke startups before you, so you don't repeat it.
Can Cognition build AI coding models as good as Anthropic and OpenAI?
Cognition's own coding models are becoming genuinely competitive, but its latest results still put the company behind the very best models on several important tests.
In September 2026, Cognition introduced SWE-2, a specialized model designed for software engineering.
The company's FrontierCode 1.1 benchmark tests whether AI-generated code is good enough to be merged into real software repositories. It considers correctness, tests, coding style, and compliance with project requirements.
SWE-2 scored 50.0% on the main benchmark. According to the leaderboard data available in October, Claude Opus 5.5 led with 54.6%, followed by other frontier models including Claude Fable 5 and GPT-6 Astra.
A difference of 4.6 percentage points is meaningful, although benchmark scores can vary with model settings and evaluation methods.
Cognition's own research also shows how quickly its models are improving. SWE-2 medium used an average of 53 steps on FrontierCode tasks, compared with 127 for SWE-1.7, while reducing average task cost by 81% in that comparison.
That's a particularly useful improvement for a company running agents that may perform hundreds of actions during a single assignment.
Cognition also introduced Devin Fusion, which combines multiple models and execution strategies to improve performance and control costs.
The company therefore has two ways to compete technically: developing its own specialized models and building a system that gets better results from models developed elsewhere.
FrontierCode is maintained by Cognition, so independent benchmarking remains important. Still, SWE-2's results show that the company has become a serious AI model developer rather than relying entirely on external providers.
Could cheaper AI models hurt Cognition?
Cheaper AI models could eventually put pressure on Cognition's prices, although they're also helping the company reduce the cost of running Devin.
The tension comes from Cognition's position between model developers and enterprise customers.
Devin needs powerful AI models to read code, plan changes, execute commands, run tests, and correct mistakes. Those operations consume computing resources, especially when agents work on complicated tasks for extended periods. We rate risks like compute bills that grow with long agent runs by likelihood in our market report about AI coding assistants.
As models become cheaper, Cognition can potentially run more engineering work for the same amount of money.
Its SWE-2 development already shows the financial value of efficiency improvements. Cutting the number of steps required to complete tasks reduces the computing expense associated with those tasks.
But Anthropic, OpenAI, and other model developers benefit from similar improvements. They can pass lower inference costs on to customers and make their own coding agents more capable.
Cognition's response has been to build more capabilities around the models themselves. Devin can work inside enterprise environments, coordinate tasks, connect to existing engineering systems, and handle processes extending well beyond code generation.
The company's growing security, incident-response, and automation capabilities support this approach.
We think Cognition can defend premium pricing where customers depend on these deeper integrations. Simpler coding tasks are much more vulnerable to cheaper alternatives.

In our research about AI coding assistants, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is Cognition profitable yet?
Cognition has not demonstrated profitability, and recent financial reporting suggests the company is spending enormous amounts of money to support its growth.
According to The Information's August 2026 investigation, Cognition's annual cash burn could reach approximately $800 million. The publication also reported around $200 million in second-quarter cash burn and enterprise gross margins near 50%, citing people familiar with its finances.
These figures are not audited public results, but they reveal an expensive operating model.
Traditional software companies often generate gross margins above 70%. Cognition's agents consume substantial computing resources, while the company is also investing in training specialized AI models.
At a 50% gross margin, a hypothetical $1 billion in annual revenue would leave $500 million after direct delivery costs, before research, sales, administration, and other expenses.
The financial picture becomes more interesting when we separate operating an AI coding business from developing proprietary frontier models.
The Information reported that Cognition's own model-development spending accounted for much of its projected cash burn. One person familiar with the finances suggested that the company would be close to free-cash-flow breakeven without those investments.
That could mean Cognition's core application business is already approaching sustainable economics. However, maintaining its own competitive models may require ongoing spending rather than a one-time investment.
Cognition has enough financial backing to pursue this strategy for now. It raised more than $1 billion in May and more than $2 billion in September, with major investors including Andreessen Horowitz, Accel, Founders Fund, General Catalyst, and Avenir.
For perspective, the September financing alone would equal more than 2.5 years of spending at an $800 million annual burn rate. That is a rough comparison rather than a reliable runway estimate, since we don't know its current cash balance, future commitments, or spending trajectory.
Cognition can afford to keep investing aggressively. Whether those investments eventually produce attractive profits remains an open question.
Is Cognition becoming too dependent on big customers?
Cognition's growing dependence on large enterprise customers could become a problem, especially if a few companies account for a substantial share of its revenue.
The Information reported in August 2026 that approximately 50 companies were on pace to spend more than $1 million annually with Cognition.
That represents at least $50 million in annualized spending, with the actual total potentially much higher.
More revealingly, the publication reported that one unnamed customer accounted for approximately 10% of Cognition's business.
At a $900 million annualized revenue run rate, that would represent around $90 million from a single customer. For comparison, Devin's entire ARR was $73 million before the Windsurf acquisition.
Such large contracts are commercially attractive. They allow Cognition to grow through existing relationships, particularly when customers expand from small deployments to thousands of engineers.
But concentration also increases the consequences of losing a major account.
Enterprise contracts can be affected by procurement changes, internal technology strategies, competing tools, and reductions in software budgets. Companies might also negotiate lower prices as their AI usage increases.
We don't have Cognition's full customer concentration data, net revenue retention, or contract duration figures.
For a company valued at $48 billion, those details would tell us a great deal about how reliable its future revenue really is.

If you build or invest in the AI coding market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Can Cognition keep growing this fast?
Cognition can continue growing quickly, but doubling a billion-dollar revenue business will be much harder than doubling one that generated a few hundred million dollars.
Its latest growth shows how demanding the next phase will be.
Moving from $492 million to $1 billion in annualized revenue required approximately $508 million in additional run rate. Doubling again would require another $1 billion, almost twice as much new business.
The Information reported that Cognition executives had discussed ambitious revenue goals, including more than $1.5 billion in annualized revenue and eventually $4–5 billion.
Those figures are reported projections rather than revenue already achieved.
We can see why management is aiming so high. Large customers such as Itaú and Mercedes-Benz offer opportunities to expand Devin across more engineering teams, while partnerships with AWS, Infosys, and Cognizant could help bring Cognition into additional enterprises.
However, growth will increasingly depend on convincing customers to spend more over time. The company cannot rely indefinitely on the same explosive percentages that were possible when Devin had only a few million dollars in ARR.
The economics also become more demanding as usage increases. Higher revenue is valuable only if Cognition can keep enough of it after paying for the computing infrastructure and models that power its agents.
The next meaningful milestone will be whether Cognition can sustain strong growth while improving its margins. That would provide more convincing evidence of a lasting business than another valuation increase.
Could Cognition become much bigger than an AI coding company?
Cognition could eventually become a broader enterprise automation company, although software engineering remains the only market where it has demonstrated major commercial success.
Its products already cover more than writing code. Where AI coding ends and wider engineering automation begins is a line we draw in our AI coding assistant market report.
Devin Auto-Triage investigates technical incidents. Devin Security Swarm identifies and evaluates vulnerabilities. Devin Automations can initiate engineering workflows from events in Slack, GitHub, Linear, and other systems.
These tools extend Cognition's reach into security operations, infrastructure maintenance, and ongoing software management.
There is an interesting pattern in the company's product expansion. Many of its new capabilities target work that takes place after software is written: monitoring systems, identifying problems, updating old applications, and keeping codebases secure.
That could make Cognition useful to a much wider group of enterprise teams.
Its April 2026 collaboration with Mercedes-Benz involves Devin and Windsurf across research, development, and IT. Its AWS partnership focuses partly on cloud migrations and technical debt. Consulting partners Infosys and Cognizant can bring the technology into managed services and large modernization programs.
Cognition also acquired The Interaction Company, the team behind the proactive messaging agent Poke, adding expertise in AI systems that initiate tasks rather than simply respond to requests.
These developments point toward more autonomous enterprise workflows, particularly in technical operations.
That doesn't make Cognition a leader in general business automation yet. The company has not disclosed meaningful separate revenue from non-engineering activities.
For now, the opportunity is to become a much larger part of how companies build and maintain their software.

In our document detailing everything you need to know about AI coding, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Is Cognition really worth $48 billion today?
Cognition's $48 billion valuation is hard to justify using its current financial performance alone, but continued exceptional growth could make the price look much more reasonable.
At approximately $1 billion in annualized revenue, Cognition carries a 48 times revenue multiple.
That's expensive for a business reportedly generating enterprise gross margins near 50% and spending heavily on research and computing infrastructure.
The comparison with Cursor is revealing.
According to reporting from The Information, Cursor reached approximately $4 billion in annualized revenue before SpaceX's reported $60 billion acquisition. That implies a valuation of around 15 times annualized revenue, far below Cognition's current multiple.
The companies differ in products, growth, margins, and ownership structure, so their valuations aren't perfectly comparable. Nevertheless, Cognition is being priced for a particularly optimistic future.
What happens if its business keeps expanding?
At $2 billion in annual revenue, its current valuation would equal 24 times sales. At $4 billion, the multiple would fall to 12 times. At $5 billion, it would be below 10 times.
This explains why the company's growth projections matter so much to investors. Strong revenue expansion could rapidly bring the valuation closer to multiples typically associated with successful high-growth technology businesses.
However, revenue growth alone won't settle the question. Cognition will eventually need to demonstrate improving gross margins, more efficient research spending, and strong customer retention.
| Revenue scenario | Revenue | Multiple at $48B | Growth from current run rate |
|---|---|---|---|
| Current reported pace | $1.0B | 48.0x | - |
| Moderate expansion | $1.5B | 32.0x | +50% |
| Revenue doubles | $2.0B | 24.0x | +100% |
| Continued strong growth | $2.5B | 19.2x | +150% |
| Revenue triples | $3.0B | 16.0x | +200% |
| Major enterprise expansion | $4.0B | 12.0x | +300% |
| Very ambitious growth | $5.0B | 9.6x | +400% |
What could stop Cognition from becoming a major AI company?
Cognition's biggest threat is that Anthropic, OpenAI, and other competitors improve their coding agents faster than Cognition can build a lasting advantage around Devin.
The competition is becoming more difficult because leading model developers increasingly offer complete software engineering products.
Anthropic controls Claude and Claude Code. OpenAI develops both its underlying models and Codex. Cursor already has a much larger reported revenue base and, following its acquisition by SpaceX, access to the resources of a major technology group.
Cognition must compete while paying for substantial computing infrastructure and developing its own models.
There is also the problem of increasingly capable AI models making some coding tasks easier and cheaper for everyone. If customers can get comparable results from a lower-priced product, Cognition will have to justify its premium through reliability, integrations, and performance on demanding enterprise workflows.
Its financial position adds another complication. Reported gross margins around 50% leave less room for operating expenses than many traditional software businesses enjoy.
And the company's reliance on large contracts means a handful of customer decisions can meaningfully affect revenue.
Cognition does have several defenses. Its work on legacy modernization, security remediation, and complex enterprise systems creates deeper customer relationships than a simple coding assistant might. Large deployments also involve integrations and established workflows that take effort to replace.
The challenge is to keep those advantages meaningful as competing agents become cheaper and more capable.

In our report covering the AI coding market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
So, how's Cognition really doing these days?
Cognition is doing extremely well commercially and has established itself as one of the most successful independent AI software companies. Its growth is real, its enterprise customers are substantial, and Devin has moved well beyond the demonstration stage.
The company reached approximately $1 billion in annualized revenue less than two years after Devin became generally available. Its latest $48 billion valuation reflects how strongly investors believe in its future.
Enterprise adoption provides another reason to take Cognition seriously. Itaú, Mercedes-Benz, and Nubank have reported large improvements in specific engineering workflows, while partnerships with major technology and consulting firms are helping the company reach more customers.
But Cognition's financial performance has yet to catch up with its commercial success. Its reported cash burn is substantial, its gross margins leave room for improvement, and competition from Anthropic, OpenAI, and Cursor is intense.
Our assessment is that Cognition has already proved there is a large paying market for autonomous software engineering. That's a major accomplishment for a company founded in 2023.
Whether Cognition becomes one of the dominant companies in that market will depend on how much customers continue spending, whether its proprietary models give it a lasting advantage, and how quickly it can improve profitability.
Right now, Cognition deserves its reputation as a breakout AI company. Its $48 billion valuation, however, still asks investors to believe that its extraordinary early growth is only the beginning.
Our methodology
This analysis assesses how Cognition is performing by examining six dimensions: revenue growth, enterprise adoption, engineering productivity, technical competitiveness, financial sustainability, and valuation. We prioritize measurable commercial progress over fundraising announcements or isolated demonstrations of AI coding capabilities.
For financial performance, we compare Cognition's reported revenue milestones, funding rounds, and private valuations. We distinguish annual recurring revenue from annualized revenue run rate and recognize that the acquisition of Windsurf contributed to Cognition's growth. Private financing valuations are treated as transaction-based benchmarks, not independently established market values.
Our financial assessment combines Cognition's own disclosures with reporting from Bloomberg, TechCrunch, and The Information. We use the reported $1 billion revenue run rate to calculate valuation multiples and examine cash burn, enterprise gross margins, and customer concentration separately. Reported financial estimates are distinguished from audited financial results.
To assess enterprise adoption, we examine Cognition's customer announcements and case studies involving Itaú, Mercedes-Benz, and Nubank, together with partnerships involving AWS, Infosys, and Cognizant. These examples help establish the scale and types of engineering work being automated. Customer-reported productivity improvements are treated as evidence of specific deployment outcomes rather than independently verified industry-wide gains.
We compare those enterprise outcomes with independent developer-productivity research from METR, including its randomized study of experienced open-source developers, subsequent experimental update, and survey of 349 technical workers. These studies provide context for AI-assisted engineering productivity but do not measure Devin in isolation.
Our technical assessment draws on Cognition's SWE-2 research, FrontierCode 1.1 benchmark methodology, and Devin Fusion announcements. We examine reported task performance, execution steps, and cost efficiency while accounting for the limitations of company-maintained benchmarks. Competitive comparisons with Cursor, Claude Code, and Codex consider product positioning and available commercial evidence rather than benchmark scores alone.
For valuation, we compare Cognition's latest $48 billion private-market valuation with its reported $1 billion annualized revenue run rate and calculate implied revenue multiples under several hypothetical growth scenarios. These calculations illustrate how revenue expansion could change the valuation's economics; they are not forecasts or independent estimates of fair value.
Key financial sources include Cognition's $1 billion annualized revenue announcement, its Series E financing announcement, Bloomberg's reporting on revenue growth, The Information's investigation into growth and cash burn, and TechCrunch's coverage of the $48 billion valuation.
Sources on acquisition and enterprise adoption include Cognition's Windsurf acquisition announcement, its historical funding and revenue disclosures, the Mercedes-Benz partnership, its Itaú and Nubank deployment examples, the Infosys partnership, the Cognizant partnership, the AWS collaboration, and its research on COBOL modernization.
Independent productivity research comes from METR's randomized developer productivity study, its updated experiments, and its technical worker productivity survey. Technical and product sources include Cognition's SWE-2 research, FrontierCode 1.1 methodology, Devin Fusion, Devin Fusion in desktop and CLI workflows, and the acquisition of The Interaction Company.

When you build or invest in the AI coding market, you need clarity, not confusion. In our research about AI coding assistants, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us