What is the real market size of climate tech?
Whether you're building or investing in the climate tech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The real market size of climate tech is about $2.2 trillion a year today, with roughly $2.1 trillion to $2.3 trillion as the most defensible range for broad annual climate and energy-transition spending.
The famous $31 billion to $45 billion climate-tech estimates are not necessarily wrong. They describe a much narrower technology layer, while the trillion-dollar figures count the physical deployment of EVs, renewables, grids, storage and other transition assets.
The market is far more concentrated than the climate-tech conversation suggests. Electrified transport, renewable power and grids alone absorb close to 90% of BloombergNEF's tracked transition investment, while hydrogen and carbon capture together remain well below 1%.
That creates two climate-tech economies. One is already operating at mass-market scale; the other contains frontier technologies that may become enormous but still have relatively small commercial bases today.
Venture capital is only a thin financing layer inside this market. Roughly $39 billion of climate-tech VC in 2025 sits beside more than $2 trillion of deployment spending funded through households, corporates, banks, project finance and governments.
Dollar growth now understates physical growth in several mature segments. Falling solar and battery costs mean that flat or slower investment can still produce record additions of renewable capacity, storage and electrified equipment.
Climate tech is also becoming less dependent on climate policy alone. In mature categories, buyers increasingly respond to cost, performance, energy security and operating economics, even though policy remains decisive in sectors such as hydrogen, CCS, nuclear and clean industry.
China remains the most important manufacturing and deployment center, but the financing pattern is more local than the supply chain. Most climate investment is financed domestically even though clean-energy equipment and materials move through large cross-border trade flows.
Adaptation is the biggest measurement blind spot. Tracked adaptation finance is only around $64 billion, but private spending on cooling, resilient buildings, water systems, flood protection and wildfire technologies is clearly larger than formal datasets currently capture.
The next credible scale is about $3 trillion a year under a base-case transition. A real 1.5°C pathway would require something much larger, with annual climate investment moving toward roughly $8 trillion this decade and around $9 trillion in the first half of the 2030s.
The useful conclusion is therefore narrower than the huge range usually quoted online: climate tech is already a multi-trillion-dollar annual market, but most of today's money is concentrated in a handful of mature technologies while many heavily discussed frontier sectors are still waiting for commercial scale.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the climate tech market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why do climate-tech market estimates range from $31 billion to more than $2 trillion?
Climate-tech market estimates vary by roughly 70 times because researchers are measuring very different markets under the same name.
Fortune Business Insights recently updated its climate-tech estimate to $31.45 billion for 2025. Grand View Research puts the same year at $44.74 billion. Meanwhile, Climate Policy Initiative estimates roughly $2.1 trillion of climate finance in 2025, and BloombergNEF counted $2.3 trillion of energy-transition investment.
The difference comes mostly from scope. Fortune's market is organized around technologies such as IoT, digital twins, AI and building information modeling. BloombergNEF counts money spent buying EVs, building charging networks, renewable power, batteries, grids, electrified heating, clean industrial equipment, hydrogen and carbon capture.
Both definitions can produce internally valid numbers. They are answering different questions.
For investors, founders or companies asking how much money is already moving through the climate economy, the broader definition is more useful. A market definition that leaves most EV purchases, renewable projects and grid construction outside climate tech misses the largest commercial parts of the transition.
What should actually count as climate tech?
We think climate tech should include products, infrastructure and services whose main economic use directly cuts emissions or helps people and businesses deal with climate change.
That puts solar, wind, batteries, electric vehicles, charging networks, grids, heat pumps, industrial decarbonization, low-carbon fuels, carbon capture and many adaptation technologies clearly inside the market.
Generic technologies need a tighter test. An AI model used to optimize a grid can be climate tech. The same underlying AI model used for advertising has little reason to enter a climate-tech TAM. A semiconductor inside an EV drivetrain belongs in the climate value chain more naturally than the same semiconductor inside a gaming PC.
This boundary keeps the category useful. Once every bank, software company, construction firm and chipmaker with some climate exposure gets counted, climate tech starts to mean almost the entire economy.
For this article, we therefore measure the market mainly through direct spending on climate-related technologies and infrastructure, then look separately at venture funding, company revenue and future investment needs.
If you want more recent data on this point, please see our latest climate tech market report.
Is the $31 billion to $45 billion climate-tech estimate actually useful?
A $31 billion to $45 billion climate-tech estimate is useful for a narrow technology layer, but it is far too small to describe the climate-tech economy people are actually building today.
The easiest reality check is electrified transport. BloombergNEF measured $893 billion of spending on EVs and charging infrastructure in 2025. Renewable-energy investment added another $690 billion, while power grids attracted $483 billion.
Any one of those categories dwarfs the entire climate-tech market described by the narrow commercial estimates.
The mismatch gets even clearer when we look at physical activity. More than 20 million electric cars were sold globally in 2025 according to the IEA, around one in four new cars. IRENA recorded 692 GW of new renewable capacity in the same year.
So when a report says climate tech is worth around $40 billion, we read that as a specialized software, services and technology market. We would not use it as the headline size of the broader climate-tech economy.

Theory only gets you so far. In our research about climate technology, we dig up the real signals from the field and show you the ones worth watching.
So how big is the climate-tech market today?
The best current answer is roughly $2.1 trillion to $2.3 trillion a year for broad climate-tech and energy-transition spending.
Three large datasets now land in almost the same place despite using different methodologies. Climate Policy Initiative estimates climate finance at about $2.1 trillion in 2025. The IEA expects around $2.2 trillion of clean-energy investment in 2026. BloombergNEF measured $2.3 trillion of energy-transition investment in 2025.
That convergence is more useful than any one exact number. CPI includes a wider climate-finance universe, the IEA concentrates on energy, and BloombergNEF tracks deployment across ten transition sectors. Yet all three tell us the same thing: climate-related capital is currently measured in trillions of dollars per year.
For this article, we use about $2.2 trillion as the working headline and a $2.1 trillion to $2.3 trillion range whenever precision matters.
| Measure | Latest scale | What it measures |
|---|---|---|
| Fortune Business Insights climate tech | $31.45B | Narrow technology market |
| Grand View Research climate tech | $44.74B | Climate technologies and services |
| Dealroom climate-tech VC | $39.0B | Startup venture funding in 2025 |
| BloombergNEF climate-tech equity | $77.3B | Private and public equity raised in 2025 |
| Climate Policy Initiative climate finance | ~$2.1T | Broad climate investment estimate for 2025 |
| IEA clean-energy investment | ~$2.2T | Expected clean-energy investment in 2026 |
| BloombergNEF energy transition | $2.3T | Deployment across major transition technologies in 2025 |
If you want more recent data on this point, please see our latest climate tech market report.
Does a $2.2 trillion climate-tech market mean companies make $2.2 trillion in revenue?
Climate tech's roughly $2.2 trillion headline measures annual spending and investment, so we should avoid reading it as one industry's revenue.
Some transactions translate very directly into company sales. A household buying an EV creates automotive revenue. A utility buying transformers creates revenue for grid-equipment manufacturers. A developer purchasing batteries creates revenue for battery suppliers.
Large infrastructure projects make the relationship messier. A $1 billion wind project can include turbines, construction, financing, engineering, land, grid connections and many years of future electricity production. Adding all those company revenues together can create a number above the original project investment.
This is why we prefer spending when comparing the overall size of climate tech today. It gives us a relatively clean measure of how much capital customers, households, companies and governments are committing to climate-related assets every year.
Revenue is more useful once we zoom into a particular company or submarket.

In our market report about climate technology, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Where is all the climate-tech money actually going?
Climate tech today is dominated by EVs, renewable power and grids, which together absorb close to 90% of BloombergNEF's tracked transition investment.
That concentration surprised us more than the headline market size.
Climate tech often gets discussed through hydrogen, carbon removal, green steel, fusion, sustainable aviation fuel and other frontier technologies. The actual spending picture is much more conventional. Electric transport alone attracted $893 billion in 2025. Renewable power received $690 billion. Grids reached $483 billion.
Together, those three categories account for slightly more than $2 trillion. Adding batteries takes the mature core above 92% of the total.
So most climate-tech money currently goes toward technologies that have already reached mass commercial deployment rather than technologies still proving whether they can scale.
| Climate-tech segment | 2025 investment | Approx. share |
|---|---|---|
| Electrified transport | $893B | 38.7% |
| Renewable energy | $690B | 29.9% |
| Power grids | $483B | 20.9% |
| Electrified heat | $84B | 3.6% |
| Energy storage | $71B | 3.1% |
| Nuclear | $36B | 1.6% |
| Clean industry | $34B | 1.5% |
| Hydrogen | $7.3B | 0.3% |
| Carbon capture and storage | $6.6B | 0.3% |
| Clean shipping | $4.1B | 0.2% |
How big is frontier climate tech compared with EVs, renewables and grids?
Frontier climate technologies still represent a surprisingly small share of the climate-tech market today.
If we group electrified heat, nuclear, clean industry, hydrogen, carbon capture and clean shipping together, BloombergNEF's 2025 figures add up to about $172 billion. That is roughly 7.5% of total transition investment.
Hydrogen and carbon capture show the gap especially clearly. Hydrogen attracted $7.3 billion and carbon capture $6.6 billion. Together they account for around six-tenths of one percent of the total.
Energy storage sits in a different position. Battery investment reached $71 billion and is now tied directly to huge existing markets in transport and power. It increasingly looks like part of the mature transition rather than a speculative climate category.
There are really two climate-tech markets here. The first is already enormous and led by EVs, renewables, grids and batteries. The second contains many technologies that could become huge but currently operate on a much smaller commercial base.
That distinction matters whenever someone uses a multi-trillion-dollar climate TAM to describe the opportunity for an early-stage hydrogen, carbon-removal or industrial-tech startup.
If you want more recent data on this point, please see our latest climate tech market report.

In our document detailing everything you need to know about climate tech, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Has climate tech already overtaken fossil fuels?
Clean technologies currently attract more new energy investment than fossil fuels, although the financing system itself remains much more evenly split.
The IEA expects around $2.2 trillion to go into renewables, nuclear, grids, storage, low-emissions fuels, efficiency and electrification in 2026. Oil, gas and coal are expected to attract about $1.2 trillion. On this measure, clean-energy investment is approaching twice fossil investment.
BloombergNEF also found that clean-energy supply investment exceeded fossil-fuel supply investment for the second consecutive year in 2025. The gap widened to $102 billion.
A recent BloombergNEF study adds an important qualification. Banks arranged about $0.97 of low-carbon energy-supply financing for every $1 of fossil-fuel financing in 2025. The ratio improved from $0.95 a year earlier, and low-carbon bank financing grew 16%, yet bank financing has still barely reached parity.
Capital expenditure has moved further toward clean energy than the banking system has. That describes the market better than saying the financial transition is already complete.
How big is the climate-tech startup market?
Climate-tech startups attract tens of billions of dollars a year, which makes venture capital important but small beside the trillions spent deploying climate technologies.
Dealroom recorded $39 billion of global climate-tech VC funding in 2025. Startups raised another $19.5 billion during the first half of 2026, putting the current pace roughly in line with last year.
BloombergNEF's broader equity measure, which also includes private equity and public markets, reached $77.3 billion in 2025. That was up 53% after three consecutive years of decline.
The contrast with physical investment is huge. Venture funding represents less than 2% of broad annual climate investment.
This explains why climate tech can keep getting larger while climate VC goes through a bad year. Households continue buying EVs and heat pumps. Utilities keep spending on grids. Developers keep financing solar, wind and batteries. Those markets depend much more on project finance, corporate balance sheets, banks and consumer spending than on venture firms.
For startup analysis, we therefore treat the $39 billion VC market as one financing channel inside a vastly larger climate economy.
Is the climate-tech market still growing right now?
Climate tech is still growing, although headline investment growth has slowed sharply and several major sectors have entered a more mature phase.
BloombergNEF says transition investment grew 8% in 2025, compared with 27% growth in 2021. Climate Policy Initiative sees a similar slowdown across broader climate finance.
The latest renewable numbers show what that maturity looks like. BloombergNEF counted $327.5 billion of renewable investment during the first half of 2026. That was roughly flat versus the previous six months and 21% below the peak reached in the second half of 2024.
The underlying mix changed much more dramatically. Investment in projects combining solar and storage reached a record $25 billion, nearly three times the level from one year earlier. Grid investment had already jumped 17% in 2025. EV and charging spending grew 21%.
What we see is rotation rather than a broad retreat. Plain renewable generation has become a more mature market, while grids, storage and electrified transport are taking a larger share of incremental capital.
Climate tech now looks less like one synchronized boom and more like a collection of huge markets moving at different speeds.

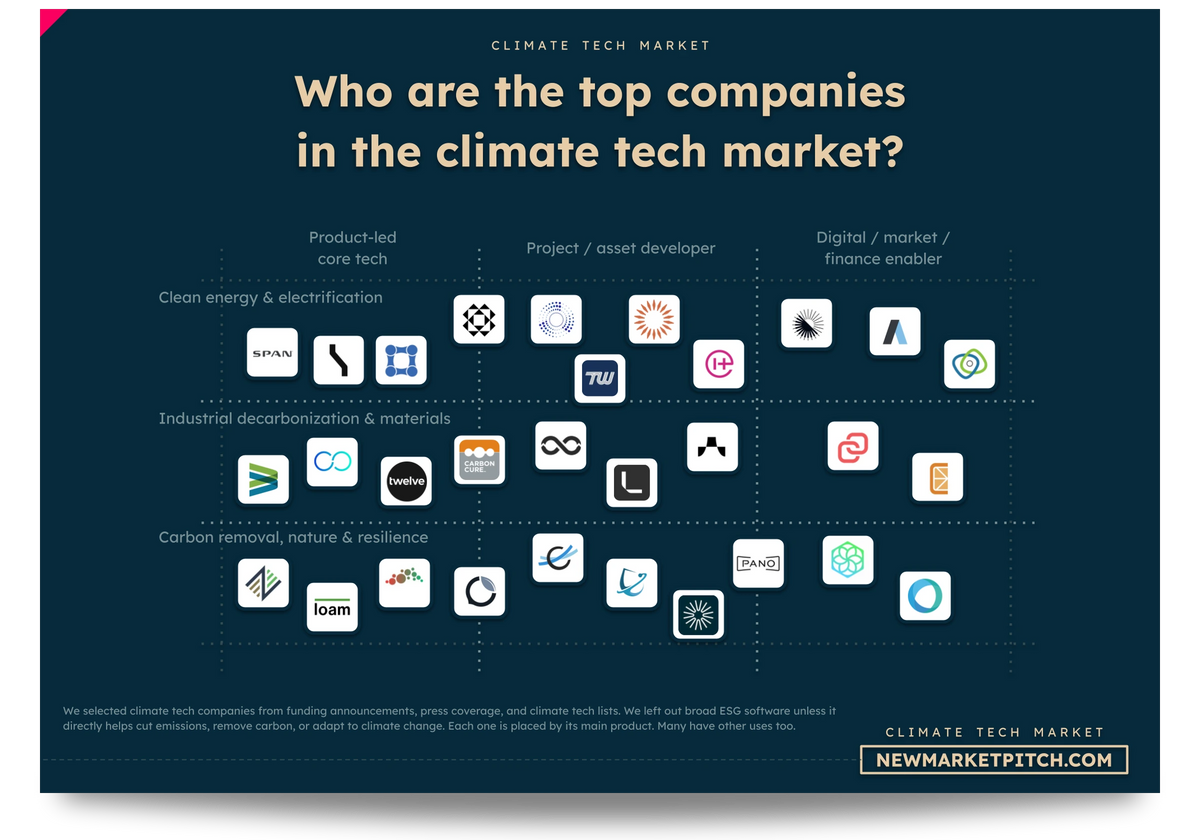
In our report covering the climate tech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Are falling solar and battery prices hiding how fast climate tech is growing?
Falling equipment prices are making climate tech grow much faster in physical terms than dollar spending alone suggests.
IRENA estimates that installed solar costs have fallen 87% since 2010 and battery-storage costs 93%. Its latest power-cost study puts average utility-scale solar electricity at about $44 per MWh and onshore wind at $33 per MWh.
That changes how we should read investment data.
Renewable-energy investment fell 9.5% in 2025 according to BloombergNEF. During the same year, IRENA counted a record 692 GW of new renewable capacity, enough to expand worldwide renewable capacity by 15.5%. Renewables represented 85.6% of all new power capacity added globally.
So fewer investment dollars can now buy more panels, batteries and generating capacity.
This effect is especially important in solar, where enormous manufacturing scale and aggressive competition have pushed equipment prices down. Battery-pack prices also fell from $118/kWh in 2024 to $108/kWh in 2025 according to BloombergNEF's latest supply-chain work.
A climate-tech market growing 8% in dollars can therefore be expanding considerably faster in units, installed capacity and actual energy delivered.
Are companies buying climate tech mainly because governments want them to?
Climate-tech demand increasingly comes from normal economic decisions as well as climate policy.
The economics are clearest in electricity. IRENA's latest cost study found that more than 90% of utility-scale renewable projects commissioned in 2025 generated power more cheaply than the cheapest new fossil-fuel alternative available in their market.
Consumer spending tells a similar story. Climate Policy Initiative found that households invested $332 billion in low-carbon technologies in 2024, including EVs, heat pumps and small-scale renewable systems. Domestic private actors now provide 60% of mitigation finance.
Energy security has become another large driver. The IEA says the second major global energy crisis in five years has pushed governments and companies to place greater value on locally available energy, grids and electrification.
Policy still matters enormously. Tax credits, mandates, carbon prices, permitting rules and public procurement can change project economics quickly, particularly in hydrogen, carbon capture, nuclear and clean industry.
But the mature end of climate tech increasingly sells on price, performance, energy security and operating costs alongside emissions reductions. That makes the current market more durable than one built entirely on climate targets.
If you want more recent data on this point, please see our latest climate tech market report.

Our research about climate technology gets updated several times a month, so you always get the latest view of where things stand.
How dependent is the climate-tech market on China?
Climate tech remains heavily dependent on China for manufacturing, while investment and deployment are gradually spreading across more countries.
BloombergNEF measured around $800 billion of Chinese transition investment in 2025, roughly 35% of the global total. The EU reached $455 billion and the US $378 billion. Those three markets together represented about 71% of worldwide spending.
China's grip is stronger on manufacturing than on deployment. BloombergNEF says the country still accounts for a clear majority of global investment in clean-tech supply chains, especially batteries, solar equipment and battery materials.
There are early signs of diversification. China's domestic transition investment declined for the first time since 2013. India is building a much larger solar-manufacturing base. Solar-cell production is spreading beyond China as module assembly expands in other countries.
Trade gives us another useful scale. Global cross-border trade in clean-energy products reached $479 billion in 2025, according to BloombergNEF. Climate Policy Initiative found that more than $1.7 trillion, or 85% of climate investment, was financed domestically in 2024.
Climate tech therefore depends heavily on global manufacturing supply chains, while most of the actual investment happens inside the country where the asset gets built or purchased.
| Geography or flow | Latest value | What it tells us |
|---|---|---|
| China transition investment | $800B | Largest national market |
| European Union | $455B | Second major investment pole |
| United States | $378B | Third major investment pole |
| India | $68B | Smaller base with rapid expansion |
| China + EU + US | ~$1.63T | About 71% of global transition spending |
| Global clean-energy trade | $479B | Cross-border equipment and materials |
| Domestic climate finance | >$1.7T | 85% of climate finance in CPI's 2024 data |
How big is the climate-adaptation market today?
Climate adaptation is still tiny beside climate mitigation, with only about $64 billion of tracked annual investment.
Climate Policy Initiative's latest Global Landscape of Climate Finance shows adaptation spending flat at around $64 billion in 2024. That represents only a few percent of the broader climate-finance market.
The number almost certainly understates the real economic activity. CPI itself struggles to capture private spending on air conditioning, flood protection, resilient buildings, water systems, wildfire technologies and other products whose adaptation role may be only part of the purchase decision.
Earlier CPI research gives an idea of what may be missing. Looking at only 113 household product categories, it estimated $48 billion to $61 billion of annual spending on products with a high likelihood of adaptation relevance. Those amounts were excluded from its main aggregate because the dataset was incomplete.
The commercial opportunity is therefore larger than the tracked $64 billion suggests, but the measurement is still weak.
For now, adaptation looks like one of the clearest gaps inside climate tech: huge physical need, growing losses from heat, drought, floods and fires, and surprisingly little capital formally classified as adaptation investment.

In our market report about climate technology, you will always find fresh funding data, taken straight from our own verified funding database.
How big could climate tech get under today's economics?
Climate tech can plausibly become a roughly $3 trillion annual investment market within a few years without assuming a perfect net-zero transition.
BloombergNEF's base-case Economic Transition Scenario expects average annual energy-transition investment of about $2.9 trillion over 2026-2030. That is around 25% above its 2025 level.
The important words are base case. BloombergNEF's scenario follows technology costs, existing policy settings, demand growth and normal investment decisions. It produces continued electrification and clean-power growth while still leaving the world well short of a full net-zero pathway.
That makes roughly $3 trillion much more useful as a medium-term commercial estimate than the giant climate-needs numbers often quoted as TAMs.
The drivers are already visible today. Electricity demand is rising. Data centers need power. Grids need reinforcement. EV adoption keeps expanding. Storage is becoming part of ordinary power infrastructure. Renewable generation remains cheaper than new fossil generation in most markets.
We therefore treat $3 trillion a year as a realistic next scale for broad climate-tech deployment, assuming the current transition continues without a major global reversal.
How big would climate tech become on a real 1.5°C pathway?
A genuine 1.5°C pathway would push annual climate investment toward roughly $8 trillion this decade and about $9 trillion in the first half of the 2030s.
Climate Policy Initiative recently updated its synthesis of 19 separate climate-finance-needs studies. Its average scenario now requires about $7.8 trillion of annual mitigation finance through 2030 and $9 trillion a year from 2031 to 2035.
Current tracked mitigation finance sits around one-quarter of that first figure.
The gap is especially large in sectors that have barely started scaling. CPI estimates that energy needs another $1.4 trillion a year through 2030 and transport another $1.5 trillion. Agriculture, forestry and land use would need roughly 153 times their current funding level on its comparison, while industry would need about 31 times more.
BloombergNEF reaches the same broad conclusion through a different model. Its Net Zero Scenario requires $235 trillion of cumulative transition investment through 2050.
We treat these figures as conditional investment requirements rather than market forecasts. CPI explicitly warns that its models use very different assumptions and should be read as indications of scale.
They still tell us something important about the upside. Today's roughly $2 trillion climate economy has room to become several times larger using technologies and infrastructure categories that already exist. The challenge is how quickly the world actually chooses, finances and manages that buildout.

In our document detailing everything you need to know about climate tech, we look at what the winners do differently, so you can learn from the best instead of guessing.
So what is the real market size of climate tech?
The real climate-tech market is currently around $2.2 trillion a year, with a defensible range of roughly $2.1 trillion to $2.3 trillion for broad annual climate and transition investment.
The narrow $31 billion to $45 billion estimates describe a useful technology slice, but they leave out most of the physical economy where climate spending actually happens.
The composition is even more revealing than the total. EVs, renewable power and grids dominate today's spending. Batteries are joining that mature core. Hydrogen, carbon capture, clean shipping and other frontier technologies remain small despite receiving a large share of climate-tech attention.
Startup funding is smaller again. Dealroom's $39 billion of 2025 climate VC shows that venture capital represents only a thin layer of the overall market.
Growth has slowed in dollar terms, yet physical deployment is still breaking records as solar and battery costs fall. Recent data also shows capital moving toward grids, storage and more integrated power systems rather than disappearing from climate tech.
For the next few years, roughly $3 trillion a year is the most credible base-case scale. A serious 1.5°C pathway would require annual investment to climb much further, toward roughly $8 trillion and eventually $9 trillion.
The useful answer is therefore far tighter than the range normally thrown around online: climate tech is already a multi-trillion-dollar annual market, with most of today's money concentrated in a handful of mature technologies and several of its most talked-about frontier sectors still waiting for real commercial scale.
If you want more recent data on this point, please see our latest climate tech market report.
Our methodology
“How big is climate tech?” looks like a simple market-sizing question, but there is no single universally accepted definition of the market and published answers can differ enormously depending on what is being counted.
Rather than picking one estimate and treating it as definitive, we approached the question from several angles: capital actually being deployed, physical adoption, financing flows, company funding, technology economics, geographic concentration and forward investment requirements. This keeps any single definition or dataset from determining the conclusion.
We prioritized the freshest available evidence and went as close to the underlying data as possible. First-hand research from institutions that directly track investment, deployment, capacity, sales, costs and financing activity carries the most weight. Commercial market estimates are used mainly to show why headline market-size figures diverge so sharply.
We kept unlike numbers separate. Venture funding, consumer spending, infrastructure investment, company revenue and future investment requirements answer different questions, so they are not pooled into one artificial total. Where several independent datasets measure a similar phenomenon, we compare them for convergence; where they differ, we look at scope, definition, period and underlying activity.
Only after that review do we form the broader conclusions. Strong statements in the article generally rely on several recent signals pointing in the same direction, while narrower evidence gets a narrower conclusion. The result is not a single-source TAM but a structured estimate built from recent, checkable evidence.
Key sources used for this analysis include: Fortune Business Insights on the narrow climate-tech market, Grand View Research on climate-tech market size, BloombergNEF's Energy Transition Investment Trends 2026, BloombergNEF's transition-investment methodology and scope, the IEA's World Energy Investment 2026, the IEA's underlying investment datafile, Climate Policy Initiative's Global Landscape of Climate Finance 2026, CPI's update on global climate-finance flows, Dealroom's climate-tech funding data, BloombergNEF on low-carbon and fossil-fuel bank financing, BloombergNEF on first-half 2026 renewable investment, IRENA's Renewable Capacity Statistics 2026, IRENA's Renewable Power Generation Costs in 2025, BloombergNEF's battery-price survey, the IEA's Global EV Outlook 2026, BloombergNEF on clean-energy trade and supply chains, CPI on private-sector adaptation finance, BloombergNEF's New Energy Outlook 2026, and CPI's synthesis of top-down climate-finance needs.

If you build or invest in the climate tech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us