Digital Twin Funding: A Quarter-by-Quarter Analysis
Everything we know about the digital twin market, in one place. Get our report whether you build or invest.
Summary
Digital twin funding was clearly slowing by Q2 2026. Deal count fell from 11 in both Q3 and Q4 2025 to eight in Q1 2026 and just five in Q2, while quarterly capital dropped to $62.6 million.
The slowdown is broader than the headline 54% fall in capital from Q1 to Q2 suggests. Q1 included Neara’s roughly $63 million Series D, but even after removing rounds above $50 million, funding still declined by about 15% and the number of financings kept falling.
Q3 2025 was the most deceptive quarter in the period. Makersite, PassiveLogic and Twin Health supplied almost 85% of its $232.1 million total, while six of the 11 deals were below $5 million and there was nothing between $5 million and $20 million.
Q4 2025 looked healthier underneath a lower headline total. Capital excluding rounds above $50 million nearly tripled from Q3, five companies raised between $5 million and $20 million, and the median round reached a five-quarter high of $9.3 million.
Infrastructure twins had a genuine Q1 2026 surge, led by Neara and ThinkLabs, but it did not carry into Q2. Infrastructure Twin Systems went from about 72% of Q1 capital to roughly 9% in the following quarter.
The latest quarter was unusually concentrated even without a classic $100 million megaround. SPREAD AI and Gigaton together accounted for about 89% of Q2 2026 funding, and the top three deals represented almost 96%.
New-company formation is not translating into many first financings. No quarter had more than two first-time raises, while the overwhelming majority of capital consistently went to companies that had already raised before.
Early-stage activity has not disappeared. Seed and Series A rounds were still a majority of deals across the period, but they rarely controlled the dollar totals; bigger follow-on rounds at more established companies determined whether a quarter looked strong or weak.
Europe has the most consistent deal footprint, but not a stable lead in capital. North America, Asia-Pacific and Europe each took the dollar lead at different points because one or two large financings could completely reshape a quarter.
The strongest recent scale-up stories are increasingly tied to concrete industrial outcomes: grid planning, warehouse operations, product engineering, industrial control and other workflows where better modelling can move energy use, downtime, inventory accuracy or engineering speed.
Corporate investors are becoming more visible just as the overall market gets smaller. Strategic participation rose from 27% of deals in Q4 2025 to 50% in Q1 2026 and 60% in Q2, suggesting that industry access and strategic fit are becoming more important in deciding which platforms get funded at scale.
Post-period funding reinforces the same pattern rather than reversing it. Buildots’ $130 million financing in September 2026 shows that nine-figure rounds remain available, but mostly for digital-twin companies that have already proved commercial traction.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the digital twin market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the digital twin market over the last years
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our report covering the Digital Twin Market.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country |
|---|---|---|---|---|---|---|---|---|
| Buildots | Building Twin Software | September 2026 | Series D+ | $130M | Uses computer vision, BIM, schedules, and recurring site captures to maintain digital twins of construction projects for progress tracking and delay forecasting. | Middle East | O.G. Venture Partners | Israel |
| Antioch | Asset Twin Platforms | September 2026 | Series A | $32M | Provides a cloud platform that converts real robots and autonomous systems into telemetry-calibrated digital twins for parallel simulation, testing, and validation. | North America | Greylock Partners | United States |
| GridSight | Infrastructure Twin Systems | September 2026 | Series B | $26M | Builds AI-powered electrical digital twins of distribution grids using utility operational data and physics to model capacity and optimize grid connections and operations. | Asia-Pacific | Insight Partners | Australia |
| Bios Life | Process Twin Applications | August 2026 | Seed | $25M | Maintains continuously updated patient digital twins from genomic, clinical, laboratory, and lifestyle data to personalize cancer screening and survivorship surveillance. | North America | Redmile; Vsquared Ventures; Kindred Capital | United States |
| NavVis | Asset Twin Platforms | August 2026 | Series D+ | $85M | Provides survey-grade reality capture and the NavVis IVION platform to maintain always-current spatial twins of factories, plants, buildings, and infrastructure. | Europe | The Jordan Company | Germany |
| Reform Technologies | Process Twin Applications | June 2026 | Seed | ≈$1.1M | Builds digital twins of banks' live AML transaction-monitoring environments so institutions can simulate, validate and optimize control changes before production deployment. | Europe | Not disclosed | Belgium |
| Gigaton | Process Twin Applications | June 2026 | Series A | $26M | Continuously models live industrial-plant processes in digital twins to predict operating behavior, simulate control changes and autonomously optimize production. | Europe | Plural | United Kingdom |
| ConeLabs | Infrastructure Twin Systems | June 2026 | Seed | $1.5M | Creates AI-powered 3D digital twins of bridges, roads and other infrastructure from field imagery for defect detection, change tracking and inspection workflows. | North America | Spatial Capital | Canada |
| Sensat | Infrastructure Twin Systems | May 2026 | Unknown | $4M | Provides geospatial AI software that creates and maintains digital twins of civil infrastructure projects and assets for planning, monitoring and delivery optimization. | Europe | Mercia Ventures | United Kingdom |
| JuliaHub | Asset Twin Platforms | April 2026 | Series B | $65M | Platform (Dyad) that builds physics-based digital twins of engineered systems | North America | Dorilton Capital | United States |
| SPREAD AI (SPREAD GmbH) | Asset Twin Platforms | April 2026 | Series B | $30M | Builds live Product Twins that unify engineering, manufacturing, operations, and service data for complex industrial products. | Europe | OTB Ventures | Germany |
| Antaris, Inc. | Asset Twin Platforms | March 2026 | Series A | $28M | Provides full-mission virtualization software whose TrueTwin environment models satellite systems and mission behavior from design through on-orbit operations. | North America | WestWave Capital | United States |
| ThinkLabs | Infrastructure Twin Systems | March 2026 | Series A | $28M | Provides physics-informed AI digital twins and high-performance simulation for electric-grid planning and operations. | North America | Energy Impact Partners | United States |
| Enline | Infrastructure Twin Systems | March 2026 | Unknown | ≈$2.3M | Provides live, sensorless multi-physics digital twins of power grids for monitoring, forecasting, capacity optimization and operational decision-making. | Europe | Not disclosed | Portugal |
| Prevu3D Inc. | Asset Twin Platforms | March 2026 | Unknown | ≈$3.7M | Provides an as-built digital-twin platform that turns repeat reality-capture data into up-to-date interactive industrial facility models linked to engineering and enterprise systems. | North America | Not disclosed | Canada |
| Neara | Infrastructure Twin Systems | February 2026 | Series D+ | ≈$63M | Builds physics-enabled digital twins of power and critical-infrastructure networks for engineering analysis, scenario simulation, planning, and operations. | Asia-Pacific | TCV | Australia |
| SPACE AIC Co., Ltd. (天空智算互联网科技(上海)有限责任公司) | Infrastructure Twin Systems | February 2026 | Seed | ≈$1.4M | Builds satellite-network digital-twin systems for constellation planning, real-time simulation and prediction, hardware-in-the-loop validation, and intelligent operations. | Asia-Pacific | Fudan Science & Technology Innovation (复旦科创) | China |
| Powerline | Asset Twin Platforms | February 2026 | Seed | $7M | Runs continuously updated AI digital twins of battery projects and portfolios using operational and market data for benchmarking, scenario testing, and optimization. | North America | MaC Venture Capital | United States |
| AVES Reality GmbH | Infrastructure Twin Systems | January 2026 | Seed | ≈$3.2M | Generates georeferenced, simulation-ready digital twins of real environments from satellite and aerial data, with live and periodic data integration for monitoring and what-if simulation. | Europe | Matterwave Ventures | Germany |
| Sim&Cure | Process Twin Applications | November 2025 | Series A | ≈$11.6M | Provides patient-specific digital twins that let clinicians simulate and optimize neurovascular device placement and endovascular treatments before intervention. | Europe | Elaia | France |
| Parallax Worlds | Factory Twin Software | November 2025 | Seed | $4M | Creates high-fidelity digital twins of factories and warehouses so robotics teams can stress-test and optimize robots before physical deployment. | North America | Pear VC | United States |
| Mondra | Process Twin Applications | October 2025 | Series A | $13.3M | Maintains product-level digital twins of food supply chains for live environmental, price and climate-risk tracking and sourcing scenario analysis. | Europe | AlbionVC; Planet A Ventures | United Kingdom |
| etalytics | Process Twin Applications | October 2025 | Series A | $9.3M | Maintains digital twins of industrial energy, HVAC and cooling systems for real-time monitoring, predictive analysis, scenario simulation and autonomous operating optimization. | Europe | M12 | Germany |
| TaDa | Building Twin Software | October 2025 | Seed | $2.3M | Creates continuously updated digital twins of homes and commercial or industrial spaces from smart-meter data to disaggregate loads, detect anomalies and optimize energy consumption. | Europe | Italian Founders Fund (IFF); Nextalia Ventures | Italy |
| Dexory | Process Twin Applications | October 2025 | Series C | $100M | Combines autonomous scanning robots with DexoryView to maintain a live digital twin of warehouse inventory and operations for continuous visibility and optimization. | Europe | Eurazeo | United Kingdom |
| Enurgen | Asset Twin Platforms | October 2025 | Seed | $4.1M | Maintains physics-based digital twins of utility-scale solar plants from design through operations, reconciling field performance with modeled output to detect and optimize losses. | North America | Business Development Bank of Canada (BDC); Brightspark; Diagram | Canada |
| Cyberwave | Asset Twin Platforms | October 2025 | Seed | $8.1M | Maintains synchronized programmable digital twins of robots, sensors and machines for live control, telemetry, simulation and AI-driven physical automation. | Europe | United Ventures | Italy |
| Intangles | Asset Twin Platforms | October 2025 | Series B | $30M | Creates data-driven digital twins of vehicles from live telematics to predict component failures and optimize fleet maintenance and performance. | Asia-Pacific | Avataar Venture Partners | India |
| Metreecs | Process Twin Applications | October 2025 | Seed | $2.7M | Maintains digital twins of retailers' distribution networks to combine inventory and external signals for forecasting, allocation, replenishment and rebalancing decisions. | Europe | Not disclosed | France |
| CYVL | Infrastructure Twin Systems | October 2025 | Series A | $14M | Builds continuously refreshed digital twins of roads, sidewalks and municipal assets from vehicle-mounted LiDAR and imagery for condition monitoring, planning and maintenance optimization. | North America | Sentinel Global | United States |
| Optimuse | Building Twin Software | October 2025 | Seed | $4.7M | Creates building digital twins used for physics-based energy simulation, variant analysis and operational performance optimization using building, consumption and sensor data. | Europe | seed + speed Ventures; Blum Ventures | Austria |
| Cetasol AB | Asset Twin Platforms | September 2025 | Seed | ≈$2.7M | Provides continuously updated vessel and engine digital twins through iHelm for fuel, operational-performance and predictive-maintenance optimization. | Europe | BackingMinds; Shift4Good | Sweden |
| C2GRID | Infrastructure Twin Systems | September 2025 | Seed | ≈$354K | Creates near-real-time 3D digital twins of evolving battlespaces from UAV and video feeds for situational awareness, change detection and mission planning. | Europe | Sunfish Partners | Estonia |
| PassiveLogic | Building Twin Software | September 2025 | Series C | $74M | Provides physics-based real-time digital twins and autonomous-control software for buildings and building systems. | North America | noa | United States |
| Crion Technologies Private Limited | Asset Twin Platforms | September 2025 | Unknown | ≈$398K | Provides the Clonos industrial digital-twin platform for live asset monitoring, simulation, predictive maintenance and remote asset management. | Asia-Pacific | SIG Tattva | India |
| Teton.ai | Process Twin Applications | September 2025 | Series A | $20M | Maintains live digital twins of residents, spaces and care delivery using computer vision to support continuous monitoring and predictive care. | Europe | Plural | Denmark |
| Red Dot Analytics Pte. Ltd. | Infrastructure Twin Systems | August 2025 | Seed | Not Disclosed | Builds AI- and physics-driven data-center digital twins using live infrastructure data for simulation, capacity planning, energy optimization and predictive maintenance. | Asia-Pacific | Granite Asia | Singapore |
| Twin Health | Process Twin Applications | August 2025 | Series D+ | $53M | Creates continuously updated metabolic digital twins from connected-device, laboratory and behavioral data to optimize chronic metabolic care. | North America | Maj Invest | United States |
| Beijing Freedo Technology Co., Ltd. (北京飞渡科技股份有限公司) | Asset Twin Platforms | August 2025 | Unknown | Not Disclosed | Develops a cross-industry digital twin platform combining spatial data, real-time rendering, simulation and AI for cities, buildings, infrastructure and factories. | Asia-Pacific | Not disclosed | China |
| Bisly | Building Twin Software | August 2025 | Series A | ≈$5M | Provides building automation software and controls centered on a real-time digital twin of each building for diagnostics and continuous energy and performance optimization. | Europe | 2C Ventures | Estonia |
| Makersite GmbH | Asset Twin Platforms | July 2025 | Series B | $70.2M | Creates digital twins of manufactured products and supply chains from enterprise product data to optimize cost, sustainability, compliance and sourcing decisions. | Europe | Lightrock; Partech | Germany |
| Dockware, Inc. | Asset Twin Platforms | July 2025 | Seed | $2.5M | Creates real-time digital twins of freight shipments from computer-vision scans to validate identity, dimensions, condition and downstream handling. | North America | Zenda Capital | United States |
| RTDT Laboratories AG | Asset Twin Platforms | July 2025 | Seed | $4M | Creates real-time digital twins of wind turbines using blade-mounted sensors and physics/data-driven analytics to optimize control, design and maintenance. | Europe | Swisscom Ventures | Switzerland |

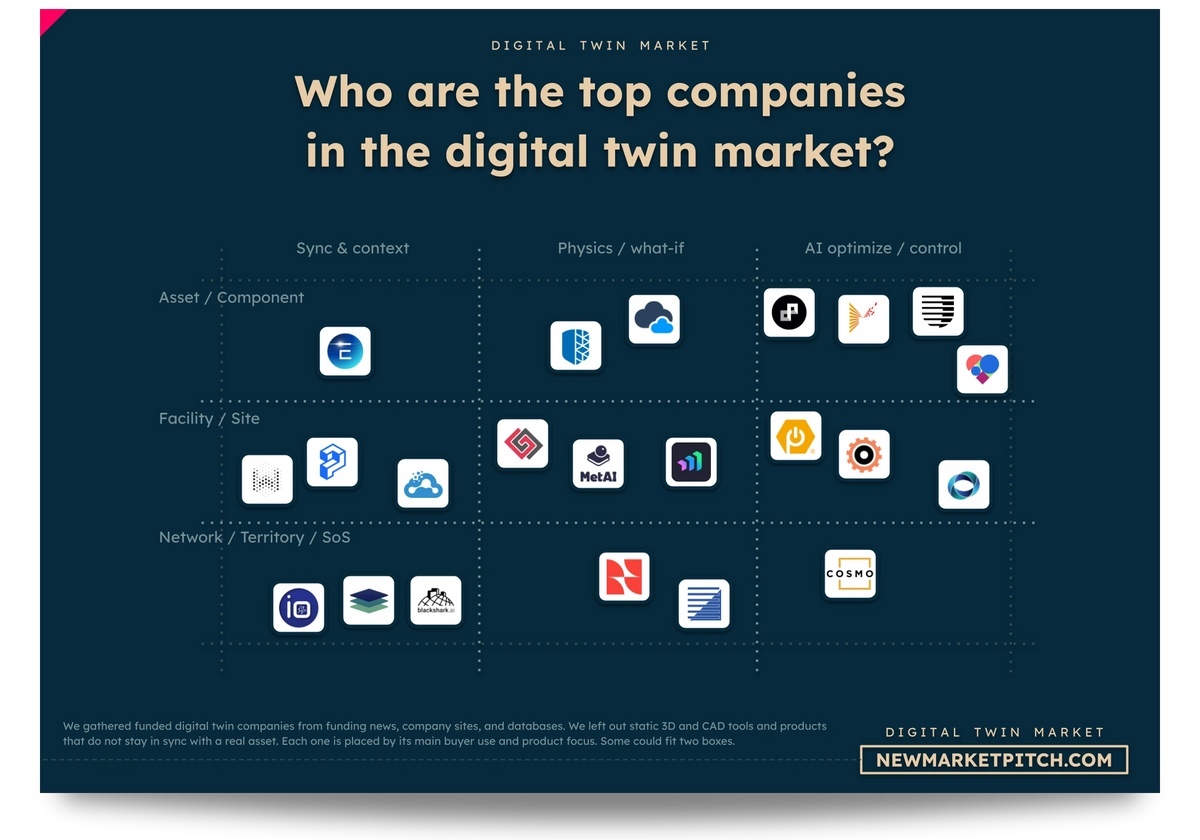
In our research about digital twins, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is digital twin funding really slowing down now?
Digital twin funding is clearly slowing in terms of deal activity right now: quarterly financings fell from 11 in late 2025 to eight in Q1 2026 and only five in Q2 2026.
Capital moved in the same direction after peaking at $232.1 million in Q3 2025. It dropped to $201.8 million in Q4, $136.5 million in Q1 2026 and $62.6 million in Q2. The slowdown therefore goes beyond one missing giant round. Fewer companies are actually raising money.
Headline capital does make the latest fall look more dramatic than it was underneath. Q1 included Neara’s roughly $63 million Series D, while Q2 had no round above $50 million. Once we remove rounds above that threshold, capital fell by about 15% from Q1 to Q2 rather than 54%.
By Q2 2026, the picture is fairly clear. Investors can still put $20–30 million into digital twin companies they like, as SPREAD AI and Gigaton showed in Q2. What has weakened is everything around those larger checks: fewer financings, fewer mid-sized rounds and less depth across the market.
| Period | Deals | Capital | Capital ex >$50M | Median round |
|---|---|---|---|---|
| Q2 2025 | 9 | $104.9M | $104.9M | $7.0M |
| Q3 2025 | 11 | $232.1M | $34.9M | $4.5M |
| Q4 2025 | 11 | $201.8M | $101.8M | $9.3M |
| Q1 2026 | 8 | $136.5M | $73.5M | $5.3M |
| Q2 2026 | 5 | $62.6M | $62.6M | $4.0M |
| Headline peak | Q3 2025 | $232.1M | - | - |
| Latest vs peak deal count | −54.5% | - | - | - |
Was the Q3 2025 digital twin funding boom basically three big rounds?
Yes. Q3 2025 looked huge on paper, but three digital twin companies generated almost 85% of the quarter’s funding.
Makersite raised roughly $70.2 million, PassiveLogic raised $74 million and Twin Health raised $53 million. Together, those three financings accounted for $197.2 million of the $232.1 million invested during the quarter.
The rest of Q3 was surprisingly thin. Six of the 11 deals were below $5 million, and there was no financing at all between $5 million and $20 million. Remove the rounds above $50 million and quarterly capital drops to $34.9 million, down sharply from $104.9 million in Q2. The median also slipped from $7 million to $4.5 million.
The large rounds themselves were grounded in real commercial progress. Makersite said its Series B would help meet growing demand from manufacturers including Microsoft, Daikin, Cummins and Schneider Electric. PassiveLogic raised its Series C to expand a physical-AI platform for buildings and infrastructure. Twin Health was already scaling a mature digital-twin approach to metabolic care.
Q3 therefore told us something useful, just not that every part of digital twin funding was booming. A few established companies had reached the point where investors were comfortable writing very large checks, while most of the market was raising much smaller amounts.

In our market report about digital twins, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why did Q4 2025 look healthier even though digital twin funding went down?
Q4 2025 was probably the healthiest digital twin funding quarter in our five-quarter window because medium-sized rounds came back strongly even as total capital slipped.
The headline number fell 13% from Q3 to $201.8 million. Underneath it, the distribution improved a lot. Capital excluding rounds above $50 million climbed from $34.9 million to $101.8 million, and the median financing jumped to $9.3 million, the highest level we recorded.
Five companies raised between $5 million and $20 million in Q4. Q3 had none. Seed and Series A deals also made up roughly 82% of the quarter’s transactions, so funding was reaching a broader mix of younger companies again.
Dexory still had an outsized effect. The company raised $100 million of Series C equity as part of a larger $165 million financing package, following strong growth after its previous round and expansion of DexoryView across Europe, North America and Asia-Pacific.
But Q4 did not depend entirely on Dexory. CYVL, etalytics, Mondra, Sim&Cure and several smaller companies gave the quarter a much fuller middle than Q3 had. The lower headline total actually hid a clear improvement in funding breadth.
Why did infrastructure digital twins suddenly take over Q1 2026, and did it last?
Infrastructure digital twins genuinely surged in Q1 2026, especially around electricity and critical infrastructure, but the boom faded immediately in the following quarter.
Infrastructure Twin Systems represented five of eight Q1 deals and about 72% of the quarter’s capital. Neara contributed roughly $63 million and ThinkLabs another $28 million, putting two grid-focused companies at the center of the move.
Neara said its physics-enabled platform had already modelled more than 15 million infrastructure assets when it announced its Series D. ThinkLabs was tackling a related problem with physics-informed AI for electricity-grid planning and operations. Its Series A brought in Energy Impact Partners alongside NVentures and Edison International.
The interest also went beyond those two rounds. AVES Reality raised seed capital for simulation-ready geospatial twins, while ABB Electrification Ventures invested in Enline, another company working around electrical-network modelling.
Then Q2 changed the picture completely. Infrastructure Twin Systems attracted only about $5.5 million, mainly through Sensat and ConeLabs. Their share of market capital fell to 9%.
Grid and infrastructure twins still have a convincing commercial story, especially as utilities deal with harder planning and capacity problems. For now, Q1 looks more like an unusually strong cluster of infrastructure financings than the start of a permanent category takeover.

Our document detailing everything you need to know about digital twin gets updated several times a month, so you always get the latest view of where things stand.
Did digital twin funding really collapse in Q2 2026?
Q2 2026 was a real contraction for digital twin funding, especially in the number of companies raising money, although the 54% drop in headline capital overstates how abruptly the underlying market changed.
Only five deals closed in the quarter. Three were below $5 million, while SPREAD AI raised $30 million and Gigaton raised $26 million. Those two companies alone supplied $56 million of the quarter’s $62.6 million.
The missing middle is hard to ignore. Q2 had no financing between $5 million and $20 million, compared with five such rounds in Q4 2025.
The two large financings also show where investors were still willing to commit serious money. SPREAD connects engineering, manufacturing, software and operating data through what it calls Product Twins for complex machines and vehicles. Gigaton, formerly Carbon Re, uses AI-driven industrial control technology in energy-intensive industries such as cement and is moving into steel, glass and chemicals.
Q2 was weak in breadth while still producing a couple of strong industrial scale-up stories. For the average digital twin startup, though, it was a much colder quarter than the total $62.6 million might suggest.
Are new digital twin startups still getting funded?
New digital twin startups are getting funded, but there are very few of them in the quarterly mix we tracked.
First financings never exceeded two deals in any quarter. Q2 2025 had one, Q3 had two, and each of the following three quarters had only one.
The capital gap is much larger. In Q3, first financings brought in about $2.9 million while companies that had already raised before collected $229.3 million. By Q2 2026, the first-financing deal was worth roughly $1.1 million, compared with $61.5 million going into follow-ons.
Several of the new entrants were genuinely young companies. C2GRID was founded in 2024 before raising its first pre-seed capital in Q3 2025. Cyberwave, founded in 2025, raised its first round in Q4. SPACE AIC, founded in 2024, was the sole first-financing company in Q1 2026.
There is still startup creation around digital twins. The funding market we observed, though, is heavily tilted toward helping existing companies scale rather than continually adding large numbers of newly financed startups.
Are investors pulling away from Seed and Series A digital twin startups?
Investors are still funding plenty of Seed and Series A digital twin companies, but those early rounds rarely decide whether a quarter looks financially strong.
Early-stage deals represented a majority of transactions throughout the period, ranging from about 55% to 82% depending on the quarter. Q4 was particularly active, with nine of 11 deals falling into Seed or Series A.
The dollar distribution looks very different. In Q3, early-stage companies received less than 15% of capital because Makersite, PassiveLogic and Twin Health dominated the quarter. In Q2 2026, Seed and Series A still accounted for three of five deals but captured less than half of the money.
The latest quarter makes the split easy to see. Gigaton’s $26 million Series A was substantial, but the two Seed rounds together were only around $2.6 million. Meanwhile, SPREAD’s Series B contributed another $30 million.
Seed and Series A activity is still alive. The market simply needs successful companies to reach larger follow-on rounds before quarterly funding totals become large.

In our report covering the digital twin market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is digital twin funding moving toward older, more established companies?
Digital twin funding is leaning toward companies with a few years of operating history, especially when we look at where the largest checks are going.
The median age of funded companies moved around rather than climbing steadily: three years in Q2 2025, seven in Q3, then five, five and six years. That is too uneven to call a clean aging trend.
The difference between first financings and follow-ons is much clearer. Newly financed companies were generally only zero to three years old. Follow-on companies had a median age of five to seven years in most quarters.
The biggest rounds fit that profile. Dexory was founded in 2015 before its $100 million equity round. Neara dates to 2016. SPREAD was founded in 2019. Gigaton’s predecessor, Carbon Re, dates to 2020.
These companies are raising money to expand products that have already spent years in development and commercial deployment. The current funding market appears much more comfortable scaling that kind of company than funding a huge wave of brand-new digital twin ventures.
Which digital twin categories are actually gaining ground now?
No single digital twin category has held the funding lead for long enough to dominate the market; capital has rotated between infrastructure, process applications and asset or product twins almost quarter by quarter.
Infrastructure Twin Systems were strong in Q2 2025, almost disappeared from the capital picture in Q3-Q4, then surged in Q1 2026 before dropping sharply again.
Process Twin Applications had their big moment in Q4, when Dexory helped push the category to 68% of quarterly funding. The segment returned with meaningful capital in Q2 2026 through Gigaton.
Asset Twin Platforms followed another path. They produced more than half of Q3’s deal count, although most rounds were small, then delivered Q2 2026’s largest financing through SPREAD.
What connects many of the better-funded companies is increasingly the problem being solved rather than a neat category label. Investors are backing digital twins tied to electricity networks, warehouses, industrial production, complex engineered products, construction, healthcare and other areas where better modelling can affect cost, downtime or operating decisions.
| Funding pattern | Strongest period | Example companies | What drove it |
|---|---|---|---|
| Infrastructure twins | Q1 2026 | Neara, ThinkLabs | Grid and critical-infrastructure planning |
| Process twins | Q4 2025 | Dexory, etalytics | Operational efficiency and automation |
| Product / asset twins | Q3 2025, Q2 2026 | Makersite, SPREAD | Engineering and lifecycle data |
| Building twins | Q3 2025 | PassiveLogic | Building control and physical AI |
| Healthcare twins | Q3 2025 | Twin Health, Teton.ai | Patient monitoring and personalized care |
| Factory twins | Q2-Q4 2025 | RIIICO, Parallax Worlds | Factory redesign and robotics |
| Overall picture | Five-quarter period | Multiple categories | Rotation rather than one durable winner |

In our research about digital twins, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are industrial product and process twins becoming the clearest digital twin scale-up story?
Industrial product and process twins are producing some of the market’s most convincing scale-up rounds today, especially when the software connects directly to expensive engineering or operational decisions.
Makersite’s roughly $70 million Series B is one example. Its platform brings together product, supply-chain, cost, compliance and environmental information for manufacturers.
Dexory tackles another high-cost workflow: warehouse operations. Its live operational model is continuously refreshed by autonomous scanning robots, giving customers a real-time view of inventory and warehouse activity.
SPREAD moves further upstream into complex product engineering. Its $30 million Series B is being used to expand Product Twins across vehicles, aerospace and defense, and heavy machinery. Salesforce also joined the round as SPREAD connects engineering data with customer and service workflows.
Gigaton adds an industrial-control angle. According to UCL Ventures, its technology was already being used by major cement producers when it raised $26 million, with reported annual savings of $1–3 million per plant.
That kind of measurable operational value is a big part of the appeal. Digital twins are easier to underwrite when the buyer can connect the software to energy costs, inventory accuracy, engineering speed or plant performance.
Is digital twin funding getting concentrated around fewer winners?
Yes. Digital twin funding has become highly concentrated around a small number of companies, and the pattern now shows up even in quarters without a traditional $100 million megaround.
Q3 was the obvious case, with its three giant financings. Q4 improved underneath the surface, although Dexory still represented almost half of the quarter’s capital. Neara then accounted for 46% of Q1 2026.
Q2 is even more revealing because no company raised more than $30 million. SPREAD and Gigaton together contributed roughly 89% of quarterly funding, and the top three deals represented almost 96%.
Geography moves around for the same reason. Europe generated most of the deals in several quarters, but North America took 56% of Q3 capital because of PassiveLogic and Twin Health. Asia-Pacific briefly reached 47% in Q1 2026 largely because Neara is Australian. Europe then captured 98% of Q2 capital as SPREAD and Gigaton raised their rounds.
A fresh development after our five-quarter measurement window points in the same direction. Buildots announced another $130 million funding round in September 2026. We keep that financing outside all of the quarterly calculations in this article, but it is useful current context: very large checks are still available to digital-twin companies with proven commercial traction.

Learning from others' mistakes is the cheapest lesson there is. In our market report about digital twins, we look at what broke startups before you, so you don't repeat it.
Is Europe actually becoming the center of digital twin funding?
Europe currently has the broadest digital twin funding footprint in our period, but the region does not consistently control the largest share of capital.
Europe produced seven of nine deals in Q2 2025, six of 11 in Q3, seven of 11 in Q4 and four of five in Q2 2026. That consistency is hard to miss.
The companies also span very different applications. Makersite and SPREAD are German industrial platforms. Dexory and Gigaton are based in the UK. Teton.ai is Danish. Tibo Energy is Dutch. RIIICO is German. Sensat is British. This is a fairly broad European company base rather than one local cluster driving all the activity.
Capital leadership is less stable. North America moved ahead in Q3 because two American companies raised very large rounds. Asia-Pacific briefly came close to half of Q1 2026 funding because of one Australian company.
Europe looks strongest when we ask where the steady flow of funded companies is coming from. The answer is much less clear when we ask which region attracts the most dollars in any single quarter.
Why are corporate investors showing up more often in digital twin rounds?
Corporate investors are becoming much more visible in digital twin funding, and the strongest recent rounds often pair venture money with companies that can provide industry access, technology or customers.
Strategic investors appeared in 27% of deals in Q4 2025, then 50% in Q1 2026 and 60% in Q2. The sample is small, so we would not call this permanent yet, but the direction across the latest two transitions is hard to ignore.
ThinkLabs is the cleanest example. Energy Impact Partners led its $28 million round while NVentures, Edison International and GE Vernova also participated. Those investors bring computing, utility and grid-technology exposure to a company selling AI-based grid modelling.
Other deals follow the same logic. ABB invested in Enline. National Grid Partners backed Sensat. Lockheed Martin Ventures joined Antaris’ Series A. Salesforce invested in SPREAD while also working with the company on connecting product and customer data. Earlier in the period, Hitachi Ventures and WEPA Ventures backed Tibo Energy, while Volvo Cars Tech Fund invested in RIIICO.
Traditional lead investors remain quite fragmented. Plural is the only lead we found recurring clearly across different quarters, first with Teton.ai and later with Gigaton. That makes the growth of strategic participation more interesting than any supposed consolidation among the VC leads themselves.
| Quarter | Deals with strategic investors | Share of deals | Median strategic-backed round | Examples |
|---|---|---|---|---|
| Q2 2025 | 4 | 44% | $7.8M | Tibo Energy, RIIICO |
| Q3 2025 | 3 | 27% | $70.2M | Makersite, PassiveLogic |
| Q4 2025 | 3 | 27% | $4.7M | etalytics, Parallax Worlds |
| Q1 2026 | 4 | 50% | $17.5M | ThinkLabs, Enline, Antaris |
| Q2 2026 | 3 | 60% | $26.0M | SPREAD, Sensat, Gigaton |
| Change since Q4 | - | +33 pts | $4.7M → $26.0M | Broader corporate involvement |
| Current read | - | Highest share in period | - | Emerging, not yet fully established |

If you build or invest in the digital twin market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
What is the digital twin funding trend actually telling us?
Digital twin funding has become a smaller and more selective market in the latest completed quarter we tracked, while investors still show plenty of willingness to fund companies that have reached real commercial scale.
Q3 2025 was the most misleading quarter at first glance. The record capital total mostly reflected three huge raises sitting above a weak middle. Q4 was healthier because medium-sized financings returned and the median round reached its five-quarter high.
The slowdown after Q4 looks more substantial. Deal count fell in consecutive quarters, the middle of the round-size distribution thinned out again, and first-time financings remained rare. The latest quarter had only five deals.
Investors have not stopped caring about digital twins. SPREAD and Gigaton raised meaningful rounds in Q2, and Buildots’ post-period financing shows that established companies can still attract nine-figure capital.
The category story is still fluid. Grid twins had a strong Q1, industrial process and product twins have produced several large scale-up rounds, and building, healthcare and warehouse applications have also attracted serious money. None has stayed on top long enough to make the rest of the market look secondary.
Corporate capital is the development we would watch most closely from here. Strategic participation has risen just as the overall number of deals has fallen, which suggests large industry players may be becoming more important in choosing which digital-twin platforms get the resources to scale.
Our methodology
This analysis tracks private-company digital twin fundraising from April 1, 2025 through June 30, 2026, covering five complete quarters from Q2 2025 to Q2 2026. The goal is to measure how deal activity, capital, round size, company maturity, category mix, geography and investor participation changed over that period rather than reproduce the output of a single funding database.
We researched company and investor announcements, regulatory and government records where relevant, established funding databases, and reputable financial and industry reporting. When several credible sources were available, we cross-checked material facts such as financing date, equity amount, stage, investors and use of proceeds.
We included qualifying private-company equity financings announced during the period and meeting our minimum deal-size rule. Debt, grants, loans, public offerings and financing instruments whose equity component could not be isolated were excluded from the equity totals. For mixed financing packages, we used only the identifiable equity component; Dexory’s $165 million package, for example, is recorded as $100 million of Series C equity.
Digital twins also had to be central to the company’s product or to the financed business at the time of the round. Clear classification mismatches were removed, while borderline cases were reviewed individually. Each distinct financing was counted once, duplicate reports were consolidated, and extensions or additional closes were assessed case by case.
We did not infer a funding stage from round size, assume an investor was the lead because its name appeared prominently, or assign an exact amount when the company disclosed only a vague figure. Financing status was reconstructed from publicly identifiable prior funding activity, and company age was based on the best-supported public founding date we could establish.
After compiling the dataset, we ran a separate quality-control pass focused on missed financings, date boundaries, duplicate rounds, equity eligibility, market fit and unusually structured deals. Post-period developments are excluded from the quarterly statistics and used only as current context.
Key sources include Makersite’s €60M Series B announcement, PassiveLogic’s $74M Series C announcement, Twin Health’s $53M investment announcement, Dexory’s financing announcement, Neara’s A$90M Series D announcement, ThinkLabs’ $28M Series A announcement, SPREAD AI’s $30M Series B announcement, UCL Ventures on Gigaton’s $26M Series A, and Buildots’ post-period $130M financing.

In our report covering the digital twin market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us