Is PhysicsX really worth $2.4B?
Building a startup or looking for your next investment in digital twin? Our report gives you the full picture.
Summary
PhysicsX is plausibly worth $2.4 billion as a high-growth industrial AI investment, but its valuation is well ahead of what the company's current financial performance can support.
The $2.4 billion figure comes from a real financing transaction. PhysicsX raised $300 million in June 2026, more than doubling its valuation from approximately $1 billion seven months earlier. Investors including Temasek, Siemens, NVIDIA, and Applied Materials are backing its ambition to change how industrial products are designed and manufactured. Who is backing physics AI and digital twin startups, and what they now avoid, is mapped in our digital twin market report.
The financial premium is substantial. With management expecting approximately $50 million in annual revenue, PhysicsX is valued at roughly 48 times sales. It would need to reach $200 million to $300 million in revenue for that multiple to fall into a more defensible 8-to-12-times range.
Commercial demand appears stronger than the current revenue figure suggests. PhysicsX reported doubling recognized revenue, tripling booked revenue, and more than doubling its customer count in one year. Bloomberg also identified roughly six months of customer demand that the company lacked the capacity to serve immediately.
That backlog exposes an unusual problem: PhysicsX may be constrained more by its ability to deploy technology than by its ability to find customers. Hiring more engineers can unlock sales, but the real financial upside depends on making each new deployment less labor-intensive than the last.
The technology has demonstrated practical advantages. PhysicsX has reported engineering predictions more than 100 times faster in specific applications, while its pre-trained automotive aerodynamics model requires approximately 80% less simulation data when adapting to new designs. Those gains are meaningful, although they have not been demonstrated across every industrial domain.
Semiconductor manufacturing could become the company's largest market. Its relationship with Applied Materials and growing work in complex industrial equipment give PhysicsX exposure to engineering problems where small improvements can be extremely valuable. The financial contribution from that segment remains undisclosed.
PhysicsX benefits from partnerships with established engineering software and computing companies, but those relationships create competitive risks. Siemens and NVIDIA can help distribute its technology while also developing tools that overlap with what PhysicsX sells. Neural Concept is another serious competitor, with more than 50 corporate customers and strong enterprise revenue growth.
The largest uncertainty is whether PhysicsX can become a scalable software platform rather than a business heavily dependent on specialist engineering services. Its nearly 400 employees and approximately $50 million revenue outlook imply a rough $125,000 in revenue per employee, while gross margins, recurring revenue, and customer retention remain undisclosed.
Our assessment is that PhysicsX has real technology, real industrial customers, and a credible path toward becoming a major engineering software company. But $2.4 billion already prices in years of rapid growth, repeatable deployments, and attractive software margins. The opportunity is substantial; the financial proof is still catching up.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

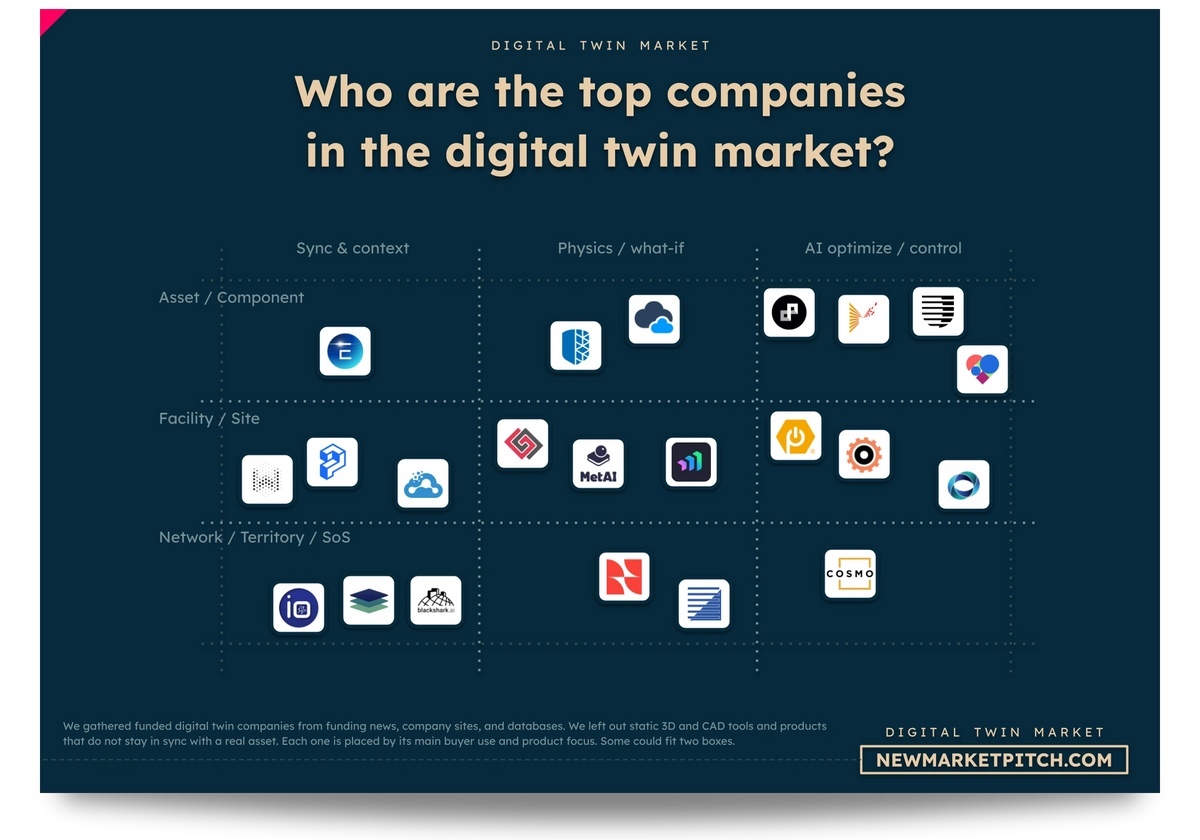
In our report covering the digital twin market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why did PhysicsX suddenly become a $2.4 billion company?
PhysicsX reached a $2.4 billion valuation because investors are betting heavily on AI-powered industrial engineering, and the company has started showing the commercial growth needed to support that ambition.
On June 8, 2026, the London-based startup announced a $300 million Series C led by Temasek, more than doubling its valuation from approximately $1 billion in November 2025. The financing followed a $135 million Series B in June 2025 and a subsequent $20 million extension involving NVIDIA's venture arm.
The investors are unusually well connected to the industries PhysicsX wants to serve. They include Siemens, Applied Materials, NVIDIA, Atomico, and General Catalyst, bringing together semiconductor equipment, industrial software, computing infrastructure, and venture capital.
There is also measurable growth behind the excitement. PhysicsX reported doubling recognized revenue, tripling booked revenue, and more than doubling its customer count over the preceding year.
According to Bloomberg's June 2026 reporting, CEO Jacomo Corbo expected approximately $50 million in annual revenue, with ambitions to more than double that figure in 2027. At $2.4 billion, investors are paying around 48 times expected annual sales. That is an enormous premium for an industrial software startup, even one growing this quickly.
Is PhysicsX's $2.4 billion valuation a real market price?
PhysicsX's $2.4 billion valuation is a genuine financing price agreed with investors, although it does not tell us exactly what the entire company would fetch in an acquisition.
The figure comes from the completed $300 million Series C, confirmed by PhysicsX, its legal adviser Cooley, Bloomberg, and the Financial Times. S&P Capital IQ identifies the transaction as a preferred-share financing at a $2.4 billion post-money valuation.
That implies approximately $2.1 billion before the new investment. On a simplified basis, the $300 million represented 12.5% of the company's post-financing equity.
Preferred shares may carry protections unavailable to ordinary shareholders, while private-company valuations depend on the terms of a specific transaction. There is also no publicly traded PhysicsX stock price against which to test the figure every day.
Investors were prepared to finance PhysicsX at approximately $2.4 billion. Whether another buyer would pay that amount for the whole business remains untested.
What does PhysicsX actually sell to industrial companies?
PhysicsX sells AI software that helps engineers design and improve complex physical products without spending hours or days running every simulation from scratch.
Traditional engineering software uses mathematical models to simulate how air, heat, forces, or materials behave. Those calculations can require hundreds of processors and considerable computing time, particularly when engineers want to test thousands of possible designs. Faster stand-ins for heavy simulation are one of the technologies we track in our report on digital twins.
PhysicsX trains AI models on simulation data so they can predict relevant physical behavior much faster. Automotive engineers can evaluate airflow and brake cooling, aerospace manufacturers can identify casting defects, and semiconductor-equipment companies can improve complicated thermal and mechanical designs.
The company wants its software to cover more than individual simulations. Its platform brings together reusable physics models, engineering optimization tools, and software for deploying these models inside industrial organizations.
This opens up several ways to make money: accelerating existing engineering work, helping customers find better designs, improving manufacturing processes, and eventually supporting operational decisions through digital twins.
The commercial attraction is easy to understand. If a manufacturer can examine hundreds of design alternatives in the time previously needed for a handful, even a small improvement in the final product could be worth far more than the software subscription.

Our research about digital twins gets updated several times a month, so you always get the latest view of where things stand.
Is PhysicsX growing fast enough to justify its valuation?
PhysicsX is growing remarkably fast for an industrial engineering software company, with its disclosed bookings increasing even faster than recognized revenue.
Its June 2025 financing announcement said revenue had more than quadrupled over the previous two years. One year later, PhysicsX reported that recognized revenue had doubled, booked revenue had tripled, and its customer count had more than doubled.
Bookings measure contractual commitments, while recognized revenue reflects sales recorded under accounting rules. Faster bookings growth suggests that new business is arriving ahead of its full contribution to reported sales.
However, the company has not disclosed how much of those bookings consists of recurring subscriptions, long-term contracts, or project-based work.
Bloomberg also reported that PhysicsX had approximately six months of customer demand it could not immediately serve because of limited delivery capacity. That supports management's account of strong demand, although the precise financial value of the backlog was not disclosed.
Customer demand appears to be running ahead of the company's ability to deliver. That's a good problem to have for now. The tougher challenge will be converting that demand into revenue without needing to expand the workforce at the same pace.
Is PhysicsX already making enough money for a $2.4 billion valuation?
PhysicsX currently makes far too little revenue to justify $2.4 billion using ordinary industrial software multiples. Its valuation assumes that sales will multiply several times over.
Based on management's approximately $50 million annual revenue outlook, the company is valued at about 48 times sales.
For perspective, Ansys generated $2.545 billion in revenue in 2024, according to its audited financial statements. PhysicsX's anticipated sales represent roughly 2% of that amount. Ansys was a mature, profitable engineering software business, so the comparison is imperfect, but it illustrates just how early PhysicsX remains.
We can calculate the revenue PhysicsX would need to achieve different valuation multiples while keeping its equity value unchanged.
| Annual revenue | Valuation / sales | Growth from $50M |
|---|---|---|
| $50M | 48× | Current reference |
| $75M | 32× | 1.5× |
| $100M | 24× | 2.0× |
| $150M | 16× | 3.0× |
| $200M | 12× | 4.0× |
| $240M | 10× | 4.8× |
| $300M | 8× | 6.0× |
| $400M | 6× | 8.0× |
Does PhysicsX have real customers or mainly big-name partnerships?
PhysicsX already works with major industrial companies on real engineering problems, although we still cannot tell how much revenue those relationships generate.
Bloomberg identified Applied Materials, Siemens, and Stellantis among its customers in June 2026. Earlier Financial Times reporting also highlighted relationships involving Rio Tinto and Leonardo. Who actually buys physics AI, and which engineering problems they would pay to solve, is what we study in our market report about digital twins.
The Siemens relationship is especially revealing because it has developed over several stages. The companies began collaborating on AI-powered physics simulation in December 2024, expanded their work around the Simcenter X engineering environment in July 2025, and announced another project involving data-center electrical infrastructure in March 2026.
PhysicsX has also published examples involving aerospace casting and automotive brake cooling, including applications integrated into manufacturing workflows.
More recently, its work with Britain's GB1 America's Cup team has progressed from conventional design optimization toward generating and evaluating new yacht-hull geometries with AI. At NVIDIA GTC Berlin in October 2026, the partners reported five times fewer high-fidelity RANS simulations, 100 times faster evaluations, and a hundredfold accuracy improvement relative to GB1's previous panel-method simulation. These are results reported by the partners, with the accuracy comparison referring to the earlier method rather than to every available high-fidelity solver.
PhysicsX has not disclosed individual customer contract values, renewal rates, or how broadly its software is used inside each organization. The customer names are impressive. The revenue behind them is still harder to judge.

In our market report about digital twins, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is PhysicsX's AI actually better than traditional engineering simulation?
PhysicsX has demonstrated major speed improvements over conventional simulation workflows, especially when engineers need to evaluate large numbers of designs.
In a September 2025 aerospace casting case study, the company reported that its machine-learning approach could predict relevant outcomes more than 100 times faster than previous methods. The application helped manufacturing teams identify potential casting defects and adjust conditions before problems became irreversible.
In automotive engineering, PhysicsX has described full-vehicle computational fluid dynamics simulations requiring more than 20 hours and hundreds of CPU cores. AI models can make repeated design exploration much faster once they have been trained.
The advantage becomes substantial when an engineering team needs thousands of evaluations. A model that predicts results in seconds can fundamentally change how many alternatives engineers consider before settling on a design.
There are limitations. AI models must be validated against accurate simulations or physical experiments, and their predictions can become less reliable when engineers move far beyond the designs represented in training data.
PhysicsX's strongest demonstrated capability today is speeding up engineering exploration within tested applications. That already has commercial value without requiring the company to replace every traditional simulation tool.
Are PhysicsX's Large Physics Models really a technological breakthrough?
PhysicsX's Large Physics Models are technically impressive, particularly because they can adapt to new engineering designs using substantially less training data.
In August 2026, PhysicsX introduced PX-Car-Aero-v1, a pre-trained automotive aerodynamics model built using 33,203 simulated designs derived from 444 baseline vehicles.
The model predicts aerodynamic forces and flow fields without requiring a full computational fluid dynamics mesh during inference. More importantly, PhysicsX found that adapting the pre-trained model to previously unseen automotive designs required approximately 80% less simulation data than training a comparable model from scratch to reach similar performance.
The published experiments included changes in vehicle geometry and simulation configurations. The company also reported that the advantage increased as the design space became broader.
Generating high-quality physics simulations is expensive. If a company can reuse a pre-trained model rather than generate a completely new training dataset for each application, the economics of deploying industrial AI improve considerably.
Strong performance in automotive aerodynamics does not establish that the same model can handle semiconductor manufacturing, turbine mechanics, or metal casting without substantial adaptation.
Still, reducing new simulation data requirements by roughly four-fifths is a serious technical achievement. The breakthrough would become much more valuable if PhysicsX could reproduce similar savings across several engineering disciplines.

In our document detailing everything you need to know about digital twin, you will always find fresh funding data, taken straight from our own verified funding database.
Is semiconductor manufacturing becoming PhysicsX's biggest business?
Semiconductors are becoming one of PhysicsX's most important markets, and management has indicated that the sector could become its largest industrial segment.
The Financial Times reported in June 2026 that semiconductor applications were on track to take that position. Bloomberg also identified Applied Materials, a major semiconductor-equipment manufacturer and PhysicsX investor, among its customers. Which industries pull demand forward, from semiconductors to automotive, is one of the growth drivers we examine in our report covering the digital twin market.
This is a noteworthy development for a company whose early identity was closely connected to Formula 1 engineering, aerodynamics, and automotive design.
Semiconductor manufacturing equipment involves difficult thermal, mechanical, fluid, and materials problems. Improving those systems can help manufacturers increase precision, reduce defects, and raise production efficiency.
PhysicsX's technology fits those requirements, particularly where engineers need to repeatedly simulate expensive manufacturing processes.
The size of potential customer contracts could also be attractive. Semiconductor-equipment manufacturers sell highly sophisticated machines, so even small performance improvements may be commercially valuable.
What we cannot establish is how much semiconductor revenue PhysicsX already generates. The company has not published segment sales, customer contract values, or the share of engineering resources devoted to semiconductor projects.
Could PhysicsX become a major industrial engineering software platform?
PhysicsX has a credible chance of becoming an important software platform for industrial engineering, helped by its growing presence inside existing simulation and cloud environments.
Its strategy increasingly involves distributing technology through systems that large manufacturers already use.
The Siemens collaboration connects PhysicsX to established engineering workflows. Its March 2026 partnership with CoreWeave lets customers develop and deploy private physics models using high-performance cloud infrastructure. PhysicsX has also worked with Deutsche Telekom on Europe's Industrial AI Cloud and with Microsoft around engineering applications.
The company is investing in leadership capable of supporting a broader software platform. In October 2026, it appointed Dael Williamson, previously EMEA CTO at Databricks, as Chief Technology and Platform Officer. His background in scaling enterprise data and AI products is particularly relevant to the challenge of moving beyond custom engineering projects.
There is a trade-off in relying on major technology partners. Siemens already controls established engineering software products, while NVIDIA and Microsoft provide much of the infrastructure that PhysicsX and its customers need.
For now, working alongside these companies gives PhysicsX access to industrial customers and deployment environments that would be extremely expensive to build independently.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the digital twin market, we look at what broke startups before you, so you don't repeat it.
Is PhysicsX stronger than Neural Concept and other engineering AI competitors?
PhysicsX is one of the best-funded startups in engineering AI, but Neural Concept has demonstrated enough commercial growth and customer adoption to challenge its position.
In December 2025, Switzerland's Neural Concept announced a $100 million Series C led by Goldman Sachs Alternatives. It reported more than 50 corporate customers, including General Motors, GE Vernova, Leonardo, Safran, and Renault Group, alongside a fourfold increase in enterprise revenue over 18 months.
Neural Concept also introduced an AI design copilot in January 2026, moving deeper into the initial stages of engineering design. Its focus on CAD-native workflows overlaps with PhysicsX's ambition to make AI part of the broader engineering process.
PhysicsX has disclosed considerably more total funding, approximately $487 million through its Series C, and emphasizes its pre-trained physics models, industrial applications, and enterprise platform.
There are also established competitors. Siemens acquired Altair in 2025, strengthening its simulation and optimization portfolio, while Synopsys completed its acquisition of Ansys in July 2025.
These businesses have something the startups are still building: longstanding relationships with engineering departments and widely used software ecosystems.
| Company | Main competitive strength | Evidence |
|---|---|---|
| PhysicsX | Pre-trained physics models and industrial AI software | $300M Series C at $2.4B |
| Neural Concept | CAD-native AI engineering and design optimization | $100M Series C; 50+ corporate customers |
| Siemens | Engineering simulation and industrial software distribution | Simcenter platform; Altair acquisition |
| Synopsys / Ansys | Multiphysics simulation and semiconductor design software | Ansys generated $2.545B in 2024 revenue |
| Altair / Siemens | Simulation, optimization, and engineering analytics | Acquired by Siemens in 2025 |
| Monolith AI | AI-driven engineering testing and product development | Specialized in engineering test-data modeling |
| NVIDIA | Physics AI development tools and computing infrastructure | PhysicsNeMo ecosystem; PhysicsX investor |
| CoreWeave | GPU cloud infrastructure for industrial AI models | PhysicsX deployment partnership |
Could Siemens or NVIDIA eventually make PhysicsX unnecessary?
Siemens and NVIDIA could reproduce parts of PhysicsX's technology, particularly as physics AI tools become more widely available. PhysicsX will need advantages that go beyond using similar AI architectures.
Siemens already owns major simulation software assets, including Altair and its existing Simcenter products. NVIDIA provides physics AI tools through PhysicsNeMo and supports model development through its computing infrastructure. Where big incumbents end and startups begin is drawn on the market maps and grids in our digital twin market report.
PhysicsX also collaborates with NVIDIA on physics-model architectures and standards. Its own Opora framework supports modeling approaches including neural operators and graph neural networks, which are available beyond PhysicsX.
The risk is that improvements in open modeling tools make it easier for established software companies to build competing products.
PhysicsX's protection could come from industrial datasets, validated models, integration with customer workflows, and the experience gained from solving difficult engineering problems repeatedly.
Developing a fast physics model is becoming more accessible to competitors. Building software that engineers trust for expensive manufacturing decisions requires years of testing, integration, and domain expertise. PhysicsX has a head start in some of those areas, but it cannot take that advantage for granted.

In our research about digital twins, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Will PhysicsX's $300 million funding actually help it grow faster?
PhysicsX's new capital should help it address its shortage of engineers and delivery capacity, and its expansion is already visible.
Bloomberg reported approximately six months of customer demand that PhysicsX lacked the capacity to serve immediately. Meanwhile, its workforce more than doubled over the preceding year.
The expansion continued after the financing. At the opening of its Singapore hub in October 2026, Singapore's Ministry of Trade and Industry described PhysicsX as having almost 400 employees globally since its founding in 2019.
The Singapore operation already had 20 employees, with plans to exceed 100 over the next three years. PhysicsX also announced a five-year S$40 million commitment with Singapore's Agency for Science, Technology and Research (A*STAR), covering areas including advanced manufacturing, maritime engineering, and semiconductors.
That funding represents a joint research and development commitment, rather than guaranteed customer sales.
The company is also moving from a relatively concentrated European operation toward a more international business, with teams in the United States and Asia.
Hiring more engineers can increase the number of customer projects PhysicsX delivers. The harder task is ensuring that each new deployment requires less work than the previous one.
Is PhysicsX becoming a scalable software company or an expensive consulting business?
PhysicsX's biggest financial uncertainty is whether it can sell reusable software at scale or will continue needing large engineering teams for every major customer.
The company already has genuine software products, including reusable physics models and an enterprise deployment platform. However, its published customer work involves substantial engineering expertise, adaptation to specialized industrial problems, and close collaboration with customers.
Consider its aerospace casting, automotive aerodynamics, and semiconductor applications. Each involves different physical systems, manufacturing constraints, datasets, and validation requirements.
These projects can be valuable, but specialist engineering services rarely achieve the same margins as widely distributed enterprise software.
Using its approximately $50 million annual revenue outlook and the nearly 400 employees reported in October 2026 gives an indicative revenue-per-employee figure of about $125,000. The calculation mixes a forward-looking revenue estimate with a later headcount figure, so it should be treated as a rough measure of the company's current scale rather than an established productivity ratio.
The company's recent hiring of a senior Databricks executive, together with its work on pre-trained physics models, suggests that management understands the need to build more repeatable software products.
PhysicsX has not disclosed gross margins, recurring revenue, or the share of sales coming from software licenses versus customized projects. Until those figures become available, valuing the company like a mature, high-margin software platform is a stretch.

If you build or invest in the digital twin market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Is the engineering software market big enough to support PhysicsX's valuation?
The industrial engineering software market is easily large enough to support a $2.4 billion PhysicsX, although winning a meaningful share will be difficult.
Ansys generated $2.545 billion in 2024 revenue, while Siemens reported approximately €6.174 billion in software revenue within its Digital Industries segment in fiscal 2025. The Siemens figure includes products beyond engineering simulation, so it represents a broader market. How big the engineering simulation market really is, we estimate ourselves in our market report about digital twins.
Following its acquisition of Ansys, Synopsys described a combined addressable market of approximately $31 billion spanning silicon design, simulation, analysis, and related technologies.
PhysicsX is entering markets where customers already spend billions on software that helps design, test, and manufacture physical products.
Its opportunity also extends into applications that traditional engineering software handles less directly, such as AI-driven design generation and real-time manufacturing optimization.
However, access to a large market does not guarantee that manufacturers will replace existing tools or increase their software budgets. PhysicsX may need to prove that its products save considerably more money than they cost, particularly when customers can already access simulation tools from established vendors.
The market is big enough. Winning recurring software budgets from customers that already have deeply embedded engineering tools will be the real test.
How much revenue would PhysicsX need to justify $2.4 billion?
PhysicsX would need roughly $200 million to $300 million in annual revenue to make its current valuation look much more reasonable at an 8-to-12-times-sales multiple.
That represents four to six times the approximately $50 million revenue expected for 2026.
Management's ambition to more than double revenue in 2027 would be an encouraging first step. At $100 million in revenue, the same valuation would represent 24 times sales.
Sustaining that growth is considerably harder as the company gets larger. Doubling from $50 million to $100 million adds $50 million in sales. Doubling again to $200 million requires another $100 million.
We can model how quickly PhysicsX might reach a more comfortable revenue level under several growth assumptions. These are illustrative calculations, not company forecasts.
| Annual revenue growth | After 1 year | After 2 years | After 3 years |
|---|---|---|---|
| 20% | $60M | $72M | $86M |
| 30% | $65M | $85M | $110M |
| 40% | $70M | $98M | $137M |
| 50% | $75M | $113M | $169M |
| 60% | $80M | $128M | $205M |
| 75% | $88M | $153M | $268M |
| 100% | $100M | $200M | $400M |
What could cut PhysicsX's valuation in half?
PhysicsX could lose more than half its valuation if growth slows before the company proves it can deliver software at attractive margins.
The arithmetic is unforgiving at its current revenue level. If investors valued $50 million in annual sales at 20 times revenue instead of 48 times, PhysicsX would be worth approximately $1 billion. At 10 times sales, the implied value would fall to $500 million.
One potential problem is competition from established engineering software companies. Siemens and Synopsys have extensive customer relationships, existing products, and the resources to incorporate increasingly capable AI models. Incumbents adding AI to software customers already use is a risk we rate by likelihood in our digital twin market report.
Another is the cost of deploying the technology. Industrial customers need reliable simulations, customized integrations, and validation against real physical systems. If every new contract requires substantial engineering work, PhysicsX could grow revenue without achieving the margins investors expect.
Customer concentration is another unknown. The company works with several major corporations but has not disclosed how much revenue comes from its largest customers.
We should also consider industrial spending cycles. Semiconductor-equipment manufacturers, aerospace companies, and automotive suppliers can delay investment when demand weakens or capital budgets tighten.
The company's substantial financing gives it room to expand. But with investors already paying a premium for years of future growth, even a profitable and technically successful business could be worth considerably less than today's headline valuation.

In our document detailing everything you need to know about digital twin, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
What would make PhysicsX worth more than $2.4 billion?
PhysicsX could become worth significantly more if its AI models turn into a widely adopted engineering software platform generating hundreds of millions in annual revenue.
The company is already moving in that direction. Its pre-trained automotive model has demonstrated meaningful savings in simulation data, its industrial customers are using the technology for practical engineering work, and partnerships with Siemens and CoreWeave make deployment easier.
Its recent GB1 yacht-design work also points toward a broader product ambition. Rather than simply predicting how an existing design performs, PhysicsX is developing systems that generate new designs, evaluate them, and use the results to guide further improvements.
That would allow the company to participate earlier in engineering decisions, where product performance and cost are often determined.
If PhysicsX eventually reaches $300 million in annual revenue and commands a 12-times-sales multiple, the implied valuation would be $3.6 billion. At $500 million in revenue and the same multiple, it would reach $6 billion.
Those outcomes require more than technological progress. PhysicsX would need repeatable deployments, strong customer retention, attractive gross margins, and growth that outpaces the cost of adding engineering staff.
For now, the valuation already reflects part of that potential. Investors will eventually need evidence that the financial model is catching up with the engineering ambition.
So, is PhysicsX really worth $2.4 billion today?
PhysicsX's $2.4 billion valuation is defensible as an ambitious venture capital investment, but it is ahead of what the company's current financial performance can justify.
There is strong evidence that PhysicsX is building something valuable. Its customer base has expanded rapidly, booked revenue is growing faster than recognized revenue, and its engineering AI has demonstrated meaningful performance gains in demanding industrial applications.
The company also has competitive advantages developing around its technology, customer relationships, and industrial expertise. Investors such as Siemens, NVIDIA, Applied Materials, and Temasek add credibility to its ambitions.
Still, the financial expectations are substantial. With approximately $50 million in anticipated annual revenue, investors are effectively paying 48 times sales. PhysicsX would need to reach something closer to $200 million to $300 million in revenue, while demonstrating healthy software margins, for the valuation to look considerably less aggressive.
Our conclusion is that PhysicsX is a credible industrial AI leader with a real opportunity to become a multibillion-dollar software business. The $2.4 billion price may eventually prove reasonable, but today it includes a large premium for growth and profitability that PhysicsX has yet to demonstrate.
Our methodology
This analysis examines whether PhysicsX's $2.4 billion valuation is supported by its commercial performance, technology, competitive position, and potential to become a scalable industrial software company. We assessed the June 2026 financing alongside reported revenue expectations, customer growth, bookings, technical research, industrial deployments, and the financial scale of established engineering software businesses.
We treat the $2.4 billion figure as a post-money private financing valuation, rather than a continuously observable market capitalization. The $300 million Series C implies approximately $2.1 billion in pre-money value and a simplified 12.5% post-financing ownership stake for the new capital. These calculations do not account for possible preferred-share protections or other contractual terms.
For financial comparisons, we used management's approximately $50 million annual revenue expectation as the reference point, rather than treating it as audited historical revenue. The 48-times-sales multiple, revenue thresholds, and growth scenarios are arithmetic illustrations based on that figure. The 8-to-12-times-sales range is an analytical benchmark, not an independently established fair-value multiple for PhysicsX. We also distinguished recognized revenue from bookings and customer demand, since they represent different levels of commercial certainty.
To assess the technology, we examined PhysicsX's original research on pre-trained physics models, published industrial case studies, and reported engineering performance improvements. We considered the specific conditions behind speed and accuracy comparisons, including the reference methods and training requirements, rather than assuming the results apply to every industrial application. Customer relationships and partnerships were assessed separately from disclosed revenue, which remains limited.
The competitive analysis compared PhysicsX with Neural Concept, Siemens, Synopsys, Ansys, and other companies active in engineering simulation and industrial AI. We also examined workforce expansion and deployment requirements to assess the risk that PhysicsX's growth could remain dependent on specialist engineering services. Where gross margins, recurring revenue, renewal rates, or contract values are not publicly disclosed, we did not assign precise estimates.
Key sources for financing and commercial performance include PhysicsX's $300 million Series C announcement, its earlier Series B announcement, Bloomberg's reporting published by The Business Times, and the Financial Times on PhysicsX's financing and industrial strategy.
Technical and deployment sources include PhysicsX's PX-Car-Aero-v1 research, its aerospace casting case study, its GB1 America's Cup engineering results, Siemens' original collaboration announcement, the Simcenter X integration, the data-center infrastructure project, and the CoreWeave deployment partnership.
For international expansion and competitive context, we used PhysicsX's Singapore hub announcement, Neural Concept's Series C disclosure, Ansys' 2024 financial results, Synopsys' announcement of its Ansys acquisition, and Siemens' 2025 annual report.

In our report covering the digital twin market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us