How's Duolingo doing these days?
Everything we know about the EdTech market, in one place. Get our report whether you build or invest.
Summary
Duolingo is doing well these days, but its business is slowing down much faster than its audience. The company remains profitable, continues attracting millions of learners, and is improving its product with AI. Its biggest problem is turning that growing popularity into stronger revenue and earnings growth.
Duolingo reached 58.7 million daily active users in the second quarter of 2026, up 23% year over year. That's 11 million additional daily learners in twelve months, even as paid subscriber growth slowed to 17%.
The most encouraging development is how frequently people return. Duolingo's daily-to-monthly active user ratio rose from 37.2% to 41.7%, while next-day retention among existing users reached a record 84%. Its audience is becoming more engaged, although a major streak-recovery campaign helped reactivate millions of learners.
The financial slowdown is much sharper. Quarterly revenue increased 18%, but bookings grew just 8%. Duolingo expects annual bookings growth to fall from 33% in 2025 to roughly 11% in 2026, suggesting that its expanding audience is generating substantially less additional commercial activity. How a free audience turns into revenue, and which models keep their margins as growth slows, is what we compare in our edtech market report.
Much of that slowdown is deliberate. Management decided it had pushed monetization too aggressively and began making more learning features available for free. Duolingo estimates that maintaining its previous strategy could have produced more than $50 million in additional potential bookings this year.
The company can afford the experiment. Duolingo generated $33.2 million in quarterly net income, held approximately $1.3 billion in cash and short-term investments, and expects around $320 million in adjusted EBITDA for 2026. But that would represent only 4.6% annual EBITDA growth despite a 16.3% increase in revenue.
AI is delivering clearer results in content production than in monetization. Duolingo produced approximately 20,500 course units in the first quarter of 2026, compared with a quarterly average of 1,800 in 2024. Conversational tools are also improving, although their impact on real-world language proficiency remains harder to establish.
ChatGPT and other AI tutors create a genuine threat to Duolingo's premium pricing. Grammar explanations and conversational practice are increasingly easy to obtain elsewhere. Duolingo's stronger competitive advantage is its ability to organize learning, maintain motivation, and bring tens of millions of people back every day.
Expansion into mathematics, music, chess, and English proficiency testing creates additional opportunities, but none has yet demonstrated the commercial importance of Duolingo's language subscriptions. The Duolingo English Test, for example, generated only 3.4% of quarterly revenue despite acceptance by more than 6,500 academic programs.
Our assessment is that Duolingo remains one of the strongest consumer education platforms, but its strategic bet is still unproven. If stronger engagement eventually restores bookings and subscriber growth, the company could emerge with a larger and more durable business. Until then, its product momentum is more impressive than its financial momentum.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

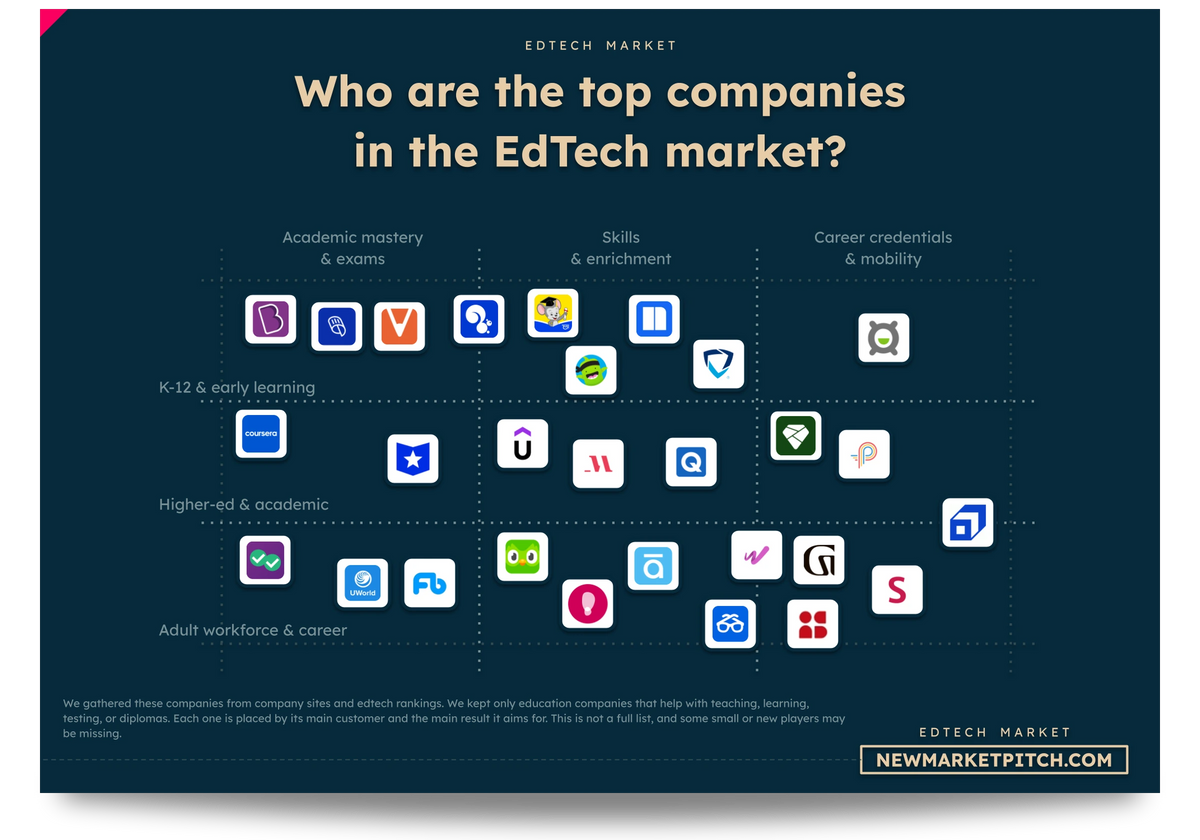
In our report covering the edtech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is Duolingo still doing well, or is the company slowing down?
Duolingo is still growing quickly as a learning platform, but its financial growth has slowed dramatically. The company keeps attracting millions of learners while earning significantly less additional revenue from each wave of new users.
In its latest quarterly results, Duolingo reported 58.7 million daily active users, up 23% year over year, and $298.5 million in revenue, up 18%. Yet bookings, which measure new subscription sales and other commercial activity more directly, increased just 8%.
That is a sharp change from 2025, when annual revenue grew 39% and bookings increased 33%. The slowdown has been partly deliberate. Duolingo decided to make more learning features available for free, improve retention and invest more heavily in AI-powered education, even at the expense of subscription sales.
Management believes this approach will eventually produce a larger and more profitable business. The early user numbers support that argument, but the financial results have yet to catch up.
Duolingo is therefore in an unusual position: its product is becoming more popular while the business is growing much less quickly than investors became accustomed to. The company is financially healthy, but its new strategy still has something important to prove.
Why did Duolingo change its strategy?
Duolingo changed its strategy because management believed it had pushed monetization too far, potentially making the free learning experience less attractive.
The decision followed a noticeable slowdown in daily user growth. Duolingo finished 2024 with 40.5 million daily active users, up 51% year over year. By the end of 2025, growth had fallen to 30%, even though its audience continued expanding.
In February 2026, CEO Luis von Ahn explained that some monetization changes had probably contributed to weaker engagement. Duolingo responded by shifting employees away from subscription optimization and toward improving the product, attracting new learners and increasing the amount of useful content available without paying.
Management also put a price on that decision. It estimated that the company could potentially have achieved bookings growth approaching 20% in 2026 by sticking with its previous approach. Instead, Duolingo targeted around 11%, accepting more than $50 million in forgone potential bookings.
That's an unusually large sacrifice for a consumer subscription company. Duolingo is betting that giving users more value today will create substantially more paying customers later.
The strategy also reflects a change in the competitive environment. As AI makes language explanations, translation and conversational practice cheaper and easier to access, charging separately for individual features becomes a harder proposition.

Our research about education technology gets updated several times a month, so you always get the latest view of where things stand.
Is Duolingo still gaining millions of users?
Duolingo is still adding users at an impressive rate, although its days of 40% to 50% annual audience growth appear to be over for now.
Daily active users increased from 47.7 million in the second quarter of 2025 to 58.7 million one year later. That's 11 million additional daily learners, or roughly 900,000 per month on average.
The latest figures also show a small but encouraging improvement. Daily active user growth accelerated from 21% in the first quarter of 2026 to 23% in the second quarter. It was one of the first indications that Duolingo's renewed focus on the free experience might be helping. A small pickup in daily user growth is the type of signal we log each quarter in our report on edtech.
However, the company benefited from a one-time Streak Revival campaign in June. Users could recover their longest lost streak by completing three lessons, and 15.4 million people participated. Nearly eight million of them had no active streak when the campaign began.
That makes it difficult to separate lasting improvements from temporary reactivation. Duolingo itself attributed the acceleration to product changes, marketing and the campaign rather than claiming that better teaching alone explained everything.
The scale of the opportunity remains enormous. Duolingo has publicly discussed reaching 100 million daily active users by 2028. Starting from 58.7 million, that would require approximately 23% to 24% compound annual growth over the following two and a half years, close to its latest reported pace.
The target is achievable, but Duolingo would need to maintain its current growth rate while adding more than 40 million additional daily users.
| Period | Daily active users | Annual growth |
|---|---|---|
| Q4 2024 | 40.5M | 51% |
| Q1 2025 | 46.6M | - |
| Q2 2025 | 47.7M | - |
| Q4 2025 | 52.7M | 30% |
| Q1 2026 | 56.5M | 21% |
| Q2 2026 | 58.7M | 23% |
| Latest annual increase | +11.0M | +23% |
Are Duolingo users actually learning more often?
Duolingo users are returning more frequently than before. The improvement is substantial enough to suggest that the app is becoming more habit-forming, although more frequent use doesn't automatically mean better learning outcomes.
In the second quarter of 2026, daily active users increased 23%, while monthly active users grew only 10%, from 128.3 million to 140.6 million.
We calculated the daily-to-monthly active user ratio using these figures. It increased from approximately 37.2% to 41.7% in one year. In other words, a much larger share of Duolingo's monthly audience is now using the app on an average day.
The company's retention data tell a similar story. According to its August 2026 shareholder letter, Duolingo's current-user next-day retention rate reached a record 84%, approximately one percentage point higher than the previous year. This metric measures whether users who have already been active during the preceding week return the following day.
A one-point retention improvement might sound small, but it affects a huge audience and can accumulate as more learners maintain their habits.
Duolingo also continues experimenting with its Green Machine system, which tests hundreds of product changes to improve learning outcomes, retention and monetization.
The real question is how much of this engagement lasts. The recent streak-recovery campaign temporarily encouraged millions of people to return, making subsequent quarters particularly important for judging whether Duolingo has genuinely improved its users' habits.
Still, the increase in daily engagement relative to monthly reach is one of the clearest positive developments in Duolingo's recent performance.

In our market report about education technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
Why is Duolingo making less money from its growing audience?
Duolingo's monetization has weakened because the company is deliberately making the free product more generous, while older subscription sales temporarily make reported revenue growth look stronger than current sales activity.
The clearest evidence is the gap between revenue and bookings.
In the second quarter of 2026, Duolingo's revenue increased 18% to $298.5 million. Total bookings grew only 8% to $289.1 million, while subscription bookings increased 10%.
Most Duolingo subscriptions run for twelve months. The company recognizes that revenue gradually throughout the subscription period, which means current revenue includes money from subscriptions purchased in earlier quarters.
Bookings therefore give us a better picture of how quickly new commercial activity is growing.
The latest comparison was also unusually difficult. In the second quarter of 2025, Duolingo benefited from a price increase, the initial rollout of its Energy system and particularly strong advertising performance. Those factors raised the baseline against which 2026 was measured.
But the broader slowdown extends beyond one difficult comparison. Full-year bookings growth is expected to fall from 33% in 2025 to roughly 11% in 2026.
There is also an interesting difference between subscription and advertising revenue. In the latest quarter, subscription revenue increased 22%, while advertising revenue grew just 2%, despite the larger audience.
Duolingo currently generates most of its money from subscribers, and its growing free audience has yet to become a much stronger advertising business. Subscriptions carrying the business while ads lag is a revenue-model question; we break down which edtech models make money in our edtech market report.
Is Duolingo struggling to turn free users into paying subscribers?
Duolingo is still attracting paying subscribers, but the pace has slowed enough to raise questions about how much more money its expanding audience can generate.
The company finished the second quarter of 2026 with 12.7 million paid subscribers, compared with 10.9 million a year earlier. That represents 1.8 million additional paying customers and 17% annual growth.
For a consumer education app, adding that many subscribers is a serious achievement. However, subscriber growth was 28% at the end of 2025 and 21% in the first quarter of 2026.
The trend has therefore weakened across three consecutive reporting periods, even as overall daily user growth recently improved.
Duolingo is experimenting with longer free trials and reducing some restrictions on AI-powered features. Most new Super Duolingo subscribers now have access to Video Call, a feature previously associated with the more expensive Max tier. Management also intends to expand access to existing Super subscribers.
These changes may improve retention and encourage more users to pay eventually. They also make the distinction between free, Super and Max subscriptions less straightforward.
Unfortunately, Duolingo does not disclose enough information about subscriber conversion by cohort, tier-specific retention or average revenue per paying customer to determine exactly how successful these experiments have been.
What we can establish is that Duolingo's audience is currently growing faster than its subscriber base. The company needs to reverse that gap eventually if it wants subscription growth to accelerate again.

In our document detailing everything you need to know about edtech, you will always find fresh funding data, taken straight from our own verified funding database.
Is Duolingo still profitable?
Duolingo remains highly profitable, but its latest quarterly results show that the company is spending more of its revenue on growth than it did a year ago.
In the second quarter of 2026, Duolingo generated $33.2 million in net income and $77.3 million in adjusted EBITDA, a measure of operating profitability before certain expenses.
Its adjusted EBITDA margin fell from 31.2% to 25.9% year over year. Free cash flow also declined, from $86.3 million to $78.6 million.
That's especially interesting because quarterly revenue increased by approximately $46 million over the same period. Duolingo earned more revenue but generated slightly less adjusted operating profit and cash.
Management attributes much of this change to its decision to invest in user growth and product improvements. AI infrastructure costs also matter, although Duolingo reported better-than-expected gross margins as AI-related efficiencies improved.
The company's full-year outlook remains healthy. Duolingo expects approximately $320 million in adjusted EBITDA on $1.207 billion in revenue, representing a 26.5% margin.
Its balance sheet is another advantage. Duolingo reported approximately $1.3 billion in cash and short-term investments at the end of the second quarter. It also authorized a $400 million share repurchase program earlier in the year and had repurchased approximately $71.9 million of shares by August 1.
That gives the company considerable room to experiment without needing outside financing.
The financial concern today is mainly how quickly profits will resume growing, rather than whether Duolingo can remain profitable.
How much has Duolingo's financial growth really slowed?
Duolingo's financial growth has slowed dramatically, with revenue, bookings and profit now growing at a fraction of their previous rates.
The company's annual revenue increased from approximately $748 million in 2024 to $1.038 billion in 2025, a gain of 39%. Its latest 2026 guidance calls for $1.207 billion, which would represent growth of only 16.3%.
Bookings show an even steeper decline. After increasing 33% in 2025, they are expected to grow just 10.9% in 2026.
The gap becomes more striking when we examine profitability.
Duolingo reported $305.9 million in adjusted EBITDA in 2025. Management expects approximately $320 million in 2026, an increase of just $14.1 million despite roughly $169 million in additional revenue.
That means less than 9% of the expected incremental revenue would translate into incremental adjusted EBITDA.
The company has deliberately accepted that weaker conversion because it believes investing in the learning experience will create more value over time.
But there's no guarantee that it will. Duolingo has demonstrated that it can grow an audience while generating substantial profits. What remains unclear is whether its new strategy can restore strong earnings growth.
| Financial indicator | 2025 actual | 2026 outlook | Change |
|---|---|---|---|
| Revenue | $1,037.6M | $1,207M | +16.3% |
| Total bookings | $1,158.4M | $1,285M | +10.9% |
| Adjusted EBITDA | $305.9M | $320M | +4.6% |
| Adjusted EBITDA margin | 29.5% | 26.5% | -3.0 pts |
| Additional revenue | - | $169.4M | - |
| Additional bookings | - | $126.6M | - |
| Additional adjusted EBITDA | - | $14.1M | - |

Learning from others' mistakes is the cheapest lesson there is. In our report covering the edtech market, we look at what broke startups before you, so you don't repeat it.
Is Duolingo's AI strategy actually making language learning better?
Duolingo's AI strategy is already making content production much faster and spoken practice more accessible, although its impact on actual language proficiency is harder to measure.
One of the most impressive changes concerns course creation.
In the first quarter of 2026, Duolingo published approximately 20,500 course units, compared with an average of 7,100 per quarter in 2025 and 1,800 in 2024. AI turning out course units several times faster is the kind of tech we split into working now and still on paper in our market report about edtech.
That's an approximately elevenfold increase compared with the 2024 quarterly average. For a company that historically needed substantial human effort to build educational content, the improvement is remarkable.
Duolingo has also expanded intermediate and advanced lessons across its nine most popular languages, with content extending toward Duolingo Score 129, which it associates with CEFR B2 proficiency.
Its conversational features are evolving as well. Video Call with Lily lets subscribers practice speaking with an AI character, while spoken-token exercises allow learners to answer ordinary questions aloud instead of tapping words on their screens.
Duolingo reported that users were speaking more than twice as many words per Video Call session as a year earlier.
These changes directly address a common complaint about language-learning apps: people can become good at completing exercises without becoming equally comfortable speaking.
Yet speaking more words inside an app doesn't necessarily mean someone can hold a fluent conversation outside it. We still lack strong independent evidence comparing the long-term outcomes of Duolingo's newer AI tools with human tutoring or immersion.
The production gains, though, are hard to dispute. AI has changed how quickly Duolingo can develop courses, and conversational practice is becoming a much bigger part of the experience.
Did Duolingo's AI-first controversy hurt its business?
Duolingo's AI-first controversy hurt its reputation, but there is little evidence that the backlash caused a lasting decline in its audience or subscriber base.
The criticism began in April 2025, when CEO Luis von Ahn announced that Duolingo would become an AI-first company. His message explained that the company would gradually reduce its reliance on contractors for work that AI could perform and incorporate AI use into operational decisions.
The announcement triggered criticism over potential job losses, educational quality and Duolingo's apparent enthusiasm for replacing human work with automation.
Von Ahn later acknowledged that the communication had been mishandled. In a May 2026 interview with Fast Company, he also discussed the limitations of AI-generated work, including quality concerns.
However, the company's audience continued growing throughout the controversy.
Duolingo added approximately 11 million daily active users between the second quarters of 2025 and 2026, while its paid subscriber base increased by about 1.8 million.
Those figures cannot tell us whether some individuals stopped using Duolingo because of its AI policies. They do show that any departures were more than offset by new and returning users.
The more lasting issue may be trust. Duolingo needs learners to believe its courses are accurate and its teaching methods are effective, particularly as AI-generated content becomes more common.
The controversy remains relevant to the brand, but claims that it seriously damaged Duolingo's commercial position are unsupported by the company's reported results.

In our research about education technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Could ChatGPT replace Duolingo for language learning?
ChatGPT can already replace several Duolingo features, especially grammar explanations, personalized exercises and conversational practice. Replacing the complete Duolingo experience is a much tougher challenge.
A learner can ask ChatGPT to explain French grammar, create a Spanish vocabulary lesson, correct written English or simulate a conversation in Japanese. Many of these activities overlap with features offered through Duolingo's paid subscriptions.
The competition is particularly relevant for Duolingo Max, whose appeal originally relied heavily on AI-powered conversations and explanations.
As conversational AI becomes cheaper and more widely available, Duolingo has less room to charge a large premium simply for providing access to an AI tutor.
However, language learning involves more than getting answers to questions.
Duolingo provides a structured sequence of lessons, automatically tracks progress, adjusts difficulty and constantly reminds users to return. Streaks, achievements and social features also help maintain motivation.
Someone using ChatGPT independently must often decide what to practice, how difficult the next exercise should be and whether to study at all. Duolingo handles much of that routine.
The company is responding to AI competition by incorporating similar capabilities directly into its existing learning system. Making Video Call more widely available to Super subscribers is a good example.
For now, we see the biggest threat to Duolingo's premium feature pricing rather than its overall audience. General-purpose AI has become excellent at generating educational material, but Duolingo still has a major advantage in keeping millions of people engaged day after day.
Can people actually become fluent using Duolingo?
Duolingo is becoming more useful for serious language learners, but the company has not demonstrated that completing its courses consistently produces advanced conversational fluency.
The app has traditionally been strongest at beginner and intermediate vocabulary, basic grammar and regular practice. Speaking spontaneously with another person is a different challenge. What learners still cannot get from an app, like speaking spontaneously with someone, is among the problems we study in our edtech market report.
Duolingo has made several changes to close that gap.
Video Call offers conversational practice without needing to book a tutor. Speaking Adventures places users in simulated situations requiring spoken answers. New mastery checks also ask learners to demonstrate their knowledge before advancing.
Meanwhile, the company has extended its major language courses toward CEFR B2-level content. B2 generally corresponds to being able to understand complex material and communicate with reasonable independence.
However, access to B2-level lessons should not be confused with achieving B2 proficiency.
A learner might complete difficult exercises while still struggling with native speakers, unfamiliar accents or spontaneous conversation. Real proficiency requires listening comprehension, vocabulary recall and the ability to communicate without prompts.
Duolingo has published research supporting the effectiveness of parts of its teaching approach, but its latest AI features still need stronger independent evaluation.
We can reasonably say that Duolingo now addresses more aspects of language learning than it did a few years ago. For advanced fluency, though, conversation with real people and exposure to natural language remain valuable complements.

If you build or invest in the edtech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Is Duolingo becoming more than a language-learning app?
Duolingo is gradually expanding beyond languages, although mathematics, music and chess have yet to demonstrate the commercial importance of its main product.
The company has introduced these subjects using the same short lessons, progress tracking, achievements and rewards that made language learning popular.
The strategy makes sense for an app with a huge existing audience. People already opening Duolingo to study French or Korean might be persuaded to spend additional time practicing arithmetic, learning musical notation or solving chess puzzles.
Duolingo also benefits from having built a reusable content and experimentation system. Its AI-assisted production methods can help develop courses across multiple subjects without starting from scratch each time.
However, the company does not provide enough detailed subject-level financial information to establish whether these newer categories are attracting significant numbers of independent paying customers.
That limits what we can conclude about their commercial success.
In the meantime, Duolingo continues investing in its brand and product experience. In August 2026, it announced the acquisition of London-based animation studio Animade, strengthening its in-house motion design capabilities. The acquisition fits its longstanding emphasis on making learning visually appealing and entertaining.
The broader opportunity is certainly attractive: if Duolingo can make mathematics or music as habit-forming as language learning, its potential audience could become much larger.
But languages still account for the overwhelming majority of its proven business.
Is the Duolingo English Test catching up with IELTS and TOEFL?
The Duolingo English Test has become a legitimate option for university admissions, but it remains much smaller commercially than Duolingo's subscription business and less widely established than IELTS or TOEFL.
The test's biggest advantage is convenience. Students can take it online without traveling to a testing center, and results are generally available much faster than with many traditional testing arrangements.
More than 6,500 academic programs now accept the Duolingo English Test, according to company data. That number has more than doubled since 2020.
Duolingo has also reported strong institutional retention, with 99% of programs that started accepting the test before January 2021 continuing to recognize it.
These figures show that acceptance is becoming more established rather than depending entirely on a few universities experimenting with a new format.
However, university admission and immigration requirements are separate issues. Some institutions accept Duolingo scores for academic purposes even when certain visa processes require another approved test.
The financial numbers also put its position in perspective.
Duolingo English Test generated approximately $10.1 million in revenue in the second quarter of 2026, almost unchanged from the previous year. That represented only around 3.4% of the company's total quarterly revenue.
Its academic distribution has expanded much faster than its recent revenue.
Duolingo has already established a place in English proficiency testing, particularly among students who value convenience and affordability. Becoming a serious commercial rival to the broader IELTS and TOEFL ecosystems will require stronger growth in actual test purchases.

Theory only gets you so far. In our document detailing everything you need to know about edtech, we dig up the real signals from the field and show you the ones worth watching.
What makes Duolingo so difficult to compete with?
Duolingo's biggest advantage is its ability to turn learning into a daily habit for an enormous audience. Its course content, AI features and exercises are increasingly easy to imitate, but recreating its engagement is much harder.
The company has spent years refining its product through experimentation.
Its Green Machine system continuously tests changes to lesson design, difficulty, rewards, reminders and subscription offers. Small improvements accumulate across millions of users, helping Duolingo understand which changes encourage people to keep learning. We look for habits like Duolingo's constant experimentation when we study what leaders do differently in our market report about edtech.
Its marketing provides another advantage.
Duolingo reported generating more than one billion organic impressions per quarter through its social accounts. It has also expanded its network of creators and influencers internationally.
In China, Indonesia and India, approximately two-thirds of its social impressions have come from influencer-generated content, according to the company's latest shareholder letter.
Duolingo also tripled both the number of channels in its performance-marketing mix and its global output of advertising creative over the preceding year.
The interesting part is that the company still says most of its user growth comes organically. Its recognizable owl mascot, widely shared content and existing user community reduce its dependence on constantly purchasing new customers through advertising.
Competitors such as Babbel, Busuu and newer AI tutors can offer strong educational products, sometimes with more specialized teaching approaches.
Yet matching Duolingo's distribution, brand recognition and habit-forming features would require more than building a good language course.
AI may gradually reduce the cost of producing educational content, which makes those existing advantages even more important.
What would prove that Duolingo's new strategy is working?
Duolingo's new strategy will have succeeded when faster user engagement begins producing stronger bookings and subscriber growth again, without forcing the company to make its free product less useful.
There are encouraging early signs. Daily active user growth has accelerated slightly, current-user retention is at a record level, and more learners are using the app frequently.
But the financial side remains much less convincing.
As seen above, bookings growth has slowed considerably, and management expects adjusted EBITDA to increase only modestly this year. Duolingo can afford the investment, but eventually the larger audience needs to generate more revenue.
The upcoming third-quarter results will offer another useful comparison. Duolingo has guided for approximately $307 million in bookings and $302 million in revenue, representing annual growth of 8.9% and 11.1%, respectively.
Those figures suggest management expects the financial slowdown to continue in the near term.
We should also pay attention to whether the company's retention improvements hold after the Streak Revival campaign fades. A temporary surge in returning learners would be less valuable than a lasting improvement in daily habits.
Longer free trials, broader access to AI conversations and additional learning subjects could all help, but their effectiveness needs to appear in subsequent subscription and engagement data.
The most encouraging outcome would be sustained daily user growth above 20%, followed by a meaningful recovery in bookings growth while profitability remains healthy.
That would demonstrate that Duolingo can make its free product more attractive while still building a faster-growing subscription business.

In our report covering the edtech market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
So, how's Duolingo actually doing these days?
Duolingo is doing well overall, and its position in consumer education remains strong. The company has a growing audience, improving engagement, substantial profits and a product that AI is making more capable. Its main weakness today is a sharp slowdown in monetization.
The difference between Duolingo's operational progress and financial performance explains much of the uncertainty surrounding the company.
Its audience continues expanding by millions of daily learners each year, and a larger share of monthly users is returning every day. Meanwhile, AI has dramatically accelerated course production and helped Duolingo introduce more conversational learning experiences.
The financial picture is less exciting. Bookings are growing at roughly one-third of their 2025 annual pace, and adjusted EBITDA growth is expected to fall below 5% for the year.
Management deliberately chose this trade-off, believing that better learning and stronger engagement will eventually create more valuable subscribers.
That strategy is credible because Duolingo has a profitable business, considerable cash reserves and a brand that competitors struggle to match. It also carries a genuine risk: additional users may continue consuming more free lessons without generating proportionately more revenue.
Our assessment is that Duolingo remains one of the strongest consumer education platforms, and the recent improvement in user engagement is encouraging. The company has a much bigger opportunity than it did when its business depended mainly on basic language exercises.
However, Duolingo has yet to prove that its new approach can restore the exceptional financial growth investors once expected.
For now, we would describe Duolingo as a healthy, growing company making a costly strategic bet. The learning platform is getting stronger. Whether the business becomes significantly more valuable because of it remains an open question.
Our methodology
This analysis assesses how Duolingo is performing across six interconnected dimensions: audience growth, user engagement, monetization, financial resilience, product effectiveness, and competitive positioning. We examine recent operating results, historical trends, management disclosures, product developments, and relevant external evidence rather than relying on popularity, share-price movements, or a single financial indicator.
Our financial assessment draws primarily on Duolingo's second-quarter 2026 shareholder letter and Form 10-Q, its first-quarter results, its 2025 annual report, and its fourth-quarter 2025 earnings disclosures. These documents provide the basis for comparing daily and monthly active users, paid subscribers, revenue, bookings, margins, cash flow, and management's financial outlook.
We place particular weight on the relationships between those metrics. Daily active user growth is compared with monthly audience growth to assess engagement frequency, while paid subscriber growth and bookings provide a clearer picture of monetization. Revenue is considered alongside bookings because subscription revenue is recognized over time and can lag changes in current commercial activity.
We calculated engagement ratios, annual growth comparisons, and incremental profitability from reported company figures. We also distinguished completed financial results from management guidance. Forecasts for 2026 are treated as expectations rather than achieved performance, and adjusted EBITDA is considered separately from net income and free cash flow.
For product effectiveness, we examined Duolingo's official explanations of its AI-powered speaking features, course expansion, learning progression, and content-production methods. We used the Council of Europe's Common European Framework of Reference for Languages to interpret proficiency levels. Access to advanced course content, increased speaking activity, and faster content creation were not treated as direct proof of equivalent improvements in real-world language ability.
Our competitive assessment considers the capabilities of general-purpose conversational AI, particularly ChatGPT Voice, alongside Duolingo's structured lessons, progress tracking, experimentation systems, brand, and user-retention mechanisms. We also examined the company's expansion into mathematics, music, chess, and English proficiency testing, distinguishing product availability and institutional acceptance from demonstrated financial contribution.
We prioritized original corporate disclosures, regulatory filings, official product documentation, and authoritative institutional references. We gave greater weight to measurable operating and financial developments than to promotional claims or isolated announcements. Where the available data do not establish the durability of an improvement or its eventual commercial impact, our conclusions reflect that distinction.
Key financial sources include Duolingo's second-quarter 2026 shareholder letter, its second-quarter 2026 Form 10-Q, the official second-quarter earnings announcement, first-quarter 2026 results, fourth-quarter and full-year 2025 results, and Duolingo's 2025 annual report.
Sources covering AI and learning effectiveness include Duolingo's product highlights, its explanation of AI-powered speaking practice, Video Call with Lily, its approach to teaching speaking skills, the Duolingo Score framework, the Council of Europe's CEFR proficiency scale, and OpenAI's ChatGPT Voice documentation.
For diversification and institutional adoption, we consulted Duolingo's chess course documentation, its Animade acquisition announcement, Duolingo English Test university acceptance data, the directory of accepting institutions, and its institutional acceptance overview.

In our research about education technology, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us