What is the EdTech market actually worth?
Building a startup or looking for your next investment in EdTech? Our report gives you the full picture.
Summary
The EdTech market is worth about $200 billion today if we mean the core technology market, while the wider digital-learning economy is already closer to $300–400 billion depending on how much tutoring, training, hardware and technology-enabled education services are included.
The biggest source of confusion is scope, not forecasting skill. Several major research groups cluster tightly around $187–197 billion for 2025, while the much larger estimates usually widen the definition beyond software, classroom technology and dedicated education hardware.
EdTech is already large, but it still captures only a small share of the roughly $7.6 trillion global education economy. A core market around $190–200 billion works out to roughly 2.5% of total education spending, which leaves substantial room for technology to take a larger share without education becoming fully digital.
The post-pandemic correction was much harsher in venture funding and valuations than in underlying demand. Funding fell dramatically from the 2020–2021 peak, yet companies such as TAL, Stride and Duolingo continued to produce strong revenue or user growth.
That reset has changed what investors reward. Recent capital is more concentrated in businesses tied to workforce skills, employment, productivity or other outcomes that are easier to connect to economic value.
Institutional software remains one of the strongest parts of the market. The $5.6 billion PowerSchool transaction and $4.8 billion Instructure acquisition show that buyers still assign multibillion-dollar values to platforms embedded deeply in school and university workflows.
Consumer EdTech is more uneven. Duolingo shows that a consumer learning product with exceptional engagement can become a billion-dollar-revenue business, while Chegg shows how quickly a large academic-help model can lose scale when a cheaper substitute changes user behavior.
K-12 still represents one of the largest existing revenue pools, but workforce learning currently has stronger investment momentum. That split matters because the biggest installed market is not necessarily the part attracting the most new capital.
Regional leadership also depends on the definition. North America looks strongest when the market emphasizes enterprise and institutional software, while Asia-Pacific gains share when tutoring, consumer learning and technology-enabled education services are included more broadly.
AI is likely to redistribute EdTech revenue more than simply expand or destroy the category. Products built mainly around access to explanations face pressure, while platforms with credentials, structured learning, assessment, institutional workflows, community or strong habits have more room to use AI as a feature rather than compete with it directly. What separates EdTech leaders that use AI as a feature from the ones it threatens is something we study in our report on EdTech.
The long-term forecasts should be read as directional rather than precise. A move from roughly $200 billion toward a market twice that size is plausible, but the better evidence is the combination of current revenue growth, multibillion-dollar transactions, workforce-learning consolidation and the still-low penetration of technology across total education spending.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the edtech market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
How big is the EdTech market today?
The global EdTech market is worth roughly $190–215 billion today if we focus on education technology itself.
That is the cleanest range we found after comparing the newest major market studies. Grand View Research puts the market at $187 billion in 2025 and $213.2 billion in 2026. Fortune Business Insights gives a very similar $189.2 billion for 2025 and $214.6 billion for 2026. MarketsandMarkets estimates $197.3 billion for 2025. Outside estimates differ in scope, so we build our own from the ground up, with every assumption visible, in our EdTech market report.
Three separate research groups land in almost the same place.
There are much larger numbers floating around. Some studies reach $280 billion, $400 billion or more because they include a wider mix of tutoring, training, online education services and hardware. Those figures can be useful, but they describe a broader business than the core EdTech market most people have in mind.
So if someone asks us what EdTech is actually worth right now, around $200 billion is the strongest starting point.
Why do some EdTech estimates say $190 billion and others say more than $400 billion?
EdTech market estimates vary so much because researchers are counting different businesses under the same name.
Grand View Research currently values EdTech at $187 billion for 2025. Fortune Business Insights says $189.2 billion. MarketsandMarkets says $197.3 billion. Those estimates cover things such as learning software, classroom technology, educational content and dedicated hardware.
The numbers grow quickly once researchers broaden the definition.
IMARC has estimated the market at close to $280 billion. Arizton has put it above $400 billion while explicitly including technology-enabled services alongside software and hardware.
That extra category changes everything. A school paying for a learning-management system is clearly buying EdTech. An individual paying for a live online tutor is buying education delivered through technology. Both involve technology, although the economics are very different.
An earlier HolonIQ forecast helps show why this gets confusing. HolonIQ expected EdTech expenditure to reach about $404 billion by 2025, using a broad definition that included hardware, software and online education services. That figure is still repeated today alongside much narrower market estimates as though they measure the same thing.
They do not.
For this article, we use roughly $200 billion for the core technology market and treat the larger estimates as the wider digital-learning economy.
| Research group | 2025 estimate | What the number broadly captures |
|---|---|---|
| Grand View Research | $187.0B | Hardware, software and content |
| Fortune Business Insights | $189.2B | Education platforms and technology systems |
| MarketsandMarkets | $197.3B | EdTech and smart-classroom technology |
| The Business Research Company | About $200B | Broad EdTech products and services |
| IMARC | About $280B | Wider digital-learning market |
| Arizton | $416.1B | Hardware, software and technology-enabled services |
| HolonIQ earlier forecast | $404B | Broad education-technology expenditure |

Theory only gets you so far. In our research about education technology, we dig up the real signals from the field and show you the ones worth watching.
How big is EdTech compared with the whole education industry?
EdTech still accounts for only a small slice of global education spending, even with a market worth around $200 billion.
HolonIQ estimates the wider education economy at roughly $7.6 trillion. Using that denominator, a $190–200 billion core EdTech market represents only about 2.5% of total education spending.
Even a very broad $400 billion definition gets us only a little above 5%.
That gives us a better sense of scale than the usual billion-dollar market forecasts. EdTech is already a major technology industry, yet most money spent on education still goes toward teachers, schools, universities, buildings, administration and other services rather than dedicated technology.
It also leaves plenty of room for growth without requiring classrooms or universities to become fully digital.
If technology eventually captures 5% rather than roughly 2.5% of the education economy, the revenue pool roughly doubles. At 10%, the opportunity becomes several times larger than today's core EdTech market.
The useful question is how much more of education spending technology can realistically absorb.
Did the EdTech market collapse after the pandemic?
EdTech spending kept growing after the pandemic even as startup funding fell off a cliff.
That difference is easy to miss because venture capital created most of the spectacular EdTech headlines during 2020 and 2021.
Funding later fell by close to 90% from its peak. Yet the latest operating results from large education businesses look nothing like an industry-wide collapse.
TAL Education generated just over $3 billion in its latest full fiscal year, up 33.7%. Its following quarter was also strong: revenue reached $758.4 million, up 31.9% from the same quarter a year earlier.
Stride produced more than $2.5 billion of annual revenue in its latest fiscal year.
Duolingo passed $1 billion of annual revenue in 2025 and was still growing daily active users by 23% year over year in its latest reported quarter.
Those businesses have very different models, which makes the pattern more useful. We see growth in Chinese learning services, U.S. virtual schooling and consumer language learning at the same time.
What disappeared after the pandemic was the assumption that almost every digital-learning company deserved a premium valuation.
The underlying market kept moving.
What does the EdTech funding crash actually tell us?
Today's much lower EdTech funding levels show that investors have become far more selective about which education startups deserve capital.
HolonIQ recorded roughly $1 billion of EdTech venture funding during the first half of 2026. That is tiny compared with the pandemic peak. How far funding has fallen from the pandemic peak is one of the market signals we track every quarter in our market report about EdTech.
The more interesting part is where the remaining money goes.
Workforce-oriented businesses have taken a large share of recent funding. Investors increasingly want products that can be connected to employment, productivity, professional skills or another outcome with obvious economic value.
Preply is a good example of the new standard. The language-learning company raised $150 million at a $1.2 billion valuation after reaching EBITDA profitability. Investors were backing a large learning platform that had already shown it could turn growth into a sustainable business.
The same filter has removed former stars from the top of the market. HolonIQ recently dropped GoStudent from its unicorn list after major investors marked the business below $1 billion.
EdTech money is still available these days. The threshold for getting it is simply much higher.

In our market report about education technology, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
What kind of EdTech companies are buyers still willing to pay billions for?
Buyers are still paying several billion dollars for EdTech businesses that schools and universities rely on every day.
PowerSchool gives us one of the clearest examples. Bain Capital agreed to acquire the K-12 software company in a $5.6 billion transaction. PowerSchool serves more than 55 million students and over 17,000 customers across more than 90 countries.
Instructure produced a similar result. KKR and Dragoneer completed their $4.8 billion acquisition of the company behind Canvas after Instructure had built a learning ecosystem reaching roughly 200 million learners across more than 100 countries.
Those are big numbers for a sector that supposedly lost investor interest.
Both companies sit deep inside institutional workflows. Schools use their systems for areas such as course delivery, administration, student data and daily operations. Replacing that kind of software can involve migration work, retraining, procurement and considerable disruption.
That makes infrastructure-heavy EdTech much easier to value than an app whose users can disappear next semester.
The market has become much clearer about this distinction.
What are the biggest EdTech companies actually earning now?
The largest education-technology businesses now generate anywhere from hundreds of millions to several billion dollars a year.
New Oriental and TAL sit at the very top if we use a broad EdTech definition that includes technology-heavy education services. New Oriental generated about $5.7 billion in its latest full fiscal year, while TAL reached just over $3 billion.
Stride produced more than $2.5 billion.
Coursera has also become much larger. Its combination with Udemy closed in 2026, bringing together businesses that generated more than $1.5 billion of combined revenue in 2025. Coursera's latest guidance now points to roughly $1.22–1.25 billion of reported 2026 revenue, although the accounting only includes Udemy from the closing date.
Duolingo crossed $1 billion of annual revenue in 2025.
At the other end, Chegg shows how quickly a once-large EdTech business can shrink. Its latest quarterly revenue was only $51.8 million, down 51% year over year.
This spread tells us more than a single market-size report. EdTech already supports billion-dollar-revenue businesses, while weaker models can lose scale remarkably fast.
| Company | Recent revenue reference | What it mainly sells |
|---|---|---|
| New Oriental | ~$5.7B annual | Education services and learning products |
| TAL Education | ~$3.0B annual | Learning services and smart-learning products |
| Stride | >$2.5B annual | Virtual K-12 education |
| Coursera + Udemy | >$1.5B combined 2025 | Online learning and workforce skills |
| Duolingo | >$1.0B annual | Consumer digital learning |
| Docebo | >$240M annual | Enterprise learning software |
| Chegg | $51.8M latest quarter | Academic and workforce learning |

In our document detailing everything you need to know about edtech, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Is consumer EdTech still where the biggest opportunity is?
Consumer EdTech can still produce huge businesses, but institutional software and workforce learning now look much harder to disrupt.
Duolingo shows what a successful consumer model can achieve. The company passed $1 billion in annual revenue, has tens of millions of daily users and continues to grow even after the pandemic boost disappeared.
Chegg shows the risk on the other side.
Chegg's latest quarterly revenue fell 51% year over year as its traditional academic-help business kept shrinking. The company is now pushing harder into workforce skilling and employability.
The Coursera-Udemy combination points in the same direction from a much larger base. The merged platform connects around 290 million learners, thousands of enterprise customers and a huge catalog of professional content. Its strategy increasingly revolves around helping workers identify and learn the skills companies actually need.
Institutional platforms have another advantage. A student can switch learning apps in seconds. A university rarely replaces its core learning-management system that casually.
Consumer EdTech still has enormous upside when engagement is exceptional. For an average company, recurring institutional or workplace demand gives the business a much firmer base.
Is K-12 still the biggest part of EdTech?
K-12 remains one of the biggest EdTech markets today, although business and workforce learning are attracting much more investor attention.
Grand View Research says K-12 represented 38.9% of its EdTech market in 2025. Applied to its $187 billion total, that comes to roughly $73 billion. Where K-12 sits among other education segments depends on the market definition, which we spell out in our report covering the EdTech market.
Fortune Business Insights also identifies K-12 as the largest end-user category in its latest market study, at around one-third of global EdTech spending.
The size makes sense. Schools buy learning platforms, student-information systems, digital curriculum, assessment tools, classroom hardware and administrative software every year.
The problem for startups is that K-12 can be painful to sell into. Procurement takes time, budgets are constrained and purchasing decisions may involve teachers, school administrators, districts and governments.
Workforce learning offers a much simpler pitch in many cases: help employees learn a skill that the company currently needs.
Recent venture funding reflects that difference. Workforce-focused EdTech has captured a disproportionate share of new investment even though K-12 remains larger by existing revenue.
K-12 owns a bigger installed market. Workforce learning currently has stronger momentum with investors.

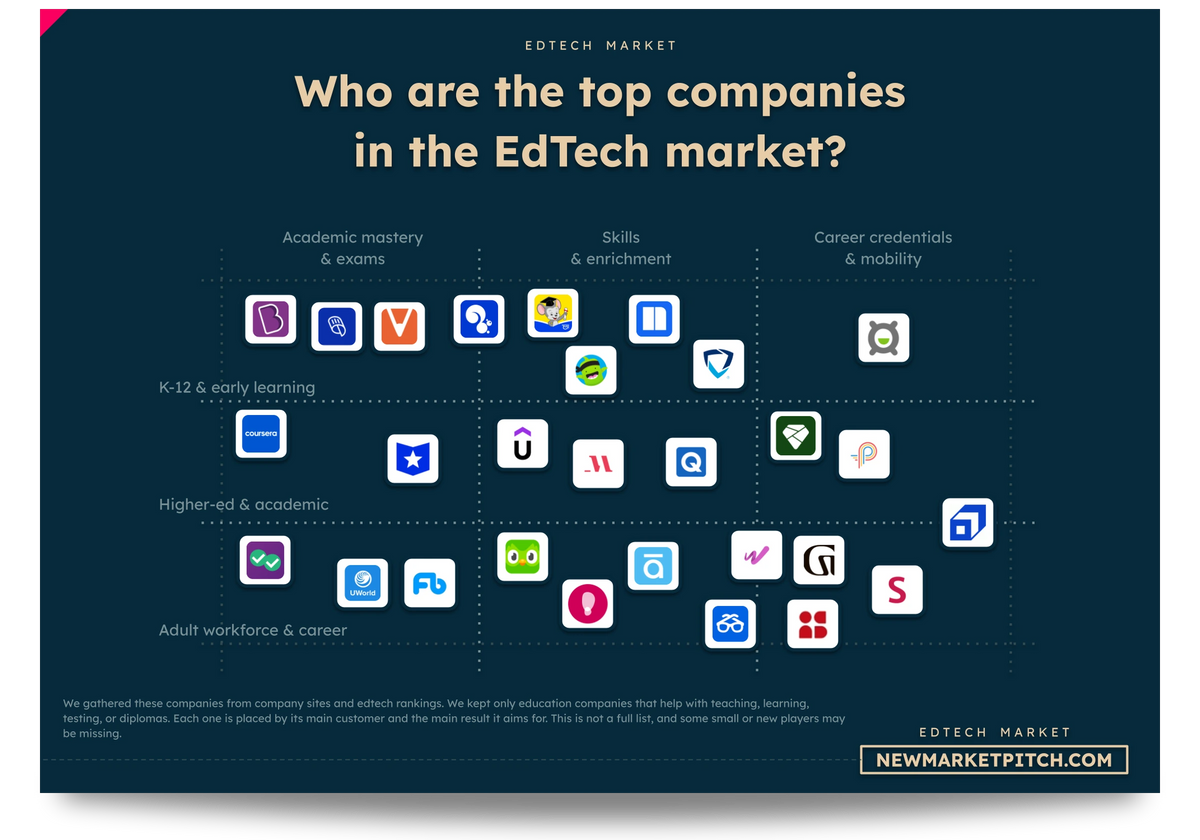
In our report covering the edtech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is North America or Asia the biggest EdTech market?
North America and Asia are now close enough that the answer changes depending on what researchers count as EdTech.
Grand View Research says North America held 36.1% of the global EdTech market in 2025. Under its $187 billion definition, that works out to roughly $67.5 billion.
Its methodology also says business customers generate 67% of EdTech revenue, which helps explain North America's strength. The region has enormous corporate-learning budgets and mature institutional software markets.
Fortune Business Insights reaches a slightly different conclusion in its latest update. It puts Asia-Pacific at roughly 34% of the market in 2025 and North America at about 33%.
Broader market studies tend to push Asia even higher because the region has huge student populations, large tutoring industries and major education-service companies in China and India.
There is no useful reason to pretend one region has an overwhelming lead today.
North America remains exceptionally strong in software and institutional spending. Asia gains quickly as we widen the market toward consumer learning, tutoring and technology-enabled education services.
Is AI making EdTech bigger or killing existing EdTech companies?
AI is making the overall EdTech opportunity bigger while putting real pressure on products that mainly sell answers or basic content access.
Chegg has become the clearest warning.
Its latest quarter produced $51.8 million of revenue, down 51% year over year. The old academic-help business has been badly exposed as students increasingly use general-purpose AI tools for explanations and homework support.
Duolingo gives us the opposite case. Its daily active users were still growing 23% in the latest quarter. Duolingo uses AI to create exercises, power conversational experiences and expand content faster, so cheaper content generation can improve its product economics.
Coursera is moving aggressively in the same direction. After completing the Udemy combination, it announced a $100 million strategic investment in Andrew Ng's new AI-native learning company, LearnVector. Coursera is also trying to build more adaptive and personalized learning into its combined platform.
Asking whether AI is “good” or “bad” for EdTech is too broad.
AI makes generic explanations abundant. That hurts businesses whose main advantage was access to explanations.
Products built around structured learning, trusted credentials, institutional workflows, community, assessment or strong user habits have more room to use AI as an improvement rather than watch it replace the product.

Our research about education technology gets updated several times a month, so you always get the latest view of where things stand.
Are Coursera and Udemy becoming one giant workforce-learning company?
Coursera and Udemy are now one company, and the combined business is clearly moving deeper into workforce skills.
The transaction closed in 2026 and brought together roughly 290 million learners, 18,000 enterprise customers, 95,000 instructors and hundreds of university and industry partners.
The two companies generated more than $1.5 billion of combined revenue in 2025.
The first results after the combination make the strategy easier to see. Coursera reported $299 million of second-quarter revenue and raised its full-year outlook to $1.22–1.25 billion. Management also expects at least $85 million of annualized net synergies by the end of 2026.
More interestingly, Coursera is talking less like a traditional online-course marketplace. The company increasingly describes its job as finding skill gaps, helping workers develop those skills and verifying what they have learned.
That puts Coursera in the same broader race as enterprise-learning companies, professional credential providers and AI-powered talent platforms.
The shift could make workforce learning one of the most important parts of EdTech over the next few years.
How much are private EdTech unicorns worth today?
The entire active EdTech unicorn group is currently worth only about $34 billion, a surprisingly modest total compared with the pandemic years.
HolonIQ counted 14 EdTech unicorns in its latest review, with a combined valuation of $34.2 billion.
That figure immediately shows how much the private market has changed.
BetterUp sits near the top at $4.7 billion. Synthesia is valued at $4 billion. Handshake is around $3.5 billion. Preply recently joined the group at $1.2 billion.
Several former names have disappeared. Physics Wallah left the private-unicorn list after going public. GoStudent was removed after investor marks pushed its valuation below $1 billion.
A $34.2 billion aggregate also gives us useful perspective. During the pandemic, individual EdTech companies could command valuations above $10 billion. Today, the whole active unicorn cohort combined is worth only a few times that amount.
Private EdTech has become a much smaller valuation story than AI infrastructure, foundation models or some fintech categories.
For companies that survive this reset, that may actually be healthier. The valuations are increasingly tied to real revenue and business quality rather than the assumption that every learner would permanently move online. What investors now reward after the reset, and what they avoid, is something we follow in our report on EdTech.
Can the EdTech market really double from here?
The EdTech market can plausibly double over the next decade, although the exact forecasts are much less reliable than the direction.
Grand View Research expects its $187 billion 2025 market to reach $437.5 billion by 2033.
Fortune Business Insights starts from $189.2 billion and projects $588.7 billion by 2034.
MarketsandMarkets starts at $197.3 billion and reaches $353.1 billion by 2030.
The ranges differ enormously, yet all three imply strong growth.
We can also see real operating evidence behind that direction. TAL's latest quarterly revenue grew 31.9%. Duolingo's daily active users were still up 23%. Coursera has just combined with Udemy to create a much larger workforce-learning platform. Large institutional assets such as PowerSchool and Instructure have attracted multibillion-dollar buyers.
At the same time, Chegg reminds us that industry growth will not lift every company.
The credible growth case comes from several separate sources: more education software, more AI-assisted learning, more digital administration and much heavier demand for continuous workforce reskilling.
A precise $500 billion or $600 billion forecast several years out deserves skepticism. Continued expansion from today's roughly $200 billion core market is much easier to defend.

In our market report about education technology, you will always find fresh funding data, taken straight from our own verified funding database.
So what is the EdTech market actually worth?
The best current answer is about $200 billion for core EdTech, with the wider digital-learning economy already worth somewhere around $300–400 billion depending on what services we include.
That conclusion holds up better than choosing the largest market report available.
The freshest estimates from Grand View Research, Fortune Business Insights and MarketsandMarkets all place the core market around $187–197 billion in 2025 and above $200 billion as we move forward.
The operating evidence fits that scale. Several education companies already produce billions of dollars in annual revenue. Institutional EdTech assets have recently sold for $4.8 billion and $5.6 billion. The combined Coursera-Udemy business has more than $1.5 billion of historical annual revenue, while Duolingo has crossed $1 billion on its own.
Yet EdTech still captures only a few percent of the roughly $7.6 trillion global education economy.
That gap is the most important number in the article.
The pandemic made EdTech look temporarily larger than it really was because valuations and venture investment ran far ahead of underlying revenue. The correction that followed stripped away a lot of that excess.
What remains today is a roughly $200 billion technology market with real billion-dollar companies, durable infrastructure businesses and a large amount of education spending that has yet to become technology spending.
That is already a big market. It also has much more room to grow.
Our methodology
This analysis asks what the EdTech market is actually worth by separating the core technology market from the much wider digital-learning economy. We tested the headline market-size estimates against total education spending, public-company operating performance, venture funding, private valuations, M&A, segment and regional mix, AI exposure and forward growth.
We gave the most weight to evidence closest to the question being tested. Company filings and investor disclosures were used for revenue and user growth, direct transaction announcements for acquisitions and funding rounds, and the original research publishers for market estimates. We did not average estimates that measure different things: where numbers diverged, we first checked what each source actually included.
Funding and private valuations were assessed separately from underlying demand. That distinction is important here because EdTech venture investment fell sharply after the pandemic while several large education businesses continued to grow. Consumer businesses were also considered separately from institutional and workforce platforms, since their retention, procurement and revenue economics are very different.
Longer-term forecasts were treated as directional rather than precise predictions. We compared them with current operating evidence, recent transactions and EdTech's penetration of the wider education economy before using them to support the growth case.
Key market-sizing sources include Grand View Research, Fortune Business Insights, MarketsandMarkets, IMARC, Arizton, and HolonIQ on the size of the global education economy. We also used HolonIQ's earlier $404 billion EdTech forecast to show how broader definitions can produce much larger headline numbers.
For funding and private-market context, we used HolonIQ's H1 2026 funding review, HolonIQ's EdTech unicorn list, and Preply's funding announcement.
For operating performance and transactions, key sources include New Oriental's SEC filing, TAL Education's FY2026 results, TAL Education's latest reported quarter, Stride's FY2026 results, Duolingo's FY2025 filing, Duolingo's Q2 2026 results, and Chegg's Q2 2026 results.
For institutional software and workforce-learning consolidation, we used Bain Capital's PowerSchool acquisition announcement, Instructure's acquisition announcement, Coursera's announcement completing the Udemy combination, and Coursera's Q2 2026 results.

In our document detailing everything you need to know about edtech, we look at what the winners do differently, so you can learn from the best instead of guessing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us