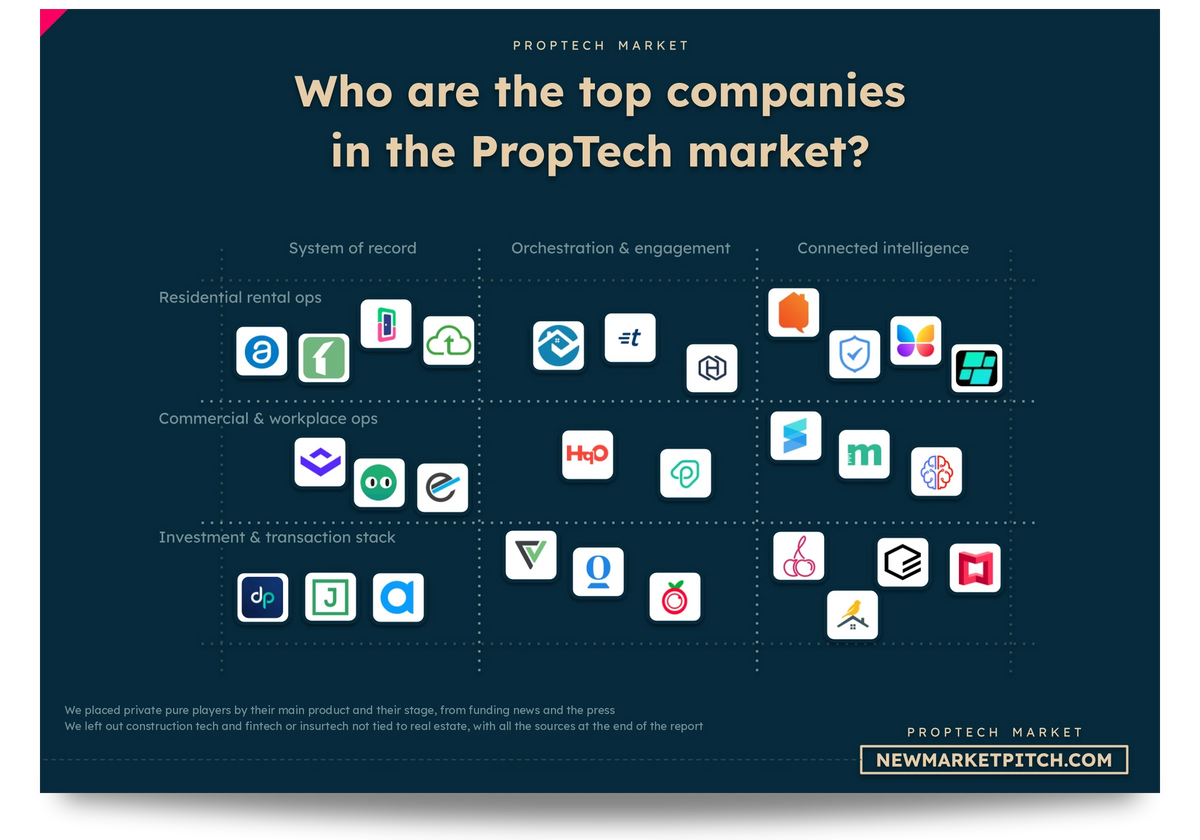
What are the most valuable PropTech startups?
Summary
Metropolis, Entrata and EliseAI are the most valuable PropTech startups today, valued at $5B, $4.3B and $4B, respectively. They lead a market where AI automation, property management software and large operating networks are attracting the highest valuations.
PropTech has a substantial unicorn population. Our ranking includes 15 startups whose valuation ranges are entirely at or above $1 billion, plus another 13 whose ranges reach that threshold. That's 28 potential unicorns, although their financial strength and growth prospects vary considerably.
The funding recovery is much narrower than the headline valuations suggest. Global PropTech investment reached $4.53 billion in the first half of 2026, virtually unchanged from 2025, while just 11 large rounds accounted for almost half of the money raised.
EliseAI is one of the clearest winners of this concentration. Its valuation climbed roughly 82% in 13 months to $4 billion, supported by more than $200 million in annual recurring revenue and AI products already used across a substantial share of US apartment buildings.
Entrata shows why established software companies remain valuable even as AI startups grow quickly. Landlords rely on its accounting, payments and property records, making it difficult for newer competitors to replace the entire system rather than automate individual tasks around it.
Metropolis represents a different investment thesis. Its acquisition of SP Plus created a network exceeding 4,000 locations and processing more than $4 billion in annual payments. The upside comes from improving the economics of that existing infrastructure, but physical operations also create costs that software-only businesses avoid.
Mews illustrates why revenue alone can be misleading. The hotel technology company generated approximately €291 million in 2025 revenue, much of it connected to payments, but reported only around €72 million in gross profit and a €111 million operating loss. Its $2.5 billion valuation depends heavily on future margin improvement.
Vacation rental software and real estate marketplaces face different pressures. Hostaway and Guesty are approaching unicorn valuations as professional rental management becomes more complex, while companies such as QuintoAndar and Loft remain exposed to housing transactions and financing conditions.
Europe has developed particular strengths in hospitality software and building efficiency technology. Mews, Lighthouse, Deepki and other specialists benefit from recurring operational needs, while tighter EU building energy rules create additional demand for property data and renovation technology.
The next PropTech winners will probably be companies that own essential operating workflows and can prove they make those workflows cheaper or more profitable. Recent funding, acquisitions and company financials suggest that investors are increasingly rewarding revenue quality and operating scale rather than growth projections alone.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us
Top startups in the PropTech market ranked by valuation
Here is an updated table that ranks the top startups in the PropTech market based on their latest reported or estimated valuations.
If you need to dig deeper and get more detailed data, please check our report covering the PropTech market.
| # | Startup Name | What They Do | Current Valuation ($) | Valuation Confidence Level | Valuation Type | Evidence Status | Total Funding ($) | Funding Confidence Level | Country |
|---|---|---|---|---|---|---|---|---|---|
| 1 | Metropolis | AI-powered automated parking infrastructure | $5B | Strong Confidence | Implied Valuation from Raise | Estimated | $1.8B1 | - | United States |
| 2 | Entrata | Multifamily property management software | $4.3B | Strong Confidence | Implied Valuation from Raise | Estimated | $707M | Full Confidence | United States |
| 3 | EliseAI | AI-powered property operations automation | $4B | Full Confidence | Announced Private Round Valuation | Observed | $392M | Full Confidence | United States |
| 4 | Ziroom | Managed residential rentals and apartments | $2.0B–$3.5B | Low Confidence | Comparables-Based Estimate | Estimated | $2.12B | - | China |
| 5 | Flow | Residential real estate operating platform | $2.5B | Strong Confidence | Implied Valuation from Raise | Estimated | $450M+ | - | United States |
| 6 | Mews | Cloud-based hotel management operating system | $2.5B | Full Confidence | Announced Private Round Valuation | Observed | $717M | Strong Confidence | Netherlands |
| 7 | QuintoAndar | Brazilian digital property rental marketplace | $2.0B–$2.8B | Partial Confidence | Comparables-Based Estimate | Estimated | $756M | Full Confidence | Brazil |
| 8 | Property Finder | Middle Eastern property listings marketplace | $1.8B–$2.2B | Strong Confidence | Implied Valuation from Raise | Estimated | $695M | Strong Confidence | United Arab Emirates |
| 9 | Lessen | Property maintenance and management platform | $1.5B–$2.2B | Partial Confidence | Comparables-Based Estimate | Estimated | $214M+ | Partial Confidence | United States |
| 10 | Loft | Brazilian real estate fintech platform | $1.3B–$1.9B | Partial Confidence | Comparables-Based Estimate | Estimated | $900M | Strong Confidence | Brazil |
| 11 | Qualia | Digital real estate closing software | $1.4B–$1.6B | Strong Confidence | Implied Valuation from Raise | Implied | $250M+ | - | United States |
| 12 | HomeLight | Real estate transaction technology | $1.2B–$1.7B | Partial Confidence | Comparables-Based Estimate | Estimated | $299M | Strong Confidence | United States |
| 13 | Tujia | Chinese vacation rental booking marketplace | $1.0B–$1.8B | Low Confidence | Comparables-Based Estimate | Estimated | $764M | - | China |
| 14 | Vantaca | AI-powered community association management software | $1.25B | Strong Confidence | Implied Valuation from Raise | Estimated | $305M | Strong Confidence | United States |
| 15 | Lighthouse | Hospitality pricing and intelligence software | $1.0B–$1.4B | Strong Confidence | Comparables-Based Estimate | Estimated | $470M | - | United Kingdom |
| 16 | Roofstock | Single-family rental investment platform | $900M–$1.3B | Partial Confidence | Comparables-Based Estimate | Estimated | $365M | Full Confidence | United States |
| 17 | Xiaozhu | Chinese short-term accommodation rental marketplace | $800M–$1.4B | Low Confidence | Comparables-Based Estimate | Estimated | $500M | - | China |
| 18 | IAD France | Digital independent real estate agent network | $850M–$1.3B | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | ~$360M | - | France |
| 19 | Blueground | Furnished flexible apartment rentals | $800M–$1.2B | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $243M | Partial Confidence | United States |
| 20 | Place | Real estate agent business platform | $800M–$1.2B | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $103M | - | United States |
| 21 | Square Yards | Integrated property transactions and mortgage platform | $900M–$1.1B | Strong Confidence | Implied Valuation from Raise | Estimated | $93M+ | Partial Confidence | India |
| 22 | Guesty | Short-term rental management software | $800M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $279M+ | Strong Confidence | Israel |
| 23 | Hostaway | Vacation rental management software | $925M | Partial Confidence | Announced Private Round Valuation | Observed | $540M+ | Partial Confidence | Finland |
| 24 | Redaptive | Commercial building energy infrastructure financing | $750M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $2.1B1 | - | United States |
| 25 | FlashParking | Smart parking management technology | $700M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $453M | - | United States |
| 26 | NoBroker | Brokerage-free property marketplace in India | $700M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $376M | Strong Confidence | India |
| 27 | Habi | Latin American digital home transactions | $650M–$1.1B | Low Confidence | Comparables-Based Estimate | Estimated | $316M | Full Confidence | Colombia |
| 28 | Snapdocs | Digital mortgage closing infrastructure platform | $600M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $260M | - | United States |
| 29 | VTS | Commercial real estate management software | $500M–$1.2B | Partial Confidence | Comparables-Based Estimate | Estimated | $304M | Partial Confidence | United States |
| 30 | Homeward | Cash-backed home buying solutions | $750M–$900M | Strong Confidence | Comparables-Based Estimate | Estimated | $360M | - | United States |
| 31 | Density | Workplace occupancy analytics and sensors | $600M–$950M | Partial Confidence | Comparables-Based Estimate | Estimated | $217M | Strong Confidence | United States |
| 32 | Cloudbeds | Cloud-based hotel management software | $600M–$900M | Partial Confidence | Comparables-Based Estimate | Estimated | $250M+ | Partial Confidence | United States |
| 33 | AvantStay | Luxury vacation rental management platform | $620M–$780M | Strong Confidence | Implied Valuation from Raise | Implied | $739M1 | - | United States |
| 34 | Canary Technologies | AI-powered hotel guest management software | $550M–$750M | Strong Confidence | Implied Valuation from Raise | Estimated | $176M | - | United States |
| 35 | GridPoint | Commercial building energy optimization | $480M–$720M | Partial Confidence | Comparables-Based Estimate | Estimated | $372M | - | United States |
| 36 | Limehome | Technology-enabled serviced apartment operator | $450M–$750M | Partial Confidence | Comparables-Based Estimate | Estimated | $85M+ | Low Confidence | Germany |
| 37 | Pacaso | Luxury vacation home co-ownership marketplace | $500M–$700M | Strong Confidence | Implied Valuation from Raise | Estimated | $357M | Strong Confidence | United States |
| 38 | Deepki | Real estate sustainability analytics software | $400M–$650M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $178M | - | France |
| 39 | Evolve | Vacation rental management services | $400M–$650M | Partial Confidence | Comparables-Based Estimate | Estimated | $224M | - | United States |
| 40 | PassiveLogic | Autonomous AI building controls platform | $450M–$600M | Strong Confidence | Implied Valuation from Raise | Implied | $155M | Strong Confidence | United States |
| 41 | DoorLoop | Cloud property management software | $420M–$600M | Partial Confidence | Comparables-Based Estimate | Estimated | $120M | - | United States |
| 42 | RoomPriceGenie | Automated hotel revenue management software | $400M–$600M | Partial Confidence | Implied Valuation from Raise | Implied | $79M | - | Switzerland |
| 43 | Venn | AI-powered residential property operations software | $350M–$650M | Partial Confidence | Implied Valuation from Raise | Implied | $162M | - | United States |
| 44 | Dwelly | AI-powered residential lettings agencies | $380M–$570M | Partial Confidence | Implied Valuation from Raise | Implied | ~$260M | - | United Kingdom |
| 45 | Runwise | Smart building energy optimization technology | $370M–$550M | Partial Confidence | Implied Valuation from Raise | Implied | $79M1 | - | United States |
| 46 | Clikalia | Digital residential property transaction platform | $350M–$550M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $176M1 | Partial Confidence | Spain |
| 47 | Casavo | Technology-enabled residential real estate transactions | $300M–$600M | Low Confidence | Comparables-Based Estimate | Estimated | $265M+1 | Strong Confidence | Italy |
| 48 | Apartment List | Online apartment search and rentals | $350M–$520M | Partial Confidence | Comparables-Based Estimate | Estimated | $169M | Strong Confidence | United States |
| 49 | Rhino | Rental deposit replacement insurance platform | $320M–$550M | Partial Confidence | Comparables-Based Estimate | Estimated | $116M | Strong Confidence | United States |
| 50 | ButterflyMX | Smart building access control systems | $350M–$500M | Partial Confidence | Comparables-Based Estimate | Estimated | $109M+ | Strong Confidence | United States |
| 51 | Crexi | Commercial real estate marketplace software | $280M–$480M | Low Confidence | Comparables-Based Estimate | Estimated | $45M | Full Confidence | United States |
| 52 | Buena | AI-powered residential property management | $300M–$450M | Partial Confidence | Implied Valuation from Raise | Implied | $58M | - | Germany |
| 53 | McMakler | Digital real estate brokerage services | $280M–$470M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $224M | - | Germany |
| 54 | PetScreening | Rental property pet compliance software | $320M–$430M | Partial Confidence | Implied Valuation from Raise | Implied | $85M | - | United States |
| 55 | Side | Technology infrastructure for independent brokerages | $250M–$500M | Low Confidence | Comparables-Based Estimate | Estimated | $263M | Full Confidence | United States |
| 56 | Measurabl | Real estate sustainability data software | $270M–$450M | Partial Confidence | Comparables-Based Estimate | Estimated | $177M+ | Partial Confidence | United States |
| 57 | Plentific | Property maintenance and operations software | $270M–$450M | Partial Confidence | Comparables-Based Estimate | Estimated | $136M | Partial Confidence | United Kingdom |
| 58 | IMMO | Technology-driven residential investment management | $230M–$430M | Low Confidence | Comparables-Based Estimate | Estimated | ~$100M | - | United Kingdom |
| 59 | Placemakr | Technology-enabled apartment hospitality operations | $240M–$420M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $190M | - | United States |
| 60 | Stanza Living | Managed student and professional accommodation | $290M–$360M | Strong Confidence | Implied Valuation from Raise | Estimated | $292M | - | India |
| 61 | Landing | Flexible furnished apartment rental network | $250M–$375M | Partial Confidence | Comparables-Based Estimate | Estimated | $155M | Strong Confidence | United States |
| 62 | Alfred | Residential property management and services | $220M–$400M | Low Confidence | Comparables-Based Estimate | Estimated | $220M | Strong Confidence | United States |
| 63 | Habyt | Flexible furnished residential accommodation | $220M–$380M | Low Confidence | Comparables-Based Estimate | Estimated | $73M | Strong Confidence | Germany |
| 64 | HqO | Commercial tenant experience software | $230M–$370M | Partial Confidence | Comparables-Based Estimate | Estimated | $163M+ | Partial Confidence | United States |
| 65 | Kasa | Technology-enabled hospitality property management | $220M–$380M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $160M | - | United States |
| 66 | Nawy | Egyptian digital real estate marketplace | $250M–$350M | Partial Confidence | Implied Valuation from Raise | Implied | ~$81M | - | Egypt |
| 67 | VergeSense | AI-powered workplace occupancy intelligence | $240M–$360M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $83M | Full Confidence | United States |
| 68 | Superlógica | Property management software and payments | $210M–$350M | Partial Confidence | Comparables-Based Estimate | Estimated | $93M | - | Brazil |
| 69 | Zumper | Digital apartment rental listing marketplace | $180M–$350M | Low Confidence | Comparables-Based Estimate | Estimated | $178M | Strong Confidence | United States |
| 70 | Belong | Technology-enabled residential rental management | $180M–$320M | Low Confidence | Comparables-Based Estimate | Estimated | $135M | Full Confidence | United States |
| 71 | Noda | AI-powered commercial building operations | $170M–$330M | Low Confidence | Proxy-Based Estimate | Estimated | $90M | - | United States |
| 72 | Obligo | Deposit-free rental financial solutions | $170M–$290M | Partial Confidence | Implied Valuation from Raise | Implied | $73M | Strong Confidence | United States |
| 73 | Findigs | Automated rental application decisions | $170M–$270M | Partial Confidence | Implied Valuation from Raise | Implied | $80M | - | United States |
| 74 | 99 Group | Southeast Asian real estate marketplaces | $150M–$250M | Partial Confidence | Comparables-Based Estimate | Estimated | $73M | Partial Confidence | Singapore |
| 75 | La Haus | Latin American digital property marketplace | $120M–$280M | Low Confidence | Comparables-Based Estimate | Estimated | ~$214M | - | Colombia |
| 76 | Spotahome | Online medium-term residential rental marketplace | $170M–$230M | Partial Confidence | Comparables-Based Estimate | Estimated | $97M | Strong Confidence | Spain |
| 77 | CompStak | Commercial real estate transaction data | $160M–$230M | Partial Confidence | Comparables-Based Estimate | Estimated | $78M | Strong Confidence | United States |
| 78 | Dealpath | Institutional real estate investment software | $140M–$230M | Partial Confidence | Comparables-Based Estimate | Estimated | $55M+ | Partial Confidence | United States |
| 79 | Funnel Leasing | Multifamily leasing automation software | $140M–$230M | Partial Confidence | Comparables-Based Estimate | Estimated | $108M | Partial Confidence | United States |
| 80 | Cohabs | Flexible coliving accommodation and management | $130M–$230M | Low Confidence | Comparables-Based Estimate | Estimated | $203M1 | - | Belgium |
| 81 | Goodlord | Digital rental transaction management | $140M–$220M | Partial Confidence | Comparables-Based Estimate | Estimated | $69M | - | United Kingdom |
| 82 | ZoloStays | Managed co-living and student housing | $130M–$230M | Partial Confidence | Revenue or ARR Multiple Estimate | Estimated | $98M | - | India |
| 83 | Nested | Technology-enabled residential estate agency | $100M–$230M | Low Confidence | Comparables-Based Estimate | Estimated | ~$230M | - | United Kingdom |
| 84 | HousingAnywhere | International mid-term rental marketplace | $140M–$160M | Strong Confidence | Implied Valuation from Raise | Implied | $42M+ | Partial Confidence | Netherlands |
| 85 | Infogrid | AI building monitoring and analytics | $90M–$210M | Low Confidence | Comparables-Based Estimate | Estimated | $119M | Strong Confidence | United Kingdom |
| 86 | Sundae | Marketplace for selling homes as-is | $80M–$180M | Low Confidence | Proxy-Based Estimate | Estimated | $136M | Strong Confidence | United States |
| 87 | Orchard | Integrated home buying and selling | $105M–$135M | Strong Confidence | Implied Valuation from Raise | Implied | $285M | Partial Confidence | United States |
| 88 | Colonies | Managed coliving housing and development | $70M–$160M | Low Confidence | Proxy-Based Estimate | Estimated | ~$34M2 | - | France |
| 89 | Yopa | Hybrid online residential estate agency | $70M–$150M | Low Confidence | Comparables-Based Estimate | Estimated | ~$100M | - | United Kingdom |
| 90 | Knock | Homebuying bridge financing platform | $40M–$110M | Low Confidence | Comparables-Based Estimate | Estimated | $104M+ | Partial Confidence | United States |
Which startups in the PropTech market have been acquired or gone public?
These startups no longer have a private-market valuation of their own, so we list them separately, using their acquisition price or their current market capitalization.
| # | Startup Name | What They Do | Current Valuation ($) | Valuation Confidence Level | Valuation Type | Evidence Status | Total Funding ($) | Funding Confidence Level | Country |
|---|---|---|---|---|---|---|---|---|---|
| 1 | SpotHero | Online parking reservation marketplace | $617M | Full Confidence | Acquisition Value | Observed | $130M | - | United States |
| 2 | TheGuarantors | Lease guarantees and rental insurance | $250M–$450M | Partial Confidence | Comparables-Based Estimate | Estimated | $112M | - | United States |
| 3 | Cherre | Real estate data intelligence platform | $230M–$370M | Low Confidence | Proxy-Based Estimate | Estimated | $105M | Full Confidence | United States |
| 4 | JustPark | Digital parking reservations and payments | $115M–$250M | Low Confidence | Comparables-Based Estimate | Estimated | $15.5M3 | - | United Kingdom |
| 5 | Rive | AI-powered residential property transactions | $100M–$250M | Low Confidence | Proxy-Based Estimate | Estimated | $156M1 | - | Finland |
| 6 | Jetty | Rental deposit insurance and guarantees | $70M–$160M | Low Confidence | Proxy-Based Estimate | Estimated | $41M+ | Strong Confidence | United States |
| 7 | Stonal | AI-powered real estate asset management | ~$82M | Partial Confidence | Acquisition Value | Observed | $130M | - | France |
| 8 | Mint House | Premium apartment-style hospitality accommodations | $20M–$80M | Low Confidence | Proxy-Based Estimate | Estimated | ~$84M | - | United States |
- Some totals include debt or credit facilities, not only equity.
- Corporate financing only; excludes institutional property investment commitments.
- Covers JustPark alone, not the combined ParkHub business.
Which startups in the PropTech market are worth the most?
Metropolis, Entrata and EliseAI currently occupy the top three positions in our PropTech valuation ranking, with Metropolis valued at $5B, Entrata at $4.3B and EliseAI at $4B. The gaps between them are small, so the order at the top could change with the next financing round.
What's interesting is how different these three businesses are. Metropolis operates AI-powered parking infrastructure, EliseAI automates property operations, and Entrata provides software that landlords use to manage apartment buildings.
Metropolis became considerably larger after acquiring SP Plus in May 2024. According to the company's announcement, the combined business had more than 4,000 locations, over 20,000 employees and a network processing more than $4 billion in annual payments.
EliseAI has taken a different route. Its September 2026 funding round valued the company at $4.0B after it reported surpassing $200 million in annual recurring revenue. Entrata, meanwhile, has spent years building software around the accounting, leasing and daily operations of residential properties.
Below these three, Ziroom ($2.0B–$3.5B), Flow ($2.5B), Mews ($2.5B) and QuintoAndar ($2.0B–$2.8B) show how broad the PropTech market has become.
The largest valuations are going to companies that control important parts of real estate operations, whether through software, physical infrastructure or large transaction networks. There isn't one dominant PropTech business model anymore.
How many PropTech unicorns are there today?
Our PropTech ranking currently includes 15 startups whose valuation ranges are entirely at or above $1 billion, with another 14 whose ranges reach that threshold.
That gives us 28 companies out of 90, or approximately 31%, whose valuations could qualify them as unicorns.
The distinction between the two groups is important. EliseAI is valued at $4.0B, for example, while Roofstock is valued at $900M–$1.3B. Roofstock could be worth more than $1 billion, but its range also allows for a valuation below that level.
The 15 companies with valuation ranges fully at or above the threshold are Metropolis, EliseAI, Entrata, Ziroom, Flow, Mews, QuintoAndar, Property Finder, Lessen, Loft, Qualia, HomeLight, Tujia, Vantaca and Lighthouse.
Another 13 companies have ranges touching or crossing $1 billion, including Guesty, NoBroker, Snapdocs, VTS and several other property technology businesses.
That's a sizable group for an industry that spans everything from parking infrastructure to hotel software. But the distance between a company generating hundreds of millions in recurring revenue and one approaching a billion-dollar valuation on future growth expectations is still enormous.
Are PropTech startup valuations going up again?
PropTech startup valuations are rising again for selected companies, especially in AI and large operating platforms, but the wider funding market is recovering much more slowly.
According to CRETI, global PropTech funding reached $4.53 billion across 231 rounds in the first half of 2026. That was 0.6% below the same period in 2025 and only 2.6% above the first half of 2024.
The more revealing figure is where the money went. Just 11 rounds of at least $100 million accounted for $2.25 billion, almost half of all disclosed funding. Meanwhile, 75 rounds below $5 million represented only 2.8% of the capital raised.
The third quarter followed a similar pattern. CRETI recorded $2.21 billion in funding, with seven large investments accounting for 58% of the total.
EliseAI was a prominent example of this concentration. Its valuation rose from approximately $2.2 billion in August 2025 to $4.0B in September 2026, an increase of about 82%.
Investors are committing much larger amounts to companies they believe can dominate an important part of property operations. Smaller companies still attract funding, but there is little evidence of a broad return to the generous valuations seen during the 2021 boom.
Why is Metropolis worth so much more than other parking startups?
Metropolis has a $5B valuation because it controls a large parking operating network as well as the technology used to automate payments and customer access.
Its biggest move was the May 2024 acquisition of SP Plus, supported by a $1.8 billion financing package. Metropolis gained thousands of parking locations, established commercial relationships and a large existing flow of payments.
That makes it quite different from FlashParking, valued at $700M–$1.1B, whose focus is smart parking management technology.
SpotHero provides another useful comparison. The parking reservation marketplace was acquired by Uber for $617M in April 2026, according to Uber's SEC filing. SpotHero helps customers discover and reserve parking, whereas Metropolis is more directly involved in operating parking infrastructure.
Metropolis can make money from operating contracts, technology deployments and payments. Its existing network also gives it thousands of locations where automation could improve margins without having to acquire a new customer for every transaction.
There is a catch. Running physical infrastructure brings staffing expenses, integration work and considerably more operational complexity than selling software.
The valuation reflects how much investors think Metropolis can earn from automating an already substantial parking business. Improving profitability across that network is the real test.
Is EliseAI becoming the biggest winner in AI-powered PropTech?
EliseAI is currently one of the strongest commercial success stories in AI-powered PropTech, with a $4.0B valuation and annual recurring revenue above $200 million.
Its September 2026 financing raised $350 million, led by Andreessen Horowitz and Bessemer Venture Partners. That followed a $250 million round approximately 13 months earlier, when the business was valued at about $2.2 billion.
According to Fortune's interview with CEO Minna Song, EliseAI had doubled revenue for five consecutive years and exceeded $200 million in ARR in June 2026. The company also reported that its technology served approximately one in six US apartments and had interacted with more than 30 million Americans.
At $4.0B, EliseAI is valued at roughly 20 times its reported ARR milestone. That's expensive, but its revenue growth and customer adoption help explain why investors are willing to pay such a premium.
Its products automate leasing inquiries, maintenance requests, resident communications and renewals. EliseAI has also expanded into healthcare administration, so part of its growth now comes from outside real estate.
Vantaca ($1.25B), Venn ($350M–$650M), Buena ($300M–$450M) and Findigs ($170M–$270M) also apply automation to property operations, but each tackles a narrower or different part of the process.
EliseAI has already turned AI automation into a large recurring-revenue business. Its next challenge is maintaining that growth as established software providers add similar capabilities. And they are moving quickly.
Can EliseAI replace Entrata and other traditional property management software?
EliseAI is becoming a serious competitor to traditional PropTech software, but Entrata's $4.3B valuation reflects how difficult it is to replace the systems landlords already depend on.
Entrata has a long-established position in multifamily property management. In 2022, the company reported serving more than 2.6 million apartment units, following a $507 million investment in 2021.
Its software handles core functions such as accounting, rent payments, resident records and leasing administration.
Entrata has also been developing its own AI products. It acquired Colleen AI in June 2024, expanded its AI-powered maintenance capabilities in 2025, and received a $200 million investment from Blackstone that same year.
So this isn't simply an old software company being challenged by a new AI startup. Both are moving into each other's territory.
A landlord can use EliseAI to automate resident communication while keeping Entrata for accounting and property records. But as AI products take on more work, the boundaries between these systems could gradually disappear.
DoorLoop, valued at $420M–$600M, and Vantaca, at $1.25B, face related questions in their own property management categories.
For now, EliseAI has a clearer path to winning more operating workflows than replacing entire property management systems. Accounting, payments and resident records are deeply embedded in how landlords work, and switching them is a much bigger decision than adding an AI assistant.
Why is Mews worth $2.5 billion?
Mews is valued at $2.5B because it has become a large hotel operating and payments platform, although its financial results show that growth has come with substantial costs.
According to Skift's October 2026 review of corporate filings, Mews generated approximately €291 million in revenue in 2025, up 39% from the previous year.
The company processed around €17 billion in transactions through its platform during the year. However, approximately €219 million of reported revenue came from transaction-related activity, compared with roughly €62 million from core software subscriptions.
That's a big distinction. Mews reports much more revenue than a conventional hotel SaaS provider of similar size might, but processing payments also carries substantial expenses.
Its gross profit was approximately €72 million in 2025, while the company recorded a €111 million operating loss.
Mews has expanded beyond property management into payments, point-of-sale systems, revenue management and other hotel functions. It also completed seven acquisitions across 2024 and 2025, according to Skift's review.
Other hospitality software companies in our ranking include Lighthouse ($1.0B–$1.4B), Cloudbeds ($600M–$900M), Canary Technologies ($550M–$750M) and RoomPriceGenie ($400M–$600M).
Mews has built a broader operating platform than most of these specialists. But with €72 million in gross profit supporting a $2.5 billion valuation, investors are placing a large bet on future profitability. Revenue growth alone won't be enough.
Are Hostaway and Guesty becoming billion-dollar vacation rental companies?
Hostaway and Guesty are close to the billion-dollar mark, with Hostaway valued at $925M and Guesty at $800M–$1.1B.
Both companies sell software to professional vacation rental managers. Their platforms help operators manage listings across booking websites, communicate with guests, coordinate operations and track revenue.
The opportunity is supported by a real change in how vacation rentals are managed. Professional operators increasingly need software to handle multiple properties and booking channels without adding administrative staff at the same rate.
Hostaway's 2026 short-term rental industry report found that 61% of surveyed operators used AI during 2025. Nearly 74% also said their markets had become more competitive, largely because of growing listing supply.
Higher competition pushes operators to improve pricing, response times and operating efficiency. That makes software more useful, particularly for managers running dozens or hundreds of properties.
But the same competition can squeeze the rental managers paying for these tools. If operators lose money or reduce their portfolios, software providers face slower customer growth and potential churn.
Hostaway and Guesty could become standard operating software for professional rental companies. The big question is whether they can increase revenue per customer while keeping those customers profitable enough to stay.
Are real estate marketplaces still worth billions?
Real estate marketplaces can still command billion-dollar valuations, but businesses that rely heavily on property sales are facing a tougher environment than those earning money from recurring services.
QuintoAndar is valued at $2.0B–$2.8B, Property Finder at $1.8B–$2.2B and Loft at $1.3B–$1.9B.
QuintoAndar built its position in Brazil by simplifying residential rentals and later expanding into property sales. Its 2021 financing valued the company at $4 billion, illustrating how much expectations for digital real estate platforms have changed since the previous funding cycle.
Loft combines technology with real estate financing and transactions, while Property Finder concentrates on property discovery in Middle Eastern markets.
The US housing market offers a useful example of why transaction exposure matters. According to the National Association of Realtors, existing-home sales reached an annualized 3.99 million in September 2026, down 2.2% year over year despite a small monthly recovery.
When fewer properties change hands, businesses paid per sale face more pressure unless they can gain market share or charge more for each transaction.
That helps explain the appeal of marketplaces that add mortgages, property management or other ongoing services.
Marketplaces can still be extremely valuable when they dominate local property discovery. But investors increasingly want to know how much money those platforms can make between transactions, rather than betting everything on a stronger housing market.
Why are Brazilian PropTech companies valued so highly?
Brazil has produced several large PropTech companies because digital platforms have found opportunities in rental management, property transactions and real estate finance.
QuintoAndar, valued at $2.0B–$2.8B, is one of the clearest examples. In 2021, the company reported more than 100,000 rental contracts under management and approximately 10,000 new leases per month.
That's serious operating scale. It also helps explain why QuintoAndar became such a major platform: building a comparable rental network from scratch would require substantial investment, local knowledge and customer acquisition.
Loft, valued at $1.3B–$1.9B, developed a different approach involving transactions, financing and services for real estate professionals.
Superlógica, at $210M–$350M, focuses on property management software and payments, giving it more exposure to ongoing property administration.
Together, these businesses show why the Brazilian market can support several valuable companies without all of them competing for precisely the same customers.
There is also a warning in QuintoAndar's valuation history. Its last widely reported funding valuation of $4 billion was achieved during a much stronger global funding market. Its current valuation range is lower, despite the company's established position.
Brazil has already proved it can produce large domestic PropTech businesses. Whether those businesses can regain their former valuations depends much more on profitability and sustainable growth than on market size alone.
Can Indian PropTech startups become worth billions?
Indian PropTech startups are approaching billion-dollar valuations, particularly in brokerage-free property services and integrated real estate transactions.
Square Yards is valued at $900M–$1.1B, while NoBroker is valued at $700M–$1.1B.
Square Yards combines property transactions, mortgage services and technology used by participants in the real estate market. NoBroker has focused on reducing the need for traditional brokerage intermediaries and adding related services for landlords, tenants and homeowners.
Managed accommodation is another important category. Stanza Living is valued at $290M–$360M, while ZoloStays is valued at $130M–$230M.
These companies benefit from India's large urban housing market and the complexity of arranging rentals, purchases and accommodation.
However, their expansion opportunities are quite different. A property marketplace depends on local regulations, consumer behavior and relationships with agents. A specialized software platform can sometimes enter another country with less operational rebuilding.
India is already producing large domestic PropTech businesses. More unicorns look achievable, although international expansion will be harder for transaction and accommodation operators than for companies selling reusable software.
Are European PropTech startups falling behind the US?
European PropTech startups trail the largest US companies in our ranking, but Europe has produced several valuable businesses in hospitality software, flexible accommodation and real estate operations.
Mews, based in the Netherlands, is valued at $2.5B. The UK's Lighthouse is valued at $1.0B–$1.4B, France's IAD France at $850M–$1.3B and Finland's Hostaway at $925M.
Germany also has Limehome ($450M–$750M) and AI-focused property operators such as Buena ($300M–$450M).
France's Deepki ($400M–$650M) and Stonal, acquired by Aareon in 2024, represent another European strength: software for managing property data, sustainability and asset operations.
One reason these businesses have an opening is regulation. The revised EU Energy Performance of Buildings Directive entered into force in 2024, with a general implementation deadline in May 2026.
In July 2026, the European Commission opened infringement procedures against all 27 member states for incomplete implementation.
That creates ongoing work for property owners and managers dealing with energy performance, building records and renovation requirements.
Europe has fewer companies at the very highest valuation levels, but hospitality technology and building software are areas where European startups have developed real advantages. Both also offer opportunities well beyond their home countries.
Can energy-saving PropTech startups become the next unicorns?
Energy-saving PropTech companies have a credible path to billion-dollar valuations because commercial property owners can measure the money saved on energy bills, equipment and building operations.
Redaptive is currently valued at $750M–$1.1B, while GridPoint is valued at $480M–$720M and PassiveLogic at $450M–$600M.
Other companies include Deepki ($400M–$650M), Runwise ($370M–$550M), Measurabl ($270M–$450M), Infogrid ($90M–$210M) and Noda ($170M–$330M).
Their business models vary. Redaptive helps finance building energy infrastructure, GridPoint and Runwise focus on energy optimization, and PassiveLogic develops autonomous building controls. Deepki and Measurabl specialize in sustainability data.
Europe provides one measurable source of demand. According to the European Commission, buildings account for roughly 40% of EU energy consumption, and the annual building renovation rate is only around 1%.
The revised Energy Performance of Buildings Directive is intended to accelerate renovation and introduce stronger requirements for poorly performing buildings.
These companies still face commercial obstacles. Equipment installation, integration with existing systems and long procurement cycles can slow growth.
Redaptive also illustrates why financing totals need context: its reported $2.1B financing exceeds its valuation range because the financing includes debt or credit facilities, which are different from equity funding.
Energy technology could produce more PropTech unicorns, particularly where savings can be verified across large portfolios. The tougher business model is one that needs substantial new financing for every deployment. That makes rapid scaling expensive.
Why do some PropTech startups have valuations below the money they raised?
Some PropTech startups are now valued below their reported cumulative funding because funding totals reflect historical capital raised, while valuations reflect what the business may be worth today.
Redaptive's $750M–$1.1B valuation is below its reported $2.1B financing total, largely because its financing includes debt or credit facilities.
Orchard presents a more direct contrast. The company is valued at $105M–$135M despite reporting $285M in historical funding, as its homebuying model has faced difficult property market and financing conditions.
AvantStay is valued at $620M–$780M against $739M in reported financing, which may include debt. Its valuation range therefore overlaps the financing total rather than sitting entirely below it.
The distinction is especially important for accommodation operators and real estate fintech companies, where credit facilities, property financing and operational capital can make reported funding look unusually large.
A lower current valuation can reflect weaker growth expectations, changes in market conditions, financial obligations or a revised assessment of the business. It doesn't automatically mean every dollar invested has been lost.
Are investors still backing homebuying and real estate transaction startups?
Investors still back real estate transaction technology, but housing market conditions make it harder for these startups to justify rapid growth expectations.
HomeLight is valued at $1.2B–$1.7B, Qualia at $1.4B–$1.6B and Roofstock at $900M–$1.3B.
Other companies include Snapdocs ($600M–$1.1B), Homeward ($750M–$900M), Habi ($650M–$1.1B) and Clikalia ($350M–$550M).
Their business models have different levels of exposure to housing activity. Homeward uses financing to help buyers make cash-backed offers, while Snapdocs and Qualia provide technology supporting mortgage and property closings.
The US market has been particularly difficult for transaction-dependent companies. September 2026 existing-home sales were down 2.2% year over year, and the National Association of Realtors reported an average 30-year mortgage rate of 6.86% for the month.
High borrowing costs reduce the number of households able or willing to purchase property. That affects how frequently transaction platforms can earn fees.
Software businesses serving existing financial and title workflows may be better protected than companies whose revenue depends directly on buying and selling homes.
There is still room for strong companies in this category, especially those that lower transaction costs or make closings faster. But expecting a recovery in housing sales to solve every startup's growth problems would be a risky bet.
Have PropTech acquisitions produced big exits for investors?
PropTech acquisitions have produced substantial exits, with Uber's $617M acquisition of SpotHero providing one of the clearest recent examples.
Uber completed the acquisition on April 16, 2026. Its SEC filing confirms the $617 million cash purchase price and explains that SpotHero's parking reservation technology will become part of Uber's consumer offering.
The acquisition makes sense for Uber. It already serves people traveling by car, and parking reservations extend what customers can do inside its app.
Other companies in the acquired or public section of our ranking include Cherre, JustPark, Rive, Jetty and Mint House.
However, their valuation ranges should be interpreted carefully. Unlike SpotHero's disclosed acquisition price, several are based on comparable transactions or company valuations rather than confirmed transaction consideration.
For example, Cherre is listed at $230M–$370M and JustPark at $115M–$250M. Those figures help indicate the scale of these businesses, but they should not be mistaken for verified cash proceeds from their transactions.
An acquisition also doesn't tell us exactly how much early investors earned. Debt repayment, dilution and shareholder preferences can materially change the final distribution.
Still, the SpotHero transaction shows that established technology groups are willing to pay hundreds of millions of dollars for real estate technology that strengthens an existing customer relationship. Parking, payments and property operations offer plenty of opportunities for similar deals.
Are PropTech startups actually worth their valuations today?
The highest PropTech startup valuations are credible in some cases, but businesses with measurable recurring revenue and operating scale have a much stronger case than those valued mainly through comparisons.
EliseAI offers one of the clearest examples. The company has a $4.0B valuation, more than $200 million in reported ARR, and widespread adoption across residential property operations. Its valuation is demanding, but its commercial growth gives investors something concrete to measure.
Mews is also a substantial operating business, valued at $2.5B, with €291 million in 2025 revenue. Yet its accounts reveal high payment processing costs and a €111 million operating loss. Its future profitability is therefore much less certain than its revenue growth alone might suggest.
Metropolis, valued at $5B, has thousands of operating locations and billions in annual payment activity. Investors are betting that its technology can make that network more profitable over time.
Other categories face a harder test. Property marketplaces and transaction-focused companies depend partly on housing activity, while accommodation operators can face high operating costs and financing needs.
The strongest PropTech businesses tend to control an important, recurring part of property operations. AI automation, integrated hotel software and large infrastructure networks currently offer some of the clearest examples.
The next wave of PropTech unicorns will likely come from companies that can demonstrate significant revenue growth while helping property owners and operators reduce costs. There's room for several different winners, but investors are becoming much less forgiving of businesses whose valuations depend mainly on what they might achieve years from now.
Our methodology
This analysis ranks the most valuable independent startups in the PropTech market as of November 2026. We cover companies operating in property management software, real estate transactions, marketplaces, hospitality technology, building infrastructure, parking, energy management and related property services. Established corporate groups and subsidiaries of larger companies are excluded from the private startup ranking.
We assessed valuations using completed funding rounds, company announcements, investor disclosures, regulatory filings, revenue and annual recurring revenue figures, operating performance and comparable transactions. Recent disclosed funding valuations received the greatest weight. Where current transaction prices were unavailable, we used relevant financial and operating indicators to estimate a reasonable valuation range, taking account of growth, business maturity, geography and industry conditions.
Valuations are expressed as single figures where recent transactions support a specific amount, and as ranges where the company's current value is less certain. Historical funding valuations were considered alongside more recent business developments rather than carried forward automatically. Reported cumulative funding was also assessed separately from equity valuation, particularly for businesses using debt, credit facilities or property financing.
Acquired and publicly traded companies are treated separately from independent private startups. For completed acquisitions, we use disclosed purchase prices when available. Where transaction consideration has not been publicly confirmed, valuation ranges reflect relevant company and transaction comparisons rather than verified acquisition proceeds.
Key sources include Metropolis' SP Plus acquisition announcement, EliseAI's September 2026 financing announcement, Fortune's reporting on EliseAI's revenue and valuation, CRETI's H1 2026 global PropTech venture report, CRETI's Q3 2026 funding analysis, Entrata's corporate announcements, Skift's analysis of Mews' financial performance, Hostaway's 2026 short-term rental industry report, the National Association of Realtors' September 2026 housing report, Freddie Mac's mortgage rate data, QuintoAndar's historical financing and operating figures, the European Commission's Energy Performance of Buildings Directive documentation, the European Commission's July 2026 implementation update, and Uber's SEC filing confirming the SpotHero acquisition.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us