Synthetic Biology: what are the top startups?
Whether you're building or investing in the synthetic biology market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Asimov is the top synthetic biology startup today, followed by Cradle, Profluent, and Antheia. These four companies lead for different reasons: pharmaceutical manufacturing partnerships, AI software adoption, gene-editing technology, and actual industrial production.
Asimov has the strongest overall commercial position. Its partnerships with Lonza, Minaris, and AGC Biologics cover several pharmaceutical manufacturing processes, giving it multiple routes into the drug-production supply chain rather than dependence on one product.
Cradle is making a compelling case for AI protein engineering as a software business. More than 50 disclosed R&D programs and multiyear pharmaceutical relationships suggest customers are moving beyond experiments and integrating its platform into regular research workflows.
Profluent may have greater technological upside than either company. Its partnership with Eli Lilly includes up to $2.25 billion in potential milestones, although most of that amount depends on future achievements rather than revenue already earned. Milestone payments that depend on future results carry risks we rate in our synthetic biology market report.
Antheia has crossed a barrier that defeats many industrial biology startups: it has manufactured and delivered a pharmaceutical ingredient commercially. Its thebaine shipments and 116,000-liter fermentation operations provide unusually concrete evidence of production-scale execution.
Ansa Biotechnologies and Culture Biosciences are less dependent on scientific breakthroughs becoming blockbuster products. Ansa sells increasingly long synthetic DNA, while Culture has supported more than 20,000 bioreactor runs, making both potential infrastructure suppliers to the wider industry.
Synthetic biology investment is recovering, but the money is concentrating in fewer companies. Reported financing rose approximately 79.5% in the latest comparable period, while deal counts declined and the median disclosed round increased about 67%.
The publicly traded companies offer a useful warning. Twist Bioscience grew fiscal revenue approximately 54% between 2023 and 2025, while Ginkgo Bioworks saw reported revenue fall around 32%. Broad platform ambitions have not automatically translated into superior financial performance.
The strongest agricultural and research-tool companies have their own evidence of adoption. Pivot Bio reached approximately five million acres of farmland in 2023, while bit.bio has built a commercial portfolio of programmable human cells. Neither has disclosed enough recent financial information to establish profitability.
The riskiest opportunities remain in genetic medicine and ambitious frontier biology. Mammoth Biosciences, Profluent, and Colossal Biosciences could create substantial value, but therapeutic success, regulatory approval, and viable business models are still major uncertainties.
Our preference is for companies selling technologies that customers need repeatedly. Asimov and Cradle currently offer the strongest combination of commercial validation and growth potential, while Antheia is the standout example of synthetic biology reaching real industrial production.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

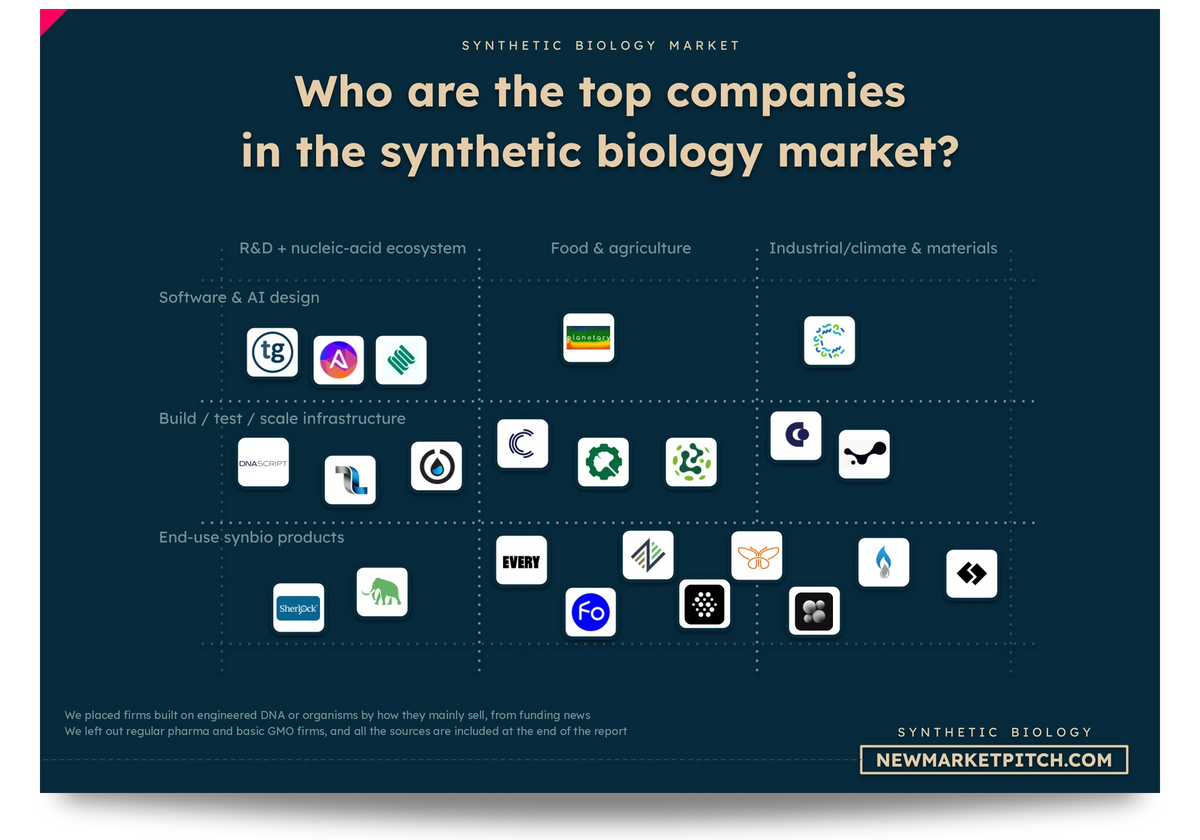
In our report covering the synthetic biology market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Which synthetic biology startups are leading right now?
Asimov is our top synthetic biology startup today, with Cradle, Profluent, and Antheia close behind for very different reasons.
Asimov has built a business around helping pharmaceutical companies engineer cells and manufacture complex medicines. Cradle is bringing AI protein-design software into major pharmaceutical R&D teams. Profluent is developing AI-designed gene-editing tools, while Antheia has already manufactured and delivered pharmaceutical ingredients using engineered biological systems.
Synthetic biology covers very different businesses. Some companies sell DNA or research software, others manufacture ingredients, and others develop experimental medicines. A startup with a promising drug candidate cannot be judged the same way as a supplier handling thousands of customer experiments. Because DNA tools, ingredients and medicines sit side by side here, we spell out what counts as synthetic biology and what does not in our report on synthetic biology.
We therefore give more weight to commercial adoption, partnerships that involve actual development work, and products that customers can already buy. Valuations and fundraising still tell us something, but they are weaker evidence of whether the underlying business works.
Asimov currently stands out for the variety of customers and manufacturing problems it serves. Cradle has impressive software adoption, with more than 50 R&D programs disclosed in December 2025. Profluent secured major agreements with Eli Lilly and BioMarin during 2026. Antheia, meanwhile, has reached commercial pharmaceutical production, a milestone many industrial biology startups never achieve.
| Startup | Main specialty | Strongest evidence | Our assessment |
|---|---|---|---|
| Asimov | Cell engineering and biomanufacturing | Lonza, Minaris, AGC partnerships | Best overall |
| Cradle | AI protein-engineering software | 50+ R&D programs | Strongest software adoption |
| Profluent | AI-designed proteins and gene editors | Lilly and BioMarin agreements | Major technology contender |
| Antheia | Biosynthetic pharmaceutical ingredients | Commercial thebaine deliveries | Industrial commercialization leader |
| Ansa Biotechnologies | Long DNA synthesis | Commercial DNA products up to 50 kb | DNA infrastructure leader |
| Culture Biosciences | Automated fermentation and bioprocessing | 20,000+ bioreactor runs | Proven infrastructure adoption |
| Mammoth Biosciences | CRISPR-based genetic medicines | Regeneron collaboration | Strong therapeutic potential |
| Pivot Bio | Engineered microbial fertilizers | Products used on 5M acres in 2023 | Agricultural deployment leader |
| bit.bio | Programmable human cells | Commercial ioCells portfolio | Strong cell-engineering specialist |
| Arzeda | Engineered industrial enzymes | Unilever commercial development | Applied protein-engineering leader |
| Pow.Bio | Continuous fermentation | 3,000-liter validation | Manufacturing challenger |
Is synthetic biology attracting more investment again?
Synthetic biology funding is recovering, but investors are backing fewer companies with larger checks.
New Market Pitch's September 2026 analysis identified $1.327 billion in financing, approximately 79.5% more than during the comparable period a year earlier. The number of deals, however, declined from 68 to 64, while the number of funded companies fell from 67 to 62.
The median disclosed round increased from approximately $8.08 million to $13.52 million, a jump of roughly 67%. And the recovery was not driven entirely by enormous transactions: excluding rounds above $50 million, funding was still approximately 35% ahead of the comparable 2025 period.
Dealroom's October 2026 synthetic biology list also identified 50 companies with approximately $32 billion in cumulative funding and 25 unicorns. That gives an idea of the capital involved, although Dealroom's classification includes established companies and businesses working in adjacent biotechnology markets.
Investors clearly see opportunities in AI protein design, pharmaceutical manufacturing, and biological infrastructure. Whether those bets produce profitable businesses remains much less certain.

Our research about synthetic biology gets updated several times a month, so you always get the latest view of where things stand.
Is Asimov the strongest synthetic biology startup overall?
Asimov currently has the strongest overall position in synthetic biology because its cell-engineering technology is being adopted across several pharmaceutical manufacturing processes.
The Boston-based company develops engineered cell lines, genetic tools, and software that help drug developers manufacture biological medicines. Its CHO Edge system focuses on antibody production, while its other platforms support viral-vector manufacturing for gene therapies.
Asimov's partnership activity in 2026 shows how broadly the company is expanding. It announced collaborations with AGC Biologics, Score Pharma, Minaris, and Lonza, covering antibody development, adeno-associated virus production, and lentiviral-vector manufacturing.
The Lonza agreement, announced in October 2026, combines Asimov's genetic design and cell-line technologies with Lonza's manufacturing expertise. The Minaris partnership, announced in September, integrates OXGENE technology into Asimov's AAV producer cell lines.
These are different production processes involving established manufacturing specialists. Asimov has several routes into the pharmaceutical supply chain, reducing its dependence on the success of any single therapeutic technology.
Asimov also reported that its work with Sidewinder Therapeutics produced a cell line exceeding 10 grams per liter in a fed-batch process. That's a meaningful manufacturing result, although it doesn't establish that Asimov consistently outperforms competitors across different antibodies.
We still lack public revenue, margin, and customer-retention figures. Even so, the company's expanding set of manufacturing relationships gives us more confidence in its commercial position than another large financing round would.
Is Cradle becoming the leading AI software company for biology?
Cradle is one of the clearest leaders in AI protein-engineering software, and its growing pharmaceutical customer base suggests the technology is becoming part of real research workflows.
The Amsterdam-based startup helps scientists design and improve proteins, including antibodies and enzymes. Pharmaceutical companies can use its software to explore new molecular designs and reduce the number of laboratory experiments needed to optimize them. Software that cuts the lab experiments needed to tune a protein is one of the technologies we sort by maturity in our report covering the synthetic biology market.
In December 2025, Cradle reported more than 50 R&D programs and customers representing six of the world's 25 largest pharmaceutical companies.
It also reported development speed improvements of up to 12 times and cost reductions of up to 90% in certain customer workflows. Those are company-reported results from specific applications, so we shouldn't assume every customer achieves comparable improvements.
More convincing is the progression from initial projects to longer commercial relationships.
In January 2026, Bayer announced a three-year collaboration to integrate Cradle's software into its antibody research. Hansa Biopharma followed in October, adopting Cradle's platform to help develop treatments for autoimmune diseases.
Cradle has also said that several proof-of-concept projects expanded into multiyear commercial commitments. Customers appear to be finding enough value to keep using the software after their initial experiments.
Its main unanswered question is financial: without disclosed revenue or retention figures, we cannot yet compare its business performance with established enterprise software companies.

In our market report about synthetic biology, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Profluent the most promising AI-driven synthetic biology startup?
Profluent is one of the most exciting AI-driven synthetic biology startups today, particularly in gene editing, but its commercial success is still largely ahead of it.
The company trains generative AI models to design proteins, including enzymes capable of editing DNA. Its OpenCRISPR initiative demonstrated an AI-designed genome editor, showing that these models can produce functional biological tools.
Profluent's pharmaceutical partnerships have become much more substantial.
In April 2026, Eli Lilly announced a collaboration focused on AI-designed recombinases, enzymes that can make precise changes to DNA. The agreement carries up to $2.25 billion in potential milestone payments, alongside an upfront payment, research funding, and possible royalties.
In September, BioMarin announced another collaboration with Profluent to design new medicines using AI.
We shouldn't mistake the Lilly deal's $2.25 billion headline for cash already received. Most of that amount depends on future development and commercial milestones.
Still, Lilly and BioMarin provide important validation for Profluent's technology. Both companies operate in areas where better biological design tools could lead to valuable treatments.
Profluent has shown that its technology can attract serious pharmaceutical partners. Proving clinical effectiveness and generating repeatable commercial income are the next hurdles.
Has Antheia actually made synthetic biology work at industrial scale?
Antheia has already achieved something many industrial synthetic biology startups are still chasing: manufacturing and delivering a pharmaceutical ingredient produced through engineered biology.
The California company develops biosynthetic production methods for complex pharmaceutical ingredients. These processes can provide alternatives to traditional agricultural supply chains or chemical manufacturing.
In October 2024, Antheia announced its first commercial shipment of thebaine, an ingredient used to manufacture several pharmaceutical drugs.
That was a major step. Antheia had fulfilled a commercial customer order and obtained the approvals needed to supply the product. Plenty of synthetic biology companies have impressive laboratory results without getting anywhere near that point.
Antheia subsequently raised $56 million in Series C financing in June 2025 and expanded its pharmaceutical manufacturing relationships, including work with Phlow.
The company has described production operations at the 116,000-liter scale and identified a pipeline of more than 70 potential starting materials and active pharmaceutical ingredients.
The remaining challenge is cost. We know Antheia can manufacture and deliver at least one commercial pharmaceutical ingredient. We don't yet know whether it can maintain attractive margins across a much larger product portfolio.

In our document detailing everything you need to know about synthetic biology, you will always find fresh funding data, taken straight from our own verified funding database.
Is Ansa Biotechnologies challenging the established DNA synthesis market?
Ansa Biotechnologies is becoming a serious competitor in DNA synthesis because it has made much longer DNA products commercially available in a relatively short period.
The company uses an enzymatic synthesis approach instead of relying exclusively on conventional chemical DNA manufacturing.
Its progress is easy to measure.
Ansa began offering commercial DNA products up to 600 base pairs in July 2024. It subsequently expanded to 5-kilobase clonal DNA products, followed by products up to 7.5 kilobases in April 2025.
By October 2025, Ansa had introduced commercially available XL clonal DNA products up to 50 kilobases. That was approximately 6.7 times longer than its earlier 7.5-kilobase offering.
The company also announced a partnership with Integrated DNA Technologies in January 2026.
IDT is already an established supplier of synthetic DNA, making the agreement particularly relevant. Ansa could potentially reach customers through existing distribution relationships rather than building an entirely new market.
Twist Bioscience shows how large that opportunity can become. The publicly traded DNA synthesis company generated $376.6 million in fiscal 2025 revenue.
Ansa's next test is whether longer DNA products can be produced consistently at competitive prices and delivery times.
Could Culture Biosciences become essential infrastructure for synthetic biology?
Culture Biosciences is already becoming an important synthetic biology infrastructure supplier, with thousands of experiments completed through its automated bioreactor systems.
The company develops connected bioreactors and software that help scientists manage fermentation experiments and improve production processes.
Culture reports more than 20,000 completed bioreactor runs, over 70 customers, and a fleet exceeding 350 bioreactors. Seventy customers running bioreactors point to a real need; we cover who they are and which problems they would pay to solve in our synthetic biology market report.
That's a substantial amount of real customer experimentation. Dividing the reported runs by the number of customers gives approximately 286 historical runs per customer, although actual usage will vary considerably between organizations.
In December 2025, Culture announced Series C financing to expand its Stratyx 250 bioreactor and AI-powered Console platform.
The company is interesting because pharmaceutical developers, industrial biotechnology firms, and other biological manufacturers all need ways to test and improve production processes.
Its customers may be developing completely different products, but they encounter many of the same challenges when moving from experiments toward manufacturing.
Culture has demonstrated meaningful adoption of its infrastructure. What remains unclear is the financial breakdown between equipment sales, software, and services, as well as how profitable those activities can become.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the synthetic biology market, we look at what broke startups before you, so you don't repeat it.
Is Mammoth Biosciences still one of the leaders in CRISPR?
Mammoth Biosciences remains one of the leading private CRISPR companies, particularly because its gene-editing technology has attracted a major pharmaceutical partner.
The company was founded by scientists including Jennifer Doudna and Trevor Martin. It develops CRISPR-based systems for genetic medicines and molecular diagnostics.
Its collaboration with Regeneron is the most important commercial evidence.
The agreement included $100 million in upfront and equity investment, with potential development, regulatory, and commercial milestone payments of up to $370 million per target.
Those payments depend on future achievements, but the structure shows that Regeneron sees opportunities for Mammoth's technology across multiple therapeutic applications.
Mammoth's approach includes compact CRISPR systems designed to address some of the difficulties involved in delivering gene-editing machinery into cells.
Of course, an effective editing enzyme still needs to reach the correct tissue and operate safely before it can become a practical treatment.
Mammoth's position is less proven commercially than Asimov's or Cradle's because the crucial tests now involve clinical outcomes, delivery performance, and eventual treatment approval.
Is Pivot Bio the clearest agricultural synthetic biology success?
Pivot Bio has some of the strongest evidence of real agricultural deployment in synthetic biology, although its current commercial performance remains difficult to assess.
The company develops engineered microorganisms that help crops obtain nitrogen, potentially reducing the amount of conventional fertilizer farmers need.
According to Pivot Bio, its products were used on approximately five million acres of US farmland in 2023.
That's substantial field deployment for a technology based on engineered microbes.
Pivot Bio also raised $430 million in Series D financing in 2021, reflecting investor interest in alternatives to traditional nitrogen fertilizers.
Agriculture brings different commercial challenges from pharmaceutical research. Farmers need products that reliably improve their economics, and results can vary with weather, soil conditions, crop types, and farming practices.
Five million acres demonstrates that Pivot Bio reached commercial farming at a meaningful scale. But the figure is historical, and public information doesn't establish how acreage, repeat purchases, or profitability have evolved since then.
Is bit.bio turning programmable cells into real products?
bit.bio has already turned its programmable cell technology into a commercial product portfolio, making it one of the stronger synthetic biology startups focused on research tools.
The Cambridge-based company uses genetic programming to turn induced pluripotent stem cells into specific human cell types.
Its opti-ox technology is designed to produce cells with consistent identities, helping researchers conduct experiments using more standardized biological materials.
These cells can be used to study diseases, test potential drugs, and investigate toxicity.
During 2026, bit.bio expanded its offerings through a cardiomyocyte partnership with myriamed, CRISPR screening services, and the launch of ioAstrocytes 2.0.
The company is gradually building a broader collection of cell products and associated research services.
bit.bio also has the advantage of selling research products without needing to develop and obtain approval for an entire medicine.
We still lack enough public revenue information to judge how quickly the business is growing. But bit.bio has moved well beyond the stage of promising to manufacture programmable cells; customers can already buy and use them.

In our research about synthetic biology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Could Arzeda become a major supplier of AI-designed industrial enzymes?
Arzeda has a credible opportunity to become a major industrial enzyme supplier because its computational protein-design technology is already being used in consumer-product development.
The Seattle company combines computational protein design, laboratory experiments, strain engineering, and manufacturing development to create enzymes for industrial applications. Which synthetic biology business models make money, enzyme sales included, is something we compare in our synthetic biology market report.
Its relationship with Unilever provides one of the clearest examples.
The companies began collaborating in 2021. By June 2023, they had developed new enzymes in less than two years, a process Arzeda described as five times faster than the previous approach.
Those enzymes were being developed for applications in categories such as detergents and personal care.
It's an attractive market because successful enzymes can potentially improve products that already have established customers and distribution networks.
A manufacturer doesn't need to persuade consumers to adopt an entirely unfamiliar technology if an engineered enzyme can simply make an existing product work better or cost less to produce.
However, Arzeda has not disclosed enough product-level revenue to establish the commercial value generated by its work with Unilever.
Is Pow.Bio solving synthetic biology's manufacturing problem?
Pow.Bio is tackling one of synthetic biology's biggest manufacturing challenges, and its continuous fermentation technology has already been demonstrated at the 3,000-liter scale.
The startup develops processes designed to keep fermentation systems operating continuously, rather than relying entirely on separate production batches.
That approach could help manufacturers use their equipment more efficiently and reduce production costs.
According to investor Synthesis Capital, Pow.Bio has validated its technology at 3,000 liters and secured its first major customer agreements.
In June 2026, the World Economic Forum also selected Pow.Bio for its Technology Pioneers program.
The more important milestone is the production-scale demonstration. Many synthetic biology processes work in laboratory fermenters but become difficult or expensive when scaled up.
Still, 3,000 liters is a long way from proving reliable economics in much larger industrial facilities. Contamination, product recovery, feedstock consumption, and operating stability can all affect the final cost of production.
Pow.Bio has made credible technical progress, but Antheia currently provides stronger evidence of commercial-scale manufacturing and actual product deliveries.
Are AI protein-design startups becoming serious synthetic biology businesses?
AI protein-design startups are starting to build serious businesses, and Generate:Biomedicines shows how far the technology can progress toward actual treatments.
Generate uses generative AI and laboratory testing to design protein-based drugs. The company reports having designed, built, and tested more than 42,000 proteins.
Its investigational antibody GB-0895 has advanced into Phase 3 clinical studies, putting Generate further along clinically than many AI protein-design businesses.
In October 2026, Generate also announced a collaboration with Zealand Pharma focused on new protein treatments for obesity and other metabolic diseases.
The agreement provides $30 million upfront, up to $35 million in early preclinical milestones, and potential additional milestone payments bringing the total to nearly $1.2 billion, plus royalties.
Generate will lead research through candidate selection, while Zealand Pharma will handle later clinical development, regulatory submissions, and worldwide commercialization.
Generate has also become publicly traded on Nasdaq under the ticker GENB, so we would now use it as a benchmark for private synthetic biology startups rather than include it in a strictly private-company ranking.
Cradle, Profluent, and Arzeda show how differently AI protein design can be commercialized. Cradle sells software that helps scientists optimize proteins. Profluent designs gene-editing tools and licenses technology through pharmaceutical partnerships. Arzeda focuses on industrial enzymes.
Their financial risks vary considerably. Cradle can potentially earn revenue from repeated software usage without owning the medicines its customers develop. Generate can capture substantial value from a successful therapeutic, but drug development involves years of clinical trials and regulatory review. Arzeda needs its enzymes to perform reliably and remain economical at industrial production volumes.
As for Profluent, its agreements with Lilly and BioMarin show how valuable AI-designed gene-editing capabilities could become, even before commercial treatments are approved.

If you build or invest in the synthetic biology market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Are the biggest synthetic biology companies actually the most successful?
The biggest synthetic biology companies have not necessarily been the most successful, and the contrasting results of Ginkgo Bioworks and Twist Bioscience make that clear.
Ginkgo became one of the industry's best-known synthetic biology platforms, backed by substantial investment and ambitious plans to make biological engineering more accessible. Ginkgo shows how a well-funded platform can still stall, and we study what the startups that failed or stalled had in common in our market report about synthetic biology.
Its financial results have been disappointing.
According to Ginkgo's SEC filings, total revenue declined from approximately $251.5 million in 2023 to $227 million in 2024 and $170.2 million in 2025.
That's a cumulative decrease of approximately 32% over two years.
There is an important accounting detail. Some reported revenue came from noncash recognition associated with terminated customer agreements. Excluding those releases, cell-engineering revenue was approximately $129 million in 2024 and $125 million in 2025, suggesting a smaller decline in that activity than headline figures might imply.
Nevertheless, Ginkgo has been restructuring and reducing its operating footprint while shifting attention toward autonomous laboratories.
Twist Bioscience has followed a different trajectory.
Its fiscal revenue increased from approximately $245.1 million in 2023 to $313 million in 2024 and $376.6 million in 2025, an increase of roughly 54% over two years.
Twist's gross margin also rose from 42.6% to 50.7% between fiscal 2024 and 2025.
We can draw a fairly strong conclusion from these two trajectories: selling standardized biological products with measurable customer demand has produced clearer financial progress than Ginkgo's broader platform strategy.
Ginkgo's experience should make us cautious about startups promising to transform entire industries before proving that customers will pay enough to support the business.
| Company | Reported evidence | What it tells us |
|---|---|---|
| Twist Bioscience | $376.6M FY2025 revenue | Product sales at substantial scale |
| Ginkgo Bioworks | $170.2M 2025 revenue, down 25% | Large platform facing restructuring |
| Cradle | 50+ R&D programs | Broad software adoption |
| Culture Biosciences | 20,000+ bioreactor runs | Substantial cumulative customer usage |
| Antheia | Commercial thebaine shipments | Industrial production reaching customers |
| Pivot Bio | 5M acres in 2023 | Meaningful agricultural deployment |
| Ansa Biotechnologies | Commercial DNA up to 50 kb | Rapid expansion of product capabilities |
| Generate:Biomedicines | Phase 3 clinical program | Advanced therapeutic development |
Which synthetic biology startups are most likely to survive and keep growing?
Asimov, Cradle, Ansa Biotechnologies, and Culture Biosciences look particularly well positioned to build lasting businesses because they solve problems that customers encounter repeatedly.
Asimov helps pharmaceutical manufacturers develop productive cell lines. Cradle provides tools for protein engineering. Ansa supplies synthetic DNA, while Culture supports fermentation experiments and process development.
These services can remain valuable regardless of which specific therapeutic, engineered organism, or industrial ingredient becomes successful.
They also offer a potential advantage when it comes to financing growth.
Cradle distributes software, Ansa sells DNA products, and Asimov works with established manufacturing partners such as Lonza. None of these companies necessarily needs to build an entirely new industrial manufacturing facility for every customer application.
Antheia and Pow.Bio operate closer to the physical production process. Their economics are therefore more sensitive to equipment utilization, manufacturing yields, energy consumption, and operating costs.
Pivot Bio faces agricultural distribution costs and the challenge of convincing farmers to keep purchasing its products.
We cannot yet determine which company has the healthiest finances because private revenue, profitability, and cash-burn figures are rarely disclosed. Still, Asimov and Cradle have particularly convincing customer-adoption evidence.

In our document detailing everything you need to know about synthetic biology, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Which synthetic biology startups have the biggest upside but also the most risk?
Profluent, Mammoth Biosciences, and Colossal Biosciences are among the highest-upside synthetic biology startups, although their future value depends on ambitious scientific and commercial outcomes.
Profluent could become an important supplier of AI-designed gene-editing tools if its technology works across multiple therapeutic applications.
Mammoth has a similar opportunity through its CRISPR systems, with Regeneron's investment providing a credible pharmaceutical development partnership.
Colossal is a more unusual case.
The de-extinction company attracted a reported $10.2 billion valuation in 2025. In July 2026, TechCrunch reported that Colossal was discussing fundraising at a potential valuation between $20 billion and $30 billion.
That range described reported financing discussions rather than a confirmed completed transaction.
Colossal's scientific work includes genome engineering and reproductive technologies, alongside related businesses such as Form Bio.
The difficulty is connecting those capabilities to a valuation of tens of billions of dollars. Public financial information does not currently provide enough detail to demonstrate commercial revenue on that scale.
Colossal may develop technologies with valuable applications beyond de-extinction. But at this stage, we would be far more confident in the commercial position of Asimov, Cradle, or Antheia than in a valuation based heavily on future technological possibilities.
Profluent and Mammoth also face substantial risks, particularly around clinical development. Their pharmaceutical partnerships offer more concrete evidence of potential economic value, but neither has yet proved that its gene-editing technology can generate sustained revenue from approved treatments.
So, what are the top synthetic biology startups today?
Asimov is our number-one synthetic biology startup right now, followed by Cradle, Profluent, and Antheia. Ansa Biotechnologies and Culture Biosciences are particularly strong infrastructure companies, while Mammoth Biosciences, Pivot Bio, bit.bio, Arzeda, and Pow.Bio complete our leading group.
Asimov deserves first place for combining useful technology with adoption across several pharmaceutical manufacturing processes. Its work with Lonza, Minaris, AGC Biologics, and other developers provides a broader commercial base than most private synthetic biology companies can currently demonstrate.
Cradle comes next because its AI protein-engineering software is already being used by major pharmaceutical companies. Profluent has greater technological upside in certain applications, but its commercial progress depends more heavily on future development milestones.
Antheia deserves a prominent position because it has actually delivered commercially manufactured pharmaceutical ingredients, something that remains surprisingly rare among ambitious industrial synthetic biology startups.
We also see significant potential in Ansa and Culture. Both provide technologies that many other biological companies need, giving them opportunities to grow alongside the wider industry.
The financial experience of Ginkgo Bioworks and Twist Bioscience makes us particularly cautious about using funding or valuations as measures of success.
For now, Asimov and Cradle make the strongest cases for durable commercial leadership. Profluent could become a much bigger company if its technology succeeds in genetic medicine, while Antheia offers one of the clearest examples of synthetic biology reaching industrial production.
Our methodology
This analysis identifies the leading private synthetic biology startups by comparing technological progress, commercial adoption, partnership quality, manufacturing execution, and long-term business viability. We assess companies according to their actual business models rather than ranking them solely by funding, valuations, or scientific ambitions.
We place greater weight on evidence that technology has moved beyond laboratory demonstrations. For software companies, that includes paying customers, recurring research programs, and multiyear partnerships. For manufacturing companies, we examine production scale, customer deliveries, and repeatability. For genetic medicine developers, we consider pharmaceutical agreements, clinical progress, and the milestones still needed before commercialization.
We also distinguish announced deal values from realized revenue. Potential milestone payments under pharmaceutical partnerships are treated as conditional opportunities, while company-reported operating figures such as bioreactor runs, production volumes, and customer programs are used as evidence of activity rather than proof of profitability. Historical deployment figures are kept separate from current commercial performance.
Publicly traded companies provide financial context for the private-company ranking. We use Twist Bioscience and Ginkgo Bioworks to examine revenue growth, gross margins, and the contrasting performance of product-focused and broad-platform business models. Generate:Biomedicines is also considered a relevant benchmark for AI protein design and therapeutic development rather than a private startup.
Our final ranking gives the greatest weight to demonstrated commercial execution, breadth of adoption, and the ability to generate value across multiple customers or applications. We then consider technological differentiation, market size, capital requirements, and the remaining scientific or operational risks. This produces a comparative assessment of business strength, not a prediction that every highly ranked company will become profitable.
Key sources include Asimov's collaboration with Lonza, its Minaris partnership, and its AGC Biologics agreement for pharmaceutical manufacturing adoption; Cradle's reported 2025 commercial progress and Bayer's three-year collaboration announcement for AI protein-engineering software; and Profluent's Lilly agreement, alongside Ropes & Gray's transaction confirmation, for gene-editing partnership economics.
For industrial and research infrastructure, we use Antheia's commercial thebaine delivery and manufacturing validation, Ansa's 50-kilobase DNA product announcement and its IDT partnership, and Culture Biosciences' disclosed bioreactor usage and customer figures. Additional evidence comes from Regeneron's collaboration with Mammoth Biosciences, bit.bio's commercial cell-product expansion, Arzeda's work with Unilever, and the World Economic Forum's 2026 Technology Pioneers announcement.
For the public-company comparisons, we rely on Twist Bioscience's SEC-filed fiscal 2025 results, Ginkgo Bioworks' full-year 2025 earnings disclosure, and Ginkgo's historical financial statements. These regulatory disclosures provide a firmer basis for financial comparison than private-company valuations or promotional operating claims.

In our report covering the synthetic biology market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us