How's Whoop doing these days?
Building a startup or looking for your next investment in wearable technology? Our report gives you the full picture.
Summary
Whoop is doing extremely well these days. The fitness wearable company has surpassed 2.5 million members, doubled its subscription business in 2025, achieved positive cash flow, and reached a $10.1 billion valuation. Its biggest challenge now is proving that customers will keep paying premium subscription prices as competitors catch up.
The commercial growth is hard to ignore. Whoop reported 103% subscription growth in 2025, while Sacra estimated annualized bookings of approximately $1.1 billion, up from $542 million in 2024. An $800 million subscription revenue run rate reported by the Financial Times points to a substantial recurring business, although these figures measure different things.
Whoop's valuation has increased approximately 181% since its $3.6 billion financing in 2021. At $10.1 billion, investors are effectively paying around 9.2 times estimated annualized bookings or 12.6 times the reported subscription revenue run rate. Both multiples assume strong future growth and durable customer retention. A $10.1 billion valuation sets a high bar, and we look at which wearable companies investors back, and which they pass on, in our report on wearable technology.
International expansion is becoming a major growth engine. Around 60% of new sales now reportedly come from outside the United States, compared with roughly 30% of Whoop's user base four years earlier. The company is increasingly selling its recovery-focused subscription to a global audience rather than relying on American fitness enthusiasts.
Whoop 5.0 improved the hardware, but the more consequential change may have been commercial. The company introduced three annual membership tiers priced at $199, $239, and $359, giving it more ways to monetize advanced health features. The controversial upgrade policy also showed how easily customers can push back when the hardware-included subscription promise changes.
Oura has emerged as Whoop's most formidable independent competitor. By June 2026, Oura had reached 5 million paid members, roughly twice Whoop's last disclosed membership figure. Oura also reported $1.215 billion in nine-month revenue and $60.8 million in net income, providing financial transparency that Whoop has yet to match.
The subscription economics remain Whoop's biggest unanswered question. Its customers make substantial annual commitments, and accumulated health data may encourage renewals, but the company does not publish comparable retention, churn, or gross-margin figures. Positive cash flow is encouraging without proving consistently profitable operations.
Whoop is also moving beyond fitness tracking. Advanced Labs offers blood testing, clinician-reviewed results, and specialized health panels, with some services available without a wearable membership. That creates opportunities to earn more from existing customers and reach people who have no interest in wearing a fitness sensor.
The healthcare expansion brings regulatory and commercial complexity. Whoop resolved its FDA dispute over the modified Blood Pressure Insights feature in June 2026, but laboratory testing depends on clinical partners, regional availability, and additional operating costs. The company has not disclosed enough Advanced Labs revenue to establish how successful this newer business is.
Whoop is increasingly positioning itself for an IPO, although no listing date has been confirmed. Its financing, membership growth, and cash-flow milestone make it a credible candidate, but public investors will want much clearer evidence about retention, customer acquisition costs, actual recognized revenue, and profitability.
Our conclusion is that Whoop has already built a successful consumer-health business, and its recent valuation is understandable given the growth. But the next stage will be harder: Whoop needs to keep its expensive memberships compelling while Apple, Garmin, and Oura offer increasingly similar capabilities. Its future value will depend less on selling more sensors and more on how many customers choose to stay, and what else they are willing to buy.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

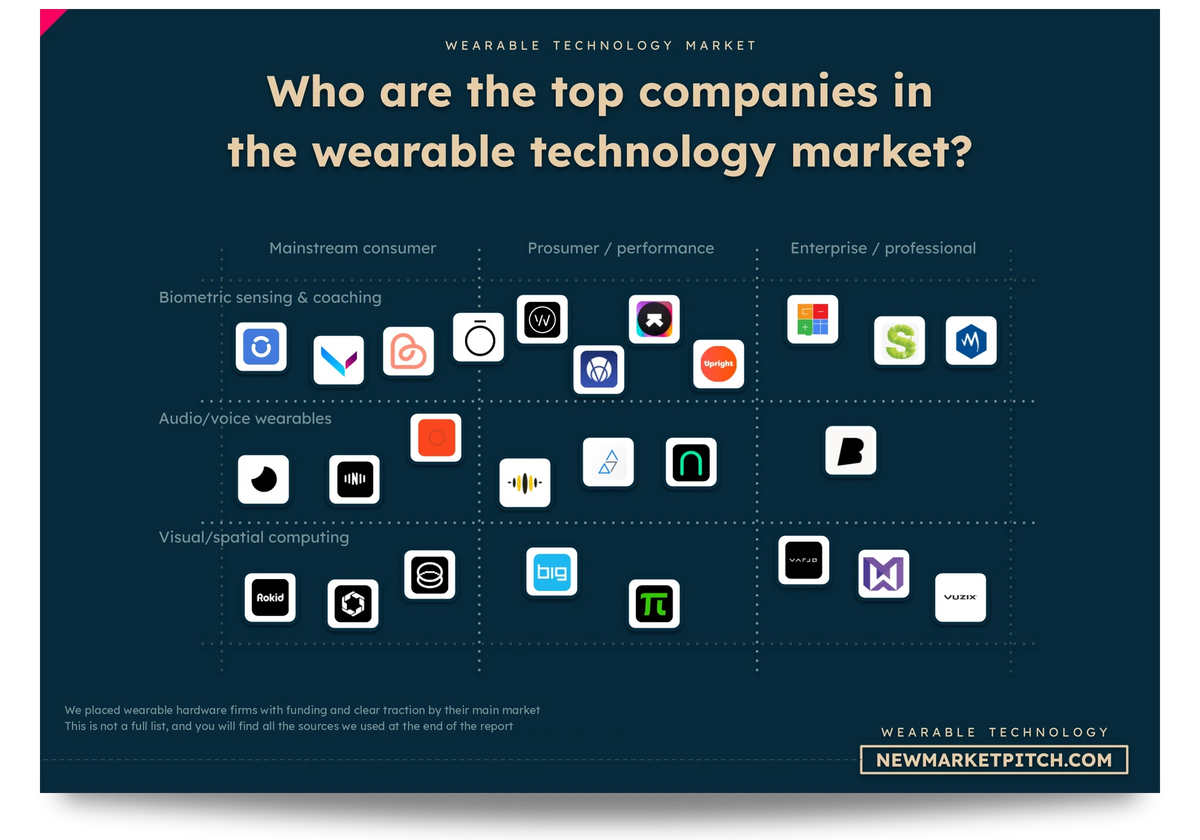
In our report covering the wearable technology market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is Whoop actually doing well right now?
Whoop is doing extremely well commercially right now, with subscriptions more than doubling in 2025, positive cash flow, and a valuation that has climbed to $10.1 billion.
The Boston-based fitness wearable company raised $575 million in March 2026, in a Series G led by Collaborative Fund. Investors included Qatar Investment Authority, Mubadala, Abbott Laboratories, and several prominent athletes. Whoop also reported more than 2.5 million members, confirming that the company has grown far beyond its original audience of professional athletes and serious fitness enthusiasts.
Its valuation has risen from $3.6 billion in 2021 to $10.1 billion, an increase of approximately 181%. That is impressive for a hardware-related business in a venture capital market that has become much more demanding about profitability.
There is one important catch: Oura has grown into a larger competitor, and Whoop's financial disclosures remain limited. The business is clearly thriving, but the $10.1 billion valuation assumes it can keep growing while convincing millions of customers to renew expensive annual subscriptions.
How big is Whoop today?
Whoop has become a major consumer-health subscription business, with more than 2.5 million members and an annualized subscription revenue run rate reportedly approaching $800 million.
According to figures reported by the Financial Times in March 2026, Whoop's subscription business had reached approximately $800 million on an annualized basis. Sacra separately estimated around $1.1 billion in annualized bookings for 2025, compared with approximately $542 million in 2024.
These figures are different measures of business activity. Bookings can include contracted revenue that has not yet been recognized, while an annualized revenue run rate projects recent revenue over a full year. Neither necessarily equals revenue recorded in audited annual financial statements. Bookings, run rate and recognized revenue measure different things, which is why we show every assumption behind our own size estimates in our wearable technology market report.
We can make one useful calculation. Dividing the reported $800 million subscription run rate by 2.5 million members gives approximately $320 per member annually. That is above Whoop's $199 and $239 annual plans, suggesting the published figures should not be treated as directly comparable without knowing their exact reporting periods, definitions, and included revenue.
The safest conclusion is that Whoop now operates a recurring business worth hundreds of millions of dollars annually. Its exact recognized revenue and revenue per paying subscriber remain undisclosed.

Our research about wearables gets updated several times a month, so you always get the latest view of where things stand.
Is Whoop still growing quickly?
Whoop is still growing remarkably fast, with reported subscription growth of 103% in 2025 despite already having an established global fitness brand.
That means subscription activity more than doubled in one year. Sacra's bookings estimates show a similar pattern, rising from approximately $542 million in 2024 to $1.1 billion in 2025. The increase is close to $558 million in annualized bookings, roughly equivalent to the entire estimated business at the beginning of the period.
International demand appears to be contributing heavily. According to Bloomberg's reporting, around 30% of Whoop users were outside the United States four years earlier, while international customers now account for approximately 60% of new sales.
That's a substantial change in where Whoop finds customers. Expansion across Europe, the Gulf, Asia, and Latin America also gives the company room to grow beyond its established American audience. Its hardware was already available in 56 markets when Whoop 5.0 launched.
Still, growth from new subscriptions tells us less about renewals. Whoop does not publish a detailed annual churn series, making it difficult to determine how much of the expansion comes from retaining existing subscribers versus acquiring new ones.
Is Whoop profitable yet?
Whoop became cash-flow positive in 2025, a major financial milestone, although we still cannot confirm that the company is consistently profitable.
Bloomberg reported the positive cash-flow milestone alongside Whoop's latest funding announcement. It marks a meaningful improvement for a company that has to manufacture hardware, fund software development, recruit subscribers, and maintain an international distribution operation.
Cash flow and accounting profit are different, though. Whoop has not released a complete income statement showing its operating margin, net income, or detailed cost structure. That limits what we can conclude about its underlying profitability.
Oura provides an interesting comparison. In its September 2026 SEC filing, the smart-ring company disclosed $1.215 billion in revenue, approximately $60.8 million in net income, and $106.7 million in adjusted EBITDA for the nine months ended June 30, 2026.
Those disclosures give investors a much clearer view of Oura's economics. With Whoop, we know cash generation has improved, but the company's actual profit margins remain unknown.
Is Whoop really worth $10.1 billion?
Whoop's $10.1 billion valuation looks ambitious but credible, given its rapid growth and recurring subscription business. The biggest unknown is how much profit the company can eventually generate.
The valuation comes from an actual $575 million financing round in March 2026. Using Sacra's estimated $1.1 billion in annualized bookings, Whoop is valued at approximately 9.2 times bookings. Using the Financial Times' reported $800 million subscription revenue run rate, the multiple rises to approximately 12.6 times.
These are indicative comparisons rather than conventional audited revenue multiples, but they give us a reasonable range for how investors are pricing the business.
For context, Whoop was valued at $1.2 billion in October 2020 and $3.6 billion in August 2021. Its valuation has now increased roughly 8.4 times in six years. Investors are paying for a business that has developed from a specialized sports product into a sizable consumer-health platform.
The latest financing also included healthcare-related investors such as Abbott and Mayo Clinic. Their participation fits with Whoop's move into blood testing, cardiovascular monitoring, and preventive health, although it does not independently prove the commercial success of those services.
| Valuation indicator | Figure | What it tells us |
|---|---|---|
| October 2020 valuation | $1.2B | Early unicorn benchmark |
| August 2021 valuation | $3.6B | SoftBank-led financing |
| March 2026 valuation | $10.1B | Latest private funding |
| Increase since 2021 | 181% | Approximately 2.8x |
| Latest financing | $575M | Substantial new capital |
| 2024 annualized bookings | ~$542M | Sacra estimate |
| 2025 annualized bookings | ~$1.1B | Sacra estimate |
| Subscription revenue run rate | ~$800M | Financial Times reporting |
| Valuation / annualized bookings | ~9.2x | Indicative multiple |
| Valuation / subscription run rate | ~12.6x | Different revenue measure |
The price is defensible if Whoop keeps growing at anything close to its current pace and holds on to subscribers. But at more than 12 times the reported subscription revenue run rate, there's not much room for a serious slowdown.

In our market report about wearables, we look at what the winners do differently, so you can learn from the best instead of guessing.
Why do people keep paying for Whoop?
Whoop keeps attracting paying customers because its recovery and training recommendations have become part of their daily routines.
Its main appeal comes from combining Sleep, Strain, and Recovery scores into practical guidance. Instead of simply displaying heart-rate measurements, Whoop tries to tell users how much physical stress they can handle, whether they are recovering properly, and how sleep or lifestyle changes affect performance.
That makes the product particularly attractive to people who train regularly. Marathon runners can compare training loads across weeks, strength athletes can monitor recovery after difficult sessions, and less competitive users can follow sleep and fatigue patterns. Athletes who want a clear read on recovery are the kind of customers, with a problem worth paying for, that we study in our market report about wearable technology.
Whoop also avoids the smartwatch experience altogether. There is no screen, notification feed, or app ecosystem on the device. Users wear the sensor continuously and consult the app when they want information.
The recurring subscription creates an ongoing relationship with customers, and historical health data can make the service more useful over time. We still lack public retention figures to measure how strongly those habits translate into renewals, but the product has a clear identity that goes beyond collecting basic fitness measurements.
Did Whoop 5.0 actually make a big difference?
Whoop 5.0 was a meaningful upgrade, especially for battery life and health monitoring, but its biggest commercial impact may come from changing how Whoop packages and prices its services.
Launched in May 2025, Whoop 5.0 was approximately 7% smaller than its predecessor and offered more than 14 days of battery life. Longer battery life fits particularly well with a device designed to be worn throughout the day and night.
Whoop also introduced the premium MG model, which added FDA-cleared ECG functionality, alongside features such as Healthspan and WHOOP Age.
More importantly, the launch created three membership levels: One at $199 annually, Peak at $239, and Life at $359. That introduced a $160 annual difference between the cheapest and most expensive plans.
The change gives Whoop more ways to charge customers according to the features they want. Someone primarily interested in activity and sleep tracking can choose the entry-level service, while customers interested in advanced health monitoring can pay more.
Longer battery life is certainly useful. But turning one recognizable membership into several tiers could have a larger effect on Whoop's long-term revenue than the hardware upgrade itself.
Did Whoop upset its customers with the 5.0 upgrade?
Whoop seriously frustrated existing subscribers during the 5.0 launch by introducing upgrade conditions that appeared to contradict its hardware-included subscription promise.
When the new devices arrived in May 2025, existing customers were initially told they needed to extend their membership by 12 months or pay an upgrade fee. The standard upgrade fee was $49, while the MG version carried a $79 fee.
The backlash spread quickly because customers had become accustomed to receiving newer hardware through their membership. TechCrunch and Bloomberg covered the complaints, and Whoop revised its policy within days.
Under the revised arrangement, Peak members with more than 12 months remaining became eligible for a free Whoop 5.0 upgrade, with refunds for eligible customers who had already paid. Other upgrade options remained tied to membership extensions or one-time fees.
The dispute exposed a weakness in the subscription model. Customers expect the hardware to be included, but producing and replacing devices still costs Whoop money. Changes to that arrangement can feel like subscribers are suddenly paying twice.
Whoop reacted quickly enough to contain the immediate controversy. There is no published churn data showing how many customers actually left because of it.

In our document detailing everything you need to know about wearable technology, you will always find fresh funding data, taken straight from our own verified funding database.
Is Whoop losing the wearable race to Oura?
Whoop is still growing strongly, but Oura has become the larger competitor by disclosed membership and now has a much clearer financial record.
Oura reported 5 million paid members at June 30, 2026, in its September SEC filing. Whoop's latest reported figure was more than 2.5 million members in March. The reporting dates differ, but Oura had approximately twice Whoop's last disclosed membership base. Two member counts from different dates only go so far, and the market maps in our report covering the wearable technology market place each player in the field.
Oura's growth has been exceptional. Its paid members increased from 1.5 million at the end of 2024 to 5 million by June 2026. The company also reported seven consecutive quarters of more than 100% year-over-year paid-member growth through that date.
Its September filing was subsequently updated to forecast approximately 5.7 million paid members by the end of its 2026 fiscal year.
However, the two businesses generate revenue differently. Around 80% of Oura's revenue during its latest disclosed nine-month period came from hardware, with subscriptions representing the remaining 20%. Whoop relies much more heavily on recurring memberships that include the device.
Oura has stronger disclosed scale in paying members, while Whoop has built a more subscription-centered model. Both products increasingly address sleep, recovery, and long-term health, although Whoop remains more closely associated with intensive training and athletic performance.
| Indicator | Whoop | Oura |
|---|---|---|
| Latest disclosed members | 2.5M+ | 5.0M paid |
| Membership reporting point | March 2026 | June 2026 |
| Latest private valuation benchmark | $10.1B | $11B |
| Recent reported growth | 103% subscription growth in 2025 | 74% nine-month revenue growth |
| Revenue indicator | ~$800M annualized subscription run rate | $1.215B in nine months |
| Profitability evidence | Positive cash flow in 2025 | $60.8M nine-month net income |
| Member retention disclosed | No comparable figure | ~85% weighted-average 12-month retention |
| Main device | Screenless wrist/body sensor | Smart ring |
| Standard annual membership | $199–$359 | $69.99 in US |
| Hardware model | Included with membership | Purchased separately |
| Main appeal | Training and recovery | Sleep and general health |
If we're judging by disclosed membership and financial performance, Oura is ahead. That doesn't make Whoop an unsuccessful business, but it does challenge the idea that Whoop is the undisputed leader in premium wearable health.
Can Whoop compete with Apple Watch and Garmin?
Whoop can compete with Apple Watch and Garmin among dedicated fitness users, but its narrow focus and annual subscription make it a harder sell to the average smartwatch buyer.
Apple Watch offers communication, payments, navigation, apps, and extensive health tracking. Garmin has deep expertise in GPS sports watches, training programs, running performance, and outdoor navigation. Both offer increasingly advanced sleep and recovery measurements.
Whoop's advantage comes from its screenless design and its emphasis on turning physiological measurements into daily recommendations. That can be appealing to athletes who already own another watch or prefer a device without notifications.
The price comparison is less comfortable. A customer paying $239 annually for Whoop Peak spends $717 over three years. Whoop Life reaches $1,077 over the same period. Some Garmin watches and Apple Watches cost several hundred dollars upfront but provide core fitness measurements without equivalent recurring fees.
Of course, expensive watches also need replacing, so the total cost depends on which device we compare and how long customers keep it.
Whoop's challenge is straightforward: its interpretation of the data needs to remain valuable enough that subscribers keep paying even when competing devices collect similar measurements.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the wearable technology market, we look at what broke startups before you, so you don't repeat it.
Is Whoop as accurate as Oura and Garmin?
Whoop is accurate enough to provide useful heart-rate and recovery tracking, but independent research does not show that it consistently beats Oura or Garmin on measurement accuracy.
A 2025 validation study compared Whoop 4.0, Oura Gen 3, Oura Gen 4, Garmin Fenix 6, and Polar Grit X Pro against ECG reference measurements during sleep.
Across 536 nights involving 13 participants, Oura Gen 4 recorded a mean absolute percentage error of approximately 1.94% for resting heart rate and 5.96% for heart rate variability. Whoop 4.0 recorded 3.00% and 8.17%, respectively.
Those results favor Oura Gen 4 for the two measurements tested, although the relatively small participant group limits broader conclusions. The findings also concern Whoop 4.0 and cannot establish the accuracy of newer Whoop 5.0 or MG hardware.
Whoop has continued updating its algorithms. During February and July 2026, the company introduced heart-rate tracking improvements aimed at activities such as HIIT, cycling, and weightlifting.
A separate issue is how Whoop interprets measurements. Its Recovery score combines physiological data into an estimate of readiness, but no single proprietary score can perfectly determine whether someone should train, rest, or seek medical attention.
Is Whoop turning into a healthcare company?
Whoop is increasingly becoming a preventive-health business, and its expansion into laboratory testing is the clearest evidence of that change.
In April 2026, Whoop introduced five specialized blood-testing panels covering heart health, athletic performance, metabolic health, women's health, and men's health. Each costs $299 and is delivered through Quest Diagnostics in the United States.
The company also offers broader Advanced Labs subscriptions. Customers can purchase one annual test for $199, two for $349, four for $599, or six for $899, with clinician-reviewed results and personalized recommendations. Selling blood tests next to a membership is the kind of business model we weigh, asking which ones keep their margins, in our report on wearable technology.
In August 2026, Whoop went further by making Advanced Labs available without a wearable membership. It also added access to GRAIL's Galleri multi-cancer early detection test.
Someone can now use a Whoop-branded health service without owning or wearing a Whoop device. The business is starting to reach beyond the customers who want continuous fitness tracking.
There is also a substantial difference in potential customer spending. A Peak member paying $239 annually and purchasing two Advanced Labs tests for $349 would spend $588 in one year. A Life member combining the $359 subscription with four annual tests for $599 would spend $958.
These are illustrative combinations, not Whoop's reported average customer spending. Blood tests also involve clinical and laboratory costs, so additional revenue will not necessarily carry the same margins as software subscriptions.
For now, Advanced Labs remains a promising newer business without disclosed adoption figures or revenue. Its importance lies in giving Whoop a credible route into healthcare services beyond wearable subscriptions.

Your time is limited. In our research about wearables, we put numbers on each part of the market, so you can see where it makes sense to focus.
Did Whoop finally resolve its FDA problems?
Whoop resolved its major FDA dispute over Blood Pressure Insights in June 2026, although the resolution came with clear limits on how the feature can be positioned.
The disagreement began in July 2025, when the FDA challenged Whoop's Blood Pressure Insights feature. The agency considered the estimated systolic and diastolic blood pressure measurements subject to medical-device requirements, while Whoop argued that the feature was intended for general wellness.
On June 17, 2026, the FDA issued a closeout letter after Whoop modified the product and its labeling.
Under the agency's updated general-wellness guidance, the FDA stated that it did not intend to enforce medical-device regulatory requirements against the modified Blood Pressure Insights feature.
This removed an important regulatory obstacle for Whoop. The letter was expressly limited to the modified feature and did not grant blanket clearance for additional medical capabilities.
Whoop's FDA-cleared ECG functionality is a separate product feature with a different regulatory status. That's worth keeping in mind as the company adds more health-related services.
Is Whoop's subscription model better than Oura's?
Whoop's subscription model gives it more recurring revenue from each customer relationship, but Oura has demonstrated stronger financial transparency and reported profitability.
Whoop includes its device within memberships ranging from $199 to $359 annually. Assuming uninterrupted subscriptions and unchanged pricing, a Peak member produces $478 over two years or $717 over three.
That recurring relationship can be attractive because customers continue paying for software, coaching, and new features. Yet Whoop must cover hardware production, distribution, replacements, and support from those membership payments.
Oura takes a different approach. Customers buy a ring separately and then pay for ongoing access to its membership features. In its SEC filing, Oura explained that upfront hardware revenue helps offset customer acquisition costs, while subscriptions contribute recurring revenue over time.
Oura also disclosed approximately 85% weighted-average 12-month paid-member retention. That means roughly 85% of subscribers in the measured cohorts remained subscribed after a year, although the exact methodology matters when interpreting retention.
Whoop has not published a directly comparable figure. Without churn, customer acquisition costs, and gross margins, we cannot reliably calculate which model generates better lifetime profits.
Whoop may ultimately enjoy attractive recurring economics. For now, Oura has provided more evidence that its own model works financially.

In our market report about wearables, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is Whoop getting ready for an IPO?
Whoop is preparing for a potential IPO, with its latest funding round and improving cash generation putting the company in a stronger position to consider a public listing.
Bloomberg described Whoop's March 2026 financing as a milestone toward an IPO, while the Financial Times reported ambitions to pursue a listing within approximately two years.
The company already has several features public investors tend to value: millions of members, substantial recurring revenue, international demand, and a recent positive cash-flow milestone.
Its planned hiring also suggests management expects further expansion. Whoop disclosed plans to increase headcount from around 800 to approximately 1,400 employees, an increase of roughly 75%.
However, a public listing would expose the company to much closer scrutiny. Investors would expect detailed figures on actual revenue, subscription churn, acquisition costs, hardware margins, and profitability.
Oura has already taken an important step in that direction by filing its S-1 registration statement in September 2026. That creates a useful financial reference point for Whoop and the wider wearable-health market.
No definitive Whoop IPO date has been established publicly. Its readiness will depend partly on whether the company can demonstrate that rapid subscriber growth translates into durable profits.
What could slow Whoop down now?
Whoop's biggest risk now is losing the pricing advantage of its specialized recovery software as Apple, Garmin, and Oura make similar health features more accessible.
The competitive pressure is already substantial. Oura has built a larger disclosed membership base, Garmin offers extensive training and recovery features without Whoop's annual membership structure, and Apple continues adding health capabilities to its smartwatch ecosystem. Stronger rivals with similar features are among the risks that could slow a market, and we rate them by likelihood in our wearable technology market report.
Customer renewals are especially important because Whoop charges every year. A Life subscriber paying $359 annually would spend $1,795 over five years at unchanged prices. That's a considerable commitment if competing devices eventually offer sufficiently similar functionality.
Healthcare expansion adds another challenge. Advanced Labs depends on laboratory partners, clinician involvement, and regional availability. Whoop can sell its wearable internationally, but its full blood-testing service is much harder to distribute everywhere. Testing purchased directly through the platform remains primarily focused on the United States, with separate arrangements in markets such as the UAE.
The company also has to manage investor expectations. Its latest valuation already assumes continued growth, and a major slowdown could be particularly uncomfortable without stronger evidence of profitability.
We would watch three developments most closely: whether subscription growth remains strong, whether Whoop begins publishing meaningful retention or margin figures, and whether Advanced Labs becomes a measurable source of revenue.

If you build or invest in the wearable technology market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
So, how's Whoop doing these days?
Whoop is doing very well. The company has become a serious consumer-health business, with more than 2.5 million members, rapid subscription growth, positive cash flow, and a $10.1 billion private valuation.
The most impressive development is how much the business has grown beyond its original athletic niche. International customers now represent a majority of new sales, and Whoop is increasingly selling health services that have little to do with tracking workouts.
The main competitive threat is Oura, which has already reached 5 million paid members and disclosed stronger financial results. Apple and Garmin also put pressure on Whoop to keep improving a product that requires expensive annual renewals.
We think Whoop has successfully built one of the most valuable independent brands in wearable health. Its recent performance justifies confidence in the business, although the premium valuation still needs support from sustained retention and higher profits.
The next chapter will be particularly revealing. If Whoop can turn its existing subscriber base into a broader healthcare customer base while maintaining strong renewals, the company could become considerably more valuable. If growth slows and competing wearables narrow the difference in features, its subscription pricing will become harder to defend.
For now, Whoop is thriving commercially. The real question is how much bigger the business can become beyond fitness tracking.
Our methodology
This analysis assesses Whoop's current business performance by examining six areas: commercial growth, financial health, valuation, competition, subscription economics, and healthcare expansion. We focused on recent company disclosures, financing announcements, regulatory records, independent research, and original financial reporting.
We used Whoop's March 2026 financing as the latest private-market valuation benchmark and compared its $10.1 billion valuation with reported revenue indicators and historical funding rounds. We distinguished the company's disclosed subscription growth and cash-flow milestone from third-party annualized bookings estimates and reported subscription revenue run rates. These financial measures are not interchangeable with audited annual revenue.
To evaluate competition, we compared Whoop's disclosed membership and business model with Oura's financial and subscription disclosures in its September 2026 SEC filings. We also considered Apple Watch and Garmin's training and recovery capabilities, recognizing that device pricing, hardware revenue, and recurring subscriptions differ substantially across these products.
Our product assessment drew on Whoop's official announcements about Whoop 5.0, membership tiers, Advanced Labs, and blood-testing partnerships. We used independent physiological validation research to assess measurement accuracy and FDA regulatory documents to examine the Blood Pressure Insights dispute and its resolution. For subscription economics, we calculated illustrative multiyear customer spending without treating those figures as disclosed customer lifetime value.
We gave the greatest weight to directly documented financial and regulatory developments, while treating management ambitions, future healthcare revenue, and IPO expectations as prospective rather than established outcomes. This approach helps distinguish Whoop's demonstrated growth from the assumptions supporting its valuation.
Key sources include Whoop's Series G announcement, Bloomberg's reporting on growth, cash flow, and IPO ambitions, the Financial Times on Whoop's revenue run rate, Sacra's financial estimates, Oura's SEC registration statement, Whoop's membership pricing, the Whoop 5.0 and MG launch announcement, TechCrunch's reporting on the upgrade controversy, the independent wearable accuracy study in Physiological Reports, Whoop's specialized blood-testing announcement, its Advanced Labs expansion announcement, the FDA's original warning letter, and the FDA's June 2026 closeout letter.

Theory only gets you so far. In our report covering the wearable technology market, we dig up the real signals from the field and show you the ones worth watching.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us