AgriTech: where's the money now?


Every funding round, every investor, and who is really ahead in livestock tech, in one document. Have a look ↓
Summary
AgriTech money is still moving toward categories that make farming more automatic, more measurable, or less dependent on expensive inputs. The second half of 2026 made that split sharper: rounds kept closing for autonomy, cattle data, soil sensors and biologicals, while 80 Acres Farms, one of the best-funded indoor farm operators, announced in August 2026 that it would wind down.
The clearest pattern is that investors are no longer funding AgriTech as one broad theme. They are backing specific pressure points: labor scarcity, chemical reduction, animal productivity, climate verification, and crop resilience.
Farm automation and livestock automation currently have the strongest capital signal because they connect directly to urgent farm operating pain. Farmers can understand the ROI quickly when a product reduces labor, improves field execution, or automates animal management.
Livestock automation may be the freshest signal in the market. Halter’s jump from a $1 billion valuation in 2025 to $2 billion in 2026 makes the category look less like niche farm hardware and more like a global automation platform. Breedr’s $27 million Series B in August 2026 adds a second layer: animal-level records across beef supply chains.
Farm robotics is also getting funded, but not randomly. Precision-ag capital is concentrating into later-stage winners, and Sabanto’s oversubscribed Series B in July 2026, led by Leaps by Bayer, shows strategic money backing retrofit autonomy for existing tractors.
Biologicals are getting money through a different channel. The strongest signal is not only startup funding, but also incumbent activity from major crop-input companies that need new categories as chemical resistance, regulation, and input costs become harder to manage.
Gene editing remains investable, but only when the platform looks large enough to survive long timelines. The money is going to companies with deep platforms, major incumbent partners, or AI-driven ways to compress R&D.
Regenerative agriculture is not being funded as a vague sustainability story. Capital is flowing when the company can turn farm practices into auditable assets, project finance, issued credits, or supply-chain data that buyers can trust.
Agri-input commerce still has momentum, especially in India, but the model has changed. The investable version now looks more like rural operating infrastructure, with distribution, private-label inputs, credit, insurance, procurement, and market linkage bundled together.
Water management and CEA tech are active, but quieter. Rounds such as Mitti Labs’ $9.5 million for rice-field water management and hexafarms’ €4.8 million for greenhouse sensing show practical demand, but round sizes still point to fragmented markets.
The coldest area is vertical farming operators. The 80 Acres Farms wind-down confirms that the old venture-backed model of building expensive indoor farms at scale is still a restructuring story, even if a narrower robotic greenhouse model like Hippo Harvest can still raise. Indoor farms that stalled are one example of what failed startups often share, which we study in our AgriTech market report.
The practical conclusion is that AgriTech money is no longer chasing futuristic farming in general. It is rewarding companies that remove real operating constraints now, especially where automation, measurement, and input substitution create clear economic value.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us


This is just a preview page. Don’t worry if a number looks old: the report gets refreshed, and you’ll always get the latest version.
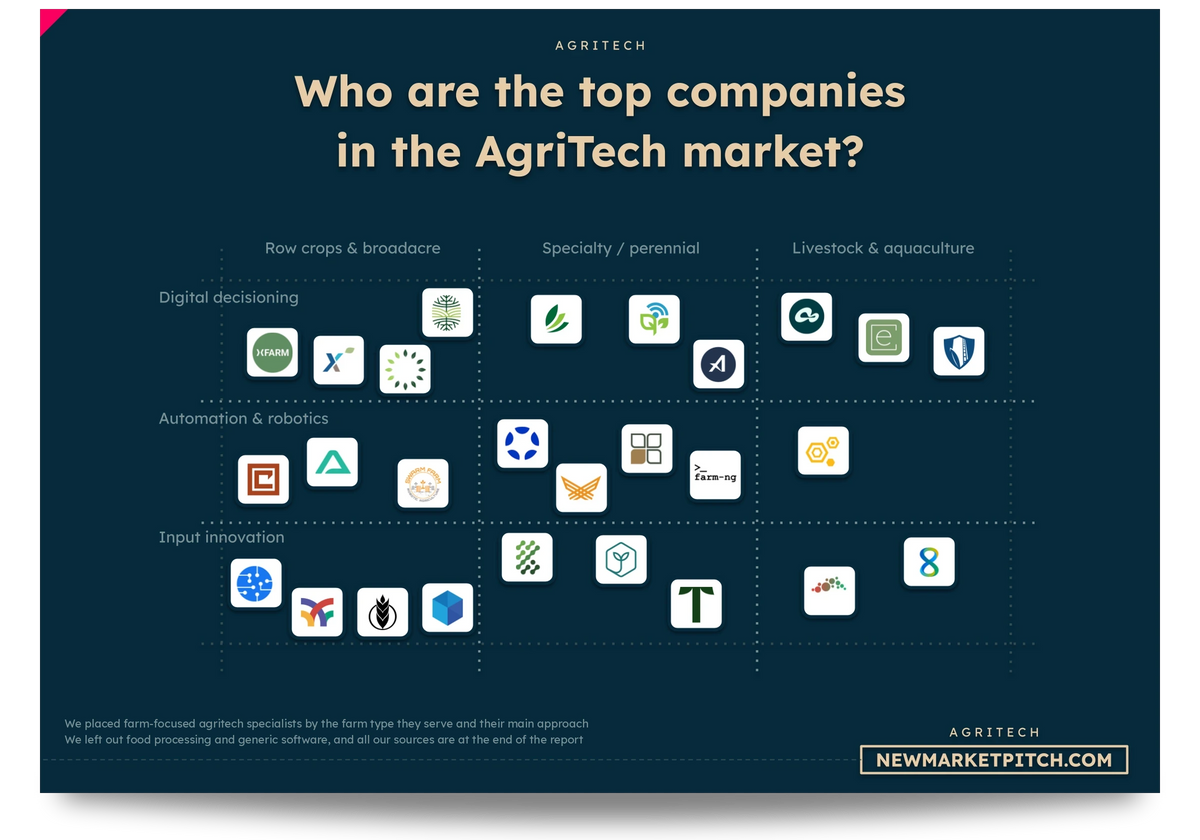
What are the main company categories in AgriTech?
AgriTech looks like one market from far away, but money does not move through it evenly at all.
Some categories are getting real conviction today. Others are mostly living off old funding, restructuring, or strategic patience.
So before asking where the money is, we need to separate the market into the right buckets.
| Category | Simple description | Example companies |
|---|---|---|
| Farm automation and robotics | Robots, autonomous equipment, precision sprayers, harvesters, and autonomy software used in fields, orchards, greenhouses, and aquaculture. | Ecorobotix, Carbon Robotics, Bonsai Robotics, farm-ng, Agtonomy, Sabanto, SwarmFarm Robotics, Orchard Robotics |
| Livestock automation and animal intelligence | Tools that automate cattle management, virtual fencing, animal monitoring, methane reduction, and herd productivity. | Halter, Breedr, ArkeaBio, Ruminant BioTech, Number 8 Bio, CH4 Global |
| Agricultural biologicals | Biofertilizers, biostimulants, biocontrols, microbial seed treatments, and natural crop-protection products. | BioConsortia, Jord BioScience, Robigo, HGS BioScience, Syngenta Biologicals, BASF AgBiTech |
| Crop genetics and gene editing | Seed design, CRISPR, AI breeding, and crop traits for yield, resilience, nutrition, or climate adaptation. | Inari, Pairwise, Biographica, Spearhead Bio, Tropic Biosciences |
| Precision agriculture and farm data infrastructure | Sensors, imagery, APIs, AI agronomy, and farm management systems that turn field data into decisions. | Leaf Agriculture, CropIn, Taranis, TerraBlaster, Ceres AI, Orchard Robotics |
| Regenerative agriculture, carbon, and MRV | Platforms that measure, verify, finance, or monetize regenerative practices, soil carbon, traceability, and nature-linked outcomes. | Varaha, Regrow Ag, Boomitra, Treefera, Mitti Labs, Klim, Soil Capital |
| Agri-input commerce and embedded finance | Platforms that bundle inputs, advisory, credit, insurance, procurement, and market access, especially in India and emerging markets. | AgroStar, DeHaat, Apollo Agriculture, Samunnati, Ninjacart |
| Smart irrigation and water management | Sensors, valves, automation, aerial analytics, and software that reduce water waste and optimize irrigation. | Lumo, FarmHQ, Verdi, Ceres AI, Mitti Labs |
| Controlled-environment agriculture tech | Software and robotics for greenhouses and CEA infrastructure, without taking on the full farm-operator balance sheet. | Source.ag, SAIA Agrobotics, eternal.ag, hexafarms, IUNU |
| Vertical farming operators | Indoor farms growing crops in warehouses or vertical systems, usually with heavy capex and direct production risk. | Plenty, Bowery, AeroFarms, AppHarvest, 80 Acres Farms (wind-down announced in August 2026) |
Is money flowing into farm automation and robotics right now?
Yes, farm automation is one of the clearest places where AgriTech money is moving right now.
The obvious signal is funding size. Ecorobotix raised $150 million across its 2024 Series C and 2025 Series D, including a $105 million Series D. Carbon Robotics raised $70 million in late 2024 with BOND leading and NVentures participating. Bonsai Robotics raised $15 million in early 2025, then moved from funding into consolidation by acquiring farm-ng a few months later. That is already a strong cluster: precision spraying, laser weeding, orchard autonomy, and field robotics all getting funded in the same window. Seeing which robotics companies work on spraying, weeding or orchards is easier on the market maps and grids in our AgriTech market report.
In 2025, precision-ag funding reached about $668 million across 37 rounds, but only four Series C and D deals captured 47% of the total. That tells us money is not being thrown randomly at every farm robot. Investors are concentrating behind companies that look close to scale, especially autonomous weeding and precision spraying.
The timing also matters. Ecorobotix raised again only about a year after its previous round. Bonsai did not just raise; it bought farm-ng, which suggests buyers are trying to assemble platforms before the category settles. Agtonomy’s oversubscribed $18 million Series B adds another useful signal because it is not a pure hardware bet but actual software and “physical AI” for off-road automation, which is exactly where investors seem more comfortable these days.
Strategic money is also showing up. In July 2026, Sabanto announced an oversubscribed Series B led by Leaps by Bayer to sell autonomy kits that retrofit existing tractors. The amount was not disclosed, and its expansion targets are plans, not customer counts. Public money is moving too: in August 2026, the UK government opened a £20 million competition for farm robotics grants. That is a budget open to bids, not venture capital already raised.
So, yes, money is flowing into farm automation, mainly because the buyer pain is real. Farmers need fewer labor hours, lower chemical use, and more precise field operations now.

Is money flowing into livestock automation and animal intelligence right now?
Yes, and we believe livestock automation may be the loudest fresh signal in the whole AgriTech market.
Halter is the main reason. It raised $100 million in June 2025 at a $1 billion valuation, then raised $220 million in March 2026 at a $2 billion valuation. That is a valuation doubling in less than a year, in a market where most AgriTech companies would be happy just to avoid a flat round. The investor quality also matters: BOND led the 2025 round, then Founders Fund led the 2026 round.
A fast valuation jump with BOND, then Founders Fund, says this is read more like a global automation platform than a niche farm device.
There are also useful second-layer signals around cattle emissions. Ruminant BioTech raised money for a methane-reduction bolus, and Number 8 Bio raised capital for synthetic-biology methane reduction. Those rounds are much smaller than Halter, but they matter because they point to the same animal-agriculture pressure point: cattle are becoming both a productivity problem and a climate-accounting problem.
Breedr shows the data side of the same trend. In August 2026, it raised a $27 million Series B led by Partech’s impact fund, bringing total funding to $46.6 million. The company says its platform holds records on 2 million cattle across 10 supply chains. Those are animals on its books, not 2 million paying subscriptions, but it is a stronger signal than any market forecast. The methane side is tighter: ArkeaBio raised a $15 million Series A2 in September 2026 for a livestock methane vaccine while cutting roughly a third of its staff, according to AgFunderNews. It is still working toward a first commercial product.
The Starlink partnership around Halter also matters. Virtual fencing sounds simple until rural connectivity breaks the product.
Livestock tech is getting capital today because it solves a dense bundle of problems at once: labor, pasture management, animal visibility, methane, and farm productivity.
Is money flowing into agricultural biologicals right now?
Yes, but in biologicals the money signal is more strategic than pure VC.
The venture signal is mixed. Some biological subcategories, like biostimulants, had a very weak funding year in 2024. So if we only looked at VC dollars, we would probably under-rank the category. But that would miss what is actually happening now: large crop-input companies are buying, building, and reorganizing around biologicals.
BASF agreed to acquire AgBiTech, a biological insect-control business, in early 2026. Syngenta announced a £100 million bioscience hub in the UK focused on sustainable crop protection, biological pesticides, and AI-supported innovation. HGS BioScience and AgroPlantae have also been active in biologicals M&A and portfolio expansion. This is not the same type of signal as a flashy Series B, but it is arguably more important because crop inputs are distributed through incumbents.
There is still startup funding too. BioConsortia raised $15 million in 2025 from existing investors to scale nitrogen-fixing seed treatment. Jord BioScience raised Series B money around microbial consortia. In September 2026, Leaps by Bayer backed Robigo’s Series A for engineered microbes that protect crops. The amount was not disclosed, its yield claims come from precommercial trials, and launches are planned for 2028 and 2029. CropLife’s Q3 2026 tracker put $407 million across 27 deals in its broad biologicals bucket, up from $57.7 million in Q2, but that bucket is wider than farm inputs alone.
The serious money is looking for products that plug into seed treatment, crop protection, or plant nutrition channels. That is a harder bar, but a much bigger market if the product works.
At the end of the day, biologicals are getting money because incumbents need a next input category as chemical resistance, regulation, and farmer input costs all get harder to manage.

This is a preview page. Spotted an outdated number? That’s normal here. The report you get is always the freshest version.
Is money flowing into crop genetics and gene editing right now?
Yes, but this is actually not a broad “everyone gets funded” market. Instead, the money is going to a small number of platforms that look big enough to matter.
Inari is the clearest signal. It raised $144 million in January 2025, bringing cumulative equity raised above $720 million. Reports put the valuation around $2.17 billion, up from about $1.65 billion previously. A valuation step-up like that matters because gene-editing and seed platforms need long timelines. Investors are basically saying: even in a tighter AgriTech market, this one is still worth funding through commercialization. Investors funding long-timeline bets despite a tighter market is a shift we follow when we study where the money goes in our report on AgriTech.
Pairwise gives a different but equally important signal. It raised $40 million and formed a five-year joint venture with Corteva around gene editing for corn and soy. That is more than funding. It is channel access, crop access, and incumbent validation in row crops, where distribution is extremely hard to crack from the outside.
Then there is the early layer. Biographica raised $9.5 million in early 2026 for AI-powered crop gene editing, and Spearhead Bio closed a $1.62 million SAFE seed round in September 2026 for its genome-engineering platform. Small rounds, with no commercial farmer adoption yet, but new capital is still entering where tools can compress discovery or trait design.
So it looks like crop genetics is still investable today, but only when investors see either a true platform, a major incumbent partner, or a way for AI to make the R&D cycle less painful.
Is money flowing into precision agriculture and farm data infrastructure right now?
Yes, but precision agriculture has changed a lot. Money is moving into decision infrastructure, not generic dashboards.
The headline number is decent: precision agriculture funding reached about $668 million across 37 rounds in 2025. But the more important detail is concentration. Four late-stage deals made up 47% of all capital. That is a very different market from the older precision-ag wave, where many startups could raise around farm analytics, scouting apps, or satellite dashboards.
Now investors seem to prefer companies that own a workflow.
Orchard Robotics raised $22 million to put vision AI into fruit farms. Agtonomy raised an oversubscribed $18 million Series B for off-road physical AI. Ceres AI has been pushing aerial analytics into irrigation, risk, lending, and insurance use cases. Leaf Agriculture is building the API layer that lets farm data move between systems. In August 2026, TerraBlaster disclosed $12.5 million in seed funding for real-time soil nutrient sensing, to fund manufacturing and field deployment; no installed base has been published yet.
That tells us something important: data alone is not the product anymore.
The product is a decision, an automation layer, a financing trigger, or an operational workflow. Orchard is interesting because it turns fruit visibility into crop-load and labor decisions. Agtonomy is interesting because it connects software to machines. Ceres is interesting because the same field signal can be useful to growers, lenders, insurers, and agribusinesses.
So precision agriculture is still getting money, but the bar is higher now.

Preview only. Some numbers may have changed since we made this page, but your report will be up to date.
Is money flowing into regenerative agriculture, carbon, and MRV right now?
Yes, but only into the parts of regenerative agriculture that can be measured, financed, and sold.
Varaha is the best current signal. It secured a $30 million carbon investment from Mirova in late 2025 for a soil-carbon project across Haryana and Punjab, covering more than 337,000 farmers and 675,000 hectares. Then WestBridge Capital led a $45 million round in Varaha in early 2026. The sequence is important: first project capital, then major growth capital. That is stronger than a normal venture round because it shows both asset buyers and equity investors showing up.
Treefera is another good signal because it raised $30 million Series B for AI-enabled first-mile supply-chain transparency. That may sound adjacent to farming, but it fits the same money pattern: companies want land, sourcing, carbon, deforestation, and origin data they can trust. Treefera is selling that infrastructure layer rather than asking buyers to care about regenerative agriculture in a vague way.
Mitti Labs adds a rice-specific signal. In August 2026, it raised a $9.5 million Series A led by Aramco Ventures for satellite and AI tools that manage water and measure methane in Asian rice fields. Its expansion is a use of the money, not a result yet.
Boomitra adds a third type of signal: actual credit issuance. Its URVARA project in India issued more than 47,000 soil-carbon credits and projected 315,000 over two decades. In carbon markets, issuance matters because “we can measure this” is much weaker than “the registry issued credits.”
So we can say pretty firmly that money is flowing into regenerative agriculture when the company turns farm practice into an auditable asset. If it is just a nice regenerative story, capital is much colder.
Is money flowing into agri-input commerce and embedded finance right now?
Yes, especially in India, but the story has moved from growth-at-all-costs to distribution, margins, and embedded finance.
AgroStar raised $30 million in November 2025, led by Just Climate, with existing investors also participating. The timing matters because the round came after a long funding gap of almost four years. The investor profile also matters: Just Climate reframes AgroStar less as a simple input marketplace and more as a sustainable-farming distribution network.
DeHaat gives a different signal. It reported FY25 revenue of about Rs 3,000 crore, up 11%, and said it posted a net profit in Q1 FY26. The FY25 profit number needs careful reading because it included a one-time fair-value gain, but the operating direction still matters: private-label inputs, exclusive distribution, exports, storage, and food processing. That is how these platforms try to escape low-margin marketplace economics. Which input and marketplace models make money and keep their margins is what we compare in our market report about AgriTech.
The category is also becoming more financial. Inputs, advisory, credit, insurance, procurement, and market access are increasingly bundled together. That is the real reason investors still pay attention: the winning platform may not just sell fertilizer or seeds. It may control enough farmer relationships to attach credit, insurance, data, and market linkage.
No new verified round for a pure agri-input finance platform turned up between July and October 2026.
So money is flowing into agri-input commerce when the company looks less like an e-commerce app and more like rural operating infrastructure.

This is just a preview page. Don’t worry if a number looks old: the report gets refreshed, and you’ll always get the latest version.
Is money flowing into smart irrigation and water management right now?
Yes, some money is flowing into irrigation and water tech, but it is still a quieter category than robotics, livestock, or biologicals.
The positive signals are real. Verdi raised $6.5 million CAD in 2025 to retrofit irrigation automation onto existing farm infrastructure, bringing total funding to $9.5 million CAD. The company claims its systems can save up to 90% of irrigation labor and 70% of water, and reported more than $1 million in labor savings plus over 100 million liters of water saved in 2024. Lumo and FarmHQ also show that irrigation automation is moving through smaller, practical deployment rounds rather than giant hype rounds.
Irrigation has a clear ROI story: labor savings, water savings, less manual fieldwork. But round sizes are still modest, which suggests useful businesses rather than venture-scale winners everywhere.
The stronger version of this category is when water connects with data platforms. Ceres AI links aerial analytics and crop stress signals to water decisions, lending, and insurance. Mitti Labs’ $9.5 million Series A in August 2026 fits the same logic for rice: field teams plus GeoAI to manage water, not new hardware. We found no independent figures on its water savings.
Water tech is investable today, but it still feels fragmented.
Is money flowing into controlled-environment agriculture tech right now?
Yes, money is still flowing into CEA tech, but mostly into software and robotics for greenhouses.
Source.ag raised $17.5 million Series B in November 2025, bringing total funding above $60 million. The round was led by Astanor, with strategic participation from Enza Zaden and grower cooperative Harvest House. That investor mix matters because it includes people close to the greenhouse value chain, not just financial investors.
The usage signal is also stronger than the funding number alone. Source.ag says its software is used in more than 300 greenhouses across 2,500 hectares and 18 countries, supporting daily supply for about 40 million people. That makes the round feel less like an AI story and more like an adoption story.
Greenhouse robotics is also getting funded. SAIA Agrobotics raised €10 million Series A in late 2025 to commercialize its “inverted greenhouse” model. eternal.ag raised €8 million in 2026 for autonomous tomato harvesting robots. In October 2026, hexafarms raised €4.8 million in equity for horticulture sensors and automated crop monitoring, plus a separate loan of up to €800,000. The amounts are small, but the logic is consistent: growers need labor automation and yield control.
So, CEA tech is not dead at all. The money has simply moved away from “we will build and operate huge farms ourselves” toward tools that help existing growers run better greenhouses.

Did 80 Acres Farms' shutdown end the vertical farming bet?
For broad, venture-backed vertical farming, yes, at least for now. Operators are still mostly a restructuring story.
The latest blow came in August 2026, when 80 Acres Farms said it would wind down after failing to secure more funding. It was one of the sector’s best-funded survivors, and local reports put its total raised at about $400 million. Its closure came after the earlier wave. Plenty filed for bankruptcy in March 2025 after raising nearly $1 billion. Bowery reportedly shut down after raising more than $700 million and reaching a $2 billion valuation in 2021. AeroFarms and AppHarvest had already filed for bankruptcy protection in 2023. One bankruptcy review counted fourteen indoor-farming and CEA-related bankruptcies in 2025, with failed companies representing more than $1.37 billion in historical funding.
That is a pattern around the operator model, not a few bad companies. The farms are expensive to build, energy can be painful, unit economics are hard, and retail demand does not automatically cover the cost structure. Plenty even had major-name backers, including SoftBank, Walmart, and Jeff Bezos, which makes the failure more telling, not less. Heavy energy costs and weak unit economics are the kind of risk we rate by likelihood in our report covering the AgriTech market.
Some operators can still raise, but on narrower terms. In July 2026, Hippo Harvest closed a $30 million Series C led by Cox Farms for robot-run greenhouses. Its proposed 30-acre site in Hollister, California, is still in permitting, so it is a plan, not capacity. That round does not cancel the 80 Acres failure. It shows investors will back a greenhouse model with lower energy needs and a strategic grower behind it.
The picture is clear. Fresh growth money has largely left warehouse vertical farms. Investors now want profitable sites, committed offtake, lower energy cost, and much tighter capex.
So where is the money now in AgriTech?
Right now, the money in AgriTech is going to categories that make farming more automatic, more measurable, or less dependent on expensive inputs.
If we simplify the whole market, the money is not really betting on “AgriTech” as a broad theme anymore but rather betting on specific farm pressure points.
The current winners are the companies that can say, very concretely: we reduce labor, cut inputs, automate animals or machines, verify climate value, or make crops more resilient.
The strongest flows are in farm automation and livestock automation.
Those two categories have the cleanest pain: labor is scarce, chemicals are under pressure, animal operations are hard to manage, and farmers can understand the ROI quickly.
After that, money is moving into biologicals, gene editing, and regenerative MRV, but with a different logic: there, investors are backing input substitution, climate resilience, and verified environmental assets.
The coldest area is vertical farming operators. The 80 Acres Farms wind-down in August 2026 confirmed that it is a restructuring market, not a growth one.
The headline numbers look healthier than the farm-level picture. CropLife counted $2.026 billion across 205 deals in Q3 2026, flat in dollars and up about 30% in deal count from Q2. But that total includes a satellite operator and a human drug-discovery company, so it overstates money going into farming itself. The ranking below rests on specific rounds, not on that total.
| Rank | Category | Signals that prove money is flowing |
|---|---|---|
| 1 | Farm automation and robotics | Ecorobotix raised $150M across 2024 and 2025, including a $105M Series D; Carbon Robotics raised $70M with BOND and NVentures; Bonsai raised $15M then acquired farm-ng; Sabanto closed an oversubscribed Series B led by Leaps by Bayer in July 2026 (amount not disclosed). |
| 2 | Livestock automation and animal intelligence | Halter doubled from a $1B valuation in 2025 to $2B in 2026; Founders Fund and BOND both showed up; Breedr raised a $27M Series B in August 2026 and reports 2M cattle on its platform; ArkeaBio raised $15M for methane vaccines. |
| 3 | Agricultural biologicals | BASF moved to acquire AgBiTech; Syngenta committed £100M to a bioscience hub; BioConsortia and Jord BioScience raised; Robigo closed a Series A backed by Leaps by Bayer in September 2026, with launches planned for 2028-2029. |
| 4 | Crop genetics and gene editing | Inari raised $144M with more than $720M cumulative equity; reported valuation rose to about $2.17B; Pairwise raised $40M and formed a Corteva JV; Biographica and Spearhead Bio brought fresh early-stage rounds into 2026. |
| 5 | Regenerative agriculture, carbon, and MRV | Varaha combined $30M project capital from Mirova with a $45M WestBridge-led round; Treefera raised $30M Series B; Boomitra issued soil-carbon credits; Mitti Labs raised a $9.5M Series A for rice water and methane measurement in August 2026. |
| 6 | Precision agriculture and farm data infrastructure | 2025 precision-ag funding reached about $668M across 37 rounds; four late-stage deals captured 47% of capital; Orchard Robotics, Agtonomy and Leaf show the move toward workflows; TerraBlaster raised $12.5M for soil sensing in August 2026. |
| 7 | Agri-input commerce and embedded finance | AgroStar raised $30M after a long funding gap with Just Climate leading; DeHaat showed revenue growth and profitability signals; the category is moving toward distribution, private labels, finance, and market linkage. |
| 8 | Controlled-environment agriculture tech | Source.ag raised $17.5M with strategic greenhouse investors and claims adoption across 300+ greenhouses; SAIA raised €10M; eternal.ag raised €8M; hexafarms raised €4.8M in equity in October 2026. |
| 9 | Smart irrigation and water management | Verdi raised fresh seed capital and reported labor and water savings; Mitti Labs raised $9.5M for rice-field water management; Lumo, FarmHQ, and Ceres AI show activity, but the category remains fragmented. |
| 10 | Vertical farming operators | Plenty filed for bankruptcy after nearly $1B raised; Bowery shut down after more than $700M raised; AeroFarms and AppHarvest went through bankruptcy; 80 Acres Farms announced its wind-down in August 2026; Hippo Harvest’s $30M greenhouse round is the narrow exception. |
Our methodology
The question of where money is flowing in AgriTech is easy to answer vaguely, because the market covers very different business models, buyer problems, and capital profiles. We therefore broke the question into clearer analytical dimensions instead of treating AgriTech as one uniform market.
For each dimension, we looked at recent signals that show where capital is moving now: funding rounds, valuation changes, acquisitions, strategic investments, project finance, adoption data, partnerships, bankruptcies, and restructurings. We then aggregated the most relevant signals category by category, rather than relying on one headline, one company, or a broad market narrative.
This structure is what makes the conclusion more solid. The analysis is not based on which AgriTech themes sound attractive, but on where the freshest evidence points. That is why the final answer separates categories with strong current capital conviction, such as farm automation, livestock automation, biologicals, gene editing, and measurable climate-linked infrastructure, from categories where the signal is weaker or negative, such as capital-heavy vertical farming operators.
We prioritized sources that added specific, checkable information: funding size, valuation, investor identity, acquisition activity, strategic investment, project finance, adoption scale, measurable savings, carbon-credit issuance, bankruptcy filings, and restructuring evidence. We treated first-hand company or investor pages as especially useful when they contained the needed details, then used tier-1 or highly relevant industry media where first-hand sources were not available or did not include the key number.
Key sources used for this analysis include: Ecorobotix on its $150 million Series C and Series D funding, Business Wire on Carbon Robotics’ $70 million Series D, Business Wire on Bonsai Robotics’ $15 million Series A, Bonsai Robotics on its acquisition of farm-ng, Agtonomy on its $18 million Series B, and iGrow News on 2025 precision-agriculture funding concentration.
Additional key sources include: Halter on its $220 million Series E, AgFunderNews on Halter’s $100 million Series D and $1 billion valuation, BASF on its agreement to acquire AgBiTech, The Guardian on Syngenta’s £100 million bioscience hub, Inari on its $144 million funding round, Yahoo Finance on Inari’s reported valuation step-up, and Corteva on the Pairwise gene-editing joint venture.
For regenerative agriculture, commerce, water, CEA, and vertical farming, key sources include: Mirova on its $30 million Varaha carbon investment, The Economic Times on Varaha’s WestBridge-led funding round, Treefera on its $30 million Series B, Boomitra on URVARA soil-carbon credit issuance, Just Climate on AgroStar’s $30 million round, The Economic Times on DeHaat’s FY25 revenue and profitability signals, PR Newswire on Verdi’s irrigation funding and savings claims, Source.ag on its $17.5 million Series B and adoption scale, TechCrunch on Plenty’s bankruptcy, PitchBook on Bowery shutting down, AeroFarms on its recapitalization process, and SEC filings on AppHarvest’s Chapter 11 process.
For funding rounds and closures from July to October 2026, key sources include: Partech on Breedr’s $27 million Series B, AgFunderNews on the 80 Acres Farms wind-down, Aramco Ventures on Mitti Labs’ $9.5 million Series A, HortiDaily on Hippo Harvest’s $30 million Series C, and AgFunderNews on Breedr’s lead investor.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us