What are the current funding trends in AI customer support?
Whether you're building or investing in the AI customer support market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
AI customer support funding is reaching record levels in 2026, but the boom is overwhelmingly concentrated among a few enterprise AI platforms. Investment reached $2.71 billion across 36 deals through September 15, up 177.5% year over year, even as smaller financing rounds collectively attracted less capital.
The gap between headline growth and ordinary fundraising is striking. Excluding rounds above $50 million, investment actually declined 38.2% to $232.9 million. Without the largest deals, the market is raising almost exactly what it raised during the equivalent period in 2024.
Funding concentration has reached an exceptional level. Six rounds above $100 million captured approximately 87% of all capital, while the five largest transactions alone represented 82.9%. Sierra's $950 million financing accounted for roughly 35% of the market.
More companies are getting funded, but participation isn't expanding nearly as quickly as investment. The number of funded startups increased from 32 to 35, and median round size rose only 13.2%, from $7.2 million to $8.15 million.
The early-stage picture is less encouraging. Seed and Series A funding declined from $220.7 million to $191.9 million despite an additional deal. First financings increased from 10 to 12, but their median size fell to $1.86 million, down from $3.04 million two years earlier.
Autonomous customer-support agents continue to dominate investment, attracting at least $2.2 billion across 25 deals. Yet their median financing fell from $8 million to $7 million. Investors are writing enormous checks for a handful of leaders while typical financing amounts in the category are shrinking.
Contact-center automation is experiencing a different kind of expansion. Its deal count rose from five to eight, bringing its share of fundraising activity to 20%. Together, autonomous agents and contact-center automation now account for the large majority of transactions and capital.
The geography of fundraising is changing too. Europe's deal count doubled to 14, nearly matching North America's 15, but North American companies still attracted $1.51 billion versus Europe's $472.3 million. Meanwhile, disclosed corporate-investor participation rose from two deals to six.
Some of the largest recipients are moving beyond customer support altogether. Wonderful raised $700 million across two rounds while expanding toward an enterprise AI operating system. That broadening creates a classification challenge: customer-support funding totals increasingly capture investment in much larger enterprise automation businesses.
The clearest trend is a widening financing advantage for enterprise platforms with commercial traction. Investors are backing real deployments, major customers and broader automation capabilities with unprecedented sums. Smaller startups can still raise money, but the typical check is increasingly disconnected from the industry's record headline investment.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the AI customer support market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the AI customer support market over the last years
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our report covering the AI customer support market.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| Karta AI | Autonomous Support Agents | October 2026 | Seed | $3M | Builds autonomous inbound voice agents that resolve banking and insurance customer-service requests. | Asia-Pacific | PeerCapital, Cedar Hill Capital | India | |
| FLÆ Robotics | Autonomous Support Agents | October 2026 | Seed | $1.1M+ | Offers an AI hotel guest-service agent that answers inquiries and handles reservations and front-desk requests. | Europe | Not disclosed | Czech Republic | |
| Flai | Contact Center Automation | October 2026 | Series A | $27M | AI voice agents for auto dealerships | North America | Base10 Partners | United States | |
| Siena AI | Autonomous Support Agents | October 2026 | Series A | $17M | Empathetic autonomous customer service agents | North America | York IE | United States | |
| Flyle | QA & Conversation Analytics | October 2026 | Series A | ~$12M | AI customer feedback analytics | Asia-Pacific | Not disclosed | Japan | |
| Parakeet Health | Autonomous Support Agents | October 2026 | Series A | $10M | AI patient access and scheduling agents | North America | Canvas Ventures | United States | |
| Decimal AI | Autonomous Support Agents | September 2026 | Seed | $4M | AI customer support and service automation | North America | Khosla Ventures, Kearny Jackson | United States | |
| Wonderful | Autonomous Support Agents | September 2026 | Series C | $550M | Enterprise AI customer service agents | Middle East | Insight Partners | Israel | |
| Capacity | Support Workflow Orchestration | September 2026 | Series D+ | $54M+ | AI-native customer support automation platform | North America | Kathy Ireland | United States | |
| Language I/O | Agent Assist Copilots | September 2026 | Growth Equity | $1.5M | AI-powered multilingual customer support translation | North America | Not disclosed | United States | |
| Wilmo AI | Autonomous Support Agents | August 2026 | Seed | ~$1.3M | AI customer support for ecommerce | Europe | Ugly Duckling Ventures | Denmark | |
| Omilia | Contact Center Automation | August 2026 | Series B | $67M | Enterprise conversational voice AI automation | Europe | Expedition Growth Capital | Cyprus | |
| Cue | Autonomous Support Agents | July 2026 | Unknown | $5M | AI customer service across messaging channels | Africa | Knife Capital, FAM Investments | South Africa | |
| Assort Health | Autonomous Support Agents | June 2026 | Series C | $120M | AI agents answering healthcare patient requests | North America | Menlo Ventures | United States | |
| Chaty AI | Contact Center Automation | June 2026 | Seed | $1.2M | AI phone and chat agents for tourism | Asia-Pacific | Not disclosed | Australia | |
| Mimir | Autonomous Support Agents | June 2026 | Seed | ~$600K | AI support agents for customer service teams | Europe | Sondo Capital | Norway | |
| ENERA | Autonomous Support Agents | June 2026 | Seed | $2M | EV charging operations and customer automation | Europe | Lakehouse Ventures | United Kingdom | |
| Sono | Contact Center Automation | June 2026 | Seed | $1.5M | AI phone agents for customer service | Europe | Maki.vc | Finland | |
| Centrical | QA & Conversation Analytics | June 2026 | Series D+ | $39M | AI-powered frontline workforce performance management | North America | Not disclosed | United States | |
| Gradient Labs | Autonomous Support Agents | June 2026 | Series A | $13M | Autonomous AI agents for financial services | Europe | Octopus Ventures, CommerzVentures | United Kingdom | |
| Kapture CX | Support Workflow Orchestration | June 2026 | Series A | $10M | Enterprise AI customer experience platform | Asia-Pacific | Not disclosed | India | |
| Sierra | Autonomous Support Agents | May 2026 | Series D+ | $950M | Enterprise AI customer service agents | North America | Tiger Global, GV | United States | |
| Netomi | Autonomous Support Agents | April 2026 | Series C | $110M | Autonomous AI customer support agents | North America | Accenture Ventures | United States | |
| Solidroad | QA & Conversation Analytics | April 2026 | Series A | $25M | AI customer service quality assurance | North America | Hedosophia | United States | |
| Phonely | Contact Center Automation | April 2026 | Series A | $16M | AI phone agents resolving customer calls | North America | Base10 Partners | United States | |
| GuruSup | Autonomous Support Agents | April 2026 | Seed | ~$1.5M | Business AI agents across departments | Europe | 4Founders Capital | Spain | |
| Gnani.ai | Contact Center Automation | March 2026 | Series B | $10M | Multilingual enterprise conversational voice AI | Asia-Pacific | Aavishkaar Capital | India | |
| Minimal AI | Autonomous Support Agents | March 2026 | Seed | $3.6M | AI customer support agents | Europe | Not disclosed | Netherlands | |
| Wonderful | Autonomous Support Agents | March 2026 | Series B | $150M | Enterprise AI customer service agents | Middle East | Insight Partners | Israel | |
| Nurix AI | Autonomous Support Agents | March 2026 | Unknown | $15M | AI voice and chat agents | Asia-Pacific | Not disclosed | India | |
| 14.ai | Autonomous Support Agents | March 2026 | Seed | $3M | AI customer support agents | North America | Y Combinator | United States | |
| Scala | QA & Conversation Analytics | February 2026 | Seed | $8.5M | AI customer support automation platform | North America | Madrona Venture Group, FUSE VC | United States | |
| Tactful AI | Autonomous Support Agents | February 2026 | Unknown | $1M | AI agents for customer service operations | Africa | Foras AI, M Empire | Egypt | |
| Decagon | Autonomous Support Agents | January 2026 | Series D+ | $250M | AI-powered enterprise customer support agents | North America | Coatue, Index Ventures | United States | |
| Level3AI | Autonomous Support Agents | January 2026 | Seed | $13M | Enterprise AI customer engagement agents | Asia-Pacific | Lightspeed Venture Partners | Singapore | |
| Elyos AI | Autonomous Support Agents | January 2026 | Series A | $13M | AI voice agents for trades | Europe | Blackbird Ventures | United Kingdom | |
| Parloa | Contact Center Automation | January 2026 | Series D+ | $350M | Enterprise AI customer service agents | Europe | General Catalyst | Germany | |
| Fini | Autonomous Support Agents | January 2026 | Seed | $3.6M | AI customer support agents | Europe | Matrix Partners | Netherlands | |
| Flip | Contact Center Automation | January 2026 | Series A | $20M | AI phone customer service automation | North America | Next Coast Ventures, Ridge Ventures | United States | |
| Open.cx | Autonomous Support Agents | January 2026 | Seed | $7M | Omnichannel AI customer support platform | North America | Y Combinator, X by Unifonic | United States | |
| PolyAI | Contact Center Automation | December 2025 | Series D+ | $86M | Conversational AI voice customer agents | Europe | Georgian, Hedosophia, Khosla Ventures | United Kingdom | |
| Fin | Autonomous Support Agents | December 2025 | Series A | $17M | High-value payments settled using stablecoins | North America | Pantera Capital | United States | |
| Language I/O | Agent Assist Copilots | December 2025 | Unknown | $1.5M | AI-powered multilingual customer support translation | North America | Not disclosed | United States | |
| GetVocal | Autonomous Support Agents | November 2025 | Series A | $26M | Hybrid human-AI customer support agents | Europe | Creandum | France | |
| Vida | Contact Center Automation | November 2025 | Series A | $4M | AI phone agents for customer operations | North America | Trammell Venture Partners | United States | |
| Wonderful | Autonomous Support Agents | November 2025 | Series A | $100M | Enterprise AI customer service agents | Middle East | Index Ventures | Israel | |
| IVRy | Contact Center Automation | November 2025 | Series D+ | ~$26M | AI voice and telephone automation | Asia-Pacific | Not disclosed | Japan | |
| Giga | Autonomous Support Agents | November 2025 | Series A | $61M | Enterprise AI customer support agents | North America | Redpoint Ventures | United States | |
| WIZ.AI | Contact Center Automation | November 2025 | Series B | $20M | Multilingual enterprise conversational voice agents | Asia-Pacific | SMBC Asia Rising Fund | Singapore | |
| Octonomy | Autonomous Support Agents | November 2025 | Seed | $20M | AI agents for technical support | Europe | Macquarie Capital Venture Capital | Germany | |
| Aunoa | Autonomous Support Agents | October 2025 | Unknown | ~$1.8M | Conversational AI for customer support | Europe | Faraday Venture Partners | Spain | |
| Uniphore | QA & Conversation Analytics | October 2025 | Series D+ | $260M | Enterprise conversational AI and analytics | North America | NVIDIA, AMD Ventures, Snowflake Ventures, Databricks | United States | |
| Hyro | Autonomous Support Agents | October 2025 | Growth Equity | $45M | Healthcare conversational AI agents | North America | Healthier Capital | United States | |
| GreyLabs AI | QA & Conversation Analytics | October 2025 | Series A | ~$10M | Voice AI agents for financial services | Asia-Pacific | Elevation Capital | India | |
| Flai | Contact Center Automation | October 2025 | Seed | $4.5M | AI voice agents for auto dealerships | North America | First Round Capital | United States | |
| Assort Health | Autonomous Support Agents | September 2025 | Series B | $76M | AI agents answering healthcare patient requests | North America | Lightspeed Venture Partners | United States | |
| Notch.cx | Autonomous Support Agents | September 2025 | Seed | $7M | AI customer support automation for ecommerce | Middle East | Lightspeed Venture Partners | Israel | |
| DOO | Autonomous Support Agents | September 2025 | Unknown | $1.7M | AI customer service agents for businesses | Middle East | Merak Capital | Saudi Arabia | |
| Rulebase | QA & Conversation Analytics | September 2025 | Seed | $2.1M | Customer support quality monitoring and coaching | North America | Bowery Capital | United States | |
| Clarity | QA & Conversation Analytics | September 2025 | Series A | $12M | AI customer support for service teams | Europe | Prosus Ventures, STV AI Fund | United Kingdom | |
| Parahelp | Autonomous Support Agents | September 2025 | Series A | $18M | AI agents automating customer support | North America | Alt Capital | United States | |
| Eloquent AI | Support Workflow Orchestration | September 2025 | Seed | $7.4M | AI operators for financial service workflows | North America | Foundation Capital | United States | |
| Quack | Autonomous Support Agents | September 2025 | Seed | $7M | AI support agents for software companies | North America | Hanaco Ventures, Storytime Capital | United States | |
| Parahelp | Autonomous Support Agents | September 2025 | Seed | $3.2M | AI agents automating customer support | North America | Hidden Capital | United States | |
| Inkeep | Knowledge & Answer Engines | September 2025 | Seed | $13M | AI agent development platform | North America | Khosla Ventures, GreatPoint Ventures, Y Combinator | United States | |
| Sierra | Autonomous Support Agents | September 2025 | Series D+ | $350M | Enterprise AI customer service agents | North America | Greenoaks | United States | |
| Hello Patient | Autonomous Support Agents | September 2025 | Series A | $23M | AI agents for patient communications | North America | Scale Venture Partners | United States | |
| Rauda AI | Autonomous Support Agents | September 2025 | Seed | $2.8M | AI customer support automation software | Europe | JME Ventures | Spain | |
| Cavalry AI | Autonomous Support Agents | August 2025 | Seed | $2.1M | AI support and shopping agents for ecommerce | North America | Not disclosed | United States | |
| Kustomer | Support Workflow Orchestration | August 2025 | Series B | $30M | AI-powered customer service CRM | North America | Norwest | United States | |
| Lorikeet | Autonomous Support Agents | August 2025 | Series A | $35M | AI customer service concierge agents | Asia-Pacific | QED Investors | Australia | |
| Pylon | Support Workflow Orchestration | August 2025 | Series B | $31M | AI-powered B2B customer support platform | North America | Andreessen Horowitz, Bain Capital Ventures | United States | |
| Capacity | Support Workflow Orchestration | August 2025 | Series D+ | $17M | AI-native customer support automation platform | North America | Not disclosed | United States | |
| Gradient Labs | Autonomous Support Agents | July 2025 | Series A | $13M | Autonomous AI agents for financial services | Europe | Redpoint Ventures | United Kingdom | |
| Brainfish | Knowledge & Answer Engines | July 2025 | Seed | $6.6M | Proactive AI in-product customer support | Asia-Pacific | Prosus Ventures | Australia | |
| Wonderful | Autonomous Support Agents | July 2025 | Seed | $34M | Enterprise AI customer service agents | Middle East | Index Ventures | Israel | |
| Waypoint AI | Autonomous Support Agents | June 2025 | Seed | $3.1M | AI customer support resolution agents | North America | 42CAP, Dreamcraft Ventures | United States | |
| Synthflow AI | Contact Center Automation | June 2025 | Series A | $20M | Voice agents answering and routing customer calls | Europe | Accel | Germany | |
| Decagon | Autonomous Support Agents | June 2025 | Series C | $131M | AI-powered enterprise customer support agents | North America | Accel, Andreessen Horowitz | United States | |
| Maven AGI | Autonomous Support Agents | June 2025 | Series B | $50M | Enterprise AI customer service automation | North America | Dell Technologies Capital | United States | |
| Toma | Contact Center Automation | June 2025 | Series A | $17M | AI phone agents for dealerships | North America | Andreessen Horowitz | United States | |
| Solidroad | QA & Conversation Analytics | June 2025 | Seed | $6.5M | AI customer service quality assurance | North America | First Round Capital | United States | |
| OmniChat | Support Workflow Orchestration | June 2025 | Series B | $9M | WhatsApp sales and marketing automation | Latin America | Quartzo Capital, Altitude Ventures | Brazil | |
| Forethought | Autonomous Support Agents | May 2025 | Series D+ | $25M | AI customer support automation platform | North America | Blue Cloud Ventures | United States | |
| Voyc | QA & Conversation Analytics | May 2025 | Seed | $2M | AI quality monitoring for customer conversations | Europe | Not disclosed | Netherlands | |
| Parloa | Contact Center Automation | May 2025 | Series C | $120M | Enterprise AI customer service agents | Europe | Durable Capital Partners, Altimeter Capital, General Catalyst | Germany | |
| CallMiner | QA & Conversation Analytics | May 2025 | Growth Equity | $7.5M | AI speech and conversation analytics | North America | Not disclosed | United States | |
| Assort Health | Autonomous Support Agents | April 2025 | Series A | $22M | AI agents answering healthcare patient requests | North America | First Round Capital, Chemistry | United States | |
| Loopia | Autonomous Support Agents | February 2025 | Seed | ~$640K | AI sales and support agents | Latin America | Funses I | Brazil | |
| Reddy | Agent Assist Copilots | February 2025 | Seed | $2M | AI customer support automation software | North America | DA Ventures | United States | |
| Sanas | Agent Assist Copilots | February 2025 | Series B | $65M | Real-time speech and accent AI | North America | Quadrille Capital | United States | |
| Plain | Support Workflow Orchestration | February 2025 | Series A | $15M | AI-powered B2B customer support platform | Europe | Battery Ventures | United Kingdom | |
| ToumAI | Contact Center Automation | February 2025 | Seed | ~$1M | Conversational AI for customer service teams | Africa | Launch Africa | Morocco | |
| Ushur | Support Workflow Orchestration | February 2025 | Series D+ | $15M | AI-powered customer communication automation | North America | Not disclosed | United States | |
| Lorikeet | Autonomous Support Agents | February 2025 | Unknown | $9M | AI customer service concierge agents | Asia-Pacific | Blackbird | Australia | |
| Octonomy | Autonomous Support Agents | February 2025 | Seed | $5.5M | AI agents for technical support | Europe | Capnamic | Germany | |
| GetVocal | Autonomous Support Agents | January 2025 | Seed | ~$2.8M | Hybrid human-AI customer support agents | Europe | Speedinvest, Elaia Partners | France | |
| Applied Labs | Autonomous Support Agents | January 2025 | Seed | $4.2M | AI customer support automation platform | North America | Abstract Ventures | United States | |
| Intryc | QA & Conversation Analytics | January 2025 | Seed | $3.1M | AI customer support quality assurance | North America | General Catalyst | United States | |
| Mojo-CX | QA & Conversation Analytics | January 2025 | Growth Equity | ~$2.8M | AI customer service conversation platform | Europe | NPIF II – Praetura Equity Finance | United Kingdom | |
| Open.cx | Autonomous Support Agents | January 2025 | Seed | $1.5M | Omnichannel AI customer support platform | North America | Not disclosed | United States | |
| Carecode | Autonomous Support Agents | December 2024 | Seed | $4.3M | AI agents for healthcare customer service | Latin America | Andreessen Horowitz, QED Investors | Brazil | |
| Yampa | Autonomous Support Agents | December 2024 | Seed | $3.2M | Autonomous AI customer service agents | Europe | Partech | France | |
| Hyro | Autonomous Support Agents | December 2024 | Series B | $15M | Healthcare conversational AI agents | North America | Healthier Capital | United States | |
| Scorebuddy | QA & Conversation Analytics | November 2024 | Growth Equity | ~$5.2M | Contact center quality assurance software | Europe | Foresight Group | Ireland | |
| LearnWise AI | Knowledge & Answer Engines | November 2024 | Seed | ~$2.1M | AI support assistants for higher education | Europe | Emerge | Netherlands | |
| Cresta | Contact Center Automation | November 2024 | Series D+ | $125M | AI-powered contact center platform | North America | World Innovation Lab, QIA | United States | |
| CommBox | Contact Center Automation | November 2024 | Growth Equity | $15M | Omnichannel AI customer service platform | Middle East | PSG Equity | Israel | |
| Hello Patient | Autonomous Support Agents | October 2024 | Seed | $6.3M | AI agents for patient communications | North America | 8VC | United States | |
| Sierra | Autonomous Support Agents | October 2024 | Series C | $175M | Enterprise AI customer service agents | North America | Greenoaks | United States | |
| interface.ai | Autonomous Support Agents | October 2024 | Growth Equity | $20M | AI banking customer service agents | North America | Avataar Venture Partners | United States | |
| Decagon | Autonomous Support Agents | October 2024 | Series B | $65M | AI-powered enterprise customer support agents | North America | Bain Capital Ventures | United States | |
| Neuron7.ai | Knowledge & Answer Engines | October 2024 | Series B | $44M | AI technical service resolution intelligence | North America | Smith Point Capital | United States | |
| Parakeet Health | Autonomous Support Agents | October 2024 | Seed | $3M | AI patient access and scheduling agents | North America | Canvas Ventures | United States | |
| Lorikeet | Autonomous Support Agents | October 2024 | Seed | $5M | AI customer service concierge agents | Asia-Pacific | Square Peg | Australia | |
| Kapa.ai | Knowledge & Answer Engines | October 2024 | Seed | $3.2M | AI support agent for technical products | Europe | Initialized Capital | Denmark | |
| Crescendo | Autonomous Support Agents | October 2024 | Series C | Undisclosed | Augmented AI customer experience platform | North America | Not disclosed | United States | |
| Numa | Contact Center Automation | October 2024 | Series B | $32M | AI phone and messaging for dealerships | North America | Touring Capital, Mitsui & Co | United States | |
| Capacity | Support Workflow Orchestration | October 2024 | Series D+ | $26M+ | AI-native customer support automation platform | North America | TVC Capital | United States | |
| UJET | Contact Center Automation | September 2024 | Series D+ | $76M | Cloud contact center AI platform | North America | Sapphire Ventures | United States | |
| Engaige | Autonomous Support Agents | September 2024 | Seed | ~$1.1M | AI agents for customer service teams | Europe | Graduate Entrepreneur Fund | Netherlands | |
| Rauda AI | Autonomous Support Agents | September 2024 | Seed | ~$576K | AI customer support automation software | Europe | Not disclosed | Spain | |
| Gladly | Support Workflow Orchestration | September 2024 | Series D+ | $40M | AI-powered customer service platform | North America | Not disclosed | United States | |
| Phonely | Contact Center Automation | September 2024 | Seed | ~$3M | AI phone agents resolving customer calls | North America | Not disclosed | United States | |
| Convin | QA & Conversation Analytics | August 2024 | Series A | $6.5M | AI-powered conversation intelligence platform | Asia-Pacific | India Quotient | India | |
| Gradient Labs | Autonomous Support Agents | August 2024 | Seed | ~$3.6M | Autonomous AI agents for financial services | Europe | LocalGlobe | United Kingdom | |
| Unthread | Ticket Triage & Routing | August 2024 | Seed | $3M | AI-native customer support ticketing | North America | Not disclosed | United States | |
| DevRev | Support Workflow Orchestration | August 2024 | Series A | $101M | AI-native customer support and product platform | North America | Khosla Ventures | United States | |
| Pylon | Support Workflow Orchestration | August 2024 | Series A | $17M | AI-powered B2B customer support platform | North America | Not disclosed | United States | |
| Gnani.ai | Contact Center Automation | July 2024 | Series A | $4M | Multilingual enterprise conversational voice AI | Asia-Pacific | Info Edge Ventures | India | |
| Siena AI | Autonomous Support Agents | July 2024 | Seed | $6M | Empathetic autonomous customer service agents | North America | Not disclosed | United States | |
| Level AI | QA & Conversation Analytics | July 2024 | Series C | $39M | AI contact center performance analytics | North America | Adams Street Partners | United States | |
| Vida | Contact Center Automation | July 2024 | Seed | $3M | AI phone agents for customer operations | North America | Stillmark | United States | |
| Language I/O | Agent Assist Copilots | July 2024 | Series D+ | $5M | AI-powered multilingual customer support translation | North America | Not disclosed | United States | |
| Solidroad | QA & Conversation Analytics | July 2024 | Seed | $1.2M | AI customer service quality assurance | North America | Not disclosed | United States | |
| Synthflow AI | Contact Center Automation | June 2024 | Seed | $7.4M | Voice agents answering and routing customer calls | Europe | Singular | Germany | |
| Decagon | Autonomous Support Agents | June 2024 | Series A | $30M | AI-powered enterprise customer support agents | North America | Accel | United States | |
| Decagon | Autonomous Support Agents | June 2024 | Seed | $5M | AI-powered enterprise customer support agents | North America | Andreessen Horowitz | United States | |
| GreyLabs AI | QA & Conversation Analytics | June 2024 | Seed | $1.5M+ | Voice AI agents for financial services | Asia-Pacific | Z47 | India | |
| Cognigy | Contact Center Automation | June 2024 | Series C | $100M | Conversational AI agents for customer service | Europe | Eurazeo Growth | Germany | |
| Neople | Agent Assist Copilots | June 2024 | Seed | ~$6.5M | AI customer service agents for support teams | Europe | Newion, Simon Capital | Netherlands | |
| Maven AGI | Autonomous Support Agents | May 2024 | Series A | $20M | Enterprise AI customer service automation | North America | M13 | United States | |
| IVRy | Contact Center Automation | May 2024 | Series C | ~$19M | AI voice and telephone automation | Asia-Pacific | ALL STAR SAAS FUND | Japan | |
| PolyAI | Contact Center Automation | May 2024 | Series C | $50M | Conversational AI voice customer agents | Europe | Hedosophia, NVIDIA | United Kingdom | |
| Brainfish | Knowledge & Answer Engines | May 2024 | Seed | $2.5M | Proactive AI in-product customer support | Asia-Pacific | Peak XV Partners' Surge | Australia | |
| Gorgias | Autonomous Support Agents | May 2024 | Series C | $29M | Ecommerce AI customer support automation | North America | Not disclosed | United States | |
| Parloa | Contact Center Automation | April 2024 | Series B | $66M | Enterprise AI customer service agents | Europe | Altimeter Capital | Germany | |
| Maven AGI | Autonomous Support Agents | April 2024 | Seed | $8M | Enterprise AI customer service automation | North America | Lux Capital | United States | |
| Kodif | Support Workflow Orchestration | April 2024 | Seed | $3M | Post-purchase support and returns resolution agents | North America | Not disclosed | United States | |
| Klark | Agent Assist Copilots | March 2024 | Seed | ~$1.9M | AI support agents for customer service | Europe | Not disclosed | France | |
| Aimiable | Support Workflow Orchestration | March 2024 | Unknown | $3.1M | AI customer support automation software | North America | Not disclosed | United States | |
| Assort Health | Autonomous Support Agents | March 2024 | Seed | $3.5M | AI agents answering healthcare patient requests | North America | Quiet Capital | United States | |
| Neuron7.ai | Knowledge & Answer Engines | March 2024 | Unknown | Undisclosed | AI technical service resolution intelligence | North America | Not disclosed | United States | |
| Cue | Autonomous Support Agents | February 2024 | Seed | $1.5M | AI customer service across messaging channels | Africa | Not disclosed | South Africa | |
| NLX | Contact Center Automation | February 2024 | Series A | $12M | AI voice agents for customer service | North America | Cercano | United States | |
| Rasa | Contact Center Automation | February 2024 | Series C | $30M | AI agent development platform for enterprises | Europe | StepStone Group, PayPal Ventures | Germany | |
| Sierra | Autonomous Support Agents | February 2024 | Unknown | $110M | Enterprise AI customer service agents | North America | Sequoia Capital, Benchmark | United States | |
| Intryc | QA & Conversation Analytics | February 2024 | Seed | $1.1M | AI customer support quality assurance | North America | Not disclosed | United States | |
| Kore.ai | Contact Center Automation | January 2024 | Growth Equity | $150M | Enterprise conversational AI automation platform | North America | FTV Capital | United States |

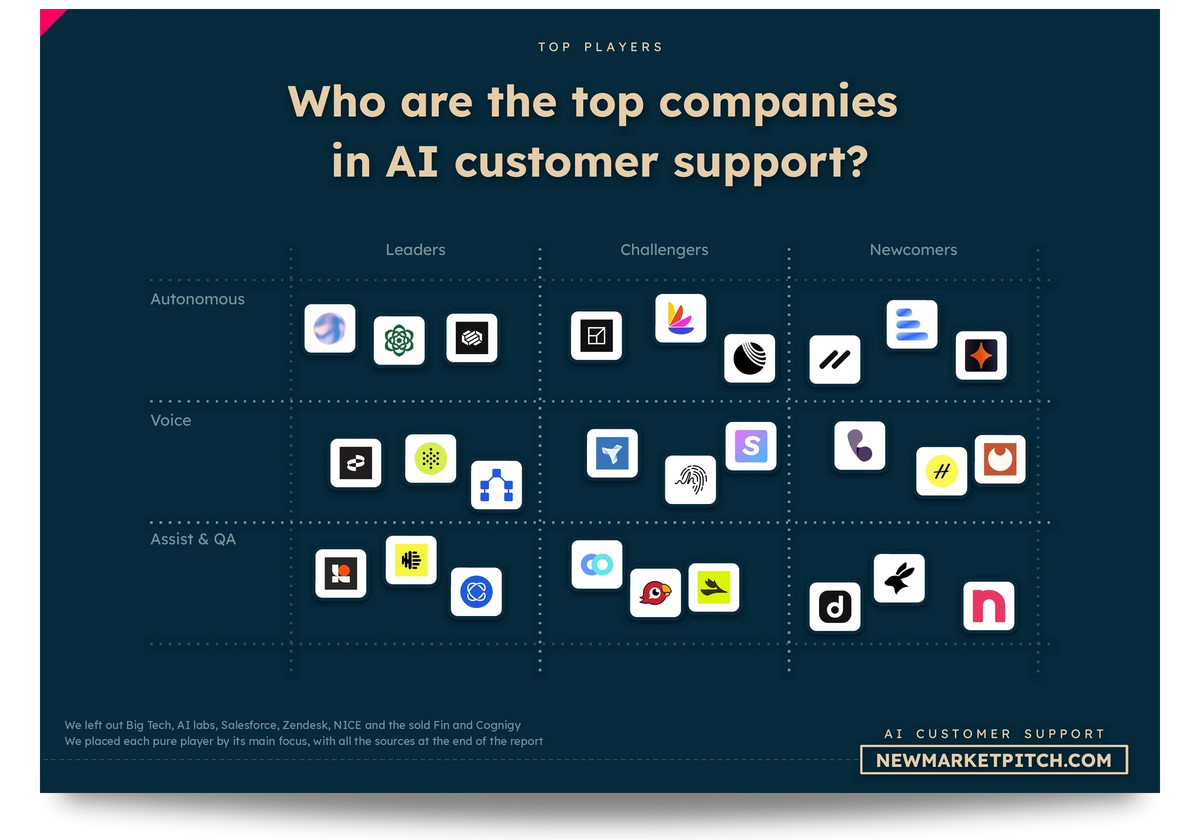
In our research about AI customer support tools, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is AI customer support funding really booming in 2026?
AI customer support funding is reaching record levels in 2026, but most startups are seeing nothing close to the boom suggested by the headline numbers.
We counted at least $2.9 billion raised across 40 financings from January 1 to October 31, 2026, up from $1.6 billion during the same period in 2025. Two years ago, funding stood at $1.4 billion across 51 deals.
The surprising part is how little deal activity has changed lately. The number of financings increased by only 5.9% year over year, while the number of companies raising money grew from 32 to 35. Median financing increased just 13.2%, from $7.2 million to $8.15 million.
Meanwhile, average financing jumped from $28.8 million to $75.4 million. That unusually large gap between the median and average points toward a handful of enormous transactions.
Companies such as Sierra, Wonderful, Parloa and Decagon explain much of the difference. These businesses are attracting hundreds of millions of dollars per round, while most other customer-support startups continue raising considerably smaller amounts.
| Funding metric | 2024 YTD | 2025 YTD | 2026 YTD |
|---|---|---|---|
| Total funding | $506.14M | $977.88M | $2,713.88M |
| Number of deals | 23 | 34 | 36 |
| Funded companies | 22 | 32 | 35 |
| Median round | $6.50M | $7.20M | $8.15M |
| Average round | $22.01M | $28.76M | $75.39M |
| Largest round | $110M | $350M | $950M |
| Funding excluding rounds above $50M | $230.14M | $376.88M | $232.88M |
| Funding excluding rounds above $100M | $396.14M | $376.88M | $353.88M |
| Share captured by three largest deals | 54.5% | 61.5% | 68.2% |
Would AI customer support funding still be growing without the biggest deals?
Without the biggest AI customer support financings, the market would actually be shrinking in dollar terms this year.
We removed every round above $50 million from our calculations. The result was $232.9 million in remaining 2026 funding, down from $376.9 million in 2025. That's a 38.2% contraction beneath a headline market that grew 177.5%.
The comparison with 2024 is even more revealing. Funding below that threshold totaled $230.1 million two years ago, almost exactly the same as today.
Even excluding only rounds above $100 million changes the picture significantly. Funding falls to $353.9 million, compared with $376.9 million in 2025 and $396.1 million in 2024.
Six financings above $100 million account for approximately 87% of all money raised in 2026.
For a startup raising $5 million or $20 million, the funding environment can therefore feel relatively normal, or even difficult, while the market's total investment appears to be exploding.
There are still plenty of smaller deals, but much less money is flowing through ordinary financing rounds than the headline totals suggest.

Your time is limited. In our market report about AI customer support tools, we put numbers on each part of the market, so you can see where it makes sense to focus.
Are more AI customer support startups actually getting funded?
Fewer AI customer support startups are receiving investment in 2026: 39 companies raised money, compared with 48 last year.
That 9.4% increase is meaningful, but it represents just three additional companies.
The two-year comparison is more encouraging. In 2024, only 22 companies received funding during the equivalent period. The number of funded businesses has therefore risen nearly 60% in two years.
The market is still attracting new participants, especially around autonomous customer-service agents and AI-powered contact centers. What has changed most is how much money the largest companies can raise once they become established.
Wonderful illustrates that distinction particularly well. It completed two financings during 2026, raising $150 million in March and another $550 million in September. Those two transactions represent $700 million, equivalent to 25.8% of the market's total funding.
Most companies are operating on an entirely different financing scale. Only one business in the current cohort recorded multiple rounds, so repeat financing across many companies cannot explain the market-wide increase.
Three more companies received funding than last year. The much bigger change is the amount investors are prepared to commit to a few of them.
Why are investors putting so much money into AI customer support agents?
Investors are writing much larger checks for AI customer support agents because several leading companies have moved beyond promising demos and are now handling real customer interactions for major enterprises.
Sierra offers the clearest example. In its May 2026 funding announcement, the company said its platform served more than 40% of Fortune 50 companies and handled billions of customer interactions.
Its AI agents were performing tasks such as refinancing mortgages, processing insurance claims and handling product returns. These are more involved than answering simple support questions: they require access to business systems, reliable execution and the ability to complete requests from start to finish.
Decagon provided another concrete example when announcing its $250 million Series D in January 2026. The company said it had added more than 100 enterprise customers during its previous fiscal year, including Avis Budget Group, Block and Deutsche Telekom.
Parloa, meanwhile, reported in May that it had exceeded $50 million in annual recurring revenue, with 150% net revenue retention. Its platform supports enterprise customer interactions across voice and other channels, and the company is investing in making those agents reliable enough for large-scale deployment.
Investors can increasingly evaluate these companies against actual customers, production usage and recurring revenue rather than relying entirely on projected adoption.
The funding figures don't prove that the entire customer-service industry is adopting AI at the same pace. They do show that companies with credible enterprise deployments can attract financing on a scale previously uncommon in this market.

In our document detailing everything you need to know about AI customer support, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Which AI customer support startups are raising the biggest rounds?
Sierra is leading the AI customer support funding race in 2026, with a $950 million financing that is almost as large as the entire market's comparable funding total last year.
The May transaction, led by Tiger Global and GV, valued Sierra at more than $15 billion. It alone represented approximately 35% of the money raised by AI customer support companies during the period we studied.
Wonderful followed with a $550 million Series C in September, valuing the business at $5 billion. Parloa raised $350 million at a $3 billion valuation, while Decagon secured $250 million at a $4.5 billion valuation.
Sierra isn't the only company raising at this scale. The five largest transactions captured 82.9% of total funding, compared with 70.2% in 2025.
Other substantial rounds show that funding activity extends beyond the very top of the market. Netomi raised $110 million in April, backed by investors including Accenture Ventures and Adobe Ventures. Omilia secured $67 million in August, with Expedition Growth Capital leading the round.
The companies attracting the most funding aren't identical. Sierra and Decagon emphasize autonomous customer-service agents, while Parloa and Omilia focus heavily on enterprise contact-center automation. Netomi positions itself around agentic customer experiences in complex environments.
All are selling enterprise-focused products designed to handle customer operations at scale.
| Company | Funding | Category | Financing context |
|---|---|---|---|
| Sierra | $950M | Autonomous Support Agents | May; valuation above $15B |
| Wonderful | $550M | Autonomous Support Agents | September Series C; $5B valuation |
| Parloa | $350M | Contact Center Automation | January Series D; $3B valuation |
| Decagon | $250M | Autonomous Support Agents | January Series D; $4.5B valuation |
| Wonderful | $150M | Autonomous Support Agents | March Series B; $2B valuation |
| Netomi | $110M | Autonomous Support Agents | April; Accenture Ventures-led |
| Omilia | $67M | Contact Center Automation | August Series B |
| Capacity | More than $54M | Support Workflow Orchestration | September Series E |
Is contact-center automation becoming the hottest part of AI customer support?
Contact-center automation is attracting the fastest growth in funding activity among AI customer support categories this year, even though autonomous agents still receive far more money.
We counted 12 contact-center automation financings in 2026, up from just three in 2025. Its share of total deals jumped from 8.8% to 33.3%.
Parloa's $350 million Series D and Omilia's $67 million Series B demonstrate the category's ability to attract substantial growth capital. But the median financing declined from $22.5 million to $16.5 million.
Investors are backing many more contact-center companies, while financing amounts outside the very largest rounds remain relatively modest.
Parloa's technology lets large enterprises manage AI agents across customer-service channels. Omilia takes an approach shaped by its long experience in enterprise voice automation, combining AI capabilities with systems designed for high-volume and regulated customer interactions.
Phonely adds a different kind of example. The company announced a $16 million Series A led by Base10 Partners, with participation from contact-center operators and enterprise customers including Etech Global Services, TSA Group and Engage CX.
These businesses are approaching the contact-center market from different directions, helping explain why financing activity has become more widespread.
There's one important qualification: contact-center automation already represented 30.4% of recorded AI customer support deals in 2024. Its current 33.3% share looks more like a strong recovery from a weak 2025 than the beginning of an entirely new category.

Our report covering the AI customer support market gets updated several times a month, so you always get the latest view of where things stand.
Are investors losing interest in autonomous AI customer support agents?
Investors are still pouring money into autonomous AI support agents, but smaller companies in the category are no longer raising larger rounds on average.
We recorded 20 autonomous-agent financings in both 2025 and 2026. Yet capital increased from $720.5 million to approximately $2.08 billion.
That extraordinary increase came alongside a decline in median round size, from $8 million to $7 million.
Sierra, Wonderful, Decagon and Netomi attracted some of the industry's largest investments, while the typical autonomous-agent financing became significantly smaller.
The category's share of all financing deals also slipped from 58.8% to 55.6%, partly because contact-center automation became much more active.
Looking back further, autonomous support agents accounted for only 22 transactions and 34% of funding in 2024. Their current position reflects a major two-year expansion, even if recent financing growth has become much more concentrated.
Some smaller autonomous-agent businesses may now face stronger competition from heavily financed platforms. Large companies can invest more in enterprise sales, security requirements, integrations and support teams.
Funding announcements alone cannot establish whether that competition is preventing smaller companies from raising. But the sharp decline in median round size makes one thing clear: record investment in autonomous agents doesn't mean financing conditions are improving at every level.
Are smaller AI customer support software categories disappearing?
Standalone AI customer support tools are receiving less financing attention as autonomous agents and contact-center platforms take over a larger share of the market.
Quality assurance and conversation analytics recorded three financings in 2026, compared with five last year. Their median round size actually increased from $3.1 million to $8.5 million, so fewer transactions didn't translate into weaker financing for every company.
Support workflow orchestration recorded just two deals, down from seven. One of those transactions involved Capacity, which announced more than $50 million in Series E financing in September.
The company had already reported reaching $100 million in annual recurring revenue and was expanding a platform combining AI customer-service automation, knowledge orchestration, quality assurance and related workflows.
Other narrower categories, including agent-assist copilots, knowledge and answer engines, and ticket triage, recorded no transactions during the current period after each attracting one financing in 2025.
Those samples are too small to claim investors have abandoned these products. The functions themselves are also increasingly available inside larger support platforms.
Capacity illustrates this development: customers can obtain multiple customer-experience capabilities through an integrated offering rather than buying independent tools for every workflow.
Two categories now account for the large majority of current financing deals and capital. Smaller categories have become less visible in fundraising, even where their underlying technology remains commercially useful.
| Category | 2024 deals | 2025 deals | 2026 deals | 2026 capital |
|---|---|---|---|---|
| Autonomous Support Agents | 7 | 20 | 20 | $2,075.1M |
| Contact Center Automation | 7 | 3 | 12 | $543.5M |
| QA & Conversation Analytics | 3 | 5 | 3 | $41.3M |
| Support Workflow Orchestration | 1 | 3 | 1 | $54M |
| Other categories combined | 5 | 3 | 0 | $0M |
| Total | 23 | 34 | 36 | $2,713.9M |
| Two leading categories' share of deals | 60.9% | 67.6% | 88.9% | 96.5% of capital |

In our research about AI customer support tools, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is it getting harder for early-stage AI customer support startups to raise money?
Early-stage AI customer support startups are still finding investors, but they're raising less money collectively than last year.
Seed and Series A financings totaled 24 deals in 2026, compared with 23 in 2025. Yet the amount raised fell from $220.7 million to $191.9 million.
Seed deals increased slightly, from 16 to 17, while total seed investment decreased from $83.2 million to $73.1 million. Series A activity stayed at seven deals, but funding declined from $137.5 million to $118.8 million.
The decline is even clearer among companies receiving their first recorded financing.
We identified 12 such deals this year, up from 10 in 2025. However, their median size declined from $2.46 million to $1.86 million, continuing a pattern that began with a $3.04 million median in 2024.
For founders, obtaining initial backing remains realistic, but the typical initial check is getting smaller.
The same evidence doesn't tell us how many startups tried and failed to raise capital, or whether investors are demanding better traction before committing.
What we can say is that more first financings are happening at smaller typical amounts, while later-stage winners are attracting disproportionately large investments.
Are AI customer support investors choosing established winners over new startups?
AI customer support investors are directing an overwhelming share of their money toward companies that have already raised funding, even as new startups continue entering the market.
First financings accounted for approximately one-third of the deals recorded this year, but just 1.5% of capital.
Follow-on financing tells the opposite story. The number of follow-on rounds stayed at 24 between 2025 and 2026, while capital rose from $920.5 million to $2.67 billion.
Median follow-on financing also increased from $14 million to $18.5 million.
This widening gap partly reflects investors funding platforms that have already demonstrated customer adoption, reached advanced financing stages or established substantial enterprise operations.
Sierra, Decagon and Wonderful offer visible examples, although their enormous individual rounds also make aggregate follow-on investment unusually sensitive to outliers.
Company age provides another useful check. The median age of funded businesses increased only slightly from approximately 1.9 to 2.0 years. Investors are making large commitments to selected companies relatively early in their corporate lives, rather than simply favoring businesses that have existed for many years.
The financial advantage for returning fundraising companies is now much larger than it was a year ago.
| Financing measure | 2024 YTD | 2025 YTD | 2026 YTD |
|---|---|---|---|
| First-financing deals | 8 | 10 | 12 |
| First-financing capital | $130.74M | $57.43M | $41.18M |
| Median first financing | $3.04M | $2.46M | $1.86M |
| First-financing share of deals | 34.8% | 29.4% | 33.3% |
| Follow-on deals | 15 | 24 | 24 |
| Follow-on capital | $375.40M | $920.45M | $2,672.70M |
| Median follow-on financing | $12M | $14M | $18.50M |
| Follow-on share of deals | 65.2% | 70.6% | 66.7% |

In our market report about AI customer support tools, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are late-stage AI customer support startups getting all the money now?
Later-stage AI customer support startups are receiving almost all the industry's additional capital in 2026, especially through Series C and Series D+ financings.
Those two stages attracted approximately $2.26 billion this year, compared with just $276 million during the same period in 2025.
Series D+ financing increased particularly sharply, from one $25 million transaction to four deals totaling approximately $1.60 billion.
Series C attracted $660 million across two rounds, compared with $251 million across two rounds last year.
The number of later-stage transactions increased from seven to nine, while early-stage deals remained essentially unchanged. Later-stage companies haven't suddenly become the majority of fundraising startups. Their individual financing commitments have become far larger.
Parloa's $350 million Series D illustrates why this can happen. Its January announcement described plans to expand internationally, invest in its AI Agent Management Platform and strengthen the reliability of enterprise deployments.
Decagon's $250 million Series D similarly followed substantial enterprise customer growth and supported a broader push into AI-powered customer experiences.
Investors appear increasingly prepared to fund expensive expansion plans when they see enough commercial progress.
A company with hundreds of millions of dollars available can pursue international customers, recruit specialized engineers and support complex deployments more aggressively than a startup operating on a small seed round.
That creates tougher competition for smaller providers selling directly against heavily funded enterprise platforms.
Is Europe catching up with the US in AI customer support funding?
Europe is nearly catching up with North America in AI customer support deal activity, but American companies are still raising much larger rounds.
European financing deals doubled from seven to 14 between the comparable 2025 and 2026 periods. North American transactions moved in the opposite direction, declining from 20 to 15.
Their deal shares are now remarkably close: Europe represents 38.9% of recorded financings and North America 41.7%.
The dollar comparison looks very different. North America attracted approximately $1.51 billion in 2026, while Europe received $472.3 million.
The typical European round also became smaller. Median financing fell from $12 million to $3.34 million. North America's median moved from $7.2 million to $20 million.
Europe's customer-support startup ecosystem is producing more fundraising activity, although its companies generally aren't receiving commitments comparable to the largest US rounds.
The Middle East adds another important dimension. Three transactions accounted for approximately $707 million, or 26.1% of total funding, heavily influenced by Wonderful.
Wonderful's financing illustrates how international operations complicate geographic comparisons. The company has Dutch and Israeli roots and operates across dozens of markets, while our data assigns it to a specific reporting region.
Regional capital totals therefore describe how companies were classified, rather than providing a complete breakdown of where their funding will be invested.
Europe's deal growth is one of the clearest signs of broader participation in the market. The much larger American financing amounts show how different the geography of startup fundraising can be from the geography of major capital commitments.

Learning from others' mistakes is the cheapest lesson there is. In our document detailing everything you need to know about AI customer support, we look at what broke startups before you, so you don't repeat it.
Are corporate investors starting to back AI customer support startups?
Corporate investors are becoming more visible in AI customer support fundraising, and several are investing directly in companies whose technology could reshape their own businesses.
We found six 2026 financing deals with disclosed strategic participants, compared with two in 2025. Their share of total transactions increased from 5.9% to 16.7%.
The examples span several different types of businesses.
Accenture Ventures led Netomi's $110 million financing in April. Accenture also announced a strategic partnership with the company to bring agentic customer-experience systems into enterprise operations.
Wonderful's September financing included Salesforce, a major provider of customer relationship management and enterprise software. Its participation is particularly relevant because autonomous customer-service agents increasingly interact with the systems companies already use to manage customer relationships.
Phonely offers a different kind of strategic backing. Its $16 million Series A included Etech Global Services, TSA Group and Engage CX, companies with direct experience operating customer-contact services.
Three of its enterprise customers participated in the financing alongside institutional investors. That's a more concrete commercial connection than a generic corporate venture investment.
Strategic participation also appears at earlier stages, including Atlassian Ventures' involvement in Decimal AI's seed financing.
Six transactions are still a small sample. The database doesn't show how much money each corporate investor contributed, and strategic investment doesn't automatically establish a commercial partnership.
But the combination of investor activity and explicitly announced operating partnerships shows a growing overlap between companies developing AI support technology and the businesses that could deploy or distribute it.
Why are AI customer support startups turning into broader enterprise AI companies?
Some of the best-funded AI customer support startups are expanding into broader enterprise automation, potentially making their addressable markets much larger while complicating how customer-support investment is measured.
Wonderful is the most important example in our current research.
When the company announced its $550 million Series C in September, it described a platform that had evolved into an enterprise AI operating system. Rather than concentrating exclusively on customer interactions, Wonderful now supports applications, internal workflows, agent orchestration and governance across different business departments.
The company reported operations in more than 35 markets and approximately 650 employees. Its investors included Insight Partners, Salesforce, Index Ventures and Bessemer Venture Partners.
Wonderful's two financing rounds are counted within the AI customer support market, even though the company now pursues a much broader enterprise opportunity.
Capacity shows a similar, though less expansive, integration strategy. Its platform combines support agents, knowledge orchestration, quality assurance and other customer-experience functions.
Sierra and Decagon also emphasize increasingly complex enterprise processes. Their agents can interact with existing business systems to complete customer requests, going well beyond producing conversational answers.
For investors, this creates the possibility of a much larger opportunity than standalone chatbot software. A platform embedded in multiple business processes may have more opportunities to expand customer spending and become difficult to replace.
For funding analysis, though, there's a classification problem.
If a company raises money for an enterprise-wide AI operating system, counting the entire round as customer-support financing may overstate how much investment is specifically directed toward that market.
Wonderful's $700 million is particularly important here. Excluding those transactions would leave approximately $2.01 billion in reported 2026 funding, still well above last year's comparable total.
As successful AI customer-support companies move into adjacent business functions, the largest future financings may increasingly come from platforms that started in customer service and expanded far beyond it.

If you build or invest in the AI customer support market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Have AI customer support startups already raised more than in all of 2025?
AI customer support companies have already raised more than twice the entire funding total recorded during 2025, making 2026 an exceptional year for large capital commitments.
Funding reached $2.71 billion by September 15, compared with $1.35 billion across the whole of 2025 and $1.11 billion across 2024.
Deal counts tell a less dramatic story. The 40 financings completed during the current period compare with the 61 deals recorded throughout 2025.
The record is overwhelmingly about the size of selected transactions.
Sierra's financing was nearly equivalent to the entire market's comparable 2025 funding. Wonderful then added another $550 million in September, following its $150 million March round.
These two companies alone have made an enormous difference to the annual total.
There's no reliable reason to assume another similarly large financing will happen before the year ends. Venture funding doesn't arrive evenly throughout the year, particularly when a market's totals depend on a few giant deals.
Still, 2026 has already established a new high for capital raised within our three-year funding sample.
Are AI customer support investors becoming more selective?
AI customer support investors appear to be becoming more selective about which companies receive large checks, while continuing to finance a reasonable number of new startups.
Three developments stand out in our research.
First, the number of funded companies is increasing slowly. The market remains accessible to new entrants.
Second, typical early-stage and initial financing amounts are getting smaller, putting more pressure on founders to build with limited capital.
Third, investors are committing unprecedented sums to a few companies that have already attracted major institutional backers and demonstrated enterprise adoption.
The top five financings now represent more than four-fifths of total market funding, a much higher concentration than during either of the previous two comparable periods.
We also found 39 distinct disclosed lead-investor names in 2026, compared with 37 in 2025. These included repeat appearances by Y Combinator, 6 Degrees Capital and Insight Partners.
That's only a modest increase in observed investor breadth despite the huge rise in capital. The boom is being driven primarily by much larger investments rather than an equally dramatic influx of new lead investors.
One limitation remains: completed deals don't reveal how many companies tried unsuccessfully to raise funding. We cannot directly measure rejection rates or establish whether investment committees have tightened their requirements.
Even so, the outcomes show an increasingly uneven market. A startup with promising technology can still obtain an initial investment, while companies with proven enterprise demand may be able to raise amounts that would have been extraordinary only a few years ago.
For founders, the question is how to reach the commercial traction needed to justify a major follow-on investment. For investors, it's distinguishing future enterprise leaders from the growing number of smaller AI agent providers competing for the same customers.

In our research about AI customer support tools, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
What is actually changing in AI customer support funding?
AI customer support funding is becoming much more concentrated, with investors putting extraordinary amounts into a few established platforms while most financing activity remains relatively modest.
The biggest change is the gap between headline capital and ordinary funding. Investment rose 177.5% year over year, but removing rounds above $50 million produces a 38.2% contraction. A few giant transactions now determine whether the entire market appears to be booming.
Fewer startups are getting funded: we counted 39 funded companies, versus 48 a year earlier, although initial financing activity remains healthy. The concern for smaller businesses is the decline in typical first-financing amounts, which have fallen for two consecutive comparison periods.
Later-stage companies are the main beneficiaries. Series C and D+ financings account for most of the increase in total capital, driven by Sierra, Wonderful, Parloa, Decagon and other heavily backed platforms.
Investor attention is also shifting within customer support. Autonomous agents dominate total dollars, while contact-center automation is attracting significantly more financing transactions. Smaller standalone categories are becoming less visible as integrated platforms offer broader sets of capabilities.
Europe is generating more fundraising activity, and corporate investors are appearing in more deals. Neither trend has yet changed the market's dependence on a limited number of very large financings.
The definition of AI customer support itself is becoming harder to maintain. Some of the most successful businesses are expanding from customer-service agents into enterprise-wide automation, meaning future funding totals may increasingly reflect investment in broader AI software platforms.
The strongest companies are gaining a substantial financing advantage. They can fund international expansion, recruit specialized teams and compete for large enterprise customers on a scale that smaller startups cannot easily match.
Whether that advantage turns into lasting market leadership will depend on customer retention, deployment reliability and commercial performance. The financing evidence already shows where investors are placing their biggest bets.
Our methodology
This analysis examines the current funding trends in AI customer support, using global private-company fundraising data across three comparable periods: January 1 to September 15, 2026; January 1 to September 15, 2025; and January 1 to September 15, 2024. We used full-year 2024 and 2025 totals only as secondary benchmarks, keeping the main comparisons aligned to equivalent reporting windows.
Our primary analysis covers 93 financing records within those periods, drawn from a broader database of 125 transactions classified in the AI customer support market. We aggregated disclosed capital, financing counts, unique funded companies, median and average round sizes, funding stages, first financings, follow-on rounds, product categories, geographic distribution and disclosed investor participation.
We structured the analysis around several questions: whether higher funding reflects more companies receiving investment, whether typical financing amounts are increasing, which stages and categories are attracting capital, and how dependent the market has become on a few exceptional transactions. For each dimension, we aggregated the financing records, compared the equivalent periods and examined the strongest patterns before drawing conclusions.
To measure concentration, we calculated funding totals after excluding individual rounds above $50 million and $100 million. We also measured the shares of capital captured by the largest transactions. These comparisons distinguish changes affecting the broader fundraising market from growth driven by exceptional financing rounds.
The market classification includes companies substantially involved in autonomous AI customer-service agents, contact-center automation, quality assurance, conversation analytics, support workflow orchestration and closely related customer-experience software. Companies expanding into broader enterprise AI remained in the recorded cohort where appropriate, but we considered that expansion when interpreting market boundaries and funding concentration.
Each separately recorded financing was treated as a distinct transaction, with attention to potential duplicates, historical funding announcements and unusually structured deals. Funding stages, investor roles and first-financing classifications followed the available transaction records and supporting disclosures. The dataset principally measures private-company equity financing, without deliberately including ordinary debt facilities, grants or unrelated public-market proceeds.
We retained disclosed amounts and database conventions where financing figures were approximate or represented lower bounds. Some totals consequently include numeric proxies rather than independently verified exact figures. Transaction-level checks concentrated on large financings, ambiguous classifications and records capable of materially affecting the findings.
We also reviewed company announcements, investor statements and financial reporting to understand enterprise adoption, revenue milestones, operational deployments, geographic expansion and strategic partnerships. Company-reported commercial metrics were treated as attributed claims. We used these developments to contextualize financing decisions without assuming that commercial progress automatically caused a particular investment.
Key financing sources include Sierra's enterprise deployment announcement and TechCrunch's reporting on Sierra's $950 million financing; Wonderful's $550 million Series C announcement, Bessemer Venture Partners' financing coverage and Wonderful's earlier $150 million Series B announcement; Parloa's $350 million Series D disclosure; and Decagon's $250 million Series D announcement.
Additional financing and investor sources include Accenture's announcement concerning Netomi, TechCrunch's coverage of Omilia's $67 million Series B, Capacity's company disclosures and Phonely's $16 million Series A announcement.
For commercial adoption, strategic development and product expansion, we also considered Parloa's enterprise deployment updates, Sierra's platform and integration disclosures, Wonderful's enterprise AI platform information and Phonely's customer implementation material. These sources provide company-level context; market-wide capital totals, stage comparisons and category shares are calculated from our financing database.
The results describe the identified financing cohort rather than every undisclosed transaction worldwide. By comparing aligned periods, separating large-round effects and checking major company developments against primary announcements and independent reporting, we assess where funding is expanding, where it is contracting and how capital allocation across the AI customer support industry is changing.

When you build or invest in the AI customer support market, you need clarity, not confusion. In our market report about AI customer support tools, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us