How big can the alternative protein market really get?
Everything we know about the alternative protein market, in one place. Get our report whether you build or invest.
Summary
Alternative protein can realistically become a $100 billion-plus global market, but getting to $200 billion or $300 billion requires breakthroughs in price, repeat purchasing, geographic reach and industrial-scale fermentation or cultivated meat that have not been demonstrated yet.
The market is already substantial, but much smaller than the protein system it is trying to disrupt. Global plant-based food sales are close to $29 billion, while conventional meat production alone exceeds 370 million tonnes a year and is still growing.
Plant-based milk is the clearest proof that alternatives can become mainstream. It has reached double-digit retail share in the United States and close to 10% of volume in Germany, while plant-based meat remains below 1% of the U.S. meat market.
The gap between milk and meat suggests that category structure matters as much as consumer attitudes. Replacing milk in coffee or cereal is simply easier than recreating chicken breast, steak, fish fillets or cheese with the same taste, texture and cooking behavior.
Price is important, but the European data show that it is not enough on its own. French plant-based meat volumes jumped as prices fell, while several weaker markets stagnated or contracted, yet consumers still pay premiums for products they consider genuinely better.
The near-term opportunity may depend more on frequency than conversion. Many households buying plant-based meat also buy conventional meat, which means the industry can grow considerably by becoming a more regular flexitarian purchase rather than persuading consumers to abandon animal protein altogether.
Product format is another hidden constraint. Alternative meat has made much more progress in burgers, nuggets, sausages and mince than in the whole cuts that account for many ordinary meals, leaving a large part of the addressable market barely touched.
Precision fermentation has a different route to scale because its proteins and fats can disappear inside ordinary products. That could eventually make it larger than branded meat substitutes, although manufacturing economics remain the decisive unresolved issue.
Cultivated meat is further behind commercially. Regulation has advanced, but current production is tiny beside global meat demand, making premium foods, fats, ingredients and hybrid products more credible early markets than direct replacement of commodity meat. Premium foods, fats and hybrids may be the early money-makers, and we compare which business models keep their margins in our market report about alternative protein.
Geography may ultimately be the toughest constraint on the largest forecasts. Europe and North America still dominate plant-based meat sales, while much of future conventional protein growth is expected in lower- and middle-income markets where affordability is much harder to solve.
The old roughly $290 billion mid-2030s scenarios are better viewed as high-adoption cases than default trajectories. Reaching that range would require several technologies and regions to accelerate at the same time, while the more defensible path today is toward a market measured in the low hundreds of billions over the longer term.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the alternative protein market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
How big is the alternative protein market today?
The alternative protein market currently generates tens of billions of dollars in retail sales, but it is still small beside the animal-protein market it hopes to disrupt.
The most useful global benchmark comes from Euromonitor data analyzed by the Good Food Institute. Plant-based meat, seafood, milk, yogurt, ice cream and cheese generated about $28.9 billion in retail sales in 2025, 3% more than a year earlier. Plant-based meat and seafood accounted for only $6.6 billion of that total.
Those figures also show why market-size estimates can become confusing. “Alternative protein” can include plant-based food, cultivated meat, precision fermentation, traditional tofu, mycoprotein and protein ingredients. Some market reports bundle most of these together; others measure only products designed to replace meat or dairy.
For this article, the roughly $29 billion plant-based retail market is the best starting point because consumers are actually buying those products at meaningful scale today. Cultivated meat still generates very little commercial food revenue, while fermentation-derived proteins are reaching more products but remain small beside conventional dairy, meat and egg supply chains.
The market is established, global and commercially relevant. Calling it a mass replacement for animal protein would still be far too early.
| Segment | Best current commercial benchmark | What it tells us |
|---|---|---|
| Global plant-based food across major categories | $28.9B | The largest measurable alternative-protein consumer market |
| Global plant-based meat and seafood | $6.6B | Meat alternatives remain a relatively small part of the total |
| U.S. plant-based milk | $2.7B | The strongest mature replacement category |
| U.S. plant-based meat and seafood | ~$1.0B | Still below 1% of the overall meat market |
| European plant-based food in six major markets | €4.75B | Large enough to reveal very different national trends |
| Precision fermentation | Commercial, but still limited | More relevant today as an ingredient platform than a mass food category |
| Cultivated meat | Very small commercial sales | Regulation has moved much faster than volume |
Is alternative protein actually replacing meat yet?
Alternative protein is taking some eating occasions from animal products, but today there is no sign of a broad global replacement of meat.
FAOSTAT puts world meat production at 374 million tonnes in 2024, alongside 985 million tonnes of milk and 100 million tonnes of eggs. These are enormous physical markets, and they are still growing.
The latest OECD-FAO outlook expects another 47.9 million tonnes of meat consumption over the coming decade. Poultry alone is projected to account for 62% of that additional consumption. World milk production is expected to reach 1.146 billion tonnes by 2034, up at an average 1.8% a year. How much of that growing meat demand alternatives can realistically take is estimated from the ground up in our alternative protein market report, with every assumption visible.
The geography makes the challenge harder. Most additional food demand is coming from low- and middle-income economies, while alternative-protein sales remain heavily concentrated in rich markets. Europe and North America currently account for almost 83% of global plant-based meat and seafood retail sales.
So alternative protein is chasing a market that keeps getting larger. Even if alternatives sell considerably more food over the next decade, animal-protein volumes can grow at the same time.
That is the baseline to keep in mind throughout the article. A big alternative-protein market does not automatically mean a shrinking meat market.

In our research about alternative proteins, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Can plant-based milk show us how big alternative protein could become?
Plant-based milk currently gives us the strongest evidence that an animal-product alternative can capture a genuine double-digit share of a mainstream category.
U.S. plant-based milk generated $2.7 billion in retail sales in 2025 and represented about 13% of total milk dollar sales. In Germany, plant-based milk reached 9.2% of retail milk volume during the same year. Private-label alternatives accounted for 60% of German plant-based milk volume, helped by prices that had become cheaper than private-label dairy milk before tax differences.
Meat looks completely different. U.S. plant-based meat and seafood generated about $1 billion in 2025 and remained below 1% of overall meat retail sales.
Milk has structural advantages. Oat or soy milk does not have to recreate the muscle fibres of steak, the skin and juiciness of chicken or the melting behavior of cheese. Coffee shops also made plant-based milk easy to try repeatedly without asking consumers to rethink an entire meal.
Yet milk teaches us another useful lesson: people can use both products. Consumers routinely keep dairy milk and oat milk in the same household, just as 96% of U.S. households buying plant-based meat also buy conventional meat.
The biggest alternative-protein market therefore does not require everyone to become vegetarian. It requires flexitarian consumers to replace animal products often enough that an alternative becomes an ordinary part of the shopping basket.
Why is plant-based meat struggling in the United States right now?
Plant-based meat is struggling in the United States because too many products still cost more without giving mainstream consumers a strong enough reason to pay the premium.
SPINS data analyzed by GFI show U.S. plant-based meat and seafood sales falling 10% in dollars and 11% in units in 2025. The category still generated about $1 billion, so consumers have hardly abandoned it, but several consecutive years of contraction have erased the idea that early growth would simply continue.
Price remains one obvious problem. Plant-based meat was around 76% more expensive per pound than conventional meat on average in U.S. retail in 2025. Consumer research cited by GFI also suggests that roughly three quarters of consumers are willing to pay no more than the conventional-meat price.
Taste and texture make that premium harder to defend. Some individual products perform well, particularly nuggets and other highly processed formats. The average product has a tougher job when it sits beside inexpensive chicken, beef or pork that consumers already know how to cook.
The category also suffers from weak repeat purchasing. Trial can create impressive household-penetration figures, but occasional curiosity does little for annual volume.
For now, U.S. plant-based meat has found a real customer base without finding the proposition that makes enough of those customers buy frequently.

In our market report about alternative proteins, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Why is plant-based meat growing in France while falling in the UK?
The latest European numbers suggest that plant-based meat can still grow quickly when price and product value move in the right direction.
GFI Europe’s 2026 analysis of Circana data found that French plant-based meat volume jumped 16.8% in 2025 while its average price fell 2.8%. Italy showed a milder version of the same pattern: volume rose 4.1% as prices fell 2%.
At the other end, UK volumes dropped 9.4% while prices increased 2.3%. Dutch volumes fell 10.7% with prices roughly flat. Germany sat between the two groups, with a 1.7% volume decline as prices rose 2%.
The pattern extends beyond meat. Total plant-based food volume grew 13% in France, 6.2% in Germany, 5.8% in Italy and 6.6% in Spain. It declined 1.3% in the Netherlands and 2.5% in the UK.
Price cannot explain every national difference. Retail distribution, brand strength, product quality and local eating habits vary too much for that. Still, six countries moving in such different directions give us a much better read than another global growth percentage.
Plant-based demand these days is highly sensitive to the deal consumers think they are getting. Where the product becomes cheaper and good options are readily available, growth can return surprisingly fast. Prices that shift demand this quickly are among the growth drivers we weigh in our report on alternative protein.
| Market | Plant-based meat volume change | Average price change | What consumers did |
|---|---|---|---|
| France | +16.8% | -2.8% | Bought substantially more |
| Italy | +4.1% | -2.0% | Bought more |
| Germany | -1.7% | +2.0% | Bought slightly less |
| Spain | -7.0% | +0.7% | Bought less |
| United Kingdom | -9.4% | +2.3% | Bought substantially less |
| Netherlands | -10.7% | +0.3% | Bought substantially less |
Would cheaper plant-based meat be enough to make the market explode?
Cheaper plant-based meat would probably bring back a lot of demand, but price parity alone will not turn a sub-1% category into a mainstream replacement for meat.
The European results above give us good evidence that prices affect volume. They also show the limit of that explanation. Germany’s plant-based milk is doing well with a narrow price gap, while its plant-based meat volumes still declined. In the UK, some relatively expensive oat and barista milks continued to perform well even as the wider plant-based market contracted.
Consumers clearly pay extra when they think the product deserves it.
That brings taste, texture and cooking performance back into the equation. A plant-based burger that costs the same as beef but tastes noticeably worse has achieved price parity without achieving product parity.
There is still a huge amount of revenue available before mass conversion. Existing U.S. plant-based meat households buy infrequently enough that one extra purchase per month across those buyers could add roughly another $1 billion in annual retail sales, according to GFI's consumer analysis.
The category could therefore roughly double its U.S. sales without converting every meat eater. Getting occasional buyers to come back more often may be a more realistic near-term growth engine than persuading millions of people to give up meat.

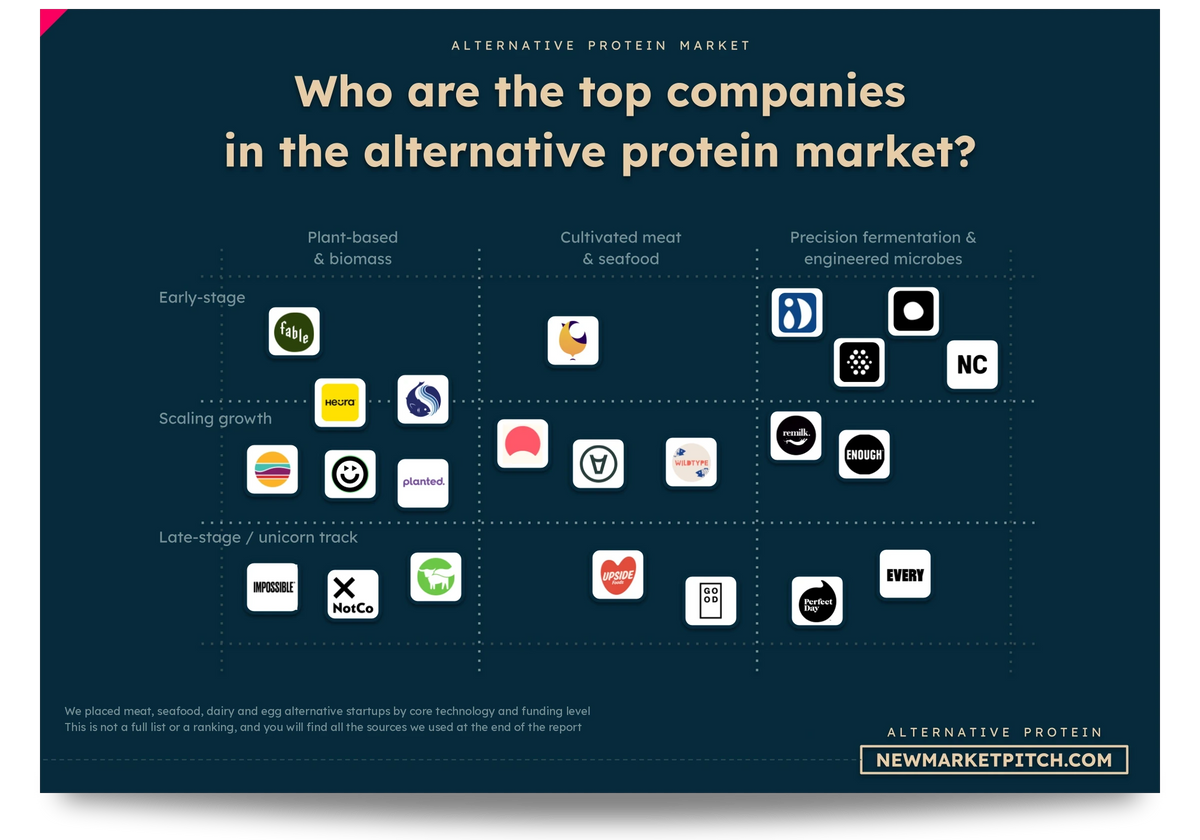
In our document detailing everything you need to know about alternative protein, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is alternative protein too focused on burgers and nuggets?
Yes. Plant-based meat has become much better at replacing processed meat than at replacing the large whole cuts people eat every week.
This creates a ceiling that is easy to miss when we only look at supermarket product counts. Burgers, sausages, mince and nuggets are technically convenient formats because manufacturers can grind, bind, flavor and reshape plant proteins.
Chicken breasts, thighs, steaks and fish fillets are much less forgiving.
Consumer research in the United States has found that nearly 70% of meat eaters regularly consume whole-cut products such as chicken breast, steak, salmon and pork chops. Roughly half regularly eat formats such as patties, sausages, deli meat or nuggets.
Yet most successful plant-based meat remains concentrated in that second group.
The UK gives us a recent example. Sausages represented 23.7% of plant-based meat volume in 2025, while breaded or battered products and burgers each accounted for another 12.4%. Together, familiar processed formats take a large part of the category.
The next major jump in market size may depend less on producing another better burger and more on cracking products such as chicken breast and fish fillets. Whole cuts open eating occasions that plant-based meat barely reaches today.
Can precision fermentation become much bigger than plant-based meat?
Precision fermentation could eventually become one of the biggest parts of alternative protein because it can enter ordinary food as an ingredient without asking consumers to buy an obvious meat substitute.
Instead of trying to recreate an animal protein with peas, soy, starches and flavoring, precision fermentation can use microorganisms to produce specific proteins or fats with properties closer to the animal-derived ingredient.
That opens very different markets. Fermentation-derived whey can go into sports nutrition. Dairy proteins can improve cheese or ice cream. Egg proteins can be used for foaming and binding. Functional fats could make plant-based or cultivated meat taste better. Fermentation-made whey, egg proteins and fats sit at very different stages of readiness, and we sort them in our report on alternative protein.
Consumers may therefore eat considerably more fermentation-derived protein without ever deciding to join an “alternative protein” market.
Commercial scale remains the hard part. GFI counted more than 160 specialist fermentation companies in 2025, yet funding fell to $357 million from $632 million a year earlier. High-profile closures and restructurings pushed investors to ask much harder questions about utilization rates, production costs and profitability.
The latest funding numbers show some life returning: fermentation companies raised $132 million during the second quarter of 2026. Even so, financing a factory is very different from proving that food-grade proteins can compete economically with dairy or eggs year after year.
Precision fermentation now looks technically credible enough to create real products. We still do not know how cheaply the industry can produce those proteins once volumes become genuinely large.

Our report covering the alternative protein market gets updated several times a month, so you always get the latest view of where things stand.
Can cultivated meat actually work at mass-market scale?
Cultivated meat has moved into real commercial food, but today we still have nowhere near enough evidence to say that it can supply mass-market meat at competitive prices.
The regulatory story has progressed much faster than the production story. Pathways now exist in markets including Singapore, the United States and Australia-New Zealand, and the range of approved or marketed products has widened to include foods such as cultivated foie gras, pork fat and salmon.
Scale is where the comparison becomes uncomfortable.
Global meat production reached 374 million tonnes in 2024. Replacing only 1% of that volume would mean roughly 3.7 million tonnes of cultivated product a year if we use a simple mass comparison.
The cultivated-meat industry currently operates nowhere close to that level.
Funding has also become much harder to find. Companies raised only about $74 million in 2025, down from $144 million a year earlier. GFI's latest figures show another $25 million raised in the second quarter of 2026. Investors are increasingly rewarding businesses that can demonstrate reliable output, falling costs or revenue outside the final food product.
That shift is useful because cultivated meat no longer needs another decade of impressive prototypes. It needs production runs that work repeatedly.
The most believable early path currently involves premium products, cultivated fats, ingredients and blended foods where a relatively small amount of cultivated material adds flavor or functionality. Those applications can become commercially useful long before a supermarket chicken breast grown entirely from cells becomes cheap.
Can alternative protein become a truly global market?
Alternative protein can become global, but the current market is still far too concentrated in Europe and North America to justify applying Western adoption rates to the rest of the world.
Euromonitor estimates that Europe and North America account for nearly 83% of global plant-based meat and seafood retail sales.
Meanwhile, the conventional protein market is gaining much of its new demand elsewhere. The OECD-FAO expects middle-income countries to drive most agricultural consumption growth over the next decade. Meat consumption in Africa alone is projected to rise 33%, helped by rapid population growth.
That creates a price problem as much as a distribution problem.
A premium alternative burger can build a good business in London, Berlin or Los Angeles. It has a much harder time competing for everyday protein demand in places where poultry is cheap, household incomes are lower and the alternative product needs a new cold chain, retail presence and marketing budget.
This is where fermentation, local crops and cheaper formats could change the picture. The products that eventually succeed in Indonesia, Nigeria or India may look very different from the premium faux-beef products that defined the first Western plant-based boom.
Until that happens at meaningful scale, forecasts for a giant global alternative-protein market should carry a large geographic discount.

In our research about alternative proteins, you will always find fresh funding data, taken straight from our own verified funding database.
How fast would alternative protein have to grow to reach $100 billion?
A $100 billion plant-based market is quite plausible over time, but reaching it within ten years would require growth to accelerate from roughly 3% today to about 13% a year.
Starting from the current $28.9 billion global plant-based retail market, the compounding is straightforward.
At 3% annual growth, sales reach only about $39 billion after ten years. At 7%, they reach roughly $57 billion. At 10%, the market gets to about $75 billion. Whether any of those growth rates is realistic depends on market signals we track every quarter in our report covering the alternative protein market.
The $100 billion threshold requires roughly 13.2% compound annual growth.
That is demanding rather than absurd. Individual European markets are already growing volumes at double-digit rates, and plant-based milk has shown that a substitute can take meaningful category share. But sustaining 13% globally for a decade would require several engines to work at once: better mature-market repeat buying, lower prices, new geographies and products that reach beyond milk, burgers and nuggets.
As seen above, current global growth of 3% will not get the industry remotely close by itself.
| Annual growth from $28.9B | Approximate market after 10 years |
|---|---|
| 3% | $39B |
| 5% | $47B |
| 7% | $57B |
| 10% | $75B |
| 13.2% | $100B |
| 15% | $117B |
| 20% | $179B |
Is the old $290 billion alternative-protein forecast still believable?
A roughly $300 billion alternative-protein market is still possible eventually, but the famous mid-2030s version of that forecast now looks much more aggressive than it did during the sector's boom.
Boston Consulting Group and Blue Horizon estimated in 2021 that alternative proteins could reach 97 million tonnes by 2035, around 11% of the global protein market under their definition, producing roughly $290 billion in revenue.
A key part of that scenario was rapid adoption once alternatives reached parity with animal products on taste, texture and price.
Five years of commercial evidence have made that assumption much easier to test.
Plant-based meat still sells at a large premium in the United States. U.S. volumes are falling. Cultivated meat has gained regulatory access without proving mass production. Fermentation is commercially further along but is still trying to bring manufacturing costs down.
Meanwhile, going from $28.9 billion to $290 billion in ten years would require the plant-based market alone to compound at roughly 26% a year. Fermentation and cultivated meat could add revenue on top, so that is not a literal forecast of what the full industry must achieve, but it shows the scale of acceleration involved.
The old forecast remains useful as a picture of what could happen if parity causes a sharp adoption curve. It no longer works well as a default trajectory from where the market stands now.

In our market report about alternative proteins, we look at what the winners do differently, so you can learn from the best instead of guessing.
Could alternative protein really reach 10% of global protein consumption?
Alternative protein could reach 10% of global protein consumption, but getting there would require several categories to break through at once rather than one technology suddenly replacing meat everywhere.
Plant-based milk already shows that double-digit penetration can happen. U.S. retail dollar share is around 13%, while German plant-based milk has reached 9.2% of volume.
Plant-based meat gives us the opposite benchmark. It still accounts for less than 1% of the overall U.S. meat retail market.
A future 10% global share would almost certainly be uneven. Milk alternatives could exceed 20% in some countries. Fermentation-derived whey or egg proteins could become common food ingredients. Plant-based nuggets and mince might gain substantial share while steaks remain overwhelmingly animal-based. Cultivated fats could enter hybrid products long before fully cultivated meat reaches supermarkets at scale.
This uneven route is actually more believable than expecting all animal products to lose the same percentage of sales.
It also means that measuring the industry will get harder. A burger containing plant protein, fermentation-derived fat and conventional beef sits across several categories at once. The same could happen with cheese, eggs and seafood.
Ten percent therefore looks technically possible as a long-term aggregate. Reaching it would still represent a transformation several orders of magnitude beyond what cultivated meat and precision fermentation sell today and many times the current penetration of plant-based meat.
How big can the alternative protein market really get?
Alternative protein can realistically become a $100 billion-plus global market, while a move toward $200 billion or $300 billion needs breakthroughs that the industry has not demonstrated at scale yet.
We can be fairly confident about the first part because the market already has several independent routes to growth. Plant-based foods start from almost $29 billion in annual retail sales. Milk alternatives have shown double-digit share in a major food category. France has just demonstrated that plant-based meat volume can jump by almost 17% in a year when the consumer proposition improves. Precision fermentation can reach markets that branded meat substitutes cannot.
The higher numbers require more assumptions.
A $200 billion market needs alternative proteins to move well beyond their current Western concentration and become competitive in everyday food. At around $300 billion, we would expect precision fermentation to be operating at serious industrial scale, plant-based meat to have solved much more of its repeat-purchase problem and cultivated or hybrid technologies to be contributing meaningful revenue.
Current capital flows reinforce that more sober view. Alternative-protein companies have raised over $19.5 billion since 2017, but investment was only $881 million in 2025 and $359 million in the first half of 2026. Plenty of science has now been funded. Investors increasingly want commercial proof.
At the same time, conventional protein keeps expanding. The OECD-FAO expects another 47.9 million tonnes of meat consumption over the next decade, while milk production is projected to pass 1.1 billion tonnes.
That puts the realistic long-term opportunity in the hundreds of billions without assuming a near-term takeover of the global protein system.
The biggest upside appears once alternative proteins stop feeling like alternatives. If a consumer chooses a product because it tastes good, costs the right amount and happens to use plants, fermentation or cultivated ingredients, the addressable market becomes enormous.
Today, the industry is somewhere between those two worlds. Plant-based milk has already crossed into ordinary consumption. Much of plant-based meat has not. Precision fermentation is moving from technical promise into commercial testing, while cultivated meat is still proving that production can work reliably.
How large the market eventually becomes will be decided by how many of those categories make the same transition that plant-based milk already has. Which categories make that jump depends partly on what counts as alternative protein, a line we draw in our alternative protein market report.
Our methodology
This analysis asks how large the alternative-protein market can realistically become from the commercial position it occupies today. Rather than starting from a single market forecast, we compare current retail sales with category penetration, consumer purchasing behavior, product formats, geographic differences, production scale, regulatory progress and investment.
We use the roughly $28.9 billion global plant-based retail market as the cleanest current commercial starting point. It captures products consumers already buy at meaningful scale, while cultivated meat and precision fermentation are treated separately because their commercial maturity and revenue bases are still very different.
We prioritized the freshest observable evidence available, using 2025 data and 2026 updates where possible. Actual retail sales, units, market shares, physical production volumes and regulatory outcomes received more weight than consumer intentions or long-range industry forecasts.
We did not treat every dataset as a measure of the same thing. Retail dollars show current consumer spending, physical tonnes show the scale of the conventional protein system, category share measures penetration, investment indicates access to commercialization capital, and regulatory approvals show whether a technology has moved beyond the laboratory. Each is used only for the question it can reasonably answer.
Country differences are used as a practical test of the industry's growth assumptions. France, Germany, Italy, Spain, the United Kingdom and the Netherlands provide useful comparisons because changes in plant-based volumes can be examined alongside price movements instead of relying on one global growth number.
We also separate demonstrated commercial performance from technical possibility. Regulatory clearance does not prove mass production, investment does not prove consumer demand, and success in plant-based milk does not mean meat, cheese or whole cuts will automatically reach the same penetration.
The $100 billion scenario is tested directly through compound growth from the current plant-based commercial base. Larger figures such as $200 billion or $300 billion are treated as conditional scenarios because reaching them would require additional growth engines including greater repeat purchasing, lower prices, expansion beyond Western markets, broader product coverage and meaningful scale from fermentation or cultivated technologies.
The older BCG and Blue Horizon $290 billion scenario is therefore used as a reference case rather than a baseline forecast. We compare its underlying assumption of rapid adoption after taste, texture and price parity with the commercial evidence that has accumulated since the forecast was published.
Key sources include the Good Food Institute's State of the Industry research on plant-based foods, GFI's U.S. retail market research, GFI Europe's European retail analysis based on Circana data, FAO agricultural production statistics, the OECD-FAO outlook for meat and dairy, GFI's research on precision fermentation and cultivated meat, and GFI's alternative-protein investment data.
For regulatory progress, we used primary sources including the U.S. Food and Drug Administration, Food Standards Australia New Zealand and the Singapore Food Agency. The historical high-growth scenario comes from Boston Consulting Group and Blue Horizon's 2021 alternative-protein analysis.
The final market-size conclusion is not the output of one preferred forecast. It comes from testing how much consumers buy now, how often they buy it, which categories have achieved meaningful penetration, where demand can expand and whether newer technologies can eventually supply large volumes at competitive cost.

If you build or invest in the alternative protein market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us