What are the most valuable cell therapy startups?
Everything we know about the cell therapy market, in one place. Get our report whether you build or invest.
Summary
Kite Pharma, Arcellx, Kelonia Therapeutics, Iovance Biotherapeutics and Legend Biotech sit at the top of our cell therapy valuation ranking, but the figures mix acquisition prices, public-market values and transaction-based estimates rather than one clean valuation method.
The market is extremely top-heavy. The first five companies represent roughly $33 billion in our dataset, while the broader billion-dollar group totals around $45 billion.
CAR-T still controls the high end because it now combines regulatory proof, real commercial revenue and aggressive strategic M&A. CARVYKTI alone reached about $1.9 billion in 2025 net trade sales.
The newest valuation premium is moving toward in-vivo CAR-T. Lilly, AbbVie, Bristol Myers Squibb, AstraZeneca, Kite and Johnson & Johnson have all committed large sums to platforms designed to create therapeutic cells directly inside patients.
Autoimmune disease is widening the addressable market far beyond late-line blood cancers. Several of the largest recent transactions now target immune reset in diseases such as lupus and other B-cell-mediated conditions.
Solid tumors are also becoming less theoretical after the first CAR-T approval in that setting. That does not solve the biological problems, but it gives investors a regulatory precedent that did not exist before.
Commercial success is uneven. Legend is already at blockbuster scale, while Iovance, Mesoblast and Autolus have meaningful product revenue but much smaller valuations and very different launch profiles.
Funding totals are a poor guide to current value. Sana, Lyell, Nkarta, Century, Instil Bio and Senti Biosciences show how hundreds of millions of dollars of historical financing can coexist with severe public-market repricing. Companies repriced sharply despite big funding show what investors now avoid, a shift we follow in our cell therapy market report.
Off-the-shelf, Treg, NK and iPSC platforms still matter, but they generally sit below the leading CAR-T names because the clinical and commercial proof is thinner. Investors are paying more for evidence now, not just for an elegant manufacturing concept.
The clearest premium today goes to companies that either have strong human data, real sales, or a platform that could remove the manufacturing and access bottlenecks of current cell therapy. That is why late-stage differentiated CAR-T and in-vivo delivery are absorbing so much of the sector’s valuation.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

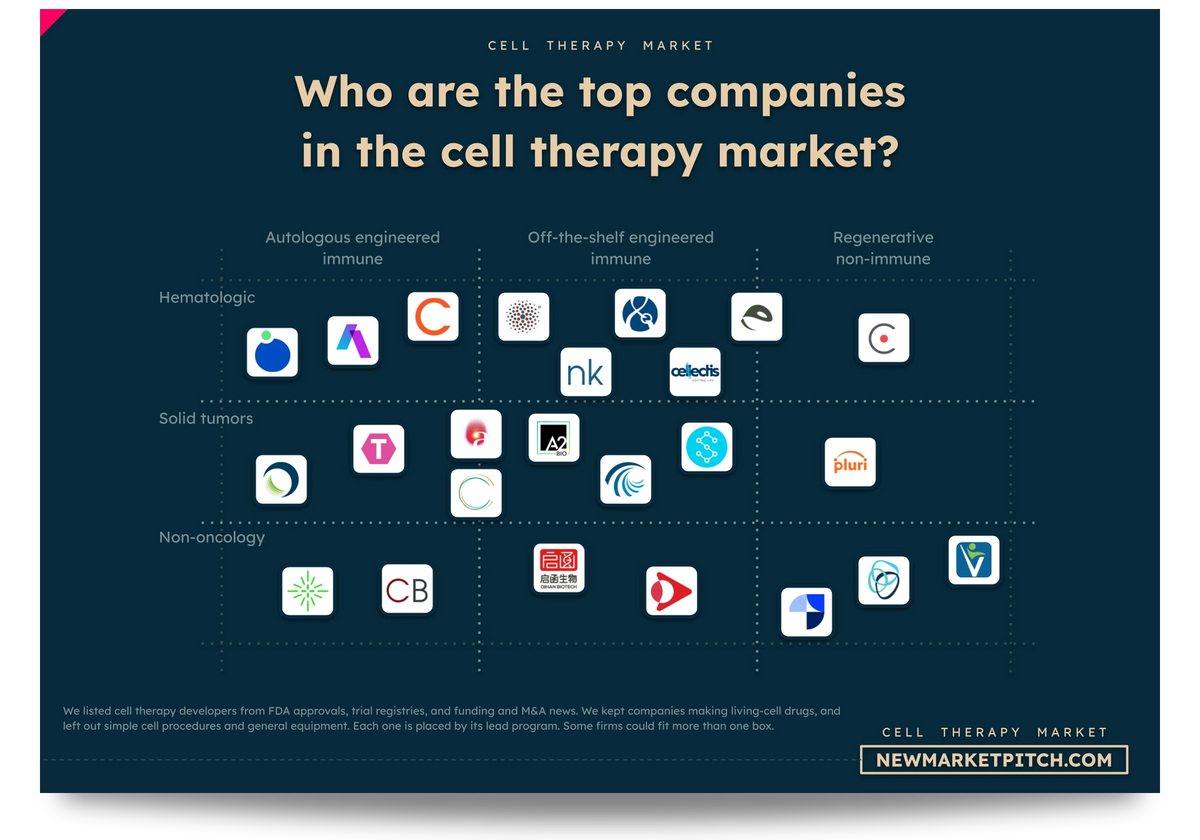
In our report covering the cell therapy market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Top startups in the Cell Therapy Market ranked by valuation
Here is an updated table that ranks the top startups in the Cell Therapy Market based on their latest reported or estimated valuations.
If you need to dig deeper and get more detailed data, please check our report covering the Cell Therapy Market.
| # | Startup Name | What They Do | Current Valuation ($) | Valuation Confidence Level | Valuation Type | Evidence Status | Total Funding ($) | Funding Confidence Level |
|---|---|---|---|---|---|---|---|---|
| 1 | Kite Pharma | Commercial CAR-T cancer therapies | $11.9B | Full Confidence | Acquisition Value | Observed | $85.25M | Full Confidence |
| 2 | Arcellx | Novel CAR-T immunotherapies | $7.8B | Full Confidence | Acquisition Value | Observed | $205M | Full Confidence |
| 3 | Kelonia Therapeutics | In-vivo CAR-T gene delivery | $4.9B | Full Confidence | Acquisition Value | Observed | $90M | Full Confidence |
| 4 | Iovance Biotherapeutics | TIL therapies for solid tumors | $4.8B | Full Confidence | Public Market Cap | Observed | ~$1.6B | Strong Confidence |
| 5 | Legend Biotech | Markets BCMA CAR-T for myeloma | $3.6B | Full Confidence | Public Market Cap | Observed | $150M | Full Confidence |
| 6 | Capstan Therapeutics | In-vivo RNA CAR-T therapies | $2.1B | Full Confidence | Acquisition Value | Observed | $340M | Full Confidence |
| 7 | Mesoblast | Allogeneic mesenchymal stem-cell therapies | $2.0B | Full Confidence | Public Market Cap | Observed | >$500M | Strong Confidence |
| 8 | Vor Biopharma | Autoimmune biologics and cell therapies | $1.3B | Full Confidence | Public Market Cap | Observed | $152M | Full Confidence |
| 9 | Immatics | TCR therapies targeting solid tumors | $1.2B | Full Confidence | Public Market Cap | Observed | $248M | Full Confidence |
| 10 | Obsidian Therapeutics | Engineered TIL therapies for tumors | $1.1B | Full Confidence | Public Market Cap | Observed | $675M+ | Strong Confidence |
| 11 | Poseida Therapeutics | Allogeneic CAR-T and gene therapies | $1.1B | Full Confidence | Acquisition Value | Observed | $324M | Full Confidence |
| 12 | OriCell Therapeutics | Solid-tumor and hematologic CAR-T | $800M–$1.3B | Strong Confidence | Implied Valuation from Raise | Implied | $387.3M | Full Confidence |
| 13 | Gracell Biotechnologies | Next-generation CAR-T therapies | $1.0B | Full Confidence | Acquisition Value | Observed | $185M | Full Confidence |
| 14 | BlueRock Therapeutics | iPSC-derived regenerative cell therapies | $1.0B | Strong Confidence | Acquisition Value | Observed | $225M | Full Confidence |
| 15 | Sana Biotechnology | Engineered hypoimmune cell medicines | $997M | Full Confidence | Public Market Cap | Observed | ~$1.8B | Strong Confidence |
| 16 | CARsgen Therapeutics | CAR-T therapies for cancers | $880M–$940M | Strong Confidence | Public Market Cap | Observed | $286M | Full Confidence |
| 17 | Arsenal Biosciences | Programmable in-vivo CAR-T therapies | $650M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $630M | Full Confidence |
| 18 | AbelZeta Pharma | CAR-T oncology and autoimmune therapies | $650M–$1.1B | Partial Confidence | Comparables-Based Estimate | Estimated | $120M+ | Strong Confidence |
| 19 | Quell Therapeutics | Engineered Treg cell therapies | $620M–$940M | Partial Confidence | Proxy-Based Estimate | Estimated | $236M | Full Confidence |
| 20 | Exuma Biotech | In-vivo CAR-T gene delivery | $470M–$875M | Partial Confidence | Implied Valuation from Raise | Implied | $107M | Full Confidence |
| 21 | Sonoma Biotherapeutics | Engineered Tregs for autoimmune disease | $550M–$750M | Partial Confidence | Comparables-Based Estimate | Estimated | $365M | Full Confidence |
| 22 | Umoja Biopharma | In-vivo CAR-T cancer therapies | $420M–$800M | Low Confidence | Announced Private Round Valuation | Estimated | $363M | Full Confidence |
| 23 | Allogene Therapeutics | Allogeneic CAR-T cancer therapies | $591M | Full Confidence | Public Market Cap | Observed | $420M | Full Confidence |
| 24 | IASO Biotherapeutics | Commercial CAR-T and immune therapies | $450M–$700M | Partial Confidence | Comparables-Based Estimate | Estimated | ~$243M | Strong Confidence |
| 25 | AvenCell Therapeutics | Switchable CAR-T cancer therapies | $450M–$670M | Partial Confidence | Proxy-Based Estimate | Estimated | $362M+ | Strong Confidence |
| 26 | Simnova Biotherapeutics | CAR-NK and in-vivo CAR-T | $450M–$650M | Strong Confidence | Implied Valuation from Raise | Implied | ~$87M | Strong Confidence |
| 27 | Capricor Therapeutics | Cell therapy for muscular dystrophy | $543M | Full Confidence | Public Market Cap | Observed | ~$600M | Strong Confidence |
| 28 | Autolus Therapeutics | Autologous CAR-T cancer therapies | $540M | Full Confidence | Public Market Cap | Observed | $186M | Full Confidence |
| 29 | T-knife Therapeutics | TCR-T therapies for solid tumors | $350M–$650M | Low Confidence | Comparables-Based Estimate | Estimated | $188M | Full Confidence |
| 30 | Indapta Therapeutics | Allogeneic g-NK cell therapies | $339M–$635M | Strong Confidence | Implied Valuation from Raise | Implied | $157.8M | Full Confidence |
| 31 | Kyverna Therapeutics | CAR-T for autoimmune diseases | $464M | Full Confidence | Public Market Cap | Observed | $170M | Full Confidence |
| 32 | EsoBiotec | In-vivo lentiviral cell therapies | $425M | Full Confidence | Acquisition Value | Observed | $12.7M | Full Confidence |
| 33 | Cabaletta Bio | CAR-T therapies for autoimmune disease | $424M | Full Confidence | Public Market Cap | Observed | $88M | Full Confidence |
| 34 | Juventas Cell Therapy | CAR-T therapies for blood cancers | $320M–$500M | Partial Confidence | Comparables-Based Estimate | Estimated | ~$232M | Strong Confidence |
| 35 | Bioheng Therapeutics | Allogeneic CAR-T cell therapies | $300M–$500M | Low Confidence | Comparables-Based Estimate | Estimated | $94.77M | Full Confidence |
| 36 | Artiva Biotherapeutics | Allogeneic NK-cell therapies | $396M | Full Confidence | Public Market Cap | Observed | $198M | Strong Confidence |
| 37 | Tr1X | Allogeneic regulatory T-cell therapies | $350M–$400M | Strong Confidence | Announced Private Round Valuation | Observed | ~$133M | Strong Confidence |
| 38 | Interius BioTherapeutics | In-vivo CAR gene therapies | $350M | Full Confidence | Acquisition Value | Observed | $166.08M | Full Confidence |
| 39 | Aspen Neuroscience | Autologous neurons for Parkinson's | $325M–$375M | Strong Confidence | Announced Private Round Valuation | Observed | $387M | Full Confidence |
| 40 | Century Therapeutics | iPSC-derived allogeneic cell therapies | $342M | Full Confidence | Public Market Cap | Observed | ~$792M | Strong Confidence |
| 41 | GentiBio | Engineered Tregs restoring immune tolerance | $250M–$400M | Low Confidence | Comparables-Based Estimate | Estimated | $177M | Full Confidence |
| 42 | Fate Therapeutics | iPSC-derived cellular immunotherapies | $309M | Full Confidence | Public Market Cap | Observed | $76M | Full Confidence |
| 43 | A2 Biotherapeutics | Logic-gated precision CAR-T therapies | $250M–$330M | Partial Confidence | Announced Private Round Valuation | Estimated | $288M | Full Confidence |
| 44 | Triumvira Immunologics | TAC-engineered T-cell cancer therapies | $220M–$330M | Partial Confidence | Proxy-Based Estimate | Estimated | $160M | Full Confidence |
| 45 | Lyell Immunopharma | Next-generation CAR-T cell therapies | $273M | Full Confidence | Public Market Cap | Observed | $851M | Full Confidence |
| 46 | Wugen | Allogeneic CAR-T blood-cancer therapies | $180M–$350M | Low Confidence | Proxy-Based Estimate | Estimated | $323M | Full Confidence |
| 47 | Lineage Cell Therapeutics | Cell transplants for degenerative diseases | $263M | Full Confidence | Public Market Cap | Observed | >$300M | Strong Confidence |
| 48 | Acepodia | Antibody-conjugated allogeneic cell therapies | $241M | Full Confidence | Public Market Cap | Observed | $256M | Full Confidence |
| 49 | Curocell | CAR-T therapies for blood cancers | $230M–$240M | Strong Confidence | Public Market Cap | Observed | $82.85M | Full Confidence |
| 50 | Cargo Therapeutics | Resistance-bypassing CAR-T cancer therapies | $204M–$220M | Strong Confidence | Acquisition Value | Estimated | $200M | Full Confidence |
| 51 | Nkarta | Engineered allogeneic NK therapies | $211M | Full Confidence | Public Market Cap | Observed | $885M+ | Strong Confidence |
| 52 | Precision BioSciences | ARCUS gene-editing therapeutics | $198M | Full Confidence | Public Market Cap | Observed | $178.9M | Full Confidence |
| 53 | Verismo Therapeutics | KIR-CAR therapies for cancer | $185M–$210M | Strong Confidence | Implied Valuation from Raise | Implied | $84M | Full Confidence |
| 54 | Inceptor Bio | CAR-T therapies for solid tumors | $150M–$220M | Partial Confidence | Proxy-Based Estimate | Estimated | $85M | Full Confidence |
| 55 | PersonGen BioTherapeutics | CAR-T and cellular immunotherapies | $120M–$220M | Partial Confidence | Comparables-Based Estimate | Estimated | $46M+ | Strong Confidence |
| 56 | Unicar Therapy | CAR-T therapies for cancer | $120M–$220M | Low Confidence | Proxy-Based Estimate | Estimated | Undisclosed | Low Confidence |
| 57 | Shoreline Biosciences | iPSC-derived NK cell therapies | $120M–$220M | Low Confidence | Comparables-Based Estimate | Estimated | $186M | Full Confidence |
| 58 | JW Therapeutics | Commercial CAR-T therapies in China | $152M | Full Confidence | Public Market Cap | Observed | ~$190M | Strong Confidence |
| 59 | Caribou Biosciences | Genome-edited allogeneic CAR-T therapies | $144M | Full Confidence | Public Market Cap | Observed | $158M | Full Confidence |
| 60 | Affini-T Therapeutics | TCR therapies targeting oncogenic mutations | $90M–$180M | Low Confidence | Comparables-Based Estimate | Estimated | $192.6M | Full Confidence |
| 61 | Xyphos Biosciences | ConvertibleCAR cancer immunotherapies | $120M | Full Confidence | Acquisition Value | Observed | Not disclosed | Low Confidence |
| 62 | Cellectis | Gene-edited allogeneic CAR-T therapies | $110M | Full Confidence | Public Market Cap | Observed | $220M+ | Strong Confidence |
| 63 | Gamida Cell | Expanded stem cells for transplantation | $90M–$120M | Partial Confidence | Acquisition Value | Implied | >$250M | Strong Confidence |
| 64 | Adicet Bio | Allogeneic gamma-delta CAR-T therapies | $98M | Full Confidence | Public Market Cap | Observed | $131M | Full Confidence |
| 65 | Immuneel Therapeutics | Affordable autologous CAR-T therapies | $75M–$115M | Strong Confidence | Implied Valuation from Raise | Implied | $37.64M | Full Confidence |
| 66 | ImmPACT Bio | Next-generation CAR-T cancer therapies | $94M | Full Confidence | Acquisition Value | Observed | $166M | Full Confidence |
| 67 | Atara Biotherapeutics | Allogeneic T-cell immunotherapies | $90M | Full Confidence | Public Market Cap | Observed | $72M | Full Confidence |
| 68 | AffyImmune Therapeutics | Affinity-tuned CAR-T solid-tumor therapies | $50M–$90M | Low Confidence | Proxy-Based Estimate | Estimated | $38M | Full Confidence |
| 69 | Leucid Bio | Lateral CAR-T solid-tumor therapies | $55M–$85M | Partial Confidence | Implied Valuation from Raise | Implied | ~$25M | Strong Confidence |
| 70 | MiNK Therapeutics | Off-the-shelf iNKT cell therapies | $62M | Full Confidence | Public Market Cap | Observed | $40M+ | Strong Confidence |
| 71 | ONK Therapeutics | Engineered off-the-shelf NK therapies | $40M–$80M | Low Confidence | Comparables-Based Estimate | Estimated | $29.5M | Full Confidence |
| 72 | PeproMene Bio | BAFF-R CAR-T therapies | $44M–$66M | Partial Confidence | Comparables-Based Estimate | Estimated | ~$63M | Strong Confidence |
| 73 | Prescient Therapeutics | Cell therapies and targeted oncology | $51M | Full Confidence | Public Market Cap | Observed | $27M+ | Strong Confidence |
| 74 | Cartherics | iPSC-derived CAR immune therapies | $39M–$58M | Partial Confidence | Comparables-Based Estimate | Estimated | $14.2M | Full Confidence |
| 75 | Instil Bio | Strategic cell-therapy pipeline assets | $48M | Full Confidence | Public Market Cap | Observed | ~$726M | Strong Confidence |
| 76 | Invectys | Cancer immunotherapies and CAR-T | $35M–$55M | Low Confidence | Comparables-Based Estimate | Estimated | $36.34M | Full Confidence |
| 77 | Catamaran Bio | Engineered off-the-shelf NK therapies | $30M–$60M | Low Confidence | Comparables-Based Estimate | Estimated | $42M | Full Confidence |
| 78 | Coeptis Therapeutics | Allogeneic NK and cell therapies | $25M–$60M | Low Confidence | Proxy-Based Estimate | Estimated | ~$10.3M | Strong Confidence |
| 79 | Clade Therapeutics | iPSC-derived allogeneic cell therapies | $40M | Full Confidence | Acquisition Value | Observed | $87.04M | Full Confidence |
| 80 | Noile-Immune Biotech | PRIME CAR-T solid tumors | $38M | Full Confidence | Public Market Cap | Observed | $21.92M | Full Confidence |
| 81 | Carina Biotech | CAR-T therapies for solid tumors | $25M–$45M | Low Confidence | Proxy-Based Estimate | Estimated | $9M | Full Confidence |
| 82 | Glycostem Therapeutics | Donor-derived NK cancer therapies | $20M–$50M | Low Confidence | Proxy-Based Estimate | Estimated | $15.4M | Full Confidence |
| 83 | Celularity | Placental-derived allogeneic cell therapies | $34M | Full Confidence | Public Market Cap | Observed | ~$582M | Strong Confidence |
| 84 | Sernova | Cell Pouch diabetes cell therapy | $25M–$35M | Strong Confidence | Public Market Cap | Observed | $53M | Full Confidence |
| 85 | Gadeta | Gamma-delta TCR cancer therapies | $15M–$35M | Low Confidence | Acquisition Value | Estimated | $7.8M | Full Confidence |
| 86 | TScan Therapeutics | TCR-engineered T-cell therapies | $24M | Full Confidence | Public Market Cap | Observed | $160M | Full Confidence |
| 87 | Antion Biosciences | Multiplex-engineered allogeneic cell therapies | $15M–$30M | Low Confidence | Proxy-Based Estimate | Estimated | $2.1M+ | Strong Confidence |
| 88 | Luminary Therapeutics | Non-viral CAR-T cell therapies | $16M–$26M | Partial Confidence | Implied Valuation from Raise | Implied | $14.8M | Full Confidence |
| 89 | Elicera Therapeutics | CAR-T and oncolytic immunotherapies | $18M | Full Confidence | Public Market Cap | Observed | $1.48M | Full Confidence |
| 90 | Celyad Oncology | Licenses allogeneic CAR-T intellectual property | $13M–$15M | Strong Confidence | Public Market Cap | Observed | $47M | Full Confidence |
| 91 | Shenzhen Geno-Immune Medical Institute | Academic CAR-T immunotherapy research | $8M–$20M | Low Confidence | Proxy-Based Estimate | Estimated | Undisclosed | Low Confidence |
| 92 | BrainStorm Cell Therapeutics | Stem-cell therapy for neurodegeneration | $13M | Full Confidence | Public Market Cap | Observed | ~$188M | Strong Confidence |
| 93 | CytoMed Therapeutics | Gamma-delta T-cell cancer therapies | $11M | Full Confidence | Public Market Cap | Observed | $9.6M+ | Strong Confidence |
| 94 | Senti Biosciences | Gene-circuit engineered cell therapies | $10M | Full Confidence | Public Market Cap | Observed | $378M+ | Strong Confidence |
| 95 | Adaptimmune | Engineered TCR cancer cell therapies | $7M | Full Confidence | Public Market Cap | Observed | $107M | Full Confidence |
| 96 | Achilles Therapeutics | Personalized neoantigen T-cell therapies | $2M–$8M | Low Confidence | Proxy-Based Estimate | Estimated | $206M | Full Confidence |
| 97 | Appia Bio | Stem-cell-derived CAR-iNKT therapies | $0M–$5M | Low Confidence | Proxy-Based Estimate | Estimated | $52M | Full Confidence |
| 98 | Abata Therapeutics | Tregs for autoimmune diseases | $0M–$5M | Low Confidence | Proxy-Based Estimate | Estimated | ~$110M | Strong Confidence |
| 99 | TC BioPharm | Gamma-delta T-cell therapies | $0M–$2M | Low Confidence | Proxy-Based Estimate | Estimated | $16M | Full Confidence |
| 100 | Chimeric Therapeutics | CAR-T therapies for solid tumors | $0M–$1M | Strong Confidence | Public Market Cap | Observed | $26M+ | Strong Confidence |

Our research about cell therapies gets updated several times a month, so you always get the latest view of where things stand.
Which cell therapy startups are worth the most today?
The biggest cell therapy valuations currently belong to Kite Pharma, Arcellx, Kelonia Therapeutics, Iovance Biotherapeutics and Legend Biotech, with a huge gap between these companies and most of the market.
Kite sits at $11.9 billion in our dataset, the price Gilead paid when it acquired the company. Arcellx follows at $7.8 billion after Gilead completed its acquisition of the company and gained full control of anito-cel, its BCMA CAR-T candidate for multiple myeloma. Kelonia is another exceptional case: Lilly agreed to pay $3.25 billion upfront and as much as $7 billion in total if clinical, regulatory and commercial milestones are reached.
The next two companies show a different side of the market. Iovance is a public company built around tumor-infiltrating lymphocyte therapies, while Legend Biotech has turned CARVYKTI into one of the largest commercial successes in modern cell therapy. Legend reported approximately $1.9 billion in CARVYKTI net trade sales for 2025, followed by about $597 million in the first quarter of 2026 and $657 million in the second quarter.
Once we move beyond the first few companies, valuations fall quickly. Mesoblast is around $2 billion by our estimate, while most companies outside the top 15 are worth less than $1 billion.
| Rank | Company | Valuation in our dataset | Main valuation reference |
|---|---|---|---|
| 1 | Kite Pharma | $11.9B | Acquisition |
| 2 | Arcellx | $7.8B | Acquisition |
| 3 | Kelonia Therapeutics | $4.9B | Acquisition-based estimate |
| 4 | Iovance Biotherapeutics | $4.8B | Public market |
| 5 | Legend Biotech | $3.6B | Public market |
| 6 | Capstan Therapeutics | $2.1B | Acquisition |
| 7 | Mesoblast | $2.0B | Public market |
| 8 | Vor Biopharma | $1.3B | Public market |
| 9 | Immatics | $1.2B | Public market |
| 10 | Obsidian Therapeutics | $1.1B | Public market |
How many cell therapy unicorns are there?
Around 14 companies in our cell therapy ranking reach the $1 billion level when we use the midpoint of valuation ranges, although only a fraction are conventional private unicorns.
Kite, Arcellx, Kelonia, Capstan, Poseida, Gracell and BlueRock appear around or above the billion-dollar level because of acquisition values. Iovance, Legend, Mesoblast, Immatics and Sana are or were represented by public-market values. Billion-dollar names come from acquisitions and public markets alike, and market maps in our report on cell therapy show where companies sit.
Poseida is a good example. Roche offered about $1 billion in equity value at closing, with contingent payments capable of increasing the deal to approximately $1.5 billion. AstraZeneca paid roughly $1 billion upfront for Gracell, with another $200 million tied to a milestone. Bayer’s BlueRock transaction implied a total company value of around $1 billion.
So there are roughly 14 billion-dollar valuation points in our dataset, rather than 14 independent private cell therapy unicorns.

In our market report about cell therapies, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is most of the value in cell therapy concentrated in just a few companies?
Yes. Cell therapy valuations are currently extremely concentrated at the top.
Using our dataset and the midpoint of each valuation range, the first five companies represent roughly $33 billion. The roughly 14 companies at or above $1 billion together represent about $45 billion, meaning the top five account for close to three-quarters of the value in that billion-dollar group.
The drop afterward is steep. Around rank 20, Exuma Biotech has an estimated midpoint below $700 million. Around rank 30, the valuation level is already below $500 million. Around rank 50, companies are clustered near $200 million. By the bottom quarter of the ranking, we are mostly dealing with tens of millions.
Most of the premium is going to a small group of assets with commercial proof, strong human data or technology that could remove a major limitation of current cell therapies.
Why are CAR-T companies worth so much more than most cell therapy startups?
CAR-T companies dominate cell therapy valuations because CAR-T already works commercially, while newer versions could make the technology much easier to use.
Legend reported approximately $1.9 billion in CARVYKTI net trade sales in 2025, almost double the $963 million reported for 2024. By the second quarter of 2026, quarterly net trade sales had reached about $657 million. More than 10,000 patients had already been treated by the end of 2025.
The acquisition market points in the same direction. Gilead completed the $7.8 billion purchase of Arcellx around anito-cel. AbbVie paid $2.1 billion for Capstan. Bristol Myers Squibb agreed to pay $1.5 billion for Orbital Therapeutics. Lilly agreed to pay Kelonia shareholders $3.25 billion upfront, with the total potentially reaching $7 billion.
Some of these companies are improving conventional ex-vivo CAR-T, while others are trying to create CAR-T cells directly inside the patient. Investors already know engineered T cells can produce valuable medicines; the biggest valuations now go to companies that could make them faster, simpler or useful in many more patients.
Is in-vivo CAR-T now the hottest part of the cell therapy market, and why are pharma companies paying billions for it so early?
Yes. In-vivo CAR-T is currently attracting some of the largest strategic bets anywhere in cell therapy because a successful platform could replace a difficult personalized manufacturing process with something much more scalable.
Conventional autologous CAR-T usually requires extracting a patient’s cells, shipping them to a manufacturing facility, engineering them, testing them and returning them for infusion. In-vivo platforms try to reprogram the relevant immune cells directly inside the patient. Extracting, shipping and re-engineering cells is a heavy manufacturing burden, and we sort which approaches already work in our market report about cell therapy.
AbbVie paid $2.1 billion for Capstan and its targeted lipid nanoparticle platform. Bristol Myers Squibb agreed to buy Orbital for $1.5 billion. AstraZeneca paid $425 million upfront for EsoBiotec, with milestones capable of taking the transaction to $1 billion. Kite bought Interius for $350 million.
Lilly pushed the ceiling much higher with Kelonia, agreeing to pay $3.25 billion upfront and potentially $7 billion in total. Johnson & Johnson then entered a collaboration with Sail Biomedicines around in-vivo CAR-T for immune-mediated diseases, made an equity investment and secured an exclusive option to acquire Sail for $2.58 billion.
The attraction is broader than one drug candidate. If an in-vivo delivery system works reliably, the same platform could potentially be reused across several targets and diseases.
The risk is still substantial. Precise targeting, immune reactions, persistence, dose control and unwanted genetic modification remain unresolved questions. Current deal prices show how much pharma values the upside, not that the technology has already been fully proven.
| Company | Buyer or partner | Disclosed economics | Main focus |
|---|---|---|---|
| Kelonia | Lilly | $3.25B upfront, up to $7B | In-vivo CAR-T |
| Sail Biomedicines | Johnson & Johnson | Acquisition option at $2.58B | In-vivo autoimmune CAR-T |
| Capstan | AbbVie | $2.1B | In-vivo autoimmune CAR-T |
| Orbital | Bristol Myers Squibb | $1.5B | RNA-based in-vivo CAR-T |
| EsoBiotec | AstraZeneca | $425M upfront, up to $1B | In-vivo cell therapy |
| Interius | Kite / Gilead | $350M | In-vivo CAR |
| Exuma | Independent | $470M–$875M estimate | In-vivo CAR-T |

In our document detailing everything you need to know about cell therapy, you will always find fresh funding data, taken straight from our own verified funding database.
Is autoimmune disease becoming a major CAR-T market?
Yes. Autoimmune disease is now one of the clearest reasons CAR-T valuations are expanding beyond cancer.
Capstan’s lead in-vivo program targets B-cell-mediated autoimmune diseases rather than cancer, yet AbbVie still paid $2.1 billion for the company. Sail is also focused on immune-mediated disease, and Johnson & Johnson valued its acquisition option at $2.58 billion. Gracell’s GC012F was being developed in systemic lupus erythematosus alongside multiple myeloma before AstraZeneca acquired the company.
Autolus is studying obe-cel in lupus nephritis, while Kyverna and Cabaletta are developing CAR-T programs specifically around autoimmune diseases. The basic idea is to remove disease-driving immune cells deeply enough that the immune system can rebuild without immediately recreating the same disease.
The potential patient pool is much larger than the late-line blood-cancer population where CAR-T first became established. The challenge is that autoimmune patients also demand a much higher safety and convenience standard than patients with aggressive refractory cancer.
Is CAR-T finally working in solid tumors?
CAR-T has now achieved its first regulatory breakthrough in solid tumors, which makes this part of the market considerably more credible than it was even a year ago.
CARsgen announced that Chinese regulators approved satricabtagene autoleucel, or satri-cel, for certain patients with advanced gastric or gastroesophageal junction cancer. The company describes it as the world’s first approved CAR-T therapy for a solid tumor.
That is a meaningful milestone after years of disappointment. Blood cancers gave CAR-T relatively accessible targets such as CD19 and BCMA. Solid tumors are harder because target expression can vary across cancer cells, engineered T cells have difficulty penetrating some tumors, and the tumor microenvironment can suppress their activity.
Several companies in our ranking are built around that opportunity. Immatics sits around $1.2 billion in the dataset with TCR-based solid-tumor programs. Arsenal Biosciences is estimated at $650 million to $1.1 billion. T-knife, Affini-T, Inceptor Bio, Carina Biotech and Chimeric Therapeutics are all approaching solid tumors in different ways.
The first approval proves that engineered T cells can work in at least one solid-tumor setting. The next test is whether that success can be repeated across more targets and tumor types.
Are commercial cell therapy companies actually making serious money now?
Yes. A few cell therapy companies are now generating hundreds of millions or even billions of dollars in annual product sales, although the commercial results vary dramatically from one company to another.
Legend is the clearest example. CARVYKTI net trade sales increased from approximately $963 million in 2024 to $1.9 billion in 2025. The product then generated about $597 million in the first quarter of 2026 and $657 million in the second quarter.
Iovance is smaller but also has real commercial evidence. Its SEC filing shows Amtagvi revenue rising from about $104 million in 2024 to $220 million in 2025, while total product revenue including Proleukin reached about $264 million. Companies with real product sales are one business model, and we compare which ones keep their margins in our report covering the cell therapy market.
Mesoblast reported $115.2 million of Ryoncil net revenue in its first full commercial year, compared with total company revenue of only $17.2 million in the previous year. Gross profit reached $103.6 million. Autolus reported $74.3 million of Aucatzyl net product revenue in 2025.
Cell therapy can now be judged on real sales, manufacturing capacity and treatment-center adoption rather than almost entirely on clinical promises.
| Product / company | Recent commercial figure | What it shows |
|---|---|---|
| CARVYKTI / Legend | $1.9B 2025 net trade sales | CAR-T can reach blockbuster scale |
| CARVYKTI / Legend | $657M latest reported quarter | Sales are still growing quickly |
| Amtagvi / Iovance | $220M 2025 revenue | TIL therapy has real commercial demand |
| Ryoncil / Mesoblast | $115.2M first full-year net revenue | Non-CAR-T cell therapy can scale commercially |
| Aucatzyl / Autolus | $74.3M 2025 net product revenue | New CAR-T launches can build meaningful sales |
| Mesoblast | $103.6M FY2026 gross profit | Commercial cell therapy can generate strong product gross profit |
| Iovance | $263.5M total 2025 product revenue | A commercial platform can support several revenue streams |

Learning from others' mistakes is the cheapest lesson there is. In our report covering the cell therapy market, we look at what broke startups before you, so you don't repeat it.
Why can a pre-revenue cell therapy startup be worth more than a company already selling a product?
A pre-revenue cell therapy startup can be worth billions when buyers think its technology could eventually address a much larger market than an already approved product.
Capstan makes the contrast obvious. AbbVie paid $2.1 billion for the company while its lead program was still in Phase 1. Meanwhile, Autolus has an approved CAR-T product and tens of millions of dollars in annual sales but sits far lower in our valuation ranking.
A commercial product has measurable sales, costs, treatment-center penetration and competition. A platform company can still carry several large possibilities at once. An in-vivo delivery system might support different targets and diseases while also removing personalized manufacturing.
That optionality can support a high valuation, although it also leaves much more room for the valuation to fall if the platform disappoints.
Is off-the-shelf cell therapy still a big opportunity?
Yes, although investors have become much less willing to pay a premium simply because a company describes its therapy as “off-the-shelf.”
Allogeneic therapies still offer an attractive idea: manufacture cells in batches, keep them available as inventory and avoid making a new product from scratch for every patient.
The difficulty is getting those donor-derived or stem-cell-derived cells to persist, remain effective and avoid immune rejection. Years of clinical development have made investors more selective about which platforms can actually achieve that.
Poseida was acquired by Roche for around $1 billion upfront because Roche saw value in its donor-derived CAR-T platform and broader pipeline. Allogene sits around $591 million in our dataset, Century Therapeutics around $342 million, Fate Therapeutics around $309 million, Artiva around $396 million and Nkarta around $211 million.
Off-the-shelf cell therapy still has real value, but these days the premium depends much more on clinical evidence than on the manufacturing concept alone.
Are Treg, NK and iPSC cell therapies catching up with CAR-T?
Treg, NK and iPSC platforms are becoming more credible, but their valuations still sit well below the leading CAR-T companies.
Treg therapy has recently gained a particularly useful proof point. The FDA approved Tregzi, developed by Orca Bio, for use in matched-donor stem-cell transplantation in adults with certain blood cancers. The FDA described it as the first regulatory T-cell-based immunotherapy approved for improving chronic graft-versus-host-disease-free survival in this setting.
Our dataset values Quell at roughly $620 million to $940 million, Sonoma at $550 million to $750 million, Tr1X at $350 million to $400 million and GentiBio at $250 million to $400 million. Treg, NK and iPSC therapies sit alongside CAR-T inside one field, and we set out what counts as cell therapy in our cell therapy market report.
NK-cell companies sit in a similar middle tier. Artiva is around $396 million, Indapta around $339 million to $635 million, Nkarta around $211 million and Shoreline around $120 million to $220 million. iPSC-based companies such as Century and Fate also remain active.
For now, these modalities are credible challengers rather than valuation leaders. CAR-T still has a much deeper combination of approvals, revenue and acquisition activity.

In our research about cell therapies, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is China becoming one of the most important cell therapy markets?
Yes. China is now producing cell therapy companies, approvals and technologies that materially influence the global market.
Legend is the most valuable example in our dataset, with CARVYKTI turning into a multibillion-dollar commercial product globally. CARsgen has now added another major milestone with the first approval of a CAR-T product for a solid tumor.
The private-company pipeline is also substantial. OriCell sits around $800 million to $1.3 billion in our dataset, IASO around $450 million to $700 million, Juventas around $320 million to $500 million and Bioheng around $300 million to $500 million.
Western pharmaceutical groups are paying attention directly. AstraZeneca acquired Gracell, which maintained operations in China and the United States, and gained a dual-target BCMA/CD19 program being developed in both cancer and autoimmune disease.
China is now producing regulatory precedents, globally relevant products and acquisition targets, not just lower-cost development capacity.
Does raising more money make a cell therapy startup worth more, or can investors still lose most of it?
No. In cell therapy, huge funding totals can coexist with very low current valuations when clinical progress or commercial potential disappoints.
The gap is striking in our dataset. Sana has raised roughly $1.8 billion but sits around $1 billion in valuation. Lyell has approximately $851 million in funding against a value around $273 million. Nkarta has more than $885 million of reported funding and a valuation around $211 million. Century has roughly $792 million of reported funding and sits around $342 million.
Lower down, the difference becomes brutal. Instil Bio has around $726 million of reported funding and a valuation near $48 million. Senti Biosciences has raised more than $378 million according to our dataset and is worth around $10 million.
Cell therapy is unusually exposed to this kind of repricing because clinical trials are expensive, manufacturing infrastructure is difficult to build, and companies can spend heavily for years before investors know whether the technology is competitive.
A disappointing efficacy result can remove the main reason investors owned the stock. Safety problems can damage an entire platform, while technically successful therapies can still struggle if manufacturing costs stay high or easier alternatives emerge.
Kelonia sits at the other extreme. The company reached a multibillion-dollar acquisition despite having raised far less money than many public cell therapy businesses. Lilly’s offer puts $3.25 billion upfront behind the platform, with contingent payments capable of taking the total to $7 billion.
Funding measures how much capital went into the company. It tells us surprisingly little about what the company will eventually be worth.
| Company | Funding in our dataset | Valuation in our dataset | Approx. valuation / funding |
|---|---|---|---|
| Kelonia | $90M | $4.9B | 54× |
| Capstan | $340M | $2.1B | 6.2× |
| Sana | ~$1.8B | $997M | 0.6× |
| Century | ~$792M | $342M | 0.4× |
| Lyell | $851M | $273M | 0.3× |
| Nkarta | $885M+ | $211M | <0.3× |
| Instil Bio | ~$726M | $48M | 0.07× |
| Senti Biosciences | $378M+ | $10M | <0.03× |

If you build or invest in the cell therapy market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Are acquisitions now setting the biggest cell therapy valuations?
Yes. At the top of the cell therapy market, acquisitions currently create many of the largest valuation benchmarks.
Kite’s $11.9 billion sale to Gilead remains the biggest figure in our dataset. More recently, Gilead paid an implied $7.8 billion for Arcellx. Lilly agreed to $3.25 billion upfront for Kelonia. AbbVie paid $2.1 billion for Capstan, and Bristol Myers Squibb agreed to pay $1.5 billion for Orbital.
These strategic prices can sit well above public-market valuations for companies at a similar development stage because buyers also value control, manufacturing expertise, future royalties they no longer have to pay and the ability to keep a platform away from competitors. Acquirer appetite can speed the market up, and we look at what else has to go right for growth in our report on cell therapy.
Gilead’s Arcellx transaction shows this clearly. The two companies were already collaborating on anito-cel, and buying Arcellx gave Gilead full control of the program while removing future profit-share, milestone and royalty obligations.
Acquisition values are useful benchmarks for what pharma will pay, although they should not be treated as identical to private funding valuations or public market caps.
Could simpler CAR-T treatment make the cell therapy market much bigger?
Yes. Making CAR-T easier to manufacture and administer could increase the real market far more than another incremental improvement in an already crowded blood-cancer indication.
The FDA has already removed the REMS programs for six approved autologous CAR-T therapies after concluding that those extra restrictions were no longer necessary. The change removed requirements such as special hospital certification under the REMS program and immediate on-site access to tocilizumab.
Commercial networks are expanding too. Legend reported that CARVYKTI was available through 348 sites across 19 markets by the second quarter of 2026, up from 294 sites at the end of 2025.
In-vivo CAR-T could push accessibility much further if the technology works. AstraZeneca says EsoBiotec’s platform is designed to deliver therapy through an IV injection without the conventional weeks-long manufacturing cycle. Capstan and Sail are trying to remove similarly cumbersome steps in autoimmune disease.
A therapy that can be delivered more like a conventional medicine would address a much larger practical market than one restricted to highly specialized treatment centers.
What could wipe billions off a cell therapy company’s valuation?
A failed pivotal trial, a serious platform-level safety problem or evidence that a therapy cannot be manufactured economically can still erase most of a cell therapy company’s value.
Clinical risk remains the most obvious threat. A biotechnology company can spend years and hundreds of millions of dollars around one lead program. If that program fails, there may be very little current value left behind.
Manufacturing is another weak point. Autologous products need reliable cell collection, production, quality control and delivery within clinically useful timelines. In-vivo platforms create a different risk: a targeting, persistence or off-target problem could affect several programs built on the same delivery system.
Competition can also erode value gradually. CD19 and BCMA are crowded targets, and cell therapies now compete with other CAR-T products, bispecific antibodies, conventional biologics and potentially new in-vivo treatments.
That mix of clinical, manufacturing and competitive risk is why companies in the same broad market can be worth billions at one end and tens of millions at the other.

Theory only gets you so far. In our document detailing everything you need to know about cell therapy, we dig up the real signals from the field and show you the ones worth watching.
What would make a cell therapy startup worth more than $5 billion?
A new cell therapy company probably needs either exceptional late-stage clinical evidence or a platform that can expand the entire addressable market to reach a valuation above $5 billion today.
Arcellx shows the late-stage route. Gilead paid an implied $7.8 billion after years of collaboration around anito-cel, with an FDA application already accepted and a potential commercial launch approaching.
The platform route is visible in Kelonia. Lilly’s $3.25 billion upfront commitment already puts the company in rare territory, while milestone payments could take the total transaction to $7 billion if the technology delivers. Late-stage and platform routes to a big valuation are patterns we study among leaders in our market report about cell therapy.
The third route is opening a much larger disease category. Solid tumors are one example after the first CAR-T approval in that area. Autoimmune diseases could be even larger if durable immune reset becomes practical and safe enough for broader use.
An early-stage company developing another conventional ex-vivo CAR-T for a crowded blood-cancer target now has a much harder case to make.
So, what does the cell therapy startup valuation ranking tell us today?
The cell therapy market is currently producing enormous valuations, but almost all of that excitement is concentrated around a small group of commercially proven products and technologies that could make cell therapy much easier to use.
Our dataset contains roughly 14 valuation points around or above $1 billion when ranges are measured at their midpoint. The first five account for close to three-quarters of the value in that billion-dollar group.
CAR-T is clearly driving the high end of the market. CARVYKTI has shown that engineered cell therapy can generate multibillion-dollar annual sales. Arcellx shows how much a late-stage differentiated CAR-T can be worth to an existing partner. Meanwhile, the recent wave of Capstan, Orbital, Kelonia, EsoBiotec, Interius and Sail transactions shows where the next strategic battle is taking place: generating therapeutic cells directly inside patients.
At the same time, the lower half of the ranking contains companies that raised hundreds of millions of dollars and are currently worth a fraction of that amount. Cell therapy investors are being highly selective rather than broadly optimistic.
Our final judgment is that the strongest valuations reflect a real shift in the market, but only a narrow part of the sector is benefiting. Commercial CAR-T, in-vivo delivery, autoimmune expansion and the first progress in solid tumors are where most of the premium is accumulating.
Our methodology
This analysis estimates the most defensible current valuation for companies in the cell therapy market and supports the ranking used on New Market Pitch’s cell therapy market page. We compare completed financing rounds, public-market values, acquisition terms, regulatory progress, commercial revenue and other company-specific evidence rather than simply repeating the last valuation ever reported.
We keep three types of valuation evidence separate. An observed valuation comes directly from evidence such as a completed financing, public market capitalization or disclosed acquisition price. An implied valuation can be derived from financing or transaction information even when no formal valuation was announced. An estimated valuation uses broader financial, operating or comparable-company evidence when a direct current mark is unavailable.
For private companies, a recent completed funding round with a disclosed valuation normally provides the strongest anchor. Older rounds receive less weight, especially when clinical progress, public biotech multiples or comparable transactions have changed materially since the financing.
Public companies are valued from public-market evidence, while acquired companies are represented by disclosed transaction values when a meaningful standalone current valuation no longer exists. That is why the ranking includes acquisition benchmarks such as Kite, Arcellx, Capstan, Poseida and Gracell alongside public-market values such as Legend, Iovance and Mesoblast.
We do not mechanically average valuation methods. More recent, direct and company-specific evidence receives more weight, and we use ranges when the available evidence is indirect, old or conflicting. Funding totals are tracked separately because cumulative capital raised is not itself a valuation.
Commercial evidence is used as a supporting anchor where it materially changes the picture. That includes CARVYKTI net trade sales from Legend Biotech, Amtagvi and total product revenue from Iovance, Ryoncil revenue and gross profit from Mesoblast, and Aucatzyl product revenue from Autolus.
Regulatory and strategic evidence also matters because this market can reprice quickly after approvals, clinical readouts or large pharma transactions. We therefore used FDA updates on CAR-T REMS requirements and Treg therapy, CARsgen’s solid-tumor CAR-T approval announcement, and acquisition or partnership disclosures from Gilead, Lilly, AbbVie, Bristol Myers Squibb, AstraZeneca, Roche, Bayer and Johnson & Johnson.
Key sources include: Gilead on the $11.9 billion Kite acquisition, Gilead on the Arcellx acquisition, Lilly on the Kelonia transaction, AbbVie on Capstan, Bristol Myers Squibb on Orbital, AstraZeneca on EsoBiotec, Johnson & Johnson on Sail Biomedicines, Legend Biotech’s earnings releases, Iovance’s 2025 Form 10-K, the FDA on removal of CAR-T REMS requirements, and the FDA on the first approved regulatory T-cell-based immunotherapy.
The principle behind the ranking is simple: use the strongest current company-specific evidence available, keep acquisition values, public market caps and inferred private valuations clearly distinguished, and avoid false precision when the data does not support it.

In our report covering the cell therapy market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us