How big is the conversational AI market really?
Whether you're building or investing in the conversational AI market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The conversational AI market is about $18 billion today on a broad definition, while the newer customer-facing AI-agent layer is closer to $3 billion to $5 billion.
The headline disagreement between market reports is mostly a definition problem. Some studies count chatbots and virtual assistants; others add speech, NLP, agent-assist software, orchestration, services and older enterprise systems.
The freshest 2026 estimates mostly cluster near $17 billion to $18 billion. The main outlier is 360iResearch at $23.22 billion, which pushes the average up even though the median of the current estimates is only $17.8 billion.
An $18 billion market only makes sense if conversational AI includes the installed base as well as the new agent wave. The disclosed revenue of Sierra, Parloa and other AI-native vendors is growing quickly, but it is nowhere near large enough by itself to explain the full category.
Customer service is where the economics are clearest. Genesys, NiCE, Zendesk, Fin, Sierra, Parloa and Five9 are all monetizing AI around support interactions, and recent acquisitions show large platforms are willing to spend heavily to own that layer.
The pricing model is changing underneath the market. Seats still matter, but outcomes, usage credits and agent work units are becoming more common, so future revenue may depend less on how many employees use the software and more on how much work the software completes.
That creates an unusual growth dynamic: conversational AI usage can explode even if revenue grows more slowly. Falling inference and speech costs could let companies automate far more conversations without increasing spending at the same pace.
The market has moved beyond the pilot stage in a meaningful number of large deployments. Genesys, NiCE, Microsoft and Sierra are already reporting paid adoption, ARR or consumption growth that looks like production spending rather than innovation-budget experimentation.
The real economic opportunity is much larger than today's software revenue. Contact-center outsourcing alone is around $110 billion a year, and U.S. customer-service wages are roughly $119 billion, although those pools overlap and should not be treated as software TAMs.
A $50 billion conversational AI market is plausible if the broad category keeps growing around 20% annually. Forecasts above $150 billion require much more: the definition has to stay broad, AI agents need to capture far more enterprise work, and revenue has to keep scaling despite cheaper technology and tighter platform bundling.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the conversational AI market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why does one conversational AI report say $17B while another says $23B?
Conversational AI market estimates disagree by billions because researchers are putting different products inside the same category.
Some reports count mostly chatbots, voice bots, virtual assistants and newer AI agents. Others also include speech recognition, NLP software, agent-assist tools, orchestration, implementation services and older enterprise systems that have been around for years.
The difference gets messy quickly. Fortune Business Insights currently values conversational AI at $17.97 billion for 2026. Its separate “enterprise conversational GenAI” category reaches $24.9 billion for the same year. The supposedly narrower GenAI category is therefore larger than the general category from the same research company.
That alone should make us cautious about treating any single market report as the answer.
We found the same problem elsewhere. Grand View Research says 62.4% of conversational AI revenue in 2025 still came from on-premise deployments and 67.3% came from chatbots. Those numbers describe a market with a large legacy software base, rather than a market made mostly of the LLM agents launched over the past three years.
So before asking how big conversational AI is, we need to decide which conversational AI we are talking about.
What should we actually count as conversational AI?
We would count software whose main job is understanding a human conversation and responding, helping or taking action through that conversation.
That gives us a fairly practical boundary.
Fin, Sierra, Parloa and Cognigy clearly fit. Voice agents fit. Traditional enterprise virtual assistants fit. AI systems that listen to a customer call and guide a human support agent also fit because understanding the conversation is central to the product.
For platforms such as Genesys, NiCE, Zendesk, Salesforce, Microsoft and Google, we would count the conversational part of their AI businesses rather than the entire company or platform.
We would exclude most foundation-model revenue. ChatGPT, Claude and Gemini obviously hold conversations, but adding all of their subscription and API revenue would pull huge chunks of the general generative-AI market into conversational AI.
The same rule applies to CRM and contact-center software. A Genesys subscription may contain routing, workforce management, analytics, telephony and AI. Calling the entire subscription conversational AI would inflate the market.
This definition still gives us a broad category, but at least the economic activity has something in common: companies are paying software to understand and handle conversations.
If you want more recent data on this point, please see our latest conversational AI market report.

Theory only gets you so far. In our research about conversational AI, we dig up the real signals from the field and show you the ones worth watching.
Do the latest conversational AI estimates actually agree once we compare the same years?
Mostly yes: the freshest estimates put today's broad conversational AI market around $18 billion, with a few much higher estimates pulling the range upward.
We compared seven published estimates for 2025. They run from $13.2 billion to $19.2 billion. The average is about $16.0 billion and the median is $16.82 billion.
The studies that already publish a 2026 estimate make the picture even clearer. The Business Research Company says $17.12 billion, Grand View Research says $17.6 billion, and Fortune Business Insights says $17.97 billion. 360iResearch is the clear outlier at $23.22 billion.
The median of those four current estimates is $17.8 billion. Their average is $19.0 billion, largely because the 360iResearch estimate sits much higher.
That is why we would use roughly $18 billion as the cleanest single number today rather than simply quoting whichever research firm has the biggest forecast.
| Research firm | Market estimate | Year | Forecast growth |
|---|---|---|---|
| Future Market Insights | $13.2B | 2025 | 17.3% CAGR |
| The Business Research Company | $13.64B | 2025 | 25.5%–25.9% CAGR |
| Fortune Business Insights | $14.79B | 2025 | 21.0% CAGR |
| 360iResearch | $16.82B | 2025 | 44.5% CAGR |
| MarketsandMarkets | $17.05B | 2025 | 19.6% CAGR |
| IMARC | $17.6B | 2025 | 28.0% CAGR |
| Market Glass | $19.2B | 2025 | 17.5% CAGR |
| Current 2026 estimate range | $17.12B–$23.22B | 2026 | Depends heavily on definition |
Does an $18B conversational AI market pass a revenue sanity check?
An $18 billion conversational AI market is believable only when we include incumbent software, older conversational systems, AI assistance and services alongside the new autonomous agents.
The company numbers give us a useful reality check.
Genesys recently passed $400 million of Genesys Cloud AI ARR while the full Genesys Cloud platform approached $2.9 billion ARR. NiCE finished 2025 with $328 million of AI and self-service ARR. Zendesk says its AI business reached $200 million ARR.
The AI-native companies are becoming substantial too. Sierra entered 2026 above $150 million ARR after reaching $100 million only a quarter earlier. Parloa passed $50 million ARR with 150% net revenue retention. SoundHound generated about $169 million of 2025 revenue across voice and conversational AI products.
Salesforce adds another huge number, with Agentforce ARR now above $1.5 billion. We have to discount that heavily when sizing conversational AI because Agentforce also automates sales, workflow and back-office work that has little to do with customer conversations.
Across Salesforce, Genesys, NiCE, Zendesk, Sierra and Parloa alone, the disclosed AI-related ARR adds up to more than $2.6 billion. Much of that falls outside our narrow definition, but the calculation also leaves out Microsoft, Google, AWS, Fin, Five9, Kore.ai, PolyAI, Decagon and hundreds of smaller vendors.
That makes a broad market in the high teens reasonable. It would be much harder to defend $18 billion as the size of the new autonomous-agent business alone.
| Company | Latest disclosed AI metric | Approximate scale | What is included |
|---|---|---|---|
| Salesforce | Agentforce ARR | >$1.5B | Conversational and non-conversational agents |
| Genesys | Genesys Cloud AI ARR | >$400M | AI inside customer-experience software |
| NiCE | AI and self-service ARR | $328M | AI agents, copilots and self-service |
| Zendesk | AI ARR | $200M | Customer-service AI |
| SoundHound AI | 2025 revenue | ~$169M | Voice and conversational AI plus related products |
| Sierra | ARR | >$150M | Customer-facing AI agents |
| Parloa | ARR | >$50M | Enterprise customer-service AI agents |
| Five9 | Enterprise AI revenue growth | +50% YoY in latest FY Q4 | AI inside contact-center software |

In our market report about conversational AI, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
How big is the new AI-agent market inside conversational AI?
We think the modern customer-facing AI-agent market is currently around $3 billion to $5 billion, far below the roughly $18 billion broad conversational AI number.
There is no clean audited total because vendors disclose completely different metrics. Still, the bottom-up evidence gives us the right order of magnitude.
Sierra is already above $150 million ARR. Parloa is above $50 million. Genesys has more than $400 million of AI ARR, although that includes more than autonomous agents. Zendesk has $200 million. NiCE has $328 million across AI and self-service. Fin currently handles more than 2 million customer issues every week. Microsoft is generating rapidly growing consumption revenue from customer-service agents.
Salesforce is much larger, but only part of Agentforce's $1.5 billion-plus ARR belongs here.
We therefore have several billion dollars of visible spending already, while a lot of private-company and hyperscaler revenue remains undisclosed.
A $3 billion to $5 billion range fits that evidence better than pretending every dollar inside a broad conversational-AI report comes from modern AI agents.
The two markets are also moving at very different speeds. Legacy chatbots and enterprise conversational software already provide a large revenue base. AI agents are the smaller layer growing on top of it much faster.
If you want more recent data on this point, please see our latest conversational AI market report.
Where is conversational AI actually making money right now?
Customer service is currently the clearest commercial market for conversational AI.
The biggest disclosed numbers keep coming from customer experience.
Genesys sells AI into contact centers. NiCE's AI growth comes heavily from CXone and Cognigy. Zendesk's $200 million AI business revolves around service. Fin resolves support issues. Sierra and Parloa both built their businesses around customer-facing agents. Five9 says enterprise AI revenue grew 50% in its latest full-year fourth quarter.
The acquisition market points in the same direction.
NiCE paid about $955 million for Cognigy, a specialist in conversational and agentic AI. More recently, Salesforce completed its roughly $3.6 billion acquisition of Fin, formerly Intercom. Fin joins Salesforce with more than 30,000 companies already in its customer base.
Those are large strategic purchases aimed directly at automating customer conversations.
Voice is increasingly part of the same market rather than a separate world. Fin now works across chat, email, WhatsApp, SMS, Slack and voice. Sierra has expanded further into voice. Genesys and NiCE combine digital and telephone interactions inside the same platform.
Conversational AI is spreading into commerce, sales, HR and internal support, but customer service still gives vendors the easiest place to prove the economics: huge interaction volumes, expensive human labor and outcomes that can actually be measured.

In our document detailing everything you need to know about conversational AI, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Are companies really moving conversational AI out of pilot mode?
Yes. Paid conversational AI deployments are scaling fast enough today that the “everyone is still experimenting” description is already outdated.
Genesys gives us one of the clearest examples. More than 70% of Genesys Cloud customers were already using its AI earlier this year. Genesys Cloud AI ARR has since passed $400 million and is growing at more than twice the rate of the overall Genesys Cloud business.
NiCE shows a similar pattern. Its AI and self-service ARR grew 66% during 2025, and AI was included in every new seven-figure CXone deal during the year.
Microsoft provides another useful angle because it measures consumption. Nearly 60% of its customer-service customers were already buying usage-based credits earlier this year. In its latest full-year results, Microsoft said customer-service credit consumption had jumped fourfold from the previous quarter.
Sierra's growth looks different because it started from scratch. The company crossed $100 million ARR after seven quarters and entered this year above $150 million. One quarter alone contributed about $50 million of additional ARR.
These are production budgets, not innovation-lab budgets.
The deployments are still uneven across companies, especially when data quality, integrations or compliance become difficult. But a handful of pilots can no longer explain the revenue.
Are businesses paying for conversations, seats or outcomes now?
Conversational AI is increasingly being sold through usage and outcomes alongside the familiar software subscription.
Fin gives us the cleanest example. Its standard price is $0.99 for many successful AI outcomes, including a resolved conversation. Fin says its agent currently resolves more than 2 million customer issues every week.
At the standard $0.99 price, 2 million weekly outcomes would annualize to roughly $103 million. Real customer contracts include different volumes and commercial terms, so we should treat that calculation as an order-of-magnitude check rather than Fin's reported revenue.
Still, it is revealing. A single AI agent product already has enough weekly usage to support a nine-figure annual revenue business at list price.
Microsoft is moving in the same direction with usage-based credits. Salesforce measures agent activity through Agentic Work Units. Sierra explicitly sells around outcomes rather than tokens, and its newer agents can manage customer interactions that continue over days or weeks.
This pricing shift also changes what “market size” means. Traditional SaaS revenue often followed the number of human seats. Conversational AI revenue can increasingly follow how much work the AI actually completes.
As companies automate more conversations, software spending can rise even while the number of human customer-service seats falls.

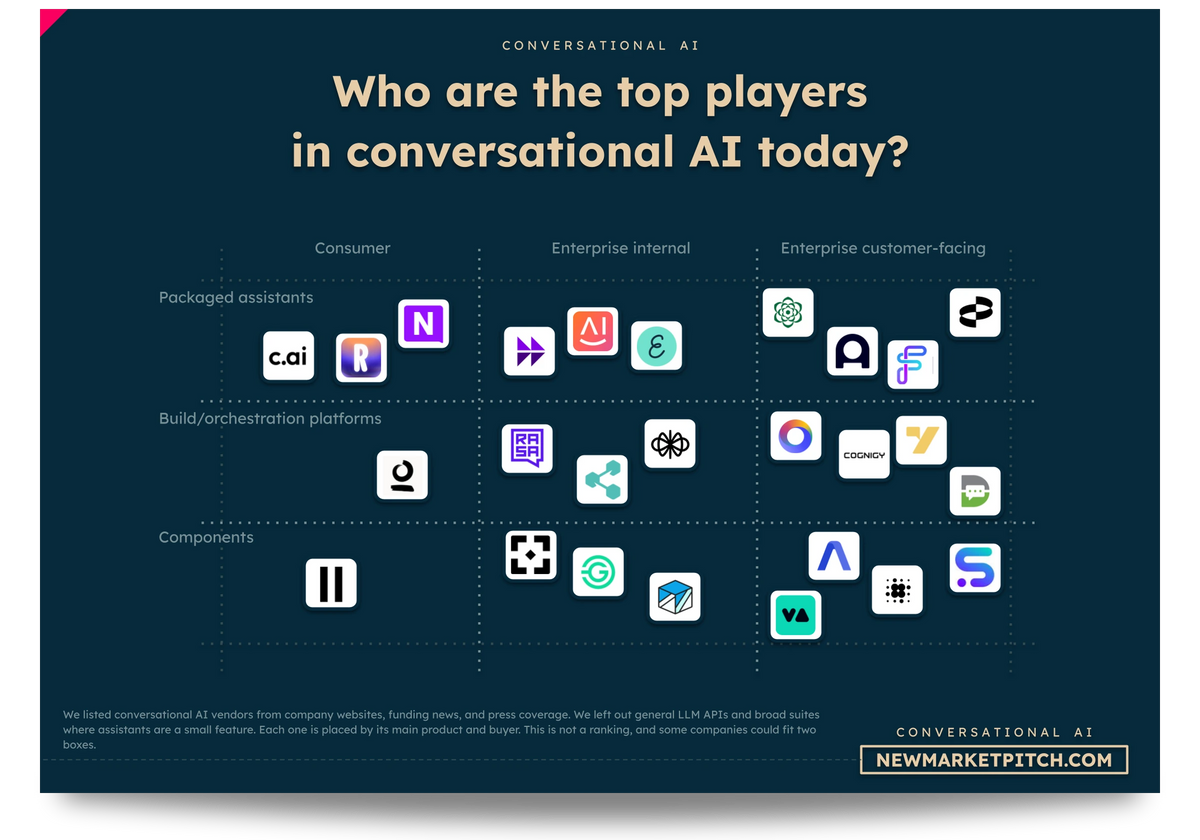
In our report covering the conversational AI market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Can conversational AI already replace human support agents?
Conversational AI can already finish a large share of routine customer-service work, while harder conversations still require people.
Fin currently reports an average resolution rate of about 76% across its AI customer agent. That means roughly three out of four participating issues can reach a resolution without another support interaction under Fin's current measurement system.
We should be careful with that number because resolution rates vary enormously between businesses. A password-reset workflow and a disputed insurance claim have very different levels of difficulty.
The broader evidence points in the same direction. McKinsey has estimated that generative AI could create productivity gains worth 30% to 45% of current customer-care costs. In more recent research, McKinsey said AI could unlock as much as 60% of addressable customer-care volume.
Human assistance remains a large part of the conversational-AI business too. Genesys, NiCE, Zendesk and Microsoft all sell tools that listen to conversations, retrieve information, recommend answers and coach human agents.
The economic opportunity therefore includes two things happening at once: AI finishing more conversations by itself and AI making the remaining human conversations cheaper or faster.
That makes the market bigger than pure chatbot replacement.
If you want more recent data on this point, please see our latest conversational AI market report.
Is conversational AI already bigger than the contact-center software market?
On today's broad research definitions, conversational AI is already more than twice the size of the cloud contact-center software market.
The comparison is unusually clean if we use the same research publisher.
Fortune Business Insights currently puts conversational AI at $17.97 billion for 2026. Its estimate for contact center as a service, or CCaaS, is $8.33 billion.
That makes conversational AI about 2.2 times larger.
The gap sounds strange at first because many conversational-AI products are sold inside contact centers. The explanation comes from scope.
Conversational AI research also captures chatbots on websites and apps, enterprise virtual assistants, voice systems, NLP technology, self-service products, professional services and conversational tools used outside formal contact centers.
Grand View Research reaches a similar conclusion from another angle. Its conversational-AI category includes a large on-premise installed base, while CCaaS is specifically cloud contact-center software.
The comparison gives us a useful warning when sizing the market. An $18 billion conversational-AI estimate cannot represent only the new AI bots being added to cloud call centers. There simply is not enough underlying CCaaS revenue for that interpretation to make sense.

Our research about conversational AI gets updated several times a month, so you always get the latest view of where things stand.
How much spending could conversational AI eventually go after?
Conversational AI is attacking customer-service spending pools worth well above $100 billion a year, which leaves plenty of room above today's roughly $18 billion software market.
One external spending pool already reaches that scale by itself. Grand View Research estimates the global call and contact-center outsourcing industry at about $110 billion in 2026.
The U.S. labor market gives us another way to check the order of magnitude. The Bureau of Labor Statistics currently counts about 2.666 million customer-service representatives, with median annual pay of $44,770.
Multiplying those two figures gives roughly $119 billion of annual base wages in the U.S. alone.
We should never add the $110 billion outsourcing market and the $119 billion U.S. wage figure together because they overlap. Neither should be treated as a software TAM. Companies will keep human workers, and AI vendors will capture only part of the savings they create.
They still show why the market can become much larger.
A vendor does not need to capture anywhere near the full labor cost of an automated conversation. If conversational AI software eventually absorbs even a modest percentage of the money businesses currently spend answering customer questions, a market several times larger than today's becomes possible.
Could cheaper AI make conversational AI revenue grow slower than usage?
Yes. Conversational AI usage could grow much faster than conversational AI revenue as the cost of running each conversation keeps falling.
This is one of the biggest reasons to be cautious with aggressive market forecasts.
Imagine an AI agent that costs a company $1 to handle an issue today. If inference, speech and software costs eventually cut that price to $0.30, the company could more than triple its automated volume before spending the same amount of money.
We are already seeing pricing move closer to completed work. Fin charges by outcome. Microsoft sells consumption credits. Sierra sells around outcomes. Salesforce tracks agent work units.
That means the number of AI-handled conversations could explode without revenue following at exactly the same speed.
Competition creates another pressure. Customer-service platforms increasingly bundle AI with routing, analytics, CRM data and workflow automation. A company that previously bought five separate tools may eventually buy one larger platform.
So we are much more confident that conversational AI usage will grow dramatically than we are in any forecast that assumes a 30% or 40% revenue CAGR for most of the next decade.

In our market report about conversational AI, you will always find fresh funding data, taken straight from our own verified funding database.
Are today's conversational AI growth forecasts realistic?
Growth around 20% a year looks realistic today, while forecasts above 40% need a much more aggressive set of assumptions.
The current company data are certainly strong enough to support a fast-growing market.
Genesys Cloud AI is growing at more than twice the rate of the company's cloud platform. NiCE's AI ARR grew 66% in 2025. Five9's enterprise AI revenue grew 50% in its latest full-year fourth quarter. SoundHound almost doubled annual revenue. Sierra went from launch to more than $150 million ARR in roughly two years.
These AI products are growing much faster than the companies around them.
Genesys overall revenue grew 13% in its latest completed fiscal year. NiCE's total revenue grew far slower than its AI business. Five9's full company revenue also grew much slower than its enterprise AI line.
That is what we would expect while spending moves from older software into a newer product category.
The market-research forecasts reflect very different assumptions about how long this phase lasts. Market Glass expects 17.5% annual growth through 2032. MarketsandMarkets uses 19.6%. Fortune uses 21%. Grand View Research uses 23.8%. IMARC uses 28%.
Then 360iResearch jumps to 44.5%.
A sustained high-teens or low-20s rate fits the revenue evidence we see today. A 44% annual rate sustained for years would require conversational AI to keep behaving like an early-stage startup category even after it becomes a very large software market.
Possible, yes. But it is an aggressive scenario.
If you want more recent data on this point, please see our latest conversational AI market report.
Can conversational AI really become a $50B market?
Yes. A $50 billion conversational AI market looks quite plausible if today's broad definition survives and revenue keeps growing around 20% a year.
The arithmetic is fairly forgiving.
Starting from roughly $18 billion, a 20% annual growth rate gets the market past $50 billion in about six years. MarketsandMarkets reaches $49.8 billion by 2031. Market Glass reaches $59.4 billion by 2032.
Those forecasts require strong growth, but nothing close to the most extreme assumptions in the market.
The underlying spending pool is large enough. Customer-service outsourcing alone is already around $110 billion annually. U.S. customer-service wages are around $119 billion. Conversational AI is also moving beyond support into sales, commerce, internal service desks and other workflows.
The harder question starts above $100 billion.
IMARC expects $172.5 billion by 2034. 360iResearch goes even further, projecting more than $220 billion by 2032. Those outcomes require the category to expand very quickly while keeping a broad definition and capturing much more enterprise spending.
We see enough evidence to take $50 billion seriously. The $150 billion to $200 billion forecasts still depend on several things going right at once.

In our document detailing everything you need to know about conversational AI, we look at what the winners do differently, so you can learn from the best instead of guessing.
How big is the conversational AI market really?
We would put the broad conversational AI market at about $18 billion today, with only around $3 billion to $5 billion coming from the newer generation of customer-facing AI agents.
That is the cleanest answer we can get from the evidence.
Seven separate 2025 estimates average almost exactly $16 billion. The newest 2026 estimates cluster around $17 billion to $18 billion, with a few reports pushing above $20 billion. The median of the four current estimates we compared is $17.8 billion.
The company data broadly support that order of magnitude. Genesys already has more than $400 million of AI ARR. NiCE has $328 million. Zendesk has $200 million. Sierra has passed $150 million. Parloa has passed $50 million. SoundHound generated about $169 million in annual revenue. Salesforce's Agentforce is above $1.5 billion ARR, although only part of it belongs in conversational AI.
The $18 billion figure works when conversational AI includes the older chatbot and virtual-assistant market, agent assistance, voice technology, enterprise platforms and related services.
The newer AI-agent layer is still much smaller. Our best working range is $3 billion to $5 billion today. That is the part currently growing fast enough to change the shape of the wider market.
And behind both numbers sits a much larger economic pool. Call-center outsourcing alone is worth about $110 billion a year, while U.S. customer-service wages are around $119 billion.
So the useful answer is three numbers: roughly $18 billion for conversational AI broadly, around $3 billion to $5 billion for modern customer-facing AI agents, and more than $100 billion of customer-service spending that these products can gradually attack.
Conversational AI is already a large software market. The newer AI-agent business inside it is still early enough that the next several years can materially change the size of the category.
If you want more recent data on this point, please see our latest conversational AI market report.
Our methodology
The conversational AI market is unusually hard to size because published reports often use the same label for materially different businesses. Some focus on chatbots, voice bots and virtual assistants; others also include speech recognition, NLP software, agent-assist tools, orchestration, implementation services and older enterprise systems.
Rather than choosing one market report and treating it as the answer, we broke the question into the few dimensions that actually determine the result: category definition, convergence between published estimates, observable vendor revenue, commercial adoption, pricing models, the size of the customer-service spending pool and the growth assumptions embedded in longer-term forecasts.
For each dimension, we prioritized recent, checkable evidence from company disclosures, earnings materials, official pricing and product pages, government statistics, acquisition announcements and the original pages of major market-research publishers. We aligned figures to comparable years where possible and kept revenue, ARR, usage, deployment share, resolution rates and broader platform sales separate rather than treating them as interchangeable.
Published market estimates were then checked against bottom-up company evidence. That meant testing whether a broad $18 billion market was compatible with disclosed AI revenue from Genesys, NiCE, Zendesk, Sierra, Parloa, SoundHound and Salesforce, while avoiding the mistake of counting an entire CRM, contact-center or foundation-model business as conversational AI.
We used ranges where the evidence supports an order of magnitude but not a precise total. That is especially important for the newer customer-facing AI-agent layer, where vendors disclose different metrics and several large providers do not separately report conversational-agent revenue.
Long-term forecasts were treated as scenarios rather than facts. We compared their implied growth rates with current company growth, falling inference costs, usage-based pricing, platform bundling and the much larger labor and outsourcing pools that conversational AI is trying to capture.
Key sources used for this analysis include: Fortune Business Insights on the conversational AI market, Fortune Business Insights on enterprise conversational GenAI, Grand View Research on conversational AI, The Business Research Company, 360iResearch, MarketsandMarkets, IMARC, Future Market Insights, Genesys on Cloud and AI ARR, NiCE on 2025 results and AI/self-service ARR, Zendesk on AI ARR, Sierra on ARR progression, Parloa on ARR and net revenue retention, SoundHound AI on 2025 revenue, Salesforce on Agentforce ARR, Fin pricing, Fin usage data, Microsoft FY2026 Q3 earnings, Microsoft FY2026 Q4 earnings, NiCE on the Cognigy acquisition, Salesforce on the Fin acquisition, the U.S. Bureau of Labor Statistics on customer-service employment and pay, and Grand View Research on call and contact-center outsourcing.
Sources were reviewed using information available through September 2026.

If you build or invest in the conversational AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us