What is the real market size of femtech?
Whether you're building or investing in the femtech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The real market size of FemTech is roughly $10–15 billion today for dedicated FemTech businesses, while a broader technology-enabled women's-health ecosystem can reasonably reach $40–65 billion.
The huge gap between published estimates is mostly a boundary problem. A $10.7 billion estimate and a $66.4 billion estimate can both be internally coherent when one counts dedicated female-health products and the other pulls in wearables, diagnostics, hospitals and broader healthcare services.
The category has quietly expanded over time. FemTech once referred mainly to products built around menstruation, fertility, pregnancy and reproductive health; some current definitions now reach deep into mainstream healthcare and consumer technology.
General-purpose technology is where the numbers can get distorted fastest. Oura and Apple have meaningful women's-health features, but assigning all of their wearable revenue to FemTech would make the category look much larger without creating any new female-specific revenue.
Actual company economics fit a low-tens-of-billions core market better than a $50–60 billion pure-play market. Progyny alone generates more than $1 billion annually, while companies such as Midi Health, Natural Cycles, Flo and Pomelo Care show real scale without adding up to anything close to $60 billion.
The biggest FemTech businesses are not necessarily the ones with the biggest audiences. Fertility and family-building platforms can monetize a much smaller population than menstrual apps because a single treatment pathway can involve thousands or tens of thousands of dollars of healthcare spending.
Menopause is becoming unusually important because it combines recurring care with a long duration of need. Midi Health's roughly $150 million revenue run rate suggests the category can support substantial businesses well before menopause expands into broader midlife health.
Women's-health funding numbers need the same scrutiny as market-size estimates. Recent investment totals sometimes include companies that serve women meaningfully but are not primarily women's-health businesses, which can make the funding ecosystem look much larger than core FemTech itself.
The widely quoted $500 billion and $1 trillion figures should not be treated as current FemTech revenue. The former describes potential commercial value from improving selected women's-health conditions, while the latter describes potential annual GDP gains from narrowing the wider women's-health gap.
The cleanest way to read the market is therefore in layers: roughly $10–15 billion of core FemTech, roughly $40–65 billion when adjacent technology-enabled women's health is included, and vastly larger future economic value that may ultimately be captured by startups, pharma companies, hospitals, diagnostics groups and other healthcare providers.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

Your time is limited. In our report covering the femtech market, we put numbers on each part of the market, so you can see where it makes sense to focus.
How big is the FemTech market really today?
The dedicated FemTech market is probably worth around $10–15 billion today, while broader definitions of technology-enabled women's health can push the number above $50 billion.
That range looks absurdly wide until we examine what researchers are actually counting.
Fortune Business Insights' latest estimate puts the global FemTech market at $10.67 billion. Grand View Research currently calculates $52.9 billion. The Business Research Company arrives at $55.88 billion, while Precedence Research goes as high as $66.37 billion.
A market cannot realistically be both $10.7 billion and $66.4 billion at the same time under the same definition. The sixfold gap mostly comes from what gets included.
The lower estimates stay relatively close to technology built specifically around menstruation, fertility, pregnancy, menopause and other female-health needs. The larger ones bring in much more: general wearables, consumer health products, diagnostic services, hospitals, fertility clinics and pieces of businesses that serve both men and women.
We therefore think $10–15 billion is the more useful figure when talking about core FemTech today. The $40–65 billion range makes sense only for a much wider women's-health technology ecosystem.
| Research source | Current market estimate | What the estimate broadly includes |
|---|---|---|
| Fortune Business Insights | $10.67B | Products, software and tech-enabled services |
| Grand View Research | $52.9B | Devices, software, services and consumer products |
| The Business Research Company | $55.88B | Devices, software, services and multiple healthcare settings |
| Precedence Research | $66.37B | Very large wearable component plus diagnostic services |
| Core FemTech estimate we would use | ~$10–15B | Businesses built primarily around female-specific health needs |
If you want more recent data on this point, please see our latest femtech market report.
Why do FemTech market estimates differ by more than six times?
FemTech market estimates differ so much because researchers are measuring different collections of businesses under the same label.
Fortune Business Insights currently estimates a $10.67 billion market and focuses on products such as fertility monitors, sexual-wellness devices, reproductive-health apps, pregnancy apps, telehealth and subscription programs.
Grand View Research reaches $52.9 billion after adding a wider set of devices, consumer products, services, hospitals and fertility clinics.
Precedence Research goes further. Its $66.37 billion estimate says wearable devices represented 80% of product revenue in the previous year. Once general wearable technology becomes such a large part of the calculation, the result will naturally look very different from a market built mainly around companies such as Flo, Natural Cycles or Elvie.
This is why averaging the estimates does not help. An average of $10.7 billion and $66.4 billion would look precise while describing no clearly defined market.
For anyone using FemTech market-size numbers, the definition deserves more attention than the headline figure.

In our research about women's health technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Has the meaning of “FemTech” quietly become much broader?
Yes. FemTech has gradually expanded from a fairly narrow group of female-health technologies into a label that can now cover large parts of women's healthcare.
Grand View Research gives us a particularly useful example because we can compare the same research publisher over time.
An earlier version of its research projected that FemTech would reach roughly $13.1 billion in 2030. Its newer methodology now expects the market to reach well above $100 billion only a few years later.
FemTech businesses obviously grew during that period, but company revenue did not multiply fast enough to explain such a dramatic change by itself. The newer definition reaches further into devices, services, consumer health and care delivery.
We can see the same expansion in current women's-health investment research. Silicon Valley Bank's 2026 report explicitly looks beyond reproductive and sexual health and covers a much wider set of conditions affecting women. That makes sense for a women's-health report. It gets more complicated when the resulting ecosystem is described as one single FemTech market.
The word still works well as shorthand, but its economic meaning has become much less stable.
What should actually count as a FemTech company?
A company belongs in core FemTech when a female-specific health need is central to why its product exists.
Flo fits easily because menstrual and reproductive health sit at the center of the product. Natural Cycles does too because its core product is digital birth control and fertility tracking. Elvie builds products around pelvic and maternal health. Midi Health focuses heavily on menopause and midlife women's care.
General health technology gets harder to classify.
Oura now has substantial women's-health functionality, including cycle and pregnancy features, but the ring also measures sleep, recovery, cardiovascular signals and general health for everyone. Oura generated $907.9 million in its latest fiscal year. Counting all of that revenue as FemTech would clearly inflate the category.
Apple Watch creates an even larger version of the same problem. Cycle tracking is part of the product, yet Apple Watch sales cannot sensibly become FemTech revenue in full.
We use a practical test: would most of the product still exist without the female-specific health problem it addresses?
When the answer is no, the business sits close to the core of FemTech. When the answer is yes, we treat the company as adjacent even if women's health has become an important product area.
If you want more recent data on this point, please see our latest femtech market report.

Theory only gets you so far. In our market report about women's health technology, we dig up the real signals from the field and show you the ones worth watching.
Is women's health really a $1 trillion market?
The often-quoted $1 trillion figure refers to potential economic gains from improving women's health, so using it as the size of the FemTech market badly overstates current commercial revenue.
The World Economic Forum and McKinsey Health Institute estimated that closing the health gap between women and men could add about $1 trillion to global GDP annually by 2040.
Their calculation includes effects such as fewer years spent in poor health, higher workforce participation and greater productivity. Women currently spend about 25% more of their lives in poor health than men, according to the same research.
Those benefits can be economically enormous without flowing into FemTech company revenue.
A treatment that allows someone to stay healthier and remain in the workforce can create thousands of dollars of economic value even if the company providing that treatment captures only a small portion of it.
So the $1 trillion estimate tells us that women's health has major economic consequences. It tells us very little about how much FemTech companies sell today.
What does the $500 billion women's-health opportunity actually measure?
The $500 billion figure is much closer to a business opportunity, although it still describes potential value rather than current FemTech sales.
In its later women's-health work, McKinsey and the World Economic Forum estimated that addressing a selected group of major conditions could create more than $500 billion in new commercial value.
The conditions include areas such as breast cancer, cardiovascular disease, menopause, endometriosis, migraine and maternal health.
Some of that opportunity could clearly become FemTech revenue. Better diagnostics, menopause platforms, remote maternal monitoring and new digital-care models are obvious examples.
A large part will probably be captured elsewhere. Pharmaceutical companies, hospitals, diagnostic companies, medical-device manufacturers and traditional healthcare providers are also positioned to benefit.
FemTech currently captures only a fraction of the commercial value that could eventually emerge from better women's healthcare.
Do actual FemTech company revenues support a $10–15 billion market?
Yes. The revenues we can observe at major women's-health companies fit much more comfortably with a market in the low tens of billions than with a pure-play FemTech market already worth $50–60 billion.
Progyny generated roughly $1.29 billion of revenue in 2025 from fertility and family-building benefits. Midi Health reached about a $150 million annual revenue run rate after being around $60 million at the end of the previous year. Natural Cycles has been estimated at roughly $63 million of annual revenue.
Pomelo Care is another useful current example. The maternal-care company raised $92 million at a $1.7 billion valuation in early 2026 and says its model now covers nearly 7% of U.S. births. Pomelo does not publicly disclose revenue, which is exactly why we should resist filling every gap with third-party estimates.
Flo is already large enough to operate like a global consumer-health platform, although it remains private and does not regularly publish audited revenue figures.
These businesses give us several billion dollars of visible or strongly evidenced activity once the wider set of fertility, maternal-health, menopause, pelvic-health and reproductive-health companies is included.
Finding the additional tens of billions needed to support a $60 billion pure-play FemTech market is much harder. Most of that missing revenue appears only after broader healthcare and general technology businesses enter the calculation.
| Company | Latest useful scale indicator | How reliable is it? |
|---|---|---|
| Progyny | ~$1.29B annual revenue | Reported revenue |
| Oura | $907.9M annual revenue | Reported, but only partly women's health |
| Midi Health | ~$150M revenue run rate | Company-confirmed figure reported publicly |
| Pomelo Care | Covers nearly 7% of U.S. births | Company-disclosed operating scale |
| Natural Cycles | ~$63M estimated annual revenue | Third-party estimate |
| Flo Health | Large global subscription business | Revenue remains private |
If you want more recent data on this point, please see our latest femtech market report.

In our document detailing everything you need to know about femtech, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Why do the $50–60 billion FemTech estimates still look plausible?
The larger FemTech estimates become plausible once we include real women's-health revenue that sits inside broader technology and healthcare businesses.
Oura shows how quickly the boundary can move. The company generated $907.9 million in fiscal 2025, more than double the previous year, and women's-health features are increasingly important to its product. Yet Oura remains a general health wearable.
Hospitals create the same issue on a much bigger scale. Pregnancy, gynecology, fertility and other women's-health services generate substantial healthcare revenue, but hospital revenue belongs to FemTech only under an unusually broad definition.
Diagnostic centers, consumer-health manufacturers and general telehealth businesses add still more.
A $50 billion ecosystem number can therefore be perfectly defensible even when a $50 billion pure-play FemTech number looks far too high.
The disagreement mostly disappears once we stop pretending both figures measure the same thing.
Which parts of FemTech are actually generating the most money today?
Fertility and family-building care currently produce some of the strongest revenue in FemTech because each patient can be associated with thousands of dollars of healthcare spending.
Progyny is the clearest example. Its annual revenue already exceeds $1 billion, even though its member population is tiny compared with the hundreds of millions of people who have downloaded menstrual-health apps.
That difference comes down to economics.
IVF, fertility drugs and associated medical care are expensive. Employers and insurers can also pay part of the bill, allowing fertility platforms to tap budgets much larger than a normal consumer subscription.
Menstrual apps have the opposite profile. Flo can reach an enormous global audience while most users pay little or nothing. Even a very successful premium subscription usually generates far less revenue per user than a fertility treatment pathway.
Pregnancy and maternal care are becoming more commercially important too. Pomelo Care's latest financing valued the company at $1.7 billion after it expanded to nearly 7% of U.S. births. That scale is especially interesting because maternal care connects digital health to large existing medical expenditures.
Population size alone tells us surprisingly little about FemTech revenue. Who pays and how much money already flows through the health problem usually matter more.
Is menopause becoming one of the biggest FemTech businesses?
Menopause is now one of the fastest-developing parts of FemTech, and Midi Health has given the category its clearest proof that substantial revenue can be built around it.
Midi said its annual revenue run rate had reached about $150 million, up from roughly $60 million at the end of the previous year. The company was also treating around 20,000 women per week when those figures were reported.
The broader funding data points in the same direction. Dealroom's latest FemTech breakdown puts menopause at the top of its momentum ranking, with about $104 million invested in the category in 2025 and one unicorn already created.
The opportunity is larger than the current startup revenue suggests because menopause can involve years of recurring care. It also overlaps with bone health, cardiovascular risk, sexual health, metabolic health and longevity.
Midi is already widening into several of those areas.
That could eventually make menopause the entry point into a much larger midlife-health business rather than a standalone treatment category.
If you want more recent data on this point, please see our latest femtech market report.

In our report covering the femtech market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Is FemTech investment still growing?
Investors are still putting serious money into women's health, although the latest data also shows why funding totals need the same definition checks as market-size estimates.
Silicon Valley Bank's latest women's-health report counted about $2 billion of venture investment across the U.S. and Europe in 2025. SVB said that was below the previous year's peak but expected activity to rebound based on deals already visible in 2026.
The more recent quarterly numbers make the classification issue obvious.
FutureFemHealth tracked $738.8 million across 40 women's-health funding rounds in the second quarter of 2026. Its two largest deals were CREATE Medicines at $122 million and Nourish at $100 million. Together they represented around 30% of the tracked total, yet neither company is a pure-play women's-health business.
That does not make the funding figure wrong. It shows how quickly “women's health” becomes larger than FemTech when companies treating broader conditions are included.
Dealroom currently counts 13 FemTech unicorns under its own methodology. We would read that as evidence that the category has produced genuine scale companies, while staying cautious about turning women's-health funding totals into a measurement of core FemTech.
Is FemTech really growing at 15–20% a year?
FemTech is clearly growing quickly, but the exact industry CAGR is far less reliable than the precision of the published forecasts suggests.
Fortune Business Insights currently forecasts roughly 18.4% annual growth. Grand View Research expects 15.5%. The Business Research Company projects more than 20%. Precedence Research expects only about 8.7%.
Those forecasts cannot all describe the same underlying market.
Company data gives us a more useful picture.
Midi's revenue run rate moved from roughly $60 million to $150 million. Oura's total revenue jumped 123% in its latest fiscal year, although only part of Oura belongs inside women's health. Pomelo Care reached a $1.7 billion valuation after expanding its maternity model nationally. Flo continues to build out beyond period tracking into a broader hormonal-health platform.
The strongest categories are growing much faster than mature healthcare markets, but saying that “FemTech grows at 17%” still implies a level of precision the market does not really have.
Change the boundary and you change the growth rate.
| Current forecast | Expected annual growth |
|---|---|
| Precedence Research | ~8.7% |
| Grand View Research | ~15.5% |
| Fortune Business Insights | ~18.4% |
| The Business Research Company | ~20.8% |
Is FemTech being undercounted or overcounted?
Core FemTech revenue is probably overcounted in the biggest market reports, while the economic importance of women's health is still seriously undercounted if we look only at startups.
Breast cancer illustrates the second part well. Enormous amounts are spent on drugs, diagnostics and hospital care, yet most of that activity would never appear in a normal list of FemTech companies.
Cardiovascular disease in women creates the same problem. So do maternal complications treated inside hospitals and many hormone therapies sold by large pharmaceutical companies.
If we define FemTech narrowly, all of this activity disappears.
If we solve that problem by assigning large pieces of hospitals, Apple, Google, Garmin and mainstream healthcare companies to FemTech, the market quickly loses its usefulness as a distinct category.
The cleaner approach is to keep three layers separate: dedicated FemTech businesses, the broader technology-enabled women's-health ecosystem, and the much larger economic opportunity created by improving women's health.
Mixing those layers is where most of the confusion starts.
If you want more recent data on this point, please see our latest femtech market report.

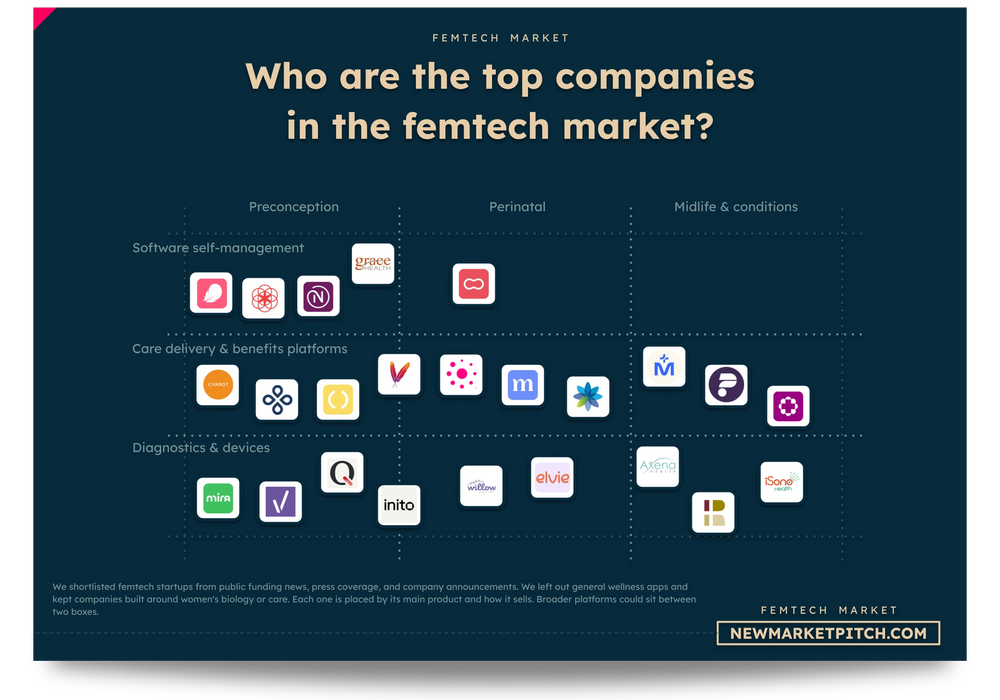
In our research about women's health technology, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
So what is the real market size of FemTech today?
We would put core FemTech at roughly $10–15 billion today, with the broader technology-enabled women's-health ecosystem somewhere around $40–65 billion.
The lower figure fits the revenue we can actually trace across dedicated fertility, menstrual health, maternal care, menopause, reproductive health, pelvic health and related companies.
The higher range becomes reasonable once general wearables, diagnostic services, hospitals, consumer-health products and adjacent technology businesses enter the picture.
Beyond that, the numbers describe future value rather than today's FemTech sales. McKinsey and the World Economic Forum see more than $500 billion of potential commercial value from better solutions for selected women's-health conditions, while closing the broader women's health gap could eventually add around $1 trillion a year to global GDP.
FemTech has already moved beyond the tiny niche it was often treated as a decade ago, but current revenue still captures only a small part of the health problems the industry is trying to address. Fertility already supports billion-dollar businesses. Menopause is producing companies with nine-figure revenue run rates. Maternal care is creating billion-dollar valuations. Women's-health AI companies are now receiving materially higher valuations than the wider sector median, according to SVB's latest analysis.
For now, calling FemTech a $10–15 billion core market gives us the cleanest picture of what dedicated companies actually sell. Calling the wider ecosystem a $40–65 billion market is also defensible, provided we say clearly what has been added.
| Figure | What it really describes |
|---|---|
| ~$10–15B | Core FemTech revenue market today |
| ~$40–65B | Broader technology-enabled women's-health ecosystem |
| >$500B | Potential commercial value from improving selected women's-health conditions |
| ~$1T annually | Potential global GDP gain from closing the women's health gap by 2040 |
Our methodology
This analysis tests how much of the published FemTech market can reasonably be attributed to dedicated female-health businesses rather than to the much wider women's-health economy. Instead of selecting one market report, we compared competing definitions, current company economics, investment activity, adjacent healthcare revenue and the larger commercial and economic opportunity around women's health.
Market estimates were compared on scope rather than averaged together. Fortune Business Insights provides the narrower current benchmark, while Grand View Research, The Business Research Company and Precedence Research show how quickly the number expands when more devices, services, healthcare settings and wearables are included.
We also compared definitions over time. Grand View Research's earlier FemTech work, which projected a market of roughly $13.1 billion by 2030, was particularly useful because its much larger current estimate shows how methodology and category boundaries can change even within the same research publisher.
For company economics, we prioritized reported or company-confirmed numbers where they were available. Progyny's SEC filing provides a directly observable revenue benchmark, while Oura's filing helps illustrate the problem of assigning the full revenue of a general health platform to women's health. Pomelo Care and Midi Health provide more recent operating-scale examples in maternal care and menopause.
We applied a simple boundary test throughout the analysis: would most of the product or business still exist without the female-specific health problem it addresses? Companies built primarily around menstruation, fertility, pregnancy, menopause, pelvic health or related needs sit close to core FemTech. General wearables, hospitals and broad healthcare platforms are treated as adjacent when women's health is only one part of their activity.
Funding data was treated the same way. Silicon Valley Bank, Dealroom and FutureFemHealth help show how capital is moving into women's health, but we checked which companies sit inside those totals rather than assuming every dollar represents investment in pure-play FemTech.
The large opportunity figures were kept separate from current revenue. The World Economic Forum and McKinsey Health Institute's roughly $1 trillion estimate measures potential annual GDP gains from closing the women's-health gap, while their later work identifying more than $500 billion of potential commercial value covers a broader set of conditions and future opportunities. Neither is used as today's FemTech market size.
Key sources used for this analysis include Fortune Business Insights on the FemTech market, Grand View Research's current FemTech analysis, Grand View Research's earlier market methodology, The Business Research Company, Precedence Research, the World Economic Forum and McKinsey Health Institute on the women's-health gap, and McKinsey's work on the commercial opportunity in women's health.
Company and investment evidence came from Silicon Valley Bank's women's-health report, Progyny's SEC filing, Oura's SEC filing, Oura's company background, Apple's health platform documentation, Pomelo Care's Series C announcement, Business Insider on Midi Health's company-confirmed revenue run rate, Dealroom's FemTech analysis, FutureFemHealth's Q2 2026 funding analysis, Flo Health, and Natural Cycles.

Our market report about women's health technology gets updated several times a month, so you always get the latest view of where things stand.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us