Healthcare AI: what are the top startups?
Whether you're building or investing in the healthcare AI market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
OpenEvidence, Abridge, Viz.ai, Hippocratic AI, and Ambience Healthcare are the top private healthcare AI startups today, with OpenEvidence leading overall thanks to its extraordinary physician adoption and commercial growth.
OpenEvidence has reached a $15 billion valuation, with estimated annualized revenue of $300 million. Its unusual advantage is that physicians can use the platform for free while pharmaceutical and medical-device advertisers pay to reach them during clinical research. Free for doctors and paid for by advertisers is one of the business models we test in our market report about healthcare AI.
Abridge is the strongest enterprise medical documentation startup, supporting more than 100 million clinical conversations annually across over 300 health systems. Its deeper hospital integrations and expansion into clinical decision support could prove more durable than standalone transcription technology.
Viz.ai may have the most established operating business of the leading startups. With deployments across approximately 2,000 hospitals and reported profitability in its healthcare division, it has already achieved the clinical reach and financial discipline that many younger healthcare AI companies are still pursuing.
Hippocratic AI leads patient-facing agents on reported activity, with more than 250 million interactions. But the gap between automating conversations and replacing qualified healthcare professionals remains enormous, especially when independently verified patient outcomes are still limited.
Ambience Healthcare is becoming a serious threat to Abridge. At Ardent Health, its software supported more than one million patient encounters, with clinicians using it in 87% of eligible ambulatory visits and saving over three hours per week on documentation.
Medical scribes are producing measurable time savings, but documentation alone is becoming a less defensible business. Microsoft, Epic, and OpenAI can compete through existing distribution, pushing independent startups toward clinical reasoning, specialty workflows, coding, and deeper hospital integration.
Medical imaging offers a different kind of competitive protection. Viz.ai and Aidoc have built clinical workflows, diagnostic infrastructure, and institutional relationships that are considerably harder to reproduce than a basic AI note-taking application.
Healthcare billing may be an underrated opportunity. AKASA's customers account for approximately 10% of U.S. inpatient discharges, while Candid Health has reported rapid contracted revenue growth and 180% net dollar retention. Their value can be measured directly through administrative efficiency and financial performance.
International adoption is another important dividing line. Heidi Health reports approximately 2.7 million consultations per week across 190 countries, showing that clinician-led distribution can generate enormous usage without depending entirely on contracts with large American hospital systems.
Valuations are already pricing in substantial future success. OpenEvidence trades at roughly 50 times estimated annualized revenue, while Abridge's last disclosed valuation was approximately 53 times its estimated ARR at the time. Both have real traction, but there is very little room for growth to disappoint.
Our overall choice is OpenEvidence for commercial momentum, followed by Abridge for enterprise adoption and Viz.ai for proven clinical deployment. The longer-term winners may ultimately be the companies that become essential to hospital operations rather than those attracting the most physician attention today.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

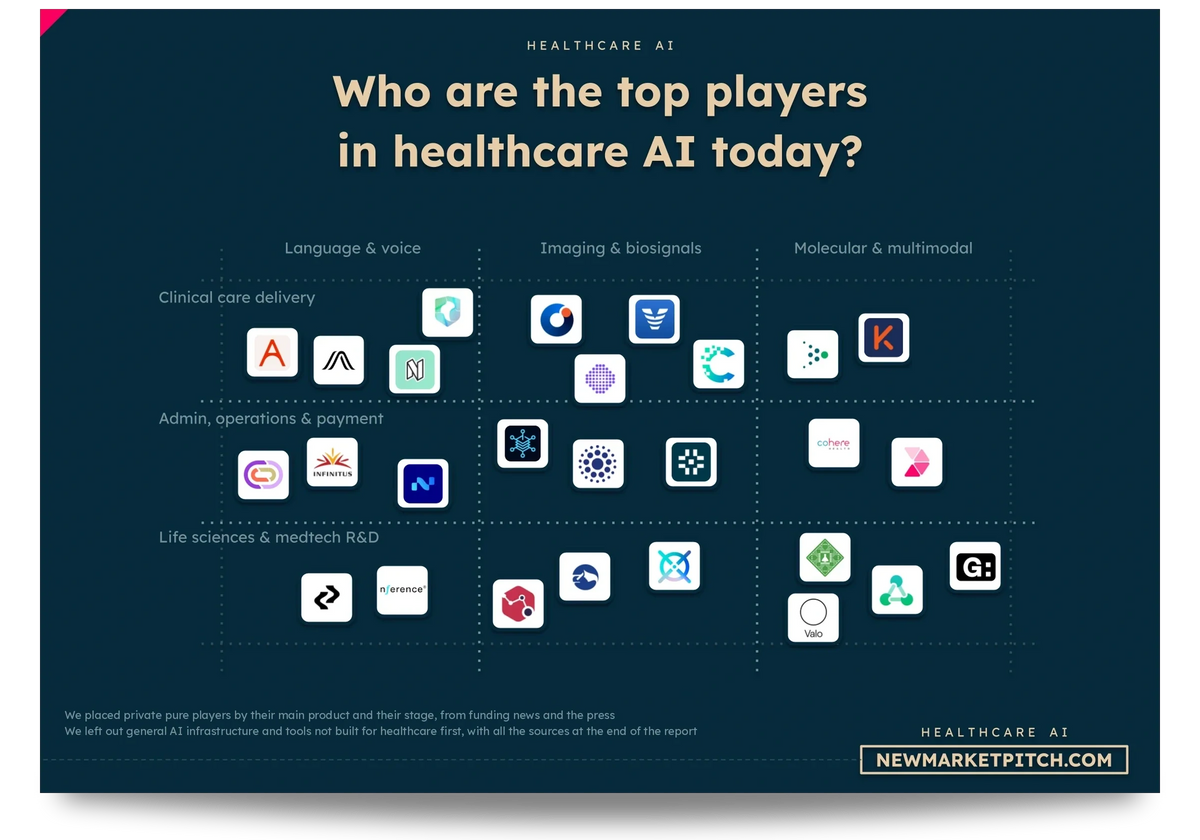
In our report covering the healthcare AI market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why are healthcare AI startups getting so big right now?
Healthcare AI has become one of the hottest startup markets because doctors and hospitals are finally using these products at a scale that would have seemed unlikely just a few years ago.
OpenEvidence reached a $15 billion valuation after raising another $250 million in September 2026. Abridge now operates across more than 300 U.S. health systems, while Viz.ai has reached approximately 2,000 hospitals. Hippocratic AI, which develops conversational agents for patient care, has reported more than 250 million patient interactions.
The speed of growth is striking, but the companies are solving very different problems. OpenEvidence helps physicians research medical questions, Abridge handles clinical documentation, Viz.ai detects diseases and coordinates treatment, and Hippocratic AI automates patient conversations. Research, documentation, disease detection and patient calls are four problems clinicians pay to solve, and we map the others in our report covering the healthcare AI market.
What has changed is the amount of real usage behind these businesses. According to Sacra, OpenEvidence went from approximately 3 million monthly clinical consultations in early 2025 to 20 million in January 2026. Meanwhile, healthcare systems are moving from limited AI scribe trials toward deployments involving thousands of clinicians. The strongest startups have moved well beyond demonstrating that their technology works.
Which healthcare AI startups are actually leading today?
OpenEvidence, Abridge, Viz.ai, Hippocratic AI, and Ambience Healthcare currently stand out as the top private healthcare AI startups, although each leads a different part of the industry.
We give more weight to actual medical usage, paying customers, and clinical results than to funding rounds. That's especially important in healthcare, where a free application used by thousands of physicians and a hospital platform generating substantial subscription revenue can both claim impressive adoption.
OpenEvidence has the strongest combination of physician reach and estimated revenue growth. Abridge leads our assessment of enterprise medical documentation, while Viz.ai has a much longer track record in clinical deployment. Hippocratic AI looks strongest in patient-facing voice agents, and Ambience Healthcare has won some particularly demanding hospital customers.
Aidoc, AKASA, Heidi Health, Nabla, and Candid Health complete our broader shortlist. We exclude publicly traded companies such as Tempus AI from the private-startup ranking, although they remain important competitors.
| Startup | Main focus | Strongest evidence | Our assessment |
|---|---|---|---|
| OpenEvidence | Medical research AI | $15B valuation; ~$300M estimated annualized revenue | Overall commercial leader |
| Abridge | Clinical documentation | 300+ health systems; 100M+ annual conversations | Enterprise documentation leader |
| Viz.ai | Disease detection and care coordination | ~2,000 hospitals; profitable healthcare business | Most established clinical platform |
| Hippocratic AI | Patient-facing AI agents | 250M+ reported patient interactions | Patient-agent leader |
| Ambience Healthcare | Documentation and coding | Major hospital customers; strong usage at Ardent Health | Strong Abridge challenger |
| Aidoc | Medical imaging AI | Large imaging deployments; 12-system consortium | Imaging AI contender |
| AKASA | Hospital revenue cycle | Customers cover ~10% of U.S. inpatient discharges | Major hospital automation specialist |
| Heidi Health | AI medical scribing | 2.7M reported consultations weekly | International adoption leader |
| Nabla | AI clinical documentation | Enterprise customers and clinical evaluations | Established scribe challenger |
| Candid Health | Billing automation | 190% annual contracted run-rate growth reported for 2025 | Fast-growing billing specialist |

Our research about AI in healthcare gets updated several times a month, so you always get the latest view of where things stand.
Is OpenEvidence the biggest healthcare AI startup now?
OpenEvidence is currently the most impressive private healthcare AI startup by the combination of valuation, estimated revenue growth, and physician adoption.
Sacra estimates that OpenEvidence reached $300 million in annualized revenue in July 2026, compared with $150 million at the end of 2025 and just $7.9 million at the end of 2024. That's roughly 38 times its earlier annualized revenue level in nineteen months, although these figures are third-party estimates rather than audited company results.
The adoption is equally remarkable. The Financial Times recently reported that nearly two-thirds of U.S. physicians use the platform, which processed more than 42 million prompts during one month. Doctors use OpenEvidence to search medical literature, check treatment options, and answer clinical questions.
Its free-access model has helped it spread quickly. Instead of charging individual physicians, OpenEvidence generates revenue from pharmaceutical and medical-device advertising. Sacra estimates gross margins of approximately 90%, with advertisers reportedly paying exceptionally high prices to reach physicians during clinical research.
It's rare to see a specialist healthcare application combine this level of professional adoption with such fast monetization. OpenEvidence's biggest challenge is now preserving that advantage as competing products become more capable.
Can OpenEvidence really take on UpToDate and ChatGPT?
OpenEvidence has become a genuine threat to UpToDate, but its biggest new competitor may be ChatGPT itself.
According to Sacra, Wolters Kluwer's UpToDate generated approximately $690 million in 2025 revenue, growing about 8% annually. OpenEvidence's estimated $300 million annualized revenue already represents roughly 43% of that figure, despite having a very different business model and a much shorter commercial history.
UpToDate remains deeply established in hospitals, with more than 3 million clinicians worldwide using its clinical knowledge services. OpenEvidence has grown through individual physician adoption and is now integrating more deeply into electronic medical records at institutions including Mount Sinai and Sutter Health.
The competition has become much more interesting since OpenAI introduced ChatGPT for Clinicians in April 2026. Both products offer verified physicians free access to AI-powered medical research tools. Abridge and Doximity are also adding research capabilities to their existing physician products.
OpenEvidence is pushing in the opposite direction, expanding beyond research into note-taking, billing suggestions, and other medical workflows. These companies increasingly want to become the assistant that doctors keep open throughout the working day.
We currently give OpenEvidence the advantage among specialist medical research startups, but its lead is less secure than its valuation suggests. OpenAI already has enormous consumer distribution, while UpToDate still has institutional contracts and a long-established editorial reputation.

In our market report about AI in healthcare, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Abridge still the leader in AI medical scribes?
Abridge is currently the strongest independent enterprise AI medical scribe startup, and its lead is supported by far more than its funding.
The company says its software supports more than 100 million clinical conversations annually across hundreds of health systems. That's equivalent to approximately 274,000 conversations per day when averaged across a year.
Abridge has also built a record of expanding within major customers. BJC Health extended access to approximately 4,000 clinicians, WVU Medicine planned a deployment covering more than 2,800, and CHRISTUS Health expanded its agreement into inpatient care. Those expansions carry more weight than announcing another small hospital pilot.
Its work with the U.S. Department of Veterans Affairs adds another dimension. Abridge reported deployment across more than 75 VA medical centers, demonstrating that its software can operate inside a large, complicated public healthcare system.
Lately, Abridge has been going beyond transcription. In August 2026, the company said its clinical decision-support product had been adopted across its partner network, with monthly active users representing more than half of eligible clinicians and queries per user tripling over two months.
That expansion puts Abridge increasingly close to OpenEvidence's territory. Its advantage is that hospitals already trust it to handle clinical conversations and integrate with patient records. Where AI scribing ends and clinical search begins is a line we draw in our report on healthcare AI.
Is Ambience Healthcare catching up with Abridge?
Ambience Healthcare is one of Abridge's most credible competitors, particularly in hospital specialties where medical documentation and coding are complicated.
Ambience raised $243 million in July 2025 at a $1.25 billion valuation. Its customers include Cleveland Clinic, UCSF Health, Houston Methodist, and Memorial Hermann, giving it a stronger enterprise customer list than many larger-funded healthcare AI startups.
The best evidence comes from Ardent Health. In July 2026, the hospital operator reported that Ambience had supported more than one million patient encounters. Participating clinicians used it in 87% of eligible ambulatory encounters and saved more than three hours per week on documentation.
Cleveland Clinic also selected Ambience after evaluating five competing ambient documentation systems. Winning such an evaluation suggests the company can compete on actual product quality rather than merely pricing.
Abridge still has a considerable advantage in publicly reported health-system coverage, and the two companies do not disclose customer counts in perfectly comparable ways. But Ambience has shown that Abridge can't take the enterprise market for granted.

In our document detailing everything you need to know about healthcare AI, you will always find fresh funding data, taken straight from our own verified funding database.
Are AI medical scribes actually saving doctors time?
AI medical scribes are genuinely reducing physicians' paperwork, with several studies and hospital deployments now showing measurable benefits rather than relying on anecdotal testimonials.
WashU Medicine and BJC Health reported in September 2026 that Abridge users initially reduced their documentation time by 8%. After 150 days, the reduction reached 15%, while after-hours documentation fell by 20%.
Ardent Health's experience with Ambience points in the same direction. Its reported savings of more than three hours per week would translate into more than 150 hours annually for a clinician working roughly 50 weeks, although individual results vary.
A randomized crossover study involving 160 outpatient clinicians, published in the Journal of the American Medical Informatics Association in 2026, also examined how competing ambient scribes affected documentation efficiency and burnout.
The results help explain why major healthcare systems keep investing in this category. But time savings aren't identical across physicians. Medical specialty, the quality of generated notes, required corrections, and the way software integrates with electronic records can all affect the result.
Is Viz.ai the strongest medical imaging AI startup?
Viz.ai is currently one of the most established independent clinical AI startups, and its hospital reach puts it ahead of many better-publicized generative AI companies.
In July 2026, Viz.ai reported reaching 2,000 U.S. hospitals, supporting networks serving an estimated 230 million people. Its products cover more than 50 AI-enabled clinical pathways across neurology, radiology, cardiology, oncology, pulmonology, and other specialties.
The company began with stroke detection and care coordination. Over its first decade, it expanded from identifying urgent conditions in medical images toward helping clinical teams decide what to do next. Viz.ai also cited more than 125 peer-reviewed publications associated with its technology and applications. Moving from spotting urgent findings to guiding the next step is progress we sort into working, being tested or still on paper in our healthcare AI market report.
An especially important development came in January 2026, when Viz.ai announced that its healthcare business had become profitable. It also said its life-sciences business had doubled over the preceding eighteen months.
Those are company-reported results, and the 230 million figure refers to the population served by its hospital network, rather than the number of patients directly treated using Viz.ai.
Even with that distinction, Viz.ai has something most young healthcare AI businesses are still trying to build: widespread deployment, a decade of clinical experience, and reported operating profitability.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the healthcare AI market, we look at what broke startups before you, so you don't repeat it.
Can Aidoc beat Viz.ai in medical imaging?
Aidoc is a serious challenger to Viz.ai in medical imaging, especially for hospitals that want to run multiple diagnostic algorithms across their radiology departments.
At University Hospitals, Aidoc reported that 13 active algorithms analyzed approximately 1.3 million scans annually across 13 hospitals and more than 50 ambulatory centers. Its 2026 case study estimated that these tools helped prioritize care for more than 12,000 patients and generated around 2,700 hours of efficiency improvements.
In August 2026, Aidoc announced a Diagnostic AI Consortium involving 12 U.S. health systems, including Cedars-Sinai, Mount Sinai, Houston Methodist, and Northwestern Medicine. Together, those organizations serve nearly 20 million patients annually.
Aidoc's clinical reach should not be confused with the total patient population of its partner hospitals. Still, the consortium gives it access to some of America's most sophisticated medical institutions.
The difference between the two companies is fairly clear. Viz.ai has a particularly strong position in disease detection followed by care coordination, while Aidoc concentrates heavily on imaging analysis and the infrastructure hospitals use to deploy diagnostic AI.
We would put Viz.ai ahead on publicly documented hospital penetration, with Aidoc among the strongest competitors for enterprise radiology AI contracts.
Is Hippocratic AI actually replacing human healthcare workers?
Hippocratic AI is already automating large numbers of patient conversations, but there isn't enough public evidence to conclude that it can safely replace nurses or other clinical professionals across their full responsibilities.
The company reported more than 115 million patient interactions in November 2025 and subsequently passed 250 million. Its voice agents handle activities such as patient follow-up, medication-related outreach, chronic-care engagement, and appointment coordination.
In August 2026, Hippocratic AI introduced more than 30 agent orchestrators designed to coordinate several AI agents around broader healthcare tasks. These include reducing readmissions, improving medication adherence, and reconnecting with patients who have missed follow-up care. Software calling patients instead of staff carries risks we rate by likelihood, subtle ones included, in our market report about healthcare AI.
The growth in interactions is substantial, and the move toward coordinated workflows suggests that hospitals are looking beyond individual automated phone calls. But interaction volume says little about revenue per conversation, task completion rates, or patient outcomes without additional data.
Hippocratic AI says its safety architecture has been validated by more than 7,700 licensed clinicians and reports zero incidents of patient harm. These remain company-reported claims rather than independent guarantees of safety.
For now, Hippocratic AI looks strongest where repetitive patient conversations can be automated under clinical supervision. The company has much more to prove before its agents can be treated as replacements for the wider work of healthcare professionals.

In our research about AI in healthcare, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is Heidi Health beating American AI scribe startups overseas?
Heidi Health is one of the clearest international success stories in healthcare AI, with reported medical scribe usage that rivals much larger U.S. enterprise platforms.
The company said its tools were supporting approximately 2.7 million consultations per week across 190 countries in mid-2026. At a constant weekly pace, that would amount to around 140 million consultations over a year, although it is an extrapolation rather than a verified annual total.
Heidi has benefited from offering accessible documentation tools directly to clinicians, alongside contracts and integrations with medical organizations. Its partnership with Canada's Accuro electronic medical record platform, used by more than 25,000 clinicians, is an example of how it can reach healthcare professionals through existing software.
Its approach differs from Abridge's emphasis on large U.S. health systems. Heidi can spread among individual doctors and smaller practices without waiting for a nationwide hospital group to approve deployment.
However, consultation counts are not paying-customer counts, and Heidi has not disclosed enough comparable revenue information to demonstrate that its business is larger than Abridge's.
Heidi is our strongest international adoption candidate, particularly outside the U.S. hospital enterprise market.
Which healthcare AI startups are winning in medical billing?
AKASA and Candid Health are two of the most interesting healthcare AI companies working on hospital billing and revenue-cycle automation, where errors and delays can have immediate financial consequences.
In October 2026, AKASA reported that its customers represented approximately 10% of U.S. inpatient discharges and more than $180 billion in combined annual net patient revenue. It also said its inpatient processing volume had increased almost sixfold over the preceding year.
That gives AKASA exposure to a remarkably large part of American hospital activity, although the figures describe its customers' operations rather than revenue earned by AKASA itself.
Candid Health offers a different approach, automating billing and claims processes for healthcare providers. After raising $120 million in July 2026, the company reported 190% year-over-year growth in annual contracted run-rate revenue and 180% net dollar retention for 2025.
A 180% retention rate means that an existing customer cohort increased its contracted spending by 80% after accounting for expansion and contraction. It's a strong sign that customers are buying more once they start using the platform, although the company has not disclosed enough financial detail to compare profitability.
Medical billing may attract less attention than AI diagnosis, but the economics are relatively straightforward. Hospitals can measure denied claims, processing times, administrative costs, and collected revenue. That gives companies such as AKASA and Candid a concrete way to demonstrate value.

If you build or invest in the healthcare AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Are healthcare AI startup valuations getting ridiculous?
OpenEvidence and Abridge are now valued at levels that leave little room for disappointing growth, even though both have built unusually successful healthcare AI businesses.
OpenEvidence's $15 billion valuation represents around 50 times Sacra's estimated $300 million annualized revenue. Abridge's $5.3 billion valuation in June 2025 was approximately 53 times Sacra's estimated $100 million annual recurring revenue the preceding month.
Those are enormous multiples by conventional enterprise software standards. They also refer to different periods and estimated financial metrics, so we should treat them as indicators of investor expectations rather than exact like-for-like comparisons. Multiples like these say a lot about investor expectations, and we follow what investors back and avoid in our report covering the healthcare AI market.
What's striking is how differently these businesses generate revenue. OpenEvidence monetizes physician attention through pharmaceutical advertising, while Abridge sells deeply integrated clinical software to healthcare organizations.
OpenEvidence's business could scale very profitably if it retains its physicians and advertising prices. Abridge could benefit from longer customer relationships and greater involvement in everyday hospital operations, although enterprise implementation is more demanding.
At these valuations, investors are already paying for substantial future growth. A slowdown in usage, weaker pricing, or a successful product from Microsoft, Epic, or OpenAI could change the investment case quickly.
| Company | Valuation benchmark | Available commercial evidence | Main valuation question |
|---|---|---|---|
| OpenEvidence | $15B, September 2026 | ~$300M estimated annualized revenue | Can advertising growth support a ~50x multiple? |
| Abridge | $5.3B, June 2025 | ~$100M estimated ARR in May 2025 | Can enterprise expansion justify a ~53x multiple? |
| Hippocratic AI | $3.5B, November 2025 | Large cumulative interaction volume | How much profitable revenue comes from each interaction? |
| Ambience Healthcare | $1.25B, July 2025 | Major enterprise customers and measurable time savings | Can it narrow Abridge's deployment lead? |
| Viz.ai | No verified comparable recent valuation | Broad hospital reach; healthcare business reportedly profitable | How fast can its profitable business keep growing? |
| AKASA | No verified comparable recent valuation | Customers cover a major share of U.S. hospital activity | How much revenue can it capture from automated workflows? |
| Heidi Health | No verified comparable recent valuation | Millions of weekly consultations | How efficiently can it convert usage into paid subscriptions? |
Can Microsoft, Epic, and OpenAI crush healthcare AI startups?
Microsoft, Epic, and OpenAI are becoming serious competitors for healthcare AI startups, especially in medical documentation and research, where their existing distribution gives them a considerable advantage.
Microsoft already sells Dragon and DAX products used for clinical documentation. Epic controls critical electronic health record workflows at large healthcare systems, while Oracle Health has an established hospital software presence. OpenAI has also moved directly into medical research and enterprise healthcare applications.
This puts particular pressure on standalone AI scribe companies. As models become cheaper and more accurate, generating a reasonable medical note becomes easier for competitors. Hospitals may increasingly prefer features already included in the software they use.
Abridge is responding by adding clinical decision support to its documentation platform. OpenEvidence is expanding into additional physician workflows, while Ambience has built capabilities around specialty documentation and medical coding.
Viz.ai and Aidoc face a somewhat different challenge. Their products involve regulated medical imaging, diagnostic workflows, and treatment coordination, where clinical validation and integration are harder to reproduce.
Generic AI documentation tools will probably face the toughest competition. The independent companies with the best chance of staying relevant are those deeply involved in clinical decisions, coding, or hospital operations.

In our document detailing everything you need to know about healthcare AI, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Do AI drug discovery companies belong among the top healthcare AI startups?
AI drug discovery deserves a place in the healthcare AI conversation, but its leading companies are difficult to compare with medical software startups because their success depends heavily on clinical trials.
Insilico Medicine provided one of the more important developments in September 2026 when it reported dosing the first patient in a Phase III trial of rentosertib, its AI-enabled investigational treatment for idiopathic pulmonary fibrosis.
The milestone followed Phase IIa results published in Nature Medicine. Moving a drug candidate into Phase III is meaningful, but the treatment still needs to demonstrate sufficient safety and effectiveness before regulatory approval.
Recursion Pharmaceuticals offers another example. In October 2026, the company reported a 47% median reduction in polyp burden after twelve weeks among an expanded adult cohort receiving REC-4881 for familial adenomatous polyposis.
Both Insilico Medicine and Recursion are publicly traded, so neither belongs in our strict private-startup ranking. Their progress remains useful when assessing whether AI can create valuable medicines rather than simply speed up existing research processes.
The reward could be enormous if an AI-discovered treatment succeeds commercially. However, drug candidates can fail after years of development, and the path to revenue is much longer than selling documentation software to hospitals.
We therefore treat drug discovery as a separate healthcare AI market, with clinical results carrying much more weight than user counts or recurring software revenue.
So, what are the top healthcare AI startups today?
OpenEvidence and Abridge are our top two private healthcare AI startups overall, while Viz.ai, Hippocratic AI, and Ambience Healthcare complete the leading group.
OpenEvidence currently has the most impressive commercial growth story. Its physician adoption and estimated revenue acceleration put it ahead of most specialist healthcare software companies, although its advertising model and high valuation create substantial expectations.
Abridge is our preferred enterprise clinical AI leader, with broad deployment in major healthcare systems and a growing role in clinical decision support. Its hospital integrations could become a lasting advantage as documentation software becomes more competitive.
Viz.ai deserves particular recognition for its maturity. A decade of development, extensive hospital adoption, and reported profitability in its healthcare division give it a stronger operating track record than several more highly valued startups.
Hippocratic AI leads the patient-facing agent category on reported interaction volume, while Ambience is establishing itself as a serious competitor in enterprise documentation and coding. Aidoc, AKASA, Candid Health, Heidi Health, and Nabla also deserve attention within their respective markets.
Our ranking favors OpenEvidence for commercial acceleration, Abridge for enterprise adoption, and Viz.ai for proven clinical deployment. If we had to choose one overall leader today, it would be OpenEvidence. But when we look at which businesses have built the deepest relationships with healthcare institutions, Abridge and Viz.ai make the competition much closer than a simple valuation ranking would suggest.
Our methodology
This analysis identifies the leading private healthcare AI startups by comparing commercial traction, medical adoption, clinical effectiveness, institutional deployment, competitive positioning, and financial momentum. We examine companies across medical research, clinical documentation, diagnostic imaging, patient-facing agents, and revenue-cycle automation, recognizing that each category requires different measures of success.
We give greater weight to demonstrated use in healthcare settings, repeat deployments, paying customers, and measured outcomes than to funding announcements or valuations alone. Where possible, we compare company disclosures with healthcare-provider results, clinical publications, and specialist financial research. We also distinguish direct product usage from broader figures such as the number of patients served by a hospital network.
Our financial comparisons separate disclosed funding valuations from estimated annualized revenue and ARR. We use Sacra's estimates for OpenEvidence and Abridge as commercial benchmarks, while acknowledging that third-party estimates are different from audited financial results. Similarly, company-reported patient interactions, consultation volumes, and hospital coverage are treated as adoption metrics rather than direct measures of revenue or clinical effectiveness.
For clinical documentation, we examine enterprise rollout and measured physician time savings. For medical imaging, we prioritize hospital deployment, clinical validation, and integration into care pathways. For patient-facing agents, we consider interaction volume alongside the limits of available safety and patient-outcome evidence. For billing automation, we focus on customer exposure, processing growth, contracted revenue expansion, and operational efficiency. Publicly traded companies are excluded from the main ranking but included where they provide useful competitive or clinical context.
We prioritized original announcements from healthcare providers and companies, peer-reviewed research, investor disclosures, and specialist financial analysis. Key sources include Sacra's OpenEvidence financial and adoption estimates, Sacra's competitive analysis of medical research AI, and OpenAI's announcement of ChatGPT for Clinicians.
For enterprise deployment and documentation efficiency, we used Abridge's platform adoption disclosure, its VA enterprise contract announcement, the WashU Medicine and BJC Health expansion results, Abridge's clinical intelligence update, Ardent Health's Ambience deployment results, and Cleveland Clinic's account of its ambient AI evaluation.
For diagnostic imaging and clinical scale, important sources include Viz.ai's hospital deployment figures, its financial and operational update, and Aidoc's Diagnostic AI Consortium announcement.
For patient-facing agents, international adoption, and hospital automation, we consulted Hippocratic AI's published deployment and safety claims, Heidi Health's consultation figures, AKASA's hospital automation disclosures, and Sixth Street's Candid Health financing announcement.
For AI drug discovery, we used Insilico Medicine's Phase III trial announcement and the Phase IIa rentosertib study published in Nature Medicine. These sources help distinguish commercial healthcare software adoption from pharmaceutical development, where clinical trial results and regulatory progress are more relevant measures of success.
The final ranking combines these different forms of evidence rather than applying a single financial or usage metric to every company. We favor startups showing progress across several dimensions, while keeping company-reported metrics, independent research, and financial estimates separate when assessing their strength.

In our report covering the healthcare AI market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us