Procurement software: what’s funding like now?
Whether you're building or investing in the procurement software market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Procurement software funding has dipped in dollars and weakened more in breadth. We tracked 42 deals worth at least $596M over the last 12 months, led by ORO Labs and its $100M Series C in March 2026. The headline total is 8% below the $652M+ of the preceding 12 months, while the number of deals fell 18%.
The difference is the size of the checks. 3 rounds above $50M raised $245M in the latest period, against $109M+ from 2 such rounds before. Money became more concentrated while the median round stayed close to $6.5M.
Removing rounds above $50M changes the verdict. The remaining deals raised $351M+, compared with $543M+ in the 12 months before. We therefore do not read the modest headline dip as a sign of resilience.
Fewer separate startups secured funding. A large expansion check tells us little about how easily a first-time founder can find backing.
First financings lost ground while follow-ons captured a larger share of disclosed capital. The market still creates funded companies, but subsequent rounds now explain far more of the money changing hands.
Procurement intake and orchestration has become the clearest beneficiary. ORO Labs, Lio, Didero and Magentic are selling different ways to move purchasing work from forms and emails into software that can coordinate and execute tasks.
Strategic sourcing tells a less comfortable story. It remained active by deal count, but the money attached to the category dropped sharply after the previous period's larger checks.
Investors are also looking beyond office purchasing. Freehand's spend automation, Fragment's exception handling and SPARETECH's spare-parts data address work that keeps factories and supply chains running.
Geography narrowed. The United States still gets the most deals and dollars, while Europe's deal share fell and Saudi procurement marketplaces continued to attract identifiable investment.
Procurement software can still support large funding rounds, but the market is not hotter for most startups. Newcomers face fewer transactions, fewer active leads and weaker first-round activity.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the procurement software market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the procurement software market over the last 24 months
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our procurement software market report.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| SPARETECH | Spend Intelligence & Controls | November 2026 | Series B | $20M | Enterprise MRO software identifies spare-part suppliers and alternative sources while optimizing parts spend and inventories. | Europe | Blume Equity, Insight Partners | Germany | |
| Atmospheric AI | Strategic Sourcing | November 2026 | Seed | $10M | AI models raw-material production chains to inform supplier cost, supply risk and sourcing decisions. | Europe | DBL Partners | United Kingdom | |
| Kodiact | Strategic Sourcing | November 2026 | Seed | $2.5M | Simulation and AI sourcing platform helps manufacturers optimize raw-material procurement decisions. | North America | Supply Change Capital | United States | |
| SpendRule | Spend Intelligence & Controls | October 2026 | Seed | $4M | Contract compliance software for healthcare spending | North America | Radical Investments | United States | |
| Opply | Strategic Sourcing | October 2026 | Unknown | $7.5M | CPG sourcing and procurement automation | Europe | Chalfen Ventures | United Kingdom | |
| Syncmeon | Procurement Marketplaces | October 2026 | Seed | $600K | AI-powered B2B procurement marketplace that helps small businesses find suppliers and automate purchasing. | North America | Not disclosed | United States | |
| Elevatry | Strategic Sourcing | October 2026 | Seed | ~$3.5M | AI strategic procurement software | Europe | Not disclosed | Germany | |
| Finches | Supplier Management & Risk | October 2026 | Seed | $2.2M | Agricultural sourcing risk intelligence software | Europe | High-Tech Gründerfonds, Vanagon Ventures | Germany | |
| Bloom | Procurement Marketplaces | October 2026 | Seed | $3.6M | Software matching manufacturing buyers with suppliers | North America | SNAK Venture Partners | United States | |
| Project Suppliers | Procurement Marketplaces | October 2026 | Seed | $1M | Industrial supplier discovery and procurement marketplace | Middle East | Not disclosed | Saudi Arabia | |
| Axya | Procure-to-Pay | September 2026 | Series A | ~$8.8M | Procurement execution software for manufacturers | North America | McRock Capital | Canada | |
| Magentic | Procurement Intake & Orchestration | September 2026 | Series A | $18M | AI agents for procurement teams | Europe | Felicis | United Kingdom | |
| BRKZ | Procurement Marketplaces | September 2026 | Series B | $13M | Construction materials procurement marketplace | Middle East | Wa’ed Ventures, 500 Global | Saudi Arabia | |
| Aron | Strategic Sourcing | September 2026 | Seed | $6M | AI procurement negotiation and sourcing assistant | North America | Storm Ventures | United States | |
| Fitting | Procurement Marketplaces | August 2026 | Seed | $1.1M | Construction materials procurement marketplace | Middle East | Not disclosed | Saudi Arabia | |
| Freehand | Spend Intelligence & Controls | July 2026 | Series B | $75M | AI invoice auditing and spend management | North America | Battery Ventures, NewRoad Capital Partners | United States | |
| Prolo | Strategic Sourcing | July 2026 | Seed | $5.4M | AI procurement and supplier sourcing software | Europe | Triple Point Ventures | United Kingdom | |
| compri | Procurement Intake & Orchestration | June 2026 | Seed | ~$3.7M | AI procurement automation software | Europe | Picus Capital | Italy | |
| SubBase | Procure-to-Pay | June 2026 | Series A | $7M | Construction procurement management software | North America | FINTOP | United States | |
| Soource | Strategic Sourcing | June 2026 | Seed | $3.3M | AI procurement and supplier automation | Europe | Vertis | Italy | |
| givvable | Supplier Management & Risk | June 2026 | Unknown | $1.1M | Supplier sustainability and procurement intelligence | Asia-Pacific | Not disclosed | Australia | |
| Definic | Supplier Management & Risk | June 2026 | Seed | $2.8M | Vendor intelligence for IT procurement teams | Europe | J&T Ventures | Slovakia | |
| Pivot | Procurement Intake & Orchestration | May 2026 | Series B | $40M | Procurement intake and spend management software | Europe | Forestay Capital, Notion Capital | France | |
| ProcurePro | Strategic Sourcing | May 2026 | Series B | $11M | Construction procurement and contract management software | Asia-Pacific | QIC Ventures | Australia | |
| TradeForm | Strategic Sourcing | April 2026 | Seed | $2M | AI procurement agents for direct materials | North America | Foundation Capital | United States | |
| Traza | Procurement Intake & Orchestration | April 2026 | Seed | $2.1M | AI agents for procurement operations | North America | Base10 Partners | United States | |
| Mandel AI | Procurement Intake & Orchestration | March 2026 | Seed | $3.9M | AI sourcing and ordering coordination platform | North America | Not disclosed | United States | |
| Aerchain | Procurement Intake & Orchestration | March 2026 | Series A | $13M | AI sourcing and procurement software | Asia-Pacific | Pavestone VC | India | |
| Candex | Procure-to-Pay | March 2026 | Series C | $7M+ | Tail-spend supplier payment and procurement platform | North America | HSBC | United States | |
| ORO Labs | Procurement Intake & Orchestration | March 2026 | Series C | $100M | Enterprise procurement requests approvals and supplier workflows | North America | Brighton Park Capital, Goldman Sachs Alternatives | United States | |
| SkySelect | Strategic Sourcing | March 2026 | Unknown | $9M | Aircraft parts procurement automation software | North America | Verb Ventures, RockCreek | United States | |
| Lio | Procurement Intake & Orchestration | March 2026 | Series A | $30M | AI agents for enterprise procurement | North America | Andreessen Horowitz | United States | |
| Eezee | Procurement Marketplaces | February 2026 | Unknown | $5M | B2B marketplace for industrial procurement | Asia-Pacific | Korea Investment Partners Southeast Asia | Singapore | |
| SpendRule | Spend Intelligence & Controls | February 2026 | Seed | $2M | Contract compliance software for healthcare spending | North America | Abundant Venture Partners | United States | |
| Didero | Procurement Intake & Orchestration | February 2026 | Series A | $30M | AI procurement agents for manufacturers | North America | Chemistry, Headline | United States | |
| Naboo | Services Procurement | February 2026 | Series B | $70M | Corporate event venue sourcing and procurement | Europe | Lightspeed Venture Partners | France | |
| SiFi | Spend Intelligence & Controls | February 2026 | Series A | $20M | Procurement and spend management software | Middle East | Ra'ed Ventures | Saudi Arabia | |
| 1Buy.AI | Strategic Sourcing | January 2026 | Seed | $3.9M | Electronics procurement intelligence and sourcing software | Asia-Pacific | 100Unicorns | India | |
| Interos | Supplier Management & Risk | January 2026 | Unknown | $20M | Supply chain risk intelligence software | North America | Blue Owl Capital | United States | |
| Monq | Procurement Intake & Orchestration | November 2025 | Seed | $3M | AI procurement workflow software | Europe | Outward VC | United Kingdom | |
| Zinit | Strategic Sourcing | November 2025 | Seed | $8M | AI procurement sourcing and bidding platform | Middle East | AltaIR Capital | United Arab Emirates | |
| Coverbase | Supplier Management & Risk | November 2025 | Series A | $17M | Third-party risk management software | North America | Canapi Ventures | United States | |
| Procure Ai | Procurement Intake & Orchestration | November 2025 | Seed | $13M | AI procurement automation software | Europe | Headline | United Kingdom | |
| Belidor | Strategic Sourcing | October 2025 | Seed | $3.1M | Procurement automation and sourcing software | North America | Not disclosed | United States | |
| Green Cabbage | Spend Intelligence & Controls | October 2025 | Series B | $40M | Procurement intelligence and cost benchmarking | North America | Sageview Capital | United States | |
| Resourcly | Spend Intelligence & Controls | October 2025 | Seed | $3M | AI procurement and supplier management software | Europe | Project A | Germany | |
| Gain | Procurement Intake & Orchestration | September 2025 | Seed | $12M | AI employees for procurement teams | Middle East | The Garage | Israel | |
| Beroe | Spend Intelligence & Controls | September 2025 | Growth Equity | $34M | Procurement intelligence and supplier research software | North America | Relativity Resilience Fund, Mukul Agrawal, Ashish Kacholia, Lashit Sanghvi, Alchemy Long Term Ventures Fund | United States | |
| sun.store | Procurement Marketplaces | September 2025 | Seed | $6.6M | B2B marketplace for solar equipment | Europe | Contrarian Ventures, Market One Capital, Movens Capital | Poland | |
| Omnea | Procurement Intake & Orchestration | September 2025 | Series B | $50M | Procurement requests and supplier management software | Europe | Insight Partners, Khosla Ventures | United Kingdom | |
| Fitting | Procurement Marketplaces | September 2025 | Seed | $500K | Construction materials procurement marketplace | Middle East | Not disclosed | Saudi Arabia | |
| Infinity Loop | Strategic Sourcing | August 2025 | Seed | $5M | Procurement negotiation intelligence software | North America | Glasswing Ventures, TIAA Ventures | United States | |
| Kunzapp | Spend Intelligence & Controls | August 2025 | Seed | $2M | Procurement analytics and supplier management software | Latin America | Wollef | Mexico | |
| Magentic | Procurement Intake & Orchestration | July 2025 | Seed | $5.5M | AI agents for procurement teams | Europe | Sequoia Capital | United Kingdom | |
| Cienty | Procurement Marketplaces | July 2025 | Seed | $2.7M | Procurement marketplace for independent pharmacies | Latin America | Astella | Brazil | |
| Candex | Procure-to-Pay | July 2025 | Series C | $33M | Tail-spend supplier payment and procurement platform | North America | 9Yards Capital | United States | |
| Levelpath | Procurement Intake & Orchestration | June 2025 | Series B | $55M+ | Procurement intake and purchasing workflow software | North America | Battery Ventures | United States | |
| Delfio | Procure-to-Pay | June 2025 | Seed | $1.7M | AI procurement software for industrial purchasing | Europe | Peak | Netherlands | |
| Mercanis | Strategic Sourcing | June 2025 | Series A | $20M+ | Procurement sourcing and supplier management software | Europe | Partech, AVP | Germany | |
| Nvelop | Strategic Sourcing | June 2025 | Seed | $1.3M | AI sourcing and procurement automation | Europe | Failup Ventures | Finland | |
| Remarcable | Procure-to-Pay | June 2025 | Series A | $15M | Procurement and materials software for contractors | North America | Insight Partners | United States | |
| Pactum AI | Strategic Sourcing | June 2025 | Series C | $54M | AI agents for supplier negotiations | North America | Insight Partners | United States | |
| Spendflo | Spend Intelligence & Controls | June 2025 | Unknown | Undisclosed | SaaS purchase procurement and spend management | North America | Not disclosed | United States | |
| Speya | Supplier Management & Risk | May 2025 | Seed | $1.2M | Supplier intelligence for industrial procurement | Europe | Not disclosed | Sweden | |
| Arkestro | Strategic Sourcing | May 2025 | Series B | $36M | Predictive procurement and sourcing software | North America | Altira Group, Aramco Ventures | United States | |
| Scalera | Strategic Sourcing | May 2025 | Seed | ~$6.5M | AI procurement platform for construction firms | Europe | firstminute capital, Speedinvest | Switzerland | |
| Predikt | Spend Intelligence & Controls | May 2025 | Seed | $1.4M | AI procurement and supplier intelligence software | Europe | Not disclosed | Belgium | |
| Field Materials | Procure-to-Pay | April 2025 | Series A | $11M | Construction procurement and materials software | North America | Navitas Capital | United States | |
| MatBook | Procure-to-Pay | April 2025 | Seed | $750K | Construction materials procurement and logistics software | North America | Seedstars International Ventures, Fluent Ventures, Everywhere Ventures | United States | |
| Vallor | Supplier Management & Risk | April 2025 | Seed | $4M | AI procurement workflows and supplier sourcing | North America | Dynamo Ventures, Bloomberg Beta | United States | |
| LightSource | Strategic Sourcing | March 2025 | Series A | Undisclosed | Direct-materials sourcing and procurement software | North America | Lightspeed Venture Partners, Bain Capital Ventures | United States | |
| BuildVision | Strategic Sourcing | March 2025 | Series A | $10M | Procurement software for construction materials | North America | Norwest | United States | |
| compri | Procurement Intake & Orchestration | March 2025 | Seed | ~$1.7M | AI procurement automation software | Europe | Italian Founders Fund, DFF Ventures | Italy | |
| Shoppable Business | Procurement Marketplaces | March 2025 | Seed | $1.2M | B2B procurement marketplace for business supplies | Asia-Pacific | Ignite House of Innovation | Philippines | |
| TimeFlow | Services Procurement | February 2025 | Unknown | $4.4M | IT vendor management and procurement software | Europe | Vertis, Azimut | Italy | |
| BRKZ | Procurement Marketplaces | February 2025 | Series A | $8M | Construction materials procurement marketplace | Middle East | 9900, BECO Capital | Saudi Arabia | |
| comstruct | Procure-to-Pay | February 2025 | Series A | $14M | Construction procurement software | Europe | GV, 20VC | Germany | |
| Response | Spend Intelligence & Controls | February 2025 | Seed | $4M | Procurement intake and vendor management software | North America | Not disclosed | United States | |
| Crown | Strategic Sourcing | February 2025 | Seed | $2.2M | Procurement e-auction software | Europe | Heartfelt | France | |
| Naboo | Services Procurement | January 2025 | Series A | $22M | Corporate event venue sourcing and procurement | Europe | Notion Capital | France | |
| Vertice | Spend Intelligence & Controls | January 2025 | Series C | $50M | Procurement and SaaS spending management software | Europe | Lakestar | United Kingdom | |
| Matchory | Strategic Sourcing | January 2025 | Seed | $6.6M | Supplier data and matching software | Europe | Capmont | Germany | |
| Soource | Strategic Sourcing | January 2025 | Seed | $1.7M | AI procurement and supplier automation | Europe | 360 Capital | Italy | |
| ProcureYard | Procurement Marketplaces | January 2025 | Seed | $1.7M | Construction materials procurement and supplier platform | Asia-Pacific | Powerhouse Ventures | India | |
| Reeco | Procure-to-Pay | January 2025 | Series A | $15M | Hotel procurement and inventory software | North America | Aleph | United States | |
| Labviva | Procurement Marketplaces | January 2025 | Series B | $25M | Life sciences procurement marketplace and software | North America | 53 Stations | United States | |
| BRM | Supplier Management & Risk | December 2024 | Series A | $15M | AI procurement and vendor management software | North America | Caffeinated Capital | United States | |
| BRM | Supplier Management & Risk | December 2024 | Seed | $6.6M | AI procurement and vendor management software | North America | Base10 Partners | United States | |
| Pegbo | Supplier Management & Risk | November 2024 | Seed | $1.4M+ | Construction procurement and supplier management software | North America | Nirman Ventures | United States | |
| Freqens | Spend Intelligence & Controls | November 2024 | Seed | $3M | Agentic planning software for finance teams | Europe | Not disclosed | France | |
| Kodiak Hub | Supplier Management & Risk | November 2024 | Series B | $6.6M | Supplier relationship and procurement management software | Europe | Oxx | Sweden | |
| Lightyear | Strategic Sourcing | November 2024 | Series B | $31M | Telecom procurement and network inventory software | North America | Altos Ventures | United States | |
| Civic Marketplace | Procurement Marketplaces | November 2024 | Seed | $3.2M | Marketplace for government procurement and vendors | North America | Kindred Capital | United States |

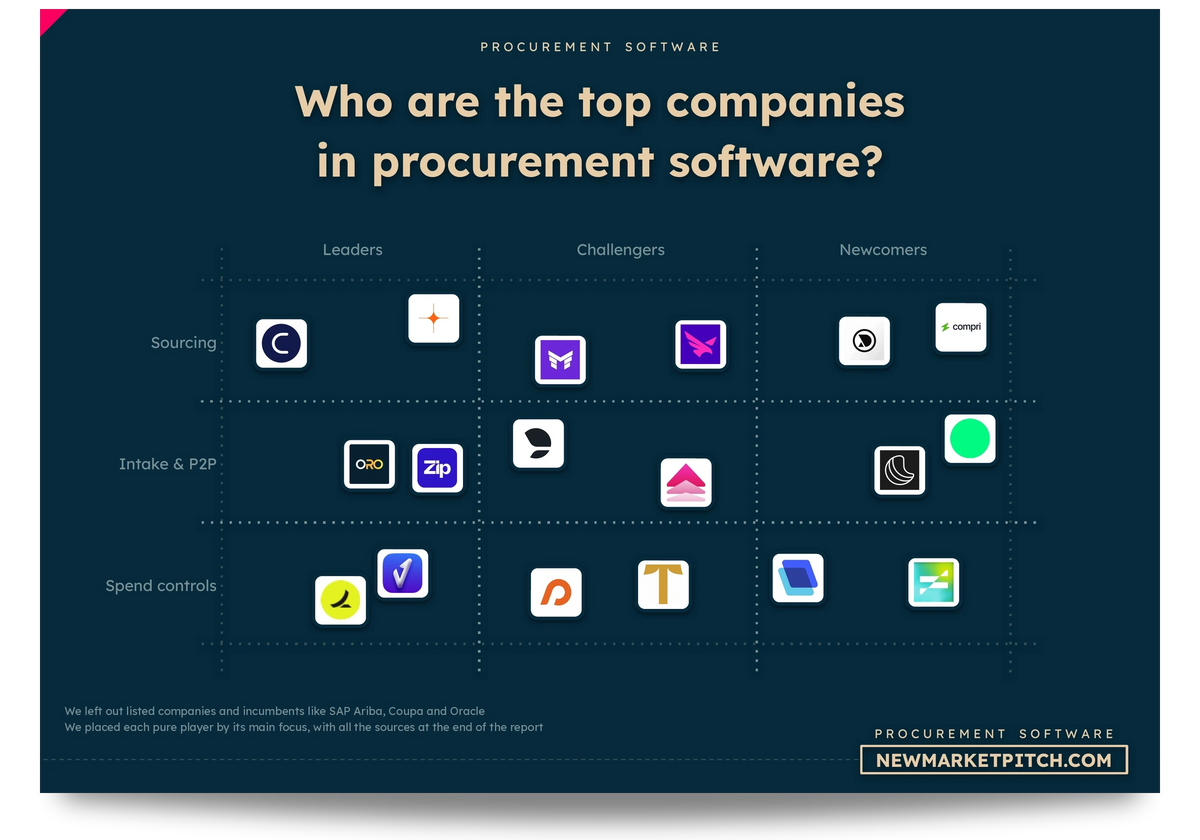
In our research about procurement software startups, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is procurement software funding actually healthy right now?
Procurement software is getting funded, but the latest 12 months do not show a healthier market across the board.
Our count found 42 deals involving 41 companies and at least $596M in capital. The 12 months before recorded 51 deals among 50 companies and at least $652M. Deals and funded companies both fell 18%, while the disclosed total fell 8%. So investors did not abandon the sector, but fewer startups managed to raise.
The contrast becomes clearer in the underlying transactions. Freehand raised a $75M Series B in July 2026 for supply-chain spend automation; Naboo raised a $70M Series B in February 2026 for corporate-event purchasing; and Pivot raised a $40M Series B in May 2026 for purchasing controls. Selected vendors can still raise serious money. These deals tell us much less about the prospects for a small newcomer.
ORO's March announcement reported 300% revenue growth and named Novartis, Roche, Coca-Cola and Siemens Energy among customers. Big enterprises already use ORO Labs, which helps explain its ability to raise a large round. A newcomer without those customers faces a different test.
Are investors writing bigger procurement software checks to fewer startups?
Only at the top. Fewer companies attracted financing and the largest checks grew, but the typical procurement software round did not get bigger.
The median round slipped 2%, to $6.5M from $6.6M. At the company level, the median amount raised in the period was $7M, against $6.5M previously. The middle of the market is roughly flat.
It sits beside a very different result at the top. The latest period had 3 rounds above $50M, compared with 2 previously. ORO Labs, Freehand and Naboo completed the current group of large financings. Levelpath's $55M+ Series B in June 2025 and Pactum AI's $54M Series C that month carried the earlier comparison.
These firms tackle different spending problems. Freehand's July announcement named Meta, Unilever and Pfizer among customers using its agents; Levelpath's June 2025 announcement described agents built into procurement intake; Pactum AI's announcement described automated supplier negotiations. Investors can support several distinct products while still concentrating their checks in the more established or ambitious financings. A founder can see bigger funding headlines while finding fewer investors willing to write a first check.
Would procurement software funding still look strong without giant rounds?
No. Remove rounds above $50M and procurement software financing is materially weaker than in the preceding 12 months.
Excluding those larger transactions, the latest 12 months generated $351M+ in funding, down 35% from $543M+ in the 12 months before. The 3 qualifying large rounds supplied $245M in the latest period, versus $109M+ from 2 such rounds before it. The headline minimum fell only 8%, to $596M+ from $652M+, because the bigger deals offset much of the reduced flow elsewhere.
There is an important threshold distinction. No deal exceeded $100M in either period, so excluding rounds above $100M leaves the published period totals unchanged. ORO Labs' $100M Series C in March 2026 sits at that boundary, rather than above it. Investors have not produced an endless succession of ever-larger rounds; a small group of sizable financings is doing more of the work.
The companies help explain the concentration. Naboo's February announcement described a corporate-event procurement platform with contracts across major enterprise accounts. Freehand's July announcement described AI agents managing supply-chain spend for Fortune 500 companies. Both promise relatively direct financial benefits to large customers. Their products explain why those companies appealed to investors. They cannot make the missing smaller transactions disappear.
The table below shows the headline market measures under the same two-period definition.
| Measure | Last 12 months | Prior 12 months |
|---|---|---|
| Deals | 42 | 51 |
| Funded companies | 41 | 50 |
| Capital raised | $596M+ | $652M+ |
| Excluding above $50M | $351M+ | $543M+ |
| Above-$50M rounds | 3 | 2 |
| Median round | $6.5M | $6.6M |
| Unique investors | 63 | 88 |
| Unique lead investors | 44 | 61 |
“+” means at least: some disclosed rounds were published as minimum amounts. Medians are rounded; exact values are given in the text.
Are smaller procurement software startups still getting meaningful funding?
Yes, but smaller procurement software checks are no longer creating enough activity to offset the loss of deals.
In the last 12 months, 18 rounds under $5M raised $46M, while 15 rounds from $5M to under $20M raised $145M+. In the preceding 12 months, those bands held 21 deals totaling $46M+ and 16 deals totaling $156M. The smallest funding band still exists, but fewer transactions are clearing it.
The commercial cases vary. Kodiact's $2.5M Seed in November 2026 targets sourcing simulation, Traza's $2.1M Seed in April 2026 focuses on procurement operations, and Definic's $2.8M Seed in June 2026 works on IT vendor intelligence. None is trying to replace a global ERP suite immediately. They seek a smaller, identifiable workflow where buyers can test the product.
Evidence from actual procurement customers makes that approach plausible. In its September 2025 case study, LightSource said Time Manufacturing used its direct-sourcing platform to achieve over $5M in awarded savings. That result comes from the vendor, so we cannot treat it as an independently verified gain for new startups. Even so, the cases show why a narrow purchasing problem can attract a backer when fewer small rounds are closing.

In our market report about procurement software startups, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Can new procurement software startups still raise a first round?
Yes, but first-time procurement software financings have become noticeably less common and smaller in aggregate.
We found 12 first financings worth $37M in the last 12 months, compared with 18 worth $83M+ in the 12 months before. First rounds accounted for 29% of recent deals, down from 35%, and just 6% of disclosed capital, versus 13% previously. The decline is meaningful because it appears in both the number of entrants and the money reaching them.
Recent first-round cases include TradeForm's $2M Seed in April 2026, Prolo's $5.4M Seed in July 2026 and Project Suppliers' $1M Seed in October 2026. Their products address industrial materials, supplier discovery and organizational purchasing rather than general-purpose consumer marketplaces. In the earlier period, Procure Ai's $13M Seed in November 2025 offered a different scale of initial backing. Its company announcement described buyers such as EnBW and Kärcher and positioned agents as a way to handle sourcing volume without adding staff.
We classify first financing from the funding histories we can establish; this is a directional check, not a definitive census of founders raising their first external dollar. Even with that limitation, fewer first rounds alongside stable aggregate capital means newcomers did not participate evenly in the headline resilience.
Are existing procurement software startups taking most of the money?
Yes. Follow-on procurement software rounds account for the overwhelming majority of disclosed funding in the latest 12 months.
The period contains 19 follow-on deals worth at least $440M, representing 45% of all deals and 74% of disclosed capital. The previous period recorded 21 follow-ons worth $459M+, or 41% of deals and 70% of disclosed money. For 11 recent deals, the funding history does not show whether the company had raised before, so these shares are minimums. Follow-on activity did not increase in deal count. It became more dominant because other financing activity contracted.
The types of customers behind those rounds matter. ORO Labs already connected enterprise purchasing requests with approval and supplier workflows when it raised in March 2026. Pivot's $40M Series B in May 2026 came with a company claim that its platform processed $3 billion in invoices annually. SPARETECH's $20M Series B in November 2026 came with named industrial users including Nestlé, Porsche and Bosch.
ORO Labs, Pivot and SPARETECH can point to customers and real purchasing activity. That gives investors something concrete to assess before writing another check. We cannot tell which revenue targets individual funds required, but follow-on rounds took a larger share of the money as first financings fell.
Repeated rounds within the same period are unusual. We counted 41 companies across 42 recent deals, and only 1 company completed multiple recorded financings in the window. SpendRule, for example, raised a $2M Seed in February 2026 and a $4M Seed in October 2026. Most follow-on recipients had raised their previous capital before the comparison period.
Are procurement software startups raising their next round faster?
No. The available procurement software funding histories point to slower repeat fundraising, not acceleration.
Among the gaps between financing rounds for which we could establish timing, the median was 21 months in the latest period, compared with 20.5 months before. The share of such gaps shorter than 24 months declined from 77% to 53%; the share shorter than 12 months moved from 23% to 16%. The measure covers 45% of eligible round gaps in the latest period and 51% in the earlier one, so it cannot represent every startup's fundraising rhythm.
Naboo shows why individual stories can diverge from the aggregate. Its $70M Series B in February 2026 came about a year after its Series A of January 2025. Magentic similarly progressed from a $5.5M Seed in July 2025 to an $18M Series A in September 2026. Such fast progressions are visible, but they should not be mistaken for the normal pace across every company.
Some founders may be choosing to wait; others may be struggling to raise. Deal histories cannot separate those explanations. They do show that procurement startups are not returning for funding faster as a group.

Our document detailing everything you need to know about procurement software gets updated several times a month, so you always get the latest view of where things stand.
Is AI doing all the work in procurement software fundraising?
AI is central to several prominent procurement software financings, but it is not the whole market and cannot explain every check.
ORO Labs builds orchestration agents, Lio automates purchasing work, Didero handles supplier communication for manufacturers, and Magentic addresses fragmented procurement data. Each firm automates a different task, so describing them as interchangeable AI apps misses the buyer problem. The companies' 2026 announcements show that autonomous procurement is not one single product category.
More specialized software also won backing. BRKZ's $13M Series B in September 2026 addressed construction-material purchasing and supplier access. ProcurePro's $11M Series B in May 2026 focused on procurement control for contractors. SPARETECH's November financing supported industrial spare-parts data and inventory management. AI appears in many of these product announcements, but the work is tied to purchasing needs that existed before generative models.
These businesses sell different procurement functions, and a company mentioning AI does not make it a separate market. Investors are backing tools that can do work employees previously handled through emails and spreadsheets. To keep customers, those tools must work reliably inside existing systems.
Why are procurement orchestration companies attracting such large rounds?
Procurement intake and orchestration is attracting large rounds because it sits at the point where employees, approvals and existing purchasing systems meet.
The category recorded 10 deals raising $244M in the latest 12 months, up from 6 deals and $137M+ previously. Its share of disclosed capital rose from 21% to 41%. ORO Labs contributed the category's leading transaction, while Lio, Didero and Magentic show that several competing automation approaches attracted investment.
Company announcements show why buyers want these tools. ORO's March announcement described moving procurement work across finance, legal and supply-chain functions while keeping existing enterprise systems in place. Omnea's September 2025 Series B announcement explained how requests, vendor reviews and third-party risk often live in separate tools; it named Spotify and Wise among customers. Zip's March 2026 product discussion described purchase requests starting in email and approvals moving through chat before the ERP is updated.
These companies want their software to coordinate the steps between requesting, approving and paying for a purchase. That job can support a bigger enterprise contract than a standalone dashboard. The financing data cannot tell us which vendor will win those customers.
Has procurement software's strategic sourcing boom faded?
In capital terms, yes. Strategic sourcing remains active in procurement software, but investors wrote far fewer dollars into it than before.
Strategic sourcing generated 12 deals and $72M in the last 12 months, compared with 13 deals and $177M+ in the preceding period. Its deal share actually rose from 25% to 29%, while its share of disclosed capital fell from 27% to 12%. Businesses still raise for supplier search and negotiation, but the big sourcing checks have become rarer.
The prior period included Pactum AI's $54M Series C in June 2025, a sizeable investment in automated supplier negotiation. Pactum said its platform handled more purchasing spend, grew recurring revenue and added corporate clients including Honeywell and Tetra Pak. The latest period instead includes Atmospheric AI's $10M Seed in November 2026, Aron's $6M Seed in September 2026 and 1Buy.AI's $3.9M Seed in January 2026. Each addresses an identifiable sourcing task, but none approaches the size of Pactum's earlier round.
Sourcing software has not disappeared from manufacturing. In September 2025, LightSource published a customer case study describing more than $5M in awarded savings for Time Manufacturing. That commercial evidence helps explain continued attention. The funding pattern, however, is clear: strategic sourcing kept a pipeline of deals but lost its earlier concentration of large checks.

In our report covering the procurement software market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Are spend intelligence and purchasing controls falling out of favor?
Spend-intelligence startups have lost deal breadth, but they can still attract substantial procurement software capital.
Spend intelligence and controls recorded 5 deals raising $121M in the latest 12 months, after 9 deals and $137M+ in the preceding period. Deal share declined from 18% to 12%, yet the category still supplied 20% of recently disclosed capital. Freehand's $75M Series B in July 2026 carries much of that dollar result. SiFi's $20M Series A in February 2026 and SPARETECH's $20M Series B in November 2026 show the category is not a one-product story.
The previous period included Vertice's $50M Series C in January 2025 and Green Cabbage's $40M Series B in October 2025. Vertice argued in its January announcement that procurement teams needed better pricing benchmarks, purchasing controls and integrated workflow software. In a 2026 customer account, Vertice described Arm obtaining savings from better oversight of technology purchases. SPARETECH meanwhile reported industrial customers using its parts data to manage inventory across multiple facilities.
These are very different budgets: software subscriptions, supply-chain spend and maintenance stock. The lower number of recent deals is a real warning about funding breadth, but the ability to attract large checks persists for companies that can make a purchasing cost or operational problem measurable.
Are procurement marketplaces being left behind by investors?
Procurement marketplaces are raising less money than before, although investors have not deserted them.
The latest 12 months produced 8 marketplace deals totaling $39M, compared with 11 deals and $82M in the previous period. Marketplace share of all deals declined from 22% to 19%, and its share of disclosed capital went from 13% to 6%. This is a weaker outcome on both activity and funding, not merely the absence of one giant round.
BRKZ's $13M Series B in September 2026 backed an AI-enabled marketplace for construction materials in Saudi Arabia. Its announcement separates that equity round from an additional debt commitment, a distinction that matters when comparing venture investment. SkySelect's $9M round of undisclosed stage in March 2026 addressed aircraft-parts purchasing, while Prolo's $5.4M Seed in July 2026 targeted organizational supplier discovery. Each is much more specialized than a generic online wholesaler.
Companies buying aircraft parts, construction materials or specialist supplies need accurate catalogs and dependable quotations. That gives industry-focused marketplaces a reason to exist. We cannot see how much buyers spend through these platforms, but we can see that fewer marketplace financings closed for less money.
The table below shows how procurement software funding shifted across its business categories, ordered by capital in the latest period. Procure-to-Pay's $23M+ is a reported minimum.
| Category | Recent deals | Recent capital | Prior capital |
|---|---|---|---|
| Procurement Intake & Orchestration | 8 | $201M | $137M+ |
| Spend Intelligence & Controls | 5 | $121M | $137M+ |
| Procure-to-Pay | 5 | $70M+ | $87M |
| Services Procurement | 1 | $70M | $28M+ |
| Strategic Sourcing | 11 | $56M | $148M+ |
| Supplier Management & Risk | 4 | $40M | $32M |
| Procurement Marketplaces | 8 | $39M | $82M |
“+” indicates a reported minimum; capital shares use only rounds with public amounts.
Is procurement software moving beyond office purchasing?
Yes. Investors are financing procurement software that handles physical materials, industrial operations and specialized services, not just employee software requests.
Fragment, whose October 2026 announcement covered its cumulative seed and Series A funding, focuses on resolving order, delivery and invoice exceptions in direct procurement. Freehand addresses supply-chain spend with AI agents, while Didero handles supplier communications, purchase orders and exception management for manufacturers. These products live close to the operations that keep factories supplied.
Other deals broaden the picture. ProcurePro raised an $11M Series B in May 2026 for construction procurement controls, BRKZ raised a $13M Series B in September 2026 for construction-material purchasing, and SPARETECH raised a $20M Series B in November 2026 for maintenance spares. These tools help contractors and manufacturers avoid project delays, missing parts and unresolved supplier paperwork.
The companies' own disclosures provide operational context. Didero described agents working in existing email and ERP systems. ProcurePro's May release described contractor workflows from comparing suppliers to approving contracts. SPARETECH's November release cited a rollout across Nestlé's industrial sites. These are factory and contractor problems, backed by customer deployments rather than AI product descriptions alone.
Is procurement software funding becoming more concentrated in the U.S.?
The United States still dominates procurement software financing, but its share of recent deals has not suddenly surged.
American startups accounted for 18 deals and at least $321M in the last 12 months, compared with 23 deals and at least $402M in the prior period. Their share of deals moved from 45% to 43%, while they still captured 54% of recently disclosed capital. At the regional level, North America held 19 deals and $330M+ versus 23 deals and $402M+ previously.
ORO Labs and Freehand are U.S.-headquartered procurement software vendors selling to enterprises with complex international supplier operations. Their products illustrate why headquarter location need not match the geography of the purchasing problems they solve. The concentration of large enterprise-software rounds is a dollar story more than an increased American deal-share story.
The broader market nevertheless reached fewer places. We observed 12 headquarters countries in the latest 12 months, versus 17 in the preceding period. A startup headquartered in a smaller procurement ecosystem may still sell globally, but a narrower set of country locations received recorded equity financing. The steady total hides the fact that startups in fewer countries are getting checks.

In our research about procurement software startups, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Is Europe losing momentum in procurement software investment?
Yes. European procurement software funding lost both deal share and disclosed capital in the latest 12-month comparison.
Europe recorded 13 deals worth $189M, against 21 deals and $222M+ in the 12 months before. Its share of deals fell from 41% to 31%, and its share of disclosed capital from 34% to 32%. The United Kingdom still accounted for 5 recent deals and $44M, but its earlier period included 4 deals and $118M. Different leading transactions can make a national dollar comparison volatile.
European product ambition has not vanished. France-based Pivot and Naboo both secured substantial recent financings. Pivot said it processed procurement invoices for DoorDash, Lemonade and Flix, while Naboo described expanding from Europe to North America while serving major corporate clients. Germany-based SPARETECH followed with a $20M Series B in November 2026 for industrial spare-parts software.
European startups are still signing large customers and raising significant rounds. The decline we measure is in the number of financings, not proof that European procurement products are losing buyers.
Is Saudi Arabia emerging as a procurement software funding hub?
Saudi Arabia is a visible niche for procurement software financing, particularly construction purchasing and spend controls, but it is still a small sample.
We tracked 4 Saudi Arabian deals totaling $35M in the latest 12 months, equivalent to 10% of all deals and 6% of disclosed capital. They include SiFi's $20M Series A in February 2026, BRKZ's $13M Series B in September 2026, Fitting's $1.1M Seed in August 2026 and Project Suppliers' $1M Seed in October 2026. The companies do not all sell the same service: some manage corporate spend, while others organize construction-material sourcing.
BRKZ's September 2026 announcement is particularly informative. It described an equity round co-led by Wa'ed Ventures and 500 Global, plus a separate debt commitment for working capital. It also described customers submitting requests for quotations for building materials through the platform. That is a concrete procurement workflow, not simply lending to contractors.
At the broader regional level, Middle Eastern procurement software deals increased from 3 deals worth $20M to 5 deals worth $43M. We cannot call it a regional boom on so few deals. The Saudi startups sell products for identifiable local purchasing problems, while U.S. and European startups still account for most activity.
Are seed rounds still the main entry point for procurement startups?
Yes by deal count, but Seed funding represents a much smaller share of procurement software capital than later rounds.
The latest 12 months contained 21 Seed deals, or 50% of all deals, worth $75M and 13% of disclosed capital. The 12 months before had 28 Seed deals, 55% of transactions, totaling $103M+ and 16% of disclosed money. Seed remains the most frequent named stage even as the number of such financings has declined.
Series A looks different: 8 deals raised $143M in the latest period, compared with 10 deals raising $129M+ previously. Series B held 6 recent deals and $229M, against 7 deals and $244M+ before. The reported change is not a uniform move out of early stages: among deals with a named stage, early stages represented 78% in both periods.
Didero's $30M Series A in February 2026 backed software used by manufacturers, while a Seed investor in supplier discovery is funding a much earlier product. Investors are still making both kinds of bet. Most rounds start small; a few later checks account for much more of the money.
Does one large Series C mean late-stage procurement funding is back?
Not yet: ORO Labs' large Series C does not establish a broad return of late-stage procurement software financings.
Only 2 Series C deals appeared in the latest 12 months, totaling $107M+, versus 3 deals and $137M in the preceding period. No Series D+ or Growth Equity deals appeared in the latest window. Among transactions with a named stage, later rounds represented 22% in both periods. The top-end market remains selective despite the prominent ORO financing.
ORO Labs' March 2026 announcement tied its expansion plans to procurement orchestration and claimed 300% revenue growth. In contrast, Candex's $7M+ Series C in March 2026 addresses tail-spend supplier payment and procurement workflows. The fact that both carry the Series C label does not imply comparable company size or financing circumstances. The label alone says little about how big the business has become.
The previous window included Levelpath's $55M+ Series B in June 2025 and Pactum AI's $54M Series C that same month. This demonstrates that large expansion checks were not invented recently. What has changed is the relative contribution of a few standout transactions. A durable late-stage recovery would require more companies to reach large rounds regularly, not simply a high-profile announcement.

Learning from others' mistakes is the cheapest lesson there is. In our market report about procurement software startups, we look at what broke startups before you, so you don't repeat it.
Are procurement software investors becoming more selective?
Fewer investors are writing procurement software checks now, although the deals cannot tell us exactly how their standards changed.
We identified 63 distinct investors in the last 12 months, compared with 88 previously. The count of distinct disclosed lead investors fell from 61 to 44. The lead investor was identifiable for 86% of deals in both periods, so the decline is not explained by a deterioration in reported lead coverage. No investor led multiple identified recent rounds, whereas the earlier period had 1 repeat lead.
Brighton Park Capital and Goldman Sachs Alternatives share first place among recent lead investors, because they co-led the ORO Labs round. That place comes from the size of one round, not from a string of repeated leads. In the earlier period, Insight Partners led 3 deals with a combined round value of $119M. Its investments included procurement companies with quite different approaches to supplier negotiation and purchasing workflow.
Commercial traction gives useful context, but not proof of how each fund made its decision. ORO announced enterprise revenue growth, Pivot reported invoice processing for global customers, and SPARETECH cited an industrial rollout. A smaller lead-investor pool alongside fewer deals is consistent with a more selective market. It cannot by itself prove that investors formally raised revenue, margin or contract requirements.
Is procurement software fundraising steady from month to month?
No. Procurement software fundraising still comes in bursts, and the ordinary completed month became quieter.
Across 11 completed months in each comparison window, the median monthly deal count fell from 4 to 2, and the median monthly disclosed amount fell from $41M to $24M. October 2026 had 7 deals, the highest monthly count in the latest period. March 2026 was the largest capital month at $163M+, led by ORO Labs. The earlier period's capital high was June 2025 at $147M+, led by Levelpath.
The contrast is visible in actual transactions. March brought ORO Labs' major announcement alongside Lio's $30M Series A and Aerchain's $13M Series A. October was made of smaller checks such as Project Suppliers' $1M Seed and Finches' $2.2M Seed. One month can therefore show an impressive dollar total or an unusually long deal list without indicating an equally strong flow in every month.
A single large announcement can dominate a month. The full 12-month comparison is more persuasive: the ordinary month became quieter while the headline total fell only 8%.
So, what does procurement software funding look like right now?
Procurement software funding is down 8% at the headline level and weaker underneath: fewer companies are raising, first financings have declined and large expansion rounds carry more of the total.
The market still supports credible enterprise winners. ORO Labs' $100M Series C in March 2026 is the largest deal in the latest 12 months, and Brighton Park Capital and Goldman Sachs Alternatives, which co-led it, share first place among lead investors. New procurement software teams are still getting funded, but the path to a first check has narrowed. The sector still rewards proven products, but fewer startups are making it through the funding process.
The table below shows what we found.
| Question | Answer |
|---|---|
| Did stable funding mean the sector expanded? | Not in breadth; financing reached fewer procurement startups. The latest period had 42 deals versus 51 before. Large checks compensated for the missing smaller transactions. |
| Are a few giant rounds hiding weaker ordinary ones? | Yes, the big checks change the whole picture. Funding without rounds above $50M fell 35% between periods. A headline total down only 8% makes money look easier to get than it is. |
| Did more independent companies attract investors recently? | No, the funded-company base contracted rather than expanded. We counted 41 companies recently, down from 50 previously. That limits how broadly the funding total should be celebrated. |
| Are first checks getting easier for founders? | No, first-time backing has become harder to find. We counted 12 first financings, against 18 before. New entrants receive a smaller portion of investor attention. |
| Are follow-on financings increasingly driving the market? | Yes, companies with previous funding captured most dollars. Follow-ons represented at least 74% of recently disclosed procurement software capital. That leaves less of the total for first-time financings. |
| Do startups now return for funding faster? | Not in the observed timing of repeat rounds. The median interval was 21 months in the latest period. Faster individual examples should not be mistaken for acceleration. |
| Has purchasing orchestration become a capital magnet? | Yes, workflow coordination attracted major enterprise rounds recently. Intake and orchestration drew $201M across its recent deals. Buyers increasingly demand purchasing tools that execute actual tasks. |
| Has sourcing stopped attracting new procurement companies? | No, sourcing still attracted a broad deal pipeline. Strategic sourcing recorded 11 deals in the latest period. Its weaker dollar total matters more than disappearance. |
| Did Europe keep its previous funding breadth? | No, fewer European procurement startups completed recent rounds. Europe recorded 13 deals recently, against 21 in the prior period. Large individual successes cannot reverse that breadth decline. |
| Are seed rounds still the dominant transaction? | Yes by deal count, but certainly not by capital invested. Seed rounds accounted for 50% of all recent procurement deals. Larger follow-on checks determined the headline funding result. |
| Can enterprise procurement still secure major backing? | Certainly, established procurement workflows can still attract substantial investment. ORO Labs led the current period's enterprise procurement financing activity. Its deal belongs among 3 recent rounds above $50M. |

If you build or invest in the procurement software market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Our methodology
Our data runs through November 14, 2026. We compared the last 12 months, November 15, 2025 to November 14, 2026, with the preceding 12 months, November 15, 2024 to November 14, 2025. Both periods are fully within our market coverage beginning in January 2024. We use equal windows to avoid comparing a partial year with a complete year.
We count private-company equity financings of at least $300K. We exclude debt facilities, grants, loans, unconverted convertible instruments, SAFEs and public offerings. A financing is counted once even when several investors announce it separately; duplicate reporting is merged. Undisclosed equity rounds still count as deals, but cannot add to the reported capital total, so minimum totals are marked with a plus sign.
We define procurement software by the purchasing work the product performs for organizations: sourcing, supplier management and risk, intake and approvals, procure-to-pay, spend controls, contingent-services purchasing and business-to-business marketplaces with substantive buyer-side procurement workflows. We include borderline companies when purchasing software is a real core product instead of discarding them. We exclude generic ERP, payment-only systems, seller-side order-to-cash software, freight brokers and ordinary wholesale distribution without procurement workflows.
Every counted company is a startup under our working definition: independent, founded in 2000 or later, designed for fast growth around a product or technology and financed through founders, investors or eligible early backing. Companies recently listed or acquired remain eligible only within our stated recent-listing and acquisition windows. We classify categories by the primary procurement workflow, regions by headquarters country, and stages by announced financing stage; early-stage and later-stage comparisons include only deals with named stages.
We prioritize company statements, regulatory filings and established reporting.
Rounds confirmed by a company announcement, a press article or a regulatory filing are counted in full. Where no article exists, a round is counted only when at least two recognised databases agree on its date (within one month) and amount (within 5%), and it is marked as low confidence; a round found in a single database stays in the company's history but is left out of totals. For companies that have raised more than $100M, every round counted is backed by an article.
We also distinguish a company's total historical fundraising from one specific round and separate equity from debt when both appear in an announcement. Fundraising velocity is calculated only for round-to-round gaps where the dates are established, and its percentages refer to those gaps, not to the number of companies. Investor counts represent disclosed participation or leads, not a measure of investor willingness to fund the market.
If our capital total differs from a press headline, first check the market boundary, date window, deal-size threshold and whether the announcement includes debt or an earlier seed round. A missing major software company may be outside our startup definition or may primarily sell ERP, payments or general workflow tools. The comparison answers a specific question about eligible private procurement software financings, not every dollar ever deployed into purchasing technology.
Key sources include ORO Labs' March 2026 Series C, customer accounts and revenue-growth claim, Freehand's July 2026 financing and enterprise customers, Naboo's February 2026 Series B, customer traction and expansion, Fragment's October 2026 financing announcement and procurement product, Pivot's May 2026 funding and invoice-processing business, Didero's February 2026 Series A and manufacturing procurement agents, Lio's March 2026 Series A and autonomous procurement strategy, SPARETECH's November 2026 Series B and industrial customer rollout, BRKZ's equity and separate debt financing for construction procurement, Omnea's September 2025 funding and procurement customer roster, Levelpath's June 2025 Series B and AI-agent announcement, Pactum AI's June 2025 Series C and supplier-negotiation business, Vertice's January 2025 Series C and spend-management product, ProcurePro's May 2026 construction procurement funding and platform, Procure Ai's November 2025 Seed and enterprise customer claims, LightSource's Time Manufacturing procurement savings case study, LightSource's July 2026 product launch and direct sourcing context, Arm's 2026 spend-management customer case study, Zip's March 2026 account of upstream purchasing workflows, and Magentic's September 2026 Series A and product focus.

In our report covering the procurement software market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us