Space Economy Funding: A Quarter-by-Quarter Analysis
Whether you're building or investing in the space economy, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Space Economy funding has become dramatically larger quarter by quarter, but the boom is concentrated in bigger checks for proven companies rather than a broad increase in the number of businesses getting funded.
Across the five quarters studied, total capital rose from $1.33 billion in Q2 2025 to $3.77 billion in Q2 2026, while deal count actually slipped from 32 to 30. The median round, meanwhile, more than tripled from $14.3 million to $45 million.
The strongest broad expansion happened in Q4 2025. That was the quarter when deal count, median financing size and capital outside mega-rounds all improved at the same time instead of headline growth depending mainly on a few outsized transactions.
Q1 2026 changed the scale of the market. Funding jumped to $3.79 billion as the number of $100 million-plus rounds doubled, even though capital below $50 million was almost unchanged from the previous quarter.
Q2 2026 made the shift toward maturity even clearer. Total funding stayed near the Q1 record despite 30% fewer deals, the median round rose to $45 million, and later-stage financings represented more than half of transactions.
Mega-rounds now shape the market structurally rather than occasionally. In Q2 2026, rounds above $50 million absorbed 90.1% of all capital, while one-third of transactions were already above $100 million.
The weak point is startup replenishment. Seed fell to 6.7% of Q2 deals, only one first financing was identified, and 96.7% of transactions were follow-ons. The money is deep at the top of the funnel and much thinner at the bottom.
Spacecraft manufacturing has the strongest current momentum. It represented 40% of Q2 2026 deals and 57.7% of capital, with companies such as True Anomaly, Impulse Space, Astranis and Apex raising large rounds to scale factories, fleets and production capacity.
Government and defense demand are becoming a central part of the financing story. ESA and OECD data show rising institutional and military demand, while several of the largest company rounds are directly tied to national-security missions, sovereign satellite systems or government procurement.
Geographically, North America has moved back into the lead, with 46.7% of Q2 deals and 67.4% of capital. Europe also rebounded, but its latest strength still depends heavily on a smaller number of large financings such as ICEYE.
The post-Q2 2026 market has not suddenly reverted to smaller rounds either. Stoke Space's $1 billion Series E and Impulse Space's $308 million Series D extension reinforce the same pattern: investors are still willing to deploy very large amounts behind a select group of space companies that have already cleared major technical and commercial hurdles.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the space economy market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the space economy over the last years
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our report covering the Space Economy.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| EnduroSat | Spacecraft Manufacturers | September 2026 | Unknown | ≈$205M | Builds and operates modular CubeSat and small-satellite platforms and constellations. | Europe | Not disclosed | Bulgaria | |
| Open Cosmos Ltd. | Spacecraft Manufacturers | September 2026 | Unknown | ≈$349M | Designs, builds and operates small-satellite missions while selling shared constellation data and connectivity services. | Europe | Lightrock | United Kingdom | |
| Galaxia Mission Systems Inc. | Spacecraft Manufacturers | September 2026 | Seed | ≈$3.3M | Designs intelligent satellite platforms and in-orbit edge-compute payloads for real-time mission processing. | North America | Amiral Ventures; Invest Nova Scotia | Canada | |
| Stoke Space | Launch Providers | September 2026 | Series D+ | $1B | Develops Nova, a fully and rapidly reusable orbital launch vehicle family. | North America | Point72 Ventures; Spark Capital | United States | |
| The Exploration Company | Spacecraft Manufacturers | September 2026 | Series C | $450M | Builds the reusable Nyx orbital cargo spacecraft and related high-thrust propulsion for space transportation. | Europe | Bessemer Venture Partners; Atomico; Scaleup Europe Fund managed by EQT | Germany | |
| Pixxel | Earth Observation Services | September 2026 | Series C | $100M | Operates a hyperspectral Earth-observation constellation and sells satellite imagery and Earth-intelligence software. | Asia-Pacific | Temasek; Seraphim | India | |
| HyImpulse Technologies GmbH | Launch Providers | September 2026 | Series A | >$58M | Develops hybrid-propulsion suborbital and orbital launch vehicles for small-satellite launch services. | Europe | JOIN Capital; Ace Capital Partners; OMVP | Germany | |
| PLD Space | Launch Providers | September 2026 | Series C | $125M | Develops and operates reusable orbital launch vehicles and commercial satellite launch services. | Europe | Mitsubishi Electric Corporation | Spain | |
| Kepler Aerospace | Satellite Operators | September 2026 | Seed | $8M | Develops autonomous swarming ISR satellites together with mission-operations and space-avionics infrastructure. | Asia-Pacific | Blue Ashva Capital; Finvolve India Accelerator | India | |
| InspeCity | Spacecraft Manufacturers | August 2026 | Unknown | $10.5M | Develops propulsion, robotics, rendezvous and docking systems for satellite inspection, life extension and other in-orbit servicing missions. | Asia-Pacific | Speciale Invest; Ashish Kacholia | India | |
| ArcSpace | Spacecraft Manufacturers | August 2026 | Unknown | >$2.3M | Develops electron-beam tools for cutting, welding, assembly and repair of spacecraft directly in orbit. | Europe | DEPO Ventures | France | |
| Starcloud | Satellite Operators | August 2026 | Series A | $250M | Develops and operates satellite-based orbital data centers designed to run large-scale AI compute in space. | North America | Manhattan West | United States | |
| Shanghai Spacecom Satellite Technology (SpaceSail) | Satellite Connectivity Services | August 2026 | Series B | ≈$973M | Operates the Qianfan (SpaceSail) low-Earth-orbit satellite broadband constellation. | Asia-Pacific | Not disclosed | China | |
| Letara Ltd. | Spacecraft Manufacturers | August 2026 | Unknown | ≈$16M | Develops and manufactures hybrid rocket propulsion systems for satellites, launch vehicles and other space systems. | Asia-Pacific | Headline Asia; JIC Venture Growth Investments; Incubate Fund | Japan | |
| Muon Space, Inc. | Spacecraft Manufacturers | August 2026 | Series C | $250M | Designs, manufactures and operates complete satellite constellations through an integrated spacecraft, payload, software and mission-operations platform. | North America | Eclipse Capital | United States | |
| Hubble Network, Inc. | Satellite Connectivity Services | August 2026 | Unknown | $30M | Operates a satellite-powered network that connects standard Bluetooth Low Energy devices directly to satellites. | North America | Not disclosed | United States | |
| cosmobloom Inc. | Spacecraft Manufacturers | August 2026 | Seed | ≈$2.1M | Designs and develops deployable flexible space structures including membrane antennas, thin-film solar arrays and deorbit devices. | Asia-Pacific | Not disclosed | Japan | |
| Neuraspace | Ground Segment Providers | August 2026 | Series B | ≈$6.9M | Provides AI-driven space traffic management, space-domain awareness, collision avoidance and autonomous satellite-operations services. | Europe | Not disclosed | Portugal | |
| K2 Space | Spacecraft Manufacturers | July 2026 | Series D+ | $500M | Designs and manufactures large, high-power satellite platforms for communications, defense and other demanding orbital missions. | North America | Kleiner Perkins; ICONIQ | United States | |
| Genesis Space Flight Laboratories | Spacecraft Manufacturers | July 2026 | Seed | $1.4M | Develops reusable reentry spacecraft and microgravity capsules for scientific and commercial payload missions. | Europe | Fil Rouge Capital | Croatia | |
| Outlier Space Limited | Spacecraft Manufacturers | July 2026 | Seed | $7.4M | Builds reusable autonomous satellite capsules that carry research and manufacturing payloads to microgravity and return them to Earth. | Asia-Pacific | GD1 (Global from Day One) | New Zealand | |
| Array Labs | Earth Observation Services | July 2026 | Unknown | $21M | Designs, builds and operates radar-satellite clusters that produce high-resolution 3D Earth imagery and tracking data. | North America | Not disclosed | United States | |
| SWISSto12 SA | Spacecraft Manufacturers | July 2026 | Series C | $70M | Manufactures satellite payloads, antennas and compact geostationary HummingSat spacecraft for communications missions. | Europe | Not disclosed | Switzerland | |
| BAAS Technologies Private Limited | Launch Providers | July 2026 | Seed | $525K | Develops reusable sub-orbital and orbital launch vehicles, including in-house propulsion and flight hardware. | Asia-Pacific | Inflection Point Ventures | India | |
| Chang Guang Satellite Technology | Earth Observation Services | July 2026 | Unknown | ≈$700M | Operates the Jilin-1 optical remote-sensing satellite constellation and sells imagery and data services. | Asia-Pacific | Changfa Group; Lushi Investment | China | |
| FOSSA Systems S.L. | Satellite Connectivity Services | June 2026 | Series B | $10.5M | Designs, launches and operates LEO satellites providing global IoT connectivity, secure communications and space-based intelligence. | Europe | Kibo Ventures | Spain | |
| Ubotica Technologies | Earth Observation Services | June 2026 | Series A | $11M | Provides onboard satellite AI and space-based Earth-observation intelligence, including real-time maritime monitoring. | Europe | Act Venture Capital; Greencode Ventures | Ireland | |
| ElevationSpace Inc. | Spacecraft Manufacturers | June 2026 | Series B | $40M | Develops recoverable spacecraft for transporting payloads and manufactured materials from orbit back to Earth. | Asia-Pacific | SPARX Asset Management / Space Frontier Fund II | Japan | |
| Dawn Aerospace | Launch Providers | June 2026 | Series B | $25M | Develops reusable suborbital spaceplanes and in-space propulsion systems for commercial space transportation. | Asia-Pacific | Balerion Space Ventures | New Zealand | |
| Isar Aerospace SE | Launch Providers | June 2026 | Series D+ | $310M | Develops, manufactures and operates Spectrum orbital rockets for dedicated satellite launch services. | Europe | Not disclosed | Germany | |
| ICEYE | Earth Observation Services | June 2026 | Series D+ | $520M | Owns and operates SAR satellite constellations providing high-frequency Earth imagery and space-based intelligence. | Europe | General Atlantic | Finland | |
| NewOrbit Space Ltd | Spacecraft Manufacturers | June 2026 | Series A | $18.5M | Designs and manufactures satellites engineered to operate commercially in very-low Earth orbit. | Europe | Voyager Ventures | United Kingdom | |
| Apex | Spacecraft Manufacturers | June 2026 | Series D+ | $200M | Manufactures standardized configurable satellite-bus platforms for commercial and national-security constellations. | North America | Glade Brook Capital Partners; Washington Harbour Partners | United States | |
| Axiom Space, Inc. | Spacecraft Manufacturers | June 2026 | Series D+ | $175M | Develops a commercial space station, human-spaceflight infrastructure and spacesuits for orbital and lunar missions. | North America | Not disclosed | United States | |
| Impulse Space, Inc. | Spacecraft Manufacturers | June 2026 | Series D+ | $500M | Builds and operates orbital transfer vehicles and propulsion systems for moving spacecraft after launch. | North America | 137 Ventures; BANNER VC | United States | |
| UNASTELLA Corporation | Launch Providers | June 2026 | Series B | $24M | Develops proprietary orbital and suborbital launch vehicles, rocket engines and launch services. | Asia-Pacific | Altos Ventures | South Korea | |
| Gilmour Space Technologies | Launch Providers | May 2026 | Series D+ | $10.2M | Develops Eris orbital launch vehicles and provides launch services for small satellites. | Asia-Pacific | Not disclosed | Australia | |
| Observable Space | Ground Segment Providers | May 2026 | Series A | $90M | Builds ground-based optical sensing and laser-communications infrastructure, alongside related in-space optical systems. | North America | Lux Capital; Upfront Ventures; Detroit Venture Partners; Island Green Capital; RTX Ventures | United States | |
| Star Catcher Industries, Inc. | Satellite Operators | May 2026 | Series A | $65M | Develops an orbital satellite network that optically beams solar power on demand to other spacecraft. | North America | B Capital; Shield Capital; Cerberus Ventures | United States | |
| Cowboy Space Corporation | Satellite Operators | May 2026 | Series B | $275M | Develops and plans to operate solar-powered orbital AI-compute satellites integrated with its own launch architecture and optical data links. | North America | Index Ventures | United States | |
| Lunar Outpost | Spacecraft Manufacturers | May 2026 | Series B | $30M | Designs and manufactures autonomous lunar rovers and robotic mobility infrastructure for Moon and cislunar missions. | North America | Industrious Ventures | United States | |
| Skyroot Aerospace Private Limited | Launch Providers | May 2026 | Unknown | $50M | Develops Vikram orbital launch vehicles and commercial launch services for satellites. | Asia-Pacific | Sherpalo Ventures; GIC | India | |
| Astranis Space Technologies Corp. | Spacecraft Manufacturers | May 2026 | Series D+ | $300M | Designs, manufactures and deploys small high-orbit communications satellites and dedicated satellite networks. | North America | Snowpoint Ventures; Franklin Templeton | United States | |
| True Anomaly | Spacecraft Manufacturers | April 2026 | Series D+ | $650M | Builds autonomous spacecraft and software for space-domain awareness, orbital security and national-security missions. | North America | Eclipse Ventures; Riot Ventures | United States | |
| Spaceflux | Ground Segment Providers | April 2026 | Seed | $4.7M | Provides optical space-surveillance, tracking and space-domain-awareness services through a global sensor network and AI platform. | Europe | Blackfinch Ventures | United Kingdom | |
| Univity | Satellite Connectivity Services | April 2026 | Series A | $32M | Develops a very-low-Earth-orbit satellite constellation providing 5G and direct-to-device connectivity services through telecom operators. | Europe | Blast; Expansion Ventures; Deeptech 2030 | France | |
| ATMOS Space Cargo | Spacecraft Manufacturers | April 2026 | Series A | $30.2M | Develops reusable orbital transport and re-entry spacecraft for carrying payloads to orbit and returning them to Earth. | Europe | Balnord; Expansion Ventures | Germany | |
| Archangel Lightworks | Ground Segment Providers | April 2026 | Series A | $13.5M | Develops optical laser communications systems and deployable ground stations connecting space networks with terrestrial infrastructure. | Europe | Santander Alternative Investments | United Kingdom | |
| Rhea Space Activity | Ground Segment Providers | April 2026 | Series A | $6M | Develops optical, GPS-independent navigation software for spacecraft operating in GPS-denied environments. | North America | Boston Global Space Tech Investors | United States | |
| Turion Space | Spacecraft Manufacturers | April 2026 | Series B | $75M | Builds maneuverable satellites, payloads and mission software for orbital intelligence and space-domain-awareness operations. | North America | Washington Harbour Partners | United States | |
| Citra Space Corp | Ground Segment Providers | April 2026 | Series A | $15M | Develops space-object identification technology that combines multiple data sources to characterize and identify objects in orbit. | North America | Washington Harbour Partners | United States | |
| Portal Space Systems | Spacecraft Manufacturers | April 2026 | Series A | $50M | Builds rapidly maneuverable spacecraft designed to reposition and operate across different orbital regimes. | North America | Geodesic Capital; Mach33 | United States | |
| Spacety | Spacecraft Manufacturers | April 2026 | Unknown | $190M | Designs and mass-produces small satellites including SAR satellites and plans an IPO. | Asia-Pacific | Liangxi Sci-Tech Innovation Phase II Fund (Bohua Capital) | China | |
| Starfish Space | Spacecraft Manufacturers | April 2026 | Series B | $110M | Develops and operates autonomous spacecraft for satellite life extension, orbital maneuvering and end-of-life disposal. | North America | Point72 Ventures; Activate Capital; Shield Capital | United States | |
| Xoople | Earth Observation Services | April 2026 | Series B | $130M | Builds satellite-based Earth-observation infrastructure and high-precision physical-world datasets for enterprise and government users. | Europe | Nazca Capital | Spain | |
| SatLeo Labs | Earth Observation Services | April 2026 | Seed | $2.2M | Develops thermal and visible-light satellite systems and Earth-observation data products for applications including defense, agriculture and climate monitoring. | Asia-Pacific | Unicorn India Ventures | India | |
| Antaris, Inc. | Ground Segment Providers | March 2026 | Series A | $28M | Provides software for satellite design, simulation, mission virtualization and spacecraft operations. | North America | WestWave Capital | United States | |
| Starcloud | Satellite Operators | March 2026 | Series A | $170M | Designs, launches and plans to operate satellites functioning as orbital AI-compute and data-center infrastructure. | North America | Benchmark; EQT Ventures | United States | |
| Bellatrix Aerospace Private Limited | Spacecraft Manufacturers | March 2026 | Unknown | $20M | Manufactures satellite propulsion systems and orbital-transfer vehicles for in-space mobility. | Asia-Pacific | Cactus Partners | India | |
| Xona Space Systems, Inc. | Satellite Operators | March 2026 | Series C | $170M | Develops and plans to operate the Pulsar low-Earth-orbit positioning, navigation and timing satellite constellation. | North America | Mohari Ventures Natural Capital | United States | |
| Arlula Pty Ltd | Earth Observation Services | March 2026 | Unknown | ≈$2.4M | Provides satellite tasking, imagery access, processing and Earth-observation data infrastructure across multiple satellite operators. | Asia-Pacific | Paspalis Capital | Australia | |
| PAVE Space SA | Spacecraft Manufacturers | March 2026 | Seed | $40M | Develops orbital-transfer spacecraft and high-energy kick stages for moving payloads between orbits. | Europe | Visionaries Club; Creandum | Switzerland | |
| Beijing Uishi Space Technology / AstronStone | Launch Providers | March 2026 | Unknown | ≈$28M | Develops the reusable AS-1 methalox orbital launch vehicle and associated launch infrastructure. | Asia-Pacific | GL Ventures; Xingxiang Capital | China | |
| Agnikul Cosmos Private Limited | Launch Providers | March 2026 | Unknown | ≈$2.6M | Designs, manufactures and plans to commercially launch the Agnibaan family of orbital rockets. | Asia-Pacific | Not disclosed | India | |
| Mantis Space, Inc. | Satellite Operators | March 2026 | Seed | >$10M | Plans to operate a constellation of spacecraft that beams solar power to other satellites while they are in eclipse. | North America | Rule 1 Ventures; Montauk Capital | United States | |
| GalaxEye Space Solutions | Earth Observation Services | March 2026 | Series A | ≈$4.8M | Develops and plans to operate multi-sensor Earth-observation satellites combining radar and optical imaging. | Asia-Pacific | Not disclosed | India | |
| AIRMO | Earth Observation Services | March 2026 | Seed | ≈$5.8M | Develops high-resolution greenhouse-gas monitoring using proprietary airborne instruments and a planned satellite-based observation system. | Europe | Ananda Impact Ventures | Germany | |
| Lux Aeterna Space Inc. | Spacecraft Manufacturers | March 2026 | Seed | $10M | Develops reusable satellite platforms designed to return payloads from orbit and be reflown. | North America | Konvoy | United States | |
| Vast, Inc. | Spacecraft Manufacturers | March 2026 | Series A | $300M | Designs, manufactures and plans to operate commercial space stations and crewed orbital infrastructure. | North America | Balerion Space Ventures | United States | |
| Sierra Space Corporation | Spacecraft Manufacturers | March 2026 | Series C | $550M | Develops spacecraft, spaceplanes, satellite platforms and other space systems for government and commercial missions. | North America | LuminArx Capital Management | United States | |
| PLD Space | Launch Providers | March 2026 | Series C | ≈$209M | Develops and operates the MIURA family of commercial launch vehicles. | Europe | Mitsubishi Electric Corporation | Spain | |
| In-Space Propulsion Technologies GmbH (ISPTech) | Spacecraft Manufacturers | February 2026 | Seed | ≈$6.5M | Develops and manufactures non-toxic chemical propulsion systems for maneuvering spacecraft in orbit. | Europe | Join Capital | Germany | |
| Beijing E-Drive Space Technology Co., Ltd. | Spacecraft Manufacturers | February 2026 | Series D+ | Not Disclosed | Develops and manufactures electric propulsion systems and electromechanical products for satellites and other spacecraft. | Asia-Pacific | Not disclosed | China | |
| Sophia Space | Spacecraft Manufacturers | February 2026 | Seed | $10M | Builds modular, solar-powered orbital computing spacecraft infrastructure for in-space data processing. | North America | Alpha Funds; KDDI Green Partners Fund; Unlock Venture Partners | United States | |
| Aalyria Technologies, Inc. | Satellite Connectivity Services | February 2026 | Series B | $100M | Builds software-defined communications-network orchestration and optical communications technology for satellites and other aerospace platforms. | North America | Battery Ventures; J2 Ventures | United States | |
| SatVu | Earth Observation Services | February 2026 | Unknown | ≈$38M | Operates a satellite constellation providing high-resolution thermal Earth-observation imagery and intelligence. | Europe | NATO Innovation Fund; Molten Ventures | United Kingdom | |
| Hefei Xinghuo Space Technology Co., Ltd. | Launch Providers | February 2026 | Seed | Not Disclosed | Develops electric-pump liquid rocket engines and the Evolution-1 orbital launch vehicle. | Asia-Pacific | Xingtai Capital | China | |
| Deep Space Energy SIA | Spacecraft Manufacturers | February 2026 | Seed | ≈$415K | Develops radioisotope-based electrical power generators for satellites and lunar space infrastructure. | Europe | Outlast Fund; Linas Sargautis | Latvia | |
| constellr GmbH | Earth Observation Services | February 2026 | Series A | ≈$44M | Operates thermal-imaging satellites and sells high-resolution temperature and thermal-intelligence data. | Europe | Alpine Space Ventures; Lakestar | Germany | |
| Stoke Space | Launch Providers | February 2026 | Series D+ | $350M | Develops Nova, a fully reusable orbital launch vehicle and its propulsion systems. | North America | Not disclosed | United States | |
| iSpace | Launch Providers | February 2026 | Series D+ | ≈$729M | Develops and commercializes reusable liquid-fueled orbital launch vehicles. | Asia-Pacific | Cowin Capital; Jingming Innovation Capital | China | |
| Satlabs Space Systems | Satellite Connectivity Services | February 2026 | Seed | $1M | Develops a LEO data-relay satellite network designed to reduce latency in downlinking Earth-observation data. | Asia-Pacific | Finvolve; India Accelerator | India | |
| Shanghai Puxing Aerospace Technology Co., Ltd. | Spacecraft Manufacturers | February 2026 | Seed | ≈$4.3M | Develops optical remote-sensing payloads and micro/nanosatellite platforms for Earth-observation constellations. | Asia-Pacific | TusStar Venture Capital | China | |
| Morpheus Space GmbH | Spacecraft Manufacturers | February 2026 | Series A | $15M | Manufactures electric propulsion systems used by satellites for maneuvering and orbital mobility. | Europe | Not disclosed | Germany | |
| Sanyark Space | Satellite Connectivity Services | February 2026 | Seed | $500K | Develops a LEO satellite constellation combining high-precision positioning, timing and communications services. | Asia-Pacific | AUM Ventures | India | |
| Hunan Hangsheng Satellite Technology Co., Ltd. | Spacecraft Manufacturers | February 2026 | Series A | ≈$23M | Designs and manufactures satellites, payloads and related spacecraft systems for commercial constellations. | Asia-Pacific | Not disclosed | China | |
| AstroX Inc. | Launch Providers | February 2026 | Series A | ≈$3.3M | Develops balloon-assisted and conventional launch systems for placing satellites into orbit. | Asia-Pacific | Not disclosed | Japan | |
| The Tomorrow Companies Inc. (Tomorrow.io) | Earth Observation Services | February 2026 | Unknown | $175M | Operates weather-observation satellites and converts proprietary atmospheric observations into weather intelligence services. | North America | Stonecourt Capital; HarbourVest Partners | United States | |
| CesiumAstro Inc. | Spacecraft Manufacturers | February 2026 | Series C | $270M | Designs and manufactures satellite communications payloads, phased-array systems and spacecraft platforms. | North America | Trousdale Ventures | United States | |
| Northwood Space | Ground Segment Providers | January 2026 | Series B | $100M | Builds vertically integrated satellite ground stations and network services using phased-array and parabolic antenna systems. | North America | Washington Harbour Partners; Andreessen Horowitz | United States | |
| Gilmour Space Technologies | Launch Providers | January 2026 | Series D+ | $145M | Develops orbital launch vehicles and provides launch services from its Australian spaceport. | Asia-Pacific | National Reconstruction Fund Corporation; Hostplus | Australia | |
| Canada Rocket Company | Launch Providers | January 2026 | Seed | $4.5M | Develops reusable light- and medium-lift rockets to provide Canadian orbital launch services. | North America | BDC; Garage Capital | Canada | |
| Ethereal Exploration Space and Defence Private Limited (EtherealX) | Launch Providers | January 2026 | Series A | $20.5M | Develops a fully reusable medium-lift orbital launch vehicle and rocket engines for commercial launch services. | Asia-Pacific | TDK Ventures; BIG Capital | India | |
| Hydrosat | Earth Observation Services | January 2026 | Series B | $60M | Operates thermal-infrared Earth-observation satellites and sells temperature and water-stress intelligence derived from their imagery. | North America | Hartree Partners; Subutai Capital Partners; Space 4 Earth | United States | |
| Interstellar Technologies | Launch Providers | January 2026 | Series D+ | $95.5M | Develops and operates commercial orbital launch vehicles, including the ZERO small-satellite launcher. | Asia-Pacific | Woven by Toyota | Japan | |
| SkyFi | Earth Observation Services | January 2026 | Series A | $12.7M | Provides an online platform for ordering, accessing and analyzing commercial satellite imagery and other Earth-observation data. | North America | Buoyant Ventures; IronGate Capital Advisors | United States | |
| Diffraqtion | Earth Observation Services | January 2026 | Seed | $2.7M | Develops quantum-camera-enabled satellite and telescope constellations for high-sensitivity Earth and space imaging. | North America | QDNL Participations | United States | |
| TakeMe2Space | Satellite Operators | January 2026 | Series A | $5M | Builds and operates low-Earth-orbit compute satellites and its OrbitLab satellite-as-a-service platform for running workloads in orbit. | Asia-Pacific | Chiratae Ventures | India | |
| Array Labs | Earth Observation Services | January 2026 | Series A | $20M | Develops a formation-flying radar satellite constellation to produce high-resolution 3D Earth-observation and monitoring data. | North America | Catapult Ventures | United States | |
| Chengdu Xingweixun Technology Co., Ltd. (CVSAT) | Ground Segment Providers | December 2025 | Series A | >$14M | Develops satellite-communications systems, modems, baseband technology, chips and user terminals. | Asia-Pacific | Oriza Seed (元禾原点) | China | |
| Beijing EllipSpace Technology Co., Ltd. (EllipSpace / 椭圆时空) | Satellite Operators | December 2025 | Series C | >$28M | Develops and operates the Star Pool satellite constellation combining remote sensing, communications, navigation augmentation and onboard computing. | Asia-Pacific | Not disclosed | China | |
| Shaanxi Xingyi Space Technology Co., Ltd. (星邑空间) | Ground Segment Providers | December 2025 | Seed | ≈$42M | Builds and operates satellite TT&C ground-station networks, mission-control software and spacecraft operations infrastructure. | Asia-Pacific | Shenzhen Capital Group | China | |
| Axiom Space, Inc. | Spacecraft Manufacturers | December 2025 | Series D+ | $100M | Develops commercial space-station modules and associated privately operated human-spaceflight infrastructure. | North America | Not disclosed | United States | |
| Orbion Space Technology, Inc. | Spacecraft Manufacturers | December 2025 | Series C | $27.1M | Manufactures Hall-effect electric-propulsion systems for satellites and spacecraft. | North America | Not disclosed | United States | |
| HawkEye 360, Inc. | Satellite Operators | December 2025 | Series D+ | $81M | Operates an RF-sensing satellite constellation and sells geolocation and signals-intelligence data and analytics. | North America | NightDragon; Center15 Capital | United States | |
| Tenchijin Inc. | Earth Observation Services | December 2025 | Series B | ≈$646K | Combines satellite Earth-observation data with AI to provide infrastructure, water, agriculture and energy intelligence. | Asia-Pacific | Not disclosed | Japan | |
| EraDrive | Spacecraft Manufacturers | December 2025 | Seed | $5.3M | Builds autonomous spacecraft flight-computing and control systems designed to give satellites self-driving capabilities. | North America | Haystack | United States | |
| Digantara Industries | Satellite Operators | December 2025 | Series B | $50M | Operates space-based and ground sensors providing space-domain-awareness, orbital intelligence and missile-warning data. | Asia-Pacific | 360 ONE Asset; SBI Investment; Ronnie Screwvala | India | |
| Chengdu Xinglian Xintong Technology Co., Ltd. (星联芯通) | Ground Segment Providers | December 2025 | Series B | >$14M | Develops satellite-communications baseband systems, chips and ground terminals for high- and low-orbit networks. | Asia-Pacific | Not disclosed | China | |
| Beijing Yushi Space Aerospace Technology Co., Ltd. (宇石空间) | Launch Providers | December 2025 | Seed | >$14M | Develops and manufactures the reusable stainless-steel AS-1 liquid launch vehicle. | Asia-Pacific | Cornerstone Capital (基石资本) | China | |
| Shenzhen Weilian Xingzhi Technology Co., Ltd. (Sbeit / 斯北图) | Spacecraft Manufacturers | December 2025 | Series C | >$56M | Manufactures satellite-internet communications payloads, TT&C/data-transmission modules, phased-array systems and related space-grade electronics. | Asia-Pacific | Not disclosed | China | |
| Fortastra | Spacecraft Manufacturers | December 2025 | Seed | >$8M | Designs and operates highly maneuverable spacecraft for on-orbit security and defensive space missions. | North America | Upfront Ventures | United States | |
| K2 Space | Spacecraft Manufacturers | December 2025 | Series C | $250M | Designs and manufactures large, high-power satellite platforms for commercial and government missions across multiple orbits. | North America | Redpoint | United States | |
| Smartlink AI Limited (Orbit AI) | Satellite Operators | December 2025 | Unknown | $500K | Develops and operates satellites providing in-orbit AI computing, connectivity and blockchain-verified processing. | Asia-Pacific | Not disclosed | Singapore | |
| ODIN Space | Satellite Operators | December 2025 | Seed | $3M | Operates an on-orbit sensor network that detects and maps small, otherwise untrackable orbital debris. | Europe | Steel Atlas | United Kingdom | |
| ICEYE | Earth Observation Services | December 2025 | Series D+ | ≈$175M | Operates a large synthetic-aperture-radar satellite constellation and sells persistent Earth-observation imagery and intelligence. | Europe | General Catalyst | Finland | |
| Spotlite | Earth Observation Services | December 2025 | Seed | ≈$4.1M | Uses satellite Earth-observation data and AI to monitor infrastructure and detect ground movement and asset risks. | Europe | Indico Capital Partners; Explorer Investments | Portugal | |
| WorkerInSpace Inc. | Spacecraft Manufacturers | December 2025 | Seed | $6.9M | Develops robotic spacecraft for satellite life-extension, refueling, repair, towing and in-space servicing and manufacturing. | Asia-Pacific | IMM Investment | South Korea | |
| Marble Imaging GmbH | Earth Observation Services | December 2025 | Seed | ≈$6.1M | Builds a very-high-resolution multispectral Earth-observation satellite constellation and associated imagery analytics. | Europe | High-Tech Gründerfonds (HTGF) | Germany | |
| AstroX Inc. | Launch Providers | November 2025 | Series A | $8.7M | Develops balloon-launched Rockoon vehicles intended to place small satellites into orbit. | Asia-Pacific | alpha Inc. | Japan | |
| Quindar | Ground Segment Providers | November 2025 | Series A | $18M | Provides autonomous cloud-based mission-control and ground-operations software for satellites and hybrid space systems. | North America | Washington Harbour Partners | United States | |
| Leanspace | Ground Segment Providers | November 2025 | Series A | $11.6M | Provides software-defined ground-segment and mission-operations software for satellites and constellations. | Europe | Karista; 42CAP | France | |
| HyPrSpace | Launch Providers | November 2025 | Series A | $24.4M | Develops hybrid-propulsion suborbital and orbital launch vehicles for small-satellite access to space. | Europe | Red River West; DeepTech 2030 | France | |
| U-Space SAS | Spacecraft Manufacturers | November 2025 | Series A | $28M | Designs, manufactures and operates modular small-satellite platforms for civil, commercial and defense constellations. | Europe | Blast; Definvest; Expansion | France | |
| Extellis Inc. | Earth Observation Services | November 2025 | Seed | $6.8M | Develops high-volume all-weather synthetic-aperture-radar satellite imagery using metasurface antenna technology. | North America | Oval Park Capital | United States | |
| Agnikul Cosmos Private Limited | Launch Providers | November 2025 | Series C | $6.8M | Develops small-lift launch vehicles and associated launch infrastructure for dedicated small-satellite missions. | Asia-Pacific | Advenza Global Limited | India | |
| ULOOK Technologies Private Limited | Earth Observation Services | November 2025 | Seed | $2.1M | Develops autonomous satellite swarms that detect and geolocate terrestrial radio-frequency emissions for space-based intelligence. | Asia-Pacific | growX Ventures; InfoEdge Ventures | India | |
| Reflex Aerospace GmbH | Spacecraft Manufacturers | November 2025 | Series A | $57.6M | Designs and manufactures high-performance satellite platforms for ISR, Earth observation and communications missions. | Europe | Human Element | Germany | |
| Farcast | Ground Segment Providers | November 2025 | Series A | $5M | Develops electronically steered flat-panel satellite user terminals for broadband satellite networks. | North America | Not disclosed | United States | |
| EnduroSat | Spacecraft Manufacturers | October 2025 | Unknown | $104M | Designs and mass-manufactures modular small and midsize satellite buses and complete constellation solutions. | Europe | Riot Ventures | Bulgaria | |
| Catalyx Space | Spacecraft Manufacturers | October 2025 | Seed | $5.4M | Builds reentry spacecraft, lightweight satellite buses and related mission infrastructure for orbital logistics. | North America | Outlander VC | United States | |
| NXGSAT SRL | Ground Segment Providers | October 2025 | Seed | ≈$1.4M | Develops software-defined 5G NR-NTN satellite modems for interoperable terrestrial and multi-orbit satellite networks. | Europe | imec.istart future fund; PMV | Belgium | |
| HyImpulse Technologies GmbH | Launch Providers | October 2025 | Series A | ≈$17.5M | Develops hybrid-propulsion suborbital and orbital rockets for commercial satellite launch services. | Europe | Campus Founders Ventures | Germany | |
| Beijing Space Pioneer Technology Co., Ltd. | Launch Providers | October 2025 | Series D+ | ≈$350M | Develops liquid-propellant orbital launch vehicles and commercial launch services under the Tianlong family. | Asia-Pacific | Not disclosed | China | |
| Eoliann S.r.l. Società Benefit | Earth Observation Services | October 2025 | Seed | ≈$4.9M | Provides satellite-data and AI-based climate-risk analytics for physical assets and infrastructure. | Europe | Montage Ventures | Italy | |
| Stoke Space | Launch Providers | October 2025 | Series D+ | $510M | Develops the fully reusable Nova medium-lift orbital launch vehicle and associated launch service. | North America | U.S. Innovative Technology Fund (USIT) | United States | |
| Aspia Space Limited | Earth Observation Services | October 2025 | Unknown | ≈$1.3M | Provides AI-powered Earth-observation products including cloud-free satellite imagery and land-intelligence analytics. | Europe | Not disclosed | United Kingdom | |
| Commcrete Ltd. | Ground Segment Providers | September 2025 | Series A | $21M | Develops compact tactical satellite-communications terminals and systems for mobile voice and data connectivity. | Middle East | Greenfield Partners | Israel | |
| Beijing Galactic Energy Aerospace Technology Co., Ltd. | Launch Providers | September 2025 | Series D+ | $336M | Develops and provides commercial launch services using the Ceres and Pallas families of orbital launch vehicles. | Asia-Pacific | Not disclosed | China | |
| Cosmoserve Space | Spacecraft Manufacturers | September 2025 | Seed | $3.2M | Develops autonomous robotic spacecraft to capture, service and remove defunct satellites and orbital debris. | Asia-Pacific | Alan Rutledge | India | |
| VyomIC | Satellite Operators | September 2025 | Seed | $1.6M | Develops a planned LEO satellite constellation providing high-precision positioning, navigation and timing services. | Asia-Pacific | Speciale Invest | India | |
| Zhejiang Geespace Technology Co., Ltd. | Satellite Operators | September 2025 | Growth Equity | $281M | Builds and operates the Geely Future Mobility Constellation for global satellite IoT communications and related positioning services. | Asia-Pacific | Not disclosed | China | |
| iSpace | Launch Providers | September 2025 | Series D+ | $98M | Develops and launches commercial orbital rockets, including reusable methane-fueled launch vehicles. | Asia-Pacific | Chengdu Major Industrialization Project Phase II Equity Investment Fund Co., Ltd. | China | |
| Hubble Network, Inc. | Satellite Connectivity Services | September 2025 | Series B | $70M | Operates a satellite network that connects standard Bluetooth-enabled devices directly to space for global low-power IoT connectivity. | North America | Ryan Swagar | United States | |
| K2 Space | Spacecraft Manufacturers | September 2025 | Unknown | $15M | Designs and manufactures large, high-power satellite buses capable of operating from LEO through GEO. | North America | Not disclosed | United States | |
| Apex | Spacecraft Manufacturers | September 2025 | Series D+ | $200M | Mass-produces configurable satellite buses for commercial, civil and national-security payloads. | North America | Interlagos | United States | |
| ReOrbit | Spacecraft Manufacturers | September 2025 | Series A | ≈$52.7M | Designs and manufactures software-defined sovereign satellites and connected satellite systems for communications and intelligence missions. | Europe | Springvest | Finland | |
| Space DOTS Ltd | Ground Segment Providers | September 2025 | Seed | $1.5M | Provides in-orbit environmental intelligence and threat-detection data to help spacecraft operators understand and manage orbital risks. | Europe | Female Founders Fund | United Kingdom | |
| Aerospacelab | Spacecraft Manufacturers | August 2025 | Series B | ≈$66M | Designs and manufactures vertically integrated satellites, platforms, payloads and subsystems for commercial and institutional missions. | Europe | Not disclosed | Belgium | |
| ICEYE | Earth Observation Services | August 2025 | Growth Equity | ≈$11M | Builds and operates a global synthetic-aperture radar satellite constellation providing Earth-observation imagery and analytics. | Europe | Not disclosed | Finland | |
| SpinLaunch | Satellite Connectivity Services | August 2025 | Series C | $30M | Develops space-access technology and the Meridian low-Earth-orbit broadband satellite constellation. | North America | ATW Partners | United States | |
| EMPOSAT (Beijing Aerospace Yuxing Technology Co., Ltd.) | Ground Segment Providers | August 2025 | Series C | ≈$59.9M | Operates ground-station networks and provides satellite telemetry, tracking, control, data reception and in-orbit operations services. | Asia-Pacific | Not disclosed | China | |
| Orbital Paradigm | Spacecraft Manufacturers | August 2025 | Seed | ≈$1.7M | Develops reusable autonomous orbital re-entry spacecraft for returning commercial payloads from orbit to Earth. | Europe | Not disclosed | Spain | |
| Xovian Aerospace | Earth Observation Services | August 2025 | Seed | $2.5M | Develops and plans to operate RF-sensing satellites that convert radio-frequency observations into real-time intelligence. | Asia-Pacific | Piper Serica; Turbostart | India | |
| Orbital Operations | Spacecraft Manufacturers | August 2025 | Seed | $8.8M | Develops high-thrust, long-duration cryogenic orbital vehicles for rapid satellite maneuvering and in-space missions. | North America | Initialized Capital | United States | |
| Spaceflux | Ground Segment Providers | July 2025 | Seed | ≈$7.3M | Operates a global optical ground-sensor network and analytics platform for tracking satellites and other orbital objects. | Europe | UK Innovation & Science Seed Fund; Foresight Group; Blackfinch Ventures | United Kingdom | |
| Cascade Space | Ground Segment Providers | July 2025 | Seed | $5.9M | Provides software and infrastructure for designing, testing and operating spacecraft communication systems. | North America | Not disclosed | United States | |
| Inbound Aerospace | Spacecraft Manufacturers | July 2025 | Seed | $1M | Develops autonomous reusable re-entry spacecraft for orbital experiments, microgravity manufacturing and payload return. | Asia-Pacific | Speciale Invest | India | |
| Omspace Rocket & Exploration Private Limited | Launch Providers | July 2025 | Seed | $3M | Develops modular reusable launch vehicles for small satellites in low Earth orbit. | Asia-Pacific | Not disclosed | India | |
| Auriga Space, Inc. | Launch Providers | July 2025 | Seed | $4.6M | Develops electromagnetic launch systems intended to propel payloads toward eventual orbital deployment. | North America | OTB Ventures | United States | |
| Apolink | Satellite Connectivity Services | July 2025 | Seed | $4.3M | Builds a LEO relay-satellite network providing continuous RF and optical connectivity for other satellites. | North America | Not disclosed | United States | |
| Varda Space Industries, Inc. | Spacecraft Manufacturers | July 2025 | Series C | $187M | Builds and operates orbital spacecraft and re-entry capsules for in-space manufacturing and payload return. | North America | Natural Capital; Shrug Capital | United States | |
| Interstellar Technologies | Launch Providers | July 2025 | Series D+ | $45.1M | Develops and operates commercial launch vehicles for satellite delivery, alongside related satellite infrastructure. | Asia-Pacific | Not disclosed | Japan | |
| Chloris Geospatial | Earth Observation Services | July 2025 | Series A | $8.5M | Provides satellite-derived measurements of forest biomass, carbon stocks and ecosystem change. | North America | Future Energy Ventures | United States | |
| Genesis Space Flight Laboratories | Spacecraft Manufacturers | July 2025 | Seed | ≈$351K | Develops reusable re-entry spacecraft for microgravity missions and returning payloads from orbit. | Europe | Fil Rouge Capital | Croatia | |
| Astrobase Space Technologies | Launch Providers | July 2025 | Seed | $10M | Develops reusable launch vehicles and methane-fueled rocket engines for orbital payload delivery. | Asia-Pacific | BanyanCo | India | |
| Astrophel Aerospace Private Limited | Launch Providers | July 2025 | Seed | $800K | Develops reusable semi-cryogenic launch vehicles for small-satellite missions. | Asia-Pacific | Not disclosed | India |

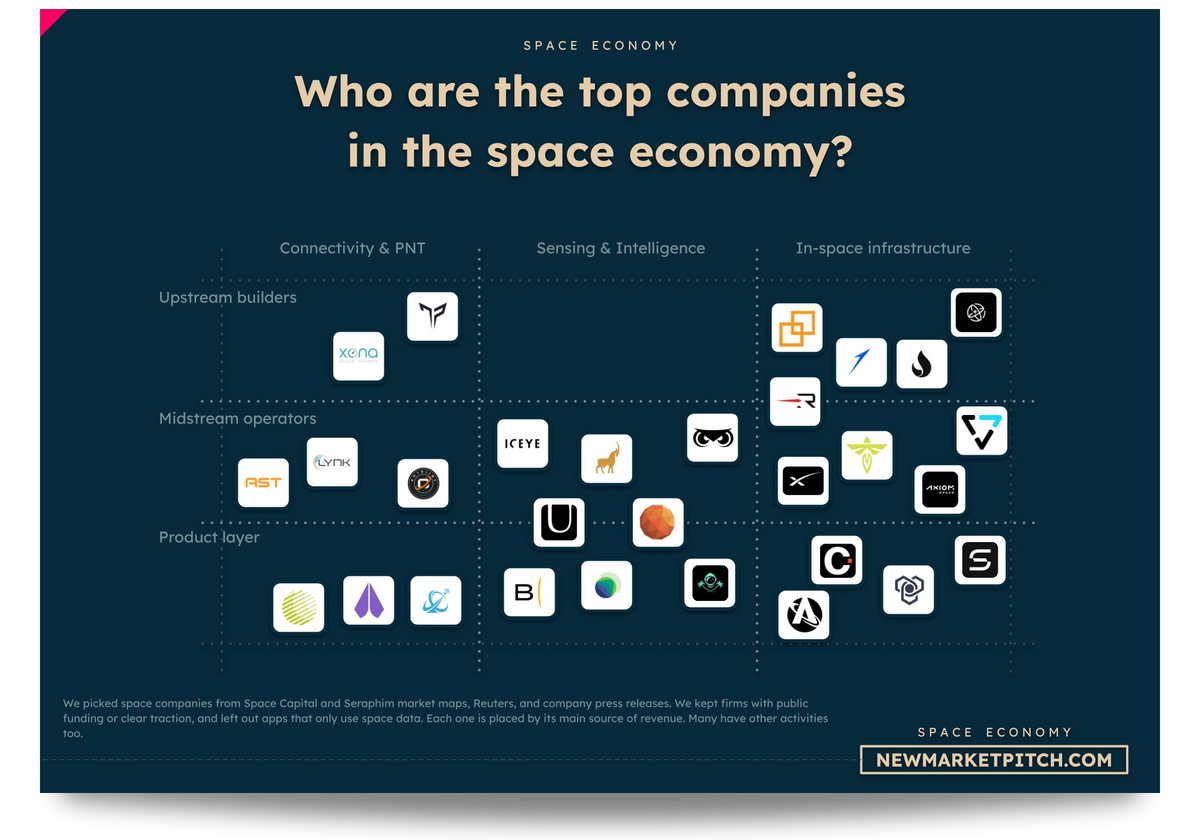
In our research about the space economy, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is Space Economy funding really booming right now?
Space Economy funding is booming in dollar terms, but today's market is financing roughly the same number of companies with much bigger checks.
Across the five quarters we studied, capital climbed from $1.33 billion in Q2 2025 to $3.77 billion in Q2 2026. Deal count went the other way, slipping from 32 to 30. The median round gives an even clearer picture: $14.3 million at the start of the period, then $45 million in the latest quarter.
The gap becomes hard to ignore when we remove rounds above $50 million. Those smaller and mid-sized financings represented $514.7 million in Q2 2025 and only $372.8 million one year later.
So the surge in dollars is real. What has changed most is the size and destination of the money. Space companies that have already made it through several years of technical development are now able to raise hundreds of millions of dollars in a single transaction.
| Quarter | Deals | Capital | Median round | Capital excluding >$50M |
|---|---|---|---|---|
| Q2 2025 | 32 | $1.33B | $14.3M | $514.7M |
| Q3 2025 | 30 | $1.54B | $9.4M | $187.2M |
| Q4 2025 | 38 | $2.05B | $14.0M | $365.6M |
| Q1 2026 | 43 | $3.79B | $20.5M | $363.0M |
| Q2 2026 | 30 | $3.77B | $45.0M | $372.8M |
| Q2 2025 → Q2 2026 | -6% deals | +183% capital | +215% median | -28% |
When did Space Economy funding actually start getting stronger?
Q4 2025 was the quarter when Space Economy funding genuinely broadened instead of relying mainly on a handful of huge rounds.
Q3 had looked strong on the surface because total capital rose 15.5%. Underneath, deal count fell, the median round dropped from $14.3 million to $9.4 million and capital excluding rounds above $50 million collapsed by 63.6%. Galactic Energy, Geespace, Apex and Varda carried a large part of the quarter.
Q4 was much healthier across the distribution. Deals jumped from 30 to 38, total capital rose another 33.2%, and funding outside rounds above $50 million almost doubled. The number of $5 million to $20 million rounds also went from seven to 15.
Several things improved at once. More companies raised, the typical round got larger, and the middle of the market came back. Among the five quarters we studied, Q4 2025 is the cleanest example of a broad funding expansion.
Was the huge Q1 2026 Space Economy funding jump mostly mega-rounds?
Yes. The Q1 2026 Space Economy funding record came overwhelmingly from a sudden wave of very large rounds.
Capital jumped 84.8% quarter over quarter, yet funding below the $50 million mark barely moved: $365.6 million in Q4 versus $363 million in Q1. The huge headline increase was therefore concentrated almost entirely above that threshold.
The number of $100 million-plus financings doubled from six to 12 in one quarter. iSpace raised $729 million, while large rounds from Stoke Space, Vast, CesiumAstro, Sierra Space, PLD Space and several others pushed the total much higher.
The average round reached more than $92 million, while deal count increased by a much more modest 13.2%. Investors were clearly becoming comfortable financing industrial space companies at a scale that would have looked exceptional only a few quarters earlier.
Q1 marked a major change in funding capacity, especially at the top of the market. The broader venture layer underneath it was almost unchanged.

In our market report about the space economy, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why did Space Economy funding stay near record highs with 30% fewer deals in Q2 2026?
Q2 2026 stayed near record funding levels because Space Economy investors shifted hard toward fewer, more mature companies and much larger rounds.
Deal count fell 30.2% from Q1, while total capital barely changed. At the same time, the median financing more than doubled from $20.5 million to $45 million.
The stage mix moved just as sharply. Early-stage companies represented 58.1% of Q1 deals and 36.7% in Q2. Later-stage deals jumped from 27.9% to 56.7%.
This is where the market really changed shape. Q1 showed how much money investors were prepared to deploy. Q2 showed where they increasingly wanted to deploy it: companies with previous funding, more advanced products and much larger capital requirements.
Are mega-rounds taking over Space Economy funding?
Mega-rounds currently dominate Space Economy funding, and there are now enough of them that one freak transaction can no longer explain the concentration.
In Q2 2026, rounds above $50 million absorbed 90.1% of all capital. Deals above $100 million alone represented 84% of the quarter's funding and one-third of its transactions.
Interestingly, the largest single deal represented only 17.2% of capital. Earlier quarters were sometimes more dependent on their number-one transaction. What has emerged instead is a whole group of companies capable of raising nine-figure rounds.
The progression has been steady enough to take seriously. Only 9.4% of Q2 2025 deals exceeded $100 million. That share reached 13.3% in Q3, 15.8% in Q4, 27.9% in Q1 2026 and 33.3% in Q2.
At the other end, sub-$5 million rounds almost vanished in the latest quarter. The funding market is increasingly built around scaling expensive businesses rather than spreading capital evenly across every stage.
| Funding-size indicator | Q2 2025 | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 |
|---|---|---|---|---|---|
| Deals below $5M | 25.0% | 36.7% | 21.1% | 23.3% | 6.7% |
| Deals $5M–<$20M | 34.4% | 23.3% | 39.5% | 18.6% | 23.3% |
| Deals $20M–<$50M | 18.8% | 10.0% | 13.2% | 20.9% | 20.0% |
| Deals $50M–<$100M | 12.5% | 16.7% | 10.5% | 4.7% | 16.7% |
| Deals $100M+ | 9.4% | 13.3% | 15.8% | 27.9% | 33.3% |
| Capital from >$50M rounds | 61.4% | 87.8% | 82.2% | 90.4% | 90.1% |
| Capital from >$100M rounds | 55.9% | 65.3% | 67.8% | 81.0% | 84.0% |
Are early-stage Space Economy startups getting squeezed out?
Early-stage Space Economy startups are clearly getting squeezed in the latest funding mix, although we need more than one extreme quarter before calling that a permanent condition.
Seed fell from 30.2% of deals in Q1 2026 to 6.7% in Q2. Series B moved from 7% to 30%, while Series D+ more than doubled its share to 26.7%. Seed and Series A together received only 8.7% of Q2 capital.
Financing history points the same way. We identified ten first financings in Q3 2025, nine in Q4, nine in Q1 2026 and only one in Q2. The other 29 Q2 transactions were follow-ons.
Company age adds some nuance. The median age of funded companies was roughly five years in the latest quarter, close to several earlier periods, so companies are not simply becoming much older every quarter. The bigger change is financial maturity: far more money is going to businesses that have already raised and progressed into later funding stages.
We treat first-financing status as directional because reconstructing every historical financing for every private company is imperfect. Even with that caveat, the latest gap is too large to brush aside.
| Maturity indicator | Q2 2025 | Q3 2025 | Q4 2025 | Q1 2026 | Q2 2026 |
|---|---|---|---|---|---|
| Seed deal share | 37.5% | 50.0% | 34.2% | 30.2% | 6.7% |
| Series A deal share | 28.1% | 10.0% | 23.7% | 27.9% | 30.0% |
| Series B deal share | 15.6% | 6.7% | 7.9% | 7.0% | 30.0% |
| Series D+ deal share | 3.1% | 13.3% | 13.2% | 11.6% | 26.7% |
| First-financing share | 12.5% | 33.3% | 23.7% | 20.9% | 3.3% |
| Follow-on share | 87.5% | 66.7% | 76.3% | 79.1% | 96.7% |
| Approx. median company age | 4 yrs | 3 yrs | 6 yrs | 5 yrs | 5 yrs |

Our document detailing everything you need to know about space economy gets updated several times a month, so you always get the latest view of where things stand.
Is spacecraft manufacturing the hottest part of Space Economy funding right now?
Yes. Spacecraft manufacturing currently has the clearest funding momentum in the Space Economy, especially among companies moving into high-rate production and large-scale deployment.
The category accounted for 40% of Q2 2026 deals and 57.7% of all capital. Its median round reached $92.5 million, compared with $17.5 million only one quarter earlier.
The company examples make the shift tangible. True Anomaly raised $650 million to scale spacecraft and software for national-security missions. Impulse Space raised $500 million after flying three missions and signing hundreds of millions of dollars of customer contracts. Astranis raised a $300 million Series E equity round as it expanded production, while Apex raised more than $200 million to increase high-rate satellite manufacturing.
These companies are spending on factories, fleets, production capacity, engineering teams and deployments. Investors are increasingly financing the jump from working technology to industrial output.
The pattern also reaches beyond one narrow satellite product. Space stations, orbital mobility, standardized satellite buses, national-security spacecraft and high-orbit platforms are all attracting nine-figure capital.
| Current funding theme | Q1 2026 | Q2 2026 | What changed |
|---|---|---|---|
| Spacecraft manufacturers: deal share | 30.2% | 40.0% | Broader presence |
| Spacecraft manufacturers: capital share | 33.0% | 57.7% | Large jump |
| Spacecraft manufacturers: median round | $17.5M | $92.5M | Much larger checks |
| Launch providers: deal share | 25.6% | 16.7% | Sharp pullback |
| Launch providers: capital | $1.59B | $419M | Q1 peak reversed |
| Earth observation: deal share | 23.3% | 13.3% | Fewer deals |
| Earth observation: capital share | 9.6% | 17.6% | Bigger rounds despite fewer deals |
Has Space Economy launch funding already peaked?
Launch funding peaked inside our five-quarter window in Q1 2026, then fell sharply in Q2, but fresh funding since the window closed shows investors are still willing to make enormous bets on launch.
The build-up before that reversal was real. Launch went from three deals in Q2 2025 to seven in Q3, seven in Q4 and 11 in Q1 2026. Capital climbed from $74 million to $498 million, then $931 million and finally $1.59 billion.
Q2 broke the sequence. Only five launch financings appeared, totaling $419 million, and the median fell from $61.8 million to $25 million.
There is an important current update, though. After our June 30 dataset cutoff, Stoke Space announced a new $1 billion Series E as it prepared Nova for its first orbital flight and expanded production capacity. That post-period round does not change the quarterly figures above, but it makes the idea of a broad investor retreat from launch much harder to defend.
For now, Q1's extraordinary density of launch deals looks more like a peak in deal concentration than an end to investor appetite. A smaller number of companies can still attract huge amounts of capital.

In our report covering the space economy market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Earth observation funding really gaining momentum, or is ICEYE doing most of the work?
Earth observation is currently attracting bigger checks without attracting more deals, and ICEYE explains a large part of that apparent acceleration.
Deal count dropped from ten in Q1 2026 to four in Q2. Even so, Earth observation's share of total capital rose from 9.6% to 17.6%, while the median round jumped from $16.4 million to $70.5 million.
ICEYE is the obvious reason to be careful with the headline. The company raised $520 million of primary Series F capital as part of a transaction exceeding €1 billion including secondary shares. By then, seven European governments had procured sovereign satellite systems from the company.
There were other credible businesses in the category, including weather and geospatial intelligence companies, so the market goes beyond one name. Still, Q2 looked much more like a scale-up quarter for Earth observation than a fresh wave of startup formation.
Investors are putting serious money behind proven satellite-data businesses, especially where governments and large enterprises are already paying customers.
Is defense spending driving the current Space Economy funding boom?
Defense and sovereign demand are clearly helping drive today's large Space Economy rounds, particularly in spacecraft, launch and Earth observation.
The European Space Agency's 2026 Space Economy Report gives us the strongest broad confirmation. ESA found that private space investment increased 60% globally in 2025, while 80% of demand in the €75 billion upstream spacecraft-manufacturing and launch market came from institutional customers dominated by defense.
The OECD's 2026 review reaches a similar conclusion from public budgets. Military space programs represented 46.3% of U.S. government space spending in 2025, 25% in France and 14.8% in Japan. The OECD also documents new sovereign investment in satellite intelligence, resilient communications, space-domain awareness and launch capacity across several countries.
The company-level deals line up with that backdrop. True Anomaly's $650 million raise was explicitly tied to space superiority. Apex said its latest funding would help serve critical U.S. government missions and national-security constellations. Stoke had already secured a U.S. Space Force National Security Space Launch contract when it raised its large Series D. ICEYE entered its Series F after multiple European governments bought sovereign radar-satellite systems.
Commercial demand still matters. Impulse Space, Astranis, Tomorrow.io and other companies sell into mixes of government and private customers. But government procurement now gives investors a much more credible route to revenue for capital-heavy systems that used to depend heavily on future-market assumptions.

Theory only gets you so far. In our research about the space economy, we dig up the real signals from the field and show you the ones worth watching.
Is Space Economy funding moving back to North America while Europe catches up?
North America has regained a clear lead in Space Economy funding, while Europe's latest rebound is real but still much more dependent on a few large rounds.
North America's deal share fell as low as 28.9% in Q4 2025, then recovered to 41.9% in Q1 and 46.7% in Q2. Its share of capital reached 67.4% in the latest quarter, and the median North American round hit $100 million.
That fits what we saw company by company. True Anomaly, Impulse Space, Apex and Astranis all raised very large U.S. rounds during Q2.
Europe also bounced back strongly. European companies represented one-third of Q2 transactions and 28.6% of capital, the region's highest capital share in our five-quarter period. ICEYE accounts for a meaningful part of that jump, which is why we would wait before calling it a generalized European funding boom.
Asia-Pacific went in the opposite direction. After representing around 40% of deals during its strongest stretch, its share fell to 20% in Q2 and only 4% of capital. Earlier Chinese mega-rounds had made the region look especially strong in dollar terms, so the reversal is partly a change in large-deal timing as well as deal volume.
For now, the geographic center of gravity has moved back toward North America, with Europe showing a credible but less proven acceleration.
Are Space Economy investors concentrating too, or just the companies getting funded?
The companies receiving Space Economy capital are concentrating much faster than the investors providing it.
We found 29 unique disclosed lead investors in Q2 2025, 21 in Q3, 38 in Q4, 56 in Q1 2026 and 41 in Q2. There is no small group of venture firms repeatedly controlling most transactions across the entire period.
Washington Harbour Partners stands out because its activity became more frequent toward the end of the window. Expansion Ventures and Shield Capital also appeared more than once in Q2, while firms such as Index, Lux, Point72, Riot and Interlagos show up across different quarters.
Corporate investors tell a slightly different story. Strategic participation peaked in breadth in Q1 2026, when ten deals included an identified corporate or industrial investor. Q2 had only four, but the median round involving strategic capital reached $182.5 million. Nokia's participation in ICEYE is a good example of corporate money appearing inside a much larger scale-up financing.
Disclosure also improved during the period, with the share of deals carrying an identified lead rising from 60% in Q3 2025 to 90% in Q2 2026. That makes raw investor counts easier to interpret toward the end than at the beginning.
The concentration story therefore sits mainly on the company side today. Fewer mature companies are absorbing more money, while the pool of investors backing them remains fairly broad.

In our market report about the space economy, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
What was really happening in Space Economy funding in Q3 2025?
Q3 2025 was a barbell market: lots of tiny and first-time financings at one end, with most of the actual dollars going to a handful of very large rounds at the other.
One-third of transactions were first financings, the highest share in our five-quarter period. More than 36% of all deals were below $5 million.
At the same time, $100 million-plus financings absorbed 65.3% of all capital. Galactic Energy, Geespace, Apex and Varda were operating on a completely different scale from the quarter's new entrants.
That helps explain why Q3 can look contradictory depending on which metric we use. It was an active quarter for new-company funding, yet the middle of the market weakened badly. The median round fell and capital below $50 million dropped to only $187.2 million.
What happened next is even more revealing. The first-financing wave faded over the following quarters, while large follow-on rounds became increasingly common. The top-heavy part of Q3 turned out to be the more durable direction.
Is the current Space Economy funding boom actually healthy?
Today's Space Economy funding market looks very strong for industrial scale-ups and much thinner for companies trying to enter the funding funnel.
The positive side is easy to see. Investors are financing real factories, spacecraft fleets, launch infrastructure, satellite constellations and mission capacity at levels that were rare a few years ago. Several companies now combine technical milestones, customer contracts and government demand before raising their largest rounds.
The weak spot is startup replenishment. As seen above, the latest quarter had very few small rounds and almost no identified first financings. If that remains true for several more quarters, the market could end up with plenty of money for today's winners but a thinner pipeline behind them.
For now, the market looks mature and capital-rich rather than uniformly broad. That distinction explains why record fundraising can coexist with fewer transactions.
Have the huge Space Economy rounds continued since the Q2 2026 cutoff?
Yes. The freshest post-period announcements suggest that the appetite for very large Space Economy rounds has continued beyond our quarterly dataset.
Stoke Space announced a $1 billion Series E after the period we analyzed, taking its total capital raised to $2.3 billion as it moved toward Nova's first orbital flight and a larger launch vehicle.
Impulse Space also added a $308 million extension to the Series D that began with its $500 million Q2 financing, bringing the combined round to $808 million. The company linked the additional funding to product development, hiring and growing demand from commercial, civil and government customers.
These deals sit outside the April 1, 2025 to June 30, 2026 comparison window, so we keep them out of every quarterly calculation in this article. They are still useful as a reality check on the interpretation.
As of now, there is little evidence that the market suddenly reverted to smaller checks after Q2. If anything, the post-period announcements reinforce the idea that investors are willing to keep funding a select group of proven space companies at industrial scale.

Learning from others' mistakes is the cheapest lesson there is. In our document detailing everything you need to know about space economy, we look at what broke startups before you, so you don't repeat it.
What is Space Economy funding actually telling us now?
Space Economy funding has moved from a fairly broad venture market toward a much more capital-intensive scale-up market.
The clearest durable trend is round size. The median financing more than tripled across the period, while nine-figure rounds became increasingly common quarter after quarter.
Q4 2025 was the strongest broad expansion because more deals, a higher median and stronger funding outside mega-rounds arrived together. Q1 2026 then pushed headline capital much higher through large financings, and Q2 kept that capital level alive while the number of transactions fell sharply.
Spacecraft manufacturing currently has the strongest category momentum. Launch had a genuine multi-quarter run before cooling inside the dataset, while subsequent Stoke funding shows that large launch bets are still very much alive. Earth observation is attracting bigger rounds as well, although its latest capital acceleration came with fewer deals.
The market has also become more mature financially. Follow-ons and Series B/D+ deals dominate the latest mix, while startup entry has weakened. Company age alone does not explain the shift; previous funding history and stage do a much better job.
Government and defense demand have become harder to separate from the financing story. ESA, OECD data and several of the largest company rounds all point toward national-security procurement, sovereign infrastructure and government-backed demand giving investors more confidence to fund expensive systems.
The misleading headline would be that the entire Space Economy funding market simply became three times bigger. As pointed out above, deal volume barely changed from the beginning to the end of the period, while funding below the mega-round layer actually shrank. Today's market has much more money available for scaling proven companies, but much less evidence of a similarly strong expansion at the bottom of the funnel.
Our methodology
This analysis examines private Space Economy fundraising announced from April 1, 2025 through June 30, 2026, covering five complete calendar quarters from Q2 2025 to Q2 2026. The goal is to measure not just how much capital was raised, but how deal count, round size, stage, geography and company maturity changed underneath the headline totals.
We built the dataset from company and investor announcements, government and regulatory material, reputable financial and industry reporting, and established funding databases. Where several credible sources covered the same financing, we cross-checked the material facts instead of automatically using the first reported figure.
Companies were included only when their core business was clearly part of the Space Economy at the time of financing. The resulting dataset contains 173 qualifying financings. We focused on private-company equity financings and excluded debt, loans, grants, public offerings and other non-equity funding. When a transaction mixed equity with another instrument, we used only the equity component when it could be isolated reliably.
Each genuine financing was treated as a separate deal, while duplicate reports of the same transaction were consolidated. Extensions, additional closes and tranches were reviewed individually. Two Q1 2026 deals had undisclosed amounts, so they are included in deal counts but excluded from calculations that require a known funding amount.
Funding dates, stages, lead investors, strategic investors, previous financing status, company founding dates and relevant commercial or technical milestones were recorded only when public evidence supported them. We kept lower bounds and approximate amounts visible rather than turning vague disclosures into artificial point estimates.
The analysis also went through a separate quality-control pass for missed transactions, duplicates, date-boundary errors, questionable equity classifications, category inconsistencies and companies that failed the pure-play test. The principle was simple: keep a datapoint incomplete when necessary rather than make the dataset look cleaner by inventing precision.
Key sources used for market context include ESA's 2026 Space Economy Report, the OECD's 2026 review of strategic capabilities and government space spending, and Space Capital's Q1 2026 investment review.
Company-level financing and scale-up details were checked against first-hand announcements including True Anomaly's $650M Series D, Impulse Space's $500M Series D, ICEYE's Series F, Apex's latest financing, Astranis's Series E, Vast's $500M financing, Stoke Space's $510M Series D, PLD Space's €180M Series C, CesiumAstro's Series C, Tomorrow.io's $175M financing, and Turion Space's Series B.
Post-period checks were kept outside every quarterly calculation and used only to test whether the interpretation still held after June 30, 2026. Those checks include Stoke Space's $1B Series E and Impulse Space's $308M Series D extension.

If you build or invest in the space economy market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us