What are the top startups in the XR market?
Whether you're building or investing in the XR market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The top startups in the XR market today are XREAL, RayNeo, VITURE, Rokid, Varjo, VRChat, ArborXR, RealWear, Distance Technologies and Even Realities. XREAL still leads our overall ranking, but RayNeo ships more units than XREAL on IDC's and Omdia's latest counts.
The center of gravity in XR has moved toward glasses. IDC says XR glasses grew 79.8% in Q2 2026 and now make up 46.0% of the AR/VR devices it tracks, while VR devices fell 37.6%. Omdia, which counts XR headwear differently, saw the total fall 38.7% in the first half of 2026 even as glasses rose to 25.8% of units.
There is no single shipment leader across every kind of XR eyewear, because each research firm draws the category differently. RayNeo leads the startups in IDC's Q2 2026 tracker and Omdia's first-half count, VITURE leads outside China in Counterpoint's Q1 count, Rokid tops Counterpoint's combined AR-and-AI-glasses category, and Meta still dominates the overall market.
XREAL remains number one on the mix we weigh most, a business we can verify plus the strongest platform position, not on volume. Its revenue grew 30.8% in 2025, its margins, losses and financing are all visible, and its Android XR glasses, Aura, are built with Google. Its units are another story: IDC saw them fall 14.5% in Q2 2026. Aura has had more than 10,000 reservations worldwide since August 2026 and launches in Japan on 27 November 2026. Those are reservations, not sales or deliveries.
RayNeo is the company most likely to take first place. It already beats XREAL on shipment share, IDC puts it first in XR glasses with 25.2% of that category, and its iO and GT glasses went on sale in September 2026. VITURE sits just behind, with strong US retail distribution.
Waveguide glasses are becoming much more important. Their share of AR-glasses shipments rose sharply in Q1 2026, which makes lightweight products from Rokid and Even Realities more relevant than they looked a year ago.
VR has not disappeared, but the startup opportunity has narrowed. VR headset shipments keep falling on every major tracker. The better private businesses are specialized: VRChat owns social engagement, Varjo sells expensive defense simulation, and Bigscreen serves enthusiasts.
Enterprise XR is quietly more durable than the old metaverse narrative suggested. ArborXR now says more than 5,500 organizations use its platform, and RealWear and Varjo also have concrete deployment evidence, because they solve specific operational problems rather than waiting for consumers to adopt a new computing habit.
Funding still runs ahead of the market. XPANCEO and Sesame have raised huge rounds, yet XPANCEO's first integrated lens demo is planned for early 2027 and Sesame says its glasses arrive in 2027. Even Realities reached a reported $1 billion valuation in July 2026 on far smaller volumes than RayNeo.
That is why we separate current leaders from frontier bets. Distance Technologies ranks highest among deep-tech challengers: after defense integration deals, FORVIA HELLA invested in it in September 2026 to co-develop a car head-up display.
The ranking is therefore less about who has the biggest valuation and more about who already controls something difficult to replicate: shipment share, retail distribution, enterprise deployments, engaged users, defense programs or a strategic platform position inside the next XR stack.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

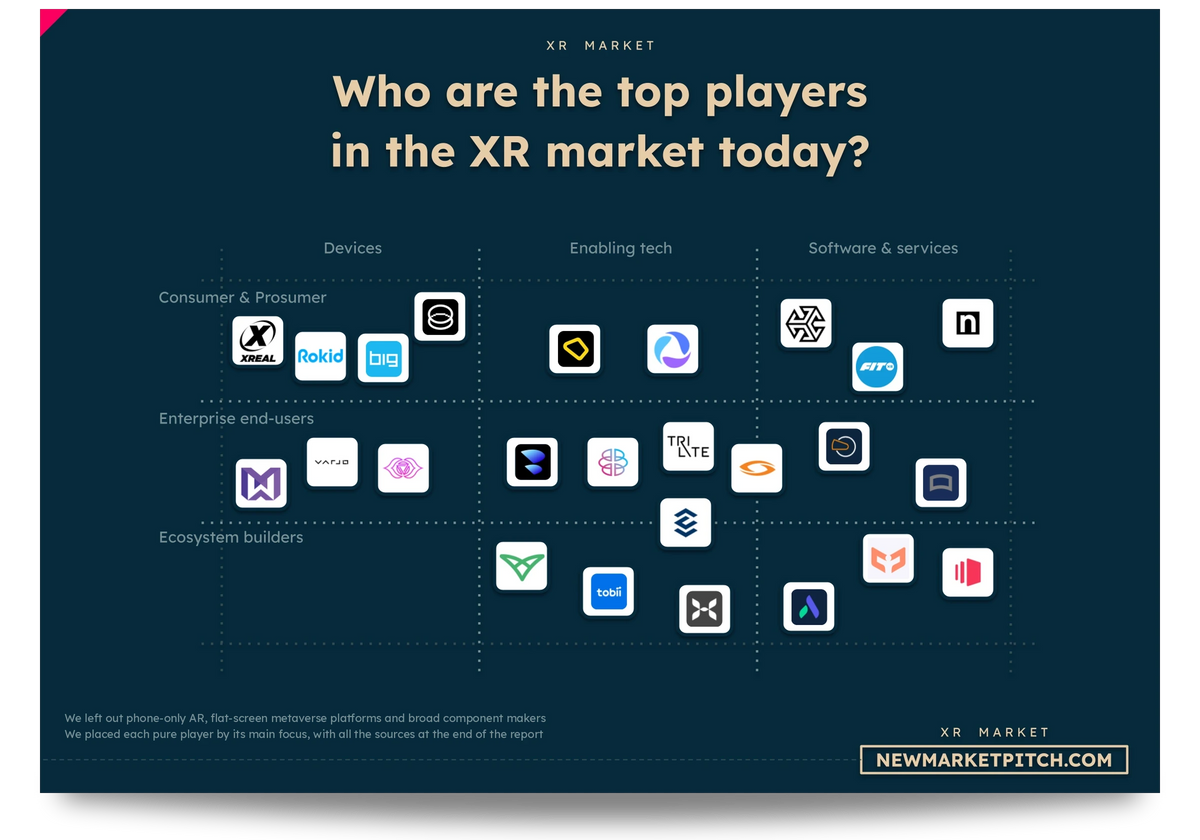
In our report covering the XR market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why are smart glasses suddenly taking over the XR startup race?
Smart glasses are taking over the XR startup race because they are the only part of the market still growing, while traditional VR and mixed-reality headsets keep falling.
The headline total depends on who is counting. Omdia, in research published in September 2026, counted about 1.9 million XR headwear units in the first half of 2026, down 38.7% year over year, while the glasses share of those units rose from 10.2% to 25.8%. IDC's Q2 2026 tracker instead shows total AR/VR shipments up 5.1%, carried by XR glasses, which grew 79.8% to 46.0% of the devices it counts, while VR devices fell 37.6%. Counterpoint's Q2 2026 data shows the same split, with AR device shipments up 138% and VR headset shipments down 18%. The scopes differ, but every firm sees glasses rising and headsets falling.
The technology mix is changing almost as quickly as volumes. Counterpoint found that waveguide AR glasses went from 18% of AR-glasses shipments a year earlier to 42% in Q1 2026. That is a big jump for the thinner optical architecture needed for glasses that look closer to normal eyewear.
So an XR startup ranking built mainly around VR headset makers would already feel dated. XREAL, RayNeo, VITURE, Rokid and Even Realities sit in the only growing part of the industry, while companies such as Varjo and ArborXR are finding narrower but much more concrete enterprise markets. The open question is the total: on Omdia's count, glasses growth is not yet big enough to offset the headset decline, while on IDC's count it already is.
| XR market indicator | Latest measured change | What we see |
|---|---|---|
| Total XR headwear shipments (Omdia) | −38.7% YoY in H1 2026, to 1.9 million units | The overall market is shrinking again |
| XR glasses share of headwear (Omdia) | 10.2% → 25.8% (H1 2025 to H1 2026) | Glasses are taking a much bigger slice |
| AR devices (Counterpoint) | +138% YoY in Q2 2026 | Display glasses are still accelerating |
| VR headsets (Counterpoint) | −18% YoY in Q2 2026 | Headsets keep losing ground |
| Waveguide share of AR glasses | 18% → 42% in one year (Q1 2026) | Lightweight AR is becoming commercially relevant |
| XR glasses (IDC) | +79.8% YoY in Q2 2026, to 46.0% of AR/VR devices | Glasses now carry IDC's whole market |
| VR devices (IDC) | −37.6% YoY in Q2 2026 | A steeper headset drop than Counterpoint finds |
What does “top XR startup” actually mean now?
For this ranking, a top XR startup needs real adoption today or a very strong chance of controlling an important part of the XR market soon.
That sounds obvious, but XR makes rankings unusually messy. XREAL sells consumer AR glasses. Varjo sells expensive simulation hardware to defense customers. VRChat runs a social platform. ArborXR manages enterprise headset fleets. XPANCEO is trying to put displays inside contact lenses. Ranking all of them by funding would tell us almost nothing.
Even shipment share is not one number. RayNeo leads XREAL on IDC's and Omdia's latest unit counts, while XREAL holds the stronger platform position through Google's Android XR. Neither measure alone picks an all-purpose winner, so we look at both.
We give the most weight to evidence that already exists: units shipped, revenue, repeat enterprise deployments, active users, distribution and whether the company's technology is becoming part of a larger ecosystem. Prototypes, pilots, memorandums of understanding and fundraising count for less unless something harder backs them up.
That changes the order considerably. XPANCEO and Sesame have each raised $250 million, yet neither has shipped its planned consumer XR product. ArborXR has raised about $25 million in total while getting its software into more than 5,500 organizations, by its own count. We rank the second type of proof higher for now.

Our research about XR headsets gets updated several times a month, so you always get the latest view of where things stand.
Who is actually selling the most AR glasses right now?
RayNeo is currently selling the most XR glasses among the startups, with XREAL and VITURE close behind on IDC's count; Meta still leads the overall market by a wide margin. The exact order depends on which research firm's definition you use.
IDC's Q2 2026 AR/VR tracker puts Meta at 45.7% of units, followed by RayNeo at 12.0%, XREAL at 8.4%, VITURE at 7.5% and Rokid at 6.6%. RayNeo grew 83.3% and led IDC's XR-glasses category with 25.2%, while XREAL's units fell 14.5%. Omdia's first-half 2026 count gives a similar order: Meta at 48.2%, down from 71.3% a year earlier, RayNeo second at 9.9% and VITURE third at 8.6%. Omdia also found that RayNeo, VITURE and XREAL together held 93.1% of tethered display glasses, a narrow segment rather than all smart glasses.
Definitions still matter. Counterpoint's Q2 count of all XR headsets puts RayNeo at 7% and VITURE at 6%, and its Q1 2026 tracker gave RayNeo 41% of Birdbath and flat-prism AR glasses against 34% for VITURE. These datasets use different denominators, so they cannot be added together, but they all point the same way: RayNeo is ahead on volume.
Rokid adds another wrinkle. Counterpoint found Rokid Glasses was one of the best-selling individual AR-glasses models in Q1 2026, alongside Meta Ray-Ban Display. Rokid also says Counterpoint ranked it first in a combined AR-and-AI-glasses category in the first half of 2026, with 41% of shipments; that category is not comparable with IDC's. So there is still no single clean leaderboard: RayNeo leads on startup volume in IDC's and Omdia's counts, Rokid leads Counterpoint's AR-and-AI-glasses count, and VITURE shipped the most AR glasses outside China in Q1 2026, according to Counterpoint.
Is XREAL still the top XR startup before Aura reaches buyers?
XREAL is still our number-one XR startup, but as the strongest platform and business case, not as the shipment leader: RayNeo ships more units, and Aura has reservations but no reported deliveries yet.
XREAL's Hong Kong listing filing gives us an unusually clear look at the business. Revenue rose 30.8% in 2025 to RMB516 million. Gross margin improved from 22.1% to 35.2%, while the net loss narrowed from RMB708.6 million to RMB456.4 million. More than 70% of revenue came from outside China.
The unit numbers are more modest. XREAL sold 133,731 AR-eyewear units in 2025, versus 124,871 a year earlier, an increase of only about 7%. Average selling price rose from RMB2,466 to RMB3,013, roughly 22%. Much of the revenue growth came from selling more expensive products rather than from a jump in unit sales. Its One Series alone accounted for 111,355 units.
Aura is what makes XREAL's platform case so strong. Google and XREAL opened orders on 28 October 2026 in the US, Canada and South Korea, at a launch price of $1,099 through the end of the year for the base model, against a regular $1,279. The glasses weigh under 95 grams, offer a 70-degree field of view and run Android XR with Gemini through a connected compute puck. In Japan, general reservations opened on 2 November at ¥229,800, and NTT Docomo will start selling Aura online on 27 November 2026, with Docomo stores following in December. XREAL plans to ship Japanese orders gradually from late November.
Aura has had more than 10,000 advance reservations worldwide since August 2026, when buyers could place refundable reservations before the price was set; Docomo repeated the figure on 2 November. It is a reservation count, not sales or delivered units, and no shipment number had been published by early November.
Add the $100 million XREAL raised earlier in 2026 and the picture is fairly clear. XREAL still loses a lot of money, and its units fell on IDC's Q2 2026 count, but its business is easy to see and its new product is tied directly to Google's XR operating system. The open question is whether those reservations turn into delivered units and repeat use quickly enough to close the volume gap with RayNeo.
If you want more recent data on this point, please see our latest XR market report.

In our market report about XR headsets, we look at what the winners do differently, so you can learn from the best instead of guessing.
Has RayNeo now passed XREAL in XR-glasses shipments?
Yes. RayNeo has passed XREAL on IDC's and Omdia's latest counts, although we still put it second overall because less of its underlying business is visible.
IDC's Q2 2026 tracker gives RayNeo 12.0% of units against 8.4% for XREAL, after RayNeo grew 83.3% while XREAL shrank, and puts RayNeo first in XR glasses with 25.2% of that category. Omdia ranks RayNeo second worldwide behind Meta for the first half of 2026. TCL Electronics' annual reporting also says RayNeo captured 32% of China's AI and AR-glasses market during 2025 and 35.4% of online AR-glasses sales volume.
RayNeo has enough funding to keep pushing. The company raised more than RMB1 billion, roughly $140 million, with China Mobile and China Unicom among the investors. That support matters as RayNeo tries to move beyond glasses used mainly as portable screens.
The new products are now in stores. RayNeo's 33-gram iO glasses for heads-up information and AI help, and its GT and GT Max display glasses for entertainment, went on sale on 4 September 2026. RayNeo said launch prices were $449 for iO, $299 for GT and $399 for GT Max; its store currently lists them at $499, $329 and $429. RayNeo is attacking lightweight ambient computing and high-end virtual displays at the same time.
On shipments alone, RayNeo would be number one. XREAL stays ahead in our overall ranking because we can verify more of its business, including revenue, margins and annual units, and because Aura ties it directly to Google's Android XR. RayNeo's glasses revenue and margins are not disclosed separately.
Is VITURE becoming the biggest XR-glasses startup outside China?
VITURE is currently the leading independent XR-glasses company outside China on Counterpoint's latest regional count and probably has the best US retail position in the startup field.
Its shipment data is solid. Counterpoint's Q1 2026 tracker found VITURE's Birdbath and flat-prism AR-glasses shipments grew 281% year over year, to a 34% segment share, and said VITURE shipped more AR glasses outside China than any other brand that quarter. Omdia then ranked it third worldwide for the first half of 2026 with 8.6%, and IDC gave it 7.5% in Q2 after 95.8% growth, just behind XREAL's 8.4%.
The retail rollout helps explain the acceleration. VITURE put its XR glasses into roughly 200 Best Buy stores, where people can actually try the product instead of buying an unfamiliar wearable from a website. It has also sold through AT&T, Micro Center and B&H. Physical demos matter in XR because a spec sheet does a poor job of showing what a virtual 100-inch screen feels like.
VITURE has backed the expansion with more than $200 million raised across two $100 million financings within six months. It is also broadening the product range. The $299 Pro 2 pushes harder on mainstream display glasses, while Helix, developed around NVIDIA's XR AI stack, moves VITURE into AI-assisted industrial safety eyewear.
We still put VITURE behind XREAL and RayNeo because its financial performance is much less transparent and IDC's latest global share puts it just under both, even if Omdia's first-half count places it ahead of XREAL. On US distribution, though, VITURE is a major competitor.
If you want more recent data on this point, please see our latest XR market report.

In our document detailing everything you need to know about XR, you will always find fresh funding data, taken straight from our own verified funding database.
Is Rokid building the closest thing to everyday AR glasses?
Rokid is one of the strongest bets on AR glasses that combine an actual display, AI, cameras and a form factor light enough for everyday use.
Counterpoint's Q1 2026 tracker named Rokid Glasses one of the best-selling AR-glasses models globally, and IDC gave Rokid 6.6% of tracked units in Q2 2026 after a 592.2% jump. Rokid also says Counterpoint put it first in AR-and-AI glasses for the first half of 2026, with 41% of that category. That matters more than another prototype award because Rokid competes in waveguide AR, the part of the market trying to put useful information in front of both eyes without the bulk of older display glasses.
Rokid is also moving beyond crowdfunding and specialist online channels. In Japan, the company began nationwide sales through 75 electronics stores and major e-commerce platforms in July 2026. It now sells a lighter AI-glasses line alongside the display-equipped Rokid Glasses, which its store lists at $699 in its fall sale. The hard part is still combining light fit, useful in-lens information and long battery life at mass scale.
Even Realities deserves mention in the same conversation. Its camera-free G1 became the leading waveguide AR-glasses model during the first half of 2025 according to Counterpoint, and the newer G2, which got new styles and accessories in October 2026, continues the same discreet approach. Even Realities raised $150 million at a reported $1 billion valuation in July 2026, according to TechCrunch, and told the Financial Times that it wants to sell hundreds of thousands of units. Those are still ambitions, while Rokid has stronger current shipment evidence.
Rokid therefore ranks higher for us today, especially as waveguides take a much larger share of AR-glasses shipments.
Which VR headset startups still hold up as XR glasses grow?
The VR startups holding up right now are the specialized ones: Varjo in defense, VRChat in social VR and Bigscreen with enthusiasts. Consumer VR headsets are shrinking fast enough that we would no longer build an XR startup ranking around them.
The hardware numbers are bad, even if the size of the drop depends on the tracker. Counterpoint found VR headset shipments fell 18% year over year in Q2 2026, IDC counted a 37.6% fall in VR devices, and Omdia's 38.7% first-half drop in XR headwear came mostly from headsets. The market is concentrated around Meta, leaving independent headset makers with expensive hardware development, limited volumes and a dominant subsidized competitor.
Rec Room gave us the harshest example. The social gaming company shut down on June 1, 2026 after reaching more than 150 million lifetime players and millions of monthly users. Rec Room said its costs kept overwhelming revenue and that it had never found a sustainably profitable model. A huge registered-user number was not enough to save the business.
The surviving VR startups are specialized. Bigscreen serves enthusiasts who buy unusually light premium PC VR headsets. Varjo focuses on defense and simulation, added a Finnish Defence Forces training pilot in October 2026, and plans to assemble its XR-4 headsets in Finland from January 2027. VRChat keeps a deeply engaged social community.
So VR startups are not all dying. The market is shrinking and shifting toward glasses, and the story that VR headsets were about to become the next mass computing platform has largely disappeared from the startup market.
If you want more recent data on this point, please see our latest XR market report.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the XR market, we look at what broke startups before you, so you don't repeat it.
Is VRChat now the clear winner in social VR?
VRChat is currently the clearest private winner in social XR, especially after several much better-funded rivals failed to turn large audiences into durable businesses.
VRChat says its concurrent-user record is nearly 160,000 people. Usage on Steam alone stays high: SteamCharts showed an average of about 43,800 simultaneous Steam players over the 30 days to late October 2026. That figure covers Steam only, not Quest or monthly users, but it shows steady daily engagement. VRChat keeps shipping creator tools too, including native face-tracking support in an SDK update released on 30 October 2026.
Rec Room had attracted more than 150 million players over its lifetime and once carried a $3.5 billion valuation, yet the company still shut down after failing to make the economics work. Meta has also pulled Horizon Worlds away from VR headsets, leaving VRChat with less direct competition for people who actually want a persistent social world in VR.
The important distinction is engagement. A lifetime registration number can become enormous while most people barely return. Concurrent usage tells us how many people choose to be inside a platform at the same moment, which is much harder to inflate with old downloads or one-time curiosity.
We still cannot judge VRChat's profitability because the company does not disclose it, and no cross-platform comparison proves it leads on monthly users or revenue. So “clear winner” is a judgment, not a measured fact. But if the question is which private company has built the strongest surviving social-XR network, VRChat is the easy answer.
Is Varjo the strongest XR startup in defense and enterprise?
Varjo is the strongest XR startup in high-end defense simulation today, and its lead keeps getting easier to defend as it spreads across real military programs.
Varjo says its technology is deployed across more than 120 defense programs in NATO and allied countries. Customers and partners have included Rheinmetall, the US Army, the Finnish Air Force and Patria. In June 2026, Varjo expanded its work with Ukrainian forces into counter-drone simulation. On 29 October 2026, Varjo and the Finnish Defence Forces announced a pilot to develop counter-drone training with Varjo XR-4 headsets. The contract value and headset volume were not disclosed, so this is a pilot, not a large purchase.
The company is investing €44 million into its next generation of defense-focused XR technology, with Business Finland providing €12 million of support, and it says all XR-4 Series headsets will be assembled in Espoo, Finland, starting in January 2027. Varjo's annual revenue reached about €22.7 million in 2025, up roughly 16%, according to Finnish company data.
Those numbers are tiny compared with mass-market consumer electronics. Defense simulation works differently: a relatively small number of programs can support expensive hardware because a simulator replacing aircraft hours, vehicle time or live-fire exercises can save far more than the headset costs.
Varjo's position is narrower than XREAL's, but the customers are unusually serious. We rank it as the clearest enterprise hardware leader in XR.
If you want more recent data on this point, please see our latest XR market report.

Your time is limited. In our research about XR headsets, we put numbers on each part of the market, so you can see where it makes sense to focus.
Which enterprise XR startups are quietly getting real adoption?
ArborXR and RealWear are already getting meaningful enterprise XR adoption, although they solve much less glamorous problems than consumer smart glasses.
ArborXR manages XR devices and software for companies deploying headsets at scale. The company now says its platform is used by more than 5,500 organizations in over 90 countries, including more than 80 Fortune and Global 500 companies, with customers such as UPS, Pfizer, Bank of America and Delta. Some older ArborXR pages still show 3,000, so the larger figure is the current company claim. Its acquisition of InformXR added learning analytics and integrations with more than 500 learning-management systems.
RealWear attacks a different problem. Its rugged, hands-free wearables are built for factories, field service and maintenance rather than immersive entertainment. RealWear says 41 of the Fortune 100 have deployed its devices, and its customer history includes companies such as BMW, Honeywell, Michelin and TotalEnergies. RealWear has not published a new customer count recently, so both companies' figures remain company-stated totals.
The interesting part is that neither company needs consumers to suddenly fall in love with XR. ArborXR gets paid when organizations deploy more headsets from multiple vendors. RealWear gets paid when a worker needs instructions, remote support or documentation without taking both hands off a task. These are mundane use cases compared with the metaverse story, but the purchasing logic is much clearer.
| Startup | What companies buy | Current adoption evidence |
|---|---|---|
| ArborXR | XR fleet management, content deployment and analytics | 5,500+ organizations and 80+ Fortune and Global 500 companies (company-stated) |
| RealWear | Rugged hands-free wearables for frontline workers | Deployed by 41 Fortune 100 companies (company-stated) |
| Varjo | High-fidelity VR/XR simulation | Used across 120+ defense programs; Finnish Defence Forces pilot from October 2026 |
Are XPANCEO and Sesame already real XR leaders?
XPANCEO and Sesame are two of the most exciting XR startups we found, but neither deserves to rank alongside the current commercial leaders yet.
XPANCEO raised $250 million at a $1.35 billion valuation and has developed more than 28 smart-contact-lens prototypes. XPANCEO and ITEN demonstrated a proof of concept for a solid-state microbattery inside a lens, and XPANCEO and JBD are working on a custom micro-LED display for contact lenses. In October 2026, lens-materials maker Contamac said it had partnered with XPANCEO to make the lenses manufacturable and comfortable.
The missing piece is still enormous: XPANCEO has never shown all the critical systems working together in one wearable. Its first public demonstration of an integrated lens combining display, power, connectivity and sensing is planned for early 2027. Until then, the $1.35 billion valuation mostly prices technical potential.
Sesame is much closer on software. Its early conversational-AI voices attracted more than one million people and generated more than five million minutes of conversation within weeks, according to investor Sequoia. Sesame then raised a $250 million Series B, and in October 2026 it opened its voice-agent apps to the public.
The eyewear remains ahead. Sesame showed a preview of its glasses in October 2026 but says they are coming in 2027 and will be made in Japan. We would therefore call XPANCEO and Sesame frontier XR companies rather than current market leaders.

In our market report about XR headsets, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Which XR deep-tech startup looks closest to real deployment?
Distance Technologies currently looks like the XR deep-tech startup making the fastest jump from impressive optics to actual deployment opportunities.
Distance started with glasses-free mixed-reality displays that can place digital information into windshields, visors and other transparent surfaces. The company has focused heavily on defense, where the value is easier to quantify: put navigation, thermal imagery, vehicle data and battlefield information directly into an operator's line of sight.
The progress during 2026 has been unusually concrete. Supacat signed a three-year framework agreement to integrate Distance's technology across its High Mobility Transporter platform family. Distance has also worked with Galvion on helmet systems. In September 2026, auto supplier FORVIA HELLA invested through HELLA Ventures and signed a partnership to develop a mirrorless 3D AR head-up display for cars, with series production as the goal but no date or amount disclosed. Distance also signed a memorandum of understanding with Morpho on spatial computing. No automaker production order has been announced.
Swave Photonics is the other deep-tech company we would keep high on the watchlist. Swave has raised roughly €33 million around its holographic display architecture, with Samsung Ventures participating. Its HXR technology tries to create true holographic images from extremely small CMOS-based pixels, potentially removing some optical compromises found in current AR glasses.
Swave could eventually become an important component supplier. Distance ranks higher today because partners in both defense and automotive are already designing its technology into real platforms.
Does XR funding actually tell us who is winning?
XR funding currently tells us more about where investors think computing is going than about which startups are already winning.
We added the major disclosed rounds across seven of the most visible recent bets: $250 million for XPANCEO, $250 million for Sesame, more than $200 million for VITURE across two rounds, $150 million for Even Realities, roughly $140 million for RayNeo, $100 million for XREAL and about €33 million for Swave Photonics. Together, that is more than $1.1 billion of recent capital.
Almost all of that money went toward glasses, contact lenses or display technology. The funding pattern lines up with the shift in shipment data toward eyewear. Investors clearly expect the next fight in XR to happen much closer to a normal pair of glasses than to the original VR-headset form factor.
But funding produces some strange rankings. XPANCEO and Sesame together account for $500 million despite having no commercial eyewear product yet. ArborXR says it has more than 5,500 organizations on its platform after raising only about $25 million in total. VRChat keeps strong usage without a giant new financing round. RayNeo leads on IDC's shipment count while raising less than VITURE or Even Realities.
So we use funding as evidence of where sophisticated investors are concentrating their bets, while keeping actual adoption higher in the hierarchy.
If you want more recent data on this point, please see our latest XR market report.

If you build or invest in the XR market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
So, what are the top XR startups today?
XREAL is still the top XR startup overall, but RayNeo leads it on shipments and is closest behind, with VITURE third; Rokid, Varjo and VRChat lead very different parts of the XR market.
XREAL keeps first place on the mix of verifiable business evidence and platform position, not on volume. We can see the revenue, units, margins, international exposure and losses. Aura is a flagship Android XR device backed by Google, with a Japanese launch set for 27 November 2026. The company still has to prove profitability, reverse its falling unit sales and turn Aura reservations into delivered units, but its evidence is broader than for any other independent XR player we reviewed.
RayNeo could realistically overtake it. IDC and Omdia both place RayNeo ahead of XREAL on units, IDC saw XREAL's units fall in Q2, and its iO and GT families, on sale since September 2026, broaden the company beyond one product type. VITURE is close behind, with the largest AR-glasses shipments outside China in Counterpoint's Q1 count and Best Buy distribution, a route to mainstream US consumers that most XR startups lack.
Rokid ranks next among consumer companies because lightweight waveguide glasses are becoming a bigger part of the market and Rokid already has one of the category's best-selling products. Varjo owns the clearest high-end defense position. VRChat has built the strongest surviving private social-XR network. ArborXR and RealWear round out the current leaders through enterprise deployments that already exist at meaningful scale.
XPANCEO, Sesame and Swave belong in a separate frontier group, and Distance Technologies sits at its edge with defense and automotive partners. We would watch them closely, but ranking unfinished platforms above companies with actual customers would blur the difference between potential and leadership.
| Rank | Startup | Where it leads | Our current judgment |
|---|---|---|---|
| 1 | XREAL | Consumer AR glasses / Android XR | Best overall mix of business evidence and platform position; Aura has 10,000+ reservations, Japan launch on 27 November 2026, no deliveries reported yet |
| 2 | RayNeo | Consumer XR-glasses shipments | Current shipment leader among startups (IDC Q2 2026: 12.0% vs XREAL 8.4%; 25.2% of XR glasses) |
| 3 | VITURE | International display glasses | Strongest challenger outside China, especially in US retail |
| 4 | Rokid | Lightweight AI + AR glasses | Strongest current waveguide contender; first in Counterpoint's H1 2026 AR-and-AI-glasses count (company-cited) |
| 5 | Varjo | Defense and simulation XR | Clear leader in high-end professional XR |
| 6 | VRChat | Social XR | Strongest surviving private social-XR network |
| 7 | ArborXR | Enterprise XR infrastructure | Quietly becoming the management layer for large XR deployments |
| 8 | RealWear | Industrial wearables | One of the most proven frontline XR businesses |
| 9 | Distance Technologies | Defense and automotive visual intelligence | Deep-tech XR startup moving fastest toward real deployments; no production order yet |
| 10 | Even Realities | Premium lightweight display glasses | Differentiated challenger with a credible waveguide product; $150M raised at a reported $1B valuation |
| Frontier | XPANCEO | Smart contact lenses | Huge technical upside, integrated lens demo planned for early 2027 |
| Frontier | Sesame | AI-native eyewear | Voice-agent apps live, glasses coming in 2027 |
| Frontier | Swave Photonics | Holographic displays | Promising enabling technology, still early commercially |
If you want more recent data on this point, please see our latest XR market report.
Our methodology
This analysis answers one question: what are the top startups in the XR market today? Instead of relying on funding, visibility or a vague sense of which companies seem important, we broke the market into a few dimensions that actually separate the leaders: where XR demand is moving, commercial traction, current momentum, quality of evidence, segment leadership and near-term execution potential.
We started with market direction. The latest first-half and Q2 2026 shipment data show that XR growth is concentrated in smart glasses and AR eyewear, while traditional VR and mixed-reality headsets keep falling. That changes which companies deserve the most attention before we even get to the company-level ranking.
We then looked at the strongest recent evidence available for each business model. For consumer hardware, that meant shipments, revenue, pricing, margins, distribution and product adoption. For enterprise XR, we cared more about repeat deployments and customer depth. For social platforms, current engagement mattered more than lifetime registrations. For deep-tech companies, we looked for technical milestones that were already moving into integration or deployment.
We did not treat every datapoint equally. Completed sales, current usage and recurring enterprise deployments carried more weight than orders, pilots, memorandums of understanding, planned launches or prototype counts. Shipment shares from IDC, Omdia and Counterpoint use different definitions, so we always name the firm behind a share and compare them side by side rather than combining or averaging them. That is also why IDC can show the AR/VR market growing in Q2 2026 while Omdia shows XR headwear shrinking in the first half. Funding was useful mainly for showing where investors are concentrating capital.
We also compared companies inside their own segment before comparing them across XR. A defense simulation company should not lose simply because it ships fewer units than a consumer-glasses brand, and a social platform should not win because it once accumulated a very large lifetime user count. The underlying economics are different, so the evidence has to be read differently too.
Current leadership and frontier potential were kept separate. XPANCEO, Sesame and Swave Photonics have credible technical or financial backing, but we did not rank unfinished XR platforms above companies with shipped products, active users or repeat deployments. Distance Technologies ranks higher among deep-tech challengers because its technology is already moving into concrete defense and automotive programs.
Key sources used for the market-level comparisons include Omdia on first-half 2026 XR headwear shipments, Counterpoint Research's quarterly XR market share tracker, Counterpoint Research on Q1 2026 intelligent-eyewear and AR-glasses shipments and IDC's AR/VR market tracker.
For company-level evidence, we relied heavily on primary or near-primary sources where they added specific, checkable numbers: XREAL's Hong Kong listing application for revenue, units, margins and international exposure; Road to VR on the Aura launch for pricing and markets; TCL Electronics' 2025 annual report and RayNeo's iO and GT launch recap for RayNeo; VITURE's financing disclosure and retail footprint; Varjo's defense program update; ArborXR's adoption figures; XPANCEO's financing announcement; Sequoia's early Sesame usage data; Distance Technologies' Supacat framework agreement; and FORVIA HELLA's partnership with Distance.
For the most recent data, we used IDC's Q2 2026 AR/VR tracker summary, company releases and launch notices, including NTT Docomo's 2 November 2026 Aura release and XREAL Japan's Aura launch notice, plus company pages such as ArborXR's and Varjo's production update. Aura's reservation count is treated as a reservation figure, never as sales or shipments.
The final ranking is not a mechanical score. It is a structured aggregation of the freshest relevant evidence available through early November 2026, with more weight placed on hard commercial proof and current adoption than on valuation, fundraising or technological ambition alone.

In our report covering the XR market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us