What’s funding like in the military drones market right now?
Building a startup or looking for your next investment in military drones? Our report gives you the full picture.
Summary
Military drone funding is growing fast, but new companies are finding it harder to get their first check. We tracked 68 deals raising at least $16.1B over the last 12 months, compared with 46 deals raising at least $4.8B in the 12 months before. Anduril raised $5.0B in a late-stage round in May 2026, the biggest deal of the current period.
More startups are getting money. The number of funded companies increased 21%, while deal count rose 48%. The median disclosed round also climbed to $32M from $11M.
A few enormous checks do much of the work, though. Take out the rounds above $100M, and the remaining funding stayed flat. The headline jump is real, but it looks far less dramatic for smaller companies.
Smaller checks are holding up better than that might suggest. Excluding rounds above $50M, companies raised at least $590M, up from at least $291M. There's growth below the biggest names.
The catch is who gets funded. First financings fell from 11 deals to 8 deals. Meanwhile, follow-on financings increased from 33 deals to 56 deals. Investors are giving more money to businesses they already know.
Those businesses are coming back sooner. The median measured gap between rounds fell to 8 months from 10 months. Companies can raise again quickly when they have a convincing case for expansion.
Aircraft and the software controlling them are both drawing money. ISR drones lead in number of deals, while strike drones attract the most disclosed capital. Mission software and interceptors also have substantial funding behind them.
Europe now produces more separate military drone financings than North America, even though North America receives more money. Ukraine looks different again: it buys and builds drones at scale, but relatively little of that activity appears as domestic startup equity rounds.
Real military customers are helping drive interest. The United States buys drones through field competitions; Ukraine uses combat results to pick equipment; NATO has opened a faster way to buy selected counter-drone systems. A place in one of these programs still doesn't guarantee sales for every startup.
So the military drone market is healthier, but the benefits are uneven. Companies that can prove their aircraft work and deliver them repeatedly have much better access to large checks. Advent International led 2 of the biggest rounds, worth a combined $2.7B. Founders still get a chance, yet fewer are getting their first financing.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the military drone market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the military drones market over the last 24 months
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our military drones market report.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| Arcanus Aerial Systems | ISR Drones | November 2026 | Series A | $27M+ | Integrates and manufactures allied military UAV systems for reconnaissance and combat-support missions in Canada. | North America | Not disclosed | Canada | |
| UFORCE | Strike Drones | November 2026 | Series A | $700M | Combat-tested autonomous military drone systems | Europe | Valor Equity Partners, UK National Wealth Fund | United Kingdom | |
| SE3 | Drone Mission & Control Systems | November 2026 | Series A | $30M | Develops onboard spatial AI and natural-language mission software that controls military drones even when GPS is denied. | Europe | Accel | Germany | |
| Shield AI | Drone Mission & Control Systems | November 2026 | Series D+ | $1.0B | AI autonomy software and military drones | North America | Disruptive, Innovation X Capital | United States | |
| Skydio | ISR Drones | November 2026 | Series D+ | $255M | Autonomous drones for defense and inspection | North America | Axon Enterprise | United States | |
| Arcanus Aerial Systems | ISR Drones | October 2026 | Unknown | $500K | Integrates and manufactures allied military UAV systems for reconnaissance and combat-support missions in Canada. | North America | Not disclosed | Canada | |
| Beyond Vision | ISR Drones | October 2026 | Series A | $32M+ | Manufactures AI-enabled military drones and ISR unmanned platforms. | Europe | Índico Capital Partners, Lince Capital | Portugal | |
| Buntar Aerospace | ISR Drones | October 2026 | Unknown | $16M | Reconnaissance drones and battlefield software | Europe | Freedom Fund | Ukraine | |
| Certo Aerospace | Cargo & Logistics Drones | October 2026 | Unknown | ~$6.6M | Builds the CAPSTONE heavy-lift autonomous VTOL aircraft for military logistics and support missions. | Europe | Not disclosed | United Kingdom | |
| Monopulse | ISR Drones | October 2026 | Unknown | $2.3M+ | Electronic-warfare-resistant reconnaissance drones | Europe | Coinvest Capital | Lithuania | |
| Fortem Technologies | Interceptor Drones | September 2026 | Series B | $50M | Radar-guided autonomous drone interception systems | North America | Lockheed Martin Ventures | United States | |
| Occam Industries | Drone Mission & Control Systems | September 2026 | Growth Equity | $4.2M | Autonomous control software for military drones | Europe | North Ventures | United Kingdom | |
| DOD Solution | Drone Mission & Control Systems | September 2026 | Seed | $2.1M | Onboard autonomy for unmanned systems | Europe | Not disclosed | Ukraine | |
| TEKEVER | ISR Drones | September 2026 | Series D+ | ~$580M | AI-powered military surveillance drones | Europe | UC Investments, Baillie Gifford | Portugal | |
| AD Systems | ISR Drones | September 2026 | Series A | ~$9.4M | Stealth military reconnaissance drone manufacturing | Asia-Pacific | LB Investment | South Korea | |
| Agilis Air | ISR Drones | September 2026 | Seed | $1.4M | Autonomous drones for defense missions | North America | Not disclosed | United States | |
| Mach Industries | Strike Drones | September 2026 | Series C | $600M | Military attack drones and aerial interceptors | North America | Not disclosed | United States | |
| XTEND | Drone Mission & Control Systems | September 2026 | Growth Equity | $68M | AI-assisted military reconnaissance and tactical drones | North America | Not disclosed | United States | |
| AITAN | Drone Mission & Control Systems | September 2026 | Series A | $41M | Edge-AI autonomous defense robotic systems | North America | Deep33, Dell Technologies Capital | United States | |
| PDW | ISR Drones | September 2026 | Growth Equity | $52M | American-made military unmanned aircraft systems | North America | Not disclosed | United States | |
| Airbility | Interceptor Drones | September 2026 | Series A | $4.7M | High-speed eVTOL counter-drone aircraft | Asia-Pacific | Sazze Partners | South Korea | |
| Swarm Defense Technologies | Swarm & Collaborative Drones | September 2026 | Unknown | $2M | Low-cost coordinated military drone swarms | Asia-Pacific | Not disclosed | India | |
| M-Fly | Drone Mission & Control Systems | September 2026 | Unknown | Undisclosed | Laser guidance and UAV gimbals | Europe | MITS Capital | Ukraine | |
| Easy Aerial | ISR Drones | August 2026 | Series B | $20M | Autonomous tethered surveillance drone systems | North America | Insight Partners | United States | |
| Mara | Interceptor Drones | August 2026 | Seed | $7M | Autonomous kinetic drone interception | North America | Khosla Ventures | United States | |
| Neros Technologies | Strike Drones | August 2026 | Series C | $250M | FPV strike and interceptor drones | North America | Sequoia Capital, American Strategic Technology Fund | United States | |
| Cambridge Aerospace | Interceptor Drones | August 2026 | Series C | $300M | Low-cost drone and missile interceptors | Europe | DFJ Growth | United Kingdom | |
| Helsing | Loitering Munitions | July 2026 | Series D+ | $1.8B | AI-powered autonomous defense systems | Europe | Dragoneer Investment Group, Lightspeed Venture Partners | Germany | |
| Quantum Systems | ISR Drones | July 2026 | Series D+ | $1.2B | AI-powered military unmanned aerial systems | Europe | Blackstone, Noteus, Airbus Ventures, Advent International | Germany | |
| Six Robotics | Swarm & Collaborative Drones | June 2026 | Seed | ~$14M | Swarm autonomy software for unmanned systems | Europe | DTCP | Norway | |
| STARK Defence | Loitering Munitions | June 2026 | Series C | $550M | Autonomous military drones and weapons | Europe | Sequoia Capital, Founders Fund | Germany | |
| Acodyne | Cargo & Logistics Drones | June 2026 | Seed | Undisclosed | Autonomous military-use VTOL cargo aircraft | Europe | Gungnir Capital, PSV Hafnium | Denmark | |
| PDKINEMATICS | Drone Mission & Control Systems | June 2026 | Seed | $2.2M | Precision-guidance kits for UAV munitions | Europe | Coinvest Capital, Iron Wolf Capital | Lithuania | |
| Alta Ares | Interceptor Drones | June 2026 | Series A | $57M | AI-powered battlefield air defense | Europe | Air Street Capital | France | |
| Mach Industries | Strike Drones | June 2026 | Series C | $300M | Military attack drones and aerial interceptors | North America | Infinite Capital, Ribbit Capital | United States | |
| Askari Defense | Interceptor Drones | May 2026 | Seed | $11M | Hand-launched autonomous drone interceptors | North America | Builders VC | United States | |
| Anduril | Strike Drones | May 2026 | Series D+ | $5.0B | Autonomous defence systems and weapons | North America | Thrive Capital, Andreessen Horowitz | United States | |
| Darkhive | ISR Drones | May 2026 | Series B | $30M | Autonomous tactical reconnaissance drones | North America | RTX Ventures | United States | |
| Apollyon Dynamics | Strike Drones | May 2026 | Seed | ~$480K | Military drones for defense operations | Asia-Pacific | Naandi Ventures | India | |
| Firestorm Labs | Strike Drones | April 2026 | Series B | $82M | Expeditionary drone manufacturing and UAS | North America | Washington Harbour Partners | United States | |
| Skydio | ISR Drones | April 2026 | Series D+ | $110M | Autonomous drones for defense and inspection | North America | Not disclosed | United States | |
| Swarm Defense Technologies | Swarm & Collaborative Drones | April 2026 | Unknown | $1.4M | Low-cost coordinated military drone swarms | Asia-Pacific | Not disclosed | India | |
| Cambridge Aerospace | Interceptor Drones | April 2026 | Series B | $200M | Low-cost drone and missile interceptors | Europe | Elad Gil, Spark Capital | United Kingdom | |
| Shield AI | Drone Mission & Control Systems | March 2026 | Series D+ | $1.5B | AI autonomy software and military drones | North America | Advent International, JPMorganChase Strategic Investment Group | United States | |
| PDW | ISR Drones | March 2026 | Series B | $110M+ | American-made military unmanned aircraft systems | North America | Ondas Holdings | United States | |
| Buntar Aerospace | ISR Drones | March 2026 | Seed | $10M | Reconnaissance drones and battlefield software | Europe | Axon Enterprise | Ukraine | |
| Swarm Aero | Swarm & Collaborative Drones | March 2026 | Series A | $35M | Large autonomous military aircraft | North America | Two Sigma Ventures, Silent Ventures | United States | |
| Orqa | Strike Drones | March 2026 | Series A | $14M | FPV drones and defence electronics | Europe | Expeditions Fund | Croatia | |
| UFORCE | Strike Drones | March 2026 | Seed | $50M | Combat-tested autonomous military drone systems | Europe | Shield Capital, Lakestar | United Kingdom | |
| FlyFocus | ISR Drones | February 2026 | Seed | $5M | Military UAV design and manufacturing | Europe | ffVC | Poland | |
| TYTAN Technologies | Interceptor Drones | February 2026 | Series A | $33M | AI-powered autonomous drone interceptors | Europe | Armira, NATO Innovation Fund | Germany | |
| MaXon Systems | Interceptor Drones | February 2026 | Seed | Undisclosed | Autonomous interceptor drones for air defense | Europe | Green Flag Ventures | Ukraine | |
| Airlogix | ISR Drones | February 2026 | Seed | $3.3M | Unmanned aerial systems for defense | Europe | bValue Fund | Ukraine | |
| Farsight Vision | Drone Mission & Control Systems | February 2026 | Seed | ~$8.6M | Drone-derived 3D intelligence and mapping | Europe | Axon Enterprise, SmartCap | Estonia | |
| Occam Industries | Drone Mission & Control Systems | February 2026 | Seed | $3.3M | Autonomous control software for military drones | Europe | Presto Tech Horizons | United Kingdom | |
| XTEND | Drone Mission & Control Systems | February 2026 | Growth Equity | $42M | AI-assisted military reconnaissance and tactical drones | North America | Not disclosed | United States | |
| STARK Defence | Loitering Munitions | February 2026 | Unknown | Undisclosed | Autonomous military drones and weapons | Europe | Founders Fund | Germany | |
| Grid Aero | Cargo & Logistics Drones | January 2026 | Series A | $20M | Autonomous cargo aircraft for military missions | North America | Bison Ventures, Geodesic Capital | United States | |
| Twentyfour Industries | ISR Drones | January 2026 | Unknown | $12M | Mass-produced modular military drones | Europe | Not disclosed | Germany | |
| HoverIt | Loitering Munitions | January 2026 | Seed | $500K | Long-range drones for defense missions | Asia-Pacific | Not disclosed | India | |
| Harmattan AI | Drone Mission & Control Systems | January 2026 | Series B | $200M | Autonomous military drones and air defence | Europe | Dassault Aviation | France | |
| Shield AI | Drone Mission & Control Systems | December 2025 | Series D+ | $300M | AI autonomy software and military drones | North America | Not disclosed | United States | |
| Heven AeroTech | ISR Drones | December 2025 | Series B | $100M | Hydrogen-powered long-endurance military drones | North America | IonQ | United States | |
| Quantum Systems | ISR Drones | November 2025 | Series C | ~$209M | AI-powered military unmanned aerial systems | Europe | Balderton Capital | Germany | |
| Thermopylae Aerospace | Interceptor Drones | November 2025 | Seed | $1.6M | Autonomous interceptor drones for counter-UAS | North America | Naval Ravikant | United States | |
| M-Fly | Drone Mission & Control Systems | November 2025 | Seed | $1.4M | Laser guidance and UAV gimbals | Europe | Not disclosed | Ukraine | |
| PDW | ISR Drones | November 2025 | Series B | $35M | American-made military unmanned aircraft systems | North America | Ondas Holdings | United States | |
| Auterion | Drone Mission & Control Systems | November 2025 | Growth Equity | Undisclosed | Autonomy software for military drone fleets | North America | Not disclosed | United States | |
| Neros Technologies | Strike Drones | November 2025 | Series B | $75M | FPV strike and interceptor drones | North America | Sequoia Capital | United States | |
| Vermeer | Drone Mission & Control Systems | October 2025 | Series A | $10M | GPS-independent drone navigation technology | North America | Draper Associates | United States | |
| Fuvex | ISR Drones | October 2025 | Series A | $2M | Long-range drones for infrastructure inspections | Europe | Sodena | Spain | |
| Hoverfly Technologies | ISR Drones | October 2025 | Series B | $20M | Tethered drones for persistent aerial surveillance | North America | Leonardo DRS, Korea Robot Manufacturing | United States | |
| Tycho AI | Drone Mission & Control Systems | October 2025 | Series A | $10M | AI navigation for unmanned vehicles | North America | FirstMark | United States | |
| Orbotix Industries | Swarm & Collaborative Drones | October 2025 | Seed | $7.2M | AI-powered autonomous defense drone systems | Europe | BVVC | Poland | |
| Unmannd | Cargo & Logistics Drones | September 2025 | Seed | $2M | Autonomous UAVs for defense operations | Asia-Pacific | Speciale Invest, Accel | India | |
| Auterion | Drone Mission & Control Systems | September 2025 | Series B | $105M | Autonomy software for military drone fleets | North America | Bessemer Venture Partners | United States | |
| NORDA Dynamics | Drone Mission & Control Systems | September 2025 | Seed | $1M | Autonomous drone navigation for defense | Europe | Varangians | Ukraine | |
| Swarmer | Swarm & Collaborative Drones | September 2025 | Series A | $15M | Autonomous drone swarm control software | Europe | Broadband Capital Investments | Ukraine | |
| Vector | Strike Drones | September 2025 | Series A | $61M | Military drones and warfare services | North America | Pelion Venture Partners, Harpoon Ventures, Point72 Ventures, Lightspeed Venture Partners, Run Ventures, Dauntless Ventures, GSB Backers, Alumni Ventures, Kickstart Fund, Shield Capital, R7, Cambria Group, Stony Lonesome Group | United States | |
| STARK Defence | Loitering Munitions | August 2025 | Unknown | $62M | Autonomous military drones and weapons | Europe | Sequoia Capital | Germany | |
| Grid Aero | Cargo & Logistics Drones | August 2025 | Seed | $6M | Autonomous cargo aircraft for military missions | North America | Calibrate Ventures, Ubiquity Ventures | United States | |
| MaXon Systems | Interceptor Drones | August 2025 | Seed | $300K | Autonomous interceptor drones for air defense | Europe | Freedom Fund | Ukraine | |
| AD Systems | ISR Drones | August 2025 | Series A | $2.1M | Stealth military reconnaissance drone manufacturing | Asia-Pacific | Not disclosed | South Korea | |
| Firestorm Labs | Strike Drones | July 2025 | Series A | $35M | Expeditionary drone manufacturing and UAS | North America | New Enterprise Associates | United States | |
| XTEND | Drone Mission & Control Systems | July 2025 | Series B | $30M | AI-assisted military reconnaissance and tactical drones | North America | Aliya Capital Partners, Protego Ventures | United States | |
| Nordic Air Defence | Interceptor Drones | July 2025 | Seed | $3M | Software-defined low-cost drone interceptors | Europe | Inflection | Sweden | |
| Cambridge Aerospace | Interceptor Drones | July 2025 | Series A | $100M | Low-cost drone and missile interceptors | Europe | Not disclosed | United Kingdom | |
| Thermopylae Aerospace | Interceptor Drones | July 2025 | Seed | $2.5M | Autonomous interceptor drones for counter-UAS | North America | Not disclosed | United States | |
| Raphe mPhibr | ISR Drones | June 2025 | Series B | $100M | Military UAVs and autonomous systems | Asia-Pacific | General Catalyst | India | |
| Helsing | Loitering Munitions | June 2025 | Series D+ | $660M | AI-powered autonomous defense systems | Europe | Prima Materia | Germany | |
| Mach Industries | Strike Drones | June 2025 | Series B | $100M | Military attack drones and aerial interceptors | North America | Khosla Ventures, Bedrock | United States | |
| Anduril | Strike Drones | June 2025 | Series D+ | $2.5B | Autonomous defence systems and weapons | North America | Founders Fund | United States | |
| Lendurai | Drone Mission & Control Systems | June 2025 | Seed | $6.4M | GPS-denied autonomous UAV navigation | Europe | Expeditions Fund, HCVC, Vsquared Ventures | Estonia | |
| Trypillian | Strike Drones | May 2025 | Seed | $5M | Ukrainian military drones and systems | Europe | Brooks Newmark | Ukraine | |
| Alta Ares | Interceptor Drones | May 2025 | Seed | $2.2M | AI-powered battlefield air defense | Europe | Expansion, Starburst Ventures | France | |
| TEKEVER | ISR Drones | May 2025 | Series C | ~$80M | AI-powered military surveillance drones | Europe | Ventura Capital | Portugal | |
| Quantum Systems | ISR Drones | May 2025 | Series C | ~$181M | AI-powered military unmanned aerial systems | Europe | Balderton Capital | Germany | |
| Vermeer | Drone Mission & Control Systems | May 2025 | Unknown | $3.5M | GPS-independent drone navigation technology | North America | Not disclosed | United States | |
| TYTAN Technologies | Interceptor Drones | April 2025 | Seed | $17M | AI-powered autonomous drone interceptors | Europe | OTB Ventures, Visionaries Club | Germany | |
| Theseus | Drone Mission & Control Systems | April 2025 | Seed | $4.3M | Autonomous defense drones and navigation systems | North America | First Round Capital | United States | |
| Askari Defense | Interceptor Drones | April 2025 | Unknown | $1.3M | Hand-launched autonomous drone interceptors | North America | Not disclosed | United States | |
| SpearUAV | Loitering Munitions | March 2025 | Unknown | Undisclosed | Encapsulated military tactical AI loitering munitions; UVision subsidiary | Middle East | Deep Insight | Israel | |
| Quantum Aero | Drone Mission & Control Systems | March 2025 | Seed | $2.7M | AI-guided autonomous defense drones | Asia-Pacific | Not disclosed | South Korea | |
| Neros Technologies | Strike Drones | March 2025 | Series A | $35M | FPV strike and interceptor drones | North America | Vy Capital | United States | |
| Shield AI | Drone Mission & Control Systems | March 2025 | Series D+ | $240M | AI autonomy software and military drones | North America | L3Harris Technologies, Hanwha Asset Management | United States | |
| Alpine Eagle | Interceptor Drones | March 2025 | Seed | ~$11M | Airborne autonomous counter-drone defense systems | Europe | IQ Capital | Germany | |
| PDW | ISR Drones | March 2025 | Series A | $16M | American-made military unmanned aircraft systems | North America | Squadra Ventures | United States | |
| M-Fly | Drone Mission & Control Systems | March 2025 | Seed | $1.3M | Laser guidance and UAV gimbals | Europe | Not disclosed | Ukraine | |
| Evolve Dynamics | ISR Drones | March 2025 | Growth Equity | $768K | All-weather ISR unmanned aircraft systems | Europe | Not disclosed | United Kingdom | |
| Airbility | Interceptor Drones | January 2025 | Unknown | $1.7M | High-speed eVTOL counter-drone aircraft | Asia-Pacific | Samho Green Investment | South Korea | |
| Harmattan AI | Drone Mission & Control Systems | January 2025 | Series A | $30M | Autonomous military drones and air defence | Europe | FirstMark | France | |
| Orqa | Strike Drones | December 2024 | Seed | $6.4M | FPV drones and defence electronics | Europe | Lightspeed Venture Partners | Croatia | |
| TEKEVER | ISR Drones | November 2024 | Series B | $77M | AI-powered military surveillance drones | Europe | Baillie Gifford, NATO Innovation Fund | Portugal | |
| Skydio | ISR Drones | November 2024 | Series D+ | $170M | Autonomous drones for defense and inspection | North America | KDDI, Axon Enterprise | United States |

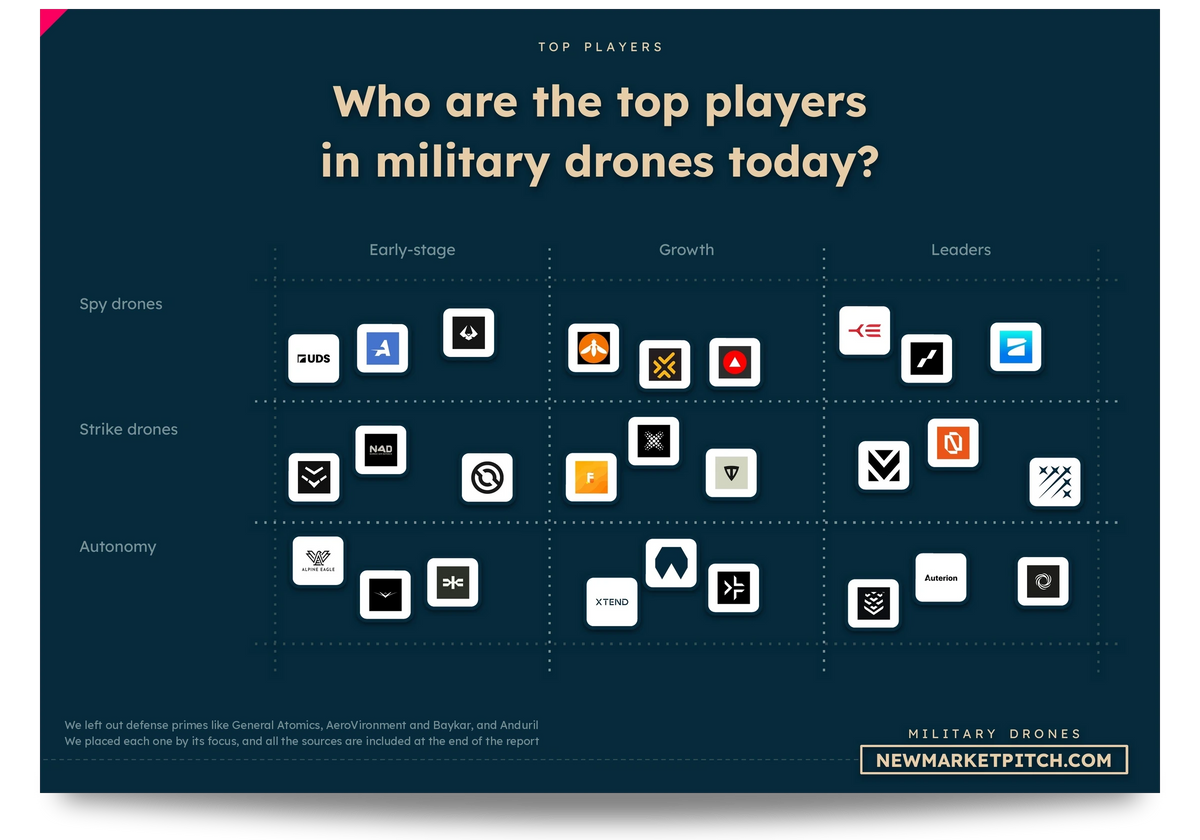
In our research about military drones, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is military drone funding actually healthier than before?
Yes. Military drone startups are raising more money across more deals and more companies, even if the biggest checks make the boom look bigger.
In the last 12 months, we counted 68 financings involving 52 companies and at least $16.1B of disclosed capital. The 12 months before brought 46 financings involving 43 companies and at least $4.8B. Total funding rose 236%. That is a big jump, and the growth in companies funded shows it reaches beyond a few giants.
Military customers have become easier for investors to identify. The U.S. Drone Dominance Program chooses aircraft through military-run flight tests and then places orders with winning suppliers. The program also allows unsuccessful candidates to apply again. That gives both established and newer drone makers a practical way to compete for purchases.
But the financing market has an obvious weak spot: fewer companies are raising their first outside round. The market is growing and has real buyers, but that doesn't make it easy for every founder.
Would military drone funding still look strong without giant rounds?
Without rounds above $100M, military drone funding is flat, although checks below $50M still grew strongly.
Without rounds above $100M, companies raised at least $948M in the last 12 months, versus at least $946M in the 12 months before. That is 0% growth. Across all sizes, disclosed funding rose 236%. Big deals therefore explain much of the change in dollars, even though they do not explain the increase in the number of companies funded.
The smaller end tells a different story. Excluding rounds above $50M, the total reached at least $590M, compared with at least $291M previously, up 103%. This is why calling the entire boom an illusion goes too far. Smaller raises grew too, but they did not follow the same pattern as the enormous late-stage checks.
Anduril's $5.0B late-stage round in May 2026 is the clearest example of how one factory-scale defense company can move the total. Its Arsenal-1 project in Ohio calls for a very different level of spending from an early drone developer. We see stronger funding below the giants, just nowhere near the headline rate.
Are more military drone companies getting funded, or only the familiar names?
More military drone startups are securing financing today, but many of the additional rounds are going to companies that already raised money.
The last 12 months covered 52 funded companies, compared with 43 in the 12 months before. At the same time, 14 companies raised more than once, versus 3 previously. The share receiving repeated financings rose from 7% to 27%. Both trends are real: the pool of funded businesses widened, and the busiest recipients came back more often.
Shield AI raised $300M in December 2025, a $1.5B Series D+ in March 2026 and a $1.0B Series D+ in November 2026. Quantum Systems secured ~$209M in a Series C in November 2025, followed by a $1.2B Series D+ in July 2026. UFORCE also raised twice in the period. Those examples explain why deal count can rise faster than the number of companies reaching investors.
Investors clearly still want new suppliers. Yet a startup getting its first round and an established supplier raising again are having very different experiences in this market.
Are military drone investors putting most of their money into follow-on rounds?
Yes. Military drone investors are overwhelmingly funding companies that have already raised, and that preference has become stronger.
Follow-on financings accounted for 56 deals and at least $16.0B of disclosed capital in the last 12 months. The 12 months before recorded 33 follow-on deals and $4.8B. Their share of deals rose from 72% to 82%. New rounds are increasingly part of an ongoing relationship, rather than the first outside check a company receives.
There are practical reasons a second or third round can be easier to evaluate. Skydio announced a U.S. Army order for X10D aircraft in March 2026 and expanded a separate Air Force program in May. PDW has been building out its manufacturing operation. Both developments give prospective investors more to judge than a prototype, although neither proves why any particular financing happened.
Follow-on money can help turn a tested aircraft into a product delivered repeatedly. The concern is what happens to companies that have not yet made it through that first financing.

In our market report about military drones, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Can a brand-new military drone startup still get funded?
A new military drone startup can still get funded, but the first round is harder to win than before.
We found 8 first financings over the last 12 months, down from 11 in the 12 months before. Their share of deals dropped from 24% to 12%. The money behind first rounds increased to $77M from $38M, so fewer entrants did not mean smaller total checks. It meant that entry became less common while the wider market grew.
New founders still have useful examples. UFORCE raised a $50M Seed round in March 2026 as its first financing. Mara raised a $7M Seed round in August 2026 for autonomous drone interception. Six Robotics' ~$14M Seed round in June 2026 backed software for coordinating unmanned aircraft. These are different businesses with different customers, which is more encouraging than one isolated exception.
Programs such as NATO DIANA can help companies test technology and meet potential military customers. A place in an accelerator is not venture funding, however. For a first-time founder, the opportunity remains real and the competition for that initial check looks tougher.
Have military drone investors stopped funding seed-stage companies?
No. Military drone seed financing is still active; the bigger change is how many later rounds are happening alongside it.
Seed investors backed 18 deals in the last 12 months, versus 16 in the 12 months before. Series A recorded 12 deals versus 11. Yet among deals with a named stage, the early-stage share fell from 66% to 51%, while later-stage deals rose from 34% to 49%. The market has more activity at both ends, and rounds beyond Series A now make up almost half of the deals with a named stage.
That fits the way buyers are testing suppliers. Ukraine is ordering drones based on battlefield performance, while the U.S. military uses practical competitions to assess candidates. These programs do not require a venture-backed company to have reached a particular funding stage. They do make it easier to distinguish a promising design from an aircraft that can actually work in service.
The table below shows military drone rounds by stage in each comparison period, sorted by current disclosed capital.
| Stage | Last 12m deals | Before deals | Last 12m capital |
|---|---|---|---|
| Series D+ | 9 | 4 | $11.7B |
| Series C | 6 | 2 | $2.2B |
| Series A | 12 | 11 | $1.0B+ |
| Series B | 9 | 7 | $827M+ |
| Growth Equity | 5 | 1 | $166M+ |
| Seed | 18 | 16 | $122M+ |
| Unknown | 9 | 5 | $41M+ |
Are military drone startups raising their next round faster now?
Yes. Military drone companies that raise again are doing so sooner, based on the round-to-round gaps we can observe.
The median measured interval between financings shortened from 10 months in the 12 months before to 8 months in the last 12 months. Gaps shorter than 12 months accounted for 67% of the observed intervals, up from 55%. Those shorter than 18 months reached 90%, compared with 74% earlier. Our comparison covers 75% of eligible gaps in the current period and 67% in the earlier one. These percentages refer to gaps between rounds, not the share of companies raising.
Mach Industries raised $300M in a Series C in June 2026 and another $600M Series C in September 2026. Shield AI and Quantum Systems also returned quickly. Raising twice does not automatically mean a startup is running out of money. It may be expanding factories, funding more engineers or responding to new orders, but the round records alone cannot tell us which explanation applies.
The practical result is that successful military drone developers can return for capital much sooner. Whether those checks produce durable businesses depends on delivery and repeat customers.

Our document detailing everything you need to know about military drone gets updated several times a month, so you always get the latest view of where things stand.
Is military drone funding steady now, or still unpredictable?
Military drone funding is arriving more regularly, but the biggest dollar totals still come in bursts.
Across the last 12 months, a completed month had a median of 4 deals and $577M in disclosed financing. In the 12 months before, the corresponding figures were 5 deals and $70M. The typical completed month did not have more transactions. It had much more money moving through the rounds that happened. September 2026 was the busiest current-period month with 13 deals, while May 2026 led in total capital.
A founder should not mistake a huge month for a guarantee that the next investor meeting will be easy. One large late-stage round can change the monthly dollar total without opening many new opportunities for small companies. Defense buyers also order aircraft in batches, depending on trials and operational needs.
Still, it would be wrong to call this a one-off spike. Our comparison shows more deals and funded companies across the full period. The timing remains uneven, as defense procurement and private fundraising both move in starts and stops.
Is AI drone software getting more funding than military aircraft?
Not overall. Military drone autonomy software is getting much bigger checks, but aircraft makers still attract more disclosed money.
Drone mission and control systems raised at least $3.2B across 16 deals in the last 12 months, compared with $444M across 12 deals in the 12 months before. The category's share of disclosed capital rose from 9% to 20%, even though its share of deals slipped from 26% to 24%. Investors are clearly willing to write much larger checks for software that actually controls aircraft.
Shield AI shows why aircraft and code are often hard to separate. It builds V-BAT drones and Hivemind autonomy. In May 2026, the company announced that the U.S. military had chosen Hivemind to help groups of LUCAS attack drones coordinate in flight. Auterion takes a more software-centered approach to managing drone fleets, while Quantum Systems has been expanding aircraft production.
Strike drone manufacturers still drew $7.0B of disclosed capital in the current period. Military buyers need aircraft to fly missions and software to help them do it. The money is following both.
Are investors backing reconnaissance drones more than attack drones?
By deal count, yes. Military reconnaissance drones now receive more separate investments, while attack-drone companies raise more money overall.
ISR drones attracted 22 deals involving 16 companies in the last 12 months, compared with 10 deals involving 9 companies in the 12 months before. Their share of deals rose from 22% to 32%. Strike drones recorded 9 deals and $7.0B in the current period. That difference tells us investors are backing a wider range of surveillance companies, even while a smaller number of strike-drone raises dominate the dollar total.
Customers have reasons to buy both. Skydio's March 2026 U.S. Army order covered more than 2,500 X10D reconnaissance drones. Shield AI was selected in April 2026 to compete for U.S. Navy surveillance services using V-BAT. Helsing said in July 2026 that its HX-2 attack drones are deployed in Ukraine. Reconnaissance and attack drones solve different battlefield problems, so one does not need to displace the other for funding to grow.
The table below shows the military drone categories, ordered by current disclosed capital.
| Category | Last 12m capital | Before capital | Last 12m deals |
|---|---|---|---|
| Strike Drones | $7.0B | $2.8B | 9 |
| Drone Mission & Control Systems | $3.2B+ | $444M | 16 |
| ISR Drones | $2.8B+ | $649M | 22 |
| Loitering Munitions | $2.4B+ | $722M+ | 4 |
| Interceptor Drones | $664M+ | $138M | 10 |
| Swarm & Collaborative Drones | $52M | $22M | 4 |
| Cargo & Logistics Drones | $27M+ | $8M | 3 |

In our report covering the military drone market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Are military drone interceptors finally getting serious investment?
Yes. Military interceptor drone startups now attract far more than small experimental rounds.
Interceptor drone developers raised at least $664M in 10 deals over the last 12 months, compared with $138M in 9 deals during the 12 months before. Cambridge Aerospace secured a $300M Series C in August 2026, Alta Ares a $57M Series A in June 2026 and Fortem Technologies a $50M Series B in September 2026. These businesses build flying interceptors that can destroy hostile drones. They are different from companies that only sell radar or radio jammers.
There is a clear route to customers. In November 2026, NATO opened its counter-drone marketplace, selecting products from Alta Ares, Quantum Systems and other suppliers. The marketplace lets allies order selected systems without starting another tender. Quantum Systems also announced an interceptor-drone contract for Ukraine in March 2026.
A marketplace listing does not guarantee future orders. But it puts dedicated interceptors much closer to normal military purchasing, which helps explain why investors are backing them with larger checks.
Does Europe or North America lead military drone funding over the last 12 months?
Europe has overtaken North America for military drone deal count, but American companies still raise more money.
European drone startups completed 33 deals involving 26 companies in the last 12 months, compared with 21 deals involving 20 companies in the 12 months before. North America recorded 29 deals involving 21 companies in the current period. The dollar gap runs the other way: North America raised at least $10.0B of disclosed capital, versus at least $6.0B for Europe.
Germany contributed 8 deals and at least $3.8B in the last 12 months. The United Kingdom had 7 deals totaling $1.3B, and TEKEVER alone raised $580M in Portugal. Helsing and Quantum Systems are producing defense drones in Germany; TEKEVER builds reconnaissance aircraft in Portugal; British businesses are raising money for attack and interception systems.
European procurement is becoming easier to finance through public channels too. The EU's SAFE program supports joint defense purchases, while the EU-Ukraine Drone Alliance is meant to connect European production with Ukrainian needs. Those programs are not private equity rounds. They help explain why manufacturers across the region have credible potential customers.
For now, Europe has the wider spread of deals. North America still has the biggest financing totals.
Is Anduril making US military drone funding look bigger than it really is?
Yes, in dollars. Anduril plays an enormous part in American military drone fundraising, although several other US startups are also raising large sums.
Anduril's $5.0B late-stage round in May 2026 was the largest qualifying round in the last 12 months. The company had raised a $2.5B round in June 2025, during the 12 months before. In the current period, the United States recorded 27 deals involving 20 companies and at least $10.0B in disclosed funding. Anduril is a major part of that total, but the deal count shows the market is wider than one name.
Shield AI raised $2.8B across 3 rounds, Mach Industries raised $900M across 2 rounds, and Neros Technologies secured a $250M Series C in August 2026. These businesses are not all making the same product. Shield AI combines aircraft with autonomy software; Mach works on attack drones; Neros sells tactical systems.
Anduril's Arsenal-1 factory project in Ohio helps explain why its capital needs are unusual. Building drones at industrial scale takes factories and equipment as well as engineers. A company financing that expansion can lift national totals sharply without telling us what smaller founders can expect.
Why do Ukrainian military drone startups raise so little venture capital?
Ukraine's military drone industry is busy producing and supplying aircraft, but relatively little of that activity shows up as venture rounds in Ukrainian startups.
Ukrainian-headquartered developers recorded 7 qualifying financings raising at least $33M in the last 12 months, against 5 deals raising $23M in the 12 months before. That is a modest amount beside the American or German market. It covers equity investments in qualifying companies, not Ukrainian drone sales, government purchases, outside grants or manufacturing partnerships.
Ukraine's Ministry of Defence said in June 2026 that locally made systems represented the great majority of drones it bought. Its DOT-Chain Defence platform lets military units choose equipment through a state-funded digital marketplace. The ministry has reported more than 1.5 million drones and other equipment items delivered through the platform since launch. These figures describe military supply, not startup fundraising.
A Ukrainian manufacturer can sell directly to the military without announcing a big venture round. An overseas supplier can also invest in a local factory without creating a financing of a Ukrainian-headquartered startup. The difference between purchase activity and equity funding is especially stark here.

In our research about military drones, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Is military drone funding going to a small group of winners?
Yes. A small set of military drone companies receives the biggest checks, even though many smaller suppliers continue to raise money.
Over the last 12 months, Anduril led fundraising, followed by Shield AI with $2.8B, Helsing with $1.8B, Quantum Systems with $1.4B and Mach Industries with $900M. Those are company totals for the period, not five individual financing announcements. They stand far above the $3.3M median Seed round. Large manufacturers and software providers can need much more money once they start scaling production and support.
Quantum Systems described expanding factories across allied countries in July 2026. Helsing has been building and deploying loitering munitions, while Anduril's Ohio plant is designed to make autonomous weapons in much greater volume. Investors can see where substantial capital might go, even before every planned production line reaches its target output.
Yet 38 companies had exactly 1 financing in the last 12 months, compared with 40 in the 12 months before. Those companies show there is still activity beyond the biggest recipients. What is concentrated is the money, not every opportunity to get funded.
Do military drone startups now need battlefield proof to raise money?
Not as a formal requirement, but battlefield performance is becoming a much stronger selling point for military drone startups seeking serious investment.
Ukraine made the change explicit in March 2026. Its Ministry of Defence said drone orders would be chosen using real combat data rather than brand preference. Under the policy, 80% of its UAV procurement budget goes to systems with proven battlefield performance, while 20% is reserved for new designs and testing. Those are procurement rules, not terms we have verified for private financing rounds.
Other customers are becoming demanding too. NATO opened a testing range in Latvia for drone and counter-drone technology in March 2026. The US military has used field competitions to compare low-cost attack drones. A manufacturer that survives those tests can show investors evidence that a customer actually wants its product.
We cannot say every investor requires combat footage or a signed purchase order. What has changed is the comparison. A company with reliable aircraft, tested software and an ability to deliver is easier to assess than a developer still promising its first working prototype.
Are swarm drones and military cargo drones being left behind?
No. Military drone swarms and cargo aircraft are still getting funded, but their checks are much smaller than the biggest strike and reconnaissance rounds.
Swarm and collaborative drone developers raised $52M in 4 deals over the last 12 months, against $22M in 2 deals during the 12 months before. Cargo and logistics developers raised at least $27M across 3 deals in the current period, compared with $8M across 2 deals previously. Those are active markets with different operational problems to solve.
The swarm idea also appears inside larger software businesses. Shield AI's May 2026 LUCAS announcement describes Hivemind helping groups of attack drones coordinate during missions. That means some investment in coordinated flight sits in broader mission software, rather than in pure-play swarm startups. Grid Aero's $20M Series A in January 2026, meanwhile, backed autonomous aircraft designed for military cargo transport.
Cargo developers still have to show that their aircraft can carry useful loads when runways, roads and communications are unreliable. Swarm companies need to show their coordination works under battlefield conditions. Both missions have buyers to convince, but the funding figures show they are still small next to the main attack and surveillance categories.
Are more investors getting into military drones, or just the usual funds?
More investors are joining military drone rounds, and many are investing in the sector repeatedly.
We counted 111 distinct participating investors in the last 12 months, compared with 79 in the 12 months before. Investors who appeared more than once increased from 8 to 23. The number of disclosed lead investors also grew to 66 from 58. That is a wider pool of firms and individuals willing to back drone makers, even as first financings remain scarce.
Axon Enterprise led the most rounds, 3 with a combined round size of $274M in the last 12 months. Advent International led 2 rounds with a combined round size of $2.7B, Sequoia Capital led 2 rounds totaling $800M, and Founders Fund led 2 rounds totaling at least $550M. Those amounts describe the whole financings, not how much each investor personally invested. Lead names were disclosed for 75% of deals in the current period, compared with 83% previously.
The bigger investor pool is encouraging. It does not erase the preference for companies that already have backing, a functioning product and a clearer path to military customers.

Learning from others' mistakes is the cheapest lesson there is. In our market report about military drones, we look at what broke startups before you, so you don't repeat it.
Are military drone startups actually getting government orders?
Yes. Military drone companies now have concrete government orders and procurement routes, although many funded startups still have to win their first customer.
Skydio announced a U.S. Army purchase of more than 2,500 X10D surveillance aircraft in March 2026, followed by a separate Air Force program expansion in May. Shield AI announced an Indian Army selection for its V-BAT aircraft in January 2026 and a U.S. Navy selection to compete for surveillance services in April. Those are customer announcements, not venture investments.
Purchasing is changing beyond individual contracts. NATO's counter-drone marketplace lets allies buy from selected suppliers without running an entirely new tender. Ukraine's digital procurement system lets military units choose equipment, with orders increasingly influenced by battlefield results. The EU's SAFE framework offers another route for joint defense purchases.
Investors now have more to look at than forecasts of future defense spending. Still, a test invitation, a framework listing and a firm purchase order are three different things. Only deliveries and repeat sales will show which manufacturers build lasting businesses.
Could military drone funding slow down even if armies keep buying more drones?
Even as military drone purchases rise, venture funding could slow, because customers and investors need different things.
An army wants drones that work, arrive when promised and fit its budget. Investors need the company making those drones to grow in value. Ukraine's procurement system can reward a supplier's battlefield results without making that supplier attractive to a venture fund. NATO can also simplify purchases for established vendors without creating new financing for an early-stage rival.
The funding figures already show why a slowdown could look dramatic. Capital excluding rounds above $100M was flat between the two periods, at 0% growth, even as the headline total jumped. A few huge companies are doing a great deal of the work. If those companies wait longer to raise again, reported funding could fall sharply without a matching collapse in military demand.
There are product risks as well: electronic warfare can disrupt navigation, and manufacturers still need to deliver reliable aircraft at scale. Demand for drones is real. It does not guarantee that every drone maker will become a good investment.
So, what does military drone funding look like right now?
Military drone funding is much stronger today, but the biggest winners are companies that have already raised money and can show they are ready to deliver.
More startups secured funding in the last 12 months than in the 12 months before. The money went further beyond just the largest rounds, although those enormous checks still dominate the totals. Anduril raised the most over the last 12 months, while Advent International led 2 of the biggest rounds, worth a combined $2.7B.
The sharpest weakness is the first round. Established suppliers can raise again quickly, and some are securing enormous checks for aircraft, autonomy software and production. New entrants still get investment, but fewer reach that first financing. Europe now has a larger number of deals than North America, while the largest dollar totals remain on the North American side.
Military drone funding has buyers behind it. The United States, Ukraine and NATO are testing and purchasing systems that work in real conditions. But customer demand is no promise that every startup will raise capital or deliver profit. The market is growing fast with a narrower opening for newcomers.
The table below shows what we found.
| Question | Answer |
|---|---|
| Is the boom reaching more drone companies? | Yes, more military drone makers are securing investment now. The funded-company count rose 21% between the comparison periods. That broadens participation beyond the best-known defense technology businesses. |
| Are billion-dollar deals doing most of the work? | Yes, a few large rounds dominate the total. Disclosed military drone capital rose 236% between the periods. Smaller financings tell a more modest growth story overall. |
| Are smaller drone developers seeing more money? | Yes, smaller financings also grew during the period. Capital excluding rounds above $50M rose 103% between periods. That gives companies below the giants more room to raise. |
| Is the first check getting harder to win? | Yes, fewer companies are securing their first military drone financing. First financings fell from 11 deals to 8 deals. That makes entry tougher even as the wider market expands. |
| Do familiar businesses receive most new financing? | Yes, investors increasingly return to companies they already know. Follow-on financing reached 56 deals in the current period. Startups with a track record have a clear advantage. |
| Are military drone startups raising again sooner? | Yes, observed gaps between rounds have become shorter lately. The median interval fell from 10 months to 8 months. Faster repeat rounds can help companies expand production sooner. |
| Are late-stage drone checks much larger now? | Yes, large mature companies absorb enormous funding sums today. Rounds from Series D+ onward brought in $11.7B in the current period. Building factories and supplying armed forces can demand heavy spending. |
| Are surveillance drones attracting the most deals? | Yes, ISR aircraft receive the most separate drone investments. The category recorded 22 deals in the current period. Attack-drone companies still attracted a larger amount of disclosed capital. |
| Has Europe overtaken America for drone capital? | No, Europe leads on deals but still trails on dollars. European companies recorded 33 deals in the current period. North American companies received more disclosed funding despite fewer rounds. |
| Does military procurement guarantee every startup succeeds? | No, an army purchase does not guarantee investor returns. Ukraine now makes drone buying decisions using battlefield performance. Companies still need sustainable margins and repeat customers to survive. |
| Could venture funding fall while drone demand grows? | Yes, purchasing demand and equity checks can move differently. Funding excluding rounds above $100M showed 0% growth. Big financings can disappear without military customers abandoning drones. |

If you build or invest in the military drone market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Our methodology
Our data runs through November 14, 2026. We then reviewed this article and updated its answers on November 17, 2026, the date shown under the title. We compare the last 12 months, from November 15, 2025 to November 14, 2026, with the 12 months before, from November 15, 2024 to November 14, 2025. Both periods lie within our complete market-deal coverage, which begins in January 2024. This article examines that pair of periods rather than a year-to-date total or the full financing history of every company.
We count equity financings of qualifying private companies at or above $300K, including separately identified equity growth rounds. Debt, grants, loans, unconverted convertibles, SAFEs and public offerings are excluded. We count each financing once and merge duplicated reporting of the same announcement. Undisclosed-amount rounds increase deal counts but not capital totals; consequently, amounts ending in a plus sign are minimum known sums rather than full estimates of undisclosed financing.
Our market covers independent companies building unmanned aircraft designed or materially configured for military intelligence, surveillance, strike, interception, electronic warfare, swarming or logistics, together with dedicated software that directly pilots, tasks or coordinates those aircraft. We include defense-centered dual-use systems and qualifying borderline companies instead of quietly omitting them. Generic image analytics, broad command software, civilian-first drones and ground- or sea-only robots do not qualify unless they also have an independently material military aerial-drone product. Interceptor aircraft qualify, whereas detection-only and jamming-only counter-UAS vendors do not.
Every counted company meets our startup definition: an independent technology-led company founded in 2000 or later, built for rapid growth and financed by venture capital, founders, angels or grants, and either private, listed within the last 5 years or recently acquired within the last 3 years. A company acquired recently can remain eligible as part of its new owner. We classify companies by headquarters country and their principal military drone product category; this is a narrower perimeter than the entire defense-technology industry.
Rounds confirmed by a company announcement, a press article or a regulatory filing are counted in full. Where no article exists, a round is counted only when at least two recognised databases agree on its date (within one month) and amount (within 5%), and it is marked as low confidence; a round found in a single database stays in the company's history but is left out of totals. For companies that have raised more than $100M, every round counted is backed by an article.
We use the original company statement, regulatory record or reliable reporting first, applying the database cross-check only where those sources do not exist. We group Seed and Series A as early stage, Series B and later rounds as later stage, and keep undisclosed stages separate. Disclosed-capital shares use only financings with a public amount; company age and gaps between rounds use records with adequate date and founding-year information. The latest incomplete month is not treated as a completed month for monthly medians.
A published total for the entire defense industry or all drone procurement can differ materially from ours without either being mistaken. We exclude public-company transactions, military contracts, debt, most purely civilian aviation, and financings below our threshold; we also avoid inserting unverified rumor rounds into totals. Our comparison uses the same company and deal rules on both sides, so changes reflect a consistent private-equity market perimeter rather than incompatible press headlines.
Key sources include Anduril's January 2025 Arsenal-1 manufacturing announcement, Official U.S. Drone Dominance Program trials and phased procurement, December 2025 Blue UAS program transition and vetting requirements, Defense Innovation Unit production-ready requirements for its low-cost ISR project, Ukraine's March 2026 frontline-performance procurement policy, Ukraine's November 2026 DOT-Chain Defence delivery update, Ukraine's June 2026 local-procurement and drone-industry update, Shield AI's January 2026 Indian Army V-BAT and Hivemind selection, Shield AI's April 2026 U.S. Navy ISR-services selection, Shield AI's May 2026 LUCAS Hivemind autonomy integration, Skydio's March 2026 U.S. Army X10D aircraft order, Skydio's May 2026 U.S. Air Force X10D follow-on contract, PDW's 2025 manufacturing-facility expansion, Helsing's July 2026 update on deployed HX-2 strike drones, Quantum Systems' July 2026 international manufacturing expansion, Quantum Systems' March 2026 Ukrainian interceptor contract, Quantum Systems' April 2026 Ukrainian joint ventures, Quantum Systems' October 2026 interceptor-production announcement, NATO's November 2026 marketplace and selected suppliers, NATO's March 2026 testing range for UAV and counter-UAS systems, European Union SAFE joint defense purchasing mechanism, European Commission EU-Ukraine Drone Alliance launch and purpose, and NATO DIANA 2026 accelerator program and participating innovators.

In our report covering the military drone market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us