What are the funding trends in procurement software right now?
Whether you're building or investing in the procurement software market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Procurement software has attracted at least $569M across 39 deals this year so far, led by ORO Labs' $100M Series C in March 2026. Funding dollars are close to the same period of 2025, while fewer deals were completed. The number of funded companies fell too.
The capital total is down 3% from the equivalent period of 2025, while deal count is down 11%. A few large rounds explain why dollars held up better than deal activity.
The largest checks now matter more. 3 rounds above $50M raised $245M this year, compared with $109M+ from 2 such rounds at this point in 2025.
Once we strip out rounds above $50M, the picture gets much weaker. The remaining disclosed funding is down 32% from the equivalent period of 2025. A near-flat total therefore does not mean that ordinary transactions are holding up.
The comparison with the same months of 2024 is more encouraging. Funding and deal activity are both higher, and the market has more funded companies than it did at that earlier point. So the recent dip is a dip against a strong 2025, not against every earlier year.
The biggest funding burst came in Q1 2026, helped by ORO Labs, Naboo and several procurement AI startups. Later quarters have continued producing deals, but none has matched that opening pace of dollars.
Procurement intake and orchestration has gained importance. Larger rounds are financing software that receives purchasing requests, routes approvals, works with supplier data and increasingly executes steps using AI agents.
Strategic sourcing is moving in the opposite direction in dollar terms. It still generates deals, but its disclosed capital contribution has fallen sharply from the equivalent period of 2025.
North America still gets the most procurement software funding, while Europe is losing deal share. Saudi Arabia's purchasing marketplaces and spend-control platforms are also visible, although their sample remains small.
Procurement software is raising about as much money as last year without becoming easier to finance for most founders. A few companies with enterprise products are securing huge checks while ordinary rounds have become less common.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the procurement software market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the procurement software market over the last years
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our procurement software market report.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| SPARETECH | Spend Intelligence & Controls | November 2026 | Series B | $20M | Enterprise MRO software identifies spare-part suppliers and alternative sources while optimizing parts spend and inventories. | Europe | Blume Equity, Insight Partners | Germany | |
| Atmospheric AI | Strategic Sourcing | November 2026 | Seed | $10M | AI models raw-material production chains to inform supplier cost, supply risk and sourcing decisions. | Europe | DBL Partners | United Kingdom | |
| Kodiact | Strategic Sourcing | November 2026 | Seed | $2.5M | Simulation and AI sourcing platform helps manufacturers optimize raw-material procurement decisions. | North America | Supply Change Capital | United States | |
| SpendRule | Spend Intelligence & Controls | October 2026 | Seed | $4M | Contract compliance software for healthcare spending | North America | Radical Investments | United States | |
| Opply | Strategic Sourcing | October 2026 | Unknown | $7.5M | CPG sourcing and procurement automation | Europe | Chalfen Ventures | United Kingdom | |
| Syncmeon | Procurement Marketplaces | October 2026 | Seed | $600K | AI-powered B2B procurement marketplace that helps small businesses find suppliers and automate purchasing. | North America | Not disclosed | United States | |
| Elevatry | Strategic Sourcing | October 2026 | Seed | ~$3.5M | AI strategic procurement software | Europe | Not disclosed | Germany | |
| Finches | Supplier Management & Risk | October 2026 | Seed | $2.2M | Agricultural sourcing risk intelligence software | Europe | High-Tech Gründerfonds, Vanagon Ventures | Germany | |
| Bloom | Procurement Marketplaces | October 2026 | Seed | $3.6M | Software matching manufacturing buyers with suppliers | North America | SNAK Venture Partners | United States | |
| Project Suppliers | Procurement Marketplaces | October 2026 | Seed | $1M | Industrial supplier discovery and procurement marketplace | Middle East | Not disclosed | Saudi Arabia | |
| Axya | Procure-to-Pay | September 2026 | Series A | ~$8.8M | Procurement execution software for manufacturers | North America | McRock Capital | Canada | |
| Magentic | Procurement Intake & Orchestration | September 2026 | Series A | $18M | AI agents for procurement teams | Europe | Felicis | United Kingdom | |
| BRKZ | Procurement Marketplaces | September 2026 | Series B | $13M | Construction materials procurement marketplace | Middle East | Wa’ed Ventures, 500 Global | Saudi Arabia | |
| Aron | Strategic Sourcing | September 2026 | Seed | $6M | AI procurement negotiation and sourcing assistant | North America | Storm Ventures | United States | |
| Fitting | Procurement Marketplaces | August 2026 | Seed | $1.1M | Construction materials procurement marketplace | Middle East | Not disclosed | Saudi Arabia | |
| Freehand | Spend Intelligence & Controls | July 2026 | Series B | $75M | AI invoice auditing and spend management | North America | Battery Ventures, NewRoad Capital Partners | United States | |
| Prolo | Strategic Sourcing | July 2026 | Seed | $5.4M | AI procurement and supplier sourcing software | Europe | Triple Point Ventures | United Kingdom | |
| compri | Procurement Intake & Orchestration | June 2026 | Seed | ~$3.7M | AI procurement automation software | Europe | Picus Capital | Italy | |
| SubBase | Procure-to-Pay | June 2026 | Series A | $7M | Construction procurement management software | North America | FINTOP | United States | |
| Soource | Strategic Sourcing | June 2026 | Seed | $3.3M | AI procurement and supplier automation | Europe | Vertis | Italy | |
| givvable | Supplier Management & Risk | June 2026 | Unknown | $1.1M | Supplier sustainability and procurement intelligence | Asia-Pacific | Not disclosed | Australia | |
| Definic | Supplier Management & Risk | June 2026 | Seed | $2.8M | Vendor intelligence for IT procurement teams | Europe | J&T Ventures | Slovakia | |
| Pivot | Procurement Intake & Orchestration | May 2026 | Series B | $40M | Procurement intake and spend management software | Europe | Forestay Capital, Notion Capital | France | |
| ProcurePro | Strategic Sourcing | May 2026 | Series B | $11M | Construction procurement and contract management software | Asia-Pacific | QIC Ventures | Australia | |
| TradeForm | Strategic Sourcing | April 2026 | Seed | $2M | AI procurement agents for direct materials | North America | Foundation Capital | United States | |
| Traza | Procurement Intake & Orchestration | April 2026 | Seed | $2.1M | AI agents for procurement operations | North America | Base10 Partners | United States | |
| Mandel AI | Procurement Intake & Orchestration | March 2026 | Seed | $3.9M | AI sourcing and ordering coordination platform | North America | Not disclosed | United States | |
| Aerchain | Procurement Intake & Orchestration | March 2026 | Series A | $13M | AI sourcing and procurement software | Asia-Pacific | Pavestone VC | India | |
| Candex | Procure-to-Pay | March 2026 | Series C | $7M+ | Tail-spend supplier payment and procurement platform | North America | HSBC | United States | |
| ORO Labs | Procurement Intake & Orchestration | March 2026 | Series C | $100M | Enterprise procurement requests approvals and supplier workflows | North America | Brighton Park Capital, Goldman Sachs Alternatives | United States | |
| SkySelect | Strategic Sourcing | March 2026 | Unknown | $9M | Aircraft parts procurement automation software | North America | Verb Ventures, RockCreek | United States | |
| Lio | Procurement Intake & Orchestration | March 2026 | Series A | $30M | AI agents for enterprise procurement | North America | Andreessen Horowitz | United States | |
| Eezee | Procurement Marketplaces | February 2026 | Unknown | $5M | B2B marketplace for industrial procurement | Asia-Pacific | Korea Investment Partners Southeast Asia | Singapore | |
| SpendRule | Spend Intelligence & Controls | February 2026 | Seed | $2M | Contract compliance software for healthcare spending | North America | Abundant Venture Partners | United States | |
| Didero | Procurement Intake & Orchestration | February 2026 | Series A | $30M | AI procurement agents for manufacturers | North America | Chemistry, Headline | United States | |
| Naboo | Services Procurement | February 2026 | Series B | $70M | Corporate event venue sourcing and procurement | Europe | Lightspeed Venture Partners | France | |
| SiFi | Spend Intelligence & Controls | February 2026 | Series A | $20M | Procurement and spend management software | Middle East | Ra'ed Ventures | Saudi Arabia | |
| 1Buy.AI | Strategic Sourcing | January 2026 | Seed | $3.9M | Electronics procurement intelligence and sourcing software | Asia-Pacific | 100Unicorns | India | |
| Interos | Supplier Management & Risk | January 2026 | Unknown | $20M | Supply chain risk intelligence software | North America | Blue Owl Capital | United States | |
| Monq | Procurement Intake & Orchestration | November 2025 | Seed | $3M | AI procurement workflow software | Europe | Outward VC | United Kingdom | |
| Zinit | Strategic Sourcing | November 2025 | Seed | $8M | AI procurement sourcing and bidding platform | Middle East | AltaIR Capital | United Arab Emirates | |
| Coverbase | Supplier Management & Risk | November 2025 | Series A | $17M | Third-party risk management software | North America | Canapi Ventures | United States | |
| Procure Ai | Procurement Intake & Orchestration | November 2025 | Seed | $13M | AI procurement automation software | Europe | Headline | United Kingdom | |
| Belidor | Strategic Sourcing | October 2025 | Seed | $3.1M | Procurement automation and sourcing software | North America | Not disclosed | United States | |
| Green Cabbage | Spend Intelligence & Controls | October 2025 | Series B | $40M | Procurement intelligence and cost benchmarking | North America | Sageview Capital | United States | |
| Resourcly | Spend Intelligence & Controls | October 2025 | Seed | $3M | AI procurement and supplier management software | Europe | Project A | Germany | |
| Gain | Procurement Intake & Orchestration | September 2025 | Seed | $12M | AI employees for procurement teams | Middle East | The Garage | Israel | |
| Beroe | Spend Intelligence & Controls | September 2025 | Growth Equity | $34M | Procurement intelligence and supplier research software | North America | Relativity Resilience Fund, Mukul Agrawal, Ashish Kacholia, Lashit Sanghvi, Alchemy Long Term Ventures Fund | United States | |
| sun.store | Procurement Marketplaces | September 2025 | Seed | $6.6M | B2B marketplace for solar equipment | Europe | Contrarian Ventures, Market One Capital, Movens Capital | Poland | |
| Omnea | Procurement Intake & Orchestration | September 2025 | Series B | $50M | Procurement requests and supplier management software | Europe | Insight Partners, Khosla Ventures | United Kingdom | |
| Fitting | Procurement Marketplaces | September 2025 | Seed | $500K | Construction materials procurement marketplace | Middle East | Not disclosed | Saudi Arabia | |
| Infinity Loop | Strategic Sourcing | August 2025 | Seed | $5M | Procurement negotiation intelligence software | North America | Glasswing Ventures, TIAA Ventures | United States | |
| Kunzapp | Spend Intelligence & Controls | August 2025 | Seed | $2M | Procurement analytics and supplier management software | Latin America | Wollef | Mexico | |
| Magentic | Procurement Intake & Orchestration | July 2025 | Seed | $5.5M | AI agents for procurement teams | Europe | Sequoia Capital | United Kingdom | |
| Cienty | Procurement Marketplaces | July 2025 | Seed | $2.7M | Procurement marketplace for independent pharmacies | Latin America | Astella | Brazil | |
| Candex | Procure-to-Pay | July 2025 | Series C | $33M | Tail-spend supplier payment and procurement platform | North America | 9Yards Capital | United States | |
| Levelpath | Procurement Intake & Orchestration | June 2025 | Series B | $55M+ | Procurement intake and purchasing workflow software | North America | Battery Ventures | United States | |
| Delfio | Procure-to-Pay | June 2025 | Seed | $1.7M | AI procurement software for industrial purchasing | Europe | Peak | Netherlands | |
| Mercanis | Strategic Sourcing | June 2025 | Series A | $20M+ | Procurement sourcing and supplier management software | Europe | Partech, AVP | Germany | |
| Nvelop | Strategic Sourcing | June 2025 | Seed | $1.3M | AI sourcing and procurement automation | Europe | Failup Ventures | Finland | |
| Remarcable | Procure-to-Pay | June 2025 | Series A | $15M | Procurement and materials software for contractors | North America | Insight Partners | United States | |
| Pactum AI | Strategic Sourcing | June 2025 | Series C | $54M | AI agents for supplier negotiations | North America | Insight Partners | United States | |
| Spendflo | Spend Intelligence & Controls | June 2025 | Unknown | Undisclosed | SaaS purchase procurement and spend management | North America | Not disclosed | United States | |
| Speya | Supplier Management & Risk | May 2025 | Seed | $1.2M | Supplier intelligence for industrial procurement | Europe | Not disclosed | Sweden | |
| Arkestro | Strategic Sourcing | May 2025 | Series B | $36M | Predictive procurement and sourcing software | North America | Altira Group, Aramco Ventures | United States | |
| Scalera | Strategic Sourcing | May 2025 | Seed | ~$6.5M | AI procurement platform for construction firms | Europe | firstminute capital, Speedinvest | Switzerland | |
| Predikt | Spend Intelligence & Controls | May 2025 | Seed | $1.4M | AI procurement and supplier intelligence software | Europe | Not disclosed | Belgium | |
| Field Materials | Procure-to-Pay | April 2025 | Series A | $11M | Construction procurement and materials software | North America | Navitas Capital | United States | |
| MatBook | Procure-to-Pay | April 2025 | Seed | $750K | Construction materials procurement and logistics software | North America | Seedstars International Ventures, Fluent Ventures, Everywhere Ventures | United States | |
| Vallor | Supplier Management & Risk | April 2025 | Seed | $4M | AI procurement workflows and supplier sourcing | North America | Dynamo Ventures, Bloomberg Beta | United States | |
| LightSource | Strategic Sourcing | March 2025 | Series A | Undisclosed | Direct-materials sourcing and procurement software | North America | Lightspeed Venture Partners, Bain Capital Ventures | United States | |
| BuildVision | Strategic Sourcing | March 2025 | Series A | $10M | Procurement software for construction materials | North America | Norwest | United States | |
| compri | Procurement Intake & Orchestration | March 2025 | Seed | ~$1.7M | AI procurement automation software | Europe | Italian Founders Fund, DFF Ventures | Italy | |
| Shoppable Business | Procurement Marketplaces | March 2025 | Seed | $1.2M | B2B procurement marketplace for business supplies | Asia-Pacific | Ignite House of Innovation | Philippines | |
| TimeFlow | Services Procurement | February 2025 | Unknown | $4.4M | IT vendor management and procurement software | Europe | Vertis, Azimut | Italy | |
| BRKZ | Procurement Marketplaces | February 2025 | Series A | $8M | Construction materials procurement marketplace | Middle East | 9900, BECO Capital | Saudi Arabia | |
| comstruct | Procure-to-Pay | February 2025 | Series A | $14M | Construction procurement software | Europe | GV, 20VC | Germany | |
| Response | Spend Intelligence & Controls | February 2025 | Seed | $4M | Procurement intake and vendor management software | North America | Not disclosed | United States | |
| Crown | Strategic Sourcing | February 2025 | Seed | $2.2M | Procurement e-auction software | Europe | Heartfelt | France | |
| Naboo | Services Procurement | January 2025 | Series A | $22M | Corporate event venue sourcing and procurement | Europe | Notion Capital | France | |
| Vertice | Spend Intelligence & Controls | January 2025 | Series C | $50M | Procurement and SaaS spending management software | Europe | Lakestar | United Kingdom | |
| Matchory | Strategic Sourcing | January 2025 | Seed | $6.6M | Supplier data and matching software | Europe | Capmont | Germany | |
| Soource | Strategic Sourcing | January 2025 | Seed | $1.7M | AI procurement and supplier automation | Europe | 360 Capital | Italy | |
| ProcureYard | Procurement Marketplaces | January 2025 | Seed | $1.7M | Construction materials procurement and supplier platform | Asia-Pacific | Powerhouse Ventures | India | |
| Reeco | Procure-to-Pay | January 2025 | Series A | $15M | Hotel procurement and inventory software | North America | Aleph | United States | |
| Labviva | Procurement Marketplaces | January 2025 | Series B | $25M | Life sciences procurement marketplace and software | North America | 53 Stations | United States | |
| BRM | Supplier Management & Risk | December 2024 | Series A | $15M | AI procurement and vendor management software | North America | Caffeinated Capital | United States | |
| BRM | Supplier Management & Risk | December 2024 | Seed | $6.6M | AI procurement and vendor management software | North America | Base10 Partners | United States | |
| Pegbo | Supplier Management & Risk | November 2024 | Seed | $1.4M+ | Construction procurement and supplier management software | North America | Nirman Ventures | United States | |
| Freqens | Spend Intelligence & Controls | November 2024 | Seed | $3M | Agentic planning software for finance teams | Europe | Not disclosed | France | |
| Kodiak Hub | Supplier Management & Risk | November 2024 | Series B | $6.6M | Supplier relationship and procurement management software | Europe | Oxx | Sweden | |
| Lightyear | Strategic Sourcing | November 2024 | Series B | $31M | Telecom procurement and network inventory software | North America | Altos Ventures | United States | |
| Civic Marketplace | Procurement Marketplaces | November 2024 | Seed | $3.2M | Marketplace for government procurement and vendors | North America | Kindred Capital | United States | |
| Predikt | Spend Intelligence & Controls | October 2024 | Seed | $825K | AI procurement and supplier intelligence software | Europe | Not disclosed | Belgium | |
| Zip | Procurement Intake & Orchestration | October 2024 | Series D+ | $190M | Purchasing intake and procurement workflow software | North America | BOND | United States | |
| Najar | Spend Intelligence & Controls | October 2024 | Series A | $17M | Software procurement and spend management | Europe | 13books Capital | France | |
| Omnea | Procurement Intake & Orchestration | October 2024 | Series A | $20M | Procurement requests and supplier management software | Europe | Accel | United Kingdom | |
| Green Cabbage | Spend Intelligence & Controls | October 2024 | Series A | Undisclosed | Procurement intelligence and cost benchmarking | North America | Sorenson Capital | United States | |
| Valdera | Procurement Marketplaces | October 2024 | Series A | $15M | Digital sourcing marketplace for chemicals | North America | Index Ventures | United States | |
| Resourcly | Spend Intelligence & Controls | October 2024 | Seed | $825K | AI procurement and supplier management software | Europe | Not disclosed | Germany | |
| Trestle | Supplier Management & Risk | September 2024 | Seed | $2.3M | Contractor vendor qualification and management | North America | Lerer Hippeau | United States | |
| Globality | Strategic Sourcing | September 2024 | Series D+ | $15M | AI sourcing and procurement platform | North America | Not disclosed | United States | |
| Mazepay | Spend Intelligence & Controls | August 2024 | Unknown | $2M | Long-tail procurement and payment software | Europe | Not disclosed | Denmark | |
| Didero | Procurement Intake & Orchestration | July 2024 | Seed | $7M | AI procurement agents for manufacturers | North America | First Round Capital | United States | |
| Pactum AI | Strategic Sourcing | July 2024 | Series B | $20M | AI agents for supplier negotiations | North America | Karma Ventures | United States | |
| Prewave | Supplier Management & Risk | June 2024 | Series B | $69M | Supply chain supplier risk monitoring software | Europe | Hedosophia | Austria | |
| Droppe | Procurement Marketplaces | June 2024 | Seed | $4.3M | B2B marketplace for industrial supplies | Europe | OpenOcean | Finland | |
| Connexus | Services Procurement | June 2024 | Seed | $800K | Multifamily procurement and vendor management | North America | Middleburg Communities, Demetrios Barnes, Todd Butler | United States | |
| Field Materials | Procure-to-Pay | June 2024 | Seed | $3.5M | Construction procurement and materials software | North America | DivcoWest Ventures, Navitas Capital, Zelda Ventures | United States | |
| SiFi | Spend Intelligence & Controls | May 2024 | Seed | $10M | Procurement and spend management software | Middle East | Not disclosed | Saudi Arabia | |
| Diagon | Strategic Sourcing | April 2024 | Seed | $4.3M | Procurement software for manufacturing equipment | North America | The Westly Group | United States | |
| ProcMart | Procurement Marketplaces | April 2024 | Series B | $30M | B2B marketplace for industrial supplies | Asia-Pacific | Fundamentum Partnership, Edelweiss Discovery Fund | India | |
| Torg | Procurement Marketplaces | April 2024 | Seed | $3M | Food supplier sourcing marketplace | Europe | Connect Ventures | Germany | |
| ProcMart | Procurement Marketplaces | March 2024 | Unknown | ~$3M | B2B marketplace for industrial supplies | Asia-Pacific | Sixth Sense Ventures | India | |
| Buddy | Procurement Marketplaces | March 2024 | Seed | $900K | Scrap metal trading marketplace | Asia-Pacific | GD1 | New Zealand | |
| Freehand | Spend Intelligence & Controls | March 2024 | Series A | $25M | AI invoice auditing and spend management | North America | Not disclosed | United States | |
| BlueBean | Procure-to-Pay | February 2024 | Seed | $1.3M | AI procurement automation for business purchasing | North America | Tola Capital | United States | |
| Naboo | Services Procurement | February 2024 | Seed | $8.3M | Corporate event venue sourcing and procurement | Europe | Not disclosed | France | |
| ProcurePro | Strategic Sourcing | January 2024 | Series A | ~$4.1M | Construction procurement and contract management software | Asia-Pacific | Airtree Ventures, Saniel Ventures | Australia | |
| akirolabs | Strategic Sourcing | January 2024 | Seed | $5M | AI procurement strategy and sourcing software | Europe | HTGF, OTB Ventures, D11Z Ventures | Germany | |
| Vertice | Spend Intelligence & Controls | January 2024 | Series B | $25M | Procurement and SaaS spending management software | Europe | 83North, Bessemer Venture Partners | United Kingdom | |
| Coverbase | Supplier Management & Risk | 2024 | Seed | $3.5M | Third-party risk management software | North America | Not disclosed | United States | |
| Hazel | Strategic Sourcing | 2024 | Seed | Undisclosed | Public-sector sourcing and solicitation workflow automation | North America | Not disclosed | United States |

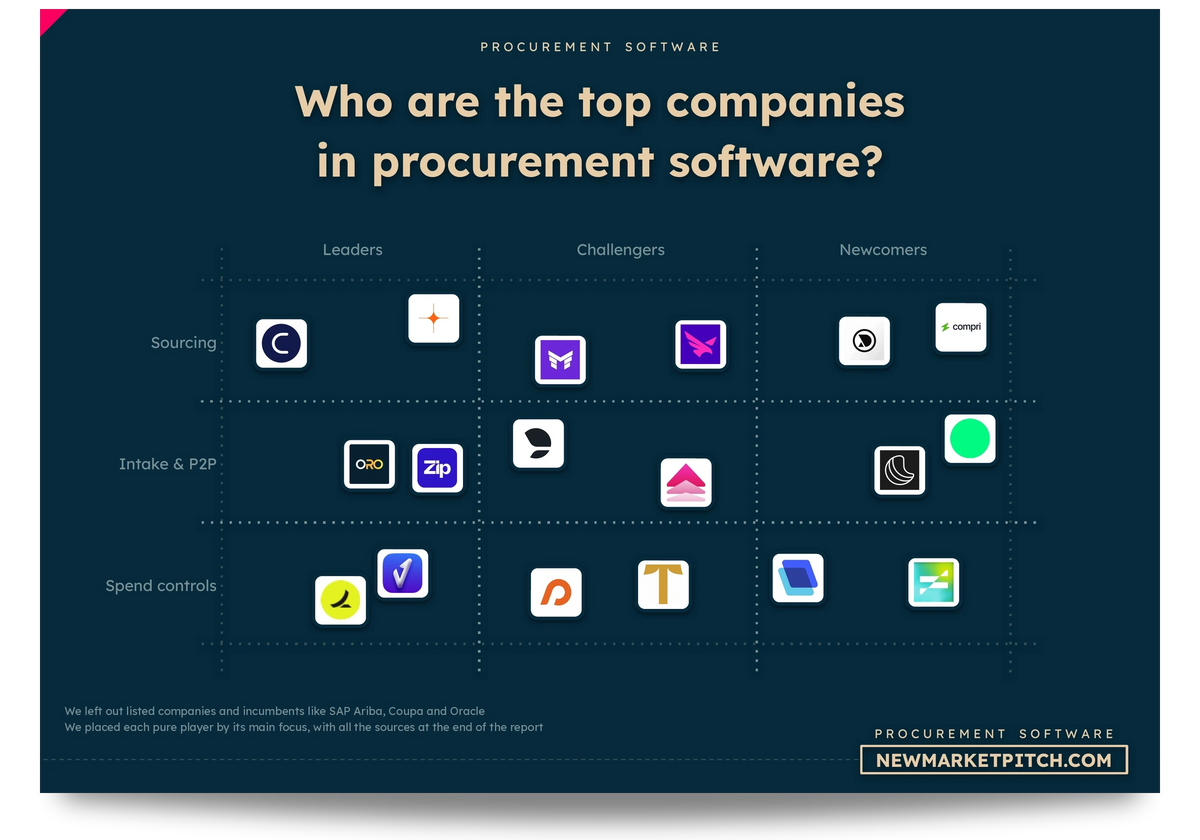
In our research about procurement software startups, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is procurement software funding rising this year?
No. Procurement software funding dipped slightly in dollars this year and fell more clearly in deals.
We tracked 39 deals worth at least $569M this year to date, versus 44 deals worth at least $585M in the same period of 2025. Capital fell 3%, and the number of deals fell 11%. The number of funded companies also slipped from 44 to 38. Investors are spending almost as much while backing fewer teams.
ORO Labs leads the current period by capital raised, while Freehand and Naboo completed other prominent enterprise procurement rounds this year. Their products address enterprise procurement orchestration, spend management and corporate-event purchasing, respectively. Large buyers have recognizable reasons to pay for those functions.
In its March 2026 announcement, ORO reported 300% revenue growth and described its deployment among enterprises including Novartis and Siemens Energy. In July, Freehand named customers including Unilever and Pfizer. Both companies describe real deployments. Their growth tells us little about whether a new procurement vendor can raise a first round.
Has procurement software already raised more than last year's full total?
Not yet. The published procurement software funding minimum for this year stands below the full 2025 minimum, although it has already passed the full 2024 total.
We report at least $569M raised this year to date and at least $612M across the complete 2025 calendar year. The year-to-date minimum represents 93% of the prior full-year reported amount, and 102% of the $557M+ recorded across all of 2024. This comparison puts a partial year against full years, and some earlier round amounts were not published.
The number of transactions puts that in perspective. This year so far has 39 deals, equivalent to 83% of the 47 deals in full-year 2025. The dollar total is closer to last year's than the number of financings is. It follows a sequence of large transactions rather than a steady expansion in funded startups.
Companies such as ORO Labs, Freehand and Naboo help explain why. Their enterprise purchasing products support large deployments across complicated organizations, and their announced rounds were sizeable. Naboo's February announcement also described its move into the U.S. and its work with major international corporations. Investors are backing those companies' expansion plans. Their success has not made fundraising easy for everyone else.
Is procurement software's funding growth just a few big rounds?
Procurement software's apparent funding increase depends heavily on large rounds rather than stronger activity throughout the market.
This year, 3 rounds above $50M raised $245M, compared with 2 rounds totaling $109M+ in the same period of 2025. Excluding rounds above $50M, disclosed funding fell to $324M+, from $476M+ at the comparable point in 2025, a 32% decline. That is the clearest test of whether the headline total reflects the whole market or only its upper end.
The current large-round group comprises ORO Labs, Freehand and Naboo. In 2025, Levelpath's $55M+ Series B and Pactum AI's $54M Series C, both in June, made up the comparable above-$50M group.
Freehand's July announcement described autonomous spend management for major enterprises, and Naboo's February announcement described corporate-event purchasing for large international companies. They show why those startups won large checks, while smaller newcomers received less money overall. Remove the big rounds and year-to-date funding falls.
Is procurement software funding stronger than two years ago?
Yes. The procurement software market is bigger than it was at the comparable point two years ago, even after adjusting for its large financing rounds.
This year so far has 39 deals against 28 deals in the same period of 2024, when at least $487M was raised. Deal volume is up 39%, disclosed capital is up 17%, and the number of funded companies is up 41%, from 27 to 38. Unlike the immediate year-on-year comparison, this longer reference point shows improvement in both breadth and money.
Crucially, the comparison also survives removing the largest rounds. Funding without deals above $50M increased 42%, from $228M+ in the comparable 2024 period to $324M+ now. The underlying market looks stronger against that earlier baseline, even after the biggest financings are removed.
That 2024 comparison was itself affected by Zip's $190M Series D+ in October 2024. Zip's announcement described a platform that coordinated corporate buying, approvals and supplier interactions and disclosed a $2.2 billion company valuation. In 2026, funding has been spread across different workflow specialists including ORO, Freehand and Naboo. Procurement software has clearly grown since 2024, but the latest results show funding clustering in fewer large deals.

In our market report about procurement software startups, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Did procurement software funding peak in the first quarter?
So far, Q1 2026 is the high point for procurement software capital, and later quarters have not matched its intensity.
Q1 2026 recorded 13 deals totaling $314M+, versus 16 deals and $167M+ in Q1 2025 and 8 deals and $73M in Q1 2024. The opening quarter's total was helped by ORO Labs, Naboo, Didero and Lio, all of which announced sizeable procurement software financings in early 2026. Those companies attack different areas of enterprise purchasing, but their announcements arrived close together.
The demand behind those investments was not invented in one quarter. Didero's February company statement described manufacturers managing supplier emails and purchase-order exceptions in disconnected systems. Lio's March announcement framed the opportunity as letting software agents handle purchasing work end to end. ORO's March release emphasized orchestration across existing enterprise systems.
Those companies are tackling different purchasing problems. Still, one busy quarter cannot prove that customer demand suddenly accelerated. Financing announcements arrive in bursts, and the following quarters have been quieter.
Did the slowdown after Q1 mean investors abandoned procurement software?
No. Procurement software continued receiving financing after the first quarter, but the early capital surge did not persist.
Q2 2026 produced 9 deals and $73M, followed by 7 deals and $127M in Q3 2026. Q4 2026 is still partial, with 10 deals and $55M reported so far. The change is not a clean downward line: the third quarter raised more money than the second despite fewer transactions, and the partial fourth quarter has already generated a relatively active deal list.
Freehand's $75M Series B in July 2026 helped the third quarter's dollar total. Magentic's $18M Series A in September 2026 supported AI procurement-data work, while BRKZ's $13M Series B in September 2026 served construction-material buying. October then brought a run of smaller rounds, mostly at Seed. This continued activity does not erase the unevenness, but it rules out the idea of a financing freeze.
Procurement investment has been patchy all year. The current quarter is still partial, so it cannot be treated as a closed period. The slowdown after Q1 has been uneven rather than a continuous collapse.
The table below shows the quarterly financing record, including the partial current quarter and the deals with no known quarter.
| Period | Deals | Capital |
|---|---|---|
| Q1 2024 | 8 | $73M |
| Q2 2024 | 8 | $125M |
| Q3 2024 | 5 | $46M |
| Q4 2024 | 14 | $310M+ |
| 2024, quarter not known | 2 | $3.5M+ |
| Q1 2025 | 16 | $167M+ |
| Q2 2025 | 14 | $207M+ |
| Q3 2025 | 10 | $151M |
| Q4 2025 | 7 | $87M |
| Q1 2026 | 13 | $314M+ |
| Q2 2026 | 9 | $73M |
| Q3 2026 | 7 | $127M |
| Q4 2026 (partial) | 10 | $55M |
“+” denotes a published minimum. The 2024 year-only deals are included in the annual total but in no quarter.
Does a busy October mean procurement software funding is rebounding?
The October deal surge shows continued interest in procurement software, but one busy month does not prove a sustained recovery.
We recorded 7 deals in October 2026, against a median of 3 deals per completed month this year. The quarter containing that burst is not yet closed, and the 10 completed months of 2026 have a median disclosed monthly capital total of $35M. These statistics show how exceptional a crowded month can look in a market with a modest normal transaction count.
October's deals were mostly small. They included SpendRule's $4M Seed, Finches' $2.2M Seed, Project Suppliers' $1M Seed and Syncmeon's $600K Seed, all announced in October 2026. Fragment also announced its funding that month, but the $56M it published covers its seed round and its Series A together, so we count it in the company's total and not as one October deal.
Fragment's company announcement described purchasing and payment exceptions in manufacturing, while Project Suppliers and Syncmeon address marketplace-style supplier discovery. Their customers face different purchasing problems. To call this a wider rebound, we would need a run of busy months. October alone cannot settle that.

Our document detailing everything you need to know about procurement software gets updated several times a month, so you always get the latest view of where things stand.
Are procurement software funding rounds getting much bigger?
No. The typical procurement software round is slightly smaller than at this point last year, even with several huge headline deals.
The year-to-date median round is $6.0M, against $6.5M in the comparable period of 2025. At the same point in 2024, the median was $5.0M, so this year's middle transaction is larger against that earlier baseline. The median amount raised per funded company, rather than per financing event, is $6.5M this year, the same as at the same point last year.
Look at the rounds on either side of that middle. This year has 17 rounds under $5M totaling $43M, and 13 deals from $5M to under $20M totaling $121M+. The same period of 2025 had 18 sub-$5M deals totaling $38M and 13 deals in the next bucket totaling $127M. These modest changes do not resemble an across-the-board jump in early funding sizes.
Contrast those transactions with the much larger ORO Labs and Freehand financings. Large checks influence the total but do not change the median much. A founder watching the largest rounds might miss how little the middle of the market has moved.
Are procurement software seed rounds drying up?
Seed rounds have become less common this year, but procurement software companies are still entering the funding market.
We counted 19 Seed deals worth $64M this year to date, compared with 24 Seed deals and $89M during the same period of 2025. The Seed share of all deals dropped from 55% to 49%. At the same point in 2024, there were 14 Seed deals worth $52M and Seed represented 50% of activity. Seed funding is weaker than at this point in 2025, though the deal count remains above the comparable 2024 level.
The new funding is directed at concrete workflow problems. TradeForm's $2M Seed in April 2026 targets direct-materials procurement agents. Prolo's $5.4M Seed in July 2026 helps organizational buyers search for suppliers. Atmospheric AI's $10M Seed in November 2026 focuses on raw-material production chains. They are different bets on software that might shrink the time needed to find or approve suppliers.
The commercial rationale is supported by other, older products. LightSource's September 2025 Time Manufacturing case study described savings from standardizing requests for quotation and supplier collaboration. But a customer case study cannot prove that new Seed-funded startups will achieve the same results. The funding evidence says early opportunities remain open, while the number of successful financings has narrowed this year.
The newer companies receiving funding are also changing. Among startups funded this year to date, 63% were founded since 2022, compared with 57% at this point in 2025 and 41% in the same period of 2024. New products keep arriving, even as fewer Seed rounds are closing.
Are giant procurement software rounds becoming normal?
No. Giant procurement software rounds remain standout events, not the ordinary financing size.
The latest year-to-date period contains 1 round of $100M or more, representing 3% of disclosed rounds: ORO Labs' Series C in March 2026. The comparable period of 2025 had no such deal. The same period of 2024 included Zip's $190M Series D+ in October 2024, which shows that large procurement financings are not a novel invention of the AI-agent cycle.
The companies have something in common beyond size. Zip's October 2024 announcement described large enterprise deployments and a procurement platform handling purchasing workflows across suppliers and internal approvals. ORO's March 2026 statement cited named enterprise customers and reported strong revenue growth. Both presented procurement software as infrastructure for large organizations, not a disposable standalone feature.
Most procurement software rounds remain far smaller, and Seed or Series A financings are the most common named stages. A few isolated nine-figure rounds do not make checks of that size routine.
Are Series A procurement software companies attracting more capital?
Procurement software Series A funding is stronger in dollars this year even though there have been fewer Series A deals.
We tracked 7 Series A rounds totaling $127M this year to date, versus 9 rounds worth $114M+ in the same period of 2025. The median Series A rose to $18M from $14M. At the comparable point in 2024, 6 Series A rounds totaled $81M+ with a $16M median. The 2026 result therefore looks stronger over more than one comparison window.
Several current rounds demonstrate the range within the stage. Didero raised a $30M Series A in February 2026 for procurement communication and execution tools. Lio raised a $30M Series A in March 2026 for enterprise purchasing agents. Magentic raised an $18M Series A in September 2026 for procurement data and autonomous workflows. These companies do not compete for identical tasks, but they are all selling software that does more than show a purchasing dashboard.
Didero's February announcement described agents working in the messages and systems manufacturers already use. Lio's March announcement explained how its agents carry out purchasing tasks under enterprise controls. Their customer problems help explain the rounds, but the bigger Series A total does not mean every founder can get a larger check.

In our report covering the procurement software market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Series B where procurement startups get their biggest checks?
Series B rounds take a large share of procurement software dollars, even though Seed rounds remain much more common.
Year to date, 6 Series B deals have raised $229M, representing 40% of disclosed capital and 15% of all deals. In the same period of 2025, 5 Series B deals totaled $206M+, while the comparable period in 2024 had 4 such rounds worth $144M. The latest Series B median is $30M, below the $40M median from the 2025 comparison but above the $28M median in 2024.
Freehand and Naboo secured substantial Series B support for enterprise spend and corporate-event procurement, respectively. SPARETECH's $20M Series B in November 2026 financed spare-parts inventory intelligence for industrial customers. These businesses face different buying cycles and implementation challenges, yet all can point to operations in which managing supplier spend is financially consequential.
A stage with only a few deals can capture a lot of money when standout companies raise. Company announcements point to customers and deployments, but they do not reveal which milestone persuaded each investor.
Why aren't more procurement software startups reaching late-stage funding?
Late-stage procurement software financings remain rare, and the current year's dollar growth is not evidence that many startups have reached maturity.
This year to date includes 2 Series C rounds totaling $107M+, compared with 3 rounds and $137M in the same period of 2025. No Series D+ or Growth Equity deal appears in the current year-to-date cohort. The comparable 2024 period did include 2 Series D+ deals worth $205M, led in size by Zip's October financing. The stage pipeline therefore does not show a simple upward progression toward more advanced rounds.
That does not mean companies are failing. ORO Labs' financing drew attention to large-scale procurement orchestration, while Candex's $7M+ Series C in March 2026 involved a different tail-spend purchasing and supplier-payment model. The Series C name alone does not say how much revenue or scale an enterprise-software company has attained.
Established procurement companies may also expand without raising a qualifying private round. What we can see in the current deals is a small number of mature financings, not a broad wave of later-stage capital.
Is AI procurement more than an investor buzzword this year?
Yes. Several procurement software startups now sell AI agents designed to perform real purchasing tasks, although their returns remain to be proven.
ORO Labs builds procurement orchestration; Didero handles manufacturer supplier interactions; Lio addresses autonomous enterprise purchasing; and Fragment develops exception reconciliation. These products perform different tasks, so their appeal cannot be reduced to one agentic AI interface. The distinction between an agent doing the work and a chatbot merely answering questions is central to their product claims.
Those claims can be tested against what customers do. Zip introduced governed procurement Superagents in June 2026, including controls and audit trails for activities such as reviews and approvals. LightSource's 2026 product announcement described AI features for quote preparation, supplier communication and sourcing analysis. Neither announcement proves that every promised workflow is fully autonomous, but both describe specific integrations with operational purchasing tasks.
Investors are backing software that takes over tasks purchasing teams used to do by hand. Whether customers stay will depend on how often the agents get the work right.
Which procurement software category is attracting the largest checks?
Procurement intake and orchestration leads the current year's procurement software categories by disclosed capital, rather than by the number of transactions alone.
The category recorded 9 deals worth $241M this year to date, or 42% of disclosed capital and 23% of deals. The same period of 2025 had 6 intake and orchestration deals worth $137M+, representing 23% of capital and 14% of deal count. The category gained both deals and dollars, which is harder to dismiss as a single outlier.
ORO Labs supplied the largest individual round, while Lio, Didero and Magentic show multiple products competing for purchasing workflow budgets. Omnea's $50M Series B in September 2025 provides the prior-year context: the company described serving Spotify, Wise and other corporate buyers and coordinating vendor reviews across functions.
Employees request purchases in one tool, risk teams check suppliers in another, and finance approves payment elsewhere. Orchestration products try to connect those steps. More investors are backing that approach, even though the winning products are still being decided.
The table below shows each procurement category's financing in this year to date against the same calendar period of 2025, ordered by current capital. Procure-to-Pay's $23M+ is a reported minimum.
| Category | Current deals | Prior deals | Current capital | Prior capital |
|---|---|---|---|---|
| Procurement Intake & Orchestration | 8 | 6 | $201M | $137M+ |
| Spend Intelligence & Controls | 5 | 8 | $121M | $134M+ |
| Procure-to-Pay | 5 | 5 | $70M+ | $87M |
| Services Procurement | 1 | 2 | $70M | $26M |
| Strategic Sourcing | 9 | 13 | $45M | $148M+ |
| Procurement Marketplaces | 8 | 9 | $39M | $48M |
| Supplier Management & Risk | 3 | 1 | $23M | $4M |
“+” indicates a reported funding minimum; category capital comparisons cover amounts publicly disclosed.

In our research about procurement software startups, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Has strategic sourcing stopped attracting procurement software investors?
Not stopped, but strategic sourcing has lost significant capital share this year despite remaining busy.
This year to date, strategic sourcing recorded 11 deals and $64M, compared with 12 deals and $146M+ at the same point in 2025. Its share of deals edged up from 27% to 28%, while its share of disclosed capital dropped from 25% to 11%. It still has the highest deal count among procurement categories, but it no longer leads by capital.
The previous period had Pactum AI's $54M Series C in June 2025 and Arkestro's $36M Series B in May 2025, which raised the category's dollar total. This year, activity includes TradeForm's $2M Seed in April 2026, Aron's $6M Seed in September 2026 and Atmospheric AI's $10M Seed in November 2026. Those newer products focus on direct-materials sourcing, negotiation assistance and supply-chain intelligence.
Market demand for better sourcing is still visible. LightSource's Time Manufacturing case study described awarded savings from supplier quote management. Buyers still need sourcing software, but the newer rounds are mostly smaller than the large transactions of the previous comparison period.
Is spend intelligence becoming less attractive than procurement orchestration?
Partly. Spend intelligence and controls is raising fewer procurement software rounds, while orchestration now takes a bigger share of the money.
We tracked 5 spend-intelligence deals worth $121M this year to date, versus 8 deals and $134M+ in the comparable period of 2025. Their share of transactions declined from 18% to 13%, while the category still captured 21% of disclosed capital. One large check can make the dollar total look resilient despite fewer companies receiving funds.
Freehand's financing is the major recent example; SiFi's $20M Series A in February 2026 and SPARETECH's $20M Series B in November 2026 serve different purchasing and inventory needs. The previous period included Vertice's $50M Series C in January 2025 and Green Cabbage's $40M Series B in October 2025. Spend controls are therefore not disappearing. Investment is concentrating in a few visible operating approaches.
Outside the funding statistics, Vertice's October 2026 procurement-cycle study reported long internal approval times for software contracts, while SPARETECH's November announcement described industrial companies managing costly spare-parts inventories. Both identify persistent buyer pain, even though the software products are different. The funding numbers show fewer spend-management businesses raising, even though a few still secure large checks.
Are procurement marketplaces still drawing new investment?
Procurement marketplaces are still drawing funding, but they have become a smaller story this year than orchestration software.
The year-to-date marketplace category contains 8 deals worth $39M, compared with 9 deals and $48M in the same period of 2025. It represented 21% of deal activity, against 20% before, but just 7% of current disclosed capital versus 8% previously. Transaction activity is fairly resilient; the money committed has not kept pace with the leading software categories.
Examples show why marketplaces should not be treated as a single consumer-style business model. BRKZ raised a $13M Series B in September 2026 for construction-material procurement in Saudi Arabia. Prolo raised a $5.4M Seed in July 2026 for organizational sourcing. SkySelect raised a $9M round of undisclosed stage in March 2026 for aviation-parts procurement. Each focuses on a specific professional purchasing process with specialized supplier requirements.
BRKZ's September financing announcement also included an $18 million growth-debt commitment alongside equity. Mixing those would overstate its equity funding. The company described AI-assisted quotation and fulfillment for contractors, which helps explain why investors may support a marketplace with a strong procurement workflow. Marketplaces are still raising money, but they have yet to match the large checks flowing into broader enterprise purchasing tools.

Learning from others' mistakes is the cheapest lesson there is. In our market report about procurement software startups, we look at what broke startups before you, so you don't repeat it.
Is Europe losing ground to American procurement software startups?
European procurement software investment is lagging its prior-year pace while the United States maintains a large share of capital.
Europe attracted 12 deals worth $186M this year to date, against 19 deals and $212M+ in the same period of 2025. Its deal share fell from 43% to 31%, while North America registered 18 deals and $313M+ this year, compared with 18 deals and $344M+ at the same point last year. The United States specifically had 17 deals worth $305M+ in the current period, the largest national pool.
Europe still has well-funded procurement products. France-based Naboo and Pivot both completed substantial financings in 2026 to expand corporate-event procurement and enterprise purchasing controls. Germany's SPARETECH raised a $20M Series B in November 2026 for spare-parts data, backed by Blume Equity and Insight Partners. These companies have international customer ambitions.
The deal count tells us where startups raised money, not where companies prefer to buy their procurement software. Europe still has strong vendors, but noticeably fewer of them are closing rounds.
Is Saudi Arabia becoming an important procurement software market?
Saudi Arabia has become a distinct procurement software funding location this year, though the number of recorded companies remains limited.
Saudi-headquartered startups recorded 4 deals and $35M in the current year-to-date period, or 10% of all deals and 6% of disclosed capital. Across the Middle East, we counted 4 deals worth $35M, up from 3 deals and $20M in the same period of 2025. This is visible activity, but a small sample should not be mistaken for a regional investment transformation.
SiFi's $20M Series A in February 2026 backed a spend-management platform, while BRKZ's $13M Series B in September 2026 supported procurement of building materials. Fitting's $1.1M Seed in August 2026 and Project Suppliers' $1M Seed in October 2026 also focus on procurement marketplaces. These companies reflect businesses that must manage supplier availability and purchasing rather than a broad social-commerce trend.
BRKZ's company announcement described its material-sourcing platform and the distinction between fresh equity and debt capital used for working needs. That detail is especially relevant where procurement platforms combine transactions with financing tools. We count the procurement equity and leave out the debt. Saudi startups are getting real backing, although the U.S. market remains far larger in both deals and dollars.
Are more venture investors joining procurement software funding?
Procurement software attracted fewer distinct investors and leads than at this point last year, although its investor base remains broader than two years ago.
We identified 60 unique investors this year to date, compared with 76 in the same period of 2025 and 35 in the equivalent period of 2024. The number of unique identified lead investors followed the same pattern: 41 now, against 55 and 30 respectively. Lead information was available for 85% of current deals, so the figures describe a substantial part of the financing activity without pretending to cover every undisclosed investor.
Brighton Park Capital and Goldman Sachs Alternatives share first place among this year's lead investors, because they co-led the ORO Labs round. In the 2025 comparison, Insight Partners led 3 rounds with a combined round value of $119M. This year no disclosed lead investor appears across multiple qualifying rounds. It would be wrong to describe one prominent transaction as proof that a fund is continuously buying the entire sector.
ORO Labs, Freehand and Naboo show what large rounds can still look like. But fewer funds are taking part and fewer startups are completing rounds. Today's strong headlines belong to a narrower market.
So, what are the funding trends in procurement software right now?
Procurement software funding is close to last year's level in disclosed dollars but becoming more concentrated in larger deals, especially enterprise orchestration and AI-driven purchasing work.
ORO Labs' $100M Series C in March 2026 is the largest current-year round, and Brighton Park Capital and Goldman Sachs Alternatives, which co-led it, share first place among lead investors. Stronger funding than at the same point in 2024 shows the sector has advanced, but falling deal count versus the same months of 2025 prevents us from calling this a broad boom. The capital market is rewarding selected procurement products that can tackle costly workflows at scale; the typical financing environment remains more restrained.
The table below shows what we found.
| Question | Answer |
|---|---|
| Does a steady investment total mean as many funded startups? | No, procurement capital is roughly flat while activity narrows. We recorded 39 deals in the current partial year. Fewer financing events make the growth less broad. |
| Has this year already beaten last year's full total? | Not yet, although it has passed the full 2024 total. Current funding equals 93% of the 2025 full-year minimum. Undisclosed earlier amounts prevent an absolute historical ranking. |
| Can ordinary rounds sustain the capital increase? | Not when compared with the same calendar period of 2025. Excluding above-$50M deals leaves $324M+ of funding currently. That drop is far steeper than the 3% headline dip. |
| Is there genuine progress since the earlier cycle? | Yes, the multiyear comparison shows a larger market. Deals are up 39% from the comparable 2024 period. This offsets an overly pessimistic reading of recent weakness. |
| Did the opening quarter determine the year? | It delivered this year's largest quarterly procurement software funding total. Q1 2026 recorded $314M+ across procurement software deals. Subsequent quarters have remained active without matching it. |
| Are companies routinely raising enormous venture rounds? | No, giant procurement software checks remain unusual financing events. Only 3% of disclosed rounds this year reached $100M or more. Most financings are far smaller than that. |
| Are early growth companies securing larger checks? | Yes, Series A capital has advanced despite fewer transactions. Series A funding reached $127M in the current period. A few ambitious enterprise products account for much of it. |
| Is purchasing coordination becoming the main investment theme? | Yes, procurement workflow coordination is attracting substantial venture capital. Intake and orchestration received $201M this year so far. Investors see value in automating cross-team purchasing execution. |
| Has supplier sourcing lost its place entirely? | No, strategic sourcing still produces frequent financing events. It logged 9 deals in the current period. Its falling dollar share is the more important change. |
| Are European procurement startups keeping up? | No, their transaction breadth has declined substantially this year. Europe recorded 12 deals compared with 19 previously. Large individual wins do not erase the regional decline. |
| Are more venture funds entering than previously? | Not compared with the same period last year. Our research identified 60 unique procurement software investors this year. The investor base remains broader than two years earlier. |

If you build or invest in the procurement software market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Our methodology
Our data runs through November 14, 2026. We cover eligible procurement software financings since January 2024 and compare January 1, 2026 to November 14, 2026 with January 1 to November 14 in 2025 and 2024. For annual benchmarks, we use the complete calendar years January 1 to December 31 in 2025 and 2024. The current year and Q4 2026 are partial; we never annualize them.
We count private-company equity financings of $300K or more. We exclude debt, grants, loans, unconverted convertibles, SAFEs and public offerings. An equity announcement is counted once, even when it is reported by multiple participating investors. Transactions without a public amount count in deal totals but not in money totals, which is why reported capital sometimes carries a plus sign.
Procurement software includes products that help organizational buyers find, evaluate, approve, onboard, pay and manage external suppliers. Our categories encompass strategic sourcing, supplier risk, purchasing intake and orchestration, procure-to-pay, spend controls, services procurement and business marketplaces with substantial buyer-side procurement workflows. We retain borderline companies where procurement software is a meaningful core product, and exclude general ERP, payment-only services, ordinary distributors, seller-side billing automation and consulting without scalable proprietary software.
Every included company meets our startup definition: independent, founded in 2000 or later, built to grow around a new product or technology, and financed by founders or eligible private backers. Recently public and recently acquired businesses are treated only within our defined recent-listing and acquisition windows. We use announced round stages, headquarters country for geographic classification, and our own primary-product grouping for procurement categories. Early- and later-stage shares use only deals with an identifiable stage.
We favor company releases, filings and reliable independent press over uncorroborated database entries.
Rounds confirmed by a company announcement, a press article or a regulatory filing are counted in full. Where no article exists, a round is counted only when at least two recognised databases agree on its date (within one month) and amount (within 5%), and it is marked as low confidence; a round found in a single database stays in the company's history but is left out of totals. For companies that have raised more than $100M, every round counted is backed by an article.
We separate one financing from a company's lifetime fundraising and exclude debt portions of mixed capital announcements. The current-year quarter series includes only transactions with a known quarter; 2 deals of 2024 are dated only by the year, so they count in the annual total but in no quarter. Missing disclosed amounts or financing stages are never silently estimated for aggregates.
If an article reports more procurement investment than our totals, it may include loans, grants, companies outside our buyer-side software definition, earlier financing dates or rounds below the threshold. A quiet current month may also be incomplete rather than structurally weak. We therefore compare matching elapsed calendar periods and describe current quarterly activity as partial instead of presenting incomplete observations as a completed year.
Key sources include ORO Labs' March 2026 Series C and enterprise customer evidence, Freehand's July 2026 funding and named corporate customers, Naboo's February 2026 funding and international procurement expansion, Fragment's October 2026 financing and automation of purchasing exceptions, Pivot's May 2026 financing and processed invoice volume, Didero's February 2026 Series A and manufacturer procurement workflows, Lio's March 2026 Series A and procurement agent proposition, SPARETECH's November 2026 financing and global manufacturing customers, BRKZ's September 2026 equity round, debt and construction procurement product, Omnea's September 2025 Series B and supplier workflow customer traction, Levelpath's June 2025 funding and AI-native buying workflows, Pactum AI's June 2025 Series C and automated supplier negotiations, Vertice's January 2025 Series C and procurement controls, Zip's October 2024 Series D and enterprise procurement platform, ProcurePro's May 2026 financing and construction purchasing workflows, Procure Ai's November 2025 Seed and operational customer examples, LightSource's Time Manufacturing case study for sourcing efficiencies, LightSource's July 2026 procurement agent product announcement, Vertice's October 2026 observations on software purchasing approval cycles, Zip's June 2026 governed AI agents and audit trails for purchasing work, and Magentic's September 2026 funding and procurement data product.

In our report covering the procurement software market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us