Is the Space Economy growing now?
Whether you're building or investing in the space economy, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The Space Economy is growing now, but the growth is concentrated in infrastructure-like segments and it is not equally profitable everywhere.
The clearest pattern is that space has become a deployment market. The strongest signals are satellites placed in orbit, government contracts, recognized revenue, backlog, and paying customers, not distant total-addressable-market slides. In September 2026, the OECD put 2025 space-related revenue at an estimated $550 to $600 billion, with nearly 15,000 operational satellites by mid-2026.
Capital is still flowing, and in very large checks. Space Capital counted $92.5 billion invested in its broad “space economy” definition in the first nine months of 2026. Stoke Space announced a $1 billion Series E in September 2026. But big rounds now also go to rockets that have not yet reached orbit, which adds risk.
Launch is still growing over the long run, but it rests on one company and 2026 is not an acceleration year. SpaceX’s SEC filing shows 110 Falcon launches in the first nine months of 2026, against 124 a year earlier, while Starship deployed its first operational Starlink satellites in September 2026. Rocket Lab pushed Neutron’s first flight into 2027.
Satellite broadband is the cleanest commercial engine. SpaceX, which now files quarterly reports with the SEC, said Starlink reached 13.6 million consumer service lines at the end of September 2026, and its Connectivity segment brought in $5.25 billion in the third quarter, up about 69% year over year. Revenue per consumer user is falling, so the growth comes from volume.
Direct-to-phone is becoming real, but it should not be confused with mature mobile broadband. T-Mobile and Starlink prove that ordinary phones can connect through satellites. AST SpaceMobile had 13 satellites in orbit and $31.5 million of quarterly revenue in its August 2026 results, still far from the density a full service needs.
Earth observation is growing most clearly where the buyer is a government, defense agency, or sovereignty-focused customer. Planet reported $116.1 million of quarterly revenue in September 2026, up 58%, and won a dedicated-satellite services contract from the German government. BlackSky’s earlier revenue drop shows that demand still does not convert evenly for every operator.
Government procurement is probably the most important non-obvious growth driver. SDA, Space Force, Golden Dome, IRIS², and Germany’s sovereign contracts show that space is increasingly treated as defense and sovereignty infrastructure, not just as a commercial communications layer. Defense and sovereign buying is an easy-to-miss growth driver, and we weigh what makes the market accelerate in our report on the space economy.
Public space companies are separating into operators and stories. SpaceX, Rocket Lab, Planet, and Redwire have credible revenue, backlog, or contract signals, while Virgin Galactic, with $0.1 million of revenue in its second quarter and its first commercial flight pushed to early Q2 2027, shows that bookings are not flights.
Commercial demand is strongest when space solves an existing budgeted problem. Airlines, ships, remote facilities, telcos, governments, and satellite operators are buying connectivity, monitoring, or launch slots; tourism and vague future-space concepts are not driving the market right now.
The market is also consolidating because customers want suppliers that can actually deliver. Rocket Lab closed its Mynaric and Motiv acquisitions, and acquisitions around manufacturing, optical communications, robotics, and defense systems suggest the sector is becoming more serious, even if that seriousness is less romantic than the old startup narrative.
The conclusion is that the space economy is growing now, but the right mental model is not “all space is booming.” It is “orbital infrastructure is scaling, while space tourism, unfinished rockets, and speculative moonshots remain exposed.”

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the space economy market, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why is it difficult to say whether the space economy is growing?
Because the space economy is not giving one clean signal, and even its size depends on who is counting.
Basically, it looks strong if we look at satellite broadband, defense, Earth observation, and government launch contracts. It looks much weaker if we look at space tourism, rockets that have not flown yet, dilution-heavy public companies, or “future space” narratives that still have little revenue.
The definition problem is real. In September 2026, the OECD estimated 2025 global space-related revenue at $550 to $600 billion, and said the range depends on how space is defined. The Satellite Industry Association, using a narrower framework, put the 2025 figure at $429 billion. Both are useful. They are not two measurements of the same basket, so neither one contradicts the other.
The positive evidence is hard to ignore.
SpaceX’s third-quarter 2026 filing showed Starlink at 13.6 million consumer service lines, up from 7.2 million a year earlier. Planet reported $116.1 million of quarterly revenue in September 2026, up 58% year over year. Rocket Lab reported $234 million of second-quarter revenue, up 62%, and a backlog of $2.36 billion. These are revenue, deployment, and backlog signals, not vague enthusiasm.
But the worrying evidence is equally concrete.
Blue Origin’s New Glenn suffered a major static-fire explosion in late May 2026, damaging launch infrastructure that matters for Amazon, AST SpaceMobile, and NASA-linked missions. In October 2026, Rocket Lab moved Neutron’s first flight into 2027. Virgin Galactic reported $0.1 million of second-quarter revenue and then pushed its first commercial Delta flight to early Q2 2027. SpaceX itself flew fewer Falcon missions in the first nine months of 2026 than a year earlier. The market is not “up everywhere.”
So the real question is whether the market is expanding in real customer spending, real satellite deployments, real procurement, real revenues, and real capital formation.
What do analysts say about space economy growth?
Analyst forecasts are broadly positive, but they are not measuring exactly the same market.
Novaspace’s Space Economy Report, released in January 2026, estimated the global space economy at $626.4 billion in 2025 and forecast $1.01 trillion by 2034. That implies about 5.5% annual growth. This is useful because Novaspace is relatively close to the actual space-sector revenue base: satellites, launch, ground systems, services, government spending, and space-enabled commercial activity. Counting satellites, launch, ground systems and services is part of our ground-up size estimate, with every assumption visible, in our space economy market report.
The OECD’s Space Economy at a Glance 2026, published in September 2026, is the most cautious recent benchmark. It estimates $550 to $600 billion of 2025 space-related revenue and nearly 15,000 operational satellites by mid-2026. It also stresses that growth is concentrated and unevenly profitable, with some newer firms still putting more than 60% of their sales into R&D and capital spending.
Space Foundation’s global economy edition estimated the space economy at $613 billion in 2024, up 7.8% year over year. That number tells us something important: the space economy was already growing before the 2026 funding wave, so the question is whether that growth is continuing rather than whether a dead market suddenly restarted.
McKinsey and the World Economic Forum use a wider frame. Their 2024 report projected the space economy could reach $1.8 trillion by 2035, but that includes “space reach”: the economic value enabled by space across logistics, agriculture, insurance, telecom, climate monitoring, navigation, and other industries. That is valuable for understanding strategic importance, but less useful for proving whether space companies are getting paid right now.
Investor-oriented views have often emphasized satellite broadband as the largest incremental commercial opportunity. SpaceX’s own filings now back that up with hard numbers, which we look at below.
The consensus is therefore positive, but not precise. The forecasts agree that the market is growing. They do not prove that every subsegment is healthy, or profitable, today.
Analyst forecasts are only one layer of evidence. The real test is what governments, operators, airlines, telcos, defense agencies, and public companies are doing right now.
So let’s check the recent signals together, so we can give you a solid answer about whether the space economy is growing now.

Theory only gets you so far. In our research about the space economy, we dig up the real signals from the field and show you the ones worth watching.
Are space companies raising real money again?
Space companies are raising serious money, and in 2026 the checks got even bigger. But the money is going to fewer companies, and some of it now funds rockets that have not flown.
The first signal is the scale of the flows. Novaspace counted $9.4 billion of private space investment in Q1 2026 across 82 companies, up 145% year over year, while the number of funded companies declined. Space Capital, which uses a much broader definition that reaches into defense manufacturing and related infrastructure, reported $92.5 billion invested in the first nine months of 2026, including $22 billion in the third quarter. Those two series measure different things and should not be compared directly. Both point the same way.
The second signal is the size of individual rounds. Astranis announced a $450 million Series E in May 2026, Impulse Space raised $500 million in June 2026, and ICEYE reportedly raised about €1 billion at a roughly €10 billion valuation the same month. In September 2026, Stoke Space announced the initial closing of a $1 billion Series E, bringing its total raised to $2.3 billion; Reuters reported a valuation of roughly $10 billion. Space Capital counted $7.8 billion raised by launch companies alone in 2026.
The third signal needs caution. In July 2026, The Information reported that Blue Origin was working on a $10 billion raise at a $130 billion pre-money valuation, based on a term sheet. A completed round of that size has not been confirmed. It is a proposed deal, not money in the bank.
Public companies can also still access capital if they look strategically important. SpaceX now files quarterly reports with the SEC, and Rocket Lab, Planet, and AST SpaceMobile all reported large cash positions or fresh capital in early 2026 to fund their build-outs. That matters because space companies burn capital before they scale; access to liquidity determines who can survive the production ramp.
So investors are backing space where it behaves like infrastructure: launch capacity, sovereign intelligence, orbital logistics, connectivity networks, and defense resilience. The weak companies are still weak. The strong categories are getting funded, and the riskiest money is going into launch vehicles that still have to prove they work.
Is launch still expanding when SpaceX flies fewer Falcon rockets?
Launch capacity is still expanding over the long run, but 2026 is not a clean acceleration year, and the market still depends heavily on SpaceX.
The FAA’s FY2026 commercial space forecast counted 204 U.S. commercial launch and reentry operations in FY2025 and projected 209 to 214 in FY2026. That is an activity forecast based on operator plans and licensing workload, not a reported total.
SpaceX’s own numbers are more mixed than its reputation. Its third-quarter 2026 SEC filing reports 110 Falcon launches in the first nine months of 2026, against 124 in the same period of 2025, and launches for external customers fell from 36 to 29. Part of the reason is that SpaceX is shifting Starlink deployment toward Starship. On 28 September 2026, Starship reached orbit and deployed 26 Starlink V3 satellites, its first operational payload delivery, although the mission flew a shortened profile after an engine problem. SpaceX says every Starship flight so far has been for its own payloads.
The broader market is less balanced. BryceTech’s 2025 orbital launch review found that small satellites under 1,200 kilograms made up 98% of spacecraft launched, showing that launch demand is pulled by constellations, not one-off large satellites. Independent trackers disagree on the exact 2026 worldwide launch count because they use different definitions, so a single audited global total is not available.
The demand side looks firmer than the supply side. Rocket Lab signed 20 more Electron launches with Synspective in September 2026, scheduled for 2028 to 2031, and won a $266 million Space Force contract in July 2026. But Neutron, its medium-lift rocket, will not fly before 2027.
This is why launch is both a positive and a risk.

In our market report about the space economy, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Is satellite broadband demand growing right now?
Yes, and satellite broadband is the clearest growth engine in the space economy right now.
Starlink is the first signal.
SpaceX’s third-quarter 2026 results, unusually detailed public disclosures, settle a debate that used to rely on leaks. Starlink had 13.6 million consumer service lines at 30 September 2026, up from 7.2 million a year earlier and 12.0 million at the end of June. The Connectivity segment generated $5.25 billion of revenue in the quarter, against $3.10 billion a year earlier. SpaceX’s consolidated revenue of $14.6 billion is not a space number: it includes an AI segment the company calls Super Intelligence. For the broadband question, Connectivity revenue is the figure that matters.
Amazon Leo is the second signal.
In June 2026, Amazon said it had completed 11 missions and deployed more than 300 satellites in its first year of launch operations, making it the third-largest constellation in orbit. Amazon also says it has secured more than 100 launches. That tells us the market is no longer a single-player experiment. A cloud giant is spending real launch and satellite capex to build a second scaled network.
The third signal is customer type.
Amazon Leo has named commitments or relationships with Delta, JetBlue, AT&T, Vodafone, DIRECTV Latin America, Australia’s NBN, and NASA. SpaceX says Starlink sales to enterprise and government customers also rose in 2026. When telcos and airlines commit, they are not buying “space.” They are buying coverage where terrestrial networks are weak.
Broadband is pulling the space economy toward recurring services.
That is healthier than selling one satellite at a time. The pressure point is pricing: SpaceX reports that consumer revenue per user fell from $83 to $69 a month over the year as it expanded into cheaper markets. That is not a demand problem as long as volume, hardware cost, and launch cost keep improving. Falling revenue per user raises the question of which business models keep their margins, which we look at in our report covering the space economy market.
Is satellite-to-phone becoming real, or still a demo?
Satellite-to-phone is real for texting and light data, but it is still in the early-coverage, early-capacity phase.
T-Mobile’s T-Satellite with Starlink is the cleanest commercial signal. The service launched commercially in July 2025 with SMS, MMS, picture messaging, and short audio clips, and T-Mobile now presents it as an add-on or included service that works when towers cannot, across outdoor areas in the U.S., Canada, New Zealand, and Japan. The user does not need a satellite phone. Ordinary phones are the distribution channel.
The second signal is that app-level service is appearing, not just emergency SOS. T-Mobile’s materials describe texting and select satellite-ready apps. In August 2026, Japan’s KDDI signed an agreement for Starlink’s next-generation direct-to-cell service, with satellite broadband and voice aimed for the end of 2027. That is a target, not a service people use today.
The third signal is AST SpaceMobile’s execution. In its August 2026 results, AST reported $31.5 million of quarterly revenue, about $1.30 billion of contracted backlog, and 13 satellites in orbit after the BlueBird 8 to 13 launches. Backlog is future contracted money, not revenue already earned. This is exactly what early infrastructure markets look like: real partnerships and government interest, heavy losses, and a network that is not yet dense enough for continuous service.
The best interpretation is that direct-to-cell is a real market opening, not a finished market. It proves demand for dead-zone coverage. It does not yet prove high-throughput economics across millions of users.

In our document detailing everything you need to know about space economy, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Is Earth observation turning into a real demand market?
Earth observation is turning into a real demand market, especially where it serves defense, sovereignty, and AI-enabled intelligence.
Planet Labs is the strongest public-company signal. In September 2026, Planet reported $116.1 million of revenue for its fiscal second quarter of 2027, up 58% year over year. Two weeks later, it announced a German federal contract giving the government exclusive access to dedicated satellites; the contract value was not disclosed. That matters because the buyer is paying for ongoing access, tasking, and analytics, not just images bought one at a time.
ICEYE gives a different, even more telling signal. In March 2026, ICEYE disclosed more than €250 million of 2025 revenue, over €100 million of EBITDA, more than €350 million of cash, and €1.5 billion of contracted backlog. For a SAR satellite company, EBITDA and backlog are especially important because radar imagery is expensive to build but valuable when governments need all-weather, day-night intelligence.
BlackSky complicates the picture. It announced up to $160 million of new contract wins and raised guidance in Q1 2026, but its quarterly revenue still fell year over year from $29.5 million to $20.8 million. Demand exists, but not every EO company is converting it smoothly. The market is not a rising tide that lifts all boats equally.
Satellogic adds one more signal at the smaller end. In May 2026, it reported Q1 revenue up 80% year over year to $6.1 million and signed a $12 million in-orbit satellite agreement with a sovereign defense customer. The absolute revenue is still tiny, but the customer pattern matches Planet and ICEYE: sovereign buyers want persistent sensing.
Are governments buying more space capability right now?
Government demand is one of the strongest growth signals in the space economy.
The U.S. Space Development Agency awarded about $3.5 billion in December 2025 for 72 Tranche 3 Tracking Layer satellites, to Lockheed Martin, Rocket Lab, Northrop Grumman, and L3Harris. This is concrete procurement: the government is buying proliferated LEO missile warning and tracking capacity, not just funding research. Awards for missile warning and tracking capacity are a signal we watch quarter by quarter in our market report about the space economy.
The U.S. Space Force added more. In May 2026, it awarded SpaceX a $4.16 billion contract for space-based airborne moving target indicator capability, and Breaking Defense reported that more vendor awards were expected. In July 2026, Rocket Lab won a $266 million Space Force award for 12 suborbital launches, with options for up to six more. Optional missions are not guaranteed revenue, but the base award is real money.
Golden Dome is also changing the demand environment. Aerospace Corporation called it one of the most important developments affecting the defense space budget since the creation of the Space Force, and the spending plan includes space-based sensors, interceptors, launch and test-range infrastructure, and moving-target-indicator satellites. SDA requests for information and proposals add to that pipeline, but they are not awarded contracts yet.
Europe is moving in the same direction. The EU describes IRIS² as a secure connectivity system of roughly 290 satellites for authorized users. In September 2026, Germany chose Planet for dedicated sovereign satellite services. The point is not that these programs produce revenue tomorrow. The point is that space is becoming sovereignty infrastructure.
This is probably the most important non-obvious driver of the current market.

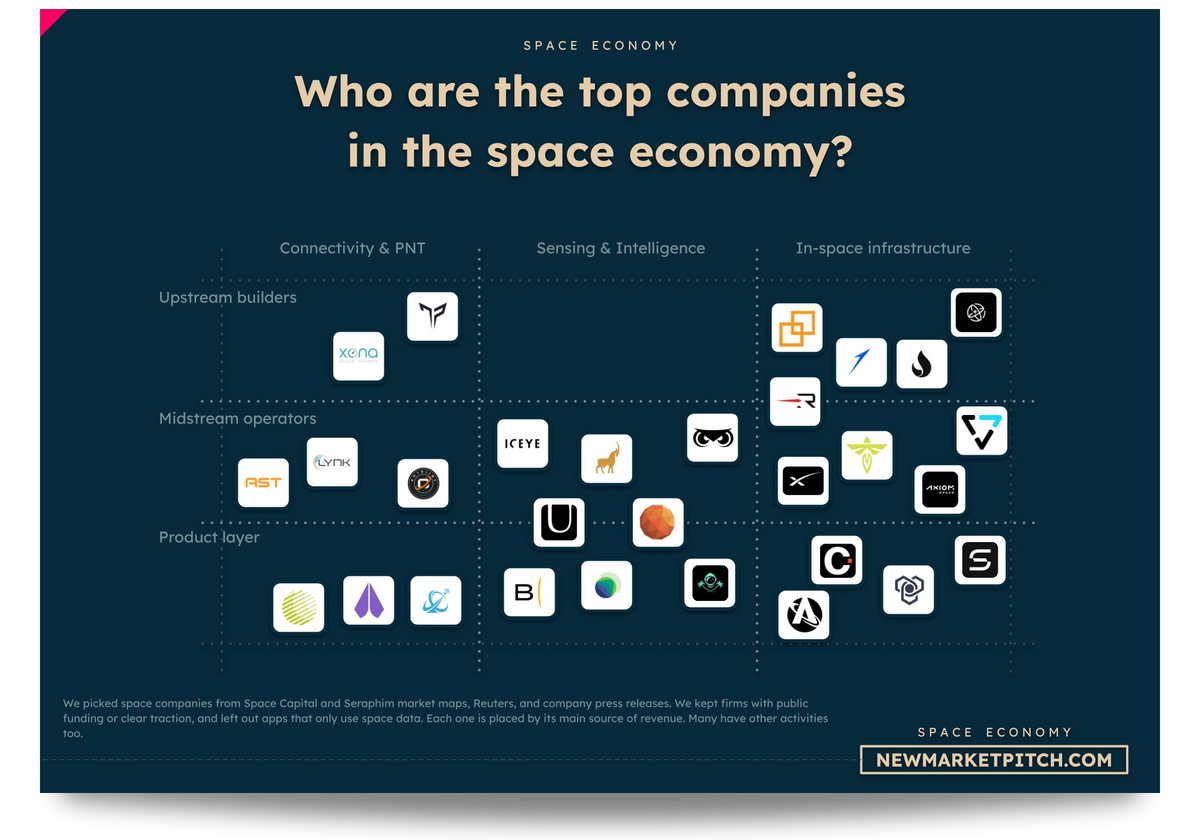
In our report covering the space economy market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Are public space companies showing real operating momentum?
Several public space companies are showing real operating momentum, but the public market still contains weak or overextended names.
SpaceX is now the biggest data point. Its third-quarter 2026 results showed Connectivity revenue up about 69% year over year, a level of disclosure investors did not have before.
Rocket Lab is the strongest diversified signal among smaller names. In August 2026, it reported second-quarter revenue of $234 million, up 62% year over year, and a record backlog of $2.36 billion. The tension is Neutron: in October 2026, Rocket Lab moved the rocket’s first flight into 2027, Its third-quarter results are scheduled for 9 November 2026.
Planet’s 58% revenue growth in its latest quarter puts it in the same group. Redwire also looked healthier in May 2026, with a book-to-bill ratio of 1.92 and record backlog of $498.1 million; a ratio above 1 means new orders are coming in faster than revenue is being recognized.
Intuitive Machines shows both strength and caution. Its Q1 2026 revenue reached about $186.7 million, almost triple the prior year, and backlog reached roughly $1.1 billion after the Lanteris acquisition. But much of that revenue came from the acquisition, so it is growth, but not clean organic acceleration.
The weak side is visible in Virgin Galactic and some former SPAC stories. Virgin Galactic’s $0.1 million of second-quarter revenue and repeated delays show that equity markets are funding a promise, not an operation. BlackSky’s falling Q1 revenue also shows that contract wins do not always translate into immediate top-line growth.
At the end of the day, the best companies are showing revenue, backlog, and procurement momentum, and the weaker companies are punished quickly when timelines slip. That is what a maturing market looks like.
Are commercial customers spending more on space services?
Commercial customers are spending more on space services, but mostly where the service solves an immediate connectivity, monitoring, or launch problem.
Aviation is the strongest commercial proof. In November 2025, IAG announced Starlink-enabled Wi-Fi for more than 500 aircraft across British Airways, Iberia, Aer Lingus, LEVEL, and Vueling, with the first aircraft going live in early 2026. Qatar Executive said in December 2025 that every Gulfstream and Bombardier aircraft type in its fleet would get Starlink. Airlines are buying passenger experience, loyalty, and premium connectivity.
Maritime and enterprise connectivity are also important. SpaceX says Starlink sales to enterprise and government customers grew in 2026, and Quilty Space had projected Starlink maritime revenue near $1.94 billion for 2026. Ships, aircraft, mines, offshore platforms, and remote facilities pay more for reliable connectivity than a price-sensitive household user.
Satellite operators are committing to launch years ahead. In September 2026, Japanese radar-satellite operator Synspective signed 20 more Electron launches with Rocket Lab, bringing its total to 47 contracted missions, with the new launches scheduled for 2028 to 2031. The contract value was not disclosed, and contracted missions are not launches flown.
Satellite IoT is a quieter signal. IoT Analytics reported 7.5 million satellite IoT connections in 2024 and forecast the satellite IoT connectivity and equipment market to exceed $4.7 billion by 2030, growing at 26% annually. That shows demand for remote asset tracking, agriculture, logistics, energy, and environmental monitoring.
The caveat is that commercial demand is narrow. Space tourism is weak. Some commercial EO use cases are still small. The growth is strongest when the customer already has a budget line for connectivity, logistics, security, aviation experience, or infrastructure monitoring.

Our research about the space economy gets updated several times a month, so you always get the latest view of where things stand.
Are new space products like Starship flying now, or still on paper?
Some important new products are now flying, but the ones that work are infrastructure layers, and several others are still on paper.
Starship is the biggest hardware milestone. In September 2026, it reached orbit and deployed 26 Starlink V3 satellites, its first operational payload delivery. That is a real deployment. It is not yet a commercial launch service: SpaceX says all Starship flights so far have carried its own payloads, and this one flew a shortened profile after an engine problem.
Amazon Leo is a real productization signal. By June 2026, Amazon had deployed more than 300 satellites and planned to raise its launch rate. The strategic angle is AWS integration: Amazon wants to connect satellite broadband to cloud, enterprise, and government workflows.
AST SpaceMobile’s BlueBird satellites and Planet’s Pelican satellites are also flying. Planet’s Pelican program, which includes a sovereign reconnaissance satellite for Sweden, shows a move from general Earth imagery toward higher-resolution, customer-specific intelligence capacity.
Other products are still promises. Stoke Space’s Nova rocket is targeting its first orbital flight in early 2027, and Rocket Lab’s Neutron has slipped to 2027. Impulse Space’s $500 million June 2026 raise points to demand for orbital transfer and in-space logistics, but that market is still early.
Space-based data centers are the most speculative category. They get attention because AI power demand is exploding on Earth, but today we should treat orbital data centers as an option, not a current demand proof. Orbital data centers are still an option, not proof of demand, and we sort proven technology from paper concepts in our report on the space economy.
Is the space economy consolidating now?
The space economy is consolidating because customers increasingly want scaled, reliable suppliers.
Lockheed Martin’s acquisition of Terran Orbital, closed in late 2024, still shapes the market. Terran had real smallsat manufacturing capability but financial pressure. Lockheed, already a major customer and investor, absorbed it into a larger defense-prime structure. That is what happens when demand is real but standalone balance sheets are too weak.
Intuitive Machines’ acquisition of Lanteris Space Systems is a fresher example. It drove much of the company’s Q1 2026 revenue jump and expanded its space communications and data-processing footprint. Lunar, defense, and orbital infrastructure companies want more complete capabilities under one roof.
Rocket Lab points in the same direction. Its August 2026 results confirmed it had closed the Mynaric and Motiv Space Systems acquisitions, adding optical communications and space robotics. Its announced Iridium transaction was still subject to conditions, and we found no confirmation that it had closed.
Not every big deal is space consolidation. SpaceX’s acquisition of Cursor is a completed transaction, but Cursor is AI software, so counting it as a space deal would mislead.
Consolidation here is not a bearish signal by itself. It says the market is moving from “many startups can pitch the future” to “customers want proven suppliers that can deliver hardware, software, launch, operations, and government compliance.”
That is less romantic, but more commercially serious.

In our market report about the space economy, you will always find fresh funding data, taken straight from our own verified funding database.
Is space tourism growing, or is Virgin Galactic still grounded?
No, space tourism is not growing in any measurable way. Virgin Galactic is still grounded, and people buying tickets is not the same as people flying.
Virgin Galactic is the clearest evidence. In August 2026, it reported second-quarter revenue of $0.1 million and moved the start of Delta-class commercial operations to February 2027, while saying a ticket offering at $750,000 per seat was oversubscribed. On 26 October 2026, it pushed the first commercial flight again, to early Q2 2027.
That is demand expressed in reservations, not completed paid flights. The company’s future depends on resuming service and scaling flight cadence, and that is exactly what has not yet been proven. Each slip means more cash spent before revenue returns.
Blue Origin is not offsetting the weakness. It ended New Shepard operations in early 2026 to focus on orbital launches and lunar programs, leaving Virgin Galactic as the main suborbital tourism story. Even a well-funded private operator prefers orbital infrastructure and lunar contracts over tourism.
Are launch failures and technical delays still holding the market back?
Yes, launch failures and technical delays are still a major constraint on space economy growth.
Blue Origin’s New Glenn setback is the biggest example of 2026. In late May 2026, a static-fire explosion destroyed the rocket and damaged infrastructure at Launch Complex-36. Blue Origin said it wanted to launch again before year-end. The damage matters because New Glenn is tied to Amazon Leo, NASA missions, and AST SpaceMobile launch plans.
AST SpaceMobile’s BlueBird 7 loss shows the downstream risk. In April 2026, the satellite was placed in an off-nominal orbit after a New Glenn mission and was expected to deorbit. For a direct-to-cell company trying to build coverage density, losing a large satellite directly delays network availability and revenue timing. A lost satellite that delays network revenue is the kind of risk we rate by likelihood in our market report about the space economy.
Rocket Lab’s Neutron delay is the newest example. In October 2026, the company moved the first flight into 2027 after development challenges. Firefly’s Alpha had its own launch anomaly in April 2025 and a booster test accident in September 2025. Even Starship’s first operational deployment flew a shortened profile after an engine problem.
Demand is not the only bottleneck. The market can have strong demand and still grow slower than expected because launch systems, pads, engines, production lines, and regulatory approvals fail. SpaceX’s Falcon reliability still masks a lot of industry fragility.

In our document detailing everything you need to know about space economy, we look at what the winners do differently, so you can learn from the best instead of guessing.
Are regulations helping or hurting the space economy?
Regulation is helping demand in defense and connectivity, but it is also a gating factor for deployment speed.
The FAA is now trying to speed things up. In October 2026, the U.S. Department of Transportation announced five proposed FAA regulatory changes, including a streamlining of the Part 450 launch and reentry licensing rules. These are proposals, not enacted rules, and there is no evidence yet that they have shortened approval times.
The FCC remains central to satellite broadband and direct-to-cell deployment. Amazon Leo faces deadline pressure around deployment milestones, while SpaceX has actively challenged competitors on spectrum and constellation rights. Regulation is no longer a background issue. It decides which networks get to scale, when, and under what interference limits.
Defense procurement is more clearly supportive. SDA’s rapid-prototyping contracts and Space Force’s OTA structures are designed to move faster than traditional procurement, so the government is using faster contracting routes to buy actual constellations.
The net effect is supportive but uneven. With nearly 15,000 operational satellites in orbit by the OECD’s count, traffic and debris rules will matter more, not less. Spectrum, launch licensing, debris rules, and constellation milestones can slow commercial execution. For the growth question, regulation is more of a throttle than a brake.
Are investors getting smarter about space, or just hyped again?
Investors are putting more money into space, and they now reward hard numbers, but the most expensive bets are on companies that have not proved repeatable flight.
The serious side is visible in what gets rewarded. SpaceX’s detailed public results, Rocket Lab’s backlog, and Planet’s sovereign contracts give investors revenue and order data to price. Novaspace’s Q1 2026 count also showed fewer funded companies but much larger dollars, which is usually a healthier pattern than a broad bubble.
The speculative side is visible in valuations. Stoke Space was reportedly valued at roughly $10 billion in September 2026 before reaching orbit, and Blue Origin’s proposed round was reported at a $130 billion pre-money valuation. Neither figure is evidence of revenue or reliable flight cadence. Virgin Galactic’s oversubscribed ticket offering and its slipping schedule are the same tension at a smaller scale.
The market also punishes delays fast. Rocket Lab’s shares fell about 11% on the day it moved Neutron into 2027, according to market reports. That is different from 2021, when many space companies traded mostly on TAM slides.
We believe investor interest is rising for valid reasons, but the valuation layer is noisy. The market can be growing while some companies are overpriced. Those are not contradictory.

If you build or invest in the space economy market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Is the Space Economy growing right now?
The space economy is growing right now, but it is concentrated and not uniformly profitable.
The strongest evidence is concrete: Starlink reached 13.6 million consumer lines and $5.25 billion of quarterly Connectivity revenue; Starship deployed its first operational satellites; Planet grew revenue 58% and won a German sovereign contract; Rocket Lab grew revenue 62% with a $2.36 billion backlog; AST SpaceMobile reached 13 satellites in orbit; capital kept flowing at very large scale; and U.S. and European governments are buying space as defense and sovereignty infrastructure.
The weak evidence is also concrete: Virgin Galactic is still not flying commercially and pushed its return to early Q2 2027; Neutron and Stoke’s Nova are 2027 stories; SpaceX flew fewer Falcon missions than a year earlier; Blue Origin and AST setbacks show technical problems still delay revenue; and valuations for pre-orbital rockets show investors sometimes buy the theme rather than the fundamentals.
So the conclusion is clear: the space economy is expanding, and the growth is concentrated in orbital infrastructure. Connectivity, defense, Earth observation, government launch, and in-space logistics are pulling the market forward. Tourism, weak SPAC-era companies, and unproven moonshots are not.
| Question | Verdict | Comment |
|---|---|---|
| Are space companies raising real money? | Yes | Large rounds for Astranis, Impulse Space, ICEYE, and Stoke Space; Blue Origin’s $10 billion round is reported but not confirmed. |
| Is launch still expanding? | Mixed | Starship began operational deployments, but SpaceX flew 110 Falcon missions in nine months versus 124 a year earlier, and Neutron slipped to 2027. |
| Is satellite broadband demand growing? | Yes | Starlink reached 13.6 million consumer lines and $5.25 billion of quarterly Connectivity revenue, while Amazon Leo builds a second network. |
| Is satellite-to-phone becoming real? | Mixed | T-Mobile/Starlink is commercial, but AST has 13 satellites and broadband-grade service is still a 2027 target. |
| Is Earth observation demand improving? | Yes | Planet’s 58% growth, its German contract, ICEYE, and Satellogic show defense-led demand, despite uneven conversion at BlackSky. |
| Are governments buying more space capability? | Yes | SDA, Space Force, Golden Dome, IRIS², and Germany show space becoming defense and sovereignty infrastructure. |
| Are public space companies gaining momentum? | Mixed | SpaceX, Rocket Lab, Planet, and Redwire show growth, while Virgin Galactic and BlackSky show stress. |
| Are commercial customers spending more? | Mixed | Aviation, maritime, enterprise broadband, launch contracts, and IoT are strong; tourism and some commercial EO use cases remain weak. |
| Are new space products flying now? | Mixed | Starship, Amazon Leo, BlueBird, and Pelican are flying; Neutron and Stoke’s Nova are still 2027 targets. |
| Is the space economy consolidating? | Mixed | M&A signals maturity and customer preference for scale, but also pressure on fragile standalone companies. |
| Is space tourism growing now? | No | Virgin Galactic has bookings but is not flying commercially, with its return pushed to early Q2 2027. |
| Are technical delays still a problem? | Mixed | New Glenn, BlueBird 7, Neutron, and Firefly setbacks show execution risk remains a serious constraint. |
| Are regulations helping growth? | Mixed | Defense procurement helps and FAA licensing reforms are proposed, while spectrum, debris, and constellation rules constrain speed. |
| Are investors getting smarter? | Mixed | Capital rewards revenue and backlog, but high valuations for pre-orbital rockets show theme-driven risk. |
Our methodology
To answer whether the space economy is growing, we did not rely on a broad market impression or a single headline number. We broke the question into practical dimensions: funding, launch activity, satellite broadband, direct-to-cell, Earth observation, government procurement, public companies, commercial demand, new products, consolidation, tourism, technical delays, regulation, and investor behavior.
For each dimension, we looked at recent signals that show what is happening now: capital raised, satellites deployed, launch cadence, reported revenue, backlog, contracts, customer adoption, service launches, and visible operational setbacks. We kept planned flights, proposed rounds, contract options, and backlog separate from revenue and missions actually delivered. We then aggregated those signals point by point to separate areas of real momentum from areas where the evidence is still weak, mixed, or speculative.
That structure is what makes the final answer clearer: the space economy is growing, but the growth is not evenly spread. It is concentrated in infrastructure-like segments such as connectivity, defense, Earth observation, launch, and in-space logistics, while tourism, fragile public companies, and unproven future-space narratives remain much weaker.
Key sources used for this analysis include: the OECD’s Space Economy at a Glance 2026, SpaceX’s third-quarter 2026 results, Planet’s fiscal Q2 2027 results, Rocket Lab’s Q2 2026 results, Rocket Lab’s Neutron development update, AST SpaceMobile’s Q2 2026 results, Novaspace on the Q1 2026 private space investment rebound, Space Foundation’s global space economy estimate, McKinsey and the World Economic Forum’s long-term space economy projection, the FAA’s FY2026 commercial space transportation forecast, Amazon’s Amazon Leo deployment updates, T-Mobile on T-Satellite with Starlink, ICEYE’s 2025 financial results, the U.S. Space Development Agency’s Tranche 3 Tracking Layer awards, Breaking Defense on SpaceX’s $4.16 billion Space Force contract, Aerospace Corporation on the FY2026 defense space budget and Golden Dome, EUR-Lex on the EU secure connectivity program and IRIS², Redwire’s Q1 2026 results, and BlackSky’s Q1 2026 results. We also used SpaceX’s Q3 2026 10-Q filing, Space Capital’s Q3 2026 Space IQ report, Stoke Space’s Series E announcement, The Information’s July 2026 report on Blue Origin’s proposed round, KDDI’s Starlink direct-to-cell agreement, Rocket Lab’s Space Force and Synspective contract announcements, Virgin Galactic’s August and October 2026 updates, and the U.S. Department of Transportation’s October 2026 FAA proposals.

When you build or invest in the space economy market, you need clarity, not confusion. In our research about the space economy, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us