Space Economy: what are the top startups?
Building a startup or looking for your next investment in space economy? Our report gives you the full picture.
Summary
ICEYE is the top private space economy startup today, ahead of Astranis, Impulse Space, Apex and Sierra Space. Its operational radar satellites, sovereign intelligence contracts with seven European governments and valuation above €10 billion give it the strongest combination of proven technology and customer demand.
The biggest divide in the space startup market is between companies already selling operational services and those still financing their first major technical milestones. A company with satellites in orbit and recurring customers deserves a different assessment from a rocket developer that has yet to reach orbit.
SpaceX remains in a league of its own. Starlink reached 12 million subscriber service lines in the second quarter of 2026, while SpaceX's connectivity business generated $4.29 billion in quarterly revenue. Its 2026 public listing also puts it outside the private-startup ranking.
Satellite communications and intelligence have some of the clearest commercial prospects. Astranis has reported more than $1 billion in contract backlog, while ICEYE is selling entire sovereign satellite systems to governments rather than relying on individual imagery purchases.
Impulse Space and Apex are betting on the infrastructure behind growing satellite activity. Impulse has completed three missions and secured an $808 million Series D, while Apex is trying to turn satellite manufacturing into a repeatable production business. Both benefit from demand for spacecraft without needing to compete directly with SpaceX in launch services.
Defense spending is reshaping the competitive landscape. Sierra Space has major US military satellite awards, True Anomaly raised $650 million, and ICEYE is benefiting from governments seeking direct control over surveillance capabilities. Public procurement is becoming a major driver of private space company growth.
Stoke Space represents the biggest contrast between technological ambition and demonstrated performance. Its approximately $10 billion valuation reflects expectations for fully reusable rockets, even though its first orbital launch remains ahead of it. Success could create enormous value, but the risk is much greater than at companies already operating spacecraft. A valuation resting on a rocket yet to reach orbit is the kind of risk we rate by likelihood in our market report about the space economy.
Europe has gained real momentum. Isar Aerospace successfully delivered satellites into orbit in September 2026, ICEYE has become a major defense-space business, and Open Cosmos is expanding satellite production. Europe still trails the United States badly in launch volume, but its commercial space companies are becoming more credible.
The next wave extends beyond conventional satellites. Varda has repeatedly recovered capsules from orbit, while Axiom Space and Vast are developing commercial space stations. These companies have demonstrated meaningful technical progress, although their largest proposed markets still need stronger evidence of sustained commercial demand.
The wider market explains our ranking. The global satellite industry generated approximately $303 billion in 2025, compared with $12.4 billion in commercial launch revenue. We therefore favor businesses converting space infrastructure into customer revenue today, while keeping a close eye on ambitious companies whose technology could transform the industry tomorrow.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

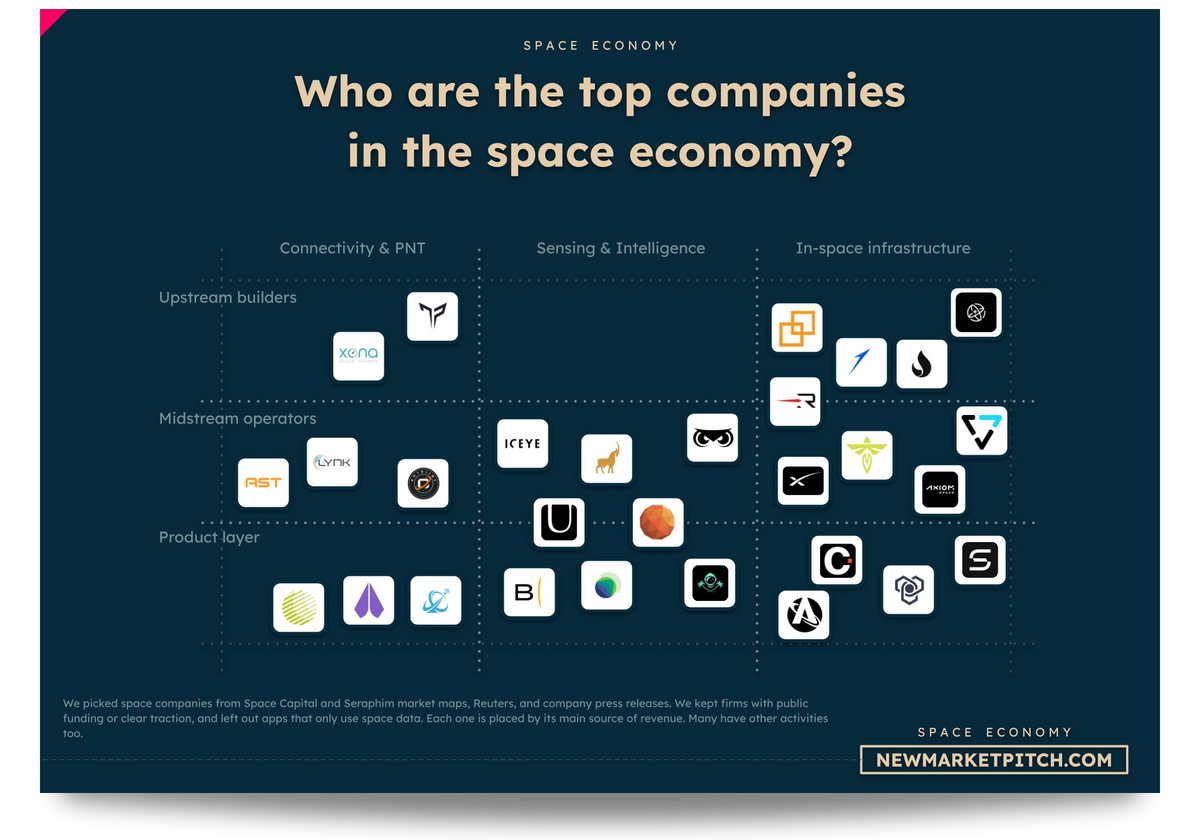
In our report covering the space economy market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is the space economy finally becoming a serious business?
The space economy is now a huge commercial market, and the strongest startups are increasingly making money from satellite communications, intelligence, spacecraft manufacturing and government contracts.
The change goes well beyond cheaper rocket launches. Starlink has shown that satellite internet can reach millions of paying customers, governments are buying their own satellite surveillance systems, and companies such as Apex are building spacecraft designed for repeatable production.
The money flowing into the sector shows how much expectations have changed. ICEYE raised €450 million in new equity at a valuation above €10 billion in June 2026. Stoke Space subsequently announced a $1 billion funding round for reusable rockets, while Impulse Space increased its Series D financing to $808 million. Together, those three companies attracted more than $2.3 billion in primary funding commitments through those rounds alone.
But there is a huge difference between selling an operational satellite service and financing a rocket that has never reached orbit. That difference separates the strongest businesses from some of the most ambitious bets. Satellites in service versus a rocket yet to reach orbit is the kind of gap we mark between proven and unproven technology in our space economy market report.
Which space startups are leading right now?
ICEYE, Astranis, Impulse Space, Apex and Sierra Space are currently among the strongest private space companies, based on their technology, customers and progress toward commercial scale.
ICEYE sells radar satellite intelligence to governments, Astranis builds dedicated communications satellites, Impulse provides orbital transportation, Apex manufactures spacecraft platforms, and Sierra Space has major defense satellite programs. Each has evidence of customer demand beyond investor funding.
Stoke Space, Isar Aerospace, K2 Space and True Anomaly are also serious contenders. Stoke is developing fully reusable rockets, Isar has successfully delivered satellites into orbit, K2 is building large satellite platforms, and True Anomaly specializes in national-security space operations.
Varda Space Industries, Axiom Space and Vast complete our shortlist. Varda has repeatedly returned capsules from orbit, while Axiom and Vast are trying to establish commercial space stations.
We give more weight to completed missions, signed contracts and operating spacecraft than to headline valuations. That favors companies with working products, although it leaves room for earlier-stage businesses that could eventually become much larger.
| Space startup | Main business | Strongest evidence | Biggest challenge |
|---|---|---|---|
| ICEYE | Radar satellite intelligence | Seven European governments have purchased sovereign systems | Delivering sustained growth at a €10B+ valuation |
| Astranis | Satellite communications | Over $1B in reported commercial backlog | Scaling satellite production and deployments |
| Impulse Space | Orbital transportation | Three missions flown and substantial customer contracts | Building a high-frequency transport business |
| Apex | Satellite manufacturing | Flown hardware and $2.3B valuation | Proving mass-production economics |
| Sierra Space | Defense satellites and space infrastructure | Major US defense satellite contracts | Executing several large programs |
| Stoke Space | Reusable rockets | $2.3B in cumulative funding | First orbital launch and actual reusability |
| Isar Aerospace | Orbital launch | Successfully deployed satellites into orbit | Establishing reliable recurring launches |
| True Anomaly | Military space operations | $650M Series D announced | Scaling operational deployments |
| K2 Space | Large satellite platforms | Substantial financing and platform development | Proving large-spacecraft economics |
| Varda Space Industries | Orbital processing and reentry | Multiple successful capsule recoveries | Finding enough commercial demand |
| Axiom Space | Commercial stations and spacesuits | Crewed missions and NASA spacesuit contract | Deploying an independent station |
| Vast | Commercial space stations | Haven Demo mission and $500M financing | Launching and operating Haven-1 |

Our research about the space economy gets updated several times a month, so you always get the latest view of where things stand.
How far ahead is SpaceX compared with other space companies?
SpaceX is still operating on a completely different scale from most space startups, especially in satellite internet and rocket launches.
According to its second-quarter 2026 financial disclosures, Starlink reached 12 million subscriber service lines, compared with 6 million one year earlier. Its connectivity segment generated $4.29 billion in quarterly revenue, up 66% year over year, and $1.66 billion in operating income.
That is approximately $17.2 billion in annualized connectivity revenue at the reported quarterly rate, before considering SpaceX's launch business. No private space startup on our shortlist has disclosed anything close to that level of recurring commercial activity.
SpaceX's launch capacity makes the gap even larger. The company reported delivering approximately 2,213 tonnes of payload to orbit in 2025, compared with 1,210 tonnes in 2023, an increase of roughly 83% in two years. Its own Starlink constellation provides substantial internal demand for those launches.
The next generation is therefore mostly competing for narrower opportunities. Astranis offers dedicated geostationary communications satellites, ICEYE supplies radar intelligence, and Impulse Space moves payloads after launch.
SpaceX became publicly listed in June 2026, so it belongs in the competitive comparison rather than our private-startup ranking. For now, its combination of revenue, launch frequency and satellite infrastructure remains unmatched.
Is ICEYE the strongest private space startup today?
ICEYE has the strongest claim to being the top private space startup today because it combines proven satellite technology with large, identifiable government customers.
The Finnish company operates synthetic aperture radar satellites, commonly called SAR satellites, which can observe Earth's surface at night and through clouds. That makes them particularly useful for military surveillance, maritime monitoring and disaster response. Surveillance, maritime monitoring and disaster response show who pays for radar data, and we study what they would pay to solve in our report on the space economy.
In June 2026, ICEYE announced €450 million in primary Series F financing at a valuation exceeding €10 billion, approximately $12 billion. A secondary share transaction took the total financing package above €1 billion, although the secondary portion did not represent new operating capital for the company.
The more important figure is seven. According to ICEYE's announcement, seven European governments had already purchased sovereign satellite systems from the company. These are much broader purchases than individual satellite images: governments can acquire dedicated space-based intelligence capabilities, including spacecraft and related infrastructure.
ICEYE is benefiting from a real change in defense procurement. Countries increasingly want direct control over their own surveillance systems, especially when access to another country's infrastructure cannot be guaranteed.
The valuation is demanding, and ICEYE does not disclose enough financial information to assess its profitability independently. Still, among private space startups, its combination of operating technology, government adoption and financing gives it the most convincing overall position.

In our market report about the space economy, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Astranis becoming a major competitor in satellite internet?
Astranis is currently one of the strongest independent satellite communications companies, but its business targets customers who need dedicated regional coverage rather than another global Starlink-style network.
Astranis manufactures relatively small geostationary communications satellites. Positioned around 35,786 kilometers above Earth, these spacecraft can provide dedicated capacity over particular countries or regions.
This approach appeals to telecom operators, governments and customers who want control over satellite capacity instead of purchasing access to a shared worldwide network.
The company announced a $300 million Series E in May 2026 alongside a credit facility of up to $155 million. Its cumulative capital raised exceeded $1.2 billion, and the US Export-Import Bank later approved a $468 million financing facility supporting further production.
According to Axios reporting in September 2026, Astranis had five satellites in orbit and more than $1 billion in commercial contract backlog.
That backlog suggests customers are committing meaningful capital to its satellites, although contracted future business cannot be treated as revenue already earned. Five spacecraft in orbit also leave Astranis far behind established satellite operators in total fleet size.
What makes Astranis attractive is the combination of demonstrated orbital hardware, identifiable commercial demand and financing to expand production. Its next challenge is delivering more satellites without losing the economics that make its smaller geostationary platform appealing.
Can Stoke Space really challenge SpaceX with reusable rockets?
Stoke Space is one of the most exciting rocket startups today, but it remains several major technical milestones away from challenging SpaceX commercially.
Stoke is developing Nova, a launch vehicle designed around rapid and full reusability, including the upper stage. Reusing the upper stage is particularly difficult because it must survive reentry after traveling at orbital speeds.
In September 2026, Stoke announced an initial $1 billion Series E closing, bringing cumulative funding to approximately $2.3 billion. Reuters reported that the financing valued Stoke at roughly $10 billion.
That's an extraordinary valuation for a company still preparing its first orbital launch. Stoke's Nova Pathfinder is targeting an initial flight in early 2027, with commercial payloads already identified for the mission, including AstroForge and Celestis.
Stoke has also presented Nova Block 2, a larger rocket designed to deliver approximately 15 tonnes to low Earth orbit, with its first flight targeted for 2029. The larger vehicle would move Stoke beyond the small-launch segment and closer to markets served by established medium-lift rockets.
The company has a coherent technological strategy and substantial financing. But investors are currently paying for the possibility of operational success rather than an established launch business.
We consider Stoke one of the leading long-term contenders. Until Nova reaches orbit, recovers its hardware and demonstrates repeat flights, comparisons with SpaceX should remain about potential rather than demonstrated performance.

In our document detailing everything you need to know about space economy, you will always find fresh funding data, taken straight from our own verified funding database.
Could Impulse Space become the biggest company moving satellites around in orbit?
Impulse Space is currently one of the strongest startups in orbital transportation, with actual missions behind it and growing customer demand for spacecraft that can move payloads after launch.
Rockets deliver spacecraft to orbit, but satellites do not always end up exactly where their operators want them. Impulse develops vehicles that can transport, reposition and support payloads once they are in space.
Its Mira spacecraft has already flown, while its larger Helios platform is designed for more demanding transportation missions.
In June 2026, Impulse announced a $500 million Series D after completing three missions and accumulating hundreds of millions of dollars in contracts. A $308 million extension in September brought the combined round to $808 million.
The company also received a $28 million US Space Force contract for a future mission involving space-domain awareness. That expands its customer base beyond commercial satellite operators.
Impulse is especially interesting because it can benefit from increasing launch activity without building a rocket itself. More military satellites, complex constellations and specialized missions create additional opportunities for transportation and positioning services.
The limitation is market maturity. We still lack public evidence of how much recurring revenue orbital transportation can generate at scale. Nevertheless, Impulse has already moved further operationally than many heavily funded space transportation startups. Whether orbital transportation can bring in recurring revenue is a business-model question we look at in our report covering the space economy market.
Could Apex and K2 Space become the next giants of satellite manufacturing?
Apex currently has the stronger commercial record, while K2 Space could become a major competitor if demand grows for larger, more powerful satellites.
Apex builds standardized satellite buses, meaning the underlying spacecraft platforms that carry customers' cameras, sensors, communications equipment and other payloads. Its selling point is faster production through repeatable designs.
The company raised $200 million in September 2025 at a valuation above $1 billion. Another financing exceeding $200 million in June 2026 increased its valuation to $2.3 billion. That means its valuation nearly doubled in less than a year.
The manufacturing idea is straightforward. A defense contractor that needs dozens of satellites benefits from purchasing standardized platforms instead of designing every spacecraft individually. Apex has already flown hardware and is expanding its production capabilities around that opportunity.
K2 Space is making a different bet. It develops larger satellite platforms with substantial power capacity, designed for missions that smaller spacecraft struggle to support. Heavier and more capable launch vehicles could make those larger satellites economically attractive.
There is no guarantee that customers will consistently prefer large satellites to distributed constellations. Smaller spacecraft offer redundancy and can be replaced individually, while larger platforms may carry more sophisticated payloads and power-hungry equipment.
We currently rank Apex ahead because its production model has more commercial validation. K2 remains one of the startups worth watching as heavy-lift rockets create new possibilities for spacecraft design.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the space economy market, we look at what broke startups before you, so you don't repeat it.
Is Sierra Space becoming a defense company more than a spaceplane company?
Sierra Space is increasingly building its business around military satellites and government infrastructure, even though its Dream Chaser spaceplane remains one of its best-known projects.
In March 2026, Sierra Space raised $550 million in Series C financing at an $8 billion post-money valuation. The round brought total investment since 2021 above $2 billion.
The company's announced programs include a $450 million contract involving more than four national-security satellites and an award with a maximum potential value of $740 million for 18 Space Development Agency missile-warning and tracking satellites.
These programs give Sierra a substantial source of demand beyond Dream Chaser. The distinction between maximum contract values and earned revenue still matters, particularly when delivery schedules extend over several years.
Dream Chaser has also continued progressing. In September 2026, Sierra announced national-security and commercial payload contracts for its inaugural mission, expanding the spaceplane's potential customer base.
Among private space companies, Sierra combines unusually large financing, a broad spacecraft portfolio and major government customers. Its biggest test now is delivering these programs successfully rather than demonstrating another ambitious technology.
Are defense contracts creating the next generation of space unicorns?
Government defense spending is currently helping companies such as ICEYE, True Anomaly and Sierra Space grow much faster than the early commercial space market alone could support.
True Anomaly illustrates how quickly this category has developed. Founded in 2022, the company announced a $650 million Series D in April 2026, including $50 million in debt, bringing cumulative financing above $1 billion.
True Anomaly builds spacecraft and software for military space operations, including tracking, inspecting and understanding the behavior of objects in orbit. Its products address a growing concern among governments: satellites themselves are becoming important military assets that require monitoring and protection. Governments treating satellites as military assets that need protection is one of the growth drivers we weigh in our market report about the space economy.
ICEYE is already selling sovereign intelligence systems, while Sierra Space has major military satellite awards. Impulse Space's $28 million Space Force contract shows that even orbital transportation companies are entering national-security programs.
The government market also has measurable underlying growth. According to the OECD's Space Economy at a Glance 2026, civilian space budgets among OECD members increased from $40.5 billion in 2022 to $46.4 billion in 2025, roughly 15%. Military space spending adds another substantial pool of funding.
Defense demand offers access to large customers, but it comes with procurement delays and the risk of heavy dependence on a few programs. We would favor a company serving several government customers over one whose valuation rests on a single contract.

In our research about the space economy, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is Europe finally catching up in the space startup race?
Europe has made real progress through ICEYE, Isar Aerospace and Open Cosmos, although it remains far behind the United States in orbital launch scale.
The biggest recent milestone came in September 2026, when Isar Aerospace successfully delivered satellites into orbit on its second Spectrum rocket flight from Norway.
The European Space Agency described it as the first orbital launch from continental Europe by a European commercial launcher. The result was particularly striking because Isar's initial test flight in March 2025 lasted approximately 30 seconds.
Isar also raised €270 million in Series D financing and signed an agreement with SEOPS for five launches planned between 2028 and 2030. Its next challenge is turning one successful orbital mission into a dependable launch service.
Open Cosmos is another company worth watching. In September 2026, it announced €300 million in financing and reported over $370 million in new contracts signed during the preceding three and a half years. It also reported five consecutive years of profitable growth and manufacturing capacity of one satellite per day across four European facilities.
The wider gap remains substantial. OECD figures show 181 orbital launch attempts from the United States in 2025, compared with 92 from China and just eight from Europe.
Europe is developing strong companies in satellite intelligence, manufacturing and launch technology. ICEYE already demonstrates how competitive a European space business can become. For launch services, Isar's success is a breakthrough, but closing the scale gap will require years of reliable flights.
Is Varda Space Industries making manufacturing in space a real business?
Varda Space Industries has already demonstrated repeated capsule returns from orbit, putting it ahead of many startups pursuing commercial manufacturing in space.
The company develops spacecraft that can carry experiments and manufacturing equipment into orbit before returning processed materials to Earth. One of its main goals is to investigate pharmaceutical production in microgravity.
By May 2026, Varda had completed six missions and successfully recovered five capsules. Its W-7 mission, launched in October 2026, was designed to investigate pharmaceutical processing, including ways microgravity might improve the manufacture of poorly soluble medicines.
Varda's spacecraft also have another use: government testing of materials and technologies exposed to extreme temperatures during atmospheric reentry.
That gives Varda a broader market than pharmaceutical manufacturing alone. A repeatable reentry vehicle can serve research customers and national-security programs while the economics of commercial orbital production are still being tested.
The company has demonstrated that capsules can return successfully. What remains uncertain is whether drug manufacturers will find enough economic value in microgravity processing to support regular commercial missions.
We rank Varda highly for its operational progress, with more caution about its long-term pharmaceutical opportunity.

If you build or invest in the space economy market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Are Axiom Space and Vast really close to commercial space stations?
Axiom Space and Vast are making tangible progress toward commercial space stations, but neither has yet established an independent orbital habitat with a proven, recurring customer business.
Axiom has the broader human-spaceflight portfolio. It has organized private astronaut missions to the International Space Station, is developing Axiom Station and has a NASA contract for next-generation spacesuits.
In June 2026, Axiom announced that it had closed an expanded financing round exceeding $525 million. That funding supports a business with several activities already connected to government and commercial human spaceflight. Money flowing into human spaceflight businesses is part of the picture of what investors back and what they now avoid in our space economy market report.
Vast is taking a more focused route with Haven-1. Its Haven Demo mission tested technologies intended for future habitats, and the company has been integrating its first habitable station module.
Vast announced $500 million in new financing in March 2026 and currently targets the first quarter of 2027 for Haven-1 readiness and launch.
We favor Axiom on business diversification, while Vast has an interesting opportunity to reach the market with a more focused independent-station design.
Both companies still face the same difficult question: how many customers will consistently pay for private orbital accommodation, research facilities and station services?
The International Space Station has shown that long-duration operations in orbit are possible. Axiom and Vast now need to prove that privately operated replacements can become commercially viable.
How big is the space economy compared with the rocket-launch market?
The global space economy is already worth roughly $600 billion, but satellite services and related businesses generate far more revenue than rocket launches.
The OECD estimated worldwide space-related revenue at approximately $550 billion to $600 billion in 2025. Novaspace, using a broader definition, estimated $626.4 billion and projected the market could reach $1.01 trillion by 2034.
The Satellite Industry Association's 2026 report provides a narrower breakdown. It estimated the global satellite industry at approximately $303 billion in 2025, compared with $12.4 billion in commercial launch revenue and $20.4 billion in satellite manufacturing revenue.
Commercial launch revenue grew 33% during 2025, showing that the rocket business is expanding rapidly. But the total satellite industry was still more than 24 times larger than commercial launch revenue.
That difference explains why companies such as Astranis and ICEYE can become major businesses without developing rockets. Satellite communications and intelligence services reach customers who pay continuously for connectivity, information and operational capabilities.
Launch companies remain essential, and breakthroughs in reusable rockets can reshape the entire industry. However, the biggest pool of commercial spending already lies in what spacecraft accomplish once they reach orbit.
| Space economy indicator | Latest reported figure | What it tells us |
|---|---|---|
| Global space economy, OECD | $550B–$600B | Broad estimate of current industry revenue |
| Global space economy, Novaspace | $626.4B | Alternative broader market estimate |
| Global satellite industry | $303B | Large existing satellite market |
| Commercial launch revenue | $12.4B | Smaller but growing quickly |
| Satellite manufacturing revenue | $20.4B | Substantial spacecraft production market |
| Commercial satellites deployed | 4,434 in 2025 | Record demand for satellite deployments |
| Operational satellites | 14,266 at year-end 2025 | Expanding infrastructure already in orbit |
| Commercial launch revenue growth | 33% in 2025 | Strong recent launch-market growth |
| Satellite broadband subscriber growth | 62% in 2025 | Rapid adoption of satellite connectivity |

Theory only gets you so far. In our document detailing everything you need to know about space economy, we dig up the real signals from the field and show you the ones worth watching.
Are space startup valuations getting out of control?
Some space startup valuations look increasingly aggressive, especially when companies attract multibillion-dollar valuations before proving their main technology commercially.
Stoke Space is the clearest example. Reuters reported a valuation of approximately $10 billion following its September 2026 financing, even though the company had yet to conduct its first orbital launch.
Compare that with ICEYE's valuation above €10 billion. ICEYE has operational radar satellites and government customers buying dedicated intelligence systems. Investors in Stoke are paying for a future reusable-launch business whose technical and financial performance has not yet been demonstrated.
Apex offers another useful comparison. Its valuation reached $2.3 billion after developing and flying satellite hardware, but it still needs to prove that standardized manufacturing can support large-scale production and attractive margins.
Astranis has reported more than $1 billion in commercial backlog, providing some visibility into future deliveries. Still, backlog figures tell us little about operating margins unless we also know production costs and the timing of revenue recognition.
These differences become especially important when financing packages combine equity, debt and secondary share sales. ICEYE's €1 billion-plus transaction included €450 million in primary financing, while Astranis's arrangements included a credit facility. Treating every headline amount as fresh equity funding would exaggerate the capital actually entering some businesses.
There is genuine commercial progress in the industry, but investors are assigning very large values to companies at widely different stages. The startups that can convert funding into completed missions, customer revenue and repeatable operations will deserve those valuations. Others may struggle to meet expectations.
Which space startups could become the next SpaceX?
ICEYE, Astranis, Impulse Space, Apex and Sierra Space currently have some of the strongest foundations for becoming major space businesses, while Stoke Space offers one of the biggest technological opportunities.
ICEYE has an attractive position in satellite intelligence, with governments purchasing sovereign systems. Astranis is expanding a business built around dedicated communications satellites, and Impulse could become an important provider of orbital transportation.
Apex is pursuing the repeatable satellite manufacturing model that defense and commercial constellation operators increasingly need. Sierra Space has major defense programs and several spacecraft technologies under development. Repeatable production can set a leader apart, and we study what leaders consistently do differently in our report on the space economy.
Stoke could eventually join the industry's largest companies if fully reusable rockets bring major cost and operational advantages. However, its path is much less proven than that of companies already delivering satellite services.
We also see meaningful opportunities for Isar Aerospace in European launch, True Anomaly in space defense, Varda in orbital processing and reentry, and Axiom and Vast in commercial human spaceflight.
There is no guarantee that the next giant will resemble SpaceX. SpaceX combines launch, spacecraft production and satellite connectivity under one business. Several of today's strongest startups are building more specialized companies that could become extremely valuable without matching that level of integration.

In our report covering the space economy market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
So, what are the top space economy startups today?
ICEYE is currently our top overall private space startup, with Astranis, Impulse Space, Sierra Space and Apex forming the strongest group of challengers.
ICEYE leads because it has demonstrated its radar satellite technology and secured sovereign system purchases from seven European governments. Its valuation above €10 billion reflects substantial expectations, but its customer adoption gives it more commercial credibility than many other heavily funded space companies.
Astranis stands out in satellite communications, Impulse in orbital transportation, Apex in spacecraft manufacturing and Sierra Space in defense infrastructure.
Stoke Space deserves a separate mention as one of the most ambitious rocket companies. It could eventually become a much larger business than several companies currently ahead of it, although its first orbital flight remains a crucial milestone.
Isar Aerospace has made a major breakthrough for European launch, True Anomaly is attracting substantial funding in military space operations, and Varda has demonstrated repeated reentry capabilities. K2 Space, Axiom Space and Vast have promising opportunities but still need to prove important parts of their business models at scale.
Satellite intelligence, communications, manufacturing and defense infrastructure currently offer some of the strongest combinations of paying customers and demonstrated technology.
Our ranking therefore favors ICEYE today, but there is plenty of room for the order to change. The next leaders will be determined by sustained customer revenue, repeatable missions and successful production at scale, rather than financing announcements alone.
Our methodology
This analysis identifies the leading private startups in the space economy by comparing demonstrated technology, completed missions, commercial contracts, government customers, manufacturing progress, financing and readiness to scale. We evaluated companies across satellite communications, Earth observation, launch services, orbital transportation, spacecraft manufacturing, defense infrastructure and commercial human spaceflight.
Our ranking gives greater weight to operational spacecraft, completed launches, customer adoption and signed commercial or government contracts than to valuations or announced technological ambitions. We also considered whether each company's financing supports credible operational expansion. Since these businesses operate in very different markets, the final ranking is an editorial assessment rather than a numerical score based on funding alone.
We distinguished primary equity financing from debt facilities and secondary transactions, and separated contracted backlog and maximum government contract awards from revenue already earned. Publicly disclosed company figures were assessed alongside independent mission confirmations, government procurement records and financial reporting. SpaceX serves as a benchmark for commercial scale but is excluded from the private-startup ranking following its June 2026 public listing.
For industry context, we used the OECD's Space Economy at a Glance 2026, its analysis of strategic capabilities and competitiveness, the OECD's reporting on government space budgets, and the Satellite Industry Association's 2026 State of the Satellite Industry Report. Their market estimates use different definitions, so we treated them as separate measures rather than interchangeable totals.
For financing and commercial progress, key sources include ICEYE's Series F announcement, Stoke Space's Nova development and financing update, Impulse Space's Series D extension, its US Space Force contract announcement, Apex's production and financing update, US Export-Import Bank financing for Astranis, Sierra Space's Series C, its Space Development Agency contract, and True Anomaly's Series D disclosure.
European launch and satellite manufacturing developments were assessed using the European Space Agency's confirmation of Isar Aerospace's orbital launch and Open Cosmos's financing and commercial update. For orbital processing and human spaceflight, we used Varda's spacecraft and mission history, its W-7 mission information, Axiom Space's financing announcement, NASA's commercial spacesuit program information, and Vast's financing and station development update.
Our conclusions reflect the evidence available through October 2026. We prioritized original company disclosures, government and institutional records, independently documented mission outcomes and attributable financial figures, while distinguishing reported future plans from completed operational achievements. The ranking ultimately reflects demonstrated commercial strength, execution and the remaining risks facing each startup.

In our research about the space economy, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us