Who is the next SpaceX?
Everything we know about the space economy, in one place. Get our report whether you build or invest.
Summary
Rocket Lab is the strongest candidate to become the next SpaceX, ahead of Blue Origin and Stoke Space. It already operates a commercial launch business, generates more than $600 million in annual revenue, and has expanded into spacecraft manufacturing. Blue Origin is its biggest rival in heavy-lift launches, while Stoke offers the most ambitious unproven reusable technology.
SpaceX's real advantage goes far beyond its rockets. Of its 170 launches in 2025, approximately 127 deployed Starlink satellites. The company controls much of its own launch demand, allowing it to fly far more frequently than competitors that depend primarily on external customers.
SpaceX's subscription business has also become enormous. Starlink reached 13.6 million consumer subscribers in the third quarter of 2026, while Connectivity generated $5.25 billion in quarterly revenue and $2.37 billion in operating income. Replicating that integrated business is a much harder challenge than developing a competitive rocket. Replicating launch plus a subscription business is hard, so we look at which business models keep their margins in our report on the space economy.
Rocket Lab has unusually strong commercial evidence for a SpaceX challenger. Its 2025 revenue reached $602 million, first-half 2026 revenue increased approximately 63%, and its contracted backlog climbed 137% year over year to $2.36 billion. Spacecraft and related products now generate considerably more revenue than launch services.
Neutron is Rocket Lab's biggest opportunity and its most obvious weakness. The medium-lift rocket could compete for missions currently served by Falcon 9, but manufacturing problems have delayed its inaugural launch until 2027. Rocket Lab has proved it can launch Electron reliably; it hasn't yet proved it can scale that capability to a much larger reusable vehicle.
Rocket Lab's planned acquisition of Iridium could be more strategically important than another rocket. Owning an established satellite communications network would bring recurring service revenue into the business, moving Rocket Lab closer to SpaceX's combination of launch, spacecraft manufacturing, and connectivity.
Blue Origin has the stronger heavy-lift hardware today. New Glenn has reached orbit and successfully landed a booster, with approximately twice Falcon 9's published maximum payload capacity. However, its limited flight history, an unsuccessful April 2026 mission, and ground infrastructure problems mean reliable high-frequency operations remain unproven.
Stoke Space represents the biggest technological gamble. It has raised approximately $2.3 billion to develop Nova, a rocket intended to recover and reuse both stages. If that architecture works with rapid turnaround, Stoke could eventually achieve attractive launch economics. For now, it hasn't completed an orbital mission.
The wider competition is developing in different directions. Firefly Aerospace has demonstrated lunar delivery through Blue Ghost, Relativity Space is pursuing a larger reusable rocket, and Chinese companies such as LandSpace and Galactic Energy are expanding domestic orbital launch capabilities. Government procurement is also supporting more providers, although eligibility for contracts is not the same as demonstrated commercial success.
Our ranking remains Rocket Lab first, Blue Origin second, and Stoke Space third. Rocket Lab has the strongest combination of existing revenue, launch experience, spacecraft capabilities, and future growth opportunities. Blue Origin could surpass it as SpaceX's closest direct launch competitor, while Stoke has the greatest upside if its unproven technology works. None is close to matching SpaceX's current scale.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

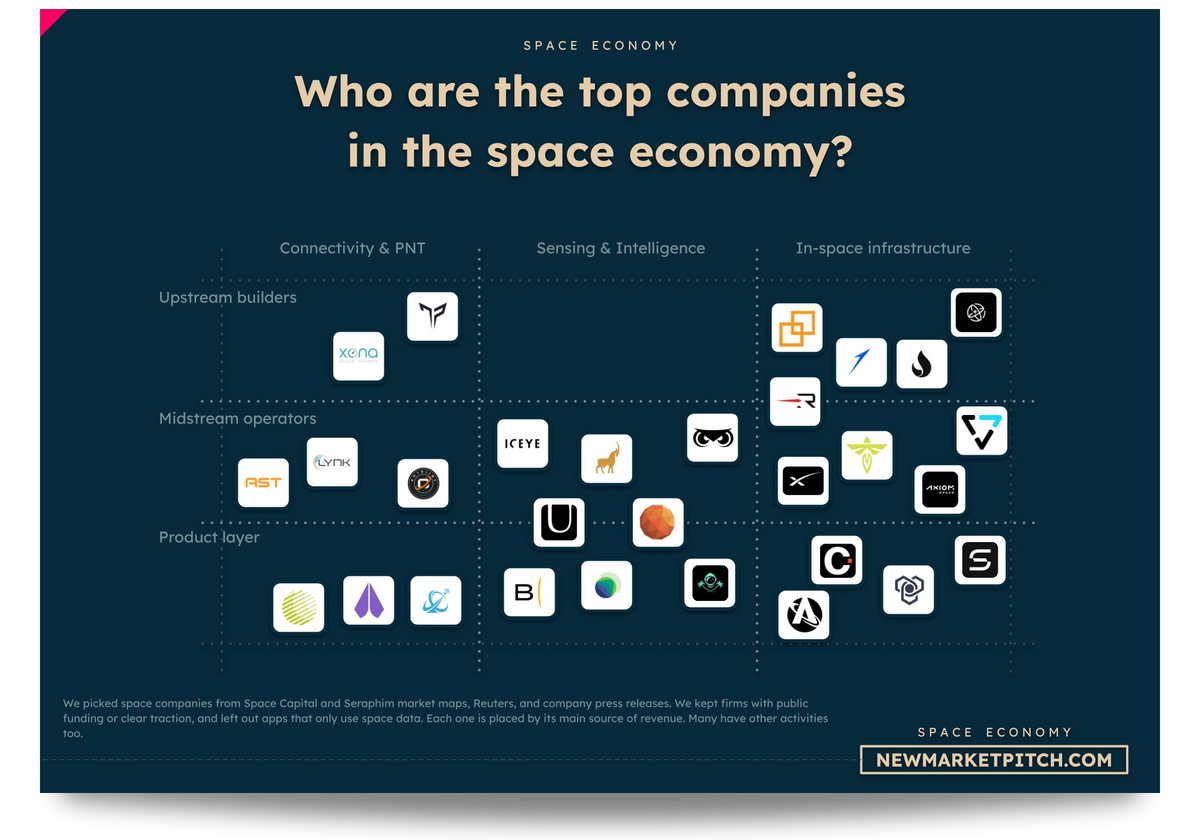
In our report covering the space economy market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why is everyone looking for the next SpaceX?
The race to find the next SpaceX is getting more serious because several companies now have working orbital rockets, major government contracts, or billions in funding. But SpaceX is still miles ahead of its competitors.
SpaceX conducted 170 launches in 2025, up from 138 in 2024 and 98 in 2023. According to orbital launch records compiled by Space Osmosis, those 170 launches represented approximately 52% of all orbital launch attempts worldwide. SpaceX alone launched more than all other countries and companies combined.
Meanwhile, Rocket Lab completed 21 Electron missions in 2025, including suborbital flights, and reported record annual revenue. Blue Origin successfully landed a New Glenn booster after an orbital launch in November 2025. Stoke Space raised $1 billion in September 2026 to develop rockets that can be reused in their entirety.
These companies are reaching milestones that would have been extraordinary a decade ago. The catch is that they are achieving different things. Rocket Lab already operates a commercial launch business, Blue Origin has a much larger rocket, and Stoke is betting on more ambitious reusable technology.
So who could actually follow SpaceX's path? We think Rocket Lab has the strongest overall case, although Blue Origin and Stoke Space could ultimately challenge it in important parts of the launch market.
What would it take to become the next SpaceX?
The next SpaceX would need to build a large, reliable space business that extends beyond selling rocket launches. That's why Rocket Lab currently has an advantage over companies whose main attraction is an upcoming vehicle.
SpaceX started with rockets but eventually developed its own source of recurring launch demand through Starlink. The satellite network now serves millions of customers, generating subscription revenue while regularly requiring additional satellites to be deployed into orbit.
That combination is difficult to reproduce. A rocket company normally has to find customers whenever it wants to launch. SpaceX can launch missions for outside customers while also using its rockets to grow a business it owns. A rocket company that must find customers for every launch plays a different game, and we compare what winners do differently in our space economy market report.
There's a difference between becoming the next major space company and becoming SpaceX's biggest launch competitor. Rocket Lab looks better positioned for the first outcome because it already manufactures spacecraft and components. Blue Origin is a stronger candidate for the second because New Glenn is capable of carrying much heavier payloads.
Stoke Space offers a third possibility: a younger company developing technology that could eventually change launch costs. That would be a major achievement even if Stoke never matched SpaceX's size.

Our research about the space economy gets updated several times a month, so you always get the latest view of where things stand.
How far ahead is SpaceX today?
SpaceX remains in a league of its own, particularly in launch frequency and satellite communications. Its latest financial results also show how much larger the company has become beyond rockets.
SpaceX's third-quarter 2026 filing reported $14.6 billion in consolidated revenue. Connectivity, which includes Starlink, generated $5.25 billion, while the Space segment generated approximately $1.77 billion. A separate Super Intelligence business generated $7.56 billion, so the total figure cannot be attributed entirely to space activities.
Starlink ended the quarter with 13.6 million consumer subscribers, compared with 7.2 million one year earlier. That represents an increase of nearly 89% in twelve months. Connectivity revenue grew 69% over the same period, demonstrating that SpaceX has an expanding subscription business alongside its launch operations.
The scale is clearer when we compare its launch history with Rocket Lab's recent performance.
| Metric | SpaceX | Rocket Lab |
|---|---|---|
| Founding year | 2002 | 2006 |
| Orbital launch attempts in 2023 | 98 | 10 |
| Orbital launch attempts in 2024 | 138 | 14 |
| Orbital launch attempts in 2025 | 170 | 18 |
| Launch attempts in 2025, including other flight categories | 170 | 21 |
| Revenue in 2025 | Not directly comparable from disclosed segment data | $602M |
| Latest reported quarterly company revenue | $14.6B | $234M |
| Latest reported quarterly space-related revenue | $1.77B Space; $5.25B Connectivity | $234M total |
| Owned satellite communications network | Starlink | Iridium acquisition pending |
The 2025 figures show SpaceX completed more than nine times as many orbital launch attempts as Rocket Lab. The difference in payload delivered to orbit was much larger because Falcon 9 carries substantially heavier loads than Electron.
A less obvious finding comes from SpaceX's launch mix. Of its 170 launches in 2025, 127 involved Starlink, according to Space Osmosis. Roughly three-quarters of the company's missions therefore supported its own satellite network.
That internal demand is a major reason SpaceX's launch business operates at a scale other companies struggle to approach.
Is Rocket Lab the closest thing to a second SpaceX?
Rocket Lab is currently the strongest overall candidate to become the next SpaceX because it has already built a working launch business and expanded into spacecraft manufacturing.
Founded by Peter Beck in 2006, Rocket Lab first reached orbit with Electron in 2018. Its small rocket has since become an established option for customers launching smaller satellites, dedicated payloads, and specialized government missions.
In 2025, Rocket Lab completed 21 Electron missions, including suborbital missions, with a reported 100% mission success rate that year. The company has since expanded its launch contracts while building spacecraft, satellite components, optical systems, and defense-related hardware.
During the second quarter of 2026, Rocket Lab generated approximately $234 million in revenue, including $181 million from products and $53 million from services. Products represented more than 77% of the total. These activities include spacecraft and related hardware, while services include launch and other contracted work.
Rocket Lab is also publicly traded, allowing us to examine audited financial statements, revenue growth, backlog, and operating expenses. Blue Origin and Stoke Space disclose far less comparable financial information.
That's a big part of why we rank Rocket Lab first. There's an actual business to evaluate, rather than mainly a rocket development program and a financing history.

In our market report about the space economy, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Rocket Lab actually growing that fast?
Rocket Lab's business is growing fast enough to justify serious attention. Its revenue grew 38% in 2025, and its latest reported quarterly revenue increased 62% year over year.
Rocket Lab generated $602 million in 2025, compared with approximately $436 million in 2024. Revenue during the first half of 2026 reached $434.4 million, up from $267.1 million during the same period in 2025.
That means Rocket Lab added about $167 million in first-half revenue year over year, an increase of nearly 63%. Its second quarter alone generated $234.1 million, approximately $34 million more than the previous quarter.
The growth is coming increasingly from spacecraft and related products. According to the company's second-quarter SEC filing, acquisitions and space systems work contributed substantially to revenue growth. Launch revenue during the quarter was slightly lower than a year earlier, partly because of mission mix and the timing of revenue recognition.
Rocket Lab's backlog has been growing even faster than its recognized revenue. It reached $2.36 billion at the end of June 2026, up 137% from a year earlier. That implies a backlog of approximately $996 million twelve months before.
The backlog includes future deliveries rather than completed sales, so it doesn't guarantee that revenue will arrive on schedule. Still, combining 63% first-half revenue growth with a 137% increase in backlog gives us considerably stronger evidence of demand than a rising launch count alone. Revenue and backlog rising together are among the market signals we follow every quarter in our market report about the space economy.
Can Rocket Lab's Neutron rocket compete with Falcon 9?
Rocket Lab's Neutron could become a real Falcon 9 alternative for medium-sized satellite missions, but the rocket's repeated delays have become the company's biggest weakness.
Neutron is designed to carry up to approximately 13 metric tons to low Earth orbit in its expendable configuration. Falcon 9's advertised maximum capacity is about 22.8 metric tons. Neutron would therefore compete for a narrower range of payload sizes, particularly satellites and constellations that are too large for Electron.
When Rocket Lab introduced Neutron in 2021, it discussed a first launch in 2024. That target subsequently moved through 2025 and 2026. On October 14, 2026, Rocket Lab formally confirmed that the inaugural launch was now expected in 2027.
According to Peter Beck's investor update, the latest delay involved manufacturing issues with the rocket's carbon-composite first-stage structures. A tank failed qualification testing earlier in the year, and problems involving automated fiber-placement manufacturing complicated the recovery.
Rocket Lab expects further qualification work before setting a more precise launch target. Until Neutron flies, Rocket Lab's ability to compete directly with Falcon 9 remains a promise. And after several delays, investors have good reason to demand more than another launch schedule.

In our document detailing everything you need to know about space economy, you will always find fresh funding data, taken straight from our own verified funding database.
Could Rocket Lab's Iridium acquisition make it more like SpaceX?
Rocket Lab's planned acquisition of Iridium could be even more important to its long-term business than Neutron because it would give Rocket Lab an established satellite communications network.
Rocket Lab and Iridium signed a merger agreement on June 28, 2026. Iridium operates a global satellite communications system used by government agencies, maritime operators, aviation customers, and businesses that need communications in remote locations.
The acquisition would bring together Rocket Lab's manufacturing and launch operations with a company that already sells communications services directly to customers.
There's a clear connection to what SpaceX achieved with Starlink. SpaceX uses its launch and spacecraft capabilities to support an owned satellite network, keeping more of the economic value generated by its infrastructure.
Rocket Lab is pursuing a related model through acquisition rather than building an entirely new global communications service from scratch.
The deal has already advanced beyond the announcement stage. In September 2026, Rocket Lab confirmed that it had completed a $1.944 billion at-the-market equity offering and secured financing arrangements for the acquisition. The company expects the transaction to close in mid-2027, subject to regulatory approvals.
There are important differences between Iridium and Starlink. Iridium serves specialized communications markets, while Starlink has developed a mass-market broadband service with more than 13 million consumer subscribers.
Is Blue Origin actually closer to SpaceX than Rocket Lab?
Blue Origin is ahead of Rocket Lab in heavy-lift rocket technology, but Rocket Lab remains ahead in demonstrated orbital launch frequency and financial transparency.
Jeff Bezos founded Blue Origin in 2000, two years before SpaceX. The company spent years developing reusable launch technologies, engines, and infrastructure before its New Glenn rocket first reached orbit in January 2025.
New Glenn completed its second launch in November 2025, successfully deploying NASA's ESCAPADE spacecraft and landing its first-stage booster on a ship in the Atlantic Ocean. Launch companies sit at very different stages of maturity, and the market maps in our report covering the space economy market show where the launch players stand.
That landing established an important achievement: Blue Origin had demonstrated the recovery of an orbital-class booster, something Rocket Lab has not yet achieved with Neutron.
New Glenn's third mission in April 2026 exposed another difficulty. The rocket carried an AST SpaceMobile satellite, but an upper-stage performance problem left the spacecraft in the wrong orbit, according to Associated Press reporting. Although the booster landed, the payload was lost and the launch program faced a review.
A separate hotfire anomaly on May 28 damaged ground infrastructure at Cape Canaveral. Blue Origin subsequently confirmed the loss of equipment including its transporter-erector and lightning tower.
Blue Origin has a large rocket that has flown, substantial financial backing, and major customers. But if we're judging companies by what they can deliver repeatedly today, Rocket Lab still has the stronger operational record. Blue Origin needs to turn a handful of impressive flights into a reliable launch service.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the space economy market, we look at what broke startups before you, so you don't repeat it.
Can New Glenn seriously challenge Falcon 9 and Starship?
New Glenn could become SpaceX's strongest competitor in heavy commercial launches, particularly if Blue Origin can turn its successful booster recovery into regular reuse.
The rocket's advertised low-Earth-orbit payload capacity is approximately 45 metric tons, almost twice Falcon 9's maximum published capacity. This gives New Glenn an attractive position for large satellite batches, national security payloads, and other missions requiring substantial lift capacity.
Blue Origin has continued investing in the infrastructure needed for higher launch frequency. In August 2026, the company announced construction work on a second pad at Launch Complex 36 to support a larger New Glenn configuration.
NASA also added Blue Origin's planned New Glenn 9×4 variant to its Launch Services II contracting framework in September 2026, making the proposed configuration eligible to compete for future missions.
New Glenn's size could help Blue Origin win customers who need more capacity than Falcon 9 offers. But payload capability alone doesn't tell us whether a rocket will be cheaper or easier to schedule. SpaceX has years of experience recovering boosters, maintaining launch pads, and reusing hardware.
Starship raises the difficulty further. SpaceX's third-quarter 2026 earnings release reported that Starship had completed its first revenue-generating orbital mission, deploying 26 Starlink V3 satellites. SpaceX stated that this mission added roughly ten times the downlink capacity of a typical Falcon 9 Starlink launch.
Is Stoke Space the most exciting new SpaceX rival?
Stoke Space is currently one of the most ambitious young SpaceX competitors because its Nova rocket is being designed for full reusability from the beginning.
Founded in 2020 by former Blue Origin engineers Andy Lapsa and Tom Feldman, Stoke wants to recover both rocket stages after a mission. Most reusable orbital rockets today recover the booster but discard the upper stage.
Recovering both stages could reduce the amount of new hardware needed per launch. The challenge is particularly difficult for upper stages because they travel at orbital speeds and face extreme heating during atmospheric reentry.
Stoke has attracted an extraordinary amount of financing for a company that has not yet completed an orbital launch.
In February 2026, it expanded its Series D round to $860 million, bringing total funding to approximately $1.34 billion. In September, Stoke announced the initial closing of a $1 billion Series E, bringing cumulative funding to $2.3 billion. Reuters reported that the latest financing valued the company at roughly $10 billion.
That represents almost $1 billion in additional capital raised within seven months, excluding any distinction between the announced financing size and capital ultimately drawn.
The company is preparing Nova Pathfinder for its first orbital flight, currently targeted for early 2027. It has also announced Nova Block 2, a larger configuration designed to carry 15 metric tons to low Earth orbit, with a first launch targeted for 2029.
Stoke has an unusually bold engineering strategy and substantial financial resources. But we still need to see an orbital flight, a successful recovery, and eventually repeated reuse before concluding that its technology can deliver lower launch costs.

In our research about the space economy, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Could Stoke Space overtake Rocket Lab?
Stoke Space could eventually surpass Rocket Lab in reusable rocket technology, but Rocket Lab has a major advantage from years of launches, spacecraft deliveries, and customer relationships.
Rocket Lab's Electron first reached orbit in 2018. The company spent the following years building its production systems, launch operations, and relationships with commercial and government customers. By 2025, it was completing roughly two Electron missions per month on average.
Stoke is attempting to reach a different technical endpoint more directly. Nova Pathfinder has been designed around full reuse from the start, while Rocket Lab's Neutron initially focuses on recovering and reusing the first stage. Full reuse of both stages is technology still being proven, and we check which space technologies already work in our report on the space economy.
If Stoke successfully recovers and reflies both stages with limited refurbishment, that architecture could eventually deliver better hardware economics.
But an advantage in architecture does not automatically mean a lower price per launch. Stoke would also need reliable engines, rapid turnaround, sufficient production capacity, launch-site availability, and enough customers to use its rockets regularly.
Rocket Lab can continue selling spacecraft components and Electron missions while developing Neutron. Stoke's commercial success remains much more dependent on getting Nova into service.
We wouldn't bet on Stoke overtaking Rocket Lab anytime soon. The technology is exciting, but the gap in actual commercial experience is enormous.
Is Relativity Space still a real SpaceX contender?
Relativity Space remains a credible contender in reusable rockets, but the company has fallen behind competitors that have already established orbital launch operations.
Relativity became famous for its heavy use of 3D printing and its ambition to automate rocket manufacturing. Its first rocket, Terran 1, launched in March 2023 but failed to reach orbit after a second-stage problem.
The company discontinued Terran 1 and focused its resources on Terran R, a much larger reusable rocket. Its published specifications advertise approximately 23.5 metric tons of capacity to low Earth orbit with a downrange booster landing.
That would place Terran R in direct competition with Falcon 9 on payload capacity, unlike Rocket Lab's smaller Electron.
Relativity received an encouraging government endorsement in July 2026 when the U.S. Space Force added its subsidiary Relativity Federal to the National Security Space Launch Phase 3 Lane 1 contract. NASA also added Terran R to its Launch Services II framework in September.
These decisions make Relativity eligible to compete for certain missions, but they do not mean Terran R has been flight-qualified or that customers have already assigned it substantial launch volumes.

If you build or invest in the space economy market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Could Firefly Aerospace become the next SpaceX through lunar missions?
Firefly Aerospace has a stronger case in lunar transportation and specialized space infrastructure than in challenging SpaceX's enormous launch business.
Firefly achieved one of the commercial space industry's most important milestones in March 2025 when its Blue Ghost lander successfully touched down on the Moon. The mission carried NASA-sponsored science and technology payloads and showed that a commercial company could deliver a complex lunar mission successfully.
The company has also continued developing its Alpha rocket. Its seventh Alpha flight, completed in March 2026, carried a Lockheed Martin technology demonstrator and helped validate improvements to the vehicle.
That creates an interesting combination: Firefly can offer launch services, spacecraft technology, and lunar delivery capabilities.
These markets may reward reliability and specialized engineering more than launch volume alone. NASA and defense customers have reasons to buy missions from several companies, especially when missions require different types of spacecraft or destinations.
Still, Firefly's launch record remains far smaller than Rocket Lab's, and its rocket has much less payload capacity than Falcon 9 or New Glenn.
Are Chinese rocket companies becoming serious SpaceX competitors?
Chinese companies such as LandSpace and Galactic Energy are becoming important launch providers, although their strongest opportunities currently lie in China's domestic space market.
LandSpace has demonstrated methane-powered orbital launch technology through Zhuque-2 and is developing reusable capabilities through Zhuque-3. Galactic Energy has built experience launching smaller satellites with its Ceres-1 rocket family. Space Pioneer is pursuing larger liquid-fueled orbital launch vehicles.
These businesses benefit from growing Chinese demand for communications satellites, government missions, and domestic launch capacity. China's broader space industry is also investing in large satellite constellations, creating potential demand for frequent launches. Constellation plans that could create steady launch demand are the kind of growth driver we examine in our market report about the space economy.
According to global orbital launch records, China conducted approximately 92 orbital launch attempts in 2025, compared with 68 in 2024. That 35% increase shows how quickly the country's launch activity is expanding, although those figures include government-operated launch systems as well as commercial companies.
We cannot attribute national launch growth directly to Chinese startups, and published financial information is generally less detailed than the disclosures available for Rocket Lab.
China could eventually produce several large independent launch businesses. For now, LandSpace and Galactic Energy deserve to be watched, but their available commercial and financial evidence is less complete than Rocket Lab's.
Europe's Arianespace and America's United Launch Alliance are also important alternatives to SpaceX. However, both are established providers with different ownership structures and business strategies. They are better understood as institutional launch competitors than emerging companies following SpaceX's entrepreneurial development path.

Theory only gets you so far. In our document detailing everything you need to know about space economy, we dig up the real signals from the field and show you the ones worth watching.
Is the U.S. government already choosing the next SpaceX?
The U.S. government is actively supporting more launch competitors, but it has deliberately avoided choosing one company to replace SpaceX.
In July 2026, the U.S. Space Force announced that seven companies were participating in its National Security Space Launch Phase 3 Lane 1 contracting framework.
The group includes SpaceX, United Launch Alliance, Blue Origin, Rocket Lab, Stoke Space, Relativity Space, and Impulse Space.
The list has expanded in stages. SpaceX, ULA, and Blue Origin joined in fiscal 2024. Rocket Lab and Stoke were added in fiscal 2025. Impulse Space and Relativity followed in July 2026.
A separate procurement modification increased the program's overall contract ceiling to $17 billion. That ceiling applies to the contracting framework as a whole rather than representing an equal allocation of funding to participating companies.
National security customers want reliable access to orbit even if one provider experiences technical problems, delays, or capacity shortages. Government contracts can also help younger companies justify expensive launch infrastructure.
However, being admitted to a procurement framework doesn't prove that a company has a working vehicle or guaranteed launch revenue. The meaningful next step is winning task orders and delivering those missions successfully.
Which space companies have the best chance of catching SpaceX?
Rocket Lab currently has the strongest all-around position, Blue Origin is the most capable heavy-lift challenger, and Stoke Space has the most ambitious unproven reusable architecture among the younger contenders.
The differences become clearer when we compare what each company has actually achieved with what it still needs to prove.
| Company | What it has proved | Biggest opportunity | Biggest remaining problem |
|---|---|---|---|
| Rocket Lab | Frequent Electron missions; $602M annual revenue | Neutron and satellite communications | Neutron has not flown |
| Blue Origin | New Glenn orbital launches and booster recovery | Large commercial and government payloads | Reliability and flight frequency |
| Stoke Space | Advanced reusable-stage development and $2.3B raised | Fully reusable Nova rockets | No orbital launch yet |
| Firefly Aerospace | Alpha orbital missions and successful Moon landing | Lunar services and defense missions | Limited launch scale |
| Relativity Space | Terran 1 test flight and Terran R development | Reusable medium-heavy launch | Terran R remains unproven |
| LandSpace | Methane-powered orbital launch experience | Reusable launch in China | Scaling reliability and reuse |
| Galactic Energy | Repeated Ceres-1 orbital missions | Chinese satellite-launch demand | Larger rocket capabilities unproven |
| Space Pioneer | Development of larger liquid-fueled rockets | Medium-lift launch market | Establishing reliable orbital service |
Rocket Lab has the most established launch cadence among these contenders, while Blue Origin has demonstrated substantially greater orbital payload capacity and booster recovery. Neither has yet matched SpaceX's combination of frequent medium-to-heavy launches and vertically integrated satellite services.
Stoke is more speculative, although its financing and engineering plans place it among the most serious younger competitors. Firefly offers a different opportunity through lunar infrastructure, while Relativity still has to convert Terran R's published specifications into an operational rocket.
We put Rocket Lab ahead because it has several ways to grow even if Neutron takes longer than expected. Blue Origin comes second because New Glenn could become a genuinely important alternative for heavy payloads. Stoke is third, but with considerably more uncertainty than either of them.

In our report covering the space economy market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Is there enough business for another SpaceX?
The space market can support several large companies, but we don't yet see evidence that launch demand alone can support another business approaching SpaceX's scale.
Satellite constellations are creating substantial demand for launch services. Amazon Leo has contracted launches from multiple providers, including Blue Origin, Arianespace, and SpaceX. Governments are also buying more communications, surveillance, and defense-related space capabilities. Whether launch demand can support another giant is a size question, so we build our own estimate, with every assumption visible, in our space economy market report.
The launch market benefits from this growth, but SpaceX has an unusual advantage: it generates much of its own launch demand.
In 2025, roughly 75% of SpaceX's launch attempts supported Starlink deployments. An independent launch provider without a large satellite constellation needs to sell most of its missions to outside customers.
Rocket Lab is expanding through spacecraft manufacturing and potentially Iridium. Blue Origin has invested in lunar systems and other space infrastructure. Firefly is pursuing lunar transportation and spacecraft programs.
We can see why these companies are branching out by looking at SpaceX's latest segment economics. Its Connectivity business generated approximately $5.25 billion in quarterly revenue and $2.37 billion in operating income. The Space segment produced approximately $1.77 billion in revenue and reported a small operating loss for the quarter.
What could prevent Rocket Lab or Blue Origin from becoming the next SpaceX?
Rocket Lab and Blue Origin could both build successful businesses and still fall far short of SpaceX if their larger rockets remain expensive, unreliable, or difficult to operate frequently.
Rocket Lab's Neutron delays illustrate how challenging it is to scale from small rockets to medium-lift systems. Its composite tank manufacturing problems have postponed first flight to 2027, even though the company already has extensive experience developing Electron.
Blue Origin faces a different challenge. New Glenn has completed orbital missions and recovered a booster, but the April 2026 mission failure and subsequent ground-test anomaly disrupted its progress toward regular commercial operations.
Stoke Space has even more technology to prove. Recovering both rocket stages could eventually improve launch economics, but reliable atmospheric reentry and quick refurbishment are exceptionally difficult engineering requirements.
There is also the cost of growing these businesses. Rockets require specialized factories, engines, testing equipment, launch pads, and qualified personnel long before they generate predictable revenue.
Stoke's $2.3 billion in cumulative funding reflects the scale of capital investors are willing to commit. Rocket Lab's Neutron spending demonstrates that even companies with established revenue streams can face costly development setbacks.

In our research about the space economy, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
So, who is the next SpaceX?
Rocket Lab is the best candidate for the next SpaceX today, although Blue Origin has the strongest chance of becoming SpaceX's principal heavy-lift launch competitor.
Rocket Lab's position comes from a combination we haven't seen from the other emerging contenders. It already launches rockets commercially, generated more than $600 million in annual revenue, has a $2.36 billion contracted backlog, and sells spacecraft hardware to customers beyond its own launch business.
Its planned acquisition of Iridium could also move Rocket Lab closer to SpaceX's integrated model, combining launch, spacecraft manufacturing, and ongoing communications services.
There are two important qualifications.
First, Neutron has not flown. Rocket Lab's medium-lift ambitions remain behind schedule, and the company still has to demonstrate booster recovery and commercially useful reuse at a larger scale.
Second, Blue Origin has already demonstrated a much heavier orbital rocket and successful booster landing. If New Glenn becomes a reliable, frequently launched vehicle, Blue Origin could become a stronger direct competitor to Falcon 9 than Rocket Lab.
Stoke Space is the wildcard. Its fully reusable architecture is ambitious enough to change the competitive picture, but we still don't know whether Nova can reach orbit reliably, return both stages, and fly again at an economically attractive cost.
Our overall ranking is Rocket Lab first, Blue Origin second, and Stoke Space third. Rocket Lab has the best combination of commercial evidence and room to grow, Blue Origin has the strongest large-rocket capability, and Stoke offers the most speculative technological upside.
The next SpaceX may ultimately look quite different from SpaceX itself. But among the companies building toward that scale today, Rocket Lab has done the most to turn the ambition into an operating business.
Our methodology
This analysis examines which space company has the strongest chance of following SpaceX's development from a launch provider into a large, integrated space business. We compared operational execution, commercial traction, financial performance, reusable rocket technology, competitive positioning, and long-term growth opportunities. Our ranking gives greater weight to completed launches, recognized revenue, contracted business, and demonstrated technical milestones than to valuations, fundraising announcements, or future vehicle specifications.
We treated launch frequency and successful missions as evidence of operational maturity, while distinguishing orbital launches from suborbital flights. We also separated existing launch capability from rockets still under development. Financial comparisons use reported company disclosures where available, with particular attention to Rocket Lab's audited results, quarterly revenue, business composition, and backlog. SpaceX's consolidated results were examined by segment because the company's reported revenue includes businesses beyond launch and satellite connectivity.
Our assessment of future competitiveness considers whether each company can expand beyond launch services into spacecraft manufacturing, satellite communications, or other recurring space businesses. We examined Rocket Lab's planned acquisition of Iridium, Blue Origin's development of New Glenn, Stoke Space's fully reusable architecture, and specialized opportunities in lunar transportation and government missions. Announced acquisitions, unreleased rockets, prospective contracts, and future launch targets were treated as opportunities rather than completed achievements.
We prioritized original financial filings, investor announcements, technical specifications, NASA publications, and U.S. Space Force procurement records. We assessed the evidence both individually and across companies, looking for consistent advantages supported by several indicators rather than selecting a winner based on any single milestone. Our ranking reflects the strength of the demonstrated business and its potential to scale, while accounting for the considerable uncertainty around newer launch systems.
Key financial and operational sources include SpaceX's third-quarter 2026 financial results, SpaceX's Falcon 9 technical specifications, Rocket Lab's 2025 annual report, Rocket Lab's full-year 2025 financial results, Rocket Lab's second-quarter 2026 financial results, and Rocket Lab's 2025 launch record.
For Rocket Lab's future development, we used the October 2026 Neutron development update and Iridium's SEC filing covering the merger agreement. For Blue Origin, we consulted the New Glenn second-mission announcement, the Launch Complex 36 expansion announcement, and NASA's confirmation of the New Glenn 9×4 contracting addition.
For the other contenders, our sources include Stoke Space's Series D financing extension, its Series E announcement, its Nova development plans, Relativity Space's Terran R specifications, NASA's Terran R contracting announcement, NASA's confirmation of Firefly's Blue Ghost lunar landing, and the U.S. Space Force announcement on National Security Space Launch Phase 3 Lane 1 providers.

When you build or invest in the space economy market, you need clarity, not confusion. In our market report about the space economy, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us