Why did SpaceX buy Cursor?
Whether you're building or investing in the space economy, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
SpaceX bought Cursor for an implied $60 billion to turn its enormous AI computing investments into a major enterprise software business, while giving Grok an established position in professional AI coding.
The acquisition closed on August 14, 2026. SpaceX reported $42.5 billion in accounting acquisition consideration and another $23.4 billion in equity awards linked to future employee service. The headline $60 billion valuation therefore needs to be distinguished from the transaction's accounting treatment.
SpaceX was already becoming an AI company before buying Cursor. Following its acquisition of xAI, the Super Intelligence division generated $7.56 billion in third-quarter revenue, representing approximately 52% of SpaceX's total. Cursor added a successful application to a business already investing heavily in computing infrastructure and foundation models. With AI now over half of SpaceX's revenue, what still counts as space business is a fair question, and we draw that line in our space economy market report.
Cursor was hardly a speculative startup when SpaceX acquired it. Its estimated annualized revenue had reached approximately $4 billion by May 2026, and SpaceX subsequently recognized $608 million from the company in roughly seven weeks. That puts the acquisition price at about 15 times Cursor's pre-acquisition estimated revenue run rate.
The enterprise customer base was arguably as valuable as the technology. Cursor had relationships with more than 50,000 engineering teams, including major companies such as NVIDIA, Salesforce, BP, and Sanofi. Building comparable distribution from scratch would have taken SpaceX years, even with substantial financial resources.
The original partnership also made a full acquisition unusually attractive. SpaceX had negotiated an option to buy Cursor, alongside conditional termination and deferred-service payments potentially totaling $10 billion if it declined. Buying Cursor was therefore part of the relationship's commercial structure from the beginning.
Owning Cursor creates an opportunity to improve AI coding margins by combining the software with Grok, Cursor's proprietary Composer models, and SpaceX's computing infrastructure. But cheaper internal inference will not help much if developers prefer competing models, and running proprietary GPUs still carries substantial costs.
That dependency became visible almost immediately. OpenAI announced plans to terminate its direct model-supply agreement with Cursor, while Anthropic continued providing Claude access. SpaceX acquired a platform whose flexibility depended partly on companies that also competed with its AI ambitions.
The price also reflected a major bet on people. SpaceX's $23.4 billion in future-service equity awards underlined the importance of retaining Cursor's engineers, particularly those developing coding agents, repository understanding, and specialized models.
The first financial results demonstrate revenue contribution, not acquisition success. Cursor contributed $608 million after closing, but SpaceX has not disclosed enough standalone profitability data to establish whether the purchase can generate an attractive return on $60 billion.
Our conclusion is that SpaceX had a convincing strategic reason to buy Cursor, but paid a demanding price for it. The acquisition brought together infrastructure, AI models, and enterprise distribution under one owner. Whether that integration is worth $60 billion depends on Cursor continuing to win developers, preserving access to competitive models, and turning rapid revenue growth into substantial profits.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

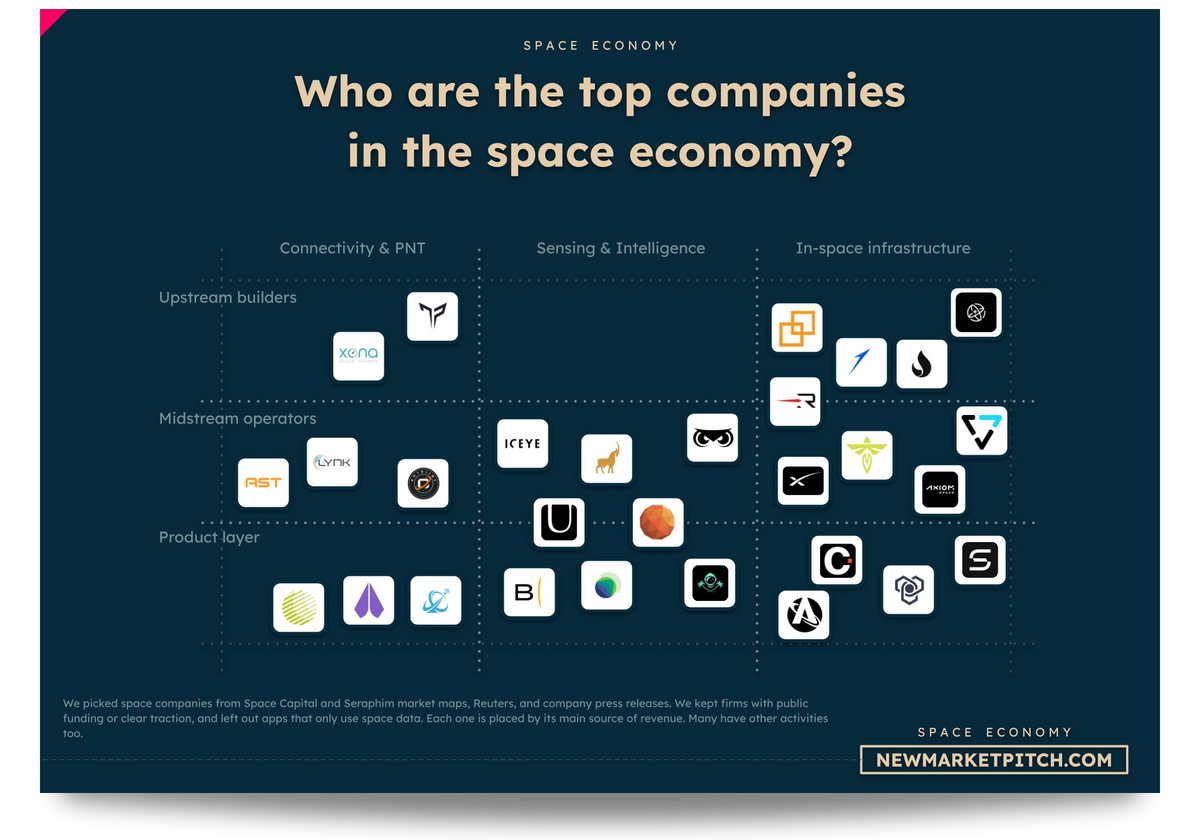
In our report covering the space economy market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Did SpaceX really buy Cursor for $60 billion?
SpaceX acquired Cursor for an implied $60 billion in August 2026, making the AI coding platform one of the biggest purchases in the company's history.
The deal was completed on August 14, when Anysphere, the company behind Cursor, became a wholly owned SpaceX subsidiary. According to SpaceX's SEC filing, Cursor shareholders received rights to approximately 389.3 million SpaceX Class A shares, plus additional shares and equity awards linked to employees.
The transaction followed an April partnership that gave SpaceX access to Cursor's AI coding technology and included an option to acquire the business. SpaceX exercised that option in June.
There is an important difference between the headline price and the accounting figures. SpaceX's third-quarter results showed $42.5 billion in GAAP acquisition consideration, alongside $23.4 billion in equity awards tied to future employee service. Those employee awards are subject to forfeiture and are accounted for separately from the acquisition price.
The $60 billion figure represents the implied equity valuation of the transaction. SpaceX paid primarily with its own stock, while a substantial part of the broader arrangement was designed to keep Cursor's employees at the company.
Why would SpaceX want to own an AI coding company?
SpaceX bought Cursor because Elon Musk's company was already becoming a major AI infrastructure business, and Cursor gave it a successful software product to sell directly to businesses.
The transformation began well before the acquisition. SpaceX acquired xAI in February 2026, bringing Grok and the Colossus AI computing infrastructure under the same corporate umbrella.
By the third quarter, SpaceX's Super Intelligence division generated $7.56 billion in revenue, accounting for approximately 52% of the company's $14.575 billion quarterly total. Connectivity represented about 36%, while the traditional Space segment contributed 12%. Seeing how SpaceX's segments stack up is easier beside the rest of the sector, which the market maps and grids in our report on the space economy lay out.
The numbers are striking for a company best known for launching rockets. SpaceX was already generating more quarterly revenue from its AI-related business than from either satellite connectivity or space activities.
Cursor fitted into this new business. SpaceX had invested heavily in computing infrastructure and AI models, but applications that companies were willing to pay for offered another way to capture the value of those investments.
Cursor already had a popular coding environment, enterprise customers, and a business generating billions of dollars in annualized revenue. Buying the company gave SpaceX an immediate presence in professional AI software.

Our research about the space economy gets updated several times a month, so you always get the latest view of where things stand.
Was SpaceX buying Cursor because Grok couldn't compete with OpenAI and Anthropic?
SpaceX bought Cursor partly to give Grok a stronger position in AI coding, where OpenAI, Anthropic, and established developer tools had already attracted large numbers of paying customers.
Grok had substantial computing resources and general-purpose AI capabilities. But having a powerful language model does not automatically make developers want to use it for programming.
Cursor had built a complete coding environment around AI models. Developers could ask it to understand repositories, edit several files, generate code, and increasingly carry out complex tasks through autonomous agents.
That gave Cursor something Grok lacked: an established product that developers were already using throughout their working day.
The acquisition also brought Cursor's expertise in handling context, coordinating coding agents, and integrating models into practical workflows.
We don't have evidence that SpaceX acquired Cursor because Grok was categorically worse than competing models. The commercial explanation is clearer. SpaceX could improve Grok's distribution overnight by connecting it to a widely adopted coding platform.
How big was Cursor when SpaceX acquired it?
Cursor was already generating approximately $4 billion in annualized revenue before the SpaceX acquisition, making it one of the fastest-growing AI software companies.
Sacra estimated that Cursor's annualized revenue rose from approximately $1.2 billion at the end of 2025 to $4 billion by May 2026. Dealroom reported a similar trajectory, with the company's revenue run rate reaching roughly $2 billion in February and $3 billion in late April.
That means Cursor roughly doubled its annualized revenue in four months.
The first figures reported after the acquisition also showed substantial commercial activity. SpaceX's third-quarter results attributed $608 million of revenue to Cursor between August 14 and September 30.
Over approximately 48 calendar days, that works out to around $12.7 million per day, or $4.6 billion on an illustrative annualized basis.
The figures are not perfectly comparable: the earlier numbers are estimated revenue run rates, while the $608 million represents recognized revenue over a short accounting period. Still, they consistently place Cursor in the multibillion-dollar revenue category.
| Cursor revenue indicator | Figure |
|---|---|
| End-2025 annualized revenue | ~$1.2B |
| February 2026 revenue run rate | ~$2.0B |
| Late-April revenue run rate | ~$3.0B |
| May–June revenue run rate | ~$4.0B |
| Post-acquisition recognized revenue through September | $608M |
| Approximate reporting period | 48 days |
| Average recognized revenue per day | ~$12.7M |
| Illustrative annualized recognized revenue | ~$4.6B |
SpaceX therefore acquired a business whose product had already found a huge market. The uncertainty concerns how much longer Cursor can maintain that pace.

In our market report about the space economy, we look at what the winners do differently, so you can learn from the best instead of guessing.
Why didn't SpaceX just build its own version of Cursor?
SpaceX could have built an AI coding editor, but buying Cursor gave it an established product, more than 50,000 engineering teams, and years of developer trust in one transaction.
Cursor's advantage extended beyond its interface. Its software understood large codebases, predicted edits, managed context for AI models, and allowed developers to work with increasingly capable coding agents.
By the time SpaceX acquired it, Cursor had introduced Cloud Agents and was developing its own Composer models. These products were designed to handle more programming work automatically, including changes across multiple files.
Replicating those capabilities would have required more than hiring engineers. SpaceX would also have needed to convince developers to switch from existing tools, negotiate enterprise contracts, and build the security and support systems expected by large companies.
According to Sacra, Cursor's customers included NVIDIA, Uber, Adobe, Salesforce, and PwC. Dealroom also reported enterprise relationships with British Airways, BP, Nokia, and Sanofi.
This distribution was especially valuable. Developers are reluctant to replace tools that have become part of their daily workflow, even when a competing product offers attractive features.
SpaceX effectively purchased an established route into corporate engineering teams, along with the technology supporting it.
Did SpaceX mainly want Cursor's enterprise customers?
Cursor's enterprise customers were a major attraction for SpaceX because they gave Grok a direct route into companies already spending heavily on AI-powered software development.
Cursor initially became popular among individual programmers. Its growth increasingly came from engineering teams purchasing subscriptions across their organizations. Who the paying customers are, and which problems they would pay to solve, is something we describe in our report covering the space economy market.
Dealroom reported that enterprise customers represented a substantial majority of Cursor's annualized revenue by early June 2026, although estimates of the exact share varied.
This shift made Cursor especially valuable. Selling AI tools to a large engineering organization can involve hundreds or thousands of seats, centralized billing, security requirements, and additional charges for intensive agent usage.
The customer base was also unusually broad. NVIDIA and Salesforce represented technology companies, while BP, British Airways, and Sanofi showed that AI coding tools were reaching energy, aviation, and pharmaceuticals.
For SpaceX, these relationships opened an enterprise software market that looked very different from its traditional business selling rocket launches or satellite connectivity.
There is still a limit to the opportunity. A company paying for Cursor will not necessarily purchase Grok directly or move its other AI workloads onto SpaceX infrastructure. The acquisition provides access to customers, but turning those relationships into additional revenue will require competitive products.

In our document detailing everything you need to know about space economy, you will always find fresh funding data, taken straight from our own verified funding database.
How does Cursor fit into SpaceX's giant AI data centers?
Cursor fits into SpaceX's AI infrastructure strategy by creating direct demand for the computing capacity SpaceX has been spending tens of billions of dollars to build.
SpaceX's IPO prospectus described a strategy of connecting computing infrastructure, AI models, and applications. Its original Cursor partnership included GPU capacity, improvements to Grok, and the possible development of new models and products.
The scale of the infrastructure expansion helps explain why this was attractive.
SpaceX increased its reported nameplate computing capacity from 0.6 gigawatts in September 2025 to 1.4 gigawatts in June 2026 and 1.7 gigawatts in September 2026. That's an increase of approximately 183% in twelve months.
Investment grew even faster. Super Intelligence capital expenditure reached roughly $40 billion during the first nine months of 2026, compared with approximately $8.1 billion during the same period a year earlier.
With Cursor, SpaceX can sell a complete AI coding product while running some of the underlying workloads on its own infrastructure.
There are potentially two financial benefits. SpaceX can earn software revenue rather than only collecting infrastructure fees, and it can optimize how models use the computing capacity it owns.
The actual savings will depend on GPU utilization, electricity costs, depreciation, and the amount of computing required by coding agents. SpaceX hasn't published enough standalone Cursor cost data to calculate those savings yet.
Could SpaceX make Cursor more profitable by replacing OpenAI with Grok?
SpaceX could improve Cursor's margins by shifting more coding workloads to Grok and its own computing infrastructure, provided the cheaper model setup performs well enough for developers.
AI coding tools have a challenging cost structure. A subscription generates recurring revenue, but each AI interaction consumes computing resources. Autonomous agents can be particularly expensive because they may inspect repositories, generate code, run tests, and repeat the process several times.
This puts pressure on companies offering generous usage allowances.
Cursor was already trying to reduce those costs before the SpaceX acquisition. Sacra reported that proprietary models and cheaper model routing helped the company reach slightly positive gross margins by April 2026, with enterprise customers producing better economics than individual subscriptions.
SpaceX could accelerate that work through its Colossus infrastructure and Grok models. It also gained access to Cursor's own Composer model development.
But cheaper inference is useful only when it preserves the coding quality customers expect. Developers may continue preferring Claude, GPT, or other models for certain tasks.
And owning the GPUs doesn't make inference free. SpaceX still has to pay for electricity, equipment, maintenance, and depreciation, even when it stops sending money to outside model providers.
For now, there's a credible path toward better margins. SpaceX has not disclosed enough standalone post-acquisition figures to prove that Cursor has become substantially more profitable.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the space economy market, we look at what broke startups before you, so you don't repeat it.
Why did SpaceX pay $60 billion instead of keeping its Cursor partnership?
SpaceX chose to acquire Cursor because owning the platform gave it control over the product, technology, and customer relationships, while the original partnership included expensive conditions if SpaceX declined the purchase.
The April 2026 agreement was more complicated than a standard computing deal.
According to SpaceX's IPO prospectus, the agreement gave SpaceX an option to acquire Cursor at a predetermined valuation. Declining that option could trigger a $1.5 billion termination fee and an $8.5 billion deferred services fee, depending on the contractual conditions.
Those two amounts totaled $10 billion, equivalent to roughly one-sixth of Cursor's $60 billion acquisition valuation.
The comparison does not mean SpaceX avoided an immediate $10 billion cash bill by buying Cursor. The contractual payments had their own conditions and timing.
Still, the structure shows that the acquisition was built into the relationship from the beginning.
Full ownership also let SpaceX determine how closely Cursor would integrate with Grok and its computing infrastructure. Without that control, Cursor could have maintained partnerships with multiple providers and eventually chosen a different technological direction.
The acquisition secured that long-term position, although it also exposed Cursor to the consequences of SpaceX's relationships with competing AI companies.
Was Cursor actually worth $60 billion?
Cursor's $60 billion valuation was expensive, but a reported $4 billion annualized revenue run rate and exceptionally fast growth made the price more defensible than the headline suggests.
At approximately $4 billion in annualized revenue, SpaceX paid around 15 times Cursor's estimated revenue run rate. Prices like 15 times revenue show where investor appetite stands, and we look at what they back and avoid in our space economy market report.
Using the short period of recognized revenue reported after the acquisition gives an illustrative multiple closer to 13 times annualized revenue. That second calculation is less reliable because it annualizes only about seven weeks of activity.
The price also needs to be compared with Cursor's previous valuations.
Sacra reported that Cursor was valued at $2.5 billion in December 2024, $9.9 billion in June 2025, and $29.3 billion in November 2025.
The SpaceX transaction therefore valued Cursor at more than six times its mid-2025 level and roughly twice its late-2025 valuation.
| Cursor valuation reference | Value | Context |
|---|---|---|
| December 2024 valuation | $2.5B | Early growth-stage benchmark |
| June 2025 valuation | $9.9B | Nearly 4x December valuation |
| November 2025 valuation | $29.3B | Approximately 3x June valuation |
| SpaceX acquisition valuation | $60.0B | Roughly 2x November valuation |
| May 2026 annualized revenue estimate | ~$4.0B | Sacra estimate |
| Acquisition / May revenue run rate | 15.0x | Based on annualized revenue |
| Illustrative post-acquisition annualized revenue | ~$4.6B | Derived from 48-day contribution |
| Acquisition / illustrative annualized revenue | ~13.0x | Not a trailing revenue multiple |
The problem is that revenue growth alone cannot tell us whether $60 billion was a good investment.
Cursor must keep expanding while improving its margins, retaining customers, and defending its position against major AI companies. A business growing this quickly can justify a high multiple, but that multiple leaves little room for a sharp slowdown.
Our view is that SpaceX paid a substantial strategic premium for Cursor. The reported numbers support the scale of the business, although they don't yet prove the acquisition will earn an attractive return.

In our research about the space economy, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Did SpaceX buy Cursor to take on OpenAI and Anthropic?
SpaceX's Cursor acquisition gave Grok a much stronger way to compete with OpenAI's Codex and Anthropic's Claude Code in professional software development.
Coding had already become one of the most commercially successful applications of generative AI. Developers were paying for tools that could write code, understand existing projects, and increasingly complete tasks with limited supervision.
Before the acquisition, Cursor served as a platform connecting developers to models from several AI companies.
That approach was attractive because customers could use different models for different jobs. A developer might prefer Claude for complex changes, a GPT model for another task, and Cursor's own models for faster editing.
SpaceX acquired that distribution channel, along with the opportunity to give Grok a larger role in the product.
But the takeover created an immediate problem. OpenAI and Anthropic were simultaneously Cursor's suppliers and competitors. Their models helped make Cursor attractive, while their own coding products competed for the same customers.
SpaceX now had to decide how aggressively to promote Grok without weakening Cursor's flexibility.
The decision became more complicated when OpenAI moved to end its direct relationship with Cursor.
Did OpenAI really cut off Cursor after SpaceX bought it?
OpenAI announced plans to terminate its direct model-supply agreement with SpaceX-owned Cursor, creating one of the clearest problems caused by the acquisition.
On August 28, 2026, OpenAI said it had notified SpaceX that it intended to wind down the agreement, with a proposed termination date of November 12.
OpenAI cited contractual concerns involving Elon Musk's companies and said it lacked sufficient confidence that its technology would be used under the agreed terms.
This was a significant commercial decision. WIRED reported in September that OpenAI had internally estimated its Cursor partnership could generate more than $1 billion in annual revenue.
That represented a potentially valuable customer relationship for OpenAI, yet the company was prepared to end it.
The planned termination affected the direct supply arrangement rather than necessarily blocking every possible way to use OpenAI models inside Cursor. IDC reported that developers could continue accessing supported models through their own API keys.
Anthropic took a different approach. IDC reported that Claude access remained available in Cursor after the acquisition.
SpaceX's IPO prospectus also disclosed a large computing relationship with Anthropic, involving approximately $1.25 billion in monthly cloud-service payments, subject to contractual terms and a ramp-up period. That relationship gives the companies commercial interests beyond competing coding tools.
We cannot establish that Anthropic maintained Cursor access because of those computing contracts. But the contrast is revealing: OpenAI moved to leave a potentially billion-dollar relationship, while Anthropic continued supplying models despite operating a competing coding product.
Cursor's dependence on outside models had become a more complicated issue under SpaceX ownership.

If you build or invest in the space economy market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Did SpaceX also buy Cursor to get its engineers?
Cursor's engineers and proprietary coding models were an important part of the SpaceX acquisition, particularly because the company needed to improve how Grok performs inside real software-development workflows.
Cursor had built specialized technology for editing code, understanding large repositories, and coordinating AI agents. Its Composer models were also designed to reduce reliance on external providers for certain programming tasks.
These capabilities required expertise different from training a general-purpose foundation model.
A coding agent must understand how different files interact, make consistent changes, run commands, interpret errors, and often revise its own work. Reliable performance depends heavily on the application surrounding the model.
The acquisition terms show how much SpaceX valued keeping Cursor's employees.
SpaceX reported approximately $23.4 billion in equity awards attributable to future employee service, subject to forfeiture. This was separate from the $42.5 billion GAAP acquisition consideration.
The arrangement tied substantial compensation to employees remaining with the business after the takeover.
Cursor also brought financial resources of its own. SpaceX's prospectus reported approximately $2.7 billion in Cursor cash and cash equivalents as of January 31, 2026. Sacra reported that Cursor had explored financing at a valuation of around $50 billion before the acquisition agreement.
Those details suggest Cursor had meaningful alternatives and was not obviously forced into a sale by an immediate shortage of cash.
SpaceX obtained the people, technology, and commercial platform together. Keeping those engineers will now be essential to maintaining Cursor's product quality.
Has buying Cursor already paid off for SpaceX?
Cursor has already added hundreds of millions of dollars to SpaceX's quarterly revenue, but there is not enough evidence yet to say the $60 billion acquisition has paid off financially.
SpaceX reported $608 million in Cursor revenue from August 14 through September 30.
That accounted for approximately 8% of the company's $7.56 billion Super Intelligence quarterly revenue and around 4% of SpaceX's total revenue. Cursor already making up about 4% of SpaceX's revenue is the kind of early signal we follow every quarter in our space economy market report.
The wider AI business was growing much faster in absolute terms.
Super Intelligence revenue increased from $813 million in the third quarter of 2025 to $7.56 billion a year later, a rise of approximately 830%. It also increased from $2.56 billion in the preceding quarter, roughly a 195% sequential increase.
Cursor was clearly contributing to SpaceX's results, but much of the division's growth came from the broader expansion of cloud computing and AI services.
The profitability picture is harder to assess. SpaceX reported $431 million in Super Intelligence operating income, including approximately $1.2 billion of acquisition-related share-based compensation.
Those segment results do not reveal Cursor's standalone post-acquisition operating profit or the return earned on the acquisition price.
For now, the clearest financial achievement is that SpaceX purchased a software business already generating revenue at a multibillion-dollar annualized pace. Whether it can earn enough profit from that business is still an open question.

Theory only gets you so far. In our document detailing everything you need to know about space economy, we dig up the real signals from the field and show you the ones worth watching.
Can Cursor really help SpaceX beat OpenAI and Anthropic in AI coding?
Cursor gives SpaceX a serious position in AI coding, but beating OpenAI and Anthropic will require stronger models, competitive pricing, and a product that developers continue trusting.
SpaceX now owns several important pieces of an AI business. It operates computing infrastructure through Colossus, develops Grok through xAI, and sells a professional coding product through Cursor.
Those assets could become more valuable together.
SpaceX can optimize its models for Cursor's workloads, run more inference internally, and develop agent features around real developer behavior. Cursor, meanwhile, can use dedicated computing capacity to support demanding tasks.
The opportunity is growing as coding tools move toward autonomous agents. Developers increasingly expect AI to inspect repositories, modify code, run tests, and complete larger pieces of work.
Cursor could become a major platform for selling that kind of automation to businesses.
Competition will be tough, though. GitHub Copilot benefits from Microsoft's distribution and integration with GitHub. Claude Code has direct access to Anthropic's models. OpenAI can build Codex around its own research and infrastructure.
Cursor will need to remain attractive even when a rival releases a better model or a cheaper agent.
OpenAI's planned contract termination also showed that SpaceX cannot assume competing model providers will always support the platform on the same terms.
The acquisition gave SpaceX an established competitor in the market. Whether Cursor can keep winning developers will depend on the product itself.
What could make SpaceX regret buying Cursor?
SpaceX could regret the Cursor acquisition if coding-agent competition weakens its growth, model-provider restrictions hurt the product, or its expensive computing requirements prevent meaningful profits.
The $60 billion valuation creates substantial expectations. Cursor was already generating approximately $4 billion in annualized revenue when the deal was announced, but even that scale leaves a long path toward earning back the investment.
There are several concrete risks.
OpenAI's planned withdrawal demonstrated how ownership can affect Cursor's access to external models. If more providers restricted their relationships, Cursor might lose some of the flexibility that helped it attract developers.
Competition could also put pressure on pricing. Microsoft, OpenAI, and Anthropic have strong reasons to make their coding products attractive, even if doing so compresses margins across the market.
Then there is the cost of agents. As developers delegate longer and more complex tasks, AI systems may consume more tokens, more GPU time, and more external tools. Higher usage does not automatically translate into higher profit.
Finally, Cursor needs to retain the engineers behind its technology. The large employee equity arrangements show that SpaceX recognized this dependence.
A sharp slowdown in revenue growth, weaker model access, and disappointing margins would be a particularly damaging combination.
Cursor can remain successful as a product while still failing to justify what SpaceX paid for it.

In our report covering the space economy market, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
So why did SpaceX buy Cursor in the end?
SpaceX bought Cursor to turn its enormous AI infrastructure investments into a major enterprise software business, while giving Grok an immediate position in the fast-growing market for AI coding tools.
The acquisition brought together computing infrastructure, foundation models, and a popular coding application under one corporate owner. Owning infrastructure, models and apps under one roof is the kind of move we study in market leaders in our report covering the space economy market.
SpaceX had already spent tens of billions of dollars expanding its AI computing capacity. Cursor gave it an established product through which companies could pay for the work performed by those models, along with specialized engineering talent and direct relationships with large enterprise customers.
The purchase also saved SpaceX from having to build a competing coding platform and persuade developers to adopt it from scratch.
The price was substantial. At approximately 15 times Cursor's estimated annualized revenue, the $60 billion deal assumed that the company would continue growing quickly and eventually produce attractive margins.
The first financial results are encouraging on revenue, but they don't establish the full economic return. Cursor contributed $608 million after the acquisition closed, while OpenAI's planned withdrawal showed how quickly ownership could complicate relationships with competing model providers.
We think the strategic reason for the acquisition is convincing. SpaceX wanted to own the application through which developers increasingly consume AI, rather than depend entirely on selling models and computing capacity to other companies.
The question now is whether that control will translate into enough profit to justify $60 billion. SpaceX has bought itself a leading position in AI coding, but it still has to prove that owning Cursor was worth the price.
Our methodology
This analysis examines why SpaceX acquired Cursor at an implied $60 billion valuation and whether the commercial rationale supports such a large purchase. We evaluated the transaction structure, Cursor's revenue growth and enterprise adoption, SpaceX's AI infrastructure spending, the opportunity to improve coding-model economics, and the competitive consequences of bringing Cursor under SpaceX ownership.
We prioritized primary corporate disclosures, particularly SpaceX's SEC acquisition filing, IPO prospectus, and third-quarter financial results. These establish the acquisition date, share consideration, accounting treatment, segment performance, computing capacity, and contractual arrangements. We distinguish the approximately $60 billion implied equity valuation from the $42.5 billion in GAAP acquisition consideration and the $23.4 billion in equity awards attributable to future employee service.
We used Sacra and Dealroom to reconstruct Cursor's private-market revenue and valuation trajectory. Their estimates provide useful benchmarks but are treated differently from company-reported financial results. The estimated $4 billion annualized revenue run rate is compared with the $608 million in recognized post-acquisition revenue disclosed by SpaceX. We annualized that short reporting period only to provide an illustrative comparison, not a trailing twelve-month revenue figure.
To understand the acquisition's strategic value, we examined the original SpaceX–Cursor partnership, its acquisition option, conditional fees, and proposed infrastructure integration. We compared these arrangements with Cursor's existing distribution, enterprise relationships, proprietary Composer models, and coding-agent capabilities. The aim was to identify what SpaceX gained through ownership that would have been harder to secure through a commercial partnership or internal product development.
For the profitability analysis, we considered Cursor's reported gross-margin improvement, model-routing economics, and the potential benefits of using Grok and SpaceX-owned computing infrastructure. We did not assume that internal GPU usage is free or that replacing external models automatically improves margins. The analysis separates plausible operating benefits from profitability improvements that have not yet been established through standalone financial disclosures.
We also examined competitive developments after the acquisition, especially OpenAI's announced plan to end its direct Cursor model-supply agreement, Anthropic's continued availability within Cursor, and the expansion of competing coding agents. These developments help explain both the strategic value of owning a popular coding platform and the risks created when its suppliers are also competitors.
Our conclusions are based on the combined evidence rather than a single valuation multiple or assumption about management's intentions. The disclosed transaction and revenue figures establish what SpaceX purchased and the commercial scale Cursor had achieved. The assessment of whether the purchase will produce an attractive financial return remains conditional on future growth, customer retention, model access, and profitability.
Key sources include SpaceX's SEC acquisition filing, SpaceX's IPO prospectus, SpaceX's third-quarter earnings release, SpaceX's second-quarter Form 10-Q, Sacra's Cursor financial and valuation research, Dealroom's Cursor revenue analysis, Cursor's introduction of Composer, Cursor's Composer 2 announcement, Cursor's Cloud Agents announcement, Cursor's enterprise self-hosting announcement, Cursor's security documentation, OpenAI's statement on its Cursor agreement, Anthropic's Claude Code development update, OpenAI's GPT-5.3-Codex announcement, and GitHub's Copilot Cloud Agent update.

In our research about the space economy, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us