Is Halter really worth $2B?
Whether you're building or investing in the AgriTech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Yes, Halter's $2 billion valuation looks credible given its rapid commercial growth, although the company still needs to prove that millions of connected cattle can generate strong recurring profits.
The valuation comes from a completed $220 million Series E financing in March 2026, just nine months after Halter raised $100 million at a $1 billion valuation. Investors effectively doubled their assessment of the business during a difficult period for agricultural technology funding.
Commercial adoption has accelerated even faster than the headline valuation. Halter grew from approximately 500,000 collars across 2,000 farms in June 2025 to 1.5 million collars across 3,500 farms by August 2026. Its reported collar base tripled while its farm count increased by 75%. Adoption numbers like collars and farms are among the signals we follow every quarter in our agritech market report.
That difference reveals an important shift in customer economics. The implied average deployment rose from 250 to approximately 429 collars per farm, suggesting Halter is increasingly serving larger herds, expanding within existing customers, or both. The company has not disclosed enough information to separate those effects.
The strongest valuation argument comes from translating deployments into subscription revenue. At 1.5 million paying collars and $7–$10 per animal per month, Halter could generate $126 million to $180 million in annualized subscriptions. That would put the $2 billion valuation at approximately 11–16 times revenue, assuming every reported collar is billable at those prices.
Actual financial disclosure is less conclusive. A private-company database reports around $89 million in revenue, while Halter's New Zealand subsidiary generated NZ$98.1 million over nine months. Neither figure establishes consolidated annual recurring revenue, particularly because substantial revenue at the New Zealand entity comes from transactions with its American parent.
Halter's business model goes beyond virtual fencing. Recurring subscriptions combine cattle movement, animal monitoring, pasture planning, and farm management tools, giving the company opportunities to earn more from each customer. But manufacturing, installations, connectivity, and hardware replacements make its cost structure more demanding than that of a pure software company.
There is evidence that farmers can earn a return on the technology. Research covering ten high-performing New Zealand dairy farms found average improvements of 13.2% in profit before tax and 9.5% in milk solids produced per hectare. Those findings are encouraging, but they do not establish that Halter alone caused every improvement or that similar returns are achievable on every ranch.
The American market provides substantial expansion potential. The United States has approximately 94.2 million cattle and calves, compared with Halter's 1.5 million reported collars worldwide. At five million paying animals and $7 monthly, Halter could generate $420 million in annualized subscriptions, although only part of the total cattle population is economically suitable for virtual fencing.
The biggest unresolved questions are customer renewals, realized revenue per collar, hardware costs, and consolidated profitability. Halter has demonstrated impressive adoption, but Nofence, Gallagher, and Vence offer alternatives, and farmers will ultimately judge the technology by its economic benefits rather than its sophistication.
Our conclusion is that $2 billion is a defensible valuation for Halter today. The deployment growth and potential recurring revenue support a serious investment case, even with incomplete financial disclosure. A future valuation of $4 billion or $5 billion is possible, but it would require much clearer proof of subscription retention, healthy margins, and profitable international scaling.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

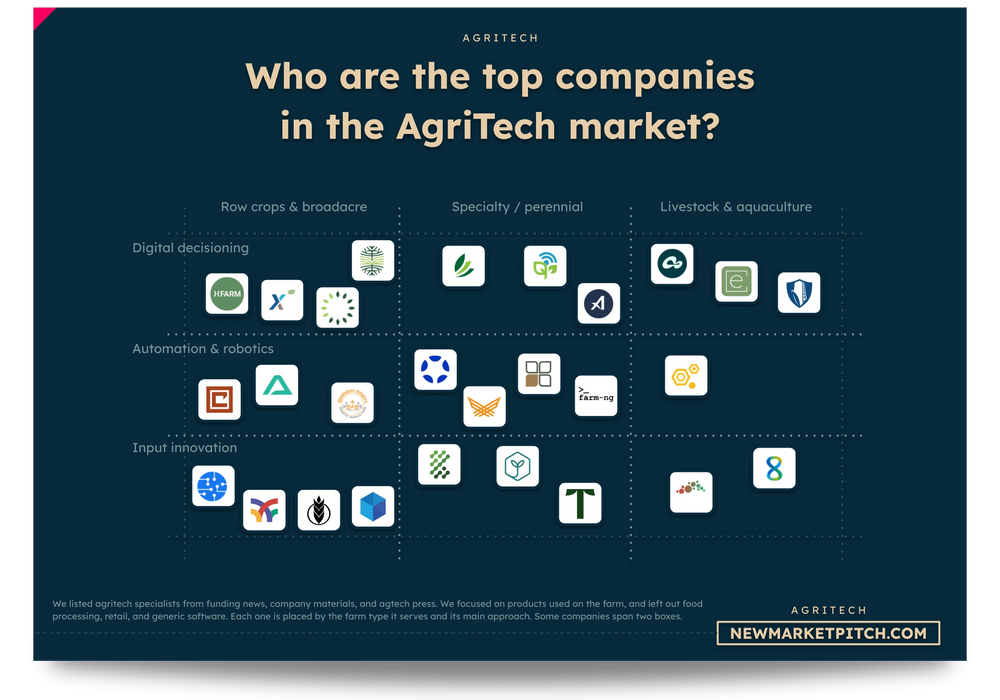
In our report covering the agritech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why did Halter suddenly become a $2 billion company?
Halter reached a $2 billion valuation because investors are betting that its smart cattle collars could become essential technology for livestock farmers worldwide. Its growth since the latest funding round makes that bet look increasingly credible.
In June 2025, the New Zealand company raised $100 million at a $1 billion valuation. Just nine months later, in March 2026, Halter raised another $220 million at twice that valuation. Founders Fund led the round, alongside investors including Bessemer Venture Partners, Bond, Blackbird, and DCVC. A round led by Founders Fund with Bessemer and DCVC says a lot about where agritech money goes, which we trace in our report on agritech.
Halter uses solar-powered collars, wireless connectivity, and software to help farmers manage cattle remotely. Farmers can create virtual fences, move herds between grazing areas, track animal behavior, and spot potential health problems without physically handling every animal.
The timing of the financing was especially striking. According to AgFunderNews, global agrifoodtech funding had fallen more than 70% from its 2021 peak, and only around ten agricultural technology companies had ever reached a $2 billion valuation.
Yet Halter's growth continued after the financing. Farmers Weekly reported in August 2026 that the company had reached 1.5 million collars across 3,500 farms, compared with 500,000 collars and 2,000 farms in June 2025.
The question is whether that commercial growth can produce enough recurring revenue and profit to support a $2 billion business.
Is Halter's $2 billion valuation official or just an estimate?
Halter's $2 billion valuation is real: it comes from a completed $220 million Series E financing, rather than a speculative estimate from an investment database.
Halter confirmed the transaction in March 2026, and its legal adviser Goodwin independently reported the financing. The company doubled its previous $1 billion valuation in nine months.
There is still a distinction between a financing valuation and what someone would pay to acquire the whole company. Venture investors may receive preferred shares carrying rights that ordinary shareholders do not have.
We should also remember that the $2 billion figure reflects the financing terms negotiated in March. Halter has since reported much higher deployment numbers, but there has been no subsequent publicly confirmed funding round establishing a new valuation.
For now, $2 billion remains the strongest documented benchmark for Halter's market value.
Is Halter still growing really fast today?
Halter is currently growing at an exceptional rate for an agricultural technology company, with its reported collar base tripling in roughly 14 months.
The company had approximately 200,000 cattle under management when it launched commercially in the United States in August 2024. Its investor NewView Capital subsequently reported 350,000 collars, while Halter's 2025 annual review disclosed almost 700,000 live collars globally.
By March 2026, Halter had sold one million collars. Five months later, Farmers Weekly reported 1.5 million collars on cattle.
The most revealing detail comes from the period between those announcements. More than 500,000 collars were signed up during April, May, and June alone, according to Farmers Weekly.
That three-month volume matched Halter's entire reported collar base from June 2025.
There is one important accounting distinction: some company announcements count collars sold, others count live collars or animals under management. We cannot treat every historical number as a perfectly consistent measurement of installed equipment.
Still, the overall trajectory is hard to dispute. Halter has moved from hundreds of thousands of connected cattle to more than a million in a relatively short period.
| Period | Reported collars | Milestone |
|---|---|---|
| August 2024 | 200,000 | Cattle under management |
| 2025 investor update | 350,000 | Reported collar base |
| June 2025 | 500,000 | Reported collar base |
| End of 2025 | Almost 700,000 | Live collars globally |
| March 2026 | 1 million | Cumulative collars sold |
| April–June 2026 | 500,000+ | New collar sign-ups during quarter |
| August 2026 | 1.5 million | Collars on cattle worldwide |

Our research about farm technology gets updated several times a month, so you always get the latest view of where things stand.
Is Halter getting bigger customers or just signing up more farms?
Halter appears to be serving substantially more cattle per farm than before, which helps explain why collar deployments are growing much faster than its customer count.
In June 2025, Halter reported approximately 2,000 farms and 500,000 collars. By August 2026, those totals had climbed to 3,500 farms and 1.5 million collars.
That's 75% growth in farms but 200% growth in collars. Herds getting bigger on each farm points to who the customers are and which problems they would pay to solve, as profiled in our market report about agritech.
Dividing the two totals gives approximately 250 collars per farm initially and 429 afterward. The implied average increased by around 71%.
These figures do not establish that existing customers individually increased their deployments by 71%. Halter may simply be attracting larger ranches, particularly in the United States. The company has not published enough customer-level information to separate those explanations.
Still, the pattern is encouraging. Halter has increased its reach across farms while also moving toward substantially larger deployments per reported customer.
That combination can make growth more efficient: signing one large ranch with 1,000 cattle potentially produces far more subscription revenue than winning several small farms.
How much money is Halter actually making?
Halter is generating meaningful revenue, but its publicly available financial figures still do not tell us exactly how much recurring revenue the entire company earns.
Private-company data provider Multiples records approximately $89 million in revenue alongside Halter's March 2026 financing. That would put the $2 billion valuation at roughly 22.5 times revenue.
However, the reporting period and accounting basis behind that estimate are not sufficiently clear to treat it as verified consolidated annual recurring revenue.
We also have financial statements from Halter's New Zealand operations.
According to Farmers Weekly in August 2026, the New Zealand entity generated NZ$98.1 million in revenue during the nine months ending December 2025. Its previous financial year, covering 12 months, produced NZ$71 million.
The improvement is striking, especially given the shorter reporting period.
But approximately half the New Zealand entity's revenue came from subscriptions and instalment payments, while the remainder came from services provided to Halter's American parent company.
Those internal payments make the subsidiary's financial statements unsuitable as a direct measure of global customer revenue.
We can establish that Halter has a sizable commercial business, but consolidated subscription revenue remains one of the biggest missing pieces in its $2 billion valuation.

In our market report about farm technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
How much subscription revenue could Halter's 1.5 million collars generate?
Halter's 1.5 million reported collars could support approximately $126 million to $180 million in annualized subscription revenue at monthly prices of $7–$10 per animal, assuming every collar is paying.
AgFunderNews reported pricing of approximately $6–$10 per cow per month around the company's Series E financing. Actual prices vary with products, markets, and contracts.
Using those reference prices, we can estimate the revenue potential of Halter's reported deployments.
At $7 monthly, 1.5 million paying collars would generate $10.5 million each month, or $126 million annually.
At $10 monthly, the same number would produce $180 million annually.
Neither figure is confirmed Halter revenue. Some reported collars may not yet be activated or billable, and realized average prices could be lower or higher than the published ranges.
The calculations are still useful because they translate Halter's physical deployment numbers into something investors can actually value.
| Monthly revenue per collar | Annualized revenue at 1.5M collars | Valuation / revenue |
|---|---|---|
| $5 | $90M | 22.2× |
| $6 | $108M | 18.5× |
| $7 | $126M | 15.9× |
| $8 | $144M | 13.9× |
| $9 | $162M | 12.3× |
| $10 | $180M | 11.1× |
| $12 | $216M | 9.3× |
The $12 figure is an illustrative higher-price scenario, rather than a confirmed average Halter subscription.
At $7 per month, Halter would already have annualized subscription capacity exceeding $125 million if all 1.5 million collars were paying. That would put its valuation below 16 times revenue, considerably less demanding than the multiple implied by the $89 million estimate.
Is Halter basically selling cow collars, or is there a bigger business?
Halter is building a recurring-revenue livestock management platform, with smart collars serving as the equipment farmers need to use its software.
Customers pay recurring subscriptions for connected collars and farm management capabilities. Depending on the package, Halter can provide virtual fencing, automated herd movements, animal monitoring, reproductive information, and pasture management tools.
These services are used repeatedly throughout a farm's operating cycle.
A farmer might use virtual boundaries to divide grazing areas, move cattle into fresh pasture, monitor animal behavior, and adjust future grazing plans. The system becomes more useful when those activities are managed together.
Halter also has opportunities to sell more advanced subscriptions to existing customers. Its higher-tier dairy products include deeper pasture forecasting, reproductive analytics, and farm management integrations.
However, Halter still has to manufacture collars, provide connectivity, install equipment, and maintain devices exposed to harsh outdoor conditions.
Those physical costs mean we should be cautious about comparing its economics directly with companies selling only software.
The business could ultimately achieve attractive recurring margins, but Halter has yet to disclose enough consolidated financial information to show how profitable each connected animal becomes over its lifetime.

In our document detailing everything you need to know about agritech, you will always find fresh funding data, taken straight from our own verified funding database.
Do farmers actually make more money using Halter?
Halter can improve farm profitability considerably, particularly on pasture-based dairy farms, although the size of the benefit depends heavily on how each farm operates.
One of the clearest studies came from agricultural consultancies AgFirst and Transform Agri in October 2025.
Researchers examined ten high-performing New Zealand dairy farms using Halter and found average improvements of 8.9% in pasture harvested, 9.5% in milk solids produced per hectare, and 13.2% in profit before tax. Farm results like these help separate what already works in livestock technology from what is still being tested, as we do in our agritech report.
Those improvements go beyond saving time on fencing.
When farmers harvest more usable pasture from the same land, they can potentially produce more milk without buying additional property. Better grazing schedules can also reduce wasted grass and improve animal management.
However, the study looked at only ten high-performing farms, and the observed improvements were associated with broader changes in farm practices.
We cannot assume that Halter alone generated every percentage point of additional profit or that an average American beef ranch would obtain the same results.
The research shows that Halter can deliver benefits large enough to justify a recurring subscription. The harder question is whether those benefits hold up across thousands of customers operating under very different conditions.
Is Halter actually cheaper than building regular fences?
Halter can be much more attractive than conventional fencing on farms that frequently move cattle or need better grazing management, but the subscription is not cheap enough to make sense everywhere.
A University of Arizona comparison published in March 2025 listed Halter's annual collar subscription at approximately $66 per animal, with base-station equipment costing around $4,500.
At that reference price, a farm with 500 cattle would spend roughly $33,000 annually on collar subscriptions alone.
That can be worthwhile when the system replaces significant labor, avoids the need for kilometers of new fencing, or improves the productive use of pasture.
It is much harder to justify if a farm already has reliable physical fences and little reason to move animals frequently.
A June 2026 study in the Journal of Agricultural Economics examined virtual fencing for an intensive British beef-finishing operation and found weaker economic results than conventional electric fencing under the researchers' assumptions.
This helps explain where Halter's biggest customers are likely to come from.
Large pasture-based operations, difficult terrain, high labor costs, and opportunities to improve grazing efficiency create a much stronger business case than small farms with inexpensive existing infrastructure.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the agritech market, we look at what broke startups before you, so you don't repeat it.
Is the cattle market big enough to make Halter worth billions?
The cattle market is easily large enough to support Halter's $2 billion valuation, even if the company ultimately serves only a small percentage of animals worldwide.
According to the USDA's National Agricultural Statistics Service, the United States had 94.2 million cattle and calves in July 2026.
That is more than 60 times Halter's reported global collar base.
Of course, many animals will never need this technology. Feedlot cattle, animals kept in confinement, and farms with simple grazing requirements offer fewer reasons to pay for virtual fencing.
The more interesting calculation is how little penetration Halter needs to build a large subscription business.
At five million paying collars generating $7 monthly, annualized revenue would reach $420 million. Ten million collars would bring that figure to $840 million.
For perspective, five million animals represent only about 5.3% of the United States' total cattle and calf inventory, although Halter's realistic addressable market is substantially smaller than that headline number.
Halter has also shown that connectivity can expand the types of farms it serves.
In April 2026, the company launched Director Satellite, using Starlink connectivity to reach properties where conventional radio infrastructure was harder to deploy. Subsequent rural reporting described deployments using satellite connectivity across New Zealand, the United States, and Canada.
That removes one practical obstacle to serving remote livestock operations, although affordability and farm economics will still determine adoption.
Has Halter really cracked the American cattle market?
Halter has already established a meaningful presence in American ranching, but it is still early in a market much larger than its original New Zealand customer base.
The company launched commercially in the United States in August 2024.
By June 2025, Reuters reported approximately 150 American ranch customers across 18 states. Halter's year-end review subsequently reported operations in 22 states, compared with only three in 2024.
In March 2026, the company said American ranchers had created 60,000 miles of virtual fencing using its platform.
That is a substantial amount of configured grazing boundaries for a product that entered the market less than two years earlier. It should not be interpreted as 60,000 miles of permanent physical fencing directly replaced, since virtual boundaries can be redrawn repeatedly.
The American market also tests whether Halter can succeed beyond the intensive dairy farming practices common in New Zealand.
Large beef ranches have different herd sizes, terrain, management routines, and connectivity challenges.
Halter's expansion across more than 20 states suggests the technology works in a wider range of operating environments. We still need stronger evidence on American customer renewal rates and profitability before calling the market conquered.

In our research about farm technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Can Halter beat Nofence and Gallagher in virtual fencing?
Halter is already one of the most commercially established virtual fencing companies, but Nofence and Gallagher offer credible alternatives with advantages for different types of farmers.
Norwegian company Nofence provides GPS-based virtual fencing for cattle, sheep, and goats. Gallagher sells its eShepherd system and benefits from an established agricultural equipment business and distribution network. Who leads in virtual fencing, and who is catching up, is mapped in our agritech market report.
Vence, owned by Merck Animal Health, also competes in cattle virtual fencing.
The products are not identical.
Nofence uses cellular connectivity and can avoid the need for certain types of dedicated base-station infrastructure. Gallagher can draw on existing relationships with farmers who already buy its traditional fencing equipment.
Halter's strongest competitive argument is its broader software offering. Farmers can combine virtual fencing with automated cattle movement, animal monitoring, grazing plans, and production management.
Price alone is unlikely to protect Halter.
The University of Arizona's 2025 comparison found competing systems with lower recurring collar fees under some pricing arrangements, although upfront equipment costs and included services differed.
We expect Halter to compete most effectively when its additional management features deliver measurable farm savings. Where customers only want inexpensive virtual boundaries, simpler rivals may have an advantage.
Will farmers keep paying Halter year after year?
Halter has several reasons to expect customers to stay, but its actual renewal rates remain undisclosed.
Farmers Weekly reported that customers typically sign contracts lasting 24 or 36 months, with payments made monthly or annually.
These contracts create revenue visibility and give farmers enough time to incorporate Halter into their operations.
Once cattle have been trained, connectivity equipment installed, and grazing routines redesigned, changing systems involves additional work.
That makes Halter potentially harder to replace than a simple monitoring device.
However, a growing collar base tells us little about how many customers renew after their initial contract.
Halter could be adding large numbers of new customers while some earlier farms discontinue the service. Public figures do not currently allow us to measure that possibility.
The information we would most like to see is the percentage of subscriptions renewed after two or three years, how many existing customers add collars, and whether the company can raise subscription prices without losing farmers.
Those figures would help establish whether Halter's recurring revenue deserves a premium software-style valuation.

If you build or invest in the agritech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Is Halter profitable yet?
Halter has reported a profit in its New Zealand operating company, but we still cannot establish whether the entire international group is profitable.
According to Farmers Weekly, the New Zealand entity earned NZ$2.6 million in net profit during the nine months ending December 2025.
That is encouraging for a company operating physical hardware and agricultural services.
However, approximately half the entity's revenue came from services provided to Halter's American parent company. Internal group payments can affect how profits appear across subsidiaries.
The result therefore cannot be treated as consolidated profit for Halter worldwide.
Meanwhile, the company expanded from 255 to 535 employees over approximately 12 months, according to its August 2026 disclosures.
That is an increase of roughly 110%, compared with approximately 200% growth in reported collars between June 2025 and August 2026.
Collar deployments have grown faster than staffing, although these periods are not perfectly aligned and employee productivity alone does not establish profitability.
There are also unavoidable physical costs. Halter must manufacture equipment, handle installations, provide support, and replace malfunctioning hardware.
The USDA Natural Resources Conservation Service has highlighted connectivity problems, training requirements, and equipment maintenance as limitations of virtual fencing systems.
On animal welfare, a May 2026 study published in Animal found no evidence of increased stress among dairy cows using Halter during the training and observation periods studied. That is encouraging evidence, although it does not cover every operating environment.
Halter currently looks like a company increasing its commercial scale faster than its workforce. Its group-level margins and cash consumption remain undisclosed, which makes profitability the biggest financial unknown in the valuation.
How much revenue does Halter need to justify $2 billion?
Halter would need approximately $133 million to $200 million in annual revenue to trade at 15 to 10 times sales, a range that could be defensible for a fast-growing subscription business.
Those are illustrative multiples, not established valuation standards for companies selling livestock hardware and software.
At a $7 monthly subscription price, reaching $150 million in annualized revenue would require approximately 1.79 million paying collars.
Reaching $200 million would require roughly 2.38 million.
Compared with Halter's 1.5 million reported collars, these targets no longer look particularly distant in deployment terms.
But the calculation depends on actual realized revenue, customer retention, and the profitability of the subscription model.
| Annual revenue | Paying collars at $7/month | Multiple at $2B valuation |
|---|---|---|
| $80M | 952,381 | 25.0× |
| $100M | 1.19M | 20.0× |
| $125M | 1.49M | 16.0× |
| $150M | 1.79M | 13.3× |
| $175M | 2.08M | 11.4× |
| $200M | 2.38M | 10.0× |
| $250M | 2.98M | 8.0× |
| $300M | 3.57M | 6.7× |

In our document detailing everything you need to know about agritech, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Could Halter eventually be worth $5 billion?
Halter could realistically reach a $5 billion valuation if it grows to several million paying collars while maintaining strong subscription revenue and improving its margins.
At five million paying animals and $7 per month, Halter would generate approximately $420 million in annualized subscription revenue. What has to happen for paying animals to reach the millions is covered under growth drivers in our market report about agritech.
A $5 billion valuation would represent 11.9 times that amount.
That would still be a substantial premium for an agricultural technology company, but potentially defensible if Halter had high customer retention, strong margins, and continued growth.
The company also has room to earn more from each customer through animal health monitoring, reproductive analytics, pasture forecasting, and broader farm management software.
Those additional services could make revenue grow faster than collar numbers, although we currently lack the data to quantify their contribution.
Halter's funding plans suggest it also sees opportunities outside its established markets. Its March 2026 announcement identified the United Kingdom, Ireland, and South America as expansion targets.
A $5 billion valuation would require strong execution across several countries and proof that the economics improve with scale.
The market opportunity is there. The financial proof is still catching up.
What could make Halter's $2 billion valuation collapse?
Halter's biggest valuation risk is disappointing subscription economics: too little revenue per collar, costly hardware, or customers who decide the service is not worth renewing.
Imagine Halter's 1.5 million reported collars generate just $5 per month each.
That would produce $90 million in annualized subscription revenue, placing the company at more than 22 times sales.
For a business with manufacturing, equipment replacement, and field service expenses, that is a demanding valuation.
The picture becomes more difficult if large farms negotiate lower prices, customers frequently replace hardware, or sales and installation costs increase during international expansion.
Competition could also limit Halter's pricing power.
Nofence, Gallagher, and Vence give farmers alternatives, particularly when basic virtual fencing is sufficient and Halter's wider management tools offer limited additional value.
Another concern is that farm economics vary enormously. The benefits demonstrated on productive New Zealand dairy farms may be weaker on ranches with cheap labor, good existing fencing, or limited opportunities to improve grazing yields.
We would become much more skeptical of the $2 billion valuation if collar deployments continued rising while realized subscription revenue, gross margins, or customer renewal rates deteriorated.

In our report covering the agritech market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Is Halter really worth $2 billion today?
Yes, Halter's $2 billion valuation looks justified by its current growth and commercial scale, although investors are still paying a premium for profitability that has not been demonstrated at group level.
There are several good reasons to take the valuation seriously.
Halter has reached 1.5 million reported collars across 3,500 farms, expanded rapidly into American ranching, and attracted $220 million in financing from established venture capital investors.
Its subscription model provides a credible path toward hundreds of millions of dollars in annual revenue, while research on New Zealand farms shows the technology can deliver meaningful productivity improvements.
There is also a useful comparison between the company's valuation and its operating growth.
Halter's valuation doubled between June 2025 and March 2026. Over the longer period from June 2025 to August 2026, its reported collar base tripled. Although these timelines differ, the commercial expansion has been substantial enough to support the investment story.
The remaining uncertainty is financial.
Halter has not disclosed sufficiently detailed consolidated revenue, gross margins, retention rates, or cash flow to establish exactly how much profit its growing collar base can produce.
We therefore see $2 billion as a credible valuation for a company with proven customer adoption, strong international expansion, and significant room to grow.
A valuation of $4 billion or $5 billion would require much stronger evidence of recurring revenue and profitable scaling.
For now, Halter has demonstrated that farmers are willing to adopt its technology on a large scale. The next challenge is proving that millions of connected cattle can support a highly profitable global business.
Sources and methodology
To assess whether Halter is really worth $2 billion, we broke the valuation into six questions: how quickly its commercial deployments are growing, how much recurring revenue those deployments could produce, whether farmers earn a meaningful return on the technology, how far its market can expand, how defensible its competitive position is, and whether the business can eventually generate sustainable profits.
We anchored the valuation to Halter's completed March 2026 Series E, then examined reported deployment milestones against the financial evidence available. We checked collar numbers across different reporting periods and distinguished collars sold, live collars, and animals under management where those definitions were disclosed. We also treated New Zealand subsidiary accounts separately from consolidated group revenue, since internal company transactions can distort the comparison.
Our subscription revenue estimates use reported collar deployments and illustrative monthly pricing to calculate annualized revenue potential. We then compare those figures with the $2 billion valuation. These scenarios assume different levels of realized revenue per paying collar; they are our calculations, not reported company revenue, audited forecasts, or confirmed recurring-revenue figures.
We assessed the economic case from the farmer's side as well, drawing on agricultural research, virtual-fencing cost comparisons, and operating studies. Where research covered a small group of high-performing farms or a specific production system, we kept those findings separate from broader claims about the entire livestock industry. We also compared Halter's product economics with competing systems and tested expansion scenarios against official cattle inventory data rather than assuming every animal represents a realistic customer.
We prioritized recent primary disclosures, completed financing records, university and government research, and specialist agricultural reporting with specific financial or operational figures. Our final assessment combines those different findings, with greater weight given to observed deployments, documented transactions, and measurable operating results than to theoretical market size or future valuation scenarios.
Key sources include Halter's official Series E announcement and Goodwin's independent financing confirmation; AgFunderNews on the financing and subscription pricing; Halter's global annual review and US annual review; Farmers Weekly on deployment growth, contracts, and New Zealand financial results; AgFirst and Transform Agri's farm profitability findings; University of Arizona research on virtual-fencing economics and its comparison of competing collar systems; the Journal of Agricultural Economics study on beef-production systems; USDA NASS cattle inventory statistics; USDA NRCS guidance on virtual fencing; Nofence's product information and Merck Animal Health's Vence product information; and Farmers Weekly's reporting on collar reliability and replacement issues.

When you build or invest in the agritech market, you need clarity, not confusion. In our research about farm technology, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us