Why is Peter Thiel investing $220M in Halter?
Everything we know about the AgriTech market, in one place. Get our report whether you build or invest.
Summary
Peter Thiel's Founders Fund is backing Halter because it has a credible chance to become a major technology platform for cattle farming. The company's rapid adoption, improving farm economics, and expansion into the United States suggest a business potentially worth far more than its current $2 billion valuation.
The $220 million was Halter's total Series E funding round, not a personal investment by Peter Thiel. Founders Fund led the financing in March 2026, nearly nine years after first backing the New Zealand startup.
Halter's valuation doubled from $1 billion to $2 billion in just nine months. That increase came as global agrifoodtech funding remained severely depressed, suggesting investors see Halter as an unusual exception in a difficult sector. Halter doubling in value while sector funding stayed low is a contrast we follow every quarter in our agritech market report.
Commercial adoption is accelerating faster than customer acquisition. Between June 2025 and August 2026, Halter's customer base increased 75%, but its collar count tripled to 1.5 million. The average number of collars per customer rose from approximately 250 to 429, pointing toward increasingly substantial deployments.
The product addresses expenses farmers already face. Virtual fencing, remote cattle movement, pasture management, and animal monitoring can reduce labor requirements and improve land utilization. At an illustrative $7 per animal per month, however, a 500-cattle operation would spend $42,000 annually, making measurable economic benefits essential.
Those benefits have started appearing in farm-level research. A study of ten selected high-performing New Zealand dairy farms found an average 13.2% improvement in pretax profit. The results are encouraging, although the selected sample cannot establish what a typical farmer should expect.
Satellite connectivity has opened another growth channel. After launching direct-to-satellite collars in April 2026, Halter reported nearly 400,000 satellite-enabled collars sold globally by June, with more than half going to the United States. Remote ranches that previously required communications infrastructure have become easier to serve.
The American market could change Halter's scale entirely. The company reached approximately 1,000 US ranches by June 2026, while the country had roughly 94 million cattle and calves. Only a portion of that herd is commercially suitable for virtual fencing, but even limited penetration could support a very large subscription business.
At $7 per paying animal per month, 10 million cattle would generate approximately $840 million in annual subscription revenue. Reaching $1 billion would require roughly 12 million paying animals at that price, around eight times Halter's latest reported worldwide collar count.
The potential advantage extends beyond the hardware. As farmers organize grazing schedules, cattle movements, herd monitoring, and pasture records through Halter, replacing the platform may become increasingly inconvenient. Gallagher, Merck, and Nofence remain credible competitors, while animal welfare rules could limit deployment in certain markets.
The biggest unresolved question is global profitability. Halter's New Zealand entity has reported positive earnings, but consolidated revenue, hardware margins, and cash burn remain insufficiently disclosed. Founders Fund is betting that today's rapid collar growth will eventually become a highly profitable recurring-revenue business. The opportunity is substantial, but the $2 billion entry valuation leaves little room for disappointing execution.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

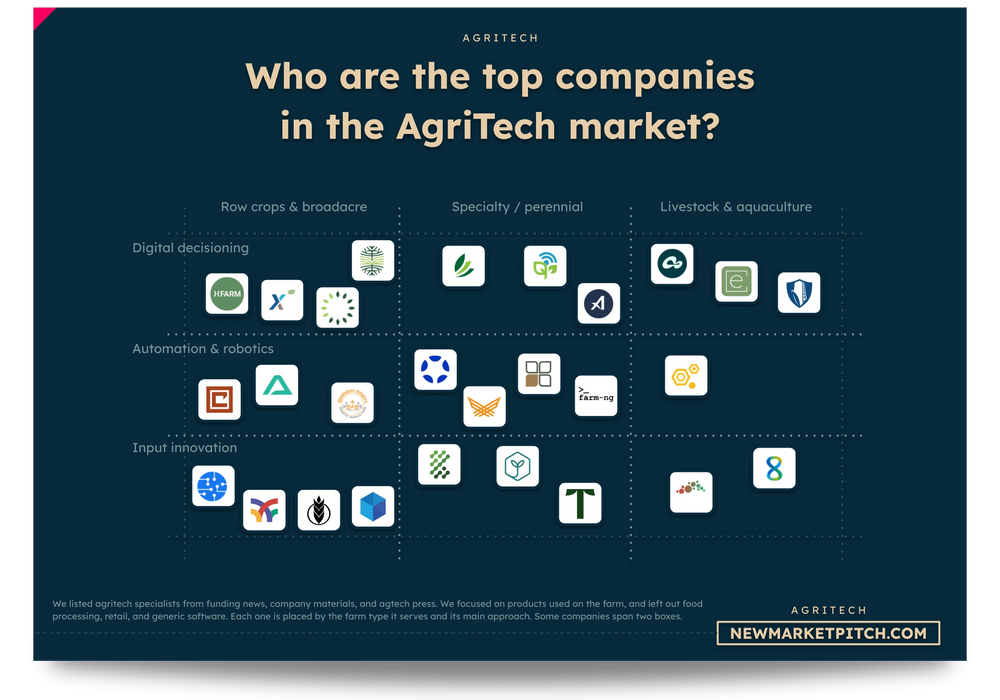
In our report covering the agritech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why is Peter Thiel investing in a company that puts collars on cows?
Peter Thiel's Founders Fund is backing Halter because the New Zealand startup has found a way to automate cattle farming, and its technology is now spreading across thousands of farms.
In March 2026, Halter raised $220 million in Series E funding at a $2 billion valuation. Founders Fund led the round, joined by Blackbird, BOND, Bessemer Venture Partners, DCVC, NewView Capital, Ubiquity Ventures, Promus Ventures, and Icehouse Ventures. Founders Fund, Bessemer and DCVC backing one livestock company shows where agritech money goes, which we trace in our report on agritech.
There is an important distinction in the headline: Peter Thiel did not personally invest a disclosed $220 million. That was the total funding round, and Founders Fund's individual contribution has not been made public.
Halter was founded in 2016 by Craig Piggott, a former Rocket Lab engineer who grew up on a New Zealand dairy farm. The company makes solar-powered smart collars that allow farmers to manage cattle remotely using GPS, wireless connectivity, and software.
Founders Fund had already backed Halter in its Series A round in 2017. This latest investment therefore follows almost a decade of watching the business develop.
The timing is revealing. Halter reached a $1 billion valuation in June 2025, doubled that valuation nine months later, and was reporting 1.5 million collars on cattle worldwide by August 2026.
According to Halter's funding announcement, Founders Fund partner Amin Mirzadegan sees an opportunity to bring software, sensors, and AI into an industry that has historically been difficult to digitize.
The attraction is easy to understand. Farmers already spend money on fences, labor, animal monitoring, and pasture management. Halter is trying to bring much of that work into one paid platform.
The harder question is whether enough farmers will keep paying for it to justify a multibillion-dollar business.
How does Halter actually work on a cattle farm?
Halter lets farmers move cattle, create virtual fences, and monitor their herds from a smartphone, often without installing physical fences or personally moving the animals.
Farmers attach a solar-powered GPS collar to each animal. Using Halter's app, they can draw virtual grazing boundaries on a map and decide where cattle should move throughout the day.
When a cow approaches a virtual boundary, its collar produces an audio warning. If the animal continues moving in the wrong direction, the collar can deliver a controlled electrical stimulus. Over time, cattle learn to respond to the audio cues. Collars that cattle learn to obey are the kind of technology we sort into working, being tested or still on paper in our market report about agritech.
The technology also allows farmers to shift herds between grazing areas without repeatedly sending workers, vehicles, or dogs across the property.
That becomes useful when managing large areas of pasture. Farmers can divide land into smaller grazing sections, control how long cattle remain in each section, and give previously grazed areas time to recover.
The collars also collect information about individual animals, including movement and behavior that can help identify health problems or reproductive activity.
Halter has been adding more features to the same system. Its Beef Pro product, launched in June 2026, introduced tools for estimating feed demand, measuring grazing intensity, tracking pasture conditions, and recording grazing activity.
For a rancher, the practical benefit is having livestock movement, pasture planning, and animal monitoring available in one place.

Our research about farm technology gets updated several times a month, so you always get the latest view of where things stand.
Is Halter really growing that fast today?
Halter is growing exceptionally fast: its reported customer base increased 75% and its cattle collar count tripled over roughly one year.
An August 2026 report by Farmers Weekly, based on Halter's financial disclosures and company figures, provides a more useful comparison than the earlier funding announcements.
In June 2025, Halter had approximately 2,000 farms and 500,000 collars. By August 2026, it was serving approximately 3,500 farms and ranches worldwide, with 1.5 million collars on cattle.
That means customer numbers rose 75%, while the number of collars increased 200%.
The number of collars per customer also climbed from approximately 250 to 429. Because the figures come from company-wide snapshots, we cannot tell precisely how much of that change came from larger customers, existing-farm expansion, or differences in reporting. Still, the gap between collar growth and customer growth is striking.
The company also reported more than 500,000 collars signed up during the April–June 2026 period alone.
That is approximately as many collars as Halter had across its entire customer base in June 2025.
Its workforce expanded from 255 to 535 people over the same broad period, an increase of approximately 110%.
Halter is scaling both its commercial activity and its operations at an unusually rapid pace.
More importantly, Halter's growth is increasingly coming from outside its original New Zealand dairy market. It now sells to beef ranchers in the United States and Australia, where the same technology can solve rather different farming problems.
| Metric | Earlier reported figure | Latest reported figure | Change |
|---|---|---|---|
| Farms and ranches | 2,000 | 3,500 | +75% |
| Collars on cattle | 500,000 | 1.5 million | +200% |
| Collars per customer | 250 | 429 | +71% |
| Global employees | 255 | 535 | +110% |
| Company valuation | $1B | $2B | +100% |
| Latest funding round | $100M | $220M | +120% |
| US operating states | 3 in 2024 | More than half of US states in 2026 | Major expansion |
| US customers | Early commercial rollout in 2024 | Approximately 1,000 ranches by June 2026 | Large new market |
The figures cover different reporting windows, with the main farm, collar, and employment comparisons drawn from Farmers Weekly's August 2026 report. The valuation and funding figures refer to the June 2025 and March 2026 rounds.
Why did Halter double its valuation in nine months?
Halter's valuation doubled because investors became more confident that its smart-collar business could work across major livestock markets, even as agricultural technology funding remained difficult.
In June 2025, BOND led a $100 million investment valuing Halter at $1 billion. Founders Fund then led its $220 million Series E in March 2026 at $2 billion.
That is a dramatic increase for an agricultural technology company.
According to AgFunder's 2026 analysis, global agrifoodtech investment had fallen more than 70% from its 2021 peak. The firm also estimated that only around ten agritech companies had ever achieved a valuation of at least $2 billion, with several subsequently failing.
Halter was attracting large checks in a sector where investors had become much more careful.
Its American expansion helps explain why. The company launched commercially in the United States in 2024, reached 22 states by the end of 2025, and had entered more than half of US states by June 2026.
That progression changed Halter's potential scale. New Zealand has a relatively small livestock market, while the United States has tens of millions of cattle.
There is also a difference between investing in technology that farmers find interesting and investing in equipment they use to run their farms every day.
Blackbird, an existing Halter investor, reported seven consecutive months without customer churn in its March 2026 investment commentary.
That's an unusually strong retention claim, although Halter has not released the full customer cohort data needed to determine whether it applies consistently across its international markets.
The valuation doubled because investors were willing to pay far more for Halter's future growth. Whether that decision was financially justified depends on the revenue and margins the company eventually achieves.

In our market report about farm technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
How much money does Halter actually make?
Halter is already generating substantial revenue, and its New Zealand business reported a profit, but the company has not disclosed enough consolidated financial information to establish how profitable the whole group is.
In August 2026, Farmers Weekly reported financial results from Halter's New Zealand operation.
The entity generated NZ$98.1 million in revenue during the nine months ending December 2025, compared with NZ$71 million during the preceding twelve-month financial year.
That comparison needs care because the reporting periods are different. The shorter period nevertheless produced approximately 38% more revenue than the previous full year.
On a simple annualized basis, the nine-month figure would represent about NZ$130.8 million. That calculation assumes the same average revenue pace continues and should not be mistaken for a reported full-year result.
The New Zealand entity also recorded NZ$2.6 million in net profit during those nine months.
But roughly half its revenue came from subscription and installment income, while the rest was associated with services performed for Halter's US operations.
These internal group transactions make the subsidiary's revenue unsuitable as a direct measure of Halter's consolidated global sales.
The broader company's finances remain less transparent. We still lack a complete public breakdown of worldwide revenue, hardware gross margins, cash burn, and recurring subscription income.
Still, the new disclosures tell us something useful: Halter now has a sizable operating business, with at least one major entity reporting positive net earnings.
Investors are paying for future growth, but they are backing a business that already has meaningful commercial revenue.
Why are farmers willing to pay Halter every month?
Farmers pay Halter because it can reduce time spent moving cattle, make grazing more productive, and replace some of the work traditionally done with physical fences.
Halter's business model generally combines subscription payments with equipment and connectivity infrastructure.
An April 2025 pricing comparison published by DTN put Halter's American subscription below $7 per animal per month, with initial infrastructure starting around $4,500. Per-animal fees on top of equipment are one of the business models we check for margins in our report covering the agritech market.
Pricing can vary by country, herd size, services, and contract terms, so that figure should be treated as an example rather than a universal tariff.
At $7 per month, a farmer managing 500 cattle would pay approximately $42,000 annually.
That sounds expensive until we consider what the farmer might gain.
A large ranch may spend substantial time and money moving animals, maintaining fences, managing pasture, and checking cattle spread across difficult terrain.
Halter also offers a way to change grazing boundaries frequently without rebuilding physical infrastructure. That flexibility can improve how much pasture cattle actually consume.
In its June 2026 Beef Pro announcement, Halter estimated that every 1% improvement in forage utilization could generate approximately $5,000 annually on a 2,500-acre ranch with 500 cattle.
Using that particular scenario, an 8.4-percentage-point improvement would theoretically offset the $42,000 subscription through additional forage value.
The calculation is illustrative, and Halter's estimate should not be confused with an independently established return for every ranch.
But where pasture management is a major constraint, the economics are appealing. Better grazing, fewer hours of manual work, and improved animal oversight can produce benefits simultaneously.

In our document detailing everything you need to know about agritech, you will always find fresh funding data, taken straight from our own verified funding database.
Does Halter actually make farms more profitable?
Halter has demonstrated meaningful productivity improvements on selected farms, including a 13.2% average increase in pretax profit, although those results should not be treated as typical for every customer.
In October 2025, agricultural consultants AgFirst and Transform Agri published research covering ten high-performing New Zealand dairy farms using Halter.
The farms recorded an average 8.9% increase in pasture harvested and a 9.5% increase in milk solids produced per hectare.
Six-week in-calf rates improved by 4.7 percentage points, while empty rates fell by 2.1 percentage points.
Together, those improvements translated into an average 13.2% increase in profit before tax, according to the study. One farm reported a gain of 37%.
The benefits reinforce each other.
More efficient grazing can increase milk production from existing land. Better reproductive performance can reduce breeding inefficiencies. Less time spent shifting cattle can free workers for other tasks.
The technology becomes especially valuable when farmers adjust their operating methods around it.
There are also newer examples from beef farming. In August 2026, New Zealand's Greenhill Farming reported using Halter to manage more than 600 Friesian bulls.
The farm moved toward daily cattle shifts instead of moving animals every second or third day and divided its operations into 25 individually managed areas.
Greenhill said it was targeting 360 kilograms of carcass weight per hectare, compared with a three-year average of 280 kilograms. That would represent a roughly 29% improvement if achieved.
That remains a target rather than an audited result, and the farm's management changes may explain part of the improvement.
The original dairy study also covered only ten deliberately selected high-performing operations.
Halter has shown that better farm economics are achievable. It has yet to establish exactly how often comparable improvements occur across ordinary farms in different countries.
Can Halter become a billion-dollar revenue business?
Halter could eventually generate more than $1 billion in annual revenue if it reaches roughly 12 million to 17 million paying cattle at monthly subscription prices of $5–$7, but that would require a major expansion beyond its current scale.
The opportunity comes from the enormous number of cattle managed around the world.
The global herd is commonly estimated at approximately 1.5 billion animals. However, many cattle are raised indoors, kept in feedlots, or managed in places where virtual fencing would offer limited benefits. Many cattle never graze outdoors, so we size the market ourselves in our agritech report.
Halter's most relevant market is pasture-based cattle farming, especially operations where land management, labor, and animal monitoring are expensive.
The United States illustrates the potential. USDA reported approximately 94.2 million cattle and calves in July 2026, including 28.5 million beef cows and 9.65 million dairy cows.
Halter's recently reported 1.5 million collars worldwide are still a small fraction of that American inventory alone.
Of course, the worldwide installed base cannot be directly compared with one country's total cattle population to calculate market share.
The useful question is how many animals could realistically become paying subscribers.
At $7 per animal per month, 5 million paying cattle would generate $420 million annually. Ten million would produce $840 million.
These calculations assume each animal pays for twelve months. They exclude discounts, hardware revenue, churn, and other adjustments.
Halter could become a very large business without approaching anything close to universal cattle adoption.
| Paying cattle | Revenue at $5/month | Revenue at $7/month | Revenue at $10/month |
|---|---|---|---|
| 1 million | $60M | $84M | $120M |
| 2 million | $120M | $168M | $240M |
| 3 million | $180M | $252M | $360M |
| 5 million | $300M | $420M | $600M |
| 10 million | $600M | $840M | $1.2B |
| 15 million | $900M | $1.26B | $1.8B |
| 20 million | $1.2B | $1.68B | $2.4B |
| 30 million | $1.8B | $2.52B | $3.6B |
These are hypothetical subscription revenue scenarios, not company forecasts.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the agritech market, we look at what broke startups before you, so you don't repeat it.
Has satellite connectivity changed Halter's business?
Halter's satellite collars have made the technology much more attractive to remote ranchers, opening areas where unreliable communications previously made virtual fencing difficult or impractical.
In April 2026, Halter launched direct-to-satellite connectivity using Starlink-based infrastructure.
In the United States, it worked with T-Mobile. In New Zealand, the satellite service involved One NZ.
Halter's satellite-enabled collars can operate without dedicated on-property communication towers where the service has a suitable view of the sky.
The commercial response was unusually quick.
By June 2026, Halter reported selling nearly 400,000 satellite-enabled collars globally, with more than half going to the United States.
Those sales came within roughly two months of the announcement. They do not prove every collar had already been activated, but the initial demand was substantial.
Halter also estimated that satellite technology could increase its addressable New Zealand beef-farming market by at least 20%.
American and Australian cattle ranches can cover far larger and more remote areas than a typical intensive dairy farm.
Removing communications towers reduces one of the practical obstacles to deploying Halter on those properties.
Satellite connectivity makes Halter's expansion plans more credible, particularly in the American West and other remote grazing regions.
Can Halter take over America's cattle ranches?
Halter has made an impressive start in the United States, but American ranching is far too large and varied for its early adoption to establish market dominance.
The company's American business started in 2024 and had reached approximately 1,000 ranches by June 2026.
Halter also reported selling more than 250,000 collars in the country.
That gives an average of around 250 collars sold per reported ranch, although the figure does not necessarily represent the number actively deployed on each property.
American expansion is important because the country combines a large beef industry with ranches that can cover thousands of acres.
But the market is not uniform.
A Montana ranch dealing with extensive grazing land faces different problems from a Texas cattle operation or a dairy farm in Wisconsin.
Halter's virtual fences may deliver substantial benefits for rotational grazing, while providing less value to cattle operations whose animals are largely confined.
The company has already shown that its product can cross borders. Its broader international rollout also includes Australia, with announced plans for the United Kingdom, Ireland, Canada, and parts of South America.
However, international expansion creates new demands for local support, livestock training, product reliability, and regulatory compliance.
The American opportunity is still in its early stages. Halter's challenge now is to turn rapid geographical expansion into a large, consistently paying customer base.

In our research about farm technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Can Merck, Gallagher or Nofence beat Halter?
Halter currently looks like one of the strongest virtual fencing companies, but Merck, Gallagher, and Nofence offer credible alternatives, and there is no reliable public market-share ranking that proves Halter's dominance.
The competition includes companies with very different advantages.
Gallagher has decades of experience selling livestock fencing equipment and already maintains relationships with farmers and agricultural distributors. How established fencing makers with farmer relationships stack up against startups is mapped in our agritech market report.
Merck Animal Health entered virtual fencing through its acquisition of Vence in 2022, giving it an established product alongside its animal health operations.
Nofence, founded in Norway, sells connected virtual fencing systems for cattle, sheep, and goats. Its wider species coverage could be attractive in farming markets where cattle are only part of the operation.
Halter has built its position through integrated virtual herding, animal monitoring, pasture-management software, and rapid expansion into major beef markets.
Its competitive strength also depends on experience. The company has developed several generations of hardware while managing increasingly large deployments across different farming conditions.
That operational history should help improve reliability and software performance.
But competitors can adopt better communications technology, develop new analytics tools, and use their existing distribution networks to reach customers.
The comparison should focus on retention, customer economics, reliability, and total operating costs rather than simply counting product features.
For now, Halter has a strong claim to being a category leader. But with several well-financed competitors pursuing the same farmers, it would be premature to assume the market is already won.
Could farmers eventually become dependent on Halter?
Halter could become difficult for farmers to replace once its software manages their fences, herd movements, animal monitoring, and grazing records every day.
A basic virtual fencing product can be compared largely on collar pricing and reliability.
Halter is moving toward a broader role.
Its Beef Pro service adds feed-demand planning, satellite forage information, grazing intensity maps, behavioral monitoring, and automated records.
That means the system can increasingly influence how farmers decide where to move cattle, how much grass remains available, and when grazing areas need to recover.
As previously seen, the company has also been adding collars faster than customers, which is consistent with larger deployments or growth within existing operations, although the public figures do not establish the precise cause.
There is a potential commercial advantage here.
Replacing a collar supplier may be relatively straightforward. Replacing the software used to organize an entire grazing operation could be more disruptive.
That's especially relevant when farmers have spent years training animals to use a system and building their operating routines around its information.
Still, Halter has not disclosed detailed net revenue retention or customer switching data.
We cannot confidently measure how much pricing power this creates.
But if its newer software tools gain widespread adoption, Halter could become increasingly embedded in how farms operate. That would make the business much harder for competitors to displace.

If you build or invest in the agritech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Could animal welfare rules slow Halter's growth?
Animal welfare regulations could restrict Halter in some markets, although published research now provides credible evidence that the technology can be used without worsening cattle welfare under properly controlled conditions.
The issue is the electrical stimulus used by virtual fencing collars when cattle ignore earlier warnings. Animal welfare rules that can slow a whole category are among the less obvious risks we rate by likelihood in our agritech market report.
An experiment published in the journal Animal in May 2026 studied 160 dairy cows over 44 days, comparing Halter's virtual fencing and herding system with conventional electric fencing and human-operated herding.
Researchers found no significant differences in milk production, cortisol concentrations, live weight, or body condition between the groups.
The study included nearly 2,500 milk samples used to assess physiological stress.
However, the researchers also observed that cows in the virtual fencing group spent approximately 5% less time grazing.
Their overall conclusion was that welfare remained comparable under the conditions tested, with careful training and safeguards.
That provides useful scientific support for Halter, but it does not establish that every possible use is harmless.
The RSPCA has raised concerns about electric stimuli, collar fit, individual differences in cattle learning, and the risks of poor management.
Australian regulatory frameworks also impose conditions on how virtual fencing systems can be used.
In New South Wales, for example, regulated uses include training and monitoring requirements, while virtual boundaries cannot simply replace all physical perimeter fencing.
These rules can increase deployment costs and limit some applications.
Halter should still have a substantial market where farmers can use the technology responsibly, but animal welfare standards will influence how quickly the company expands into new countries.
Is Halter really worth $2 billion today?
Halter's $2 billion valuation is expensive relative to the financial information available, although its rapid growth makes the price more defensible than it would be for a conventional agricultural equipment supplier.
The main difficulty is that Halter's consolidated global revenue and margins are still not fully public.
Private-market estimates have placed annual revenue around $70 million to $100 million, but these figures cannot be treated as audited consolidated revenue.
The recently reported results from Halter's New Zealand operation provide an additional financial reference point, though the subsidiary's internal service revenue means we cannot simply annualize it into a group revenue figure.
At $100 million in consolidated annual revenue, a $2 billion valuation would represent 20 times sales.
That's a steep multiple for a business that manufactures physical products, operates field infrastructure, and provides customer support.
But the valuation changes dramatically if Halter keeps growing.
At $400 million in annual revenue, the same valuation would represent five times sales. At $800 million, it would represent only 2.5 times.
The question is how much of today's valuation can eventually be supported by revenue that produces attractive margins and cash flow.
Manufacturing costs, damaged or replaced collars, customer acquisition, connectivity expenses, and international support could absorb a considerable portion of subscription income.
Investors also need to consider whether software upgrades such as Beef Pro can increase revenue per animal without proportionately increasing costs.
For now, Halter's valuation makes sense as a high-growth investment. Calling the company cheaply valued would be a stretch.

In our document detailing everything you need to know about agritech, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
What could make Peter Thiel's Halter investment go wrong?
Founders Fund's investment in Halter could disappoint if cattle adoption keeps rising but the company struggles to turn those subscriptions into sufficiently profitable recurring revenue.
The clearest risk is customer economics.
A farmer paying tens of thousands of dollars annually needs to see a reliable return. Better grazing results on selected farms are encouraging, but outcomes will vary depending on land, herd size, existing infrastructure, climate, and management.
The second risk is competition.
Gallagher, Merck, Nofence, and emerging virtual fencing providers can pressure pricing or offer comparable features. Halter will need to keep improving its product to maintain a premium.
Hardware presents another challenge. A technology platform managing livestock across millions of acres must handle device failures, difficult weather, inconsistent connectivity, and ongoing maintenance.
The company's rapid hiring also creates financial pressure. Its workforce more than doubled over approximately a year, increasing the importance of keeping revenue growth ahead of operating costs.
Finally, the valuation leaves little room for disappointing growth.
Halter has attracted the kind of valuation generally associated with businesses expected to become far larger than they are today.
If the company eventually reaches only a few hundred million dollars in annual revenue with modest margins, investors may struggle to earn attractive returns from a $2 billion entry valuation.
The biggest unanswered question is profitability at global scale. Halter's commercial progress is already impressive, but the next stage needs to prove that the business becomes more profitable as it grows.
Why is Peter Thiel investing $220 million in Halter?
Peter Thiel's Founders Fund is backing Halter because it has a credible chance to become a major technology platform for cattle farming, and its recent growth suggests the opportunity could be much larger than smart collars alone.
The $220 million represents Halter's total Series E financing, led by Founders Fund, rather than a disclosed personal investment by Thiel.
The investment rests on unusually strong commercial evidence for an agricultural technology startup.
Halter has expanded from approximately 500,000 to 1.5 million collars on cattle in a little over a year. Its customer base has grown substantially, and its American business has reached hundreds of thousands of collars despite launching only in 2024.
The company's financial disclosures also show a meaningful operating business rather than a product supported entirely by venture funding.
Farmers have reasons to pay for the technology. Independent consultants studying ten selected New Zealand dairy farms found average pretax profit improvements of 13.2%, while newer products are extending Halter's role in pasture management and animal monitoring.
There are important limits to the evidence. We still lack comprehensive group-level profitability figures, competitors are active, and the returns achieved by successful farms cannot be assumed across the entire cattle industry.
Still, the investment thesis is now quite clear.
At approximately 1.5 million collars on cattle, Halter has proved it can reach substantial commercial scale. If that grows toward 10 million paying animals, the company could approach $1 billion in annual subscription revenue at current illustrative pricing.
Whether it reaches that scale profitably will determine if today's $2 billion valuation was justified.
Our judgment is that Founders Fund has identified one of the more compelling agricultural technology businesses currently operating. Halter has real adoption, measurable customer benefits, and a huge market ahead of it.
The price is aggressive, but the opportunity is real. If Halter becomes an essential part of how large farms manage cattle, the investment could prove extremely valuable.
Our methodology
To investigate why Peter Thiel's Founders Fund is backing Halter at a $2 billion valuation, we examined the investment as a business and economic question rather than relying on the excitement surrounding agricultural automation. We broke the thesis into its main components: commercial adoption, customer economics, farm productivity, revenue quality, technological advantages, competition, addressable market, and valuation risk.
For each dimension, we collected the most recent measurable developments available, compared them with earlier reporting periods, and assessed what they actually establish about Halter's business. We used company announcements for financing and adoption figures, financial reporting for operating performance, agricultural research for productivity outcomes, and government statistics for market scale. We also examined competitors and regulatory constraints to test how defensible Halter's position might become.
Our analysis places particular weight on changes over time. The relationship between customer growth and collar deployment, the progression of financing valuations, international expansion, and the introduction of satellite connectivity provide a more informative picture when assessed together than when viewed as isolated milestones. We distinguished reported sales, subscriptions, active deployments, and hypothetical revenue wherever those measures could produce different interpretations.
We also reconstructed the economics from the farmer's perspective. Published pricing indications, operating-cost considerations, pasture-productivity research, and illustrative forage-utilization calculations helped us evaluate whether the subscription model addresses a sufficiently valuable problem. Research based on selected high-performing farms was interpreted within the limits of its sample rather than extrapolated across the entire agricultural market.
For the investment analysis, we calculated subscription-revenue scenarios using different numbers of paying cattle and monthly prices. We then compared those scenarios with Halter's reported adoption and valuation to assess the scale of growth investors are effectively underwriting. These calculations are our own analytical estimates, not Halter forecasts. We kept subsidiary-level financial results separate from consolidated revenue estimates because internal group transactions can materially distort the comparison.
The final judgment comes from aggregating the evidence across these dimensions. We gave greater weight to observable adoption, disclosed financial performance, and documented farm outcomes than to promotional claims or speculative market projections. This allowed us to distinguish the parts of the investment thesis already supported by commercial results from those still dependent on future adoption, margins, customer retention, and execution.
Key funding and commercial-growth sources include Halter's Series E funding announcement, its earlier Series D announcement, Farmers Weekly's reporting on company growth and financial disclosures, Halter's US year-in-review figures, and AgFunderNews' analysis of the financing and agritech investment environment.
For product economics and market potential, we used Halter's Beef Pro announcement, its satellite-connectivity announcement, the Australian Beef Pro launch, Farmers Weekly's reporting on the AgFirst and Transform Agri productivity study, Country-Wide's interview with the researchers, DTN's virtual-fencing pricing comparison, and USDA's July 2026 cattle inventory.
To assess competition and adoption constraints, we reviewed Merck's acquisition of Vence, Gallagher's eShepherd platform, and Nofence's virtual-fencing technology. For animal welfare and regulation, we used peer-reviewed research published in Animal, RSPCA Australia's assessment of virtual fencing, and New South Wales' official regulatory guidance.

In our report covering the agritech market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us