What are the latest funding trends in military drones?
Building a startup or looking for your next investment in military drones? Our report gives you the full picture.
Summary
Military drone startups raised at least $15.5B across 61 deals this year to date. Anduril raised the most, with $5.0B. The funding boom is real, and a handful of huge rounds still account for much of the money.
Compared with the same period last year, funding rose 240% and the number of deals climbed 42%. This is a bigger market by both measures, although the dollar total is growing much faster.
The current partial year has also passed the entire previous year in funding and deal count. There is no need to guess how the remaining weeks will go to see the change.
Investors are writing much larger checks. Once we remove rounds above $100M, the remaining disclosed capital actually slips compared with the same point last year.
That shift shows up in the stages. Later-stage rounds now make up 46% of deals with a named stage, up from 32% in the corresponding period last year.
Attack aircraft still draw the biggest share of funding dollars. But surveillance drones now lead by number of deals, and software that controls military aircraft is attracting major checks too.
Drone interceptors and loitering munitions have clearer buyers today. NATO has opened a quicker purchasing route for counter-drone equipment, while Germany is placing orders with loitering-munition makers.
Europe now accounts for 51% of military drone deals. North America still brings in 62% of the disclosed capital, so the two regions lead by different measures.
There is a practical reason for the interest. The United States is buying and testing cheaper combat drones, Britain has announced a large drone program, and NATO is trying to speed up procurement across its members.
Military drone funding is moving toward larger, repeat rounds for suppliers that can build and deliver aircraft. New companies still raise money, but winning a giant check now increasingly means proving that a product works beyond the test range.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the military drone market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the military drones market over the last years
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our military drones market report.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| Arcanus Aerial Systems | ISR Drones | November 2026 | Series A | $27M+ | Integrates and manufactures allied military UAV systems for reconnaissance and combat-support missions in Canada. | North America | Not disclosed | Canada | |
| UFORCE | Strike Drones | November 2026 | Series A | $700M | Combat-tested autonomous military drone systems | Europe | Valor Equity Partners, UK National Wealth Fund | United Kingdom | |
| SE3 | Drone Mission & Control Systems | November 2026 | Series A | $30M | Develops onboard spatial AI and natural-language mission software that controls military drones even when GPS is denied. | Europe | Accel | Germany | |
| Shield AI | Drone Mission & Control Systems | November 2026 | Series D+ | $1.0B | AI autonomy software and military drones | North America | Disruptive, Innovation X Capital | United States | |
| Skydio | ISR Drones | November 2026 | Series D+ | $255M | Autonomous drones for defense and inspection | North America | Axon Enterprise | United States | |
| Arcanus Aerial Systems | ISR Drones | October 2026 | Unknown | $500K | Integrates and manufactures allied military UAV systems for reconnaissance and combat-support missions in Canada. | North America | Not disclosed | Canada | |
| Beyond Vision | ISR Drones | October 2026 | Series A | $32M+ | Manufactures AI-enabled military drones and ISR unmanned platforms. | Europe | Índico Capital Partners, Lince Capital | Portugal | |
| Buntar Aerospace | ISR Drones | October 2026 | Unknown | $16M | Reconnaissance drones and battlefield software | Europe | Freedom Fund | Ukraine | |
| Certo Aerospace | Cargo & Logistics Drones | October 2026 | Unknown | ~$6.6M | Builds the CAPSTONE heavy-lift autonomous VTOL aircraft for military logistics and support missions. | Europe | Not disclosed | United Kingdom | |
| Monopulse | ISR Drones | October 2026 | Unknown | $2.3M+ | Electronic-warfare-resistant reconnaissance drones | Europe | Coinvest Capital | Lithuania | |
| Fortem Technologies | Interceptor Drones | September 2026 | Series B | $50M | Radar-guided autonomous drone interception systems | North America | Lockheed Martin Ventures | United States | |
| Occam Industries | Drone Mission & Control Systems | September 2026 | Growth Equity | $4.2M | Autonomous control software for military drones | Europe | North Ventures | United Kingdom | |
| DOD Solution | Drone Mission & Control Systems | September 2026 | Seed | $2.1M | Onboard autonomy for unmanned systems | Europe | Not disclosed | Ukraine | |
| TEKEVER | ISR Drones | September 2026 | Series D+ | ~$580M | AI-powered military surveillance drones | Europe | UC Investments, Baillie Gifford | Portugal | |
| AD Systems | ISR Drones | September 2026 | Series A | ~$9.4M | Stealth military reconnaissance drone manufacturing | Asia-Pacific | LB Investment | South Korea | |
| Agilis Air | ISR Drones | September 2026 | Seed | $1.4M | Autonomous drones for defense missions | North America | Not disclosed | United States | |
| Mach Industries | Strike Drones | September 2026 | Series C | $600M | Military attack drones and aerial interceptors | North America | Not disclosed | United States | |
| XTEND | Drone Mission & Control Systems | September 2026 | Growth Equity | $68M | AI-assisted military reconnaissance and tactical drones | North America | Not disclosed | United States | |
| AITAN | Drone Mission & Control Systems | September 2026 | Series A | $41M | Edge-AI autonomous defense robotic systems | North America | Deep33, Dell Technologies Capital | United States | |
| PDW | ISR Drones | September 2026 | Growth Equity | $52M | American-made military unmanned aircraft systems | North America | Not disclosed | United States | |
| Airbility | Interceptor Drones | September 2026 | Series A | $4.7M | High-speed eVTOL counter-drone aircraft | Asia-Pacific | Sazze Partners | South Korea | |
| Swarm Defense Technologies | Swarm & Collaborative Drones | September 2026 | Unknown | $2M | Low-cost coordinated military drone swarms | Asia-Pacific | Not disclosed | India | |
| M-Fly | Drone Mission & Control Systems | September 2026 | Unknown | Undisclosed | Laser guidance and UAV gimbals | Europe | MITS Capital | Ukraine | |
| Easy Aerial | ISR Drones | August 2026 | Series B | $20M | Autonomous tethered surveillance drone systems | North America | Insight Partners | United States | |
| Mara | Interceptor Drones | August 2026 | Seed | $7M | Autonomous kinetic drone interception | North America | Khosla Ventures | United States | |
| Neros Technologies | Strike Drones | August 2026 | Series C | $250M | FPV strike and interceptor drones | North America | Sequoia Capital, American Strategic Technology Fund | United States | |
| Cambridge Aerospace | Interceptor Drones | August 2026 | Series C | $300M | Low-cost drone and missile interceptors | Europe | DFJ Growth | United Kingdom | |
| Helsing | Loitering Munitions | July 2026 | Series D+ | $1.8B | AI-powered autonomous defense systems | Europe | Dragoneer Investment Group, Lightspeed Venture Partners | Germany | |
| Quantum Systems | ISR Drones | July 2026 | Series D+ | $1.2B | AI-powered military unmanned aerial systems | Europe | Blackstone, Noteus, Airbus Ventures, Advent International | Germany | |
| Six Robotics | Swarm & Collaborative Drones | June 2026 | Seed | ~$14M | Swarm autonomy software for unmanned systems | Europe | DTCP | Norway | |
| STARK Defence | Loitering Munitions | June 2026 | Series C | $550M | Autonomous military drones and weapons | Europe | Sequoia Capital, Founders Fund | Germany | |
| Acodyne | Cargo & Logistics Drones | June 2026 | Seed | Undisclosed | Autonomous military-use VTOL cargo aircraft | Europe | Gungnir Capital, PSV Hafnium | Denmark | |
| PDKINEMATICS | Drone Mission & Control Systems | June 2026 | Seed | $2.2M | Precision-guidance kits for UAV munitions | Europe | Coinvest Capital, Iron Wolf Capital | Lithuania | |
| Alta Ares | Interceptor Drones | June 2026 | Series A | $57M | AI-powered battlefield air defense | Europe | Air Street Capital | France | |
| Mach Industries | Strike Drones | June 2026 | Series C | $300M | Military attack drones and aerial interceptors | North America | Infinite Capital, Ribbit Capital | United States | |
| Askari Defense | Interceptor Drones | May 2026 | Seed | $11M | Hand-launched autonomous drone interceptors | North America | Builders VC | United States | |
| Anduril | Strike Drones | May 2026 | Series D+ | $5.0B | Autonomous defence systems and weapons | North America | Thrive Capital, Andreessen Horowitz | United States | |
| Darkhive | ISR Drones | May 2026 | Series B | $30M | Autonomous tactical reconnaissance drones | North America | RTX Ventures | United States | |
| Apollyon Dynamics | Strike Drones | May 2026 | Seed | ~$480K | Military drones for defense operations | Asia-Pacific | Naandi Ventures | India | |
| Firestorm Labs | Strike Drones | April 2026 | Series B | $82M | Expeditionary drone manufacturing and UAS | North America | Washington Harbour Partners | United States | |
| Skydio | ISR Drones | April 2026 | Series D+ | $110M | Autonomous drones for defense and inspection | North America | Not disclosed | United States | |
| Swarm Defense Technologies | Swarm & Collaborative Drones | April 2026 | Unknown | $1.4M | Low-cost coordinated military drone swarms | Asia-Pacific | Not disclosed | India | |
| Cambridge Aerospace | Interceptor Drones | April 2026 | Series B | $200M | Low-cost drone and missile interceptors | Europe | Elad Gil, Spark Capital | United Kingdom | |
| Shield AI | Drone Mission & Control Systems | March 2026 | Series D+ | $1.5B | AI autonomy software and military drones | North America | Advent International, JPMorganChase Strategic Investment Group | United States | |
| PDW | ISR Drones | March 2026 | Series B | $110M+ | American-made military unmanned aircraft systems | North America | Ondas Holdings | United States | |
| Buntar Aerospace | ISR Drones | March 2026 | Seed | $10M | Reconnaissance drones and battlefield software | Europe | Axon Enterprise | Ukraine | |
| Swarm Aero | Swarm & Collaborative Drones | March 2026 | Series A | $35M | Large autonomous military aircraft | North America | Two Sigma Ventures, Silent Ventures | United States | |
| Orqa | Strike Drones | March 2026 | Series A | $14M | FPV drones and defence electronics | Europe | Expeditions Fund | Croatia | |
| UFORCE | Strike Drones | March 2026 | Seed | $50M | Combat-tested autonomous military drone systems | Europe | Shield Capital, Lakestar | United Kingdom | |
| FlyFocus | ISR Drones | February 2026 | Seed | $5M | Military UAV design and manufacturing | Europe | ffVC | Poland | |
| TYTAN Technologies | Interceptor Drones | February 2026 | Series A | $33M | AI-powered autonomous drone interceptors | Europe | Armira, NATO Innovation Fund | Germany | |
| MaXon Systems | Interceptor Drones | February 2026 | Seed | Undisclosed | Autonomous interceptor drones for air defense | Europe | Green Flag Ventures | Ukraine | |
| Airlogix | ISR Drones | February 2026 | Seed | $3.3M | Unmanned aerial systems for defense | Europe | bValue Fund | Ukraine | |
| Farsight Vision | Drone Mission & Control Systems | February 2026 | Seed | ~$8.6M | Drone-derived 3D intelligence and mapping | Europe | Axon Enterprise, SmartCap | Estonia | |
| Occam Industries | Drone Mission & Control Systems | February 2026 | Seed | $3.3M | Autonomous control software for military drones | Europe | Presto Tech Horizons | United Kingdom | |
| XTEND | Drone Mission & Control Systems | February 2026 | Growth Equity | $42M | AI-assisted military reconnaissance and tactical drones | North America | Not disclosed | United States | |
| STARK Defence | Loitering Munitions | February 2026 | Unknown | Undisclosed | Autonomous military drones and weapons | Europe | Founders Fund | Germany | |
| Grid Aero | Cargo & Logistics Drones | January 2026 | Series A | $20M | Autonomous cargo aircraft for military missions | North America | Bison Ventures, Geodesic Capital | United States | |
| Twentyfour Industries | ISR Drones | January 2026 | Unknown | $12M | Mass-produced modular military drones | Europe | Not disclosed | Germany | |
| HoverIt | Loitering Munitions | January 2026 | Seed | $500K | Long-range drones for defense missions | Asia-Pacific | Not disclosed | India | |
| Harmattan AI | Drone Mission & Control Systems | January 2026 | Series B | $200M | Autonomous military drones and air defence | Europe | Dassault Aviation | France | |
| Shield AI | Drone Mission & Control Systems | December 2025 | Series D+ | $300M | AI autonomy software and military drones | North America | Not disclosed | United States | |
| Heven AeroTech | ISR Drones | December 2025 | Series B | $100M | Hydrogen-powered long-endurance military drones | North America | IonQ | United States | |
| Quantum Systems | ISR Drones | November 2025 | Series C | ~$209M | AI-powered military unmanned aerial systems | Europe | Balderton Capital | Germany | |
| Thermopylae Aerospace | Interceptor Drones | November 2025 | Seed | $1.6M | Autonomous interceptor drones for counter-UAS | North America | Naval Ravikant | United States | |
| M-Fly | Drone Mission & Control Systems | November 2025 | Seed | $1.4M | Laser guidance and UAV gimbals | Europe | Not disclosed | Ukraine | |
| PDW | ISR Drones | November 2025 | Series B | $35M | American-made military unmanned aircraft systems | North America | Ondas Holdings | United States | |
| Auterion | Drone Mission & Control Systems | November 2025 | Growth Equity | Undisclosed | Autonomy software for military drone fleets | North America | Not disclosed | United States | |
| Neros Technologies | Strike Drones | November 2025 | Series B | $75M | FPV strike and interceptor drones | North America | Sequoia Capital | United States | |
| Vermeer | Drone Mission & Control Systems | October 2025 | Series A | $10M | GPS-independent drone navigation technology | North America | Draper Associates | United States | |
| Fuvex | ISR Drones | October 2025 | Series A | $2M | Long-range drones for infrastructure inspections | Europe | Sodena | Spain | |
| Hoverfly Technologies | ISR Drones | October 2025 | Series B | $20M | Tethered drones for persistent aerial surveillance | North America | Leonardo DRS, Korea Robot Manufacturing | United States | |
| Tycho AI | Drone Mission & Control Systems | October 2025 | Series A | $10M | AI navigation for unmanned vehicles | North America | FirstMark | United States | |
| Orbotix Industries | Swarm & Collaborative Drones | October 2025 | Seed | $7.2M | AI-powered autonomous defense drone systems | Europe | BVVC | Poland | |
| Unmannd | Cargo & Logistics Drones | September 2025 | Seed | $2M | Autonomous UAVs for defense operations | Asia-Pacific | Speciale Invest, Accel | India | |
| Auterion | Drone Mission & Control Systems | September 2025 | Series B | $105M | Autonomy software for military drone fleets | North America | Bessemer Venture Partners | United States | |
| NORDA Dynamics | Drone Mission & Control Systems | September 2025 | Seed | $1M | Autonomous drone navigation for defense | Europe | Varangians | Ukraine | |
| Swarmer | Swarm & Collaborative Drones | September 2025 | Series A | $15M | Autonomous drone swarm control software | Europe | Broadband Capital Investments | Ukraine | |
| Vector | Strike Drones | September 2025 | Series A | $61M | Military drones and warfare services | North America | Pelion Venture Partners, Harpoon Ventures, Point72 Ventures, Lightspeed Venture Partners, Run Ventures, Dauntless Ventures, GSB Backers, Alumni Ventures, Kickstart Fund, Shield Capital, R7, Cambria Group, Stony Lonesome Group | United States | |
| STARK Defence | Loitering Munitions | August 2025 | Unknown | $62M | Autonomous military drones and weapons | Europe | Sequoia Capital | Germany | |
| Grid Aero | Cargo & Logistics Drones | August 2025 | Seed | $6M | Autonomous cargo aircraft for military missions | North America | Calibrate Ventures, Ubiquity Ventures | United States | |
| MaXon Systems | Interceptor Drones | August 2025 | Seed | $300K | Autonomous interceptor drones for air defense | Europe | Freedom Fund | Ukraine | |
| AD Systems | ISR Drones | August 2025 | Series A | $2.1M | Stealth military reconnaissance drone manufacturing | Asia-Pacific | Not disclosed | South Korea | |
| Firestorm Labs | Strike Drones | July 2025 | Series A | $35M | Expeditionary drone manufacturing and UAS | North America | New Enterprise Associates | United States | |
| XTEND | Drone Mission & Control Systems | July 2025 | Series B | $30M | AI-assisted military reconnaissance and tactical drones | North America | Aliya Capital Partners, Protego Ventures | United States | |
| Nordic Air Defence | Interceptor Drones | July 2025 | Seed | $3M | Software-defined low-cost drone interceptors | Europe | Inflection | Sweden | |
| Cambridge Aerospace | Interceptor Drones | July 2025 | Series A | $100M | Low-cost drone and missile interceptors | Europe | Not disclosed | United Kingdom | |
| Thermopylae Aerospace | Interceptor Drones | July 2025 | Seed | $2.5M | Autonomous interceptor drones for counter-UAS | North America | Not disclosed | United States | |
| Raphe mPhibr | ISR Drones | June 2025 | Series B | $100M | Military UAVs and autonomous systems | Asia-Pacific | General Catalyst | India | |
| Helsing | Loitering Munitions | June 2025 | Series D+ | $660M | AI-powered autonomous defense systems | Europe | Prima Materia | Germany | |
| Mach Industries | Strike Drones | June 2025 | Series B | $100M | Military attack drones and aerial interceptors | North America | Khosla Ventures, Bedrock | United States | |
| Anduril | Strike Drones | June 2025 | Series D+ | $2.5B | Autonomous defence systems and weapons | North America | Founders Fund | United States | |
| Lendurai | Drone Mission & Control Systems | June 2025 | Seed | $6.4M | GPS-denied autonomous UAV navigation | Europe | Expeditions Fund, HCVC, Vsquared Ventures | Estonia | |
| Trypillian | Strike Drones | May 2025 | Seed | $5M | Ukrainian military drones and systems | Europe | Brooks Newmark | Ukraine | |
| Alta Ares | Interceptor Drones | May 2025 | Seed | $2.2M | AI-powered battlefield air defense | Europe | Expansion, Starburst Ventures | France | |
| TEKEVER | ISR Drones | May 2025 | Series C | ~$80M | AI-powered military surveillance drones | Europe | Ventura Capital | Portugal | |
| Quantum Systems | ISR Drones | May 2025 | Series C | ~$181M | AI-powered military unmanned aerial systems | Europe | Balderton Capital | Germany | |
| Vermeer | Drone Mission & Control Systems | May 2025 | Unknown | $3.5M | GPS-independent drone navigation technology | North America | Not disclosed | United States | |
| TYTAN Technologies | Interceptor Drones | April 2025 | Seed | $17M | AI-powered autonomous drone interceptors | Europe | OTB Ventures, Visionaries Club | Germany | |
| Theseus | Drone Mission & Control Systems | April 2025 | Seed | $4.3M | Autonomous defense drones and navigation systems | North America | First Round Capital | United States | |
| Askari Defense | Interceptor Drones | April 2025 | Unknown | $1.3M | Hand-launched autonomous drone interceptors | North America | Not disclosed | United States | |
| SpearUAV | Loitering Munitions | March 2025 | Unknown | Undisclosed | Encapsulated military tactical AI loitering munitions; UVision subsidiary | Middle East | Deep Insight | Israel | |
| Quantum Aero | Drone Mission & Control Systems | March 2025 | Seed | $2.7M | AI-guided autonomous defense drones | Asia-Pacific | Not disclosed | South Korea | |
| Neros Technologies | Strike Drones | March 2025 | Series A | $35M | FPV strike and interceptor drones | North America | Vy Capital | United States | |
| Shield AI | Drone Mission & Control Systems | March 2025 | Series D+ | $240M | AI autonomy software and military drones | North America | L3Harris Technologies, Hanwha Asset Management | United States | |
| Alpine Eagle | Interceptor Drones | March 2025 | Seed | ~$11M | Airborne autonomous counter-drone defense systems | Europe | IQ Capital | Germany | |
| PDW | ISR Drones | March 2025 | Series A | $16M | American-made military unmanned aircraft systems | North America | Squadra Ventures | United States | |
| M-Fly | Drone Mission & Control Systems | March 2025 | Seed | $1.3M | Laser guidance and UAV gimbals | Europe | Not disclosed | Ukraine | |
| Evolve Dynamics | ISR Drones | March 2025 | Growth Equity | $768K | All-weather ISR unmanned aircraft systems | Europe | Not disclosed | United Kingdom | |
| Airbility | Interceptor Drones | January 2025 | Unknown | $1.7M | High-speed eVTOL counter-drone aircraft | Asia-Pacific | Samho Green Investment | South Korea | |
| Harmattan AI | Drone Mission & Control Systems | January 2025 | Series A | $30M | Autonomous military drones and air defence | Europe | FirstMark | France | |
| Orqa | Strike Drones | December 2024 | Seed | $6.4M | FPV drones and defence electronics | Europe | Lightspeed Venture Partners | Croatia | |
| TEKEVER | ISR Drones | November 2024 | Series B | $77M | AI-powered military surveillance drones | Europe | Baillie Gifford, NATO Innovation Fund | Portugal | |
| Skydio | ISR Drones | November 2024 | Series D+ | $170M | Autonomous drones for defense and inspection | North America | KDDI, Axon Enterprise | United States | |
| Nordic Air Defence | Interceptor Drones | November 2024 | Seed | $1.3M | Software-defined low-cost drone interceptors | Europe | SNÖ Ventures | Sweden | |
| Origin Robotics | Loitering Munitions | October 2024 | Seed | $2.6M | Autonomous precision drones for military missions | Europe | Change Ventures | Latvia | |
| STARK Defence | Loitering Munitions | October 2024 | Series A | $15M | Autonomous military drones and weapons | Europe | Sequoia Capital | Germany | |
| Firestorm Labs | Strike Drones | October 2024 | Series A | $20M | Expeditionary drone manufacturing and UAS | North America | Not disclosed | United States | |
| Quantum Systems | ISR Drones | September 2024 | Series B | ~$11M | AI-powered military unmanned aerial systems | Europe | Notion Capital, Porsche SE | Germany | |
| Farsight Vision | Drone Mission & Control Systems | September 2024 | Seed | ~$667K | Drone-derived 3D intelligence and mapping | Europe | Not disclosed | Estonia | |
| Darkhive | ISR Drones | September 2024 | Series A | $21M | Autonomous tactical reconnaissance drones | North America | Ten Eleven Ventures | United States | |
| Nordic Air Defence | Interceptor Drones | September 2024 | Seed | $540K | Software-defined low-cost drone interceptors | Europe | Not disclosed | Sweden | |
| Swarmer | Swarm & Collaborative Drones | August 2024 | Seed | $2.6M | Autonomous drone swarm control software | Europe | R-G.AI | Ukraine | |
| Anduril | Strike Drones | August 2024 | Series D+ | $1.5B | Autonomous defence systems and weapons | North America | Founders Fund, Sands Capital | United States | |
| Vector | Strike Drones | August 2024 | Seed | $13M | Military drones and warfare services | North America | Not disclosed | United States | |
| Airbility | Interceptor Drones | August 2024 | Seed | Undisclosed | High-speed eVTOL counter-drone aircraft | Asia-Pacific | Not disclosed | South Korea | |
| Helsing | Loitering Munitions | July 2024 | Series C | $495M | AI-powered autonomous defense systems | Europe | General Catalyst | Germany | |
| Granta Autonomy | ISR Drones | July 2024 | Seed | $1.1M | Autonomous drones for defense reconnaissance | Europe | ScaleWolf VC | Lithuania | |
| Unmanned Defense Systems | Swarm & Collaborative Drones | May 2024 | Seed | ~$3.5M | Autonomous military drones and robotic systems | Europe | Coinvest Capital | Lithuania | |
| Neros Technologies | Strike Drones | May 2024 | Seed | $11M | FPV strike and interceptor drones | North America | Sequoia Capital | United States | |
| XTEND | Drone Mission & Control Systems | May 2024 | Series B | $40M | AI-assisted military reconnaissance and tactical drones | North America | Chartered Group | United States | |
| ZULU Defence Systems | Strike Drones | April 2024 | Seed | $750K | Autonomous military drone systems | Asia-Pacific | Finvolve | India | |
| Firestorm Labs | Strike Drones | March 2024 | Seed | $13M | Expeditionary drone manufacturing and UAS | North America | Lockheed Martin Ventures | United States | |
| PDW | ISR Drones | March 2024 | Seed | $8.6M | American-made military unmanned aircraft systems | North America | Not disclosed | United States | |
| NewSpace Research & Technologies | Swarm & Collaborative Drones | March 2024 | Unknown | $33M | Swarm drones and long-endurance UAVs | Asia-Pacific | Cornerstone Venture Partners, 360 ONE Asset, Volrado Venture Partners | India | |
| Evolve Dynamics | ISR Drones | March 2024 | Growth Equity | $2.6M | All-weather ISR unmanned aircraft systems | Europe | Not disclosed | United Kingdom | |
| Buntar Aerospace | ISR Drones | March 2024 | Seed | $1M | Reconnaissance drones and battlefield software | Europe | Not disclosed | Ukraine | |
| Beyond Vision | ISR Drones | 2024 | Unknown | Undisclosed | Manufactures AI-enabled military drones and ISR unmanned platforms. | Europe | Not disclosed | Portugal | |
| Cambridge Aerospace | Interceptor Drones | 2024 | Seed | Undisclosed | Low-cost drone and missile interceptors | Europe | Not disclosed | United Kingdom |

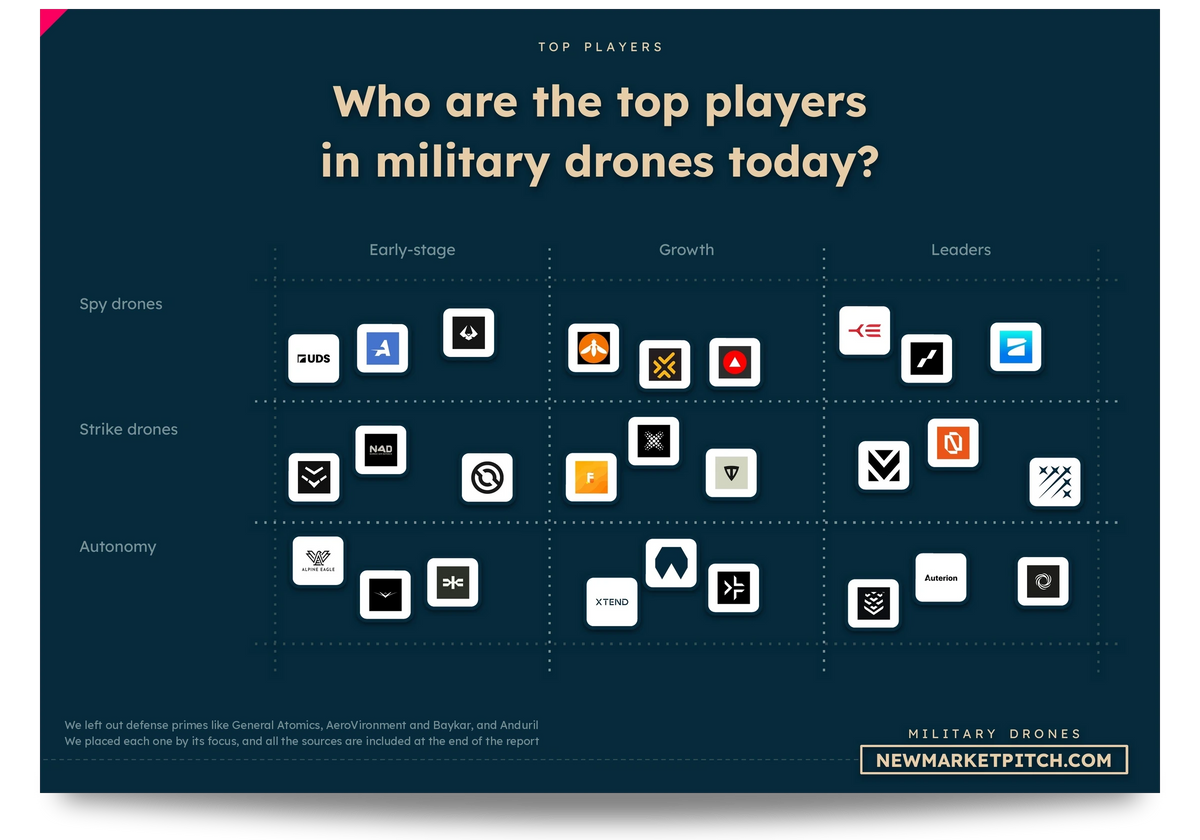
In our research about military drones, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is military drone funding really taking off this year?
Yes, military drone funding is growing sharply, and more startups are getting financed.
We tracked 61 military drone deals involving 49 companies this year to date. The same period of 2025 saw 43 deals and 41 funded companies, with at least $4.5B disclosed. At the same point in 2024, the market had 23 deals, 21 companies and at least $2.2B. The wider group of funded startups makes this more than a giant check distorting an otherwise quiet market.
Demand is changing in concrete ways. The US Drone Dominance Program puts aircraft through military-operated trials and links selection to orders. NATO's Drone Edge initiative, announced in July 2026, aims to shorten the route from testing to procurement. Neither program is venture funding, but both give investors a clearer view of what armed forces might buy.
There is still a big gap between the growth in dollars and the growth in funded companies. Today's military drone market has more winners, while the biggest checks flow to a much smaller group that can already build and supply equipment.
Has military drone funding already beaten last year?
Military drone startups have already raised more this year than during the whole of 2025.
The current partial year has reached 298% of full-year 2025 disclosed capital and 122% of its deals. Full-year 2025 recorded 50 deals and at least $5.2B. Against the completed 2024 year, the current partial year stands at 631% of capital and 218% of deal count. These are comparisons with entire previous years, not an annualized estimate.
Investors also have more to work with than forecasts. Britain's Ministry of Defence announced a drone program worth more than £5 billion over four years in June 2026, spanning strike, reconnaissance and autonomous equipment. The NATO defense-industry forum in July pressed for faster procurement and more private investment in industrial capacity.
Those government budgets cover a broader set of systems than our military aerial-drone market, and they are not counted in our funding figures. They do show why a startup building drones for the armed forces can now point to specific purchasing plans instead of relying only on general interest in autonomy.
Did the military drone funding boom happen all at once?
Military drone funding jumped in Q2 2026 and stayed high in Q3 2026, which makes the boom harder to dismiss as a one-off.
Q1 2026 brought 18 deals and at least $2.0B, followed by 14 deals and at least $6.4B in Q2 2026. Q3 2026 then delivered 19 deals and at least $5.0B. Its median round was $46M, versus $57M in Q2 2026. By contrast, Q2 2025 brought in $3.7B across 13 deals before Q3 2025 dropped to $425M across 14 deals. The earlier jump faded much faster.
The latest quarter remains partial. Q4 2026 currently has 10 deals involving 9 companies and at least $2.1B. Shield AI's $1.0B Series D+ in November 2026 and UFORCE's $700M Series A in November 2026 show that large financings are still being announced. They say little about what the completed quarter will eventually total.
Customers still matter here. Britain announced new surveillance-drone purchases for its Army in September 2026. That demand is building outside venture capital, whatever the quarterly funding totals say.
The table below shows the quarter-by-quarter disclosed capital and deal counts since 2024.
| Period | Deals | Capital |
|---|---|---|
| Q1 2024 | 5 | $58M |
| Q2 2024 | 4 | $55M |
| Q3 2024 | 10 | $2.0B+ |
| Q4 2024 | 7 | $292M |
| 2024, quarter not known | 2 | Undisclosed |
| Q1 2025 | 10 | $339M+ |
| Q2 2025 | 13 | $3.7B |
| Q3 2025 | 14 | $425M |
| Q4 2025 | 13 | $771M+ |
| Q1 2026 | 18 | $2.0B+ |
| Q2 2026 | 14 | $6.4B+ |
| Q3 2026 | 19 | $5.0B+ |
| Q4 2026 (partial) | 10 | $2.1B+ |
Quarters add up to fewer deals than the yearly totals: 2 deals of 2024 are dated only by the year, so they count in the yearly totals but in no quarter.
Is Anduril still the biggest name in military drone funding?
Anduril remains the largest military drone fundraiser this year, although rival startups now raise checks big enough to reshape the market.
Anduril's $5.0B late-stage round in May 2026 leads the current period. The company also had the largest deal in the equivalent 2025 period, Anduril's $2.5B round in June 2025, and the equivalent 2024 period, Anduril's $1.5B round in August 2024. Anduril has repeatedly set the scale for the biggest rounds.
Now look at the competition. Shield AI raised $1.5B in a Series D+ in March 2026, Helsing raised $1.8B in its Series D+ in July 2026, and Quantum Systems raised $1.2B in its Series D+ in July 2026. These businesses sell different things: Shield AI combines aircraft with Hivemind autonomy, Helsing builds loitering munitions, and Quantum Systems supplies surveillance aircraft.
Their customers give us better evidence than a funding announcement alone. Shield AI announced an Indian Army selection for V-BAT and Hivemind in January 2026. Germany signed a loitering-munition contract with Helsing in February 2026. Anduril still sets the pace in fundraising, but it now has serious company near the top.

In our market report about military drones, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Are $100M military drone rounds becoming normal?
Military drone rounds above $100M are much more common now, but most financing deals are still smaller.
There have been 17 deals above $100M this year to date, compared with 5 in the same period of 2025 and 2 at the same point in 2024. Their share of all deals has reached 28%, up from 12% and 9%. That is too large a shift to explain through Anduril alone.
Several recent checks went to distinct kinds of drone suppliers. Mach Industries raised a $600M Series C in September 2026 for military attack and interceptor aircraft. Cambridge Aerospace raised a $300M Series C in August 2026 for interceptors, while Neros Technologies completed a $250M Series C in August 2026 for strike and interceptor drones.
Founders still face a difficult test before they can follow suit. The US Drone Dominance Program scores candidates on actual flight performance, military operators' evaluations, production capability and supply chains. Its latest published leaderboard includes Neros among the leading designs in both deep-strike and close-quarters missions. A large funding round is easier to understand when a supplier can show that its drones work and can be manufactured in quantity.
Are seed-stage military drone startups being squeezed out?
Seed-stage military drone startups are still raising money, but later rounds are growing faster.
We tracked 16 Seed deals this year, compared with 15 at the same point in 2025 and 14 in the comparable 2024 period. Seed's share of all military drone deals has fallen to 26%, from 35% and 61%. The median Seed round is $4.1M now, versus $3M in the equivalent period last year. So there are still new early-stage financings, even if they no longer dominate the market.
The very small end is under pressure. We counted 14 disclosed deals under $5M this year, against 15 in the same period of 2025. Excluding rounds above $50M leaves at least $552M this year, up 94%. Excluding rounds above $100M leaves at least $810M, down 6%. The threshold matters: much of the extra money is going to rounds between the small-company market and the very largest checks.
New entrants can still reach buyers. NATO's innovation range in Latvia, launched in March 2026, gives suppliers a place to test systems under operational conditions. Mara raised a $7M Seed in August 2026 for autonomous interceptors, while Six Robotics raised a ~$14M Seed in June 2026 for collaborative drone autonomy. The opportunity for new companies remains, but the headline boom is mostly happening further along.
Are later-stage military drone startups taking all the money?
Later-stage military drone rounds receive 93% of disclosed capital, even though earlier-stage companies still close more named-stage deals.
Later-stage transactions account for 46% of deals with a named stage this year, compared with 32% in the same period of 2025. Rounds from Series D+ onward have 8 deals and $11.4B in disclosed financing, versus 3 deals and $3.4B at the comparable point last year. Series C has also reached 5 deals, against 2. Far more money is reaching companies that have already passed an initial fundraising test.
The German army's loitering-munition purchasing model shows what comes after a successful prototype. Its 2026 contracts with Helsing, STARK Defence and Rheinmetall set out deliveries in stages and require suppliers to keep software updated as tactics change. Quantum Systems, meanwhile, has been expanding production sites across allied countries. Building factories and supporting equipment in use takes more cash than getting an early aircraft into the air.
That explains the difference between the number of deals and where the dollars go. Seed and Series A companies still get financed, while the much larger checks support businesses preparing for repeat deliveries.
The table below shows this year's funding by announced stage, ordered by disclosed capital; the capital share excludes rounds with undisclosed amounts.
| Stage | Deals | Capital | Capital share |
|---|---|---|---|
| Series D+ | 8 | $11.4B | 74% |
| Series C | 5 | $2.0B | 13% |
| Series A | 12 | $1.0B+ | 6% |
| Series B | 7 | $692M+ | 4% |
| Growth Equity | 4 | $166M | 1% |
| Seed | 16 | $119M+ | 1% |
| Unknown | 9 | $41M+ | <1% |

Our document detailing everything you need to know about military drone gets updated several times a month, so you always get the latest view of where things stand.
Why do military drone investors keep backing the same startups?
Investors now put almost all disclosed military drone funding into companies that have raised before.
We identified 49 follow-on deals involving 41 companies this year, making up 80% of all military drone financings and 99% of disclosed capital. First financings brought 8 deals involving 8 companies and $77M. There were 30 follow-on deals and 11 first financings in the comparable period last year. This year, 12 companies raised through 2 rounds, compared with 2 companies at the same point in 2025.
This does not mean the pool of potential backers has shrunk. We counted 107 unique investors this year against 77 in the comparable 2025 period. Instead, investors can now follow companies from a first product into manufacturing, contract delivery and newer models. That creates reasons to finance the same supplier more than once.
New suppliers have another route to potential customers. NATO and Ukraine's UNITE – Brave NATO program connects teams through trials and possible purchases.
Are strike drones still getting most of the funding?
Strike drone startups still lead the military drone market in dollars, although other kinds of drones now win more individual rounds.
Strike drone developers raised $7.0B across 9 deals this year. They account for 45% of disclosed capital, down from 62% at the same point in 2025 and 71% at the equivalent point in 2024. The category's deal share has also slipped, from 16% to 15% over the latest comparable periods. Investors are still writing big checks for strike systems; they are also funding more things alongside them.
Recent rounds also go to products built for very different battlefield roles. Neros Technologies works on small FPV strike aircraft, Mach Industries has pursued attack and interceptor systems, and Anduril makes autonomous defense products across a broader range. Buyers need different aircraft for different tasks, which helps explain why one category can contain very different-sized suppliers.
The US military is also moving away from demonstration-only contests. Its Drone Dominance Program is placing prototype orders after military-operated flight trials. That gives strike-drone suppliers a specific route to sales while leaving plenty of room for other types of military aircraft to attract investors.
The table below shows every military drone category by disclosed capital raised this year; capital share refers only to rounds with public amounts.
| Category | Deals | Capital | Capital share |
|---|---|---|---|
| Strike Drones | 9 | $7.0B | 45% |
| Drone Mission & Control Systems | 13 | $2.9B+ | 19% |
| ISR Drones | 19 | $2.5B+ | 16% |
| Loitering Munitions | 4 | $2.4B+ | 15% |
| Interceptor Drones | 9 | $662M+ | 4% |
| Swarm & Collaborative Drones | 4 | $52M | <1% |
| Cargo & Logistics Drones | 3 | $27M+ | <1% |
Are military surveillance drones getting more deals than attack drones?
Military surveillance drones now attract more financing deals than strike drones, even though attack systems still raise more money.
ISR drone startups have recorded 19 deals involving 15 companies this year, compared with 8 deals involving 8 companies at the same point last year. The category's share of all deals has risen from 19% to 31%. Strike drones have 9 deals involving 7 companies. The split is useful: investors can back surveillance aircraft across many suppliers without committing checks as large as those raised by leading strike-drone companies.
The customers are real. Britain's Ministry of Defence laid out new surveillance-drone purchases for the Army in September 2026. In April 2026, Shield AI said the US Navy had selected V-BAT to compete for contractor-operated intelligence and surveillance work. That is a chance to win task orders, not a guaranteed contract for the full amount.
Quantum Systems, TEKEVER and PDW also build distinct military surveillance systems, from long-endurance aircraft to tactical platforms. Their funding activity helps explain why reconnaissance has moved ahead on deal count. For now, surveillance wins on deal count and strike aircraft on dollars.

In our report covering the military drone market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is military drone software getting bigger checks?
Software that directly controls military drones is now attracting major funding, especially when it is tied to aircraft in service.
Drone mission and control systems brought in 13 deals and at least $2.9B this year, compared with 12 deals and $444M during the same period last year. The much larger total came without a major rise in transactions. Shield AI is a big part of that story: it raised a $1.5B Series D+ in March 2026 and a $1.0B Series D+ in November 2026 for a business that combines flight autonomy with military aircraft.
Smaller software-related rounds are going to specific problems. AITAN raised a $41M Series A in September 2026 for autonomous defense systems, and SE3 raised a $30M Series A in November 2026 for onboard spatial AI and mission software. Shield AI's January 2026 announcement of an Indian Army V-BAT and Hivemind selection is an example of software being purchased with a flying system.
Germany's loitering-munition contracts require manufacturers to keep software current after delivery. That makes drone control software valuable for as long as the aircraft needs to adapt to jamming and changing tactics. It also explains why generic military AI products, with no direct control over aircraft, do not belong in this funding category.
Is money pouring into military interceptor drones right now?
Yes, military interceptor drone startups are raising larger checks as armed forces look for cheaper ways to shoot down hostile aircraft.
Interceptors attracted 9 deals and at least $662M in disclosed funding this year, against 9 deals and $138M at the same point in 2025. Cambridge Aerospace raised a $300M Series C in August 2026, and Alta Ares raised a $57M Series A in June 2026. The number of deals has not changed, but the checks are far larger. The sums are smaller than those going to the biggest strike-drone companies.
NATO opened a counter-UAS marketplace in November 2026 to let allies buy approved equipment without running a new full tender. Among the selected suppliers were Alta Ares and Quantum Systems. The catalogue also includes detection and defense systems that are not themselves interceptor drones, so it should not be mistaken for an interceptor-only purchasing program.
Investors are funding aircraft that physically intercept threats, from low-cost kinetic drones to more complex autonomous designs. The next commercial test is cost per successful interception and how reliably manufacturers can supply replacements. Fighting expensive threats with an even more expensive defense will not solve the buyer's problem.
Are investors really betting on military drone swarms yet?
Military drone swarms are getting funded, but investors have not begun writing the giant checks seen elsewhere in military aviation.
We tracked 4 swarm and collaborative drone deals this year, worth $52M in disclosed capital. The equivalent period last year had 2 deals and $22M. Swarm companies represent 6% of this year's deals and <1% of disclosed capital. Even with growing interest in swarms, that remains a small funding market.
There are signs of customer interest. In September 2026, Britain announced that companies would be able to use Ukrainian battlefield data to build and test AI for drone swarms. NATO's innovation range in Latvia also gives manufacturers a way to see how uncrewed systems behave around electronic interference.
The funding examples remain early. Swarm Aero raised a $35M Series A in March 2026 for large autonomous military aircraft, while Six Robotics raised a ~$14M Seed in June 2026 for collaborative autonomy. These deals support serious development work, but they do not show that armed forces are already buying coordinated combat fleets in volume.
Why are loitering-munition startups raising such huge rounds?
Loitering-munition startups can raise enormous military drone rounds because several have moved from developing weapons to supplying armies.
The category recorded 4 deals and at least $2.4B this year, compared with 3 deals and at least $722M during the same period last year. Helsing raised a $1.8B Series D+ in July 2026, and STARK Defence raised a $550M Series C in June 2026. Those large financings explain much of the category's dollar total; it is still a small group of funded developers.
Germany has given those companies a clear route to a paying customer. The Bundeswehr says it signed loitering-munition contracts with Helsing and STARK Defence in February 2026 and with Rheinmetall in April 2026. Deliveries happen in stages, with performance checks and obligations to update the software. Rheinmetall is an established defense manufacturer, not a startup.
Helsing's HX-2, introduced in December 2024, was designed as a mass-producible precision weapon able to work despite electronic interference. The big question now is how well companies can deliver and improve these weapons on the army's timetable. The financing has moved ahead of proof that a large group of suppliers can do so.

In our research about military drones, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are military cargo drones missing out on the funding boom?
Military cargo drones still receive very little startup funding compared with aircraft built for attack or surveillance.
Cargo and logistics drone developers recorded 3 deals and at least $27M this year, versus 2 deals and $8M during the same period in 2025. They attracted <1% of disclosed military drone capital. Their job is useful, carrying supplies without exposing a crew, but investors have put much larger sums into weapons and reconnaissance.
There are funded companies doing the work. Grid Aero raised a $20M Series A in January 2026 for military cargo aircraft, and Certo Aerospace raised a ~$6.6M round of undisclosed stage in October 2026 for a heavy-lift autonomous VTOL. Both offer an answer to a practical military logistics problem.
Britain included logistics drones in an April 2026 Ukraine support package. But several large autonomous-systems budgets also cover ground vehicles and unmanned boats, which fall outside our aerial-drone market. Cargo aircraft have a credible use case; the missing piece is a run of larger equity checks or repeat purchases that would put them alongside the major combat-drone categories.
Is Europe now doing more military drone deals than North America?
Europe now has more military drone funding deals, while North America still gets more disclosed investment dollars.
European-headquartered startups completed 31 deals involving 26 companies this year, or 51% of military drone transactions. North America recorded 24 deals involving 18 companies and at least $9.6B, versus at least $5.8B for Europe. North America accounts for 62% of disclosed capital and Europe for 38%. At the same point last year, Europe had 19 deals and $1.2B, compared with 18 deals and $3.3B for North America.
Europe's wider group of funded suppliers matches a growing list of buyers. In October 2026, the European Commission identified drones and counter-drone equipment among urgent shared procurement needs. The United States still has exceptionally large companies such as Anduril and Shield AI, which helps explain why North America leads on dollars.
Asia-Pacific is far behind, with 6 deals and $19M this year. Europe's rise is clearest in the number of funded developers, rather than in total dollars raised.
Is Germany now Europe's biggest military drone funding hub?
Germany leads the European military drone market by disclosed startup funding, though Britain matches it on deal count.
German-headquartered military drone companies recorded 7 deals involving 6 companies and at least $3.6B this year. The United Kingdom also had 7 deals, while TEKEVER alone raised $580M in Portugal. Germany's large dollar total comes from companies such as Helsing, Quantum Systems and STARK Defence, not a dramatically higher number of transactions.
German procurement gives those companies home-market demand. The Bundeswehr's 2026 loitering-munition contracts set staged deliveries and software-updating requirements.
The manufacturing footprint stretches beyond Germany too. Quantum Systems announced additional production across allied countries in July 2026 and described German-backed interceptor production in Ukraine in October. Germany is a leading place to raise capital for military drones in Europe today, while Britain, Portugal and Ukraine remain important parts of the supplier base.
Are British military drone startups raising serious money now?
British military drone startups are raising large rounds, though the money is going to a small group of companies.
The United Kingdom recorded 7 deals involving 4 companies and $1.3B in disclosed military drone funding this year. UFORCE raised $750M across 2 deals, while Cambridge Aerospace raised $500M across 2 deals. Those numbers show the UK can attract sizable checks without implying that every British drone startup has found an easy funding market.
Britain's procurement plans are now more specific. In June 2026, the Ministry of Defence outlined a drone transformation backed by more than £5 billion over four years. September brought plans for new Army reconnaissance drones. The National Wealth Fund also participated in UFORCE's expansion of British engineering and production, according to the government's November 2026 announcement.
UFORCE also sells uncrewed boats outside military drones, and its rounds count here in full. Britain's larger procurement program also includes boats and ground vehicles. Still, Britain now offers both serious investors and military test sites for drone suppliers that meet the requirements.

Learning from others' mistakes is the cheapest lesson there is. In our market report about military drones, we look at what broke startups before you, so you don't repeat it.
Does Ukraine's drone war show up in startup funding?
Not much: Ukrainian military drone startups raise far less disclosed venture funding than their role in modern warfare might suggest.
Ukrainian-headquartered startups recorded 6 military drone deals involving 5 companies and at least $32M this year. At the same point in 2025, they had 5 deals and $23M. Venture investment is a narrow measure here. It excludes equipment purchased by the armed forces, foreign military aid, manufacturing revenue and grants that do not qualify as equity rounds.
The actual buying activity is much larger in scope. Britain said in June 2026 that it would provide 150,000 Ukrainian-produced drones through its military support package. NATO and Ukraine's UNITE – Brave NATO program helps manufacturers test equipment and compete for future work. In October 2026, companies from both countries met at a British military facility to explore production partnerships.
Buntar Aerospace raised a $10M Seed in March 2026 and a $16M round of undisclosed stage in October 2026. Those financings show there is an equity market for Ukrainian military drone manufacturers. They cannot, however, capture the value of the drones that Ukraine builds, buys and uses outside venture-backed companies.
Can military drone startups still rely on Chinese components?
Military drone startups selling to the United States face growing restrictions on Chinese components and more demanding production tests.
The US Drone Dominance Program published a supply-chain framework in April 2026 that tightens restrictions on parts from covered countries, principally China. Its competitions also judge how reliably suppliers can produce and deliver drones. A design that flies well in a demonstration may still struggle if its manufacturer cannot replace restricted parts or meet delivery targets.
Companies have started to build across allied markets. Quantum Systems described manufacturing expansion in Germany, Ukraine, Australia and the United States in July 2026. Britain announced a Suffolk facility for Ukrainian drone maker Ukrspecsystems in February 2026. These are practical ways to bring production closer to the customers who want to control their supply chains.
Funding rounds don't show which supplier has removed which component from its designs. They do show how much money is now flowing to businesses that must make, repair and update aircraft at scale. Supply-chain compliance is becoming part of winning military customers, and investors cannot ignore that requirement.
So, what are the latest military drone funding trends?
Military drone funding is rising fast, with investors putting increasingly large checks into established companies that can build and deliver aircraft.
We tracked 61 deals and at least $15.5B raised this year to date, led by Anduril's $5.0B late-stage round in May 2026. The number of deals is growing as well as the money, but far more of the extra capital is flowing into very large follow-on rounds. Shield AI, Helsing and Quantum Systems show that Anduril no longer stands alone in the upper tier.
The mix of products is changing too. Strike drones lead in dollars, surveillance drones attract the most deals, and mission-control software and interceptor aircraft now draw larger commitments. Europe leads on deal count while North America continues to lead in disclosed capital. Military procurement is giving investors more specific reasons to finance production, but a contract opportunity is still different from cash received.
New military drone startups can get funded. The tougher task is turning a working design into an aircraft that military customers can order repeatedly, repair quickly and trust under electronic interference. That is where the biggest rounds are heading.
The table below shows what we found.
| Question | Answer |
|---|---|
| Did this boom reach more than giants? | Yes, military drone startups closed 61 deals in the current partial year. That is up 42% from the same period last year. But the biggest transactions still account for most funding dollars. |
| Has the boom passed last year's totals? | Yes, the partial year stands at 298% of last year's capital. It also reached 122% of the previous full year's deal count. Those figures require no assumptions about what happens before year-end. |
| Are smaller checks being pushed aside? | Not pushed out, but squeezed. Deals under $5M still numbered 14 this year. Their share has shrunk while bigger checks appear more often. |
| Do first-time founders get enough venture backing? | Not much, first rounds are getting rarer. First financings totaled 8 military drone deals this year. Follow-on deals make up 80% of the market's deals. |
| Are late-stage drone companies now winning everything? | In dollars, almost. Later stages received 93% of disclosed capital this year. Early-stage deals still make up most financings with named stages. |
| Has surveillance overtaken combat drones with investors? | Only on deal count. ISR drones led deal flow with 19 deals. Strike drones still took 45% of disclosed capital. |
| Is flight software becoming a bigger business? | Yes, and the checks got much bigger. Drone mission-control systems raised at least $2.9B this year. Investors want software already flying inside military aircraft. |
| Can interceptor makers finally raise significant money? | Yes, the niche has grown fast. Interceptor drone startups raised at least $662M of disclosed funding this year. Buying interest still needs to turn into repeat drone orders. |
| Has Europe caught America in drone finance? | On deals yes, on dollars no. Europe completed 31 military drone financings this year. North American startups still raised at least $9.6B. |
| Does battlefield demand automatically create venture funding? | No, war demand mostly flows elsewhere. Ukraine recorded 6 funded military drone deals this year. Its army relies on purchases and foreign support, not startup equity rounds. |
| What must drone startups prove after fundraising? | Bigger checks follow companies that can deliver working military aircraft. Today's investors are financing production and repeat customer needs. The next race is to manufacture reliably, not announce rounds. |

If you build or invest in the military drone market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Our methodology
Our data runs through November 14, 2026. We then reviewed this article and updated its answers on November 17, 2026, the date shown under the title. We examined qualifying military drone financings from January 1, 2024 to November 14, 2026. This year's comparisons use January 1 to November 14 for 2026, 2025 and 2024. Full-year 2025 and full-year 2024 totals are labelled as such and are never annualized or treated as equivalent periods.
We count equity financings of qualifying companies at or above $300K. We exclude debt, grants, loans, unconverted convertibles, SAFEs and public offerings from deal totals. Every included company meets our startup definition: an independent business founded in 2000 or later, built to grow quickly around a new product or technology, funded by venture capital, angels, founders or other qualifying backers, and either privately held or listed within the last 5 years. A recently acquired company can remain eligible under our 3-year acquisition rule.
We define military drones as uncrewed aircraft built or materially adapted for armed-forces missions, together with dedicated autonomy and mission-control systems that directly operate those aircraft. We include reconnaissance, strike, loitering, aerial logistics, electronic-warfare, swarming and aerial interceptor products. A qualifying dual-use company must have a defense-centered business or meet our independent specialist-source test. We retain borderline companies when they satisfy that test rather than arbitrarily excluding them. We exclude ground and sea-only robots, civilian-first drones without a defense-centered business, standalone components, generic analysis software and counter-drone sensors or jammers without an interceptor aircraft.
Each distinct equity financing is counted once, and duplicate reports of the same announcement are merged. An undisclosed deal contributes to the deal count but not the disclosed capital total, so some sums are reported as minimums. We preserve approximate foreign-currency conversions and the source's published stage rather than manufacturing precision. The 2 deals of 2024 dated only by the year count in yearly totals but not in any quarter.
We classify Seed and Series A as early stage; Series B, Series C, Series D+ and Growth Equity as later stage, and leave unlabelled stages unknown. Shares of early and later stage are measured among financings with named stages. Category is our classification of each company's core military-drone product, while region is determined by its headquarters country. Capital shares exclude rounds whose amounts were not disclosed.
We prioritize company announcements, regulatory filings and reliable press reporting for financing facts, with databases used only when they satisfy a stronger corroboration rule. We do not treat a government procurement announcement, planned investment or potential contract ceiling as an equity funding round. Public-source examples of customers, contracts and production programs provide context but do not add to the financing totals.
Rounds confirmed by a company announcement, a press article or a regulatory filing are counted in full. Where no article exists, a round is counted only when at least two recognised databases agree on its date (within one month) and amount (within 5%), and it is marked as low confidence; a round found in a single database stays in the company's history but is left out of totals. For companies that have raised more than $100M, every round counted is backed by an article.
Our totals can differ from broader defense-tech estimates because those often include public contractors, unmanned vehicles on land or sea, debt, public procurement and companies with only indirect drone products. Our latest quarter is explicitly partial, and we never project its result forward. We keep the same market perimeter and comparable calendar windows across periods so that the direction of funding is not an artefact of changing definitions.
Key sources include US Drone Dominance Program goals, evaluations and acquisition process, 2026 competition phases, production tests, supply-chain framework and new mission requirements, UK Ministry of Defence drone investment and procurement plans, June 2026, NATO industry forum, Drone Edge and appeal to private capital, Shield AI V-BAT aircraft and Hivemind selection by India, Helsing HX-2 product, manufacturing rationale and autonomy, Quantum Systems expansion of allied manufacturing sites, July 2026, NATO testing range for uncrewed and counter-drone systems, UNITE – Brave NATO company testing and procurement competition, German loitering-munition contracts and procurement conditions, UK surveillance drone procurement, September 2026, Shield AI selection to compete for US Navy ISR orders, NATO counter-UAS marketplace and selected suppliers, German-financed Quantum Systems interceptor production in Ukraine, UK-Ukraine battlefield-data competition for drone swarm AI, UK drone support package including aerial logistics systems, European Commission SAFE procurement priorities, October 2026, US military scoring of combat drones and production readiness, UK National Wealth Fund and UFORCE manufacturing expansion, UK commitments to Ukrainian-produced drones, June 2026, UK-Ukraine industry event and collaboration, October 2026, and Ukrainian drone manufacturing facility in Suffolk, February 2026.

In our report covering the military drone market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us