Can legal AI make money if it kills the billable hour?
Whether you're building or investing in the legal AI market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
Yes. Legal AI can make money even if it substantially reduces lawyers' billable hours, because law firms and corporate legal teams will still pay for faster, reliable legal work. The harder question is how much of the savings software vendors can actually keep.
The pressure on traditional billing is measurable. Thomson Reuters found that 71% of in-house legal professionals expect outside firms to change their pricing because of AI, while only 28% of law firms have done so. Clients are moving faster than the industry's commercial habits.
AI is already disrupting individual lawyers without destroying demand for legal services. Around 20% of extensive AI users in Clio's research struggled to meet billable targets because of the technology, yet demand among law firms tracked by Thomson Reuters still grew 3.3% in the fourth quarter of 2025.
Law firms can actually earn more per lawyer-hour even while charging clients less. In our illustrative contract-review example, moving from ten hours of work to four increases contribution per lawyer-hour from $250 to $562.50, provided the firm can capture enough additional work.
Hourly billing is proving remarkably resilient. In 2024, 95% of surveyed firms still used it for at least some work, despite a gradual shift toward fixed fees. AI adoption is accelerating much faster than the business models used to sell legal services.
Corporate legal departments may be an even more attractive customer group than law firms. They can use AI to reduce outside counsel costs directly, without worrying about losing billable revenue. That gives vendors access to budgets beyond traditional law-firm software spending.
Premium pricing is economically possible. A $500 monthly legal AI subscription costs $6,000 annually, equivalent to just 20 hours of gross billable revenue at $300 per hour. But vendors must demonstrate actual value rather than assume saved time automatically becomes additional revenue.
Investors are already assigning extraordinary valuations to legal AI. Harvey reached a reported $15.5 billion valuation and Legora approximately $5.6 billion in 2026. Their commercial adoption is substantial, but comparable public financial data still cannot establish whether those valuations are supported by durable profits.
Cheaper foundation models won't automatically translate into richer software companies. Falling inference costs can improve margins, but competition from Thomson Reuters, LexisNexis, AI-native startups, and general-purpose AI platforms can push subscription prices down simultaneously.
The clearest automation opportunities remain document-heavy workflows such as contract review, legal research, and due diligence. Independent testing has also exposed significant accuracy problems, making verification, trusted information, and professional oversight commercially important rather than optional features.
Our conclusion is that legal AI can become a large, profitable software market even as the billable hour shrinks. The strongest businesses will be those embedded in legal research, verification, document management, and complete workflows. Basic drafting assistants may create plenty of productivity gains without capturing much of the economic value themselves.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us
Is legal AI actually killing the billable hour?
Legal AI is putting real pressure on hourly billing, but law firms are changing their prices much more slowly than their technology.
The problem is simple. Lawyers have traditionally charged clients for their time, while AI tools promise to make legal research, contract reviews, document drafting, and due diligence much faster. When a task that once took six hours takes two, clients eventually start questioning why they should pay the same amount.
According to Thomson Reuters' 2026 Future of Professionals research, 71% of in-house legal professionals expect outside law firms to change their pricing because of AI. Yet only 28% of law firms reported making those changes. That's a 43-percentage-point gap between what clients expect and what their lawyers are doing.
The pressure is already affecting commercial relationships. The same research found that 32% of in-house legal professionals had reconsidered, or expected to reconsider within 12 months, relationships with firms that couldn't demonstrate AI-enabled value.
We don't expect hourly billing to disappear from complex litigation or high-stakes advisory work anytime soon. But routine tasks are becoming harder to sell by the hour. That's where AI threatens the traditional model most directly, and where a new software business is emerging.
Are lawyers actually billing fewer hours because of AI?
Legal AI is already making some lawyers struggle to meet their billable-hour targets, although industry-wide billing has yet to collapse.
Clio's 2025 Legal Trends Report found that approximately 20% of lawyers who used AI extensively had difficulty meeting billable targets because of the technology. Among these extensive users, 45% had adjusted their pricing.
That doesn't mean the legal industry has lost 20% of its billable hours. Lawyers can use time saved on one assignment to handle additional work, take on more clients, or spend longer on tasks requiring professional judgment.
Law firms also continue to find plenty of paying work. Thomson Reuters reported that demand among firms tracked by its financial index grew 3.3% in the fourth quarter of 2025.
So AI adoption is affecting individual lawyers' workloads while demand for legal services remains strong enough to support industry growth.
For now, the clearest disruption is happening inside particular tasks rather than across entire law firms. A product can save thousands of lawyer-hours without immediately causing a comparable reduction in legal spending.

A good product starts with a real problem. In our report covering the legal AI market, we show you the ones customers still live with.
Can law firms make more money by working fewer hours?
Law firms can actually become more profitable with AI, provided they keep some of the savings instead of passing everything on to clients.
Consider a contract review that previously required ten hours at $400 per hour. The firm collected $4,000. If AI reduces the assignment to four hours and the firm charges a fixed fee of $3,000, revenue falls 25%, but the amount of lawyer time required drops 60%.
Assume the lawyer costs the firm $150 per hour, excluding overhead. The original assignment generates $2,500 before overhead. The AI-assisted version generates $2,250 after accounting for $150 in technology costs.
The firm makes slightly less money per assignment, but its contribution per lawyer-hour rises from $250 to $562.50. With enough additional work, that creates room for considerably higher profits.
These figures are illustrative, but Clio's 2025 research points in the same direction. Among legal professionals using AI, 36% reported a positive revenue impact. Among extensive AI users, that share reached 69%.
We can't attribute the entire difference to AI because better-performing firms may also adopt new technology faster. Still, the findings challenge the idea that fewer billed hours must mean weaker finances.
The catch is that the firm needs enough paying work to use the capacity it frees up. Otherwise, higher contribution per lawyer-hour doesn't necessarily translate into higher total profits.
If you want more recent data on this point, please see our latest legal AI market report.
Is hourly billing disappearing as quickly as people think?
Hourly billing is declining much more slowly than the excitement around legal AI suggests, and the shift toward fixed fees started years before ChatGPT.
Clio's historical data shows that the share of law firms billing exclusively by the hour fell from 47% in 2016 to 41% in 2024. Meanwhile, firms using both hourly and flat fees increased from 49% to 54%.
That's a six-percentage-point decline in exclusively hourly billing over eight years. Even in 2024, 95% of firms in the survey still used hourly billing for at least some of their work.
Compare that with AI adoption. Clio's 2025 research found that 79% of legal professionals used some form of AI, including general-purpose tools, while 93% of surveyed mid-sized firms reported using AI.
The adoption numbers come from different survey populations, so they shouldn't be treated as a direct conversion rate. But the difference in pace is hard to miss: firms can adopt AI tools almost overnight, while changing client contracts, compensation structures, and billing habits takes considerably longer.
| Law-firm billing model | 2016 | 2020 | 2024 |
|---|---|---|---|
| Hourly fees only | 47% | 47% | 41% |
| Flat fees only | 4% | 4% | 5% |
| Both hourly and flat fees | 49% | 49% | 54% |
| Firms using any hourly billing | 96% | 96% | 95% |
| Firms using any flat-fee billing | 53% | 53% | 59% |
| Change in hourly-only share since 2016 | Baseline | 0 pp | -6 pp |
| Change in flat-fee adoption since 2016 | Baseline | 0 pp | +6 pp |
The figures come from Clio's Legal Trends reporting. Combined categories and percentage-point changes are calculated from the reported shares.

If you build or invest in the legal AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Who pays legal AI companies if law firms start losing billable revenue?
Legal AI companies have two major customer groups with different reasons to spend money: law firms that want to work more efficiently and corporate legal teams that want to spend less on outside lawyers.
That second group is particularly interesting. When a law firm automates a task, it risks reducing the hours it can bill. When a company's in-house legal department automates the same task, it can reduce external legal bills without worrying about losing revenue.
Harvey's commercial expansion shows how vendors are targeting both markets. When announcing its $550 million financing in September 2026, the company said its platform was used by 80% of Am Law 100 firms and five Fortune 10 companies.
Those figures demonstrate extensive adoption among major legal organizations, although they don't tell us how many individual lawyers use the platform or how much each customer pays.
Legora has also secured deployments at international law firms, including White & Case. Thomson Reuters sells CoCounsel Legal to private practices and corporate legal departments, while LexisNexis serves both groups through its legal research and AI products.
All four companies are pursuing spending that already exists inside the legal industry. The money may come from lawyer productivity budgets, enterprise software budgets, or reductions in outside counsel costs.
For a legal AI startup, replacing billable hours can therefore create demand rather than destroy it.
Are legal AI startups already making serious money?
Legal AI startups are attracting major customers and enormous amounts of investment, but we still don't have enough public financial information to establish how profitable the leading companies are.
Harvey reached a reported $15.5 billion valuation after its $550 million financing in September 2026, compared with $11 billion following its March financing. That's a valuation increase of roughly 41% in less than six months.
Legora, founded in 2023, reached a reported valuation of approximately $5.6 billion in 2026.
Together, the two companies were valued at around $21.1 billion. That's quite a number for a relatively young software category, particularly one serving an industry historically dominated by established information providers and specialized enterprise software.
But valuations tell us what investors are willing to pay for expected future growth. They don't reveal how much cash these businesses generate.
We lack comparable audited financial statements showing Harvey's and Legora's revenue, gross margins, customer acquisition costs, and operating profits. Enterprise subscriptions can create attractive recurring revenue, but developing advanced AI products and supporting large legal customers can also be expensive.
What we can establish is that legal AI has progressed beyond experimental deployments. Harvey's reach among Am Law 100 firms, Legora's international customers, and the investments made by Thomson Reuters and LexisNexis show that serious buyers are putting money behind the technology.
Whether the fastest-growing startups can convert that demand into durable profits remains a much harder question.

Learning from others' mistakes is the cheapest lesson there is. In our market report about legal AI tools, we look at what broke startups before you, so you don't repeat it.
How much can legal AI companies charge lawyers?
Legal AI companies can charge hundreds of dollars per lawyer each month because even modest improvements in professional productivity can justify expensive subscriptions.
GC AI publicly lists an individual subscription at around $500 per month. Harvey and Legora primarily use enterprise arrangements with negotiated pricing, while Spellbook, CoCounsel, and other providers offer different product packages and commercial models.
Those contracts aren't directly comparable. Some tools focus on research, others on contract drafting or complete legal workflows. Enterprise agreements may include usage limits, integrations, onboarding, and support.
We can still calculate how much work a subscription needs to replace.
At $500 per month, a legal AI product costs $6,000 per lawyer annually. For a firm charging $300 per hour, that's equivalent to the gross revenue from 20 billable hours per year, or fewer than two hours per month.
For an internal legal department, the calculation is different. The relevant benefit is avoided outside counsel spending, improved staff capacity, or reduced operating costs.
The table below shows the gross billable-revenue equivalent at a hypothetical $300 hourly rate. It does not account for law-firm expenses or guarantee a positive return.
| Annual AI cost per lawyer | Hours at $300/hour | Hours per month |
|---|---|---|
| $600 | 2 | 0.17 |
| $1,200 | 4 | 0.33 |
| $2,400 | 8 | 0.67 |
| $3,600 | 12 | 1 |
| $6,000 | 20 | 1.67 |
| $12,000 | 40 | 3.33 |
| $24,000 | 80 | 6.67 |
The problem for premium software providers is that customers can now compare specialist legal products with general-purpose AI services costing far less. Charging hundreds of dollars monthly becomes harder unless the product offers better accuracy, access to trusted legal information, security, or workflows that cheaper tools cannot match.
Can legal AI companies stay profitable as AI gets cheaper?
Cheaper AI models should improve legal software margins, but competition could force vendors to pass much of those savings to customers.
Legal AI providers pay for model inference, document processing, infrastructure, support, and access to legal information. Many also employ substantial engineering and customer-success teams.
As model providers reduce inference prices, the cost of generating answers can fall. But modern legal AI products are also becoming more demanding. Complex workflows may require repeated searches, large document uploads, multiple model calls, and verification steps.
Thomson Reuters' August 2026 CoCounsel Legal release emphasized connected research, drafting, verification, and agentic workflows. Harvey has also invested in legal agents and integrated processes.
These features can make products more useful, although they may consume considerably more computing resources than a single question-and-answer interaction.
Consider a hypothetical subscription priced at $500 per month. If delivering the service costs $150, its gross margin is 70%. Reducing delivery costs to $75 raises that margin to 85%, assuming the selling price remains unchanged.
But if competing products force the subscription price down to $250, gross margin returns to 70%.
That's the squeeze. Infrastructure gets cheaper, but so do the alternatives customers can buy. A legal AI company might deliver a vastly better product in three years and still struggle to defend its original subscription price.
The strongest pricing defense is likely to come from deeply integrated legal workflows rather than access to language models alone.
If you want more recent data on this point, please see our latest legal AI market report.

When you build or invest in the legal AI market, you need clarity, not confusion. In our document detailing everything you need to know about legal AI, we always try to put numbers on and quantify whatever is usually vague and confusing.
Will law firms keep buying AI when their clients demand lower fees?
Law firms will continue paying for useful AI because clients are increasingly expecting it, even when they also demand cheaper legal services.
Thomson Reuters' 2026 research found that 77% of law-firm clients considered AI-enabled quality improvements very important or essential. Only 5% believed most or all of their providers were delivering those improvements.
That enormous gap puts firms in an uncomfortable position. Clients want better technology and better value, while law firms must invest in new software without necessarily charging more.
AI adoption is also becoming relevant to hiring. The same research found that 24% of law-firm professionals would reject a job opportunity if professional-grade AI tools were unavailable.
Those expectations give legal AI vendors more than one argument for selling subscriptions. Firms can use the technology to complete work faster, satisfy clients, and attract professionals who expect modern tools.
Still, subscriptions need to earn their place in the budget. When clients reduce fees, law firms will naturally become less willing to pay for unused licenses or products that duplicate existing systems.
We've already seen legal AI providers move beyond simple chat assistants toward tools embedded in research, drafting, and document management. Those integrations can make software more useful throughout the working day and harder to remove.
For startups, becoming part of the firm's daily workflow is a stronger business than selling an impressive assistant that lawyers open occasionally.
Could corporate legal teams become bigger AI customers than law firms?
Corporate legal departments could eventually spend more on legal AI than law firms because their financial incentive to automate routine work is much clearer.
A law firm sometimes earns less when a task takes fewer hours. An in-house legal team generally benefits when the same work gets done faster, especially if it can reduce external legal expenses.
Consider a company spending $400,000 annually on recurring contract-review work. If an AI-assisted internal team reduces those outside fees by 25%, the company saves $100,000. Even after paying $60,000 for software, it would save $40,000 before accounting for implementation and internal staffing costs.
That's an illustrative calculation, but real corporate deployments show that these applications are gaining traction.
Financial Times reporting on corporate legal AI described IAG using AI-enabled invoice reviews, Shell working on drafting and legal workflows, and Dentsu applying AI to contract information. IAG reported an 800% return on investment for its invoice-review application, although that result cannot be generalized to every legal AI system.
The economics become particularly attractive when technology helps internal teams handle work they would otherwise send to expensive outside counsel.
There is also a potentially much broader market among businesses that cannot afford large legal departments. Automation could make routine compliance reviews, contract management, and document preparation affordable to more companies.
However, the industry's largest vendors don't consistently disclose revenue separately for law firms and corporate legal customers. We can't yet show that in-house departments spend more overall.
Our bet is that corporate legal teams become one of the most important growth markets. They can capture the savings from automation directly, and that is a much simpler reason to buy software than trying to reconcile fewer working hours with a business built around charging for them.
If you want more recent data on this point, please see our latest legal AI market report.

In our report covering the legal AI market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Which legal jobs can AI actually replace today?
Legal AI can already automate important parts of contract review, document analysis, research, and due diligence, while complex legal judgment still requires substantial human involvement.
The products now on the market make that division increasingly visible. Spellbook concentrates on drafting and reviewing contracts in Microsoft Word. Harvey and Legora offer broader research, drafting, and document analysis workflows. CoCounsel combines AI assistance with established legal information services, while Relativity and Everlaw use AI for electronic discovery.
These applications share a useful characteristic: much of the work involves documents, defined procedures, and outputs that a lawyer can review.
For example, a system can compare hundreds of contracts against a company's preferred terms, flag unusual provisions, and prepare summaries. That can significantly reduce the first-pass workload, although lawyers remain responsible for judging the findings and deciding what action to take.
Complex litigation strategy and negotiations are different. The relevant facts may be incomplete, commercial objectives can change, and the best decision often depends on experience rather than a repeatable document process.
Accuracy also remains a major obstacle. A Stanford-led study published in the Journal of Empirical Legal Studies in 2025 reported hallucination rates exceeding 17% for evaluated legal research systems from LexisNexis and Thomson Reuters under its test conditions.
Those findings apply to the versions and tasks tested, rather than establishing an error rate for every legal AI product. Nevertheless, they show why professional review remains necessary.
We expect the greatest pressure on billable hours in document-heavy activities where AI can complete a large first pass and lawyers can verify the result efficiently. Highly specialized advice and unpredictable disputes will be harder to price as standardized automated services.
Can Harvey and Legora compete with Thomson Reuters and LexisNexis?
Harvey and Legora have built valuable positions in legal AI, but Thomson Reuters and LexisNexis may be their most dangerous long-term competitors.
The established providers have something startups cannot easily reproduce: decades of legal content, trusted research products, existing subscriptions, and relationships with major law firms.
Thomson Reuters owns Westlaw and Practical Law and has expanded CoCounsel into legal research, drafting, and agentic workflows. LexisNexis has developed Protégé within its legal information ecosystem.
Harvey and Legora are approaching the same market from the opposite direction. They started with AI-native products and are expanding into more of the processes lawyers use every day.
The distinction becomes particularly important when customers review software budgets.
A law firm already paying for Westlaw, Microsoft 365, and several specialist tools may resist adding another expensive subscription if its existing providers offer comparable AI capabilities.
General-purpose AI platforms create additional pricing pressure. As those systems improve at document analysis and research, vendors charging a large premium for similar features must prove why their products deserve it.
Harvey's investments in legal models and customer-specific intelligence, along with Legora's workflow integrations, show that both companies understand this challenge.
We wouldn't assume the winner will be the company with the best AI model. A firm that already controls legal research content and daily workflows has a huge distribution advantage. Startups need to become important enough in their customers' operations that replacing them with an incumbent's bundled AI product feels like a genuine downgrade.
If you want more recent data on this point, please see our latest legal AI market report.

Your time is limited. In our research about legal AI tools, we put numbers on each part of the market, so you can see where it makes sense to focus.
Could legal AI make law firms cheaper without making software companies rich?
Legal AI could save the legal industry billions while leaving software vendors with a surprisingly small share of those savings.
The reason is competition. When multiple suppliers can automate similar tasks, clients have little incentive to let one provider capture most of the value.
Imagine software reduces the annual cost of a certain category of legal work from $10 million to $6 million. That creates $4 million in potential savings. Some may increase law-firm profits, some may flow to corporate clients through lower fees, and some may be captured by software suppliers.
How that money is divided depends on bargaining power, product quality, switching costs, and the availability of alternatives.
Clio's 2025 research found that extensive AI users were already experimenting with different pricing responses, including higher fees, lower fees, and new AI-related charges. Law firms clearly aren't all responding to automation in the same way.
Software suppliers face a similar problem. Harvey, Legora, CoCounsel, LexisNexis, Spellbook, and general-purpose AI companies are competing for overlapping budgets. Better technology may increase the value created while also making individual features easier to reproduce.
Pricing models are changing too. Legora's move toward consumption-based pricing for Agent Pro in 2026 suggests that advanced agent workflows may increasingly be charged according to usage rather than through unrestricted subscriptions.
That could help vendors recover the costs of demanding tasks, but customers will expect the extra spending to produce measurable results.
We see the biggest long-term risk here. Legal AI adoption can keep accelerating while prices for common capabilities decline. Vendors with distinctive workflows and deep integrations will have a much better chance of keeping a meaningful share of the savings.
Are Harvey and Legora worth their multibillion-dollar valuations?
Harvey and Legora could build very large businesses, but their reported valuations require substantial recurring revenue and strong margins that public disclosures haven't yet demonstrated.
Harvey's reported $15.5 billion valuation provides a useful test.
If the company eventually generates $500 million in annual recurring revenue, that valuation represents 31 times ARR. At $1 billion, the multiple falls to 15.5 times. At $2 billion, it falls to 7.75 times.
These are hypothetical calculations, not Harvey's reported financial results.
We can also estimate how many paying users a legal AI provider would need to reach $1 billion in recurring revenue.
At an average realized subscription price of $6,000 annually, the company would need approximately 167,000 paying equivalent seats. At $12,000 annually, it would need roughly 83,000.
Those numbers aren't impossible for software used across major law firms, corporate legal departments, and international markets. But reaching them would require broad deployment, substantial customer spending, and strong retention.
The question becomes whether premium pricing can survive growing competition from established legal software providers and increasingly capable general-purpose AI systems.
Investors are clearly paying for the possibility that a handful of legal AI companies become central platforms for professional legal work. Whether those platforms can generate the profits needed to justify their valuations is still an open question.

In our market report about legal AI tools, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Can legal AI make money if it kills the billable hour?
Yes. Legal AI can become a highly profitable business even if it eliminates a large share of traditional billable hours, because companies will pay for faster, reliable legal work regardless of how lawyers charge their clients.
The commercial evidence is already substantial. Major law firms are adopting specialized platforms, large corporations are buying legal automation, and established providers such as Thomson Reuters and LexisNexis are investing heavily in AI products. Meanwhile, hourly billing remains widespread despite years of gradual movement toward fixed fees.
The billable hour will probably survive for complex litigation, unpredictable disputes, and specialized advice. But contract review, legal research, due diligence, and other repeatable tasks are becoming much harder to price according to time spent.
The consequences can be very different depending on who buys the software. Law firms can improve productivity and handle more work. Corporate legal teams can reduce outside counsel expenses. AI vendors can collect recurring payments from both groups.
The bigger question is how much of the savings software companies will keep. Competition between Harvey, Legora, CoCounsel, LexisNexis, and general-purpose AI tools could make routine capabilities much cheaper, even as their usage grows.
That creates a fairly clear dividing line between the likely winners and losers. Vendors offering basic drafting and summarization will struggle to defend high prices. Companies deeply embedded in legal research, document management, verification, and complete workflows have a stronger chance of building durable, profitable businesses.
Our judgment is that legal AI's business opportunity survives the decline of hourly billing and may actually benefit from it. What remains uncertain is whether today's highest-valued startups can capture enough of that opportunity to justify their valuations.
The billable hour can shrink substantially while legal AI revenues keep growing. The harder challenge for AI companies is making sure those revenues turn into lasting profits.
If you want more recent data on this point, please see our latest legal AI market report.
Our methodology
This analysis examines whether legal AI can build a profitable software market as automation reduces the time lawyers can bill. We approached the question through six economic dimensions: actual changes in billing practices, law-firm productivity and profitability, corporate legal demand, software pricing and delivery costs, competitive positioning, and the financial scale needed to justify startup valuations.
For each dimension, we collected recent, measurable evidence, selected the most relevant observations, assessed what each one demonstrated, and aggregated the findings to reach stronger conclusions. Our evidence includes legal-industry surveys, law-firm financial indicators, company announcements, commercial adoption figures, product pricing, independent reliability studies, and financing disclosures. We prioritized primary reporting and attributable data over unsourced market predictions.
We used Thomson Reuters and Clio research to examine the difference between rapid AI adoption and slower changes in legal billing. We assessed law-firm demand separately from individual productivity gains, since hours saved on particular tasks do not automatically translate into falling industry revenue. Historical billing data also provides a pre-AI baseline for understanding how much of the move toward flat fees was already underway.
To evaluate profitability, we distinguished the economics of law firms, corporate legal departments, and software providers. Our contract-review examples, subscription break-even calculations, gross-margin scenarios, and revenue-multiple estimates are illustrative calculations based on explicitly stated assumptions. They test what must happen for a business model to work; they are not reported operating results for individual companies.
For startup valuations and commercial traction, we relied on announced financing, enterprise deployment figures, and publicly available pricing. We treated customer adoption, investment valuations, recurring revenue potential, and actual profitability as separate measures. For competition and product defensibility, we compared AI-native vendors with established legal information providers, paying particular attention to trusted content, verification, integrations, and the economics of increasingly sophisticated workflows.
We also examined conflicting evidence across these dimensions. High AI adoption can coexist with resilient legal-service demand; cheaper inference can coexist with falling software prices; and very large productivity savings may ultimately benefit corporate clients more than the vendors providing the technology. Our final assessment reflects the convergence of these different observations, with greater weight given to demonstrated commercial behavior than to technological forecasts.
Key sources used for this analysis include: Thomson Reuters' 2026 Future of Professionals legal research, Clio's 2025 Legal Trends Report, Clio's mid-sized law-firm research, and Thomson Reuters' Q4 2025 Law Firm Financial Index for adoption, pricing, and legal-service demand.
For company economics and competitive developments, we used Harvey's September 2026 financing announcement, Legora's Series D announcement, White & Case's Legora-related announcement, GC AI's published pricing, Thomson Reuters' CoCounsel Legal product announcement, and LexisNexis' Protégé platform announcement.
For practical applications and reliability, we drew on Relativity's reporting on an independent aiR for Review study, legal AI reliability research published in the Journal of Empirical Legal Studies, Financial Times reporting on corporate legal AI adoption, and Thomson Reuters' analysis of legal AI evaluated against real legal work. These sources help distinguish observable deployment and task-level performance from broader claims about full professional replacement.

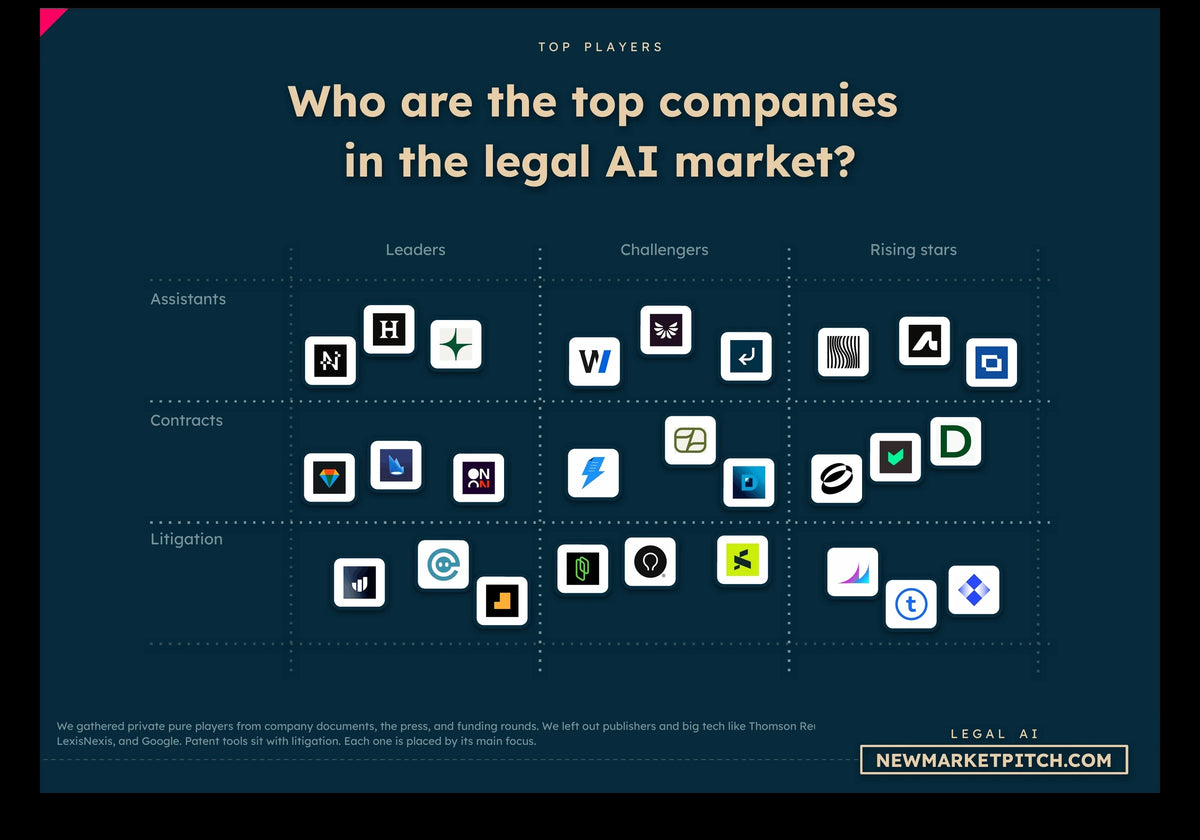
In our document detailing everything you need to know about legal AI, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us