Is the legal AI market big enough for all these startups?
Whether you're building or investing in the legal AI market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The legal AI market is big enough for several major platforms and many successful specialists, but not for every well-funded startup to become a billion-dollar business. Demand is growing rapidly, yet competition for the most valuable customers is already intense.
Harvey, Legora, Clio and GC AI carried more than $22 billion in combined disclosed financing valuations. Those valuations reflect enormous expectations, while comparable disclosures still do not establish a standalone $10 billion annual legal AI revenue market.
The existing legal technology industry provides a substantial spending base. Thomson Reuters' Legal Professionals division and RELX's Legal division generated more than $5 billion in combined annual revenue in 2025, although much of that comes from established research and software products rather than generative AI.
Adoption is moving faster than specialized software purchasing. An 8am survey found that 69% of legal professionals personally used generative AI for work, while only 34% of surveyed firms had adopted legal-specific AI platforms. Startups must turn widespread experimentation into recurring enterprise spending.
The economics become demanding at scale. At $3,000 per user annually, a legal AI company needs approximately 333,334 paying users to generate $1 billion ARR. Reaching that level through premium law-firm subscriptions alone would be extremely difficult.
Legora illustrates the valuation challenge. Its reported $150 million ARR makes it a fast-growing software business, but its $5.6 billion April 2026 valuation represents approximately 37 times that subsequent revenue run rate. A hypothetical $10 billion valuation would imply roughly 67 times the same figure.
Incumbents are holding up better than a disruption narrative would suggest. Thomson Reuters and RELX reported 8% and 9% underlying legal-business growth respectively, even as legal AI startups expanded. Many law firms are adding AI platforms without abandoning established research subscriptions.
General-purpose AI is squeezing the lower end of the market. Drafting, summarization and basic document questions are becoming harder to monetize independently when ChatGPT, Claude and Microsoft Copilot already perform much of that work. Specialized vendors need to own harder workflows, not just provide a better interface.
The strongest opportunities extend beyond general-purpose assistants for large law firms. Contract management, litigation preparation, corporate legal operations and practice management serve different buyers and budgets. A specialist can build a valuable business without winning the entire legal department.
The biggest unresolved question is who captures the productivity gains. Lawyers report saving hours, but firms rarely measure AI returns systematically, and clients may demand lower legal bills. Cheaper legal services could ultimately expand the market through additional work, but that expansion remains less proven than the savings from automating existing tasks.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

Your time is limited. In our report covering the legal AI market, we put numbers on each part of the market, so you can see where it makes sense to focus.
Why are investors putting so much money into legal AI startups?
Legal AI startups are attracting billions because some are growing exceptionally fast, although their valuations already assume they will capture a much larger share of the legal software market.
Harvey raised $200 million at an $11 billion valuation in March 2026. Legora secured $550 million at a $5.55 billion valuation that same month, followed by another $50 million at a $5.6 billion valuation in April. By the second quarter, Legora had reportedly reached $150 million in annual recurring revenue (ARR), up from $100 million shortly before, and attracted interest in another financing above a $10 billion valuation.
Other companies are attracting substantial capital. Clio raised $500 million at a $5 billion valuation in November 2025 while completing its $1 billion acquisition of vLex. GC AI raised $60 million at a $555 million valuation after growing from $1 million to more than $10 million in ARR in less than a year.
That puts Harvey, Legora, Clio and GC AI at more than $22 billion in combined valuations, using their disclosed financing valuations. And these companies are competing for at least some of the same customers, alongside established providers such as Thomson Reuters and LexisNexis.
Investors are betting that legal AI will become an essential part of how lawyers work. The risk is that several startups are being valued as future market leaders in a market that may only have room for a few.
How big is the legal AI market today?
The legal AI market is already generating hundreds of millions in recurring revenue for individual companies, but we still cannot reliably establish how much businesses spend on legal AI worldwide.
One reason is that legal AI spending is mixed into established legal software subscriptions. Thomson Reuters reported $2.87 billion in revenue from its Legal Professionals division in 2025. RELX reported £1.81 billion from its Legal division, primarily LexisNexis Legal & Professional. Together, those businesses generated more than $5 billion annually when converted into dollars, but much of that revenue comes from legal research, information products and software that existed before generative AI.
Newer providers give us a clearer view of AI demand. Legora reportedly reached $150 million ARR in the second quarter of 2026. GC AI exceeded $10 million ARR by November 2025. Clio surpassed $500 million ARR in May 2026 across its expanded business, including vLex, although that figure includes substantial non-AI revenue.
We cannot simply add these figures together and call the result the legal AI market. Doing so would mix established legal software with AI products and potentially double-count acquired revenue.
For perspective, a $10 billion annual legal AI market could theoretically support ten companies earning $1 billion each, or fifty earning $200 million each. Those are very different competitive outcomes.
Legal AI already has substantial commercial demand. What the industry has yet to demonstrate through comparable company disclosures is a standalone $10 billion annual revenue pool.

In our research about legal AI tools, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Are lawyers actually adopting legal AI that quickly?
Legal AI adoption is growing remarkably fast, although lawyers are adopting AI tools much faster than law firms are buying specialized platforms.
The 2026 Legal Industry Report from 8am found that 69% of surveyed legal professionals personally used generative AI for work, up from 31% in the previous report. Yet only 46% of surveyed firms had implemented general-purpose AI, while 34% had adopted legal-specific AI platforms.
The State Bar of Texas found a similar jump. Attorney AI usage increased from 30% in its 2024 survey to 62% in 2026. Among lawyers using AI, 63% reported using ChatGPT, while 30% reported using Westlaw or CoCounsel.
These surveys cover different populations, so we should not combine their percentages. But both show the same thing: many lawyers have already made AI part of their work, often without waiting for their firms to introduce specialized products.
That leaves room for enterprise legal AI sales to grow. It also means startups cannot treat every lawyer using ChatGPT as a potential subscriber to another expensive platform.
How much money can legal AI startups make from each lawyer?
Premium legal AI software can generate several thousand dollars per lawyer annually, which makes large recurring-revenue businesses possible. But reaching $1 billion in revenue requires an enormous number of paying users, even at high subscription prices.
Enterprise prices are often negotiated privately. Published comparisons put specialized legal AI subscriptions anywhere from relatively inexpensive add-ons to products costing thousands of dollars per user annually. We therefore use three hypothetical annual prices rather than pretending there is one reliable market average.
At $3,000 per year, a legal AI startup needs around 33,334 paying users to reach $100 million ARR. At $6,000, it needs approximately 16,667. Reaching $1 billion would require about 333,334 users at $3,000, or 166,667 at $6,000.
That scale is difficult to achieve by selling exclusively to lawyers at large international firms. Vendors need broader customer coverage, much higher spending from enterprise accounts, or products used by employees beyond the legal department.
| Paying users | $1,200/year | $3,000/year | $6,000/year |
|---|---|---|---|
| 25,000 | $30M | $75M | $150M |
| 50,000 | $60M | $150M | $300M |
| 100,000 | $120M | $300M | $600M |
| 250,000 | $300M | $750M | $1.5B |
| 500,000 | $600M | $1.5B | $3B |
| 1 million | $1.2B | $3B | $6B |
| 2 million | $2.4B | $6B | $12B |

In our market report about legal AI tools, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are Harvey and Legora growing fast enough to justify their valuations?
Harvey and Legora are proving that enterprise legal AI can become a large software business very quickly, but their valuations leave little room for growth to slow down.
Legora reportedly increased ARR from $100 million to $150 million over a short period in 2026. That represents 50% growth in its annualized recurring-revenue base, although it does not mean the company collected 50% more revenue during that period.
At $150 million ARR, Legora's $5.6 billion April valuation works out to approximately 37 times its subsequently reported revenue run rate. A $10 billion valuation would represent roughly 67 times that same ARR.
To reach $1 billion ARR, Legora would need to grow about 6.7 times from the reported $150 million level.
Harvey's $11 billion valuation presents a similar question, although its financing announcement did not disclose an independently audited revenue figure that would allow a reliable comparison.
Neither valuation can be explained by ordinary legal software growth. Investors expect Harvey and Legora to become platforms used across research, drafting, contract analysis and other daily legal workflows. Whether both can reach that scale while competing against each other and established providers remains unresolved.
If you want more recent data on this point, please see our latest legal AI market report.
Can Harvey and Legora really take customers from Thomson Reuters and LexisNexis?
Harvey and Legora can win legal work from Thomson Reuters and LexisNexis, but replacing their established research businesses will be considerably harder than winning individual AI workflows.
Thomson Reuters generated $2.87 billion in Legal Professionals revenue in 2025, with 8% organic growth despite a reported decline largely caused by portfolio changes. RELX's Legal division generated £1.81 billion, with 9% underlying growth.
Neither incumbent was experiencing a broad collapse while Harvey and Legora expanded. Both continued growing their underlying businesses.
Thomson Reuters already offers CoCounsel alongside Westlaw. LexisNexis combines Lexis+ AI and Protégé with its existing research content and Shepard's citation analysis. Both have long-standing customer relationships, proprietary information and established procurement channels.
A law firm can purchase Harvey for drafting and complex workflows while keeping Westlaw for research. It can also deploy Legora without abandoning LexisNexis.
This gives startups a realistic path into major firms, but taking over an entire legal technology budget is a much bigger challenge.

In our document detailing everything you need to know about legal AI, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Could ChatGPT, Claude and Microsoft Copilot make legal AI startups unnecessary?
ChatGPT, Claude and Microsoft Copilot are already making basic legal AI features harder to sell separately. Startups charging premium prices for ordinary drafting, summarization or document questions face increasing competition from general-purpose tools.
The 2026 Texas attorney survey found that 63% of AI-using lawyers used ChatGPT. That is a substantial distribution advantage for OpenAI because lawyers are familiar with the product before their firms formally select legal AI software.
Anthropic has also introduced legal-oriented capabilities in Claude, while Microsoft can distribute Copilot through software that many legal teams already use.
Specialized products still offer advantages for work involving confidential documents, firm-wide permissions, verified sources and complicated legal workflows. Spellbook integrates into Microsoft Word, while Harvey and Legora focus on tasks that involve several documents, steps and decisions.
But the technical gap is narrowing in some areas. A feature that once justified an expensive legal AI subscription may become available inside a general-purpose assistant or an existing software package.
Premium pricing looks much safer for products that complete difficult legal workflows. Standalone tools built around generic model capabilities will have a harder time defending their fees.
If you want more recent data on this point, please see our latest legal AI market report.
Are all these legal AI startups chasing the same law firms?
The biggest legal AI startups are competing for many of the same large law firms, creating a much more crowded market than their individual growth figures suggest.
Harvey and Legora both sell broad legal research, drafting, analysis and workflow products to major law firms. Their customer announcements include prominent firms such as Ashurst, White & Case, Cleary Gottlieb and Goodwin. Thomson Reuters and LexisNexis are targeting many of those same organizations with their own AI offerings.
The overlap becomes more important as vendors expand beyond their original products. A firm might initially purchase one platform for research and another for document analysis. But if both eventually handle research, drafting, diligence and internal knowledge management, the reason for paying for both becomes less obvious.
Corporate legal departments are attracting another group of competitors. GC AI reported more than 1,000 company customers in November 2025. LegalOn exceeded 9,000 customers worldwide by August 2026. Spellbook reported serving more than 5,000 legal teams across 80 countries.
Those customer counts cannot be added together because organizations may subscribe to several tools.
There is room for competing products, especially when they solve different problems. The difficult question is how many broad legal AI platforms a large customer will continue paying for once their features increasingly overlap.

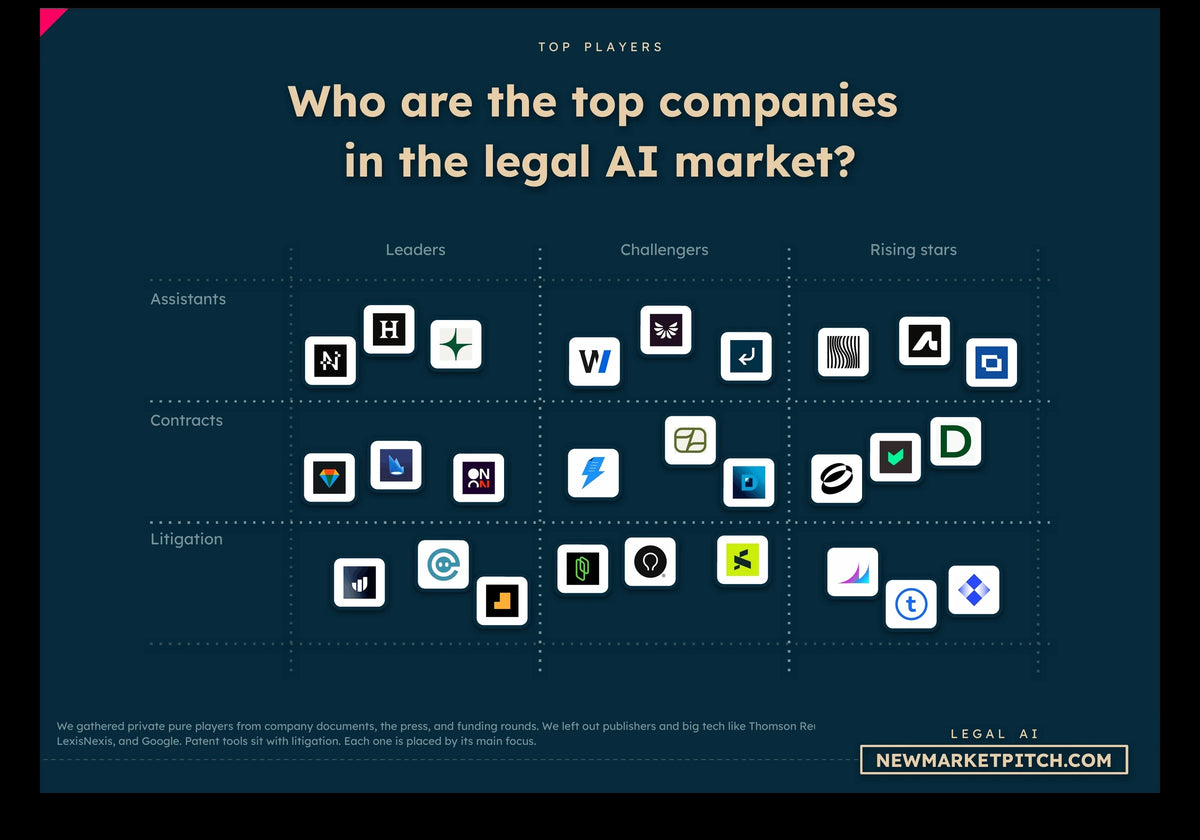
In our report covering the legal AI market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is corporate legal AI a bigger opportunity than selling to law firms?
Corporate legal AI could eventually reach more organizations than premium law-firm software, but we cannot yet establish that corporate legal departments represent a larger revenue market.
LegalOn illustrates how quickly this customer base can grow. The company reported more than 7,000 customers in July 2025, reached 8,000 in February 2026 and exceeded 9,000 by August. Its U.S. and U.K. business had also quadrupled over the year leading up to July 2025.
GC AI followed a different route, building an assistant focused on in-house counsel. By November 2025, the company had more than $10 million in ARR across over 1,000 company customers.
These products can serve legal teams in technology, manufacturing, finance, healthcare and many other industries. Demand is far less concentrated in prestigious law firms.
However, corporate legal departments often employ relatively few lawyers compared with the largest international firms. A corporation generating billions in revenue might have only dozens of in-house lawyers.
That limits traditional per-seat sales. Corporate-focused legal AI companies have a stronger growth path when their products also manage contracts, internal requests and workflows involving sales, procurement or compliance teams.
Which types of legal AI startups have the best chance of surviving?
Legal AI startups focused on recurring, expensive workflows have the strongest chance of building independent businesses. Contract management, litigation preparation and legal operations offer more room for differentiation than basic document summarization.
Several different markets are already developing. Harvey and Legora are competing to become broad enterprise platforms. Spellbook and LegalOn concentrate heavily on contract work. EvenUp and Supio target litigation-related processes, while Clio combines practice management, research and AI.
Those differences are important because the software budgets, buyers and technical requirements vary.
A litigation platform that saves substantial time preparing case documents is solving a different problem from a contract assistant used by an in-house team. Both may succeed without becoming the default AI system for every lawyer.
The most vulnerable startups are those selling features that larger platforms can reproduce and distribute through subscriptions customers already have.
| Legal AI segment | Representative vendors | Main source of revenue |
|---|---|---|
| Enterprise legal AI | Harvey, Legora | AI platforms, workflows and agents |
| Legal research | Thomson Reuters, LexisNexis, vLex | Research subscriptions and AI upgrades |
| Contract drafting | Spellbook, LegalOn | Drafting, redlining and reviews |
| Contract management | Ironclad, Icertis | Contract workflows and automation |
| In-house legal assistants | GC AI, LawGeex | Research and legal department workflows |
| Litigation discovery | Relativity, Everlaw | Document discovery and case preparation |
| Plaintiff-side litigation | EvenUp, Supio | Case analysis and demand preparation |
| Law firm operations | Clio, 8am | Practice management, billing and operations |
If you want more recent data on this point, please see our latest legal AI market report.

Our research about legal AI tools gets updated several times a month, so you always get the latest view of where things stand.
Can contract review alone create billion-dollar legal AI companies?
AI contract review can support substantial software businesses, but companies relying exclusively on reviewing contracts will face stronger pricing pressure as the technology becomes widely available.
Spellbook provides an unusually concrete measure of usage. The company reported serving more than 5,000 legal teams across 80 countries. An Anthropic case study described approximately 530,000 contract reviews processed monthly through Claude-powered agents, equivalent to about 6.36 million reviews annually if that pace continues.
This volume suggests that contract AI is becoming part of daily legal work rather than remaining an occasional experiment. It does not tell us how much revenue each review generates, since customers may pay through subscriptions rather than per-document fees.
LegalOn offers another useful comparison. Its customer count rose from more than 7,000 in July 2025 to over 9,000 in August 2026. The company had raised $200 million cumulatively by July 2025 and was expanding beyond contract review into broader workflows.
That expansion is understandable. Ironclad and Icertis already sell systems covering contract creation, negotiation, approvals and ongoing management. AI review is increasingly one feature inside a wider contracting process.
A specialized vendor can still build a large business by doing contract review exceptionally well. But controlling the surrounding workflow gives it more ways to charge customers and makes replacement harder.
Can legal AI make money if it reduces lawyers' billable hours?
Legal AI can become a profitable software market even if lawyers bill fewer hours, although law firms will have to rethink how they charge clients.
Thomson Reuters' 2026 Future of Professionals research found that 71% of surveyed in-house legal professionals expected outside firms to change their commercial models as AI usage increased. Only 28% of law firms reported changing their pricing structures in response.
The same research found that 77% of clients considered AI-driven quality improvements very important or essential, yet only 5% said they received those improvements from most or all their providers.
Consider a legal task that previously required ten billable hours and now takes three. A firm charging entirely by the hour could lose associated revenue unless it uses the freed capacity for other paying work. A firm charging a fixed fee may retain a larger share of the productivity gains.
For AI vendors, the opportunity is to capture some of the money customers save through faster and cheaper legal work. However, corporate clients will increasingly expect lower bills as these efficiencies become widespread.
The commercial outcome depends on who ultimately keeps the savings. Legal software providers have an opportunity to capture part of that value, but law firms and clients will also fight for their share.

In our market report about legal AI tools, you will always find fresh funding data, taken straight from our own verified funding database.
Are law firms saving enough money to justify expensive legal AI subscriptions?
Many lawyers are already saving enough time to justify legal AI subscription prices on paper, but relatively few organizations are measuring whether those savings translate into real financial returns.
The 2026 Legal Industry Report from 8am found that 38% of respondents saved one to five hours per week using generative AI. Another 14% reported saving six to ten hours.
Suppose a lawyer saves three hours each week over 46 working weeks. At a hypothetical internal labor cost of $100 per hour, that represents $13,800 in annual working capacity, considerably more than a $3,000 or $6,000 AI subscription.
The calculation becomes less attractive if lawyers spend considerable time checking outputs, if the tool is rarely used, or if recovered hours cannot be put to productive use.
Thomson Reuters' 2026 AI in Professional Services research found that just 18% of surveyed professionals said their organizations tracked AI return on investment. Another 40% did not know whether ROI was measured.
For startups, this creates a problem when early enthusiasm turns into formal procurement reviews. A law firm may enjoy using an AI assistant but still cancel the subscription if it cannot demonstrate faster case preparation, lower expenses or greater billable capacity.
Vendors that can show measurable financial gains should have an easier time defending renewals and increasing prices.
Will legal AI end up with just a few big winners?
Legal AI will probably consolidate around a few large platforms, while specialized companies continue serving contract, litigation and practice-management needs.
The first signs of consolidation are already visible. Clio completed its approximately $1 billion acquisition of vLex in 2025, combining legal research and AI with an established practice-management business.
Clio subsequently reported more than $500 million in ARR across its expanded operations in May 2026. The acquisition gives the company more opportunities to sell research, AI and workflow software to the same customer base.
Thomson Reuters and LexisNexis can pursue a similar approach through existing products and distribution. Harvey and Legora are trying to build newer platforms that handle an increasing share of legal work.
But the legal profession remains fragmented. A small U.S. litigation practice, a multinational law firm, a European corporate legal department and a specialist intellectual property practice have very different requirements.
One platform is unlikely to serve all of them equally well.
Broad legal AI systems will likely become more concentrated, while specialized companies retain customers by solving problems those platforms handle less effectively.
If you want more recent data on this point, please see our latest legal AI market report.

In our document detailing everything you need to know about legal AI, we look at what the winners do differently, so you can learn from the best instead of guessing.
Will law firms keep paying for legal AI after the initial excitement?
Legal AI subscriptions will face tougher renewal tests as firms start measuring actual usage, reliability and financial returns. Rapid adoption does not guarantee that every startup will retain its customers.
The 2026 Legal Industry Report from 8am found that 46% of respondents considered data security an obstacle to AI adoption, 42% cited ethical concerns, 39% privilege issues and 39% lack of trust in results.
The report also found that 54% said their firms had provided no responsible-AI training and had no plans to do so. Thomson Reuters separately reported that 34% of surveyed law firm professionals were using AI tools their organizations had not authorized.
Many organizations are still learning how to deploy AI consistently. Some subscriptions may initially be purchased by enthusiastic teams before firms understand which tools are most useful.
Harvey's March 2026 financing announcement highlighted its investment in embedded legal engineering teams and reported more than 25,000 custom agents running on its platform. That shows how much customization and support enterprise deployments can involve.
The long-term test will be whether customers keep using those workflows after implementation, and whether vendors can support more customers without proportional increases in engineering and service costs.
Are legal AI startup valuations already too high?
Some legal AI startup valuations are becoming difficult to justify without assuming that the leading companies will grow into billion-dollar revenue businesses.
Legora provides the clearest numerical example. Its reported $150 million ARR represents a rapidly growing company, but even reaching $1 billion ARR would require another 6.7-fold increase.
At $1 billion ARR, Legora's $5.6 billion April valuation would represent 5.6 times revenue, compared with approximately 37 times its subsequently reported $150 million run rate. The company therefore needs major growth for the valuation to look conventional by mature software standards.
Harvey's $11 billion valuation also implies substantial expectations, although comparable financial disclosure is too limited for us to calculate a reliable revenue multiple.
The broader concern becomes clearer when we compare hypothetical market sizes with the number of companies each could support.
| Annual legal AI revenue pool | Companies at $25M ARR | Companies at $100M ARR | Companies at $500M ARR |
|---|---|---|---|
| $2B | 80 | 20 | 4 |
| $3B | 120 | 30 | 6 |
| $5B | 200 | 50 | 10 |
| $8B | 320 | 80 | 16 |
| $10B | 400 | 100 | 20 |
| $15B | 600 | 150 | 30 |
| $20B | 800 | 200 | 40 |
Each column is a separate mathematical scenario in which companies of that size divide the entire annual revenue pool. The columns cannot be added together, and the scenarios exclude the share captured by incumbents. The market sizes are hypothetical, not measured forecasts.

If you build or invest in the legal AI market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Could cheaper legal services make the legal AI market much bigger?
Cheaper legal services could create additional demand for legal AI by making more legal work affordable, but we still have limited evidence showing how much entirely new spending AI is generating.
Today, companies can review more contracts internally, small law firms can prepare documents faster, and litigation teams can process larger amounts of material without increasing staff at the same rate.
There are plausible opportunities beyond existing legal budgets. Businesses might review agreements they previously ignored, perform more frequent compliance checks or obtain legal assistance for relatively minor problems that once cost too much to address.
The adoption figures are encouraging. Spellbook has reported hundreds of thousands of monthly contract reviews, and LegalOn has expanded to thousands of organizational customers. Yet neither figure tells us how much of that work would otherwise have gone undone.
For now, the clearest commercial opportunity comes from making existing legal work faster and capturing part of the money spent on it.
An additional market created by newly affordable legal services could become substantial, but we would need evidence of incremental work volumes, new paying customers and spending that did not previously exist.
Is the legal AI market big enough for all these startups?
The legal AI market is big enough for several major platforms and many successful specialists, but far too many startups are competing to become the same kind of billion-dollar business.
The demand is real. Lawyers are adopting AI rapidly, leading startups have reached substantial recurring revenue, and established providers continue reporting strong underlying growth. Contract-focused companies are also demonstrating that the opportunity extends beyond a handful of prestigious law firms.
But the revenue available to each company is less impressive than the industry's headline valuations might suggest.
The established legal software market already has powerful incumbents. Harvey and Legora compete for overlapping enterprise workflows. General-purpose AI providers are making basic features cheaper, while corporate buyers are starting to question how much additional software they need.
The market also contains very different opportunities. A litigation startup solving an expensive, specialized problem can become a highly successful business without needing hundreds of thousands of users. A general-purpose legal AI platform seeking several billion dollars in annual revenue faces a much harder challenge.
We expect a few companies to become dominant legal AI platforms, several others to grow into valuable specialized businesses, and many overlapping vendors to be acquired or disappear.
The biggest uncertainty is how much entirely new legal work AI will create. If falling costs unlock a much larger volume of legal services, the revenue opportunity could exceed what existing software budgets suggest. So far, that expansion has not been measured convincingly enough to support every ambitious valuation.
The legal AI market has plenty of room for strong companies. It does not have room for every well-funded startup to become the next Harvey, Legora or Clio.
If you want more recent data on this point, please see our latest legal AI market report.

When you build or invest in the legal AI market, you need clarity, not confusion. In our research about legal AI tools, we always try to put numbers on and quantify whatever is usually vague and confusing.
Our methodology
This analysis examines whether the legal AI market can support its growing number of startups, particularly companies pursuing billion-dollar revenue businesses. We assess the commercial opportunity through reported revenue, financing valuations, customer adoption, established legal software spending, competitive overlap and the economics of legal work.
We structured the research around six dimensions: market economics, demand and adoption, competitive dynamics, revenue potential, commercial sustainability and market structure. For each dimension, we collected recent company announcements, financial disclosures, original surveys and product usage data, compared the observations, and assessed what they established. We then aggregated those findings to identify patterns supported by several independent measures rather than relying on individual fundraising headlines.
We separate legal AI revenue from the wider legal technology industry. Thomson Reuters' Legal Professionals revenue, RELX's Legal division revenue and Clio's expanded ARR provide evidence of substantial legal software spending, but include existing research, practice-management and information products. Legora's and GC AI's disclosed recurring-revenue figures provide more direct indications of specialized AI demand. We also distinguish reported ARR from recognized revenue and financing valuations from operating performance.
For adoption, we compared original research from 8am, the State Bar of Texas and Thomson Reuters. Individual AI usage, firm-wide implementation, legal-specific platform adoption and unauthorized tool usage measure different behaviors. We considered these separately when assessing the potential conversion of professional AI usage into paid enterprise subscriptions, as well as the operational barriers that might affect renewals.
To test revenue potential, we modeled annual subscription prices of $1,200, $3,000 and $6,000 across different paying-user counts. We also modeled hypothetical annual legal AI revenue pools of $2 billion to $20 billion against different company ARR levels. These are arithmetic scenarios rather than market forecasts. Their purpose is to show the customer penetration and revenue concentration implied by different business ambitions, without assuming that every lawyer will purchase a specialized subscription.
Our assessment of commercial sustainability combines reported contract-processing activity, customer counts, time savings, AI return-on-investment measurement, enterprise deployment requirements and changing legal billing practices. We also compare broad platforms with specialist providers across research, contracting, litigation and legal operations. Particular attention goes to whether startups control recurring workflows, can defend pricing against incumbents and general-purpose AI providers, and can capture a meaningful share of the productivity gains their software creates.
Key sources include Harvey's March 2026 financing announcement, Legora's Series D announcement, Clio's vLex acquisition and financing disclosure, Clio's $500 million ARR announcement, GC AI's financing and growth disclosure, Thomson Reuters' FY2025 financial results, and RELX's March 2026 investor overview.
For adoption, productivity and the economics of legal work, we used the 8am 2026 Legal Industry Report, 8am's AI adoption analysis, the State Bar of Texas 2026 AI Survey, Thomson Reuters' Future of Professionals 2026 legal research, Thomson Reuters' 2026 AI in Professional Services Report, the Clio Legal Trends Report and Clio's mid-sized law firm research. Product adoption and workflow activity were informed by LegalOn's customer disclosures, LegalOn's company information and Anthropic's Spellbook case study.
The conclusions draw on the combined evidence of commercial traction, professional adoption, incumbent resilience, product differentiation, customer economics and the scale required to support leading startup valuations. Where the article discusses possible market concentration or additional demand created by cheaper legal services, those findings are our interpretation of the observed developments rather than externally published market-size estimates.

A good product starts with a real problem. In our market report about legal AI tools, we show you the ones customers still live with.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us