What are the current funding trends in AI SOC?
Whether you're building or investing in the AI SOC market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
AI SOC funding is becoming larger but more selective this year. We track 36 deals and at least $1.3B in disclosed capital year to date, compared with 38 deals and at least $1.1B at the same point last year. TENEX.AI has the largest financing this year, a $250M Series B in March 2026.
The amount of disclosed capital is up 13%, while deal count is down 5%. Investors are spending more on fewer transactions.
The smaller-round market tells a different story. Excluding rounds above $50M, financing is down 42% against the same period last year.
At the same time, the median disclosed round rose from $12M to $25M. Investors are writing larger typical checks even as fewer companies complete transactions.
Large financings explain much of that combination. There are 8 deals above $50M this year to date, compared with 2 at the same point last year.
The stage mix is still young. Seed remains the most common stage, while a handful of Series B rounds take an unusually big slice of the money.
The biggest recent deals span different products. Managed AI security operations, agentic orchestration, investigation platforms and detection tools have each attracted major rounds.
The geography is changing as well. Israel has a greater share of deals, while the United States remains the main location of disclosed capital.
Companies that raise again are doing it sooner, but the lead investors are spread out across many firms.
Huge rounds are lifting this year's AI SOC total while ordinary funding gets harder. Investors are still active, but funding is far from evenly available.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the AI SOC market, you will always find fresh funding data, taken straight from our own verified funding database.
All funding deals in the AI SOC market over the last years
Below is the table listing all the deals. You can find our methodology at the end of this page.
If you want a deeper understanding of the market and its current dynamics, get our AI SOC market report.
| Company | Category | Date | Stage | Deal size | What they do | Region | Lead investors | Country | Rank |
|---|---|---|---|---|---|---|---|---|---|
| Daylight Security | AI-First Managed SOC | November 2026 | Series B | $80M | Hybrid AI and human cyber defense | North America | Goldman Sachs Alternatives | United States | |
| Brava Security | Detection Engineering | November 2026 | Seed | $15M | Multi-agent security operations platform that generates attack telemetry, validates detection coverage, and rewrites SIEM detections. | Middle East | F2 Venture Capital, Pitango | Israel | |
| CyberKord | Incident Response Automation | November 2026 | Seed | ~$3.1M | AI platform that investigates security alerts, simulates remediation in a digital twin, and autonomously contains or resolves incidents across existing security tools. | Europe | 360 Capital | Italy | |
| Mave | SOC Copilots | October 2026 | Series A | $28M | Agentic enterprise security operations platform | Middle East | Red Dot Capital Partners | Israel | |
| Mave | SOC Copilots | October 2026 | Seed | $6M | Agentic enterprise security operations platform | Middle East | Dell Technologies Capital, Emerge Ventures | Israel | |
| StrikeReady | SOC Copilots | September 2026 | Unknown | Undisclosed | AI-powered SOC command and assistance | North America | Not disclosed | United States | |
| Corma | SOC Copilots | August 2026 | Seed | $60M | Defensive cybersecurity foundation models | Middle East | Sequoia Capital | Israel | |
| Mate Security | Autonomous Investigation & Triage | July 2026 | Series A | $35M | Autonomous AI SOC investigation agents | Middle East | Canaan Partners | Israel | |
| Beelzebub | Incident Response Automation | July 2026 | Seed | ~$3.4M | AI-native deception and autonomous defense platform that detects intrusions, investigates attacker activity and isolates compromised systems automatically. | Europe | United Ventures | Italy | |
| Abstract Security | Autonomous Investigation & Triage | July 2026 | Series A | $25M | Security analytics and SIEM platform | North America | Cheyenne Ventures, AVP | United States | |
| Beacon Security | Autonomous Investigation & Triage | July 2026 | Seed | $13M | AI security operations investigation platform | North America | Notable Capital | United States | |
| Nebulock | Threat Hunting | June 2026 | Series A | $25M | Autonomous threat hunting and response | North America | FirstMark | United States | |
| Strand Intelligence | Autonomous Investigation & Triage | June 2026 | Seed | $1.3M | AI security operations investigation platform | Europe | Osney Capital | United Kingdom | |
| Imperum | SOC Copilots | June 2026 | Seed | Undisclosed | Autonomous security operations center software | Europe | Curiosity VC | Netherlands | |
| Exaforce | Autonomous Investigation & Triage | May 2026 | Series B | $125M | Autonomous AI-powered security operations | North America | HarbourVest Partners | United States | |
| Copperhelm | Incident Response Automation | April 2026 | Seed | $7M | AI security operations platform | Middle East | TLV Partners | Israel | |
| Rilian | Case Management & Orchestration | April 2026 | Seed | Undisclosed | Agentic security investigation and orchestration | North America | 8VC, First In, Tamarack Global | United States | |
| Spectrum Security | Detection Engineering | April 2026 | Seed | $19M | Autonomous security operations and threat detection | North America | TechOperators | United States | |
| Artemis Security | Incident Response Automation | April 2026 | Series A | $55M | AI-native threat detection and response | North America | Felicis | United States | |
| Artemis Security | Incident Response Automation | April 2026 | Seed | $15M | AI-native threat detection and response | North America | First Round Capital, Brightmind Partners | United States | |
| Mallory | Autonomous Investigation & Triage | April 2026 | Seed | Undisclosed | AI security operations investigation agents | North America | Decibel | United States | |
| TENEX.AI | AI-First Managed SOC | March 2026 | Series B | $250M | AI-native managed detection and response | North America | Crosspoint Capital Partners | United States | |
| Kai Security | Autonomous Investigation & Triage | March 2026 | Unknown | $125M | Autonomous cybersecurity investigation and response | North America | Evolution Equity Partners | United States | |
| Qevlar AI | Autonomous Investigation & Triage | March 2026 | Series A | $30M | Autonomous security alert investigation agents | Europe | Partech, Forgepoint Capital International | France | |
| Cotool | Case Management & Orchestration | March 2026 | Seed | $7.4M | Agent operating system for cybersecurity | North America | Andreessen Horowitz | United States | |
| Fig Security | Detection Engineering | March 2026 | Series A | $30M | Security operations resilience software | Middle East | Ten Eleven Ventures | Israel | |
| Prophet Security | Autonomous Investigation & Triage | February 2026 | Unknown | Undisclosed | Agentic AI security operations platform | North America | Not disclosed | United States | |
| Cydelphi | Incident Response Automation | February 2026 | Seed | $3M | AI digital forensics and incident response | North America | Glasswing Ventures | United States | |
| CounterShadow | Autonomous Investigation & Triage | February 2026 | Seed | Undisclosed | Autonomous AI security operations platform | Europe | Tachles VC | United Kingdom | |
| Vega Security | Detection Engineering | February 2026 | Series B | $120M | Distributed AI-native threat detection platform | North America | Accel | United States | |
| RADICL | AI-First Managed SOC | February 2026 | Series A | $31M | Managed cybersecurity and compliance platform | North America | Paladin Capital Group | United States | |
| Sevii | Autonomous Investigation & Triage | February 2026 | Seed | Undisclosed | Autonomous cyber defense and incident response | North America | Not disclosed | United States | |
| AiStrike | Autonomous Investigation & Triage | January 2026 | Seed | $7M | AI-native preemptive cyber defense | North America | Blumberg Capital | United States | |
| Asymmetric Security | Autonomous Investigation & Triage | January 2026 | Seed | $4.2M | AI-driven cyber forensics and incident response | North America | Susa Ventures | United States | |
| Torq | Case Management & Orchestration | January 2026 | Series D+ | $140M | Agentic AI security operations automation | North America | Merlin Ventures | United States | |
| 7AI | Autonomous Investigation & Triage | December 2025 | Series A | $130M | Autonomous AI security operations agents | North America | Index Ventures | United States | |
| Cognna | Incident Response Automation | December 2025 | Series A | $9.2M | Agentic AI security operations platform | Middle East | Impact46, BNVT Capital | Saudi Arabia | |
| PRE Security | Detection Engineering | December 2025 | Seed | Undisclosed | AI-native security automation platform | North America | Not disclosed | United States | |
| Method Security | SOC Copilots | November 2025 | Seed | $26M | AI-driven synthetic security engineers | North America | Andreessen Horowitz, General Catalyst | United States | |
| Mate Security | Autonomous Investigation & Triage | November 2025 | Seed | $16M | Autonomous AI SOC investigation agents | Middle East | Team8, Insight Partners | Israel | |
| Secure.com | SOC Copilots | November 2025 | Seed | $4.5M | AI-powered digital security teammates | North America | Disrupt.com | United States | |
| Daylight Security | AI-First Managed SOC | November 2025 | Series A | $33M | Hybrid AI and human cyber defense | North America | Craft Ventures | United States | |
| AiStrike | Autonomous Investigation & Triage | November 2025 | Unknown | $5.1M | AI-native preemptive cyber defense | North America | Not disclosed | United States | |
| Rilevera | Incident Response Automation | November 2025 | Seed | $3M | Automated security operations and threat response | North America | DataTribe | United States | |
| RedCarbon | Autonomous Investigation & Triage | October 2025 | Series A | $3.3M | AI security operations and threat triage | Europe | Azimut Venture Capital Digitech Europe | Italy | |
| Bricklayer AI | Autonomous Investigation & Triage | October 2025 | Seed | $5M | Autonomous AI security analysts | North America | Tech Square Ventures | United States | |
| Conifers | Autonomous Investigation & Triage | October 2025 | Growth Equity | Undisclosed | Agentic AI security operations platform | North America | Washington Harbour Partners | United States | |
| TENEX.AI | AI-First Managed SOC | September 2025 | Series A | $27M | AI-native managed detection and response | North America | Crosspoint Capital Partners | United States | |
| Simbian | Autonomous Investigation & Triage | September 2025 | Unknown | Undisclosed | AI-powered autonomous security operations | North America | Not disclosed | United States | |
| Miru Labs | Autonomous Investigation & Triage | September 2025 | Seed | $2.7M | AI-native cybersecurity investigation graph platform | North America | Seedcamp, Dreamcraft, Cadenza | United States | |
| WiseBee | Autonomous Investigation & Triage | August 2025 | Seed | $2.5M | AI-driven autonomous security operations | North America | Frontline Ventures, BrightCap Ventures | United States | |
| Command Zero | Autonomous Investigation & Triage | July 2025 | Unknown | $10M | AI-powered autonomous cyber investigations | North America | Not disclosed | United States | |
| Legion Security | Autonomous Investigation & Triage | July 2025 | Series A | $30M | Browser-native autonomous AI SOC analyst | North America | Coatue | United States | |
| Prophet Security | Autonomous Investigation & Triage | July 2025 | Series A | $30M | Agentic AI security operations platform | North America | Accel | United States | |
| Nebulock | Threat Hunting | July 2025 | Seed | $6M | Autonomous threat hunting and response | North America | Bain Capital Ventures | United States | |
| BlinkOps | Case Management & Orchestration | July 2025 | Series B | $50M | AI-powered security automation platform | North America | O.G. Venture Partners | United States | |
| Daylight Security | AI-First Managed SOC | July 2025 | Seed | $7M | Hybrid AI and human cyber defense | North America | Bain Capital Ventures | United States | |
| Dropzone AI | Autonomous Investigation & Triage | July 2025 | Series B | $37M | Autonomous AI security alert investigations | North America | Theory Ventures | United States | |
| AirMDR | AI-First Managed SOC | July 2025 | Seed | $11M | AI-native managed detection and response | North America | Race Capital | United States | |
| RunReveal | Detection Engineering | July 2025 | Seed | $7M | AI-native security data analytics platform | North America | Not disclosed | United States | |
| Circumvent | Incident Response Automation | June 2025 | Seed | $6M | AI-driven cloud security and remediation | North America | Paladin Capital Group | United States | |
| Swimlane | Case Management & Orchestration | June 2025 | Growth Equity | $45M | Agentic AI security automation platform | North America | Activate Capital, Energy Impact Partners | United States | |
| BreachRx | Incident Response Automation | May 2025 | Series A | $15M | Incident response coordination and automated response plans | North America | Ballistic Ventures | United States | |
| Sevii | Autonomous Investigation & Triage | April 2025 | Seed | Undisclosed | Autonomous cyber defense and incident response | North America | Overline | United States | |
| Kenzo Security | Autonomous Investigation & Triage | April 2025 | Seed | $4.5M | AI-driven security operations automation | North America | The General Partnership | United States | |
| Exaforce | Autonomous Investigation & Triage | April 2025 | Series A | $75M | Autonomous AI-powered security operations | North America | Khosla Ventures, Mayfield, Thomvest Ventures | United States | |
| Sekoia | Incident Response Automation | April 2025 | Series B | $29M | AI-native cyber detection and response | Europe | Revaia | France | |
| Qevlar AI | Autonomous Investigation & Triage | April 2025 | Seed | $10M | Autonomous security alert investigation agents | Europe | EQT Ventures, Forgepoint Capital International | France | |
| ReliaQuest | Incident Response Automation | March 2025 | Growth Equity | $500M+ | AI-powered security operations automation | North America | EQT | United States | |
| RAD Security | Detection Engineering | March 2025 | Series A | $14M | AI-driven cloud threat detection platform | North America | Cheyenne Ventures | United States | |
| Crogl | Autonomous Investigation & Triage | March 2025 | Series A | $25M | Autonomous AI cybersecurity investigation agents | North America | Menlo Ventures | United States | |
| Crogl | Autonomous Investigation & Triage | March 2025 | Seed | $5M | Autonomous AI cybersecurity investigation agents | North America | Tola Capital, Firestreak Ventures | United States | |
| Zaun | SOC Copilots | March 2025 | Seed | $1.5M | AI agents for security operations centers | North America | Not disclosed | United States | |
| Andesite | SOC Copilots | February 2025 | Seed | $23M | AI-powered security operations platform | North America | General Catalyst, Red Cell Partners | United States | |
| 7AI | Autonomous Investigation & Triage | February 2025 | Seed | $36M | Autonomous AI security operations agents | North America | Not disclosed | United States | |
| Backline | Incident Response Automation | January 2025 | Seed | $9M | AI agents automate security remediation | North America | StageOne Ventures | United States | |
| Conifers | Autonomous Investigation & Triage | January 2025 | Seed | $25M | Agentic AI security operations platform | North America | SYN Ventures | United States | |
| Mitiga | Incident Response Automation | January 2025 | Series B | $30M | Cloud and AI agent security | Middle East | SYN Ventures | Israel | |
| CounterShadow | Autonomous Investigation & Triage | January 2025 | Seed | Undisclosed | Autonomous AI security operations platform | Europe | Not disclosed | United Kingdom | |
| Fig Security | Detection Engineering | 2025 | Seed | $8M | Security operations resilience software | Middle East | Team8 | Israel | |
| System Two Security | Detection Engineering | December 2024 | Seed | $7M | AI threat hunting and detection engineering | North America | Costanoa Ventures | United States | |
| Tuskira | Detection Engineering | December 2024 | Unknown | $29M | AI-powered unified threat defense platform | North America | Intel Capital, SYN Ventures | United States | |
| Cognna | Incident Response Automation | November 2024 | Unknown | Undisclosed | Agentic AI security operations platform | Middle East | Saudi Telecom Company (stc) | Saudi Arabia | |
| Embed Security | Autonomous Investigation & Triage | November 2024 | Seed | $6M | AI-powered security alert triage | North America | Paladin Capital Group | United States | |
| ContraForce | Incident Response Automation | October 2024 | Seed | $3.3M | AI security operations and incident response software | North America | Gallos Technologies, DataTribe | United States | |
| Abstract Security | Autonomous Investigation & Triage | October 2024 | Series A | $15M | Security analytics and SIEM platform | North America | Munich Re Ventures | United States | |
| Torq | Case Management & Orchestration | September 2024 | Series C | $70M | Agentic AI security operations automation | North America | Evolution Equity Partners | United States | |
| Intezer | Autonomous Investigation & Triage | September 2024 | Series C | $33M | AI-driven security investigation and triage | North America | Norwest | United States | |
| BlinkOps | Case Management & Orchestration | September 2024 | Growth Equity | $24M | AI-powered security automation platform | North America | Not disclosed | United States | |
| Command Zero | Autonomous Investigation & Triage | July 2024 | Seed | $21M | AI-powered autonomous cyber investigations | North America | Andreessen Horowitz | United States | |
| Legion Security | Autonomous Investigation & Triage | July 2024 | Seed | $8M | Browser-native autonomous AI SOC analyst | North America | Accel, Picture Capital | United States | |
| Huntress | Incident Response Automation | June 2024 | Series D+ | $150M | Managed cybersecurity detection and response | North America | Kleiner Perkins, Meritech Capital, Sapphire Ventures | United States | |
| AirMDR | AI-First Managed SOC | June 2024 | Seed | $5M | AI-native managed detection and response | North America | Foundation Capital | United States | |
| Bricklayer AI | Autonomous Investigation & Triage | May 2024 | Seed | $2.5M | Autonomous AI security analysts | North America | Not disclosed | United States | |
| RunReveal | Detection Engineering | May 2024 | Seed | $2.5M | AI-native security data analytics platform | North America | Costanoa Ventures | United States | |
| Corelight | Detection Engineering | April 2024 | Series D+ | $150M | Network detection and threat response | North America | Accel | United States | |
| Dropzone AI | Autonomous Investigation & Triage | April 2024 | Series A | $17M | Autonomous AI security alert investigations | North America | Theory Ventures | United States | |
| Prophet Security | Autonomous Investigation & Triage | April 2024 | Seed | $11M | Agentic AI security operations platform | North America | Bain Capital Ventures | United States | |
| Anvilogic | Detection Engineering | April 2024 | Series C | $45M | AI-driven security detection engineering platform | North America | Evolution Equity Partners | United States | |
| BreachRx | Incident Response Automation | April 2024 | Seed | $6.5M | Incident response coordination and automated response plans | North America | Not disclosed | United States | |
| Andesite | SOC Copilots | April 2024 | Seed | $15M | AI-powered security operations platform | North America | Red Cell Partners, General Catalyst | United States | |
| Simbian | Autonomous Investigation & Triage | April 2024 | Seed | $10M | AI-powered autonomous security operations | North America | Cota Capital, Icon Ventures, Firebolt, Secure Octane, Rain Capital | United States | |
| StrikeReady | SOC Copilots | April 2024 | Series A | $12M | AI-powered SOC command and assistance | North America | 33N Ventures | United States | |
| Surge | Autonomous Investigation & Triage | March 2024 | Seed | $5.8M | AI-driven security operations | Europe | Eurazeo | France | |
| LimaCharlie | Case Management & Orchestration | February 2024 | Series A | $10M | API-first security operations infrastructure platform | North America | Sands Capital | United States | |
| Torq | Case Management & Orchestration | January 2024 | Series B | $42M | Agentic AI security operations automation | North America | Not disclosed | United States | |
| Nebulock | Threat Hunting | 2024 | Seed | $2.5M | Autonomous threat hunting and response | North America | Not disclosed | United States | |
| PRE Security | Detection Engineering | January 2024 | Seed | Undisclosed | AI-native security automation platform | North America | strategic channel partners | United States |

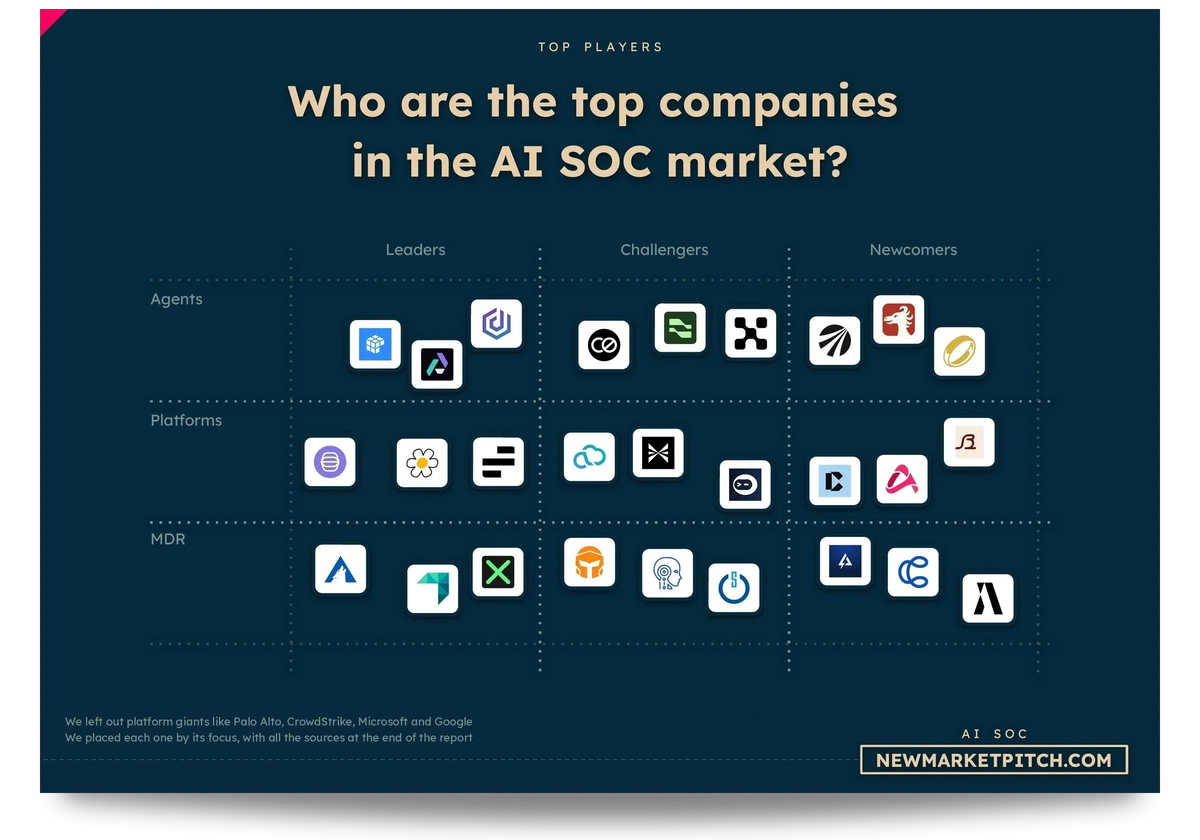
In our research about AI security operations, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is AI SOC funding booming or slowing down this year?
AI SOC financing is growing in dollars this year but shrinking by number of deals.
We tracked 36 deals totaling at least $1.3B this year, against 38 deals and at least $1.1B over the same period of 2025. Disclosed capital grew 13%, while the transaction count fell 5%. Large financings involving TENEX.AI, Torq and Exaforce help explain why fewer transactions still produced more money.
Is the rise in AI SOC funding just a handful of giant deals?
A few giant AI SOC investments explain most of the rise in disclosed capital this year.
Funding excluding rounds above $50M is $316M+ year to date, versus $547M+ over the same period of 2025, a decline of 42%. Excluding rounds above $100M also produces a decline, from $622M+ to $511M+. A small group of enterprise platforms is securing the bigger checks while the rest of the market gets less funding.
Are AI SOC funding rounds bigger than they used to be?
The median disclosed AI SOC funding round is up 104% compared with the same period last year.
The median is $25.0M this year to date, versus $12.2M over the corresponding period of 2025. The same point in 2024 showed a $12.0M median, so this jump is a real break from two flat years. The median is less sensitive to an exceptional round than the total. Most seed founders are still raising much less.

Your time is limited. In our market report about AI security operations, we put numbers on each part of the market, so you can see where it makes sense to focus.
Have nine-figure AI SOC rounds become common this year?
Nine-figure AI SOC financings have become more frequent this year, although they remain a minority of deals.
We record 5 deals of $100M or more this year to date, representing 14% of transactions and $760M in disclosed capital. The same period of 2025 had 1 such deal, for $500M, while the corresponding period of 2024 had 2. More platforms now qualify for giant checks, but nine-figure rounds are still rare. Vega Security's $120M Series B in February 2026 and Kai Security's $125M Series A in March 2026 broaden the list of big financings beyond a single business model.
Has AI SOC already raised as much as in the whole previous year?
AI SOC has reached 97% of the previous full-year disclosed funding total, but this year is not yet complete.
This year has 36 deals versus 45 in the full year of 2025, equal to 80% of that prior full-year deal count. So the money has almost caught up with last year's total, but the number of deals is still well behind.
Has the AI SOC funding boom lasted beyond its first wave?
AI SOC funding has grown since the first wave of security agents, despite a recent drop in deal count.
The comparable period of 2024 had 24 deals and at least $665M; the same period of 2025 had 38 deals and at least $1.1B; the current period has 36 deals and at least $1.3B. Against the 2024 benchmark, disclosed capital is up 91% and deal count is up 50%. The market is bigger than it was earlier, even though fewer deals are getting done this year than at the same point last year.

In our document detailing everything you need to know about AI SOC, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Why did TENEX.AI get such a big AI SOC investment?
TENEX.AI drew the largest AI SOC round this year, a $250M Series B in March 2026, with its AI-led managed security model.
The company describes an AI-native managed detection and response model in which software investigates alerts and human analysts remain accountable for consequential security decisions. Its announcement says the proceeds will support analyst and engineering hiring, enterprise partnerships and international expansion. Big as the round is, customers still have other ways to run a SOC.
Are investors abandoning early-stage AI SOC startups?
Early-stage AI SOC startups still receive most of the deals, although later stages take most disclosed capital.
Early-stage rounds represent 85% of deals with a named stage this year to date, compared with 80% over the same period of 2025. Yet later-stage deals account for 57% of disclosed capital. Early-stage deals are common, but larger later rounds take most of the money. Investors are still backing new ideas, while writing bigger checks for a small group of more established companies.
Are AI SOC seed rounds drying up?
Seed funding for AI SOC startups remains active, with no drop in deal count against the comparable period last year.
Seed accounts for 19 deals this year to date, matching the 19 seed transactions over the same period of 2025. The current seed median is $7M, compared with $6M in the earlier comparable period. In contrast, seed financing contributes $164M+ this year, a much smaller pool than the headline total for the entire sector. Seed funding is holding up, even while bigger checks make the headlines.

Our report covering the AI SOC market gets updated several times a month, so you always get the latest view of where things stand.
Why are AI SOC Series B rounds so big right now?
AI SOC Series B rounds have become huge because a small number of companies received unusually large checks this year.
We count 4 Series B rounds totaling $575M and 45% of disclosed capital year to date, against 4 rounds and $146M, or 13% of disclosed capital, over the same period of 2025. Vega Security's $120M Series B in February 2026 and Exaforce's $125M Series B in May 2026 show the scale of this group. TENEX.AI also belongs among these major Series B recipients. Those businesses tackle managed response, detection and automated investigation, each with different customer needs.
Are AI SOC startups struggling to raise a Series C?
AI SOC startups are raising almost no Series C rounds, but that does not point to a funding crisis, because other large later-stage rounds are still happening.
We see no Series C financing year to date, and none in the same period of 2025, despite the sizeable Series B cohort. There is 1 Series D+ deal this year, Torq's $140M financing in January 2026. Many AI SOC companies are still too young for a Series C. The current Series B boom does not guarantee another round will follow.
Which AI SOC products are attracting capital this year?
Case management and orchestration gets the most disclosed AI SOC capital this year, while autonomous investigation and triage gets the most deals.
Case management and orchestration accounts for at least $147M across 3 deals, while autonomous investigation and triage records 13 deals and at least $365M. The managed SOC category also attracted 3 financings totaling $361M, close behind. The most popular category by deal count also receives the most dollars, though only narrowly. Investors are backing incident investigation, response coordination, managed services and analyst tools.
The table below shows how AI SOC category financing compares with the same point last year, ordered by current disclosed capital.
| Category | This year deals | Prior deals | This year capital | Prior capital |
|---|---|---|---|---|
| Case Management & Orchestration | 4 | 3 | $272M+ | $170M |
| AI-First Managed SOC | 1 | 2 | $250M | $38M |
| Autonomous Investigation & Triage | 11 | 16 | $215M+ | $196M+ |
| Incident Response Automation | 9 | 8 | $206M | $629M+ |
| Detection Engineering | 4 | 3 | $184M | $24M |
| SOC Copilots | 6 | 5 | $119M+ | $60M+ |
| Threat Hunting | 1 | 1 | $25M | $6M |
“+” indicates at least the disclosed amount; other deal amounts may be unavailable.

In our research about AI security operations, we look at what the winners do differently, so you can learn from the best instead of guessing.
Are investors cooling on AI SOC agents that investigate alerts?
Autonomous investigation and triage still leads AI SOC funding by deal count this year, but its share of transactions has fallen.
Its deal count fell to 11 this year to date from 16 in the same period of 2025, but disclosed capital increased to $215M+ from $196M+. The category's transaction share fell from 42% to 31%. Qevlar AI's $30M Series A and Kai Security's $125M Series A, both in March 2026, show that investors still pay well for this kind of tool, even with fewer rounds. Investors are making fewer but larger investigation bets.
Are investors moving from SOC copilots toward autonomous agents?
AI SOC copilots and autonomous security agents are both attracting funding, so investors have not abandoned one for the other.
SOC copilots generated 5 deals and at least $94M this year to date, compared with 2 deals and $25M in the same period of 2025. At the same time, startups in autonomous investigation and orchestration also landed big rounds. What matters to customers is which tasks the software can finish, and when a person must approve the result. CrowdStrike's September 2026 announcement of coordinated multi-agent investigations illustrates how even incumbent platforms are converging on more automated workflows.

In our market report about AI security operations, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Is incident response automation falling out of favor with investors?
Incident response automation is still getting AI SOC funding, despite a much smaller disclosed total than at the same point last year.
The category has 6 deals this year to date versus 7 in the corresponding period of 2025. Disclosed financing fell from at least $592M to $87M, mostly because last year's total included ReliaQuest's giant growth round. Daylight Security's $80M Series B in November 2026, now counted under AI-first managed SOC, demonstrates that investors continue backing platforms that combine detection and containment with human expertise. Deal activity has slipped only slightly; there is simply no ReliaQuest-sized round this year.
Is Israel challenging the United States in AI SOC funding?
Israel is taking a larger share of AI SOC deals, but the United States still receives substantially more disclosed investment.
Israeli-headquartered startups completed 8 financings this year to date, versus 3 in the same period of 2025. Their share of deals reached 22%, against 8% a year earlier, and their disclosed capital reached $261M, against $70M. Corma's $60M seed in August 2026, Mate Security's $35M Series A in July 2026 and Daylight Security's $80M Series B in November 2026 show a varied group rather than one outsized investment. Israeli teams now account for a larger part of the AI SOC funding market.
Is the US share of AI SOC funding actually shrinking?
The US share of AI SOC deal count is shrinking this year, but American startups still attract most disclosed funding.
The United States accounts for 22 deals and 61% of transactions year to date, compared with 31 deals and 82% at the same point in 2025. US-headquartered companies attracted $973M+ in disclosed financing this year, representing 76% of the market's disclosed money. American companies still take the largest share of investment. Major rounds for TENEX.AI, Torq, Vega Security and Exaforce ensure that US-linked enterprise platforms continue to shape the totals.

Learning from others' mistakes is the cheapest lesson there is. In our document detailing everything you need to know about AI SOC, we look at what broke startups before you, so you don't repeat it.
Are brand-new AI SOC startups still getting their first checks?
First-time AI SOC fundraising is still happening, despite the attention paid to huge later rounds.
We classify 13 deals as first financings this year to date, versus 12 over the same period of 2025. Their share of transactions rose from 32% to 36%; meanwhile, follow-ons account for 17 current deals and $912M+ in disclosed money. New teams get funded, but follow-ons take most of the money.
Are AI SOC companies raising follow-on capital faster?
AI SOC startups with observable follow-on financings are raising again faster than in prior comparable periods.
The median gap between consecutive rounds is 11 months this year to date, versus 15 months in the same period of 2025 and 21 months at the same point in 2024. Among observed round-to-round gaps, 53% are under 12 months this year, compared with 21% and 18% in those corresponding earlier periods. Only part of the startups have a known earlier round, so this speed does not apply to all of them. These companies are raising again faster, although we cannot infer their revenue growth from that.
Do the same VCs keep leading AI SOC funding rounds?
No small group of repeat VC leads controls AI SOC funding this year; a wider range of investors is participating.
We identify 60 distinct investors and 40 distinct lead investors in year-to-date transactions, compared with 55 investors and 38 lead investors at the same point in 2025. No lead investor appears as a repeated lead this year, whereas 2 did at this stage last year. Crosspoint Capital Partners led TENEX.AI's large Series B, Merlin Ventures led Torq's Series D+ and Evolution Equity Partners backed Kai Security's announced raise. The lead investors are spread across more firms, with little repeat activity.

If you build or invest in the AI SOC market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Did AI SOC funding accelerate throughout the year?
AI SOC funding did not accelerate through the year; its biggest disclosed quarter came early.
Q1 2026 recorded 14 deals and $748M+, compared with Q2 2026's 10 deals and $247M+ and Q3 2026's 7 deals and $144M+. Q4 2026 has only just started, so its low figures do not mean a drop yet. The earlier quarterly history also shows bursts, notably around ReliaQuest's March 2025 announcement. A single giant round can shift the quarterly total without bringing many extra startups into the market.
The table below shows AI SOC fundraising by quarter, with the current unfinished quarter clearly marked.
| Period | Deals | Capital |
|---|---|---|
| Q1 2025 | 11 | $668M+ |
| Q2 2025 | 8 | $184M+ |
| Q3 2025 | 13 | $220M+ |
| Q4 2025 | 12 | $235M+ |
| Q1 2026 | 14 | $748M+ |
| Q2 2026 | 10 | $247M+ |
| Q3 2026 | 7 | $144M+ |
| Q4 2026 (partial) | 5 | $132M |
Quarters add up to fewer deals than the yearly totals: 1 deal of 2025 is dated only by the year, so it counts in the yearly total but in no quarter.
Can independent AI SOC startups withstand the big security vendors?
Independent AI SOC startups can still compete with major security vendors, but funding does not guarantee customer wins.
Google described security operations agents for investigation and response in June 2026, CrowdStrike introduced coordinated multi-agent investigations in September 2026, and Fortinet launched its FortiSOC platform, powered by agentic AI, in June 2026. Independent companies such as Qevlar AI, Exaforce and Dropzone AI argue for cross-tool investigations or focused workflows that fit existing environments. Investors still back smaller vendors, but customers have to see enough value to pay for another security tool.
So, what are the current AI SOC funding trends?
AI SOC fundraising is getting larger per deal and more concentrated, while the number of financings and capital below the largest rounds are falling.
The bigger checks are still doing most of the work. New AI SOC startups are getting funded, and a handful of agentic or managed providers are raising much more. Israel is becoming more prominent, follow-on rounds can happen quickly and incumbents are entering the same workflows. The next test is whether customers keep using these platforms and whether the companies can raise later-stage rounds.
The table below shows what we found.
| Question | Answer |
|---|---|
| Is AI SOC financing stronger across the board? | No, capital and transaction trends point in different directions. Disclosed funding is up 13% year to date. The financing market is growing in size, not breadth. |
| Are investors making more separate investments? | No, transactions have slipped in the latest comparison. Deal volume is down 5% year to date. Fewer announcements can still produce much more invested capital. |
| Is funding improving below the biggest rounds? | No, ordinary AI SOC financings are weaker this year. That smaller-round capital fell 42% over the comparable periods. A few giant rounds are making the headline total stronger. |
| Are nine-figure startup raises now typical? | Not yet, although they have gained considerable importance. We recorded 5 nine-figure deals in this partial year. Those financings remain a minority of market activity. |
| Can this partial year match previous totals? | AI SOC funding is already close to last year's total. It reached 97% of the previous full-year disclosed amount. The current period is still incomplete, so direct comparisons need care. |
| Are companies abandoning seed-stage security projects? | No, investors still back new AI SOC security startups. There were 19 seed deals in the current year-to-date period. The largest checks, though, went to companies at later stages. |
| Is Series B becoming more important financially? | Yes, this stage is taking substantial disclosed capital. Series B accounts for 45% of year-to-date disclosed funding. A small group of large financings explains that result. |
| Has autonomous investigation run out of investors? | No, autonomous investigation still attracts the most AI SOC deals. We recorded 11 such financings in the current partial year. The deal count declined while the checks became larger. |
| Is Israel replacing American security startups already? | No, the US still takes most of the AI SOC money. Israel now accounts for 22% of year-to-date transactions. It is growing quickly without displacing America's financial lead. |
| Do new founders still secure initial financing? | Yes, new AI SOC startups still secure their initial checks. There were 13 first financings this year to date. Previously funded companies continue to receive much more total capital. |
| Is agentic SOC adoption already decided? | No, major incumbents are competing in these workflows. CrowdStrike expanded agentic SOC investigations in September 2026. Product reliability and integration will determine durable customer demand. |

In our research about AI security operations, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Our methodology
Our data runs through November 12, 2026. The current year-to-date period runs from January 1, 2026 to November 12, 2026; we compare it with January 1 to November 12 of 2025 and 2024. We also use the complete calendar years 2025 and 2024 only where the question explicitly requires a full-year benchmark. We never annualize partial-year figures. Our minimum qualifying equity financing is $300K; debt, grants, loans, unconverted convertibles, SAFEs and public offerings are excluded.
We include companies whose core product automates or significantly augments security operations center workflows: alert triage, investigation, threat hunting, detection engineering, operational orchestration, containment, response and AI-specific analyst assistance. Technology-led managed security is eligible when its defining product is an operational AI SOC platform. We include genuine boundary cases rather than hiding them, but generic cybersecurity, posture-only tools, human-only consulting and general-purpose AI agent infrastructure without a predominantly SOC security workflow do not qualify.
All counted companies meet our startup definition: independent technology-led businesses founded in 2000 or later, privately financed and built for rapid growth, subject to recency rules for recent listings and acquisitions. We assign categories according to our own market split and geography according to headquarters country. We standardize financing stage labels and distinguish named-stage transactions from rounds of undisclosed stage.
Each financing is counted once, with duplicate press reports merged. Deals with undisclosed amounts count toward the number of transactions and companies but not capital; disclosed capital therefore often represents a minimum. First-financing and follow-on labels come from identifiable company financing histories. We measure repeated rounds only where their dates can be established and show the available coverage rather than presenting the resulting velocity as universal.
We prioritize company statements, investor announcements, filings and reliable contemporaneous reporting for deal size, timing, stage and investor roles. We calculate comparable year-to-date periods directly rather than comparing a partial year with a full one as if they had identical exposure. Some records have only a calendar year, not a known quarter: 1 deal in 2024 and 1 in 2025 are included in yearly totals but omitted from quarter aggregates.
Rounds confirmed by a company announcement, a press article or a regulatory filing are counted in full. Where no article exists, a round is counted only when at least two recognised databases agree on its date (within one month) and amount (within 5%), and it is marked as low confidence; a round found in a single database stays in the company's history but is left out of totals. For companies that have raised more than $100M, every round counted is backed by an article.
Our funding series can differ from general cybersecurity reports because we require a primary AI SOC product and consistent inclusion criteria. The partial latest month and quarter remain partial rather than being extrapolated. More importantly, funding measures investor decisions, not customer retention, automation accuracy or profitability; we discuss those product questions only when backed by distinct operating announcements.
Key sources include TENEX.AI March 2026 Series B and AI-native managed operations, TENEX.AI hiring, expansion and human oversight in AI SOC, Torq January 2026 Series D and product expansion, Exaforce May 2026 Series B and earlier financing, Vega Security February 2026 Series B, Kai Security March 2026 financing and autonomous platform, ReliaQuest March 2025 growth financing, Qevlar AI March 2026 investigation funding, Dropzone AI funding and autonomous analyst deployments, Prophet Security Series A and agentic SOC product, Corma August 2026 seed financing, Mate Security July 2026 Series A coverage, Daylight Security November 2026 Series B, Artemis Security seed and Series A announcement, 7AI agentic SOC fundraising and enterprise strategy, Google June 2026 security operations agent announcement, CrowdStrike September 2026 multi-agent investigations, and Fortinet June 2026 FortiSOC announcement.

When you build or invest in the AI SOC market, you need clarity, not confusion. In our market report about AI security operations, we always try to put numbers on and quantify whatever is usually vague and confusing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us