Is the Pet Tech Market growing now?
Everything we know about the Pet Tech market, in one place. Get our report whether you build or invest.
Summary
The Pet Tech Market is growing now, but in a much narrower, more selective way than the headline forecasts suggest.
The strongest signal is not that every pet category is expanding. It is that health-linked, recurring, and infrastructure-like models are still growing while weaker discretionary models are getting exposed.
Analyst forecasts still point to double-digit growth, but the range is unusually wide. Depending on the definition, the 2026 Pet Tech Market can look like a roughly $9 billion market or a market above $19 billion.
That definition gap matters because “Pet Tech” now mixes very different businesses. A smart feeder, an AI vet workflow tool, a pet insurance platform, a diagnostics company, and a pet marketplace do not deserve the same growth multiple. A smart feeder, a vet tool and a marketplace differ so much that we spell out what counts in our report on pet tech.
The latest quarterly results split the market in two. Chewy grew sales 7.3% in its fiscal Q2 and raised its full-year outlook in September 2026. IDEXX grew recurring diagnostics revenue 11%. Freshpet grew sales 15.5%. On the other side, Zoetis cut its 2026 outlook in August, and Petco’s sales were roughly flat.
Recurring buying is the clearest strength. 84.6% of Chewy’s sales now come from Autoship customers. But sales per active customer grew only 1.9%, and the company said treats and premium extras were under pressure.
Veterinary care is the clearest pressure point. Zoetis said lower clinic visits and pet owner price sensitivity cut demand, and its U.S. companion-animal sales fell 11% in Q2 2026.
That affordability pressure is creating one of the best Pet Tech opportunities. Insurance, telehealth triage, cost-transparency tools, online prescriptions, diagnostics, and clinic software all become more valuable when care feels expensive and confusing.
Pet insurance is still growing, but mostly in dollars. Trupanion’s Q2 revenue rose 11%, while its total enrolled pets fell 2%. Its core subscription enrolment still grew 5%.
AI veterinary software now has stronger proof. In September 2026, IDEXX bought CoVet, an AI documentation tool that says tens of thousands of veterinary professionals use it daily. The price was not disclosed.
Smart collars and connected appliances are moving from convenience toward health signals, but the proof is still uneven. New devices keep raising small rounds, yet the category still lacks published validation, sell-through, and paid-subscription data.
The weakest model is the labor-heavy local pet marketplace. Wag’s Chapter 11 is a useful warning that “pet app” demand does not automatically become software-like margins.
Our conclusion is that the Pet Tech Market is growing now, but not as one broad wave. The real growth is concentrated in ecommerce replenishment, diagnostics, veterinary software, health-linked fresh food, and insurance pricing, while vet visits, discretionary extras, and pet-health drugs are under pressure.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

Your time is limited. In our report covering the pet tech market, we put numbers on each part of the market, so you can see where it makes sense to focus.
Why is the Pet Tech Market so hard to read right now?
The Pet Tech Market is hard to read because the strongest growth signals and the strongest slowdown signals are showing up at the same time.
On the positive side, the market still has clear momentum.
Chewy reported fiscal Q2 net sales of $3.33 billion in September 2026, up 7.3% year over year, and raised its full-year outlook. IDEXX reported Q2 revenue up 10% in August 2026, with recurring companion-animal diagnostics revenue up 11%. Freshpet grew Q2 net sales 15.5% and raised its 2026 outlook. Trupanion grew Q2 revenue 11%. In February 2026, Lassie raised $75 million for prevention-led pet insurance.
That is not a dead market. The most useful, repeatable, health-linked parts are still growing.
But the negative side is just as concrete.
Zoetis cut its 2026 revenue outlook in August 2026, citing lower clinic visits and price-sensitive pet owners. Petco’s Q2 sales were roughly flat, with comparable sales up 0.6%. Trupanion’s total enrolled pets fell 2%. Wag’s 2025 Chapter 11 filing also showed that not every digital pet platform can survive just because it sits inside “pet tech.”
These are company figures, not one market index. That is exactly why the picture looks mixed.
Are Pet Tech analysts still bullish, or are they just recycling old optimism?
Pet Tech analysts are still bullish, but their optimism needs to be read carefully.
Grand View Research estimates the global pet tech products market at $9.23 billion in 2025 and forecasts 12.5% annual growth through 2033. Research and Markets puts the broader pet tech market at $9.01 billion in 2026 after 20.3% growth from 2025. Mordor Intelligence estimates $14.17 billion in 2026 and forecasts 13.19% annual growth through 2031. Global Market Insights is even larger, estimating $19.1 billion in 2026 and $52.9 billion by 2035. Estimates from $9 billion to above $19 billion are why we build our own size estimate, every assumption visible, in our pet tech market report.
The direction is consistent: analysts generally expect Pet Tech to grow. We found no newer tech-only market size to replace these estimates.
The problem is definition. Some forecasts mostly track connected products such as GPS collars, smart feeders, smart litter boxes, pet cameras, and smart toys. Others stretch closer to digital pet care, telehealth, veterinary software, insurance platforms, and tech-enabled services.
That is why the 2026 market size can range from around $9 billion to above $19 billion depending on who is counting.
These are forecasts, not measured results. Several firms, using different definitions, still see double-digit growth, but none of them has been checked against actual 2026 sales yet.
Analyst forecasts are only one layer of evidence. They can smooth over what is happening on the ground: price-sensitive pet owners, fewer vet visits, flat pet retail, and much stronger growth in diagnostics, recurring ecommerce, and veterinary software.
That is why we look at the latest company results to give a more solid answer.

In our research about pet technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is Chewy proving that Pet Tech demand is still strong?
Yes, Chewy is proving that online pet commerce is still gaining share. But it is also showing that the category underneath it is not easy.
The positive signal is clear. In September 2026, Chewy reported fiscal Q2 net sales of $3.33 billion, up 7.3% year over year. Active customers rose 3.8% to 21.7 million. Net sales per active customer reached $602, up 1.9%. Chewy also raised its full-year outlook, after cutting it in June; on its earnings call, management put 2026 net sales at $13.46 billion to $13.57 billion.
The more interesting signal is Autoship. Autoship customer sales reached $2.82 billion, up 9.3%, or 84.6% of net sales. That tells us online pet commerce is not behaving like one-off ecommerce. It is becoming a recurring replenishment layer for food, medicines, and health-related products.
But part of the growth was bought. Excluding the SmartPak and Modern Animal acquisitions, Chewy’s sales grew 5.7%. Management also said treats and premium extras slowed, while the broader consumables category was roughly flat.
So, Chewy is winning inside a slow market, not proving that the whole Pet Tech Market is accelerating.
Are pet owners actually spending more, or just paying higher prices?
Pet owners are spending more in dollars, but a meaningful part of the growth comes from price, not new demand.
The American Pet Products Association’s 2026 State of the Industry data is useful because it separates growth from inflation. U.S. pet industry expenditures reached $158 billion in 2025, up 3.7%, and APPA projected $165 billion in 2026, up about 4.4%. But APPA also said roughly 2 percentage points of the 2026 growth would come from inflation. The $165 billion is a forecast, not a measured result.
That changes the interpretation. If roughly half of the increase is pricing, the real expansion in units, adoption, or service usage is much less impressive.
Recent company results make the split visible. Chewy added 3.8% more active customers, but spending per customer grew only 1.9%. Trupanion grew revenue 11% while its total enrolled pets fell 2%. Freshpet is the exception: its 15.5% Q2 growth came almost entirely from volume, not price.
The industry-wide split between inflation and real unit growth still cannot be measured precisely. But the pattern is clear: some owners are absorbing price increases, switching channels, buying fewer extras, or delaying care.
Are pet owners starting to pull back on vet care?
Pet owners are pulling back on vet care, and this remains one of the clearest negative signals in the Pet Tech Market.
Bank of America Institute data, summarized in early 2026 coverage, showed veterinary visits declining by about 2% to 3% in 2025, while veterinary revenue rose about 2% because prices increased 5% to 6%. That is a bad mix. It means the industry can look stable in revenue while serving fewer visits. Vet visits falling while prices rise is among the risks, some less obvious, that we rate by likelihood in our market report about pet tech.
Zoetis made the signal sharper in August 2026. It said lower clinic visits and pet owner price sensitivity reduced demand across parts of its portfolio. Its U.S. companion-animal sales fell 11% in Q2, and it cut its 2026 organic operational growth outlook from 2% to 5% to a decline of 1% to 3%. That is a company’s reading of its own customers, not a measured national visit count, but it matters because Zoetis is one of the core public companies exposed to companion-animal health.
The signal is not one-sided. IDEXX grew diagnostics revenue double digit in the same quarter. Fewer visits can still mean more testing per visit.
The U.K. is showing the same affordability tension. The Competition and Markets Authority’s 2026 veterinary reforms followed a long investigation into pricing, transparency, and corporate ownership, and include clearer price lists, capped prescription fees, and better disclosure of cheaper online options.
This does not kill Pet Tech, but it redirects it. Products that help owners manage costs, compare care, insure risk, or improve clinic efficiency become more attractive. Products that add new discretionary expense become harder to sell.

Theory only gets you so far. In our market report about pet technology, we dig up the real signals from the field and show you the ones worth watching.
Is pet insurance still growing if Trupanion’s enrolled pets are falling?
Yes, pet insurance is still growing, but the latest data shows the growth is coming more from pricing and product mix than from many more insured pets.
The North American Pet Health Insurance Association’s 2025 State of the Industry report showed 7.03 million insured pets in North America at the end of 2024, up 12.2% from the prior year. U.S. gross written premiums surpassed $4.7 billion, up 21.4%. Those are the latest industry-wide figures, and they still beat overall pet spending growth.
The company data is more mixed. Trupanion reported Q2 2026 revenue of $392.9 million, up 11%, and subscription revenue of $276.7 million, up 14%. Its subscription enrolled pets rose 5% to 1.12 million. But total enrolled pets, including other products, fell 2% to 1.63 million. Net income was $6.8 million, down from $9.4 million a year earlier.
The startup signal is still strong. Lassie raised $75 million in February 2026 and was reported to have about $100 million in annual recurring revenue and 250,000 covered pets.
So insurance remains a real recurring-revenue category, and it still answers rising vet bills. But higher premiums are doing a lot of the work. The test now is whether policy counts grow again, not just revenue.
Does IDEXX buying CoVet prove AI vet tools are actually selling?
It is the strongest proof so far. AI veterinary software is moving from startup funding rounds into the product lines of the biggest companies in pet health.
In September 2026, IDEXX acquired CoVet, an AI tool that writes clinical notes and handles workflow for veterinary teams. CoVet said tens of thousands of veterinary professionals use it daily. IDEXX did not disclose the price or CoVet’s revenue, so the deal proves demand and distribution, not product profitability.
The funding signal points the same way. Digitail’s $23 million Series B in November 2025 backs AI-powered practice management, client communication, and clinic automation. Tandem’s $10 million pre-seed in 2025 backs AI-enabled care delivery and mobile clinics.
The demand logic is stronger than in consumer gadgets. Provet Cloud’s 2025 Veterinary Insights Report surveyed 600 veterinary professionals across the U.S., U.K., Spain, and Italy and described clinics facing staffing shortages, financial pressure, and changing client behavior. Those are exactly the conditions where software that saves time and reduces admin work can get budget.
AI scribes are the clearest use case. They sell a concrete promise: less documentation time, not another dashboard. Independent data on time saved and paid retention is still thin, so claims should be tested. But the buyer pain is obvious, and IDEXX can now sell this tool into its existing clinic base.

In our document detailing everything you need to know about pet tech, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are smart collars becoming real health tools?
Smart collars are becoming more credible health tools, but the category is still not proven as mass-market healthcare infrastructure.
The best scale signal is still Tractive’s July 2025 acquisition of Whistle from Mars Petcare. Tractive said it served more than 1.4 million active users worldwide and had sold millions of devices globally. That is one of the few hard user-scale numbers in pet wearables.
The second signal is product direction. Fi’s Series 3 Plus, launched in 2025, added AI-powered health and behavior tracking, Apple Watch support, stronger GPS, and detection of licking, scratching, barking, eating, and drinking. Tractive’s product direction also emphasizes activity, sleep, heart-rate-style, and respiratory-rate-style monitoring. Collar health monitoring is still maturing, and we separate what works from what is being tested or on paper in our pet tech market report.
The gap is evidence. We found no recent large independent study validating collar-based disease detection. Tracking location and activity is not the same as diagnosing illness.
The negative signal is hidden inside the consolidation. After Tractive acquired Whistle, Whistle devices were scheduled to stop working, and users were pushed into replacement devices and subscriptions.
The category is moving from “where is my dog?” to “is my dog’s health changing?” But it still needs data on retention, vet integration, and clinical usefulness before it can be called an established health platform.
Are smart feeders, fountains, and litter boxes breaking out?
Smart pet appliances are innovating quickly, but the evidence of breakout demand is weaker than the evidence of product launches.
CES 2026 was full of connected pet products. PETKIT presented an AI pet-care ecosystem covering feeders, fountains, litter boxes, and health signals, including an AI wet-food feeder positioned around urinary health. Ecovacs showed LilMilo, an AI-powered pet companion.
Small funding rounds keep coming. In August 2026, TechCrunch reported that Hoomanely raised $1.8 million in pre-seed funding for a sensor-equipped bowl that records food, water, and behavior signals to flag when a dog may be sick. The startup was still planning clinical validation and had not published accuracy results.
That tells us founders still see the pet home as a smart-home extension, and the pitch is shifting from convenience to health: water intake, food intake, toilet behavior, and routine changes.
But we need to be strict. There are many launches, but little hard data on sell-through, repeat purchase, churn, or paid-subscription retention.
That is why this segment should not carry the whole “Pet Tech is growing” argument. It is a visible innovation segment, not yet a proven mass-adoption segment.

In our report covering the pet tech market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Are diagnostics growing even if fewer pets visit the vet?
Yes. Diagnostics keep growing strongly, and that is one of the most important contradictions in the Pet Tech Market right now.
IDEXX reported Q2 2026 revenue of $1.22 billion, up 10% as reported and 9% organically. Its companion-animal diagnostics recurring revenue grew 11% as reported and 10% organically. It placed more than 1,600 inVue Dx analyzers in the quarter, taking the installed base past 9,000. It narrowed its 2026 revenue outlook to $4.70 billion to $4.745 billion and nudged the midpoint up.
This looks contradictory next to Zoetis reporting lower clinic visits in the same quarter. But it makes sense. If routine visits are under pressure, the visits that still happen may be more serious and more diagnostic-heavy. Older pets, chronic conditions, and more instruments inside clinics can support growth even when visit counts weaken.
This is why “vet visits are down” does not automatically mean “pet health tech is down.” Value is shifting from routine visits toward testing and treatment.
That is good for IDEXX-like infrastructure, but worse for businesses relying on casual, discretionary, or low-acuity visits.
Are pet marketplaces like Wag still investable?
Pet service marketplaces still look like one of the weakest Pet Tech models.
Wag’s July 2025 Chapter 11 filing is the clearest example. A company that once represented the app-based pet services story ended up restructuring, with ownership expected to transfer to its secured lender. We found no reported recovery, new funding, or scaled revenue since. A labor-heavy marketplace ending in restructuring is a reminder of what failed startups share, which we study in our market report about pet tech.
The issue is structural. Dog walking, sitting, grooming, and local services are hard to turn into high-margin software-like businesses. They involve trust, insurance, labor availability, local density, cancellations, customer support, and price sensitivity. When budgets tighten, marketplaces that depend on discretionary service frequency are exposed.
This does not mean pet services are disappearing. But the “Uber for pets” logic is weaker than the insurance, diagnostics, ecommerce, or veterinary software logic.
The market is rewarding recurring, high-need, data-rich models more than transaction-heavy local labor platforms.
Are big Pet Tech companies buying weaker players, or building stronger platforms?
Mostly building stronger platforms. Big players are buying to own the recurring customer and clinic relationship.
The clearest recent example is IDEXX buying CoVet in September 2026, adding AI workflow software to its diagnostics business. Chewy is doing the same on the consumer side: it completed its Modern Animal vet clinic acquisition in May 2026, and management said on its September earnings call that Chewy Vet Care clinic revenue grew at a triple-digit rate in fiscal Q2.
Tractive buying Whistle in 2025 shows the hardware version. Scale matters in hardware-plus-subscription models: more users, more data, better retention economics, and broader brand trust.
But consolidation is also a stress signal. Existing Whistle devices were being shut down after the deal, which shows that consolidation can be painful for customers and can destroy old installed bases.
So consolidation is less a sign of booming demand than a sign of market selection. Winners are getting bigger, and weaker platforms are being absorbed, sunset, or forced into migration.

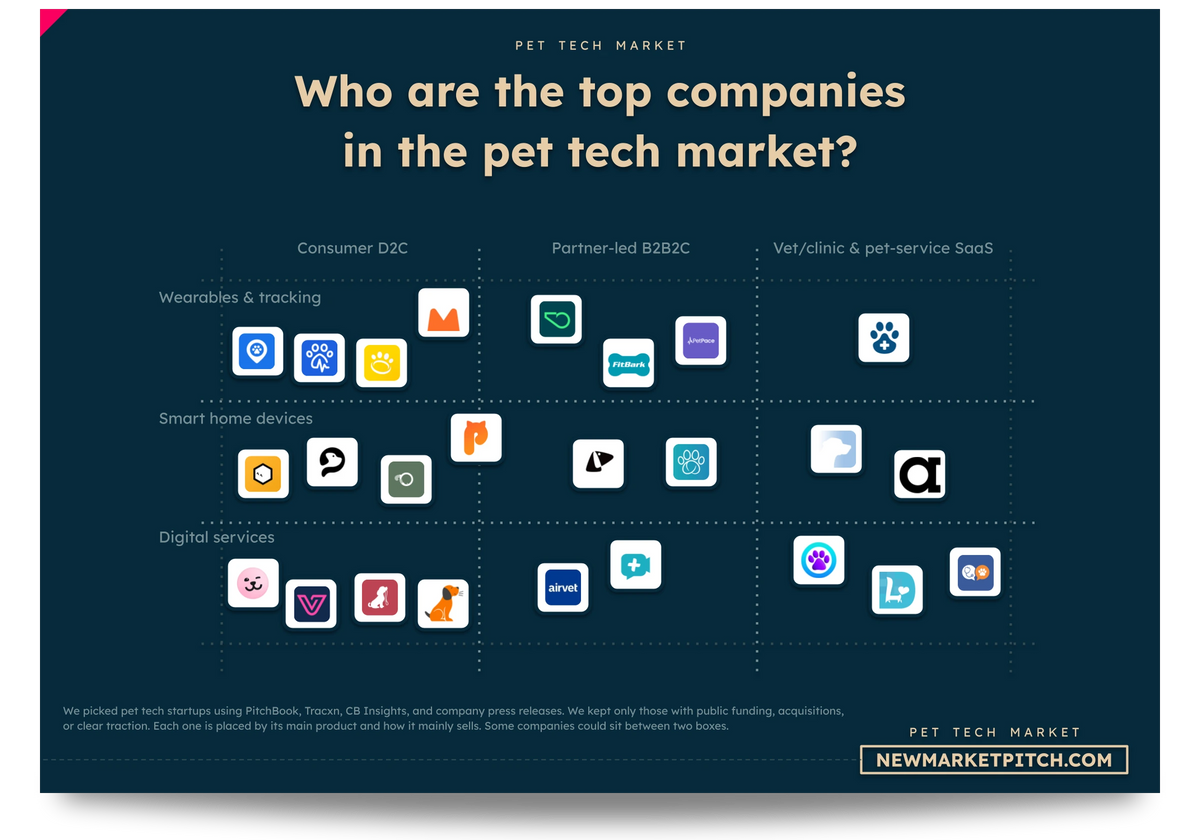
In our research about pet technology, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Are pet parents adopting more pets, or just spending more on existing pets?
Pet Tech is relying more on monetizing existing pets than on a wave of new pet households.
APPA’s 2026 State of the Industry data said 95 million U.S. households owned at least one pet in 2025. Dog ownership rose from 51% of U.S. households in 2024 to 53% in 2025, and cat ownership reached 53 million households, helped by Gen Z and Millennials. That is supportive, but not explosive. We found no newer national ownership figures.
Chewy’s 3.8% rise in active customers is a good sign for Chewy, but it does not tell us how many households adopted a pet. Some of those gains may simply be customers moving from stores.
The adoption-side signals are softer. Hill’s 2025 shelter adoption report highlighted cost, doubt, and guilt as barriers to adoption, and Bank of America Institute coverage tied rising ownership costs to weaker adoption and fewer vet visits.
The current growth engine is therefore not “more pets” but more revenue per pet. That is why insurance, Autoship, diagnostics, subscriptions, and health products matter more than raw pet-count growth.
Is premium pet care holding up as Zoetis cuts its 2026 outlook?
Partly. Premium products tied to daily feeding or urgent health are holding up. Premium products that can be delayed are not.
Freshpet is the clearest positive signal. In August 2026, it reported Q2 net sales of $305.6 million, up 15.5%, with volume up 15.7%. It raised its 2026 growth outlook to 10% to 12%. That is real volume growth in a market where many households are watching costs.
The contrast is Zoetis. Its Q2 companion-animal revenue fell 5%, and it cited price sensitivity for key dermatology products and its Simparica Trio parasite treatment. Chewy also said treats and premium extras slowed. Petco’s total sales were roughly flat. That tells us “premium” is not one bucket. Premium that holds up is a business-model question, and we compare which models keep their margins in our report covering the pet tech market.
Pet parents are not rejecting premium pet care. They are forcing a sharper test: does this product protect health, replace something necessary, or clearly improve daily care?
Is veterinary telehealth finally becoming useful?
Veterinary telehealth is slowly becoming more useful, but it is still shaped by regulation and use-case limits.
Research and Markets’ 2026 veterinary telehealth report estimates the market growing from $2.05 billion in 2025 to $2.61 billion in 2026, a 27.3% increase. That is a forecast, but one of the fastest around the broader Pet Tech stack. Pet owners want cheaper, faster advice, and clinics need better ways to triage demand.
The strongest use cases are not full remote diagnosis. Teletriage, post-visit follow-up, chronic-condition monitoring, behavioral support, nutrition advice, and dermatology check-ins are easier to scale than replacing the in-person exam.
Regulation still sets the limits, especially around veterinarian-client-patient relationships and prescribing. From July 2026, Florida has required vets to tell clients they can get a written prescription, including electronically during telehealth visits. No nationwide change has made a fully virtual first visit legal everywhere.
So telehealth is growing, but the smart interpretation is narrower.

Our market report about pet technology gets updated several times a month, so you always get the latest view of where things stand.
Are regulations making Pet Tech easier or harder to grow?
Regulation is making Pet Tech more important, but not always easier.
The U.K. veterinary market investigation is the clearest signal. In March 2026, the Competition and Markets Authority concluded its investigation and set reforms around price transparency, prescription-fee caps, clearer ownership disclosure, written estimates for higher-cost treatments, and information about cheaper online medicines.
In the U.S., Florida’s prescription disclosure rule took effect in July 2026. Vets must tell clients they can ask for a written prescription, including in telehealth consultations. That can push more medicine sales toward online pharmacies, but it is not a broad loosening of virtual vet rules.
Both changes create openings for companies that help owners compare prices, buy medicines online, or use insurance better.
But regulation can also pressure clinic margins. If price transparency reduces markups on medicines, some practices may push harder into subscriptions, care plans, insurance partnerships, or operational software.
In other words, regulation does not simply “help” or “hurt.” It changes where value can be captured.
Are investors still funding Pet Tech, or has capital moved on?
Investors are still funding Pet Tech, but they are funding a narrower, more serious version of the market.
The bigger rounds cluster around insurance, veterinary software, diagnostics, biotech, and AI-enabled care. Lassie raised $75 million in February 2026. Digitail raised $23 million in November 2025. Gallant raised $18 million in June 2025 for ready-to-use stem cell therapies for pets. More recent checks are small: Wonderdog was reported to have raised $5 million in pre-seed funding in July 2026 for at-home blood testing, and Hoomanely raised $1.8 million in August.
That pattern matters. Investors in the Pet Tech Market are backing models tied to expensive problems: vet bills, clinic bottlenecks, chronic disease, claims processing, and preventive care. Investors backing models tied to expensive problems is one reading of where the money goes, covered in our report on pet tech.
Exits matter too. The CoVet sale to IDEXX shows a real exit path in vet software, although the price was not disclosed. We found no reliable total for Pet Tech funding in recent months, so the honest reading is selective, not absent.
So, is the Pet Tech Market growing right now?
Yes, the Pet Tech Market is growing right now, but the growth is uneven and concentrated.
The strongest areas are recurring online pet commerce, veterinary diagnostics, AI clinic software, and health-linked fresh food. Chewy, IDEXX, and Freshpet all grew and raised or narrowed their 2026 outlooks upward in their latest quarter, and IDEXX’s CoVet deal shows big players paying for vet AI. Insurance is still growing in revenue, but not in total pets covered at Trupanion.
The weaker areas are vet visits, pet-health drugs that owners can delay, discretionary smart gadgets without usage proof, flat pet retail, and labor-heavy pet marketplaces. The biggest risk is not that people stop caring about pets. It is that owners become more selective because vet care, services, and pet ownership are getting expensive.
| Question | Verdict | Comment |
|---|---|---|
| Are Pet Tech analysts still bullish? | Yes | Several firms forecast double-digit growth, but definitions vary across hardware, software, insurance, and services. |
| Is Chewy proving strong Pet Tech demand? | Mixed | Sales up 7.3% and outlook raised, but 5.7% without acquisitions and spend per customer up only 1.9%. |
| Are pet owners really spending more? | Mixed | APPA forecasts higher spending, but roughly half of projected 2026 growth comes from inflation. |
| Are pet owners pulling back on vet care? | Yes | Zoetis cited lower clinic visits and cut its 2026 outlook; U.S. companion-animal sales fell 11% in Q2. |
| Is pet insurance still growing? | Mixed | Trupanion revenue rose 11%, but total enrolled pets fell 2%; growth leans on pricing. |
| Are AI vet tools actually selling? | Yes | IDEXX bought CoVet, used daily by tens of thousands of vet professionals; price not disclosed. |
| Are smart collars becoming health tools? | Mixed | Tractive and Fi show product momentum, but clinical validation and retention proof remain limited. |
| Are smart pet appliances breaking out? | Not enough evidence | Launches and small rounds like Hoomanely’s are numerous, but sell-through and validation data are thin. |
| Are diagnostics growing despite fewer vet visits? | Yes | IDEXX recurring diagnostics grew 11% in Q2, and inVue Dx passed 9,000 installed units. |
| Are pet marketplaces still investable? | No | Wag’s Chapter 11 exposed structural weakness in labor-heavy, discretionary service marketplaces. |
| Are big players absorbing weak platforms? | Mixed | IDEXX-CoVet and Chewy-Modern Animal build platforms; Tractive-Whistle showed migration pain. |
| Are pet households still expanding fast? | Mixed | Ownership is stable to modestly up, but adoption is pressured by cost concerns. |
| Is premium pet care still resilient? | Mixed | Freshpet grew 15.5% on volume, while Zoetis and Chewy report pressure on delayable premium products. |
| Is veterinary telehealth finally useful? | Mixed | Forecast growth is strong, but telehealth is more useful as triage and support than full clinic replacement. |
| Is regulation helping Pet Tech? | Mixed | U.K. reforms and Florida’s prescription rule help online pharmacies, but may pressure clinic economics. |
| Are investors still funding Pet Tech? | Mixed | Capital is active but selective: large rounds in insurance and vet software, smaller recent device checks. |
Our methodology
To answer whether the Pet Tech Market is really growing, we did not rely on a single forecast, headline number, or broad market narrative. We broke the question into the main places where growth or weakness would actually show up: consumer spending, ecommerce, veterinary care, insurance, diagnostics, software, hardware, marketplaces, regulation, and funding.
For each dimension, we looked at recent signals, compared the evidence point by point, and then aggregated the pattern across the market. That structure helped separate real demand from inflation, acquisitions, product-launch noise, old optimism, and isolated company stories.
The final view comes from where the freshest evidence converges. Pet Tech is still growing, but the growth is uneven, selective, and strongest in health-linked, recurring, and infrastructure-like categories.
Key sources used for this analysis include: Chewy fiscal Q2 2026 results, IDEXX Q2 2026 results and diagnostics growth, Zoetis Q2 2026 results and revised outlook, Trupanion Q2 2026 results, Freshpet Q2 2026 results, APPA 2026 State of the Industry, AVMA summary of NAPHIA 2025 pet insurance data, EU-Startups on Lassie’s $75 million Series C, Tractive on its acquisition of Whistle, the U.K. CMA on veterinary-sector reforms, and Chapter 11 Cases coverage of Wag’s bankruptcy filing.

In our document detailing everything you need to know about pet tech, you will always find fresh funding data, taken straight from our own verified funding database.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us