Pet Tech: where's the money now?
Everything we know about the Pet Tech market, in one place. Get our report whether you build or invest.
Summary
Pet Tech investment is currently flowing toward categories that make pet care recurring, medical, data-rich, or operationally integrated.
The strongest signal is not “pets are a big market.” It is that investors and strategic buyers are concentrating around categories with repeat owner relationships, clinical workflows, measurable revenue, and clear expansion paths.
Pet insurance is still the largest capital pocket. Lassie’s $75 million Series C stands out because it came with about 250,000 covered pets, roughly $100 million in ARR, and a prevention-led product loop. Trupanion’s second quarter of 2026 adds a nuance: subscription revenue grew 14%, but total enrolled pets fell 2%.
Veterinary AI now has the freshest proof in the market. In September 2026, IDEXX acquired CoVet, an AI scribe and workflow tool, for an undisclosed price. Together with Lupa’s fast $20 million Series A, it shows clinics are buying tools that solve real capacity and admin pain, and big incumbents are buying the companies that make them.
Full-stack veterinary care is still investable, but the bar is higher than before. Chewy now owns Modern Animal, and Supertails and Vetic raised large rounds in India: money is available when the model has clinic density, revenue scale, or a broader care ecosystem.
Fresh pet food is no longer just a DTC story. Butternut Box and KatKin raising large debt or mixed debt-equity packages, and The Farmer’s Dog making its first acquisition in 2026, show capital moving into manufacturing capacity, repeat demand, and consolidation.
Connected pet devices are becoming more interesting when they move beyond GPS. Tractive’s Whistle acquisition, its newer health features, and small early rounds such as Hoomanely’s smart bowl point to a shift from gadget sales toward continuous pet health data.
Pet commerce is only attractive when it attaches itself to care or to recurring orders. Chewy’s Autoship made up 84.6% of its net sales in its latest quarter, and Supertails ties its commerce layer to clinics, at-home vet services and quick delivery.
Pet pharmacy has momentum, but it is less visible because the money signal is more about M&A and platform logic than headline startup rounds. It becomes more valuable as insurance, clinics, vet software, and chronic care grow around it.
Diagnostics and longevity are getting more early rounds, such as Wonderdog’s reported $5 million pre-seed and Elita’s reported A$1.9 million, but the checks are still small. Their real value may come when they plug into insurance prevention, vet triage, food personalization, or long-term health monitoring.
Local services are clearly not the hottest money pocket today. Grooming, boarding, walking, and sitting can produce useful repeat behavior, but the models remain local, labor-heavy, and harder to scale with venture-style speed. Local, labor-heavy services are hard to scale, and we compare which pet tech business models actually make money in our market report about pet tech.
The conclusion is fairly clear: Pet Tech money is moving away from generic pet-parent apps and toward infrastructure-like categories that own the relationship, generate recurring data, reduce care friction, or control the clinical and commercial loop.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

In our report covering the pet tech market, you will always find fresh funding data, taken straight from our own verified funding database.
What are the main company categories in Pet Tech?
Before asking where money is flowing in Pet Tech, we need to make the market readable.
“Pet Tech” is too broad as a label. It mixes insurance, vet clinics, food, devices, diagnostics, pharmacy, marketplaces, and local services, and those categories do not attract money for the same reasons. Pet tech mixes insurance, clinics, food and devices, so we spell out what counts and what does not in our report on pet tech.
Once we know what each bucket really contains, we can look at each one with the same question: is money actually flowing there right now, or is the category mostly living off older headlines?
| Category | What the category does | Example companies |
|---|---|---|
| Pet insurance and financing | Helps owners pay for care through insurance, claims automation, care plans, and prevention-led coverage | Lassie, ManyPets, Napo, Dalma, Paw Protect |
| Veterinary clinics and full-stack care | Builds tech-enabled vet clinics, online/offline care models, urgent care, memberships, pharmacy, and commerce around the clinic | Modern Animal (Chewy), Bond Vet, Supertails, Vetic, Small Door |
| Veterinary software and AI workflow | Gives clinics software for scheduling, records, AI notes, client communication, workflow automation, and practice operations | Lupa, CoVet (IDEXX), Digitail, Scribenote, PetDesk, Vetspire |
| Fresh and functional pet food | Sells premium, fresh, personalized, or health-oriented food with recurring delivery and stronger nutrition positioning | Butternut Box, KatKin, The Farmer’s Dog, Smalls, Ollie |
| Connected pet devices and wearables | Tracks pet location, activity, behavior, and increasingly health signals through collars, GPS trackers, feeders, and cameras | Tractive, Whistle, Fi, Petcube, Halo Collar, Hoomanely |
| Pet commerce and marketplaces | Sells pet products online, often with subscriptions, quick delivery, pharmacy, services, or vet-linked recommendations | Chewy, Supertails, Zooplus, Pet Circle |
| Pet pharmacy and therapeutics access | Handles prescriptions, chronic medication, online pharmacy, vet-linked fulfillment, and medication access | Chewy Pharmacy, PetMeds, Mixlab, Vetsource |
| Pet diagnostics and genomics | Provides DNA tests, at-home lab tests, microbiome tests, early detection, and pet health data products | Basepaws, MySimplePetLab, Petwealth, Wonderdog, AnimalBiome |
| Grooming, boarding, walking and local services | Organizes local pet services such as grooming, sitting, walking, daycare, boarding, and at-home care | Rover, Wag!, BhaoBhao, PetBacker |
| Pet longevity and advanced wellness | Targets longer pet healthspan through preventive science, supplements, therapeutics, cellular health, and advanced monitoring | Loyal, Gallant, Elita, AnimalBiome |
Is money flowing into pet insurance and financing right now?
Pet insurance is where money is flowing most clearly in Pet Tech right now.
The obvious signal is Lassie’s $75 million Series C in February 2026.
But the more useful signal is, if we look deeper, the quality behind the round: the company reportedly covers about 250,000 pets, generates roughly $100 million in ARR, and has daily app engagement around 25%.
That last number matters because insurance apps are usually opened only when something goes wrong. If a pet insurance product gets daily usage, it starts to look less like a claims wrapper and more like an everyday pet health product.
Lassie’s round included Balderton, Felix, Inventure, Passion Capital, and Stena Sessan, and came with a specific plan: AI claims, preventive care, and European rollout.
The listed side of the market gives a more mixed read. Trupanion said in its August 2026 results that second-quarter revenue rose 11% to $392.9 million and subscription revenue rose 14% to $276.7 million. Subscription pets grew 5% to about 1.12 million. But total enrolled pets fell 2% to about 1.63 million. Revenue is growing faster than the number of pets, so part of the growth comes from price, not from new owners. We did not find a new insurance venture round in the past few months that matches Lassie’s.
The money still flows into insurance because it gives investors a paid relationship with the owner before the vet visit. The company that owns the insurance layer can influence care habits, collect health data, push prevention, and potentially reduce claim costs. That is why the category still ranks first, though the lead now rests on Lassie’s round more than on broad volume growth.

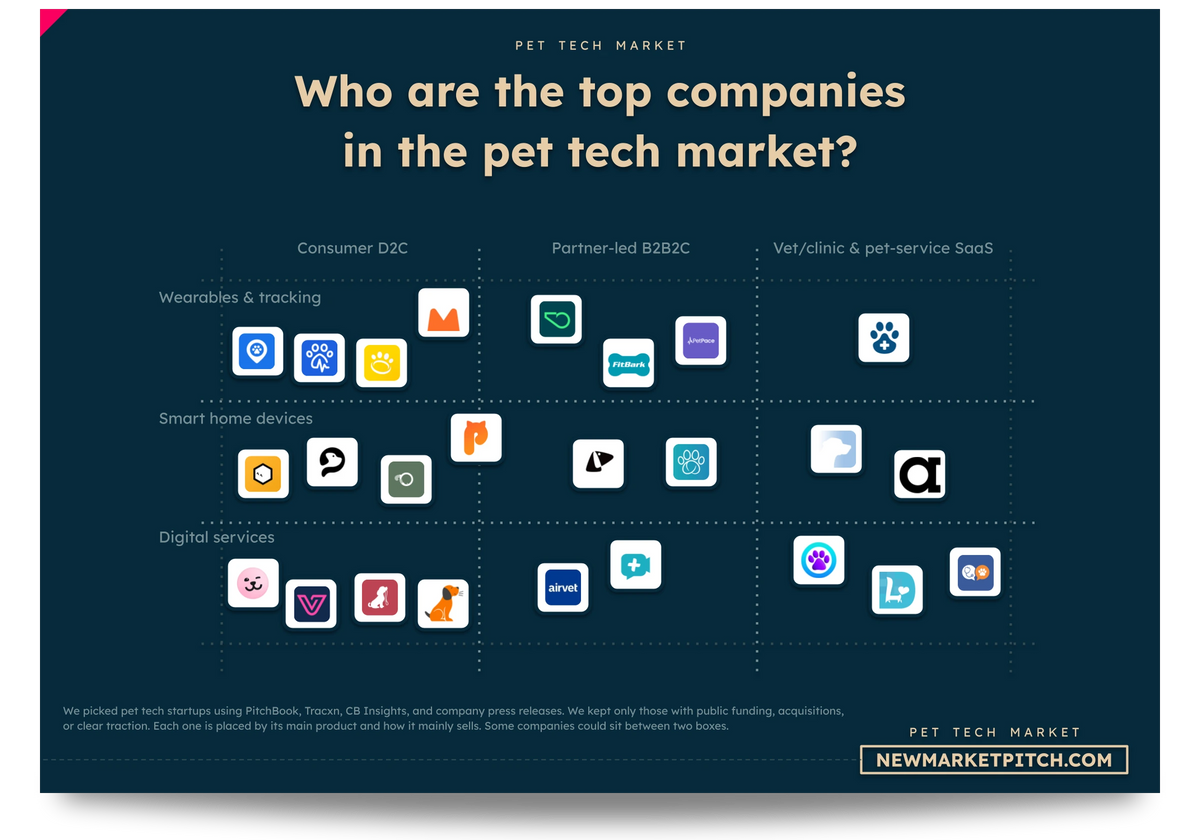
In our research about pet technology, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is money flowing into veterinary clinics and full-stack care right now?
Money is flowing into full-stack veterinary care, but only when the operator already shows real density and real revenue.
Modern Animal is the strongest US signal. In September 2025, it announced $46 million in new funding after reaching roughly $100 million in annual run rate and 85% year-over-year revenue growth in 2024. Then Chewy bought it, in a deal that closed in May 2026. In its September 2026 filing, Chewy already counted Modern Animal in its quarterly sales.
The scale markers explain the exit. Modern Animal operated around 27 clinics and served more than 100,000 pets and families when it raised. The buyer is a $3.3 billion-a-quarter retailer that wants clinics next to its pharmacy and Autoship base. That is the clearest sign that the clinic itself is becoming part of a commerce and care loop.
India gives the category a second, very different signal. In February 2026, Supertails raised $30 million led by Venturi Partners, with participation from Nippon India Alternative Investments, Titan Capital Winners Fund, Fireside Ventures, RPSG Capital Ventures, Sauce VC, and Saama Capital, for clinics, at-home vet services, quick delivery, supply chain, data, and offline expansion. In June 2026, Vetic, a clinic chain with more than 65 clinics in 11 cities, reported a $40 million round led by Bessemer Venture Partners.
In mature markets, money likes vet care when the operator proves clinic-level scale, and the exit is often a strategic buyer. In emerging pet markets, money likes integrated systems that build the care habit from scratch. The common thread is control of the pet care relationship, not just a better booking interface.
Why did IDEXX buy CoVet, and is vet AI money still flowing?
Yes, vet AI money is still flowing. IDEXX bought CoVet to own the AI layer inside the clinic rather than leave it to others. Veterinary AI software is the freshest money pocket in Pet Tech, and it now has a strategic exit to show for it.
On 16 September 2026, IDEXX announced it had acquired CoVet, which makes AI ambient listening and documentation software for vet practices. The price was not disclosed. CoVet says tens of thousands of veterinary professionals use it daily, a company claim. IDEXX said CoVet will join its software ecosystem but keep working with practice systems outside IDEXX.
That matters because IDEXX is a major diagnostics and software supplier to vets. Its recurring diagnostics revenue grew 11% in the second quarter of 2026, and its software, services and imaging line grew 12%. When that kind of buyer pays for an AI scribe, it means the AI layer is worth owning, not just licensing.
On the venture side, there is Lupa. It raised a $20 million Series A in October 2025 only five months after its seed round, after reporting 50x revenue growth since that prior round. A five-month seed-to-Series-A move usually means investors saw something moving unusually fast, either customer demand, revenue conversion, or both.
The investor signal is also strong. The round was led by Singular, with participation from existing investor Firstminute Capital and angel investors. Existing investor participation matters here because it suggests the insider read was positive enough to follow on quickly. Lupa also says its product replaces seven legacy tools, saves vets about 60 minutes per day, and doubles ROI on software spend. Saving vets an hour a day addresses real pain, and we study who would pay to fix it in our report on pet tech.
The buyer pain is obvious. Vets are overloaded, clinics are capacity constrained, and admin work eats time. If software gives a vet back one hour a day, the ROI is easier to explain than a consumer app that hopes owners remember to open it.
The tension is distribution. Standalone AI scribes now compete with tools owned by the vendors that already sit in the clinic. That raises the bar for the next startup round, but it also gives founders a clear exit path. Right now, this is one of the few Pet Tech categories where “AI” does not feel decorative.

Your time is limited. In our market report about pet technology, we put numbers on each part of the market, so you can see where it makes sense to focus.
Is money flowing into fresh and functional pet food right now?
Money is flowing into fresh and functional pet food, but mainly into scaled brands that already proved demand.
Butternut Box is where we are looking at. In May 2025, it secured more than €75 million in debt financing from Liquidity to build a second manufacturing facility in Poland. That is not the same kind of signal as a seed round. Debt at this size usually tells us lenders see enough revenue visibility, repeat purchasing, and production economics to underwrite expansion.
KatKin adds a second interesting signal for us, on the cat side. In late 2025, it secured $50 million through a mix of equity and debt, while claiming more than 100 million meals delivered and about 2% of the UK cat food market. That 2% figure is small in absolute terms, but big for a fresh cat food specialist. Cat food is a massive incumbent market, so a young brand reaching measurable national share is more meaningful than another DTC brand saying “premiumization is growing.”
Also, there is the structure of the money. Both Butternut Box and KatKin raised capital that included debt. That suggests the category is maturing. Investors are no longer just funding the story that pets eat better food. They are funding factories, capacity, distribution, and proven repeat demand.
The leaders are also starting to buy. In September 2026, The Farmer’s Dog completed its first acquisition, Woof, a maker of refillable enrichment products such as the Pupsicle; the price was not disclosed. At retail level, Petco said in its September 2026 results that consumables grew while total sales were almost flat. Food is the part of the basket that keeps selling.
So yes, money is flowing here today, but not evenly. We found no large new fresh-food startup round in recent months. The market rewards companies that already have production scale and repeat orders, not small brands with a nice subscription website.
Is money flowing into connected pet devices and wearables right now?
Money is flowing into connected pet wearables now.
However, it looks more like consolidation than a funding frenzy.
The biggest clue is still Tractive acquiring Whistle from Mars Petcare in July 2025. Whistle was not a random small device company. Mars bought Whistle in 2016 for about $117 million, then later sold it to Tractive. That tells us the category is being sorted around focus and scale. A strategic owner can decide the asset fits better inside a specialist subscription platform than inside a broader pet conglomerate.
Tractive also reported more than 1.4 million active users worldwide and millions of devices sold. That matters because wearables are hard: hardware margins, churn, connectivity costs, customer support, and device replacement can all hurt the model. A large active base makes the subscription layer more credible.
The April 2026 product launch adds the more interesting direction. Tractive’s new trackers pushed deeper into health: resting heart rate, respiratory rate, scratching behavior, territory analysis, and app-based health intelligence. So the category is shifting from “find my dog” to “tell me if my pet’s health is changing.”
Early rounds follow the same idea. In August 2026, Hoomanely reportedly raised $1.8 million in pre-seed funding for a sensor-equipped dog bowl that tracks eating and drinking to flag when a dog may be sick. The check is small, and its alert accuracy and paying user base are not disclosed.
That is why we would not treat this as a simple gadget market anymore. The best device companies are trying to become continuous pet health data platforms, but we found no large new collar or tracker round in recent months.

In our document detailing everything you need to know about pet tech, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Is money flowing into pet commerce and marketplaces right now?
Money is flowing into pet commerce only when commerce is attached to care.
Supertails is the best recent example. Its $30 million February 2026 round was not positioned as a plain online pet store. The company talked about clinics, at-home veterinary services, quick delivery, supply chain, personalization, and offline expansion. That tells us investors are not paying up for “we sell pet products online” but for actual commerce that becomes part of the pet care routine. Investors backing commerce tied to care, not plain online shops, shows where the money goes, which we follow in our market report about pet tech.
There is another subtle signal: Supertails has pushed quick commerce with more than 30,000 SKUs in Bengaluru, while also building vet and clinic touchpoints. That matters because the product shelf and the medical relationship can reinforce each other. A pet parent who buys food, books a vet, uses home care, and receives delivery from the same platform is more valuable than a one-off marketplace customer.
The listed leader shows the same logic at scale. Chewy said in September 2026 that second-quarter net sales rose 7.3% to $3.33 billion and Autoship sales rose 9.3% to about $2.82 billion, or 84.6% of net sales. Recurring orders, pharmacy and clinics keep the customer.
So the answer is yes, but with a big filter. Pet commerce is interesting now when it has a reason to own the customer beyond price and convenience. Generic marketplaces look much less exciting, and we found no new large marketplace round.
Is money flowing into pet pharmacy and therapeutics access right now?
Pet pharmacy has money momentum today, but it’s more about M&A and platform logic than splashy startup rounds.
Capstone’s April 2026 pet sector update says pet M&A activity has picked up year-to-date, after some 2025 deals were delayed. More importantly, it calls out pet pharmacy evolution as a category to monitor, partly because regulatory changes have made the space more scalable and financeable. That matters because pharmacy becomes attractive when buyers can imagine roll-ups, institutional capital, and platform strategies.
The second signal is where pharmacy sits in the care stack. It benefits from almost every other strong category. More insurance can support more reimbursed care. More vet software can make prescription workflows smoother. More full-stack clinics can push integrated medication access. More chronic pet care means more recurring fulfillment.
Capstone also points to stronger buyer appetite across Services, Vet & Health, and Products in 2026. Pharmacy sits in the middle of that triangle: clinical enough to matter and recurring enough to be financially attractive.
Regulation keeps moving in the same direction. In July 2026, Florida’s veterinary board published guidance on prescription-disclosure rules that support owners’ right to fill prescriptions outside the clinic. That can shift some margin toward pharmacies, but it is a rule change, not a funding round. We found no new pet-pharmacy startup round in recent months.
So money is flowing here, but it is less visible than in Lassie, Lupa or CoVet.

Our report covering the pet tech market gets updated several times a month, so you always get the latest view of where things stand.
Is money flowing into pet diagnostics and genomics right now?
Some money is flowing into pet diagnostics, but it is still selective and early compared with insurance or vet AI.
The largest recent startup signal is Wonderdog. In July 2026, it reportedly launched an at-home blood-testing membership for dogs, with AI-based health insights, and disclosed $5 million in pre-seed funding. Its predictive accuracy and subscriber count are not disclosed. Earlier, in April 2026, Petwealth announced $1.7 million for at-home PCR diagnostics and AI health insights. Both point the same way: diagnostics tied to AI insights and a membership, rather than a one-off test kit.
The incumbent side is much bigger. IDEXX said in August 2026 that its recurring diagnostics revenue for companion animals grew 11%, or 10% organic. That is operating revenue, not venture money, but it shows owners and clinics keep paying for testing.
MySimplePetLab sits in distributed pet testing for vets and pet parents, while Basepaws remains one of the better-known pet genetics references. But startup rounds here are still small next to insurance, fresh food, or veterinary AI. If we are ranking where money is flowing now, diagnostics should not be artificially pushed to the top.
The interesting read is that diagnostics probably becomes more valuable when it plugs into other categories. A test result can support insurance prevention, vet triage, food personalization, chronic care, or longevity tracking. Alone, it can be a nice consumer product. Inside a care loop, it becomes data infrastructure.
Is money flowing into grooming, boarding, walking and local services right now?
Money is not flowing strongly into local pet services right now.
There are small signals. BhaoBhao, a Mumbai-based at-home grooming startup founded in 2025, raised $200,000 from angel investors in August 2025. It also claimed more than 3,000 clients in Mumbai and a 95% repeat rate. That repeat rate is the most useful part of the signal because grooming can become habitual if trust is high and the experience is convenient.
But the round size tells the bigger story. Compared with $75 million for Lassie, $46 million for Modern Animal, $30 million for Supertails, $20 million for Lupa, or $50 million for KatKin, local services are clearly not where the largest current money is concentrating. Local services trailing the biggest rounds by this much is the kind of signal we track every quarter in our pet tech market report.
The reason is simple. Grooming, sitting, boarding, and walking are operationally local. They need labor, scheduling, quality control, customer trust, and city-by-city execution. That can build good businesses, but it is harder to underwrite as a fast-scaling venture category unless the company has strong density or a broader ecosystem around it.
We found no sizable new round or acquisition in grooming, boarding or walking in recent months. That does not prove the sector is shrinking, but it confirms this is not one of the hottest Pet Tech money pockets right now.
Are dog longevity startups like Elita and Wonderdog drawing real money?
Some, but the checks are small. Pet longevity has investor interest, and the money signal is still more selective than mainstream.
The category benefits from the same shift we see elsewhere in Pet Tech: owners are spending more on prevention, early detection, chronic care, and healthspan. If people treat pets more like family, products that promise more healthy years are emotionally and economically powerful.
The new rounds are real but early. In September 2026, Melbourne-based Elita reportedly raised A$1.9 million to build a dog longevity and preventive-care service. Wonderdog’s $5 million pre-seed also targets earlier disease detection. Neither shows that longevity products extend healthy years, and neither has disclosed large recurring revenue. Compared with insurance, vet AI, fresh food, or full-stack care, the money trail is still thin.
That is why we should treat pet longevity as an option-value category today. It could become very important if companies bring credible science, proprietary data, regulatory clarity, or vet distribution. Without that, it can quickly become vague wellness language.
So yes, some money is moving around the edges of longevity and advanced wellness, but today it looks more like an early frontier than a category where broad capital is rushing in.

In our research about pet technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
So where is the money in Pet Tech right now?
Pet Tech money is currently flowing toward categories that make pet care recurring, medical, data-rich, or operationally integrated.
The ranking is clearer after looking category by category.
Insurance still comes first because Lassie combines large funding, ARR, covered pets, engagement, and strong investors, even if Trupanion shows revenue growing faster than pet counts.
Veterinary AI is now neck and neck. IDEXX’s purchase of CoVet gives the category a completed strategic exit, on top of Lupa’s five-month seed-to-Series-A jump. If the next big round goes anywhere in Pet Tech, it is most likely here.
Full-stack veterinary care comes next because Chewy’s purchase of Modern Animal, Supertails and Vetic show that buyers and investors still want care platforms with real scale or a large ecosystem angle.
The figures are not of the same kind. Startup rounds, acquisitions with undisclosed prices, and listed companies’ operating revenue cannot be added up into one “money flowing” total.
| Rank | Category | Why this is where money is flowing now |
|---|---|---|
| 1 | Pet insurance and financing | Lassie raised $75M in 2026; around $100M ARR; about 250k pets covered; Trupanion Q2 2026 subscription revenue +14% but total enrolled pets −2% |
| 2 | Veterinary software and AI workflow | IDEXX acquired CoVet in September 2026 (price not disclosed); Lupa raised $20M only five months after seed; reported 50x revenue growth |
| 3 | Veterinary clinics and full-stack care | Chewy acquired Modern Animal (closed May 2026); Supertails raised $30M; Vetic reported $40M in June 2026 for 65+ clinics |
| 4 | Fresh and functional pet food | Butternut Box secured €75M+ debt for manufacturing; KatKin raised $50M; The Farmer’s Dog bought Woof in September 2026 |
| 5 | Connected pet devices and wearables | Tractive acquired Whistle from Mars; 1.4M+ active users; Hoomanely reported $1.8M pre-seed for a health-tracking bowl |
| 6 | Pet pharmacy and therapeutics access | 2026 M&A commentary calls pharmacy a key area; Florida prescription-disclosure guidance (July 2026) supports pharmacy choice |
| 7 | Pet commerce and marketplaces | Chewy Autoship was 84.6% of Q2 2026 net sales; Supertails shows commerce can raise money when linked to clinics and vet services |
| 8 | Pet diagnostics and genomics | Wonderdog reported $5M pre-seed; Petwealth raised $1.7M; IDEXX recurring diagnostics revenue +11% in Q2 2026 |
| 9 | Pet longevity and advanced wellness | Elita reported A$1.9M in September 2026; strong narrative, but rounds remain small and efficacy is unproven |
| 10 | Grooming, boarding, walking and local services | BhaoBhao raised $200k and claims strong repeat usage, but the category remains local, labor-heavy, and less capital-concentrated |
Our methodology
To answer where money is flowing in Pet Tech, we first broke the market into practical company categories and then assessed each one separately.
For each category, we looked at recent signals that show capital attention or strategic momentum: funding rounds, debt financing, acquisitions, revenue scale, user scale, product expansion, investor quality, M&A commentary, and the latest results of listed leaders such as IDEXX, Chewy and Trupanion. We kept startup funding, undisclosed-price acquisitions and operating revenue separate. We gave more weight to fresh signals because the goal was to understand where money appears to be moving now, not where the market has historically been interesting.
We then compared the strength and density of those signals across categories. A large round mattered more when it was supported by revenue, usage, repeat demand, or a clear expansion plan. Likewise, categories with strong long-term narratives ranked lower when the recent public evidence of capital concentration was thinner.
The final ranking is therefore an evidence-weighted view of where capital is concentrating today, based on aggregated recent signals rather than isolated headlines.
Key sources used for this analysis include: dvm360 on IDEXX buying CoVet and The Farmer’s Dog acquiring Woof, IDEXX on its second-quarter 2026 results, Trupanion’s second-quarter 2026 results filed with the SEC, Subscription Insider on Chewy’s Autoship share of sales, GlobalPETS on recent pet M&A deals, YourStory on Vetic’s $40 million round, Balderton on Lassie’s $75 million Series C, PR Newswire on Modern Animal’s funding, run rate, and growth, Lupa on its $20 million Series A, Vet Show on Lupa’s revenue growth, ROI, and time-saved claims, Moneycontrol on Supertails’ $30 million round and expansion plan, EU-Startups on Butternut Box’s €75 million-plus debt financing, Petfood Industry on KatKin’s $50 million funding, 100 million meals, and UK share, Tractive on its acquisition of Whistle, Capstone Partners’ April 2026 Pet Sector M&A Update, Business Wire on Petwealth’s $1.7 million funding and at-home PCR diagnostics, and Indian Startup News on BhaoBhao’s $200,000 funding, client base, and repeat rate.

Theory only gets you so far. In our market report about pet technology, we dig up the real signals from the field and show you the ones worth watching.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us