Pet Tech: what are the top startups?
Whether you're building or investing in the pet tech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The top Pet Tech startups today are Whisker, Fi, PETKIT, Halo Collar, Loyal, Lassie and Petfolk. Whisker leads on disclosed consumer hardware revenue, Fi stands out for subscription growth and capital efficiency, while Loyal has the potential to create an entirely new veterinary pharmaceutical market.
Pet Tech has already produced some substantial businesses. Whisker generates more than $300 million annually, Rover was acquired for $2.3 billion, and Tractive surpassed €100 million in annual recurring revenue before its acquisition by Bending Spoons.
The strongest commercial results have come from relatively practical products. Automatic litter boxes, GPS collars and pet-care marketplaces have scaled faster than more ambitious technologies still waiting for regulatory approval or widespread adoption. Litter boxes and GPS collars already work today while other ideas wait for approval, the split we draw in our report on pet tech.
Fi is particularly impressive relative to its fundraising history. The company expects to exceed $100 million ARR in 2026 after raising approximately $40 million across three venture rounds, showing that a Pet Tech startup can reach serious subscription scale without constant financing.
Whisker and PETKIT demonstrate the size of the connected-appliance opportunity, but their economics differ from subscriptions. Hardware manufacturers must continually manage production, warranties and replacement cycles, while GPS businesses can collect recurring payments from an existing device base.
Pet insurance is becoming another meaningful technology market. Lassie has already exceeded $100 million ARR and insures more than 250,000 pets, although rising veterinary costs mean premium growth alone says little about underwriting profitability.
Veterinary clinics have proved attractive to strategic buyers. Chewy's approximately $400 million acquisition of Modern Animal valued the business at roughly 3.2 times its annualized revenue, creating a useful benchmark for expanding operators such as Petfolk.
Loyal has the greatest scientific upside, but also one of the widest ranges of possible outcomes. Its canine longevity treatments have reached important FDA regulatory milestones, yet none has established through completed pivotal trials that it extends dogs' lifespans.
The broader pet industry is growing much more slowly than its fastest startups. With U.S. pet spending rising approximately 3.7% in 2025, companies growing at double-digit rates are largely creating new spending categories or taking market share rather than benefiting from rapid expansion of the entire industry.
Fundraising is a particularly unreliable measure of success in this sector. Wag!'s bankruptcy contrasts sharply with Fi's capital-efficient expansion and Whisker's years of product-led growth, making customer retention, profitability and recurring revenue more useful indicators than money raised.
Our overall preference among independent startups is Fi for its combination of recurring revenue and growth potential, with Whisker ahead on disclosed sales. Loyal remains the more speculative opportunity, while Rover, Tractive and Modern Animal show what successful Pet Tech exits can look like.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

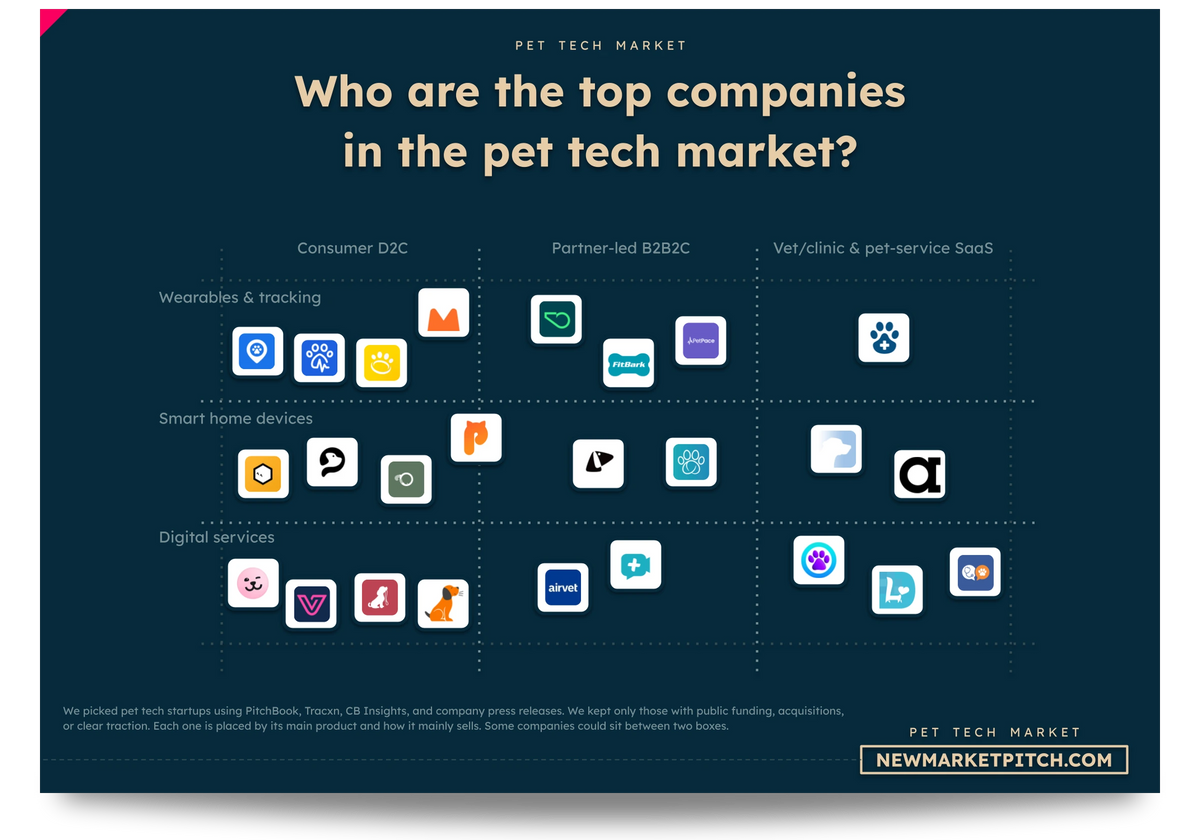
In our report covering the pet tech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Why are Pet Tech startups attracting so much attention now?
Pet Tech has produced several genuinely large businesses, and recent acquisitions show that major investors and pet retailers are taking the sector seriously. Whisker generates more than $300 million in annual revenue, Rover was acquired for $2.3 billion, and Fi expects to cross $100 million in annual recurring revenue. Meanwhile, startups such as Loyal are attracting substantial investment to develop entirely new veterinary treatments.
The market has also entered a period of consolidation. Blackstone completed its acquisition of Rover in February 2024, Bending Spoons acquired Tractive in May 2026, and Chewy bought Modern Animal for approximately $400 million that same year. Where acquirers and investors put their money across pet businesses, and what they now pass on, is covered in our pet tech market report.
Those transactions involve three very different businesses. Rover connects pet owners with caregivers, Tractive sells GPS tracking devices and subscriptions, and Modern Animal operates veterinary clinics supported by digital services.
Some Pet Tech companies have hundreds of millions in sales, others have secured valuable exits, and several promising newcomers are still developing their first commercial products. Comparing their actual achievements is more useful than ranking them by funding alone.
Which Pet Tech startups are the biggest today?
Whisker, Rover, PETKIT, Fi, Halo Collar and Tractive are among the strongest established Pet Tech companies, while Loyal, Lassie and Petfolk stand out for their growth potential. Whisker leads on disclosed specialist hardware revenue, Rover has completed a $2.3 billion exit, and Fi is approaching nine-figure recurring revenue.
Whisker has reported more than $300 million in annual revenue from its automated pet-care products. PETKIT is another major connected-device manufacturer, with approximately RMB 1.1 billion in reported 2024 revenue. The two companies demonstrate how large automated litter systems, feeders and other household devices have become.
Subscription businesses are also reaching meaningful scale. Tractive crossed €100 million in annual recurring revenue in 2024, while Fi expects to exceed $100 million ARR in 2026. Halo Collar reported approximately $99.7 million in annual sales for 2025, although that figure includes hardware revenue and cannot be directly compared with subscription ARR.
The newer contenders have different strengths. Loyal has raised more than $250 million to develop drugs targeting canine longevity, Lassie secured $75 million for its digital insurance platform after surpassing $100 million ARR, and Petfolk is expanding its technology-enabled veterinary clinics.
We also include acquired businesses in the comparison because their transaction values help establish what successful Pet Tech companies are worth. Their ownership status is important, however: Rover, Tractive and Modern Animal are no longer independent startups.
| Company | Main category | Documented achievement | Position today |
|---|---|---|---|
| Whisker | Automated litter systems | More than $300M annual revenue | Major independent hardware business |
| Rover | Pet-care marketplace | $2.3B acquisition in 2024 | Established marketplace, now private |
| PETKIT | Connected pet appliances | Approximately RMB 1.1B reported 2024 revenue | Major Chinese smart-device manufacturer |
| Fi | GPS and health wearables | Expected to cross $100M ARR in 2026 | Leading independent subscription startup |
| Tractive | GPS and health monitoring | More than €100M ARR in 2024 | Acquired by Bending Spoons |
| Halo Collar | GPS fencing and safety | Approximately $99.7M revenue in 2025 | Large connected-collar business |
| Modern Animal | Veterinary clinics | Approximately $400M acquisition in 2026 | Acquired by Chewy |
| Loyal | Animal longevity biotechnology | $100M Series C in 2026 | High-potential drug developer |
| Lassie | Digital pet insurance | More than $100M ARR and $75M Series C in 2026 | Fast-growing European challenger |
| Petfolk | Veterinary healthcare | New financing and clinic expansion in 2026 | Expanding independent clinic operator |

Our research about pet technology gets updated several times a month, so you always get the latest view of where things stand.
Is Whisker the most successful Pet Tech startup?
Whisker is currently one of the strongest Pet Tech companies by actual sales, generating more than $300 million annually from products that automate everyday pet-care tasks. Its Litter-Robot business has achieved a level of commercial scale that many better-funded startups have yet to reach.
According to Whisker's published company history, the business has sold more than one million Litter-Robots and employs over 600 people. Its modern expansion began with the Litter-Robot 3 in 2015, followed by a $31 million investment from Pondera Holdings in 2019 and the company's rebranding to Whisker in 2021.
Whisker's growth is particularly interesting because the company spent years developing the same core product before reaching its current scale. Rather than constantly introducing unrelated devices, it improved its automated litter systems, expanded distribution and built a recognizable brand. The Feeder-Robot subsequently extended the business into another everyday pet-care task.
Competition is becoming more serious, especially from PETKIT. The Chinese manufacturer sells automated litter boxes, smart feeders, water fountains and other connected appliances. Its reported RMB 1.1 billion in 2024 revenue puts it among the largest businesses in the category, although that figure comes from secondary reporting rather than a recent audited public filing.
Whisker and PETKIT also show why hardware can be such an attractive market despite its limitations. An expensive automatic litter box solves a recurring problem, and customers can judge its usefulness almost immediately. These companies don't need to convince people that the problem exists. They need to convince them to pay for a better solution.
Connected appliances have manufacturing costs, warranty obligations and relatively long replacement cycles. Whisker's disclosed revenue proves that demand is real, but detailed margins and repeat-purchase data would tell us much more about profitability.
Is Rover still the biggest Pet Tech success story?
Rover remains one of Pet Tech's biggest proven exits, with Blackstone completing its $2.3 billion acquisition in February 2024. Few companies in the sector have achieved a transaction of comparable size.
Rover built its marketplace around dog walking, sitting, boarding and daycare. Its business benefited from connecting pet owners with independent caregivers rather than having to operate every service location itself.
The company continued expanding after the acquisition. Rover bought Cat in a Flat, extending its reach into cat sitting, and acquired the European pet-care marketplace Gudog. According to Bloomberg's April 2025 reporting, Gudog added approximately 20,000 sitters and walkers across Europe while extending Rover's presence into Ireland and Denmark.
Those deals reveal a clear strategy. Rover is using acquisitions to bring fragmented local pet-care marketplaces onto a larger platform. The model becomes more attractive when owners can find services across more locations and caregivers can reach more customers.
Rover's current revenue is harder to assess because it stopped reporting public-company financial results after the Blackstone buyout. We therefore cannot place its current sales confidently above Whisker's or other private competitors.
Still, the completed $2.3 billion transaction gives Rover something many venture-backed Pet Tech companies lack: a clear, externally established exit valuation.

In our market report about pet technology, we look at what the winners do differently, so you can learn from the best instead of guessing.
Is Fi winning the smart dog collar market?
Fi is currently one of the most impressive independent smart dog collar startups, approaching $100 million in annual recurring revenue while expanding across 38 countries. Its combination of subscription revenue, international growth and limited fundraising makes it particularly interesting.
Fortune reported in July 2026 that Fi expected to cross $100 million ARR during the year. The company also introduced Fi Ultra, a collar using Starlink direct-to-cell satellite technology to improve connectivity outside conventional cellular coverage.
Fi has been unusually restrained with fundraising. According to an August 2026 interview and PitchBook data cited in the reporting, the company previously raised nearly $40 million across three venture rounds and had avoided additional fundraising for roughly five years.
A business approaching $100 million ARR after raising approximately $40 million is worth paying attention to. The figures don't prove profitability, but Fi has reached substantial subscription scale without depending on frequent new venture rounds.
Its competitors show that this opportunity extends beyond one company.
Tractive, the Austrian GPS tracking startup, exceeded €100 million in ARR in 2024 and was acquired by Bending Spoons in May 2026. Halo Collar generated approximately $99.7 million in sales during 2025, according to a September 2026 Business Insider profile.
Each approaches dog safety differently. Fi emphasizes location tracking and health monitoring, Tractive combines GPS tracking with activity and health features for dogs and cats, and Halo focuses heavily on virtual fencing.
Fi's Starlink integration could help differentiate its product, particularly in places with limited cellular coverage. But the technology's commercial impact will depend on real-world reliability, coverage, pricing and whether customers keep paying after purchasing the device.
Three connected-collar businesses have now independently reached or approached the $100 million annual revenue or ARR level. Pet wearables have moved well beyond the niche-gadget stage. Pet wearables outgrowing the gadget stage is a signal we watch quarter by quarter in our report covering the pet tech market.
Is pet insurance becoming the next big Pet Tech opportunity?
Pet insurance is one of the largest opportunities for Pet Tech startups, but growing premiums don't automatically mean insurers are making more money. Claims costs are rising too, and some of the industry's recent expansion reflects higher prices rather than a surge in new customers.
According to the North American Pet Health Insurance Association's 2026 State of the Industry Report, approximately 7.6 million pets were insured across the United States and Canada in 2025. Total premiums reached roughly $6.15 billion, growing 19.4% year over year.
The number of insured pets grew much more slowly: approximately 9% in the United States and 3.9% in Canada. That gap suggests premium increases and changes in coverage contributed substantially to revenue growth.
Insurance penetration also remains low. Only about 4.3% of U.S. pets are insured, leaving a potentially large market for companies that can make policies more appealing and affordable.
Lassie, ManyPets and Napo are pursuing that opportunity through digital distribution and customer-facing technology. Their products can simplify purchasing insurance, submitting claims and managing coverage.
An insurer can rapidly increase written premiums while struggling to control claims payouts. Veterinary inflation makes that problem especially relevant, since the cost of treating an insured pet can rise faster than expected. Customer retention, claims ratios and underwriting results are therefore better measures of success than premium growth alone.

In our document detailing everything you need to know about pet tech, you will always find fresh funding data, taken straight from our own verified funding database.
Is Lassie the most promising European pet insurance startup?
Lassie is currently one of Europe's most interesting independent pet insurance startups, having raised $75 million in a Series C financing announced in February 2026. Its main distinguishing feature is an attempt to prevent health problems rather than simply reimburse veterinary bills afterward.
The Swedish-founded company has attracted investors including Balderton Capital, Felix Capital, Inventure, Passion Capital and Stena Sessan.
Lassie has also reached meaningful commercial scale. According to Balderton's February 2026 announcement, the company already insured more than 250,000 pets across Sweden, Germany and France, generating over $100 million in annual recurring revenue.
Its application combines insurance with educational resources, preventive-care advice and rewards linked to certain health-related activities. The idea is that healthier pets may need fewer avoidable treatments, potentially benefiting customers and the insurer.
There's also evidence that its technology is improving operational efficiency. Balderton reported that Lassie processed 60% of claims in Germany end-to-end through automation in approximately six minutes. The company also reported 25% daily active usage, compared with an industry benchmark of 8% to 9%.
Those figures make Lassie more than a promising insurance concept. It already has a substantial customer base, recurring revenue and measurable customer engagement. What remains less clear is whether its preventive-care approach actually reduces claims costs and produces attractive underwriting profits over time.
ManyPets offers a useful comparison. It accumulated substantially more funding during its expansion, showing how capital-intensive digital insurance can become. Greater investment, however, doesn't automatically establish better operating results.
Is Loyal the most exciting Pet Tech startup right now?
Loyal may be the most ambitious Pet Tech startup today because it is developing medicines intended to extend the healthy lifespan of dogs. If successful, the company could create an entirely new category of veterinary treatment.
In February 2026, Loyal announced a $100 million Series C led by age1, with participation from Baillie Gifford and existing investors. Its cumulative financing exceeded $250 million.
The company's lead candidate, LOY-002, is a daily prescription pill intended for older dogs. Loyal is working toward FDA expanded conditional approval and has reported completing two of the three major technical sections required for its application: reasonable expectation of effectiveness and target animal safety. Waiting on regulatory approval is a risk that can slow a whole category, and we rate such risks by likelihood in our report on pet tech.
The remaining manufacturing requirements are important because a promising treatment still needs to be produced consistently and at commercial quality.
Loyal has also made progress beyond its lead candidate. In September 2026, the company announced that LOY-003, a daily pill under development for large and giant-breed dogs, had achieved the FDA's Reasonable Expectation of Effectiveness milestone. That was Loyal's third such acceptance across its drug programs, following LOY-001 and LOY-002. It was another regulatory step forward, though not an approval to sell the treatment.
Loyal has enrolled approximately 1,300 dogs across 70 veterinary clinics in its STAY study. That's meaningful clinical development work, although enrollment alone doesn't establish that the drug extends canine lifespan.
The commercial opportunity could be enormous if the treatment works. Pet owners already spend heavily on veterinary care, nutrition and medications to support aging animals. An approved drug that meaningfully extends healthy life could become a compelling new product.
Loyal still faces regulatory, clinical and commercial uncertainty. Its potential is exceptional, but it has substantially more to prove than established companies such as Whisker or Fi.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the pet tech market, we look at what broke startups before you, so you don't repeat it.
Did Chewy's acquisition of Modern Animal prove that veterinary startups are valuable?
Chewy's acquisition of Modern Animal for approximately $400 million established a clear benchmark for technology-enabled veterinary clinics. It showed that a network combining physical locations, digital services and customer memberships can attract a major strategic buyer.
When Chewy announced the transaction in April 2026, Modern Animal operated 29 clinics and served more than 100,000 member families. Its business represented over $125 million in annualized revenue.
Using those figures, the acquisition value was approximately 3.2 times annualized revenue. That gives us a useful valuation reference, although it should not be treated as a universal multiple for veterinary startups.
Chewy also disclosed unusually strong economics at Modern Animal's mature locations. According to its acquisition announcement, mature clinics generated more than twice the industry's average revenue per location and EBITDA margins exceeding 20%.
Those margins refer specifically to mature clinics, rather than the entire business. New locations can take years to reach that level of productivity.
The acquisition expanded Chewy's veterinary network from 18 to 47 locations. Chewy gained functioning clinics, established medical teams and an existing customer base in a single transaction.
Modern Animal's financial performance helps explain the interest. More than $125 million in annualized revenue across 29 clinics works out to over $4.3 million per location on a simple network-wide basis.
Could Petfolk become the next Modern Animal?
Petfolk is one of the more credible candidates to build another large technology-enabled veterinary network, but its financial scale remains less transparent than Modern Animal's at the time of its acquisition.
Petfolk combines physical veterinary centers with digital appointment booking, medical records and around-the-clock virtual support. The company has continued expanding geographically, including announcing its entry into Utah through a planned location in Riverton.
One particularly interesting feature is its veterinarian partnership model. Participating veterinarians can obtain equity ownership in their care centers, giving them a potential financial interest in the business they help operate.
That could be important in veterinary medicine, where expansion depends heavily on finding and retaining qualified professionals. Opening a new clinic requires more than renting premises and installing software; it needs veterinarians, technicians and enough patients to support the operating costs.
Modern Animal provides a useful benchmark. As seen above, its 29 clinics represented more than $125 million in annualized revenue when Chewy announced the acquisition. Petfolk would need to demonstrate comparable clinic productivity, attractive margins and consistent demand to justify a similar valuation.

Your time is limited. In our research about pet technology, we put numbers on each part of the market, so you can see where it makes sense to focus.
Are veterinary software startups a better business than veterinary clinics?
Veterinary software could be an even more attractive long-term business than owning clinics because companies such as Petvisor and Provet can serve existing practices without having to build and staff every location themselves.
Petvisor develops technology for veterinary practices, including customer communications, scheduling and operational workflows. Its growth financing exceeded $100 million in a transaction announced in November 2023. Scheduling and client messaging are the kind of clinic chores vets would pay to get rid of, a customer problem we describe in our pet tech market report.
Provet provides veterinary practice-management software covering appointments, patient records, billing and clinical workflows. Reported annual recurring revenue of approximately €26.8 million at the end of 2025 gives us a concrete measure of the category's commercial scale.
These products can become deeply embedded in daily clinic operations. Moving patient records, payment histories and appointment systems to another provider involves work, training and potential disruption.
The contrast with physical clinics is substantial. Modern Animal needed 29 facilities and medical teams to reach more than $125 million in annualized revenue. A software provider can grow by adding practices to its platform without financing the same amount of property, medical equipment and clinical staff.
Large veterinary groups may build their own software, while rivals can offer similar scheduling, billing and communications features. Petvisor and Provet's ability to retain customers will depend on how useful their systems become to the daily operation of veterinary practices.
Is the Pet Tech market growing as fast as startups claim?
The overall pet market is still growing, but much more slowly than several leading Pet Tech startups. U.S. pet industry spending increased by 3.7% in 2025, according to the American Pet Products Association, reaching $158 billion.
APPA projects spending of $165 billion in 2026, an increase of roughly 4.4%. Around two percentage points of that projected growth are attributed to inflation.
The longer-term picture is stronger. U.S. pet spending increased from approximately $90.5 billion in 2018 to $158 billion in 2025, representing roughly 75% cumulative nominal growth, or about 8.3% annually over seven years.
That longer-term pace is almost twice the industry's most recent annual growth rate. Pet spending has continued rising, but the extraordinary expansion associated with the pandemic period has cooled.
The customer base is nevertheless enormous. APPA reported approximately 95 million pet-owning U.S. households in 2025, including 71 million dog-owning households and 53 million cat-owning households.
Spending pressure is becoming more visible too. APPA found that 22% of pet owners reduced their pet spending in 2025.
These figures help explain why the best startups look so different from the broader industry. A company growing 30% annually while total spending increases by about 4% must be gaining customers from competitors, convincing owners to buy new kinds of products or moving existing spending into a technology-enabled service.
Whisker has benefited from the adoption of automated litter systems, while Fi and Tractive have built subscription businesses around connected pet monitoring. Their success comes from changing what owners purchase, rather than relying entirely on more pets being adopted.

In our market report about pet technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
Does raising more money make a Pet Tech startup more successful?
Pet Tech fundraising has proved to be a poor predictor of commercial success. Some heavily financed businesses have struggled badly, while companies such as Fi have reached substantial revenue scale without continuously raising venture capital.
ManyPets attracted hundreds of millions of dollars to expand its digital insurance business. Wag! also received major venture backing during its growth, including investment associated with SoftBank's Vision Fund.
Wag! ultimately entered Chapter 11 bankruptcy proceedings in July 2025, according to company disclosures. Its history demonstrates how quickly a promising pet-services platform can lose financial ground despite previous investor support.
Fi offers a very different trajectory. The company expects to exceed $100 million ARR after previously raising approximately $40 million across three venture rounds, according to PitchBook figures cited in August 2026 reporting.
Whisker also spent years building its product business before reporting more than $300 million in annual revenue.
There are important differences between the companies. Insurance requires capital to support underwriting and growth, while Loyal needs funding for expensive clinical trials and regulatory development. Hardware companies have manufacturing requirements, and marketplaces spend money acquiring customers and service providers.
Fi's commercial achievements are particularly impressive relative to its disclosed fundraising history, while Wag!'s failure shows that previous backing offers little protection when business economics deteriorate.
Can Pet Tech startups really compete with Chewy?
Specialist Pet Tech startups can compete with Chewy in their own categories, but matching Chewy's overall scale is a different challenge. The company generated approximately $12.6 billion in fiscal 2025 revenue and served around 21.3 million active customers.
That puts its size into perspective. Using Whisker's reported $300 million-plus annual revenue as a reference, Chewy's sales are more than 40 times larger than $300 million.
Chewy also benefits from its Autoship program, prescription products, veterinary services and established customer relationships. Those advantages make it difficult for a new company to compete through an ordinary online pet store.
Startups have stronger opportunities when they develop specialized products or services.
Whisker has built expertise in automated litter systems, Fi offers proprietary monitoring technology, and Loyal is developing pharmaceutical treatments that would require substantial scientific and regulatory work to reproduce.
Chewy can also become a buyer rather than simply a competitor. Its Modern Animal acquisition illustrates how an established pet-commerce company can purchase capabilities that would take years to develop internally.

If you build or invest in the pet tech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Which Pet Tech business models have the best results and growth prospects?
Connected hardware, GPS subscriptions and pet-care marketplaces have produced some of the strongest Pet Tech results so far, while veterinary software and healthcare have attractive expansion opportunities. Fi looks particularly well positioned among independent startups, and Loyal has the greatest scientific upside.
Rover's $2.3 billion exit demonstrates the value of a large service marketplace. Whisker's revenue confirms that automated household devices can become major consumer businesses. Fi and Tractive show that pet tracking can produce recurring software and connectivity revenue at substantial scale. Marketplaces, connected devices and trackers earn money in different ways, and we compare which ones keep their margins in our report on pet tech.
Fi's expansion across 38 countries and its Starlink-connected Ultra collar could support further subscriber growth. Whisker has a larger disclosed revenue base and an established brand, but expensive appliances depend on consumers making relatively large purchases.
Veterinary healthcare provides another important set of examples. Modern Animal achieved a $400 million acquisition valuation, while Provet has developed a meaningful recurring-revenue software business. Petfolk could become valuable if it builds a network with similarly productive clinics, although its financial performance remains less transparent.
Lassie's opportunity is tied to low pet insurance penetration and an already substantial revenue base, but expansion must be matched by sound underwriting results. Loyal has the widest range of potential outcomes: a successful longevity treatment could create an important new market, though regulatory approval and clinical benefits remain unproven.
| Business model | Leading examples | Evidence of success | Main challenge |
|---|---|---|---|
| Smart pet appliances | Whisker, PETKIT | Hundreds of millions in reported annual sales | Manufacturing costs and replacement cycles |
| GPS tracking subscriptions | Fi, Tractive | Around $100M ARR scale | Retention and connectivity costs |
| Virtual GPS fencing | Halo Collar | Nearly $100M annual sales | Product pricing and hardware competition |
| Pet-care marketplaces | Rover | $2.3B completed acquisition | Customer acquisition and local service supply |
| Veterinary clinic networks | Modern Animal, Petfolk | $400M acquisition for Modern Animal | Staffing and clinic utilization |
| Veterinary software | Petvisor, Provet | Meaningful investment and recurring revenue | Competition and integrations |
| Digital pet insurance | Lassie, ManyPets | More than $100M ARR at Lassie and a growing insured population | Claims costs and underwriting margins |
| Animal longevity drugs | Loyal | More than $250M raised and advanced clinical work | Regulatory approval and treatment efficacy |
So, what are the top Pet Tech startups today?
The top Pet Tech companies today include Whisker, Fi, Halo Collar, PETKIT, Rover, Tractive, Loyal, Lassie and Petfolk. Among independent businesses, Whisker stands out for commercial scale, Fi for recurring revenue, and Loyal for its potential to create an entirely new pharmaceutical market.
Rover also belongs near the top of any historical ranking after its $2.3 billion acquisition. Tractive and Modern Animal provide further evidence that successful pet technology businesses can attract substantial buyers. All three have already been acquired, so they should be distinguished from startups that remain independent.
If we had to select one independent Pet Tech startup with a particularly strong combination of current commercial results and future potential, we would choose Fi. Approaching $100 million in ARR, expanding across 38 countries and operating without frequent new venture rounds make it an unusually compelling business.
Whisker is the stronger choice if current disclosed revenue is our primary measure. Loyal deserves attention from anyone looking for a company that could create a new category, although its development risks remain much higher.
Pet Tech has now produced businesses generating hundreds of millions in sales, substantial subscription platforms and acquisitions worth hundreds of millions or billions of dollars. The next major winners will likely come from companies that can build equally strong customer demand while keeping the economics of growth under control.
Our methodology
This analysis identifies the leading Pet Tech startups by comparing their demonstrated commercial performance, customer adoption, recurring revenue, capital efficiency, competitive positioning, acquisition outcomes and future growth opportunities. We examine hardware manufacturers, pet wearables, marketplaces, insurance platforms, veterinary healthcare providers, software businesses and animal longevity developers using measures appropriate to each business model.
We prioritized company disclosures, financial filings, investor announcements, completed acquisition records, regulatory developments and industry research. Revenue and annual recurring revenue are treated separately, while announced financing rounds and reported valuations are distinguished from completed transactions. We also separate independent startups from companies that have already been acquired.
Commercial achievements receive more weight than fundraising totals. For established companies, we examine revenue scale, subscription quality, customer adoption and the economics of expansion. For earlier-stage businesses such as Loyal, we assess clinical development, regulatory progress and the evidence supporting future commercialization without treating scientific milestones as proof of market success.
We also compare company performance with wider industry conditions. Pet spending figures from the American Pet Products Association provide context for overall market growth, while North American Pet Health Insurance Association data helps distinguish insurance premium expansion from growth in the number of insured animals. For veterinary healthcare, Modern Animal's reported clinic productivity and acquisition value provide a benchmark for evaluating other clinic operators.
Our selection reflects both demonstrated achievements and credible future potential. Whisker leads on disclosed specialist hardware sales, Fi stands out for recurring revenue relative to its fundraising, and Loyal offers a potentially important new treatment category with substantially greater regulatory and clinical uncertainty. Acquired businesses such as Rover, Tractive and Modern Animal are included as evidence of realized strategic value rather than presented as independent investment opportunities.
Key sources used for this analysis include: Whisker's company history and commercial development, Blackstone's confirmation of the Rover acquisition, Fortune on Fi's recurring revenue and satellite-connected collar, Tractive's acquisition announcement, Bending Spoons' financial results and Tractive transaction value, Business Insider on Halo Collar's sales, Loyal's Series C announcement, Loyal's LOY-003 regulatory milestone, and Balderton Capital on Lassie's financing, recurring revenue and insurance operations.
Additional sources include: Chewy's Modern Animal acquisition announcement, Chewy's SEC filing on the completed transaction, Petfolk's clinic expansion announcement, Apax Partners on Petvisor's strategic investment, North American Pet Health Insurance Association industry statistics, American Pet Products Association spending and ownership research, Chewy's fiscal 2025 financial results, and Wag!'s SEC restructuring disclosure.

Theory only gets you so far. In our report covering the pet tech market, we dig up the real signals from the field and show you the ones worth watching.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us