How big is the Pet Tech market really?
Whether you're building or investing in the Pet Tech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
The core global Pet Tech market is roughly $9 billion today, while a broader definition that pulls in more monitoring equipment, digital functions and adjacent applications can reasonably push the total toward $15 billion to $18 billion.
The huge spread in published estimates is mostly a definition problem, not evidence that nobody has any idea how large the market is. The cleanest numbers cluster once Pet Tech is limited to connected and automated products made specifically for pets.
Company scale supports the narrower view. Whisker has passed $300 million in annual revenue, Tractive has more than 1.4 million active users, and several specialist brands now operate across feeding, tracking, cameras, litter and hydration without any one company approaching multi-billion-dollar dominance.
Wearables are the most established large category, but automated litter may be the best proof that premium Pet Tech can build a substantial standalone business. One million-plus Litter-Robots sold is a much harder commercial fact than another loosely defined market forecast.
Smart feeders show why category data can be deceptive. A Wi-Fi or RFID feeder belongs comfortably in Pet Tech, while a basic timer feeder does not, yet many market studies mix them together and produce estimates ranging from a few hundred million dollars to several billion. Wi-Fi feeders and basic timers being lumped together is why we spell out what counts and what doesn't in our report on pet tech.
Pet Tech is still small beside the overall pet economy. Using U.S. Pet Tech and APPA spending figures, connected pet products represent only about 2% of total U.S. pet-industry expenditure, which leaves room for growth without assuming the category takes over ordinary pet care.
Subscriptions are quietly changing the economics. GPS collars, cameras and health-oriented devices can keep generating revenue after the hardware sale, which makes the lifetime value of a connected customer much larger than the shelf price suggests.
The category is also shifting from convenience toward persistent health-related data. Activity, eating, drinking, weight and litter-box behavior can now be measured continuously, making the device more useful after the initial novelty wears off.
Cats are becoming more important because indoor routines are easy to automate and monitor. Dogs still generate more Pet Tech revenue, but feeding, hydration and litter systems give cat owners several high-frequency use cases that fit connected hardware unusually well.
A 12% to 15% annual growth range looks more credible than the most aggressive forecasts. At that pace, a roughly $9 billion core market can still exceed $20 billion within the next decade without requiring every adjacent digital pet service to be counted as Pet Tech.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us

Your time is limited. In our report covering the pet tech market, we put numbers on each part of the market, so you can see where it makes sense to focus.
What actually counts as Pet Tech?
Pet Tech today is best understood as the connected hardware and software people use specifically to feed, locate, monitor, entertain or care for their pets.
That covers GPS collars, health wearables, automated feeders, self-cleaning litter boxes, connected cameras, smart doors, water systems and the apps or subscriptions attached to them.
The definition gets messy once we move beyond those products. Some market researchers also count digital pet-care platforms, telehealth services, veterinary software or fairly conventional electronic equipment. Others stick much more closely to connected consumer devices.
Those choices explain a surprisingly large part of the disagreement over market size.
For this article, we use the narrower definition when we talk about the core Pet Tech market: products built specifically around connected or automated pet care, together with the software and subscriptions that directly support them. Ordinary food, veterinary services, grooming and insurance stay outside the total unless technology itself is the product being sold.
The boundary is not perfect, but it gives us something we can actually measure without turning nearly the entire modern pet industry into “Pet Tech.”
Why are Pet Tech market estimates all over the place?
Pet Tech market estimates are all over the place because researchers are often measuring different things under almost identical names.
Grand View Research currently values the global Pet Tech products market at $9.2 billion for 2025. Fortune Business Insights, whose report was updated again in 2026, puts its broader Pet Tech market at $17.65 billion for the same year. Other published estimates sit between those two numbers, while a few narrower “smart pet products” studies come in much lower.
An almost twofold difference between two major research firms is too large to treat as normal forecasting noise. An almost twofold gap between two research firms is why we build our own size estimate, assumptions visible, in our market report about pet tech.
Look inside individual categories and the problem becomes even clearer. Recent pet-wearable estimates for 2025 have ranged from about $2.8 billion to more than $4 billion. Published smart-feeder numbers stretch much further, from a few hundred million dollars to well above $2 billion depending on whether researchers count only genuinely connected feeders or include the much broader automatic-feeder category.
So the useful question is not which market-research firm has discovered the one correct number. We need to work out which definition best matches what people actually mean by Pet Tech.
| Published estimate | 2025 market size | What is being measured |
|---|---|---|
| Narrow smart-product estimates | roughly $2B+ | Selected connected pet products |
| Stratistics MRC | roughly $7B | Smart Pet Tech |
| Arizton | roughly $8B range | Pet Tech |
| Grand View Research | $9.2B | Pet Tech products |
| Other smart-product studies | roughly $10B | Smart pet products |
| Global Market Insights | roughly $15.6B | Wider Pet Tech market |
| Fortune Business Insights | $17.65B | Monitoring, tracking, entertainment and related Pet Tech |

In our research about pet technology, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
So how big is the Pet Tech market right now?
The core global Pet Tech market is probably worth around $9 billion today, with a sensible range of roughly $8 billion to $10 billion.
That is the number we would use if someone simply asked, “How big is Pet Tech?”
Grand View Research's latest work puts dedicated Pet Tech products at $9.2 billion in 2025 and estimates about $10.3 billion for 2026. Its definition also looks reasonably close to what an ordinary consumer would expect: wearables, trackers, feeders, automated litter boxes and related connected products.
The much higher estimates are still useful. Fortune Business Insights, for example, currently values its wider Pet Tech universe at $17.65 billion in 2025 and almost $20 billion in 2026. But that study draws the boundary more broadly across monitoring, tracking, entertainment equipment, sensors and commercial applications.
Calling Pet Tech a $17 billion or $18 billion market therefore requires a wider meaning of Pet Tech than the one we use for the core consumer-device category.
At the other extreme, estimates around $2 billion are increasingly hard to reconcile with the commercial scale of wearables, connected litter products and automated feeding on their own.
Roughly $9 billion is the cleanest working number without pretending the category has perfectly defined borders.
Is Pet Tech actually big compared with the whole pet industry?
Pet Tech is already a serious business, but it still represents only a small slice of what people spend on pets.
The latest APPA industry figures put U.S. pet spending at $158 billion in 2025, up 3.7% from the previous year. Grand View Research estimates the U.S. Pet Tech products market at $3.17 billion for that same year.
That works out to roughly 2% of total U.S. pet-industry spending.
The comparison keeps the scale in perspective. Food and treats alone account for tens of billions of dollars in annual U.S. sales. Veterinary care is another huge category. Pet Tech remains much smaller than either.
Yet 2% of an industry this large already supports several billion dollars of annual U.S. sales. It also leaves plenty of room for connected products to gain share without needing to replace traditional pet care.
APPA now counts 95 million U.S. households with at least one pet. Moving even a modest additional share of those households toward trackers, automated feeders, smart litter boxes or other connected products would add billions of dollars to the category.
Pet Tech has reached meaningful scale while still being far from universal.

Theory only gets you so far. In our market report about pet technology, we dig up the real signals from the field and show you the ones worth watching.
Which Pet Tech products are people actually spending money on?
Wearables, automated feeding and connected litter products currently provide the clearest evidence that Pet Tech has moved beyond novelty gadgets.
Wearables have the strongest published market numbers. Grand View Research says trackers and wearables accounted for 25.5% of global Pet Tech-product revenue in 2025, making them its largest segment.
Automated feeding has also become a substantial business, although the published totals are much harder to trust because some studies include basic programmable feeders while others focus on app-connected devices. App-connected feeders and basic timers differ in maturity, so we sort what works from what is being tested in our report on pet tech.
Then there is automated litter. We have better company-level evidence here than market-research estimates. Whisker says it has sold more than one million Litter-Robots and now generates more than $300 million in annual revenue. One company reaching that scale around a product that can cost several hundred dollars tells us more than another speculative category forecast.
Pet cameras, connected fountains, smart doors, containment systems and training products add another layer. Some of those markets are significant, but they overlap heavily with ordinary cameras, pet accessories or home electronics.
So we give more weight to actual product sales and company scale than to adding every published submarket estimate together.
| Pet Tech category | How established is it now? | Typical products |
|---|---|---|
| GPS tracking | Large and established | Connected collars and trackers |
| Activity and health wearables | Large and growing | Smart collars and sensor devices |
| Automated feeding | Established | App-controlled and RFID feeders |
| Smart litter systems | Strong premium category | Self-cleaning connected litter boxes |
| Pet cameras | Established but hard to measure | Cameras, treat dispensers, AI monitoring |
| Smart hydration | Smaller but growing | Connected fountains and water monitors |
| Smart access and containment | Established niche | Smart doors, fences and boundary systems |
How big are pet wearables today?
Pet wearables are already a multibillion-dollar business and probably the clearest large-scale Pet Tech category.
Recent estimates place the 2025 global pet-wearables market somewhere between roughly $2.8 billion and $4.2 billion. That range is wide, but every major estimate still points to a category measured in billions rather than hundreds of millions.
Grand View Research provides another way to check the order of magnitude. It says wearables and trackers generated 25.5% of its $9.2 billion Pet Tech-products market in 2025. That implies about $2.35 billion inside its narrower definition.
Real usage supports the same conclusion.
Tractive says it serves more than 1.4 million active users worldwide and has sold millions of devices. Its acquisition of Whistle from Mars Petcare also brought another established U.S. connected-wearable business under the same company.
Wearables have an advantage over many other Pet Tech products because they solve several problems at once. Owners can locate a lost pet, track activity, monitor sleep and increasingly receive health-related insights through the same device.
That combination also makes subscriptions easier to sell, especially when cellular GPS connectivity is involved.

In our document detailing everything you need to know about pet tech, we don't want to repeat what boring consulting reports say. Instead, we show you the real and latest market signals that matter.
Are smart pet feeders really a billion-dollar market?
Smart pet feeders probably generate more than $1 billion globally if we use a broad definition, but the exact number is too messy to quote with confidence.
Recent studies have produced estimates ranging from roughly $250 million to almost $2.5 billion for what appears, at first glance, to be the same market.
The gap mostly comes down to what counts as “smart.” A Wi-Fi feeder controlled from an app clearly belongs in Pet Tech. An automatic feeder running a simple timer sits closer to conventional pet equipment. Several market studies blend the two.
The commercial trend is much easier to see than the market total.
Current products go well beyond dropping kibble into a bowl at a set time. RFID feeders can recognize individual animals. Some models weigh portions, track consumption or restrict one pet from eating another pet's food. Refrigerated feeders have also made automated wet-food feeding more practical.
Petlibro's Polar feeder, for example, uses refrigeration and app-controlled meal scheduling for wet food, a problem older automatic feeders handled poorly.
Automated feeding is clearly a meaningful Pet Tech business these days. We just would not pretend that $1.2 billion, $1.8 billion or $2.4 billion can be distinguished reliably with the available category data.
How did smart litter boxes become a $300M business for one company?
Smart litter boxes have become one of Pet Tech's strongest premium categories because consumers will pay a lot to automate a repetitive job they genuinely dislike.
Whisker is the clearest proof.
The company says it has sold more than one million Litter-Robots, employs more than 600 people and generates over $300 million in annual revenue. Few private Pet Tech specialists disclose scale this clearly. A private specialist at this scale invites the question of what leaders consistently do differently, studied in our report covering the pet tech market.
A Litter-Robot also sells at a completely different price point from a typical litter tray. That allows a relatively modest installed base to create a large business.
The category has kept moving beyond automatic scooping. Newer models can track weight and usage, while competing systems increasingly try to identify individual cats or record changes in litter-box behavior.
That creates a second reason to own the device. Cleaning convenience gets the hardware into the home; persistent behavioral data can make the product more useful after the novelty has worn off.
Whisker's numbers show that Pet Tech does not need tens of millions of users before a specialist can build a sizeable company.
Do the biggest Pet Tech companies support a $9B market?
Yes. The scale of real Pet Tech companies fits reasonably well with a global market of around $9 billion.
We already have a specialist such as Whisker generating more than $300 million annually around automated pet-care hardware. Tractive has more than 1.4 million active users in connected tracking. Brands including PETKIT, Petlibro, Furbo, Fi, PetSafe, Garmin and others compete across adjacent categories.
At the same time, there is no dedicated Pet Tech company doing anything close to tens of billions of dollars in annual revenue.
A roughly $9 billion global market would naturally support a handful of specialists reaching hundreds of millions of dollars, several sizeable brands below them and a long tail of smaller companies. That is broadly what we see.
A $1 billion or $2 billion estimate starts to look cramped once we account for the companies and categories already operating at scale. A $30 billion or $40 billion core-device market creates the opposite problem: we would expect to see much larger specialists than the industry has produced so far.
The operating companies are a useful reality check on the research reports.
| Company or brand | Main Pet Tech business | Useful scale indicator |
|---|---|---|
| Whisker | Automated litter and feeding | $300M+ annual revenue |
| Tractive | GPS and health wearables | 1.4M+ active users |
| Fi | Connected dog collars | Subscription-based GPS and health tracking |
| PETKIT | Feeding, litter, hydration | Broad connected-device portfolio |
| Petlibro | Feeding, hydration, cameras | Expanding multi-product ecosystem |
| Furbo | Pet cameras | Global specialist camera brand |
| Garmin | Tracking and training | Large electronics company active in the category |

In our report covering the pet tech market, we like to show you the big picture. We know your time is precious, so we make every page quick to read and packed with as much learning as possible per minute.
Are subscriptions changing how big Pet Tech can become?
Subscriptions are making parts of Pet Tech much more attractive because companies can keep earning money after the device leaves the shelf.
GPS collars show the model most clearly. A tracker needs cellular connectivity, mapping, data storage and alerts, so an ongoing plan makes sense to customers in a way that a subscription attached to a simple food bowl probably would not.
Fi currently bundles connected tracking around a recurring subscription model. Tractive also relies heavily on recurring plans across its large active user base.
Other categories are starting to follow more selectively. Cameras can charge for cloud storage or AI features. Health-oriented devices can reserve more advanced analysis for paying members. Even companies without software subscriptions can create recurring revenue through filters, litter, replacement parts and other consumables.
The difference becomes large over several years. A company selling a tracker once for $80 has a limited relationship with the customer. A connected service collecting $10 or $15 every month can eventually earn several times the original hardware value from the same household.
Pet Tech is gradually becoming less dependent on one-off gadget sales, especially in products that produce useful data every day.
Is Pet Tech becoming more about health than convenience?
Pet Tech is moving quickly toward health monitoring because continuous pet data gives owners a stronger reason to keep using connected devices.
The change is happening across categories.
GPS collars increasingly track sleep and activity alongside location. Feeders can record exactly how much a specific pet eats. Smart fountains can measure drinking. Connected litter boxes can record weight, frequency and changes in bathroom routines. Cameras are getting better at recognizing specific behaviors rather than simply streaming video. Measuring a pet's habits matters if owners pay for it, so we study which problems customers pay to solve in our report on pet tech.
These products cannot diagnose an animal just because they collect data, and manufacturers generally have to be careful about medical claims. Still, the underlying information can become useful before a veterinary visit. A sudden drop in activity or a noticeable change in drinking, eating or litter-box use is easier to spot when the device has been measuring the same behavior every day.
AI fits naturally into this shift. The useful part is not putting an “AI” label on another pet gadget; it is turning thousands of ordinary readings into something an owner can understand.
That is currently one of the more convincing paths for Pet Tech to become part of routine care rather than something owners try for a few months and forget.

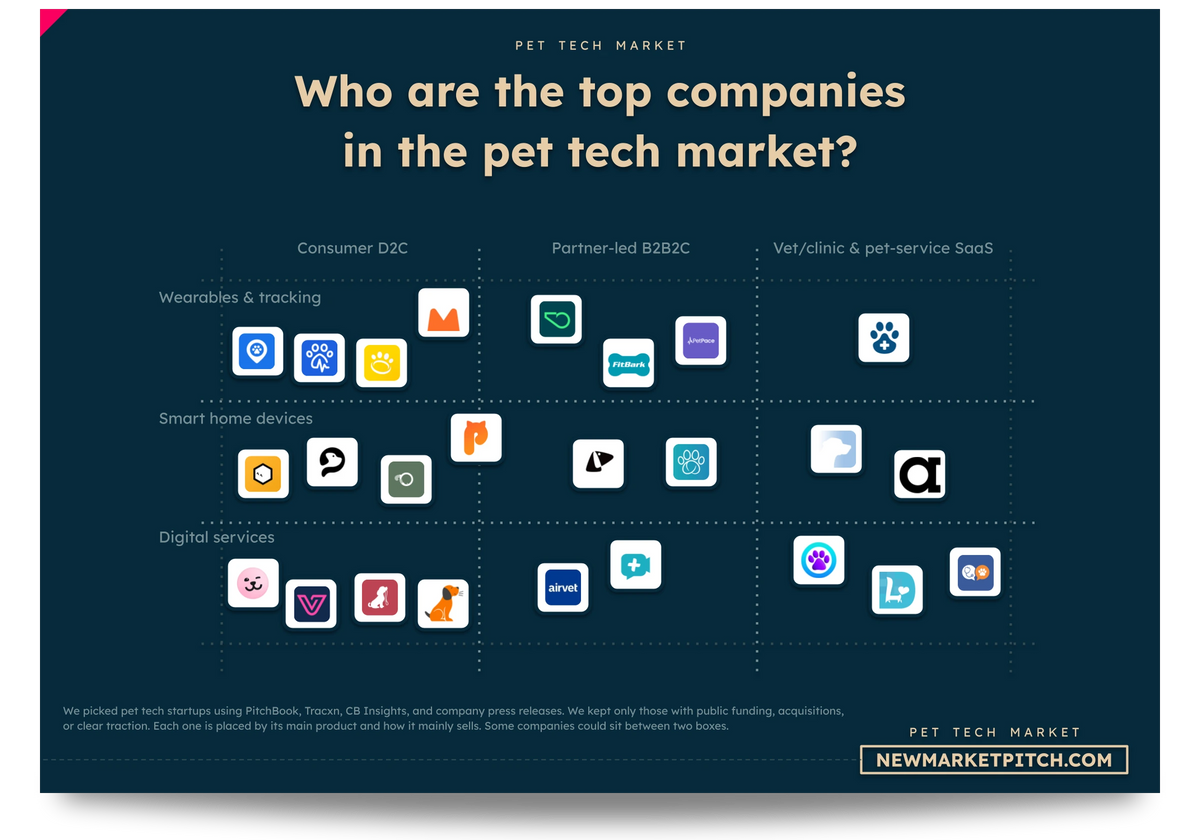
In our research about pet technology, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is the U.S. still the biggest Pet Tech market?
The U.S. remains the biggest individual Pet Tech market, while Asia is becoming increasingly important on both the product and manufacturing sides.
Grand View Research puts North America at 42.2% of global Pet Tech-product revenue in 2025 and estimates the U.S. alone at $3.17 billion.
The underlying customer base is enormous. APPA's latest figures count 95 million U.S. households with a pet. Dog ownership reached 71 million households in 2025, while its latest cat research puts feline ownership at 53 million households.
The U.S. also supports the premium pricing that drives many Pet Tech economics. Spending $100 on a tracker is one thing. Spending several hundred dollars on a feeder or $700-plus on an automated litter system requires a much smaller but wealthier target market.
Europe has produced important companies too, particularly in wearables. Tractive was founded in Austria and built a global subscriber base from there.
China plays another role entirely. Brands such as PETKIT have developed broad connected-product ranges, while the country's electronics manufacturing ecosystem makes it central to the supply side of global Pet Tech.
North America still leads on revenue, but the competitive map is already much more international than the sales split alone suggests.
Are cats becoming more important to Pet Tech?
Cats are becoming a much bigger Pet Tech opportunity because their daily routines are unusually easy to monitor and automate inside the home.
Dogs still lead overall. Grand View Research says dogs represented 60.3% of U.S. Pet Tech-product revenue in 2025, helped by GPS trackers, outdoor safety devices and connected training products.
Cats create a different set of opportunities.
An indoor cat may have little need for permanent GPS tracking, but feeding, drinking and litter-box use happen several times a day in predictable places. That makes them ideal behaviors for connected hardware.
The addressable audience is also moving in the right direction. APPA's latest cat research says 53 million U.S. households now own a cat, up from the level reported a year earlier.
We can already see the commercial effect in automated litter, RFID feeding and connected hydration. These products fit naturally into multi-cat households too, where identifying which animal ate, drank or used the litter box can be genuinely useful.
Dogs currently account for more Pet Tech revenue. Cats look increasingly capable of closing some of that gap through home automation and health monitoring.
Is Pet Tech really growing at more than 10% a year?
Pet Tech is probably growing around 12% to 15% a year right now, which is fast enough without relying on the most aggressive forecasts.
Grand View Research currently expects its Pet Tech-products market to grow 12.5% annually through 2033. Fortune Business Insights forecasts 13.16% for its broader market. Other recent studies cluster around 12% to 15%, although a few go close to 20%. Growth forecasts of 12-15% raise the question of what has to happen for the market to accelerate, covered in our pet tech market report.
The cluster matters more than the outlier.
At 12.5% annual growth, a market roughly doubles in six years. Grand View Research accordingly moves from $9.2 billion in 2025 to $23.5 billion in 2033.
That still assumes years of strong expansion, so we would not treat the forecast as guaranteed. Consumer hardware markets can slow once the easiest households have adopted a product, while premium prices and recurring subscriptions can also limit penetration.
For now, though, double-digit growth looks plausible. Pet ownership remains high, several product categories are still adding functionality, and adoption is low enough that Pet Tech does not need every household to buy something new each year.
The more aggressive 18% to 20% forecasts may prove right for individual niches. They are much harder to defend for the whole market over a long period.
| Forecast source | Expected annual growth |
|---|---|
| Global Market Insights | around 12% |
| Grand View Research | 12.5% |
| Fortune Business Insights | 13.16% |
| Arizton | around 14.6% |
| Higher-growth connected-care studies | roughly 16% |
| Most aggressive Smart Pet Tech estimates | close to 20% |
| Our useful working range | roughly 12–15% |

Our market report about pet technology gets updated several times a month, so you always get the latest view of where things stand.
What could make the Pet Tech numbers look bigger than they really are?
Double counting is probably the biggest reason Pet Tech market estimates can become inflated.
Take one connected collar. A researcher might classify it as a wearable, GPS tracker, health-monitoring device, smart collar and IoT pet product. Each label is defensible. Adding separate market reports for all five categories would count some of the same revenue several times.
Pet cameras create the same problem. A dedicated Furbo belongs comfortably inside Pet Tech, but ordinary indoor security cameras are also widely used to watch pets. Some broad market definitions can pull part of that spending into the category even though the product was never designed specifically for animals.
Automatic feeders create another gray area because a basic timed dispenser and an app-connected RFID feeder solve a similar problem with very different levels of technology.
There is also substitution. Spending $500 on a smart device does not always mean the pet industry gained $500 of entirely new demand. Part of that purchase may replace a conventional feeder, camera, litter box or training system that the household would otherwise have bought.
These overlaps are why the individual submarket estimates cannot simply be added together. Doing so can produce a wonderfully large number and a fairly useless answer.
How much bigger could Pet Tech realistically get?
Pet Tech could become a $20 billion-plus core product market if connected pet care becomes normal in a much larger share of households. Current forecasts make that plausible, not inevitable.
The easiest growth probably comes from products people already understand.
A dog owner does not need to imagine a futuristic home to see the value of a reliable GPS tracker. Cat owners already understand why an automated litter box saves work. Portion-controlled feeders solve a familiar problem. Health monitoring can then add another reason to keep those products connected.
The U.S. alone has 95 million pet-owning households. That leaves an enormous difference between today's installed base and anything resembling mass adoption across trackers, feeders, litter systems and connected health products.
We should also remember that each household can buy more than one Pet Tech product. A tracker, feeder, camera and fountain do different jobs. Multi-pet households can require additional devices or higher-priced systems capable of recognizing individual animals.
Grand View Research currently expects its narrowly defined market to grow from $9.2 billion in 2025 to $23.5 billion by 2033. Fortune Business Insights reaches much higher totals with its broader definition.
We are more comfortable with the first trajectory. It requires Pet Tech to keep gaining household penetration at a strong pace, but it does not require the category to absorb every adjacent digital pet service along the way.

In our document detailing everything you need to know about pet tech, you will always find fresh funding data, taken straight from our own verified funding database.
How big is the Pet Tech market really?
Pet Tech is roughly a $9 billion global market today under the definition that best matches dedicated connected pet products.
That is our clearest answer after comparing the current research with what operating companies are actually selling.
The wider Pet Tech ecosystem can reasonably be valued closer to $15 billion to $18 billion once broader monitoring equipment, digital functions and adjacent applications enter the definition. Fortune Business Insights currently lands at $17.65 billion for 2025, while Grand View Research's tighter product universe comes in at $9.2 billion.
The narrower figure also fits the commercial evidence better. Wearables already generate billions of dollars. A single connected-litter specialist has passed $300 million in annual revenue. GPS trackers support million-plus active-user bases. Feeders, cameras, hydration products and smart home systems fill out the rest of a fragmented but substantial market.
At the same time, U.S. Pet Tech sales equal only around 2% of total U.S. pet-industry expenditure using Grand View Research and APPA figures. Connected pet care therefore has plenty of room to grow before it becomes anything close to mainstream pet spending.
For now, calling Pet Tech a roughly $9 billion core market and a roughly $15 billion-to-$18 billion wider ecosystem gives a much clearer picture than pretending one research report has found the definitive number.
The category is already large. The real uncertainty today is how much of the surrounding digital pet economy deserves to be counted with it.
Our methodology
We treated this as a market-definition and triangulation problem rather than a search for one authoritative Pet Tech number. Published estimates are not directly comparable when one source measures dedicated connected products and another includes a wider mix of monitoring equipment, software, sensors, services or commercial applications.
Our core-market estimate therefore starts with the narrower product definition used throughout the article: connected or automated hardware made specifically for pets, plus the software and subscriptions that directly support it. Ordinary pet food, veterinary services, grooming and insurance stay outside the total unless the technology itself is the product being sold.
We compared top-down market research with bottom-up commercial evidence. Company revenue, active-user bases, installed products, product pricing, subscriptions and household pet ownership were used as reality checks on the scale suggested by the market reports, not mechanically added together to manufacture a separate market total.
We also treated overlapping submarkets carefully. The same connected collar can appear in wearable, GPS, health-monitoring, smart-collar and IoT reports, while similar overlap exists across feeders, cameras, litter systems and hydration products. We therefore did not add published submarket estimates together where the same underlying spending could be counted more than once.
For growth, we gave more weight to the cluster of recent forecasts around 12% to 15% than to isolated estimates near 20%. The working range reflects the part of the forecast set that remained most coherent with current household adoption, specialist-company scale and the still-low penetration of many connected products.
We prioritized direct company disclosures, industry association data and market-research pages that clearly state what they measure. The strongest reality checks in the article come from APPA spending and ownership data, Whisker's disclosed company scale, Tractive's active-user base and acquisition history, and first-party product information from Fi, Furbo, PETLIBRO, PETKIT and Garmin.
Key market-sizing sources include Grand View Research on the global Pet Tech Products market, Fortune Business Insights on the broader Pet Tech market, Global Market Insights on Pet Tech, Grand View Research on the U.S. Pet Tech Products market, and Grand View Research on smart pet feeders.
Key industry and company sources include APPA's 2026 State of the Industry, APPA's 2025 spending release, APPA's 2026 Dog Report preview, APPA's cat-ownership findings, Whisker on Litter-Robot sales and company scale, Tractive on the Whistle acquisition and active users, and Tractive on its subscription model.
Additional first-party product checks include Fi's GPS and health-tracking platform, Furbo's camera and subscription documentation, PETLIBRO's Polar wet-food feeder, PETKIT's connected health ecosystem, and Garmin's dog tracking and training range.

In our report covering the pet tech market, we look at what the winners do differently, so you can learn from the best instead of guessing.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us