Which FinTech startup is growing the fastest?
Whether you're building or investing in the fintech market, our report covers everything you need to know: the players, the money, and what's coming next.
Summary
FinTech's biggest unsolved problems include measuring growth consistently, turning financial activity into durable revenue, and sustaining expansion without sacrificing profitability. Ramp is currently the strongest example of a major private FinTech combining rapid revenue growth with commercial scale, although Payabli and Revolut lead on different measures.
Ramp has surpassed $2 billion in annualized revenue, compared with approximately $1.225 billion at the end of 2025. The impressive part is its ability to maintain that momentum after crossing the billion-dollar threshold, with 85,000 business customers and reported positive cash flow.
Payabli's percentage growth is much higher. Its revenue increased 5,774% between 2022 and 2025, according to the 2026 Inc. 5000, equivalent to approximately 289% compound annual growth. But extraordinary growth from a smaller base is a different achievement from adding hundreds of millions of dollars at Ramp's scale.
Revolut wins on absolute revenue expansion among the companies examined. It added approximately $2 billion in recognized annual revenue during 2025, reaching $6 billion, while generating $2.3 billion in pretax profit. It is operating at a scale most private FinTech challengers have yet to approach.
FinTech growth figures often describe different businesses altogether. Stripe's $1.9 trillion in annual payment volume, Ramp's annualized revenue, and Revolut's recognized annual revenue cannot be ranked as interchangeable measures of commercial success.
Airwallex is Ramp's most immediate international challenger. With $1.3 billion in annualized revenue and 74% year-over-year growth, it has crossed the scale threshold that separates emerging FinTech companies from established challengers. More than 90% of its revenue comes from customers using multiple products.
The expansion of financial activity inside existing customer relationships is becoming a major growth engine. Airwallex's transaction volume grew faster than its revenue, while Revolut's transaction volume increased much faster than its customer count. Winning customers is only part of the story; getting them to use more services is increasingly important.
Kapital demonstrates why acquisition-led growth needs separate treatment. Its estimated 133% revenue growth during 2025 was exceptional, but the acquisition of Intercam's banking operations expanded its financial footprint. That makes the headline increase different from purely organic customer and revenue growth.
Ramp's enterprise expansion may be more important than its customer count. In June 2026, more than 3,200 enterprise customers each generated at least $100,000 in annualized revenue, accounting for a minimum of $320 million. Larger customers are already a meaningful part of its revenue base.
Valuation expectations are rising almost as quickly as Ramp's revenue. Its private valuation increased from $44 billion in June 2026 to $60 billion in October, while its annualized revenue pace rose at least 33%. At roughly 30 times annualized revenue, investors are betting that growth and cash generation will remain exceptional.
Our conclusion is that Ramp has the strongest overall growth case among the major private FinTech challengers examined. Payabli has the more spectacular historical percentage growth, Revolut leads in absolute revenue added, and Airwallex remains a serious contender. The company that ultimately takes the lead will be the one that maintains faster comparable revenue growth at scale, ideally without depending on acquisitions or continuous external financing.

Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us
Which FinTech startup is growing the fastest right now?
Ramp is currently the strongest candidate for the fastest-growing major FinTech startup, while Payabli leads some of the most impressive percentage-growth comparisons and Revolut is adding considerably more revenue in absolute dollars.
The American corporate finance platform Ramp recently surpassed $2 billion in annualized revenue, up from approximately $1.225 billion at the end of 2025. Its annualized purchase volume grew 175% year over year, and its customer base reached 85,000 businesses.
What makes Ramp particularly interesting is how much growth it is maintaining after crossing the billion-dollar revenue threshold. According to Sacra's revenue estimates, Ramp was generating roughly $700 million annually at the beginning of 2025. Its latest reported revenue pace is almost three times that level.
Payabli, a much smaller embedded payments company, has grown even faster in percentage terms. It ranked 43rd on the 2026 Inc. 5000 after recording 5,774% revenue growth over three years.
Revolut offers another perspective. The British FinTech generated $6 billion in actual revenue during 2025, adding approximately $2 billion compared with the previous year.
These figures give us three different leaders. Ramp has the strongest recent combination of revenue growth and commercial scale among the private FinTech challengers we examined. Payabli stands out for percentage growth, while Revolut leads this group in absolute annual revenue added.
If you want more recent data on this point, please see our latest FinTech market report.
Why is it so hard to compare FinTech startup growth?
FinTech growth rankings can be misleading because revenue, payment volume, customer numbers, and annualized revenue measure very different things.
Consider three companies that look similar when we focus on transaction activity.
Stripe processed approximately $1.9 trillion in payments during 2025. Airwallex reported $287 billion in annualized transaction volume in March 2026, while Ramp disclosed more than $275 billion in annualized purchase volume later that year.
Those numbers tell us how much money flows through their platforms. They don't tell us how much the companies actually earn, and their definitions of payment volume differ.
Revenue comparisons also require care. Revolut's $6 billion represents revenue recognized during a completed financial year. Ramp's figure is annualized, meaning it takes a recent revenue pace and expresses it as a yearly amount.
This distinction is especially important when companies are growing quickly. A startup can reach a $1 billion annualized pace during December without having earned $1 billion during that calendar year.
Percentage growth creates another distortion. A company growing from $2 million to $20 million has increased revenue 900%, whereas a company moving from $2 billion to $3 billion has grown 50%. The second business added 100 times more revenue.
For our comparison, we prioritize revenue growth at meaningful scale, while examining percentage growth and absolute revenue additions separately. We also distinguish company disclosures from independently verified financial statements and third-party estimates.

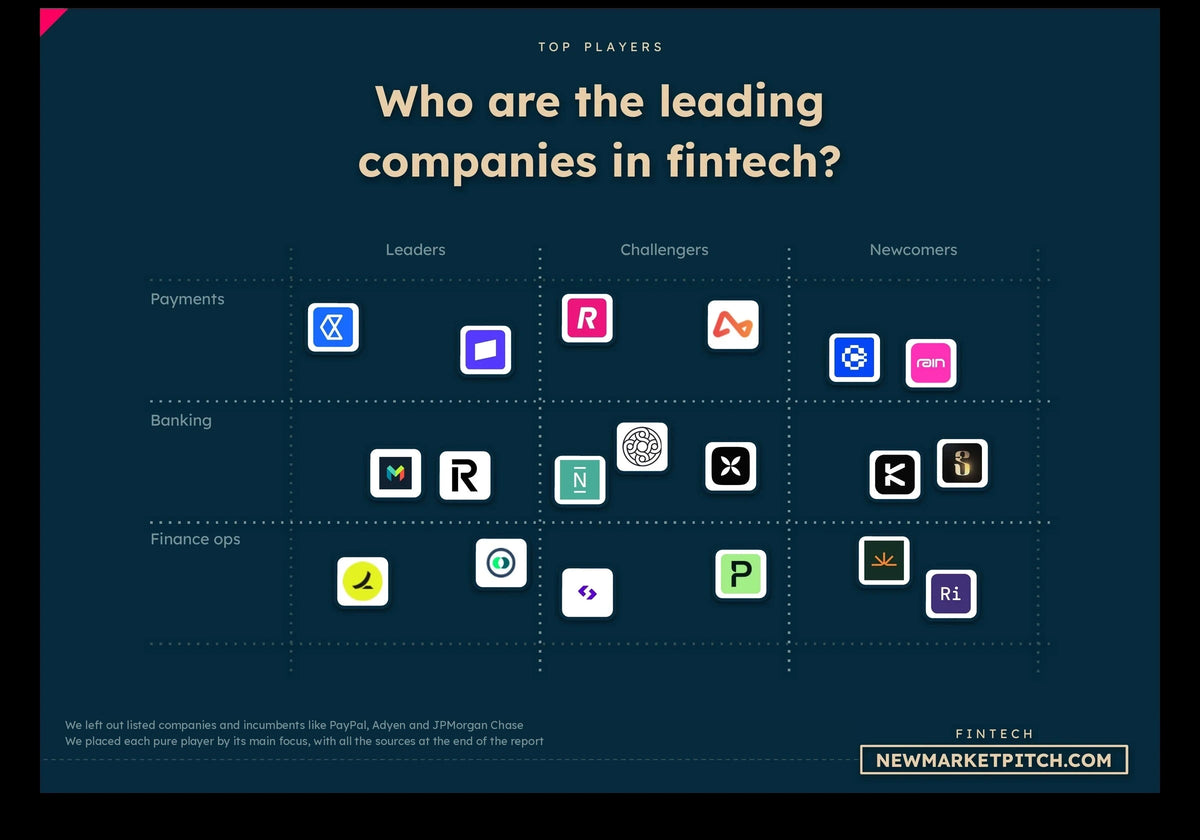
In our report covering the fintech market, we turn what is vague and complex into simple, useful visuals. Market maps like this one show you at a glance where every startup stands.
Is Ramp really growing faster than other billion-dollar FinTech startups?
Ramp is currently growing faster than several prominent billion-dollar FinTech companies on its latest disclosed revenue trajectory, although the reporting periods are not directly comparable.
In its October 2026 financing announcement, Ramp reported more than $2 billion in annualized revenue. TechCrunch noted that the company had been at approximately $1.5 billion in June.
Moving from $1.5 billion to more than $2 billion in roughly four months represents at least 33% growth in its annualized revenue pace.
Airwallex, meanwhile, reported 74% year-over-year annualized revenue growth in March 2026, reaching $1.3 billion. Mercury reached an estimated $1 billion annualized revenue pace in September, according to Sacra.
Revolut's growth rate was lower at 46% during 2025, although it generated several times more actual annual revenue.
The comparison gets more interesting when we look at the maturity of these businesses. Revolut was founded in 2015, Airwallex in 2015, Mercury in 2017, and Ramp in 2019. Ramp is younger than these competitors but has already built a multibillion-dollar annualized revenue business.
| FinTech company | Latest revenue indicator | Reported growth | Measurement |
|---|---|---|---|
| Ramp | Over $2B annualized | Over 63% above end-2025 pace | 2026 |
| Airwallex | $1.3B annualized | 74% YoY | March 2026 |
| Kapital | $310M actual annual revenue | 133% YoY | FY2025, Sacra estimate |
| Revolut | $6B actual annual revenue | 46% YoY | FY2025 |
| Mercury | $1B annualized | 44% FY2025 growth estimate | September 2026 pace |
| Monzo | Approximately £1.7B actual annual revenue | 39% YoY | FY2026 |
| Stripe | $1.9T actual annual payment volume | 34% YoY volume growth | FY2025 |
Is Payabli actually growing faster than Ramp?
Payabli has grown much faster than Ramp in percentage terms, although it remains a substantially smaller business.
The Miami-based startup provides payment infrastructure that software companies can embed into their products. Its customers can use Payabli to accept payments, send money, and manage payment operations through a single platform.
In June 2025, Payabli announced a $28 million Series B funding round and said its revenue had increased sevenfold year over year.
By August 2026, the company reported greater than fourfold year-over-year revenue growth and appeared at No. 43 on the Inc. 5000.
Its three-year growth figure of 5,774% means revenue had become approximately 58.7 times larger between 2022 and 2025. That works out to roughly 289% compound annual growth.
The payment activity behind those results is substantial. Payabli reported more than $6 billion in annual payment processing volume by early 2026. Its network had grown beyond 60,000 merchants, compared with more than 50,000 in mid-2025.
Payabli is benefiting from a different distribution model from Ramp. Instead of winning every merchant directly, it can grow through software platforms that already serve thousands of businesses.
A successful software partnership can therefore bring thousands of merchants onto its infrastructure without Payabli having to acquire them individually.
However, Inc.'s ranking measures growth over a historical three-year period, and Payabli has not published a complete set of audited annual revenue figures that would allow a direct comparison with Ramp.
Payabli wins the percentage-growth comparison. Ramp remains considerably larger, with much stronger public evidence of its current revenue scale.
If you want more recent data on this point, please see our latest FinTech market report.

Our research about fintech companies gets updated several times a month, so you always get the latest view of where things stand.
Which smaller FinTech startups have recorded the fastest revenue growth?
Payabli, Lendbox, Aspire, and Storepay are among the FinTech businesses with exceptional documented multiyear growth, although their results come from different periods and regional rankings.
The Financial Times and Statista's 2026 Asia-Pacific high-growth ranking placed Singapore-based Aspire among the leading financial technology companies, with 1,772.43% revenue growth between 2021 and 2024.
Aspire generated approximately $44.72 million in revenue in 2024. Storepay, another FinTech in the regional ranking, achieved approximately 1,722% growth over the same period and reached $8.75 million in revenue.
The previous year's Financial Times ranking highlighted Indian lending platform Lendbox, which recorded an extraordinary 536% compound annual growth rate between 2020 and 2023.
These businesses are quite different despite their similarly impressive growth percentages.
Aspire specializes in financial services for companies, Storepay operates in consumer payments, and Lendbox focuses on lending. They also serve different markets and face different banking and regulatory conditions.
These historical rankings show how quickly FinTech startups can expand, but they don't establish which company leads globally today. Their company samples, eligibility rules, and measurement periods differ.
| FinTech startup | Documented growth | Period | Reported revenue scale |
|---|---|---|---|
| Payabli | 5,774% cumulative | 2022-2025 | High eight figures reported for 2025 |
| Lendbox | 536% annual CAGR | 2020-2023 | $51M in 2023 |
| Aspire | 1,772.43% cumulative | 2021-2024 | $44.72M in 2024 |
| Storepay | Approximately 1,722% cumulative | 2021-2024 | $8.75M in 2024 |
| Kapital | 133% annual | FY2025 | $310M actual annual revenue estimate |
| Airwallex | 74% annual | March 2026 | $1.3B annualized |
| Revolut | 46% annual | FY2025 | $6B actual annual revenue |
Is Revolut growing more than Ramp in actual dollars?
Revolut is adding considerably more revenue in absolute dollars than Ramp's recent annualized revenue gains, making the British FinTech a stronger candidate when we measure total new revenue.
According to Revolut's 2025 annual report, revenue increased from approximately $4 billion to $6 billion in one year.
That means Revolut added roughly $2 billion in recognized annual revenue.
By comparison, Ramp's annualized revenue pace increased by at least $775 million between the end of 2025 and its latest disclosure.
Although the periods and accounting measures differ, the gap in absolute growth is considerable.
Revolut also recorded its fifth consecutive profitable year. Pretax profit reached $2.3 billion, up 57%, while its pretax margin improved from 35% to 38%.
The customer figures help explain how Revolut achieved this. Retail customers increased 30% to 68.3 million, business customers grew 33% to 767,000, and total customer balances climbed 66% to $67.5 billion.
And revenue grew faster than customer numbers. Revolut is earning more from a rapidly expanding customer base while generating substantial profits.
For absolute recognized revenue expansion among the companies examined, Revolut is ahead. Ramp has the stronger recent percentage-growth trajectory at major startup scale, but Revolut is already adding revenue in amounts that few private FinTechs can match.

In our market report about fintech companies, we look at what the winners do differently, so you can learn from the best instead of guessing.
Could Airwallex become the fastest-growing business FinTech?
Airwallex is one of Ramp's strongest challengers, particularly because its international payments business is growing quickly and customers increasingly use several products.
The Singapore- and San Francisco-headquartered company crossed $1 billion in annualized revenue in October 2025, having approximately doubled its revenue pace from the end of 2024.
Its March 2026 disclosure showed that revenue had reached $1.3 billion annualized.
Airwallex's growth is also becoming more geographically diverse. The company reported 171% revenue growth in the Americas during 2025 and 116% growth across Europe, the Middle East, and Africa.
Both regions grew much faster than the company's overall 74% year-over-year rate reported in March, suggesting that markets outside its original Asia-Pacific base are becoming increasingly important.
Another revealing number comes from Airwallex's June 2026 financing announcement: more than 90% of its revenue came from customers using multiple Airwallex products.
That's a substantial level of cross-product adoption.
A company might initially use Airwallex for international payments, then add business accounts, corporate cards, payment acceptance, or expense management.
The company also reported reaching EBITDA profitability in the fourth quarter of 2025.
Airwallex now combines meaningful revenue scale, international expansion, and deeper customer relationships. Its next financial disclosures should tell us whether that growth is catching up with Ramp's.
Is Kapital the fastest-growing FinTech in Latin America?
Kapital is one of Latin America's fastest-growing major business FinTech challengers, but acquisitions account for part of its recent expansion.
Sacra estimates that the Mexican company generated $310 million in revenue during 2025, up 133% from the previous year.
Its year-end annualized revenue pace reached an estimated $548 million, compared with $184 million a year earlier.
Kapital also reported major increases in financial activity. Its credit portfolio grew 290% to approximately $1.34 billion, while deposits increased 444% to around $3.1 billion.
Payment volume reached approximately $33.4 billion, nearly four times the previous year's level.
Those figures look extraordinary, but the acquisition of Intercam's banking operations affected Kapital's balance sheet and commercial reach.
Buying a bank can add deposits, loans, and existing customer relationships immediately. That creates growth that is different from acquiring customers one by one.
Kapital's revenue model also differs from that of a typical payments or financial software company. According to Sacra, approximately 60% of its revenue comes from lending, with the remaining 40% coming from software and other financial technology services.
Kapital deserves a place among Latin America's most interesting high-growth business FinTechs. But we wouldn't rank all of its recent expansion alongside organic growth at a software-led competitor. The Intercam acquisition is too important to ignore.
If you want more recent data on this point, please see our latest FinTech market report.

In our document detailing everything you need to know about fintech, you will always find fresh funding data, taken straight from our own verified funding database.
Are FinTech startups growing because customers are using them more?
Leading FinTech startups are growing partly because customers are putting more financial activity through their platforms, with transaction volumes increasing faster than customer numbers at several major companies.
Airwallex provides one clear example. Its annualized transaction volume grew more than 120% year over year in March 2026, while annualized revenue increased 74%.
Revolut showed a similar pattern during 2025. Its retail customer base grew 30%, while total transaction volume increased approximately 65%.
Ramp's recent purchase-volume growth has also been much faster than its earlier customer growth rates, although the published comparison periods do not match exactly.
Customer acquisition alone clearly doesn't explain the whole picture.
Companies are processing more financial activity, which can come from existing customers spending more, adding products, or moving a larger share of their financial operations onto the platform. Larger newly acquired customers may also contribute.
Airwallex offers the clearest evidence of product expansion, thanks to its disclosure that most revenue comes from customers using multiple services.
Ramp has reported that a majority of customers use at least two of its products, while a quarter use three or more.
Broader product adoption is becoming an increasingly important source of FinTech growth. The company-wide figures still don't tell us exactly how much comes from existing customers versus new ones, but they show that acquiring another customer is far from the only way these businesses can expand.
Is Ramp's revenue growth accelerating or slowing down?
Ramp's latest operating figures point to continued acceleration, with the company adding substantial revenue and customers over a relatively short period.
The strongest evidence comes from the company's October 2026 update, where management said revenue growth was 25% faster than around the same time a year earlier.
The customer trajectory adds some context.
Ramp started 2026 with approximately 50,000 businesses, according to Sacra. By June, it had reached 70,000, adding roughly 20,000 customers during the first half of the year.
Over the following four months, it added another 15,000.
The increase in absolute customers remained substantial, even though the percentage growth rate naturally declined as the installed base became larger.
Purchase volume provides another useful comparison. Ramp reported $200 billion in annualized purchases in June and more than $275 billion in its October update.
That represents an increase of at least 37.5% in roughly four months.
The company also described its 175% year-over-year purchase-volume growth as its fastest in three years.
Independently verified quarterly revenue figures would make the acceleration easier to measure precisely. Still, the reported purchase-volume and revenue trends point in the same direction: Ramp is expanding exceptionally quickly for a company already operating at this scale.

Learning from others' mistakes is the cheapest lesson there is. In our report covering the fintech market, we look at what broke startups before you, so you don't repeat it.
Is Ramp making more money from each customer?
Ramp has maintained a high revenue pace per customer while expanding rapidly, but the public figures don't prove that average monetization has improved.
Using Sacra's estimated $1.225 billion annualized revenue at the end of 2025 and approximately 50,000 customers around the beginning of 2026, we calculate roughly $24,500 in annualized revenue per customer.
The latest figures imply somewhat more than $23,500 per customer.
Those approximations are close, suggesting that Ramp has broadly maintained its revenue intensity while adding tens of thousands of companies.
However, the figures don't identify how much each customer actually spends, how long customers have been using Ramp, or how much revenue comes from customers added during the period.
There's a more interesting development inside Ramp's product mix.
In June 2026, the company reported that more than 3,200 enterprise customers generated at least $100,000 in annualized revenue each.
That group alone represented a minimum of $320 million in annualized revenue, equivalent to more than 20% of Ramp's approximately $1.5 billion pace reported that month.
Because $100,000 is only the threshold, the group's actual contribution could be materially higher.
Large customers already account for a meaningful part of Ramp's business. That helps explain its expansion beyond corporate cards into procurement, accounting, travel, and other finance tools.
Ramp's growth increasingly depends on becoming part of how companies manage their finances, rather than simply issuing more cards.
Can Ramp keep growing without burning huge amounts of cash?
Ramp's growth looks financially healthier than that of many early-stage startups because the company has reported positive cash flow while its revenue has increased.
Its June 2026 financing announcement confirmed positive free cash flow, and its latest update again reported positive cash flow.
That's encouraging for a business expanding its workforce, product portfolio, engineering capabilities, and customer operations.
However, Ramp has not published the same level of detailed audited profitability information as Revolut.
Positive cash flow doesn't tell us precisely how much operating profit Ramp generates, how much working capital affects its cash position, or what its long-term margins might look like.
Revolut provides a useful benchmark. Its 2025 annual report showed $1.7 billion in net profit, compared with approximately $1 billion the previous year.
Those earnings are substantial enough to fund further expansion without relying entirely on venture capital.
For Ramp, the evidence is more limited but still favorable. The company is reporting positive cash generation despite rapidly increasing revenue and developing new products.
Its next challenge is demonstrating that this financial performance holds as it competes with increasingly sophisticated banking and software providers.

Your time is limited. In our research about fintech companies, we put numbers on each part of the market, so you can see where it makes sense to focus.
Does Ramp's $60 billion valuation make sense given its growth?
Ramp's $60 billion valuation is extremely demanding, although its recent revenue growth explains much of the increase from its previous financing round.
In June 2026, Ramp raised $750 million at a $44 billion valuation.
Four months later, the company raised another $1.85 billion at $60 billion, an increase of approximately 36%.
During roughly the same period, its annualized revenue pace rose by at least 33%.
The company's valuation therefore increased at almost the same rate as its reported revenue pace. Investors didn't need to assign a dramatically higher revenue multiple to explain the new headline valuation.
At $60 billion, Ramp has an implied private-market valuation of less than 30 times its disclosed annualized revenue pace.
That's a very high multiple for a financial technology company, especially compared with many established payments and banking businesses.
Investors appear to be paying for the expectation that Ramp will continue expanding into procurement, accounting, payments, and broader financial software.
And the valuation leaves little room for a serious slowdown.
If Ramp's revenue growth falls sharply before its profitability becomes more visible, investors could become less willing to pay such a substantial multiple.
Its recent financial expansion supports the direction of the valuation increase. Whether $60 billion is justified over the longer term depends on several more years of growth and cash generation. That's a lot of execution still to come.
If you want more recent data on this point, please see our latest FinTech market report.
Could smaller FinTech startups overtake Ramp in the next few years?
Smaller FinTech startups could easily beat Ramp's percentage growth rate, but catching up with its actual revenue scale will require several years of exceptional expansion.
We can illustrate the challenge using Payabli.
Even if a FinTech company starts with $50 million in annual revenue and grows 200% annually, it would reach $150 million after one year, $450 million after two years, and $1.35 billion after three years.
That would be remarkable growth, yet it would still be below Ramp's latest annualized revenue pace, even if Ramp stopped growing entirely.
Smaller competitors also face challenges as their businesses become larger. Each year, they need to generate increasingly substantial revenue additions to maintain the same growth percentage.
Kapital, for example, already has a sizable lending business, but its expansion brings credit risk, capital requirements, and regulatory obligations.
Payabli has a different challenge. Its embedded payments model can scale quickly through software partnerships, but revenue depends on the commercial success and transaction activity of those partners.
Airwallex is a more immediate challenger because it has already passed the billion-dollar annualized revenue threshold and operates across numerous international markets.
The strongest threat to Ramp's current position would come from another major FinTech generating comparable revenue while maintaining a higher growth rate over several consecutive quarters.

In our market report about fintech companies, we always try to gather several sources and make estimates that make sense, so you can work with solid numbers.
What would prove another FinTech startup has overtaken Ramp?
A FinTech competitor would need to report faster sustained revenue growth at a similar scale, supported by real customer adoption and enough financial detail to distinguish growth from acquisitions or accounting differences.
Airwallex is one of the clearest companies to watch. Its next disclosures could show whether its international expansion is translating into faster revenue growth.
Mercury is another contender, particularly as it broadens its banking and financial software services for businesses.
Kapital could become more competitive if it demonstrates that its rapid growth continues organically after integrating acquired banking operations.
Payabli could also challenge the ranking as its revenue base grows, although it would need considerably more financial disclosure to support a like-for-like comparison.
The most useful evidence would be twelve-month revenue growth calculated on the same basis for all companies, accompanied by customer retention, transaction volume, and profitability data.
A challenger moving from $1 billion to $2.5 billion in actual annual revenue within a year, for instance, would have a particularly strong claim if the growth were largely organic.
Until comparable figures become available, Ramp remains our preferred leader among major private FinTech growth companies. That doesn't make it the fastest-growing FinTech in every market or by every measure.
Which FinTech startup is growing the fastest overall?
Ramp is currently the strongest answer among major private FinTech startups, although Payabli has grown faster in percentage terms and Revolut has added more revenue in absolute dollars.
Ramp's advantage comes from the combination of its scale, recent expansion, customer growth, and reported positive cash flow.
Its annualized revenue has nearly tripled since early 2025. More importantly, that growth has continued while the company has expanded into more financial operations and secured larger business customers.
Payabli deserves recognition for exceptional percentage growth. Its Inc. 5000 performance shows how quickly a smaller embedded payments platform can expand through software partnerships.
Revolut is arguably the more impressive business financially. Its $6 billion in annual revenue, substantial profits, and tens of millions of customers make it considerably larger and more profitable than most private FinTech competitors.
Airwallex also remains a serious contender because of its rapid international growth and high adoption of multiple financial products.
Still, when we combine recent revenue momentum, commercial scale, customer expansion, and available evidence of financial sustainability, Ramp has the most convincing overall growth case.
Ramp is our leading major FinTech growth startup today. Calling it the single fastest-growing FinTech worldwide would stretch the evidence beyond what the available numbers can establish.
If you want more recent data on this point, please see our latest FinTech market report.

If you build or invest in the fintech market, you need to know which business models pay off now and which ones are fading. That's why our report covering it has a whole section on it.
Our methodology
We examined recent revenue growth, commercial scale, customer adoption, transaction activity, and profitability to identify the fastest-growing major FinTech startups. We prioritized revenue growth at meaningful scale because it provides a more useful measure of commercial expansion than transaction volume or customer growth alone. We then looked separately at percentage growth and absolute revenue additions to identify companies leading on those measures.
We distinguished annualized revenue from revenue recognized during a completed financial year. Ramp's latest annualized revenue figures, for example, describe its current revenue pace, while Revolut's financial results cover actual revenue earned during 2025. We used percentage changes over the stated reporting periods and avoided treating growth over a few months as directly equivalent to a full-year growth rate.
For smaller FinTech companies, we used the original Inc. 5000 and Financial Times/Statista rankings to assess exceptional multiyear growth. These rankings establish performance during their respective measurement windows, rather than a single global ranking for October 2026. We also considered whether reported expansion was driven by organic business growth, broader product adoption, or acquisitions, particularly in Kapital's case.
We relied on company financial disclosures for reported results and on Sacra for clearly identified independent estimates. Positive cash flow, EBITDA profitability, and audited net profit were treated as distinct financial measures. Our overall selection gives particular weight to companies combining substantial revenue growth with a large existing revenue base and evidence of financial sustainability.
Key sources for Ramp include Ramp's October 2026 financing and operating update, its June 2026 financing announcement, Sacra's Ramp financial estimates, and Sacra's analysis of Ramp's business model.
For Airwallex, we used its June 2026 Series H announcement, its Series G announcement, its $1 billion annualized revenue milestone commentary, its EMEA expansion update, and its 2025 year-end performance review.
Payabli's growth figures come from its 2026 Inc. 5000 profile, its August 2026 growth announcement, and its June 2025 Series B announcement.
For large-scale financial benchmarks, we used Revolut's FY2025 financial results, Monzo's 2026 annual report, and Stripe's 2025 annual update. Additional company estimates come from Sacra's Mercury analysis and Sacra's Kapital analysis.
For regional and historical high-growth comparisons, we used the Financial Times and Statista's Asia-Pacific High-Growth Companies 2026 ranking and Asia-Pacific High-Growth Companies 2025 ranking. Together, these sources underpin the revenue comparisons, growth calculations, and company assessments used in the article.

Theory only gets you so far. In our report covering the fintech market, we dig up the real signals from the field and show you the ones worth watching.
Written by the New Market Pitch teamWe track new markets so founders and investors can move faster. About us